
 Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market | 2026-2036
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market Insights
Project finance through non-recourse limited-recourse structures is fragmenting the competitive landscape in Asia Pacific EPCM, allowing specialist contractors to bid against integrated conglomerates. Samsung Engineering leverages its LNG module fabrication capacity to anchor large-scale energy contracts across Southeast Asian coastal zones. China State Construction Engineering Corporation sustains dominance in domestic mega-project delivery through state-backed financing access and captive steel supply chains. Hyundai Engineering & Construction differentiates via offshore engineering capabilities that extend into floating production facility integration.
Engineering, Procurement, and Construction Management denotes a bundled service delivery framework where a single contractor or consortium assumes responsibility for front-end engineering design, vendor selection and materials procurement, construction execution, and overall project controls including schedule and cost management. The model typically employs milestone-based payment structures tied to completion percentages, with risk allocation shifting between owner and contractor depending on contract variant. Oil & Gas and Energy verticals generate the deepest margin pools due to process complexity and safety certification requirements, while Infrastructure projects offer volume scale through government-backed programs. Mega Projects and Large Scale categories concentrate engineering talent and bonding capacity among a handful of qualified contractors, whereas Medium Scale work fragments across regional specialists competing on localized procurement networks.
China's MEE enforces dual carbon compliance timelines that reshape feasibility studies for new petrochemical complexes, pushing owners toward lower-carbon process designs. India's CEA mandates domestic content requirements in power sector EPCM contracts that alter procurement sourcing for foreign contractors. Australia's TGA-equivalent building codes and Japan's METI industrial facility standards add compliance layers that filter market access. Stakeholders must track how carbon border adjustments and local content rules redefine contractor qualification criteria across jurisdictions.
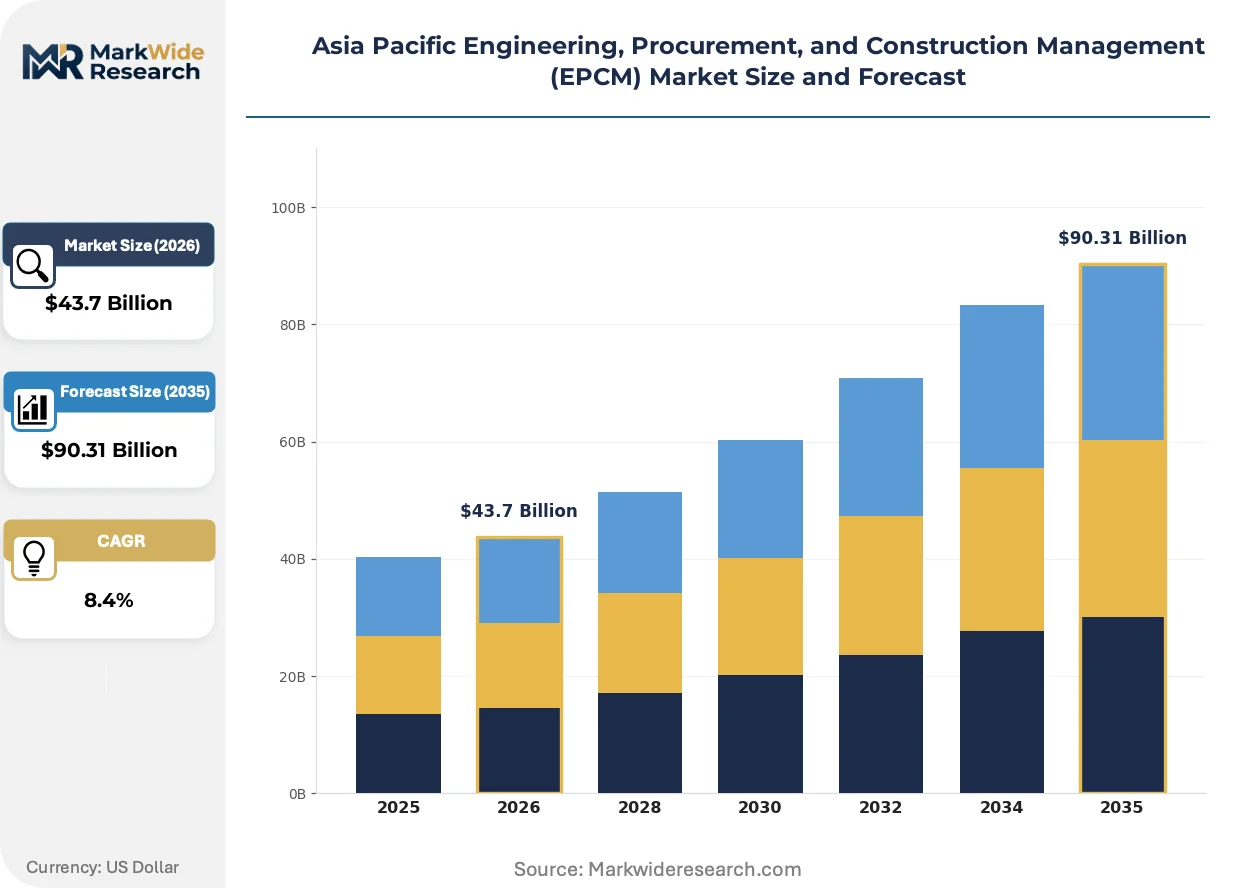
Market Dynamics
Project finance fragmentation through non-recourse structures is redistributing contract access across Asia Pacific EPCM, enabling specialist contractors to challenge integrated conglomerates for mega-project awards previously locked by balance-sheet scale.
Growth Catalysts
- LNG Terminal Expansion:Energy sector owners across Southeast Asian coastal zones are expanding import terminal capacity, driving demand for module fabrication and marine construction expertise.
- Dual Carbon Compliance:China's MEE enforcement timelines are pushing petrochemical owners toward lower-carbon process designs and modular construction methods that compress field assembly time.
- Industrial Corridor Development:Indonesia's government-backed programs spanning Java and Sumatra are concentrating medium-scale EPCM awards for manufacturing infrastructure and utilities integration.
Market Restraints
- Steel Supply Concentration:Captive steel supply chains controlled by state-linked construction groups in China limit procurement flexibility for foreign contractors bidding domestic mega-projects.
- Domestic Content Mandates:India's CEA requirements in power sector contracts force foreign EPCM firms to reconfigure vendor networks, adding compliance cost and schedule risk.
- Specialized Engineering Talent Scarcity:Floating production facility integration and offshore engineering capabilities remain concentrated among a handful of qualified contractors, constraining capacity expansion.
Strategic Opportunities
- Carbon Border Adjustment Preparation:Australia's TGA-equivalent building codes and Japan's METI industrial standards are creating premium service tiers for contractors with certified low-carbon construction methodologies.
- Modular Fabrication Scale-Up:Petrochemical owners are converging digital twin technology with prefabrication workflows, opening white space for engineering firms with captive module yard access.
- Medium-Scale Regional Fragmentation:Indonesia's industrial corridor projects outside Java present acquisition targets for specialists with localized procurement networks and provincial regulatory relationships.
Industry Challenges
- Cross-Border Certification Complexity:Contractors face divergent safety certification timelines between Australia's TGA-equivalent standards, Japan's METI facility codes, and China's GB standards, compressing bid preparation windows.
- Schedule-Cost Control Integration:Milestone-based payment structures tied to completion percentages require real-time project controls that many regional specialists lack, creating execution risk on complex process installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market |
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $90.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Procurement, Construction, Project Management Industry Vertical: Oil & Gas, Energy, Infrastructure, Mining Project Size: Large Scale, Medium Scale, Small Scale, Mega Projects Delivery Model: Design-Bid-Build, Design-Build, Integrated Project Delivery, Construction Management |
| Companies Covered | Samsung Engineering, China State Construction Engineering Corporation, Hyundai Engineering & Construction, China National Chemical Engineering Group, China Petroleum Engineering & Construction Corporation, Fluor Corporation, Worley, Jacobs Engineering Group, Bechtel Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market Trends and Innovations
Digital construction methodologies are compressing front-end engineering timelines while regulatory carbon accounting is reshaping contractor qualification criteria across Asia Pacific energy and industrial verticals.
Modular construction technology is hybridizing traditional stick-built execution with prefabricated process skids. Petrochemical owners in China's coastal provinces are adopting this approach at accelerated pace to meet MEE dual carbon deadlines. The technology is hybridizing project delivery models by shifting fabrication labor to controlled yard environments while reducing field assembly hours and associated emissions exposure.
China's MEE dual carbon goals are enforcing compliance timelines that reshape feasibility studies for new petrochemical complexes. Industrial facility owners must now integrate carbon intensity metrics into front-end engineering design, altering vendor selection criteria and process technology preferences. The petrochemical segment across Shandong and Jiangsu provinces is responding by prioritizing contractors with certified low-carbon construction methodologies and modular fabrication capabilities.
Buyer procurement patterns are fragmenting across specialist contractors and integrated conglomerates depending on project scale and financing structure. Large-scale energy contracts increasingly favor firms with captive module fabrication and state-backed financing access, while medium-scale industrial work distributes across regional players with localized supply chains. This bifurcation is most visible in Indonesia's Java-Sumatra corridor, where government-backed programs sustain volume for domestic specialists while LNG terminal awards concentrate among engineering groups with offshore integration experience.
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market Segmentation
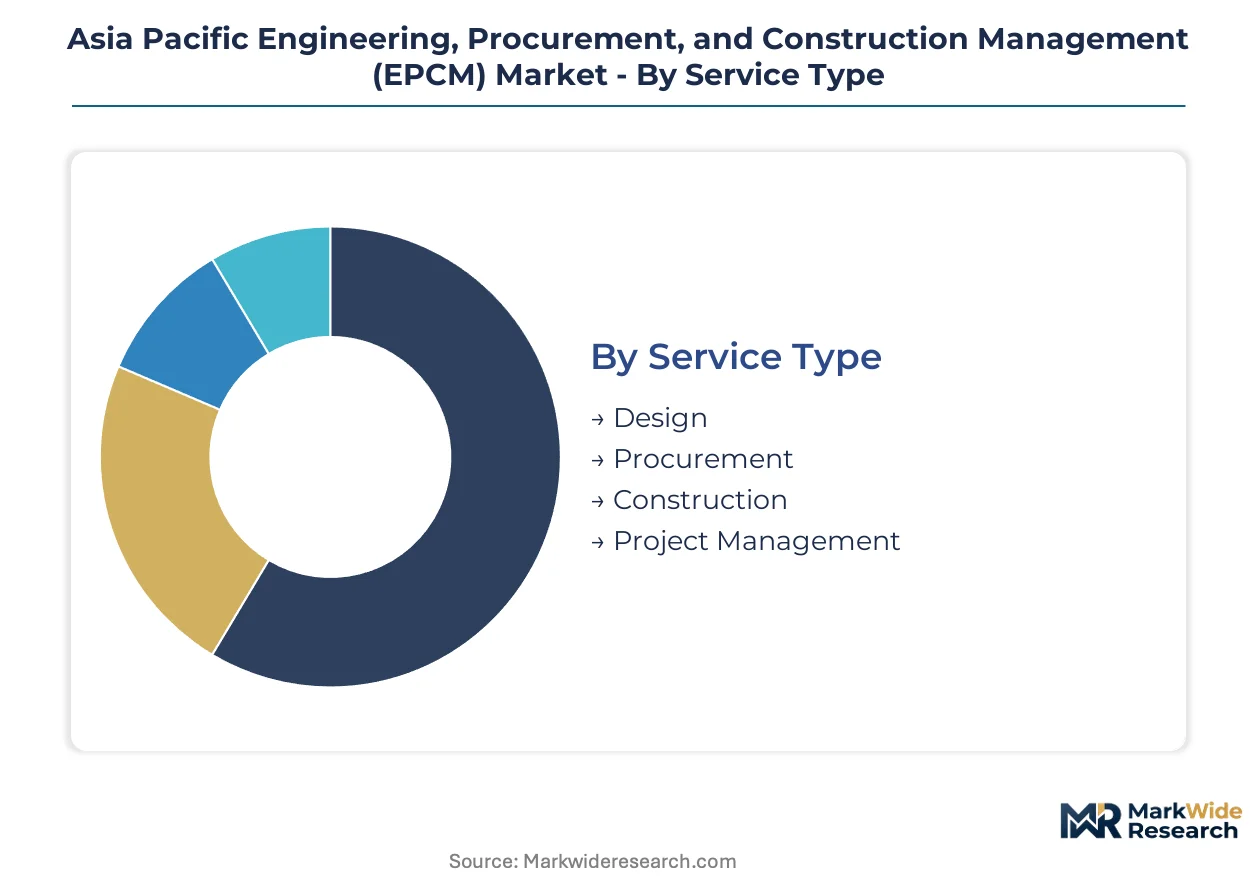
EPCM contract structures vary dramatically in capital intensity, risk allocation, and contractor qualification requirements across Asia Pacific. Segment boundaries determine which engineering groups can bid, how financing arranges, and where margins concentrate.
Service Type:
Front-end design cycles stretch 18-36 months on complex process installations, while procurement and construction phases compress or extend based on module fabrication access and labor mobility.
- Design:Front-end engineering packages define process configuration, equipment specifications, and regulatory compliance pathways for petrochemical and LNG facilities. China's MEE dual carbon timelines are compressing feasibility study durations and elevating demand for low-carbon process design expertise in Shandong and Jiangsu provinces.
- Procurement:Vendor selection and materials sourcing spans long-lead equipment, bulk commodities, and specialized subcontracts across fragmented Asian supply chains. India's CEA domestic content mandates force foreign contractors to reconfigure vendor networks for power sector contracts, adding compliance layers.
- Construction:Field execution covers civil works, mechanical installation, and commissioning for process and infrastructure assets. Indonesia's industrial corridor projects across Java and Sumatra sustain steady demand for regional contractors with localized labor relationships.
- Project Management:Schedule controls, cost management, and interface coordination bind engineering and construction phases into unified delivery. Milestone-based payment structures require real-time visibility that many regional specialists lack on complex installations.
Construction commands the largest share of contract value. Design is where capability scarcity creates the steepest vendor differentiation.
Industry Vertical:
Margin profiles diverge sharply: process complexity and safety certification requirements deepen profitability in hydrocarbon sectors, while government-backed programs drive volume in infrastructure.
- Oil & Gas:Upstream, midstream, and downstream facilities require specialized process engineering, pressure vessel fabrication, and hazardous area compliance. Southeast Asian LNG terminal expansions concentrate demand for module fabrication and marine construction expertise among contractors with offshore integration capabilities.
- Energy:Power generation, transmission, and renewable integration projects span thermal, hydro, and emerging hydrogen infrastructure. India's CEA mandates reshape procurement sourcing for foreign EPCM firms bidding domestic power contracts.
- Infrastructure:Transportation, water, and urban development projects offer scale through government-backed programs with standardized designs. Indonesia's Java-Sumatra corridor concentrates medium-scale awards for manufacturing infrastructure and utilities integration.
- Mining:Extractive and mineral processing facilities require bulk materials handling, tailings management, and remote site logistics. Australia's METI-equivalent standards and TGA building codes add compliance layers that filter contractor access.
Oil & Gas retains the deepest margin pools. Energy is expanding most quickly under decarbonization investment cycles.
Project Size:
Bonding capacity and engineering talent concentration restrict mega-project participation to a handful of qualified contractors, while medium-scale work fragments across regional specialists.
- Mega Projects:Multi-billion dollar complexes requiring integrated consortium structures, state-backed financing access, and captive supply chains. China's domestic mega-projects concentrate among state-linked construction groups with captive steel supply chains.
- Large Scale:Major industrial and energy facilities demanding specialized process expertise and extended performance guarantees. Samsung Engineering anchors large-scale energy contracts across Southeast Asian coastal zones through LNG module fabrication capacity.
- Medium Scale:Manufacturing infrastructure, utilities, and regional industrial parks suited to localized procurement networks. Indonesia's industrial corridor projects outside Java present acquisition targets for specialists with provincial regulatory relationships.
- Small Scale:Maintenance, retrofit, and discrete facility upgrades with compressed timelines and limited engineering oversight. These contracts distribute across domestic contractors with established owner relationships.
Mega Projects concentrate engineering talent and financing access. Medium Scale is where regional fragmentation creates the most competitive churn.
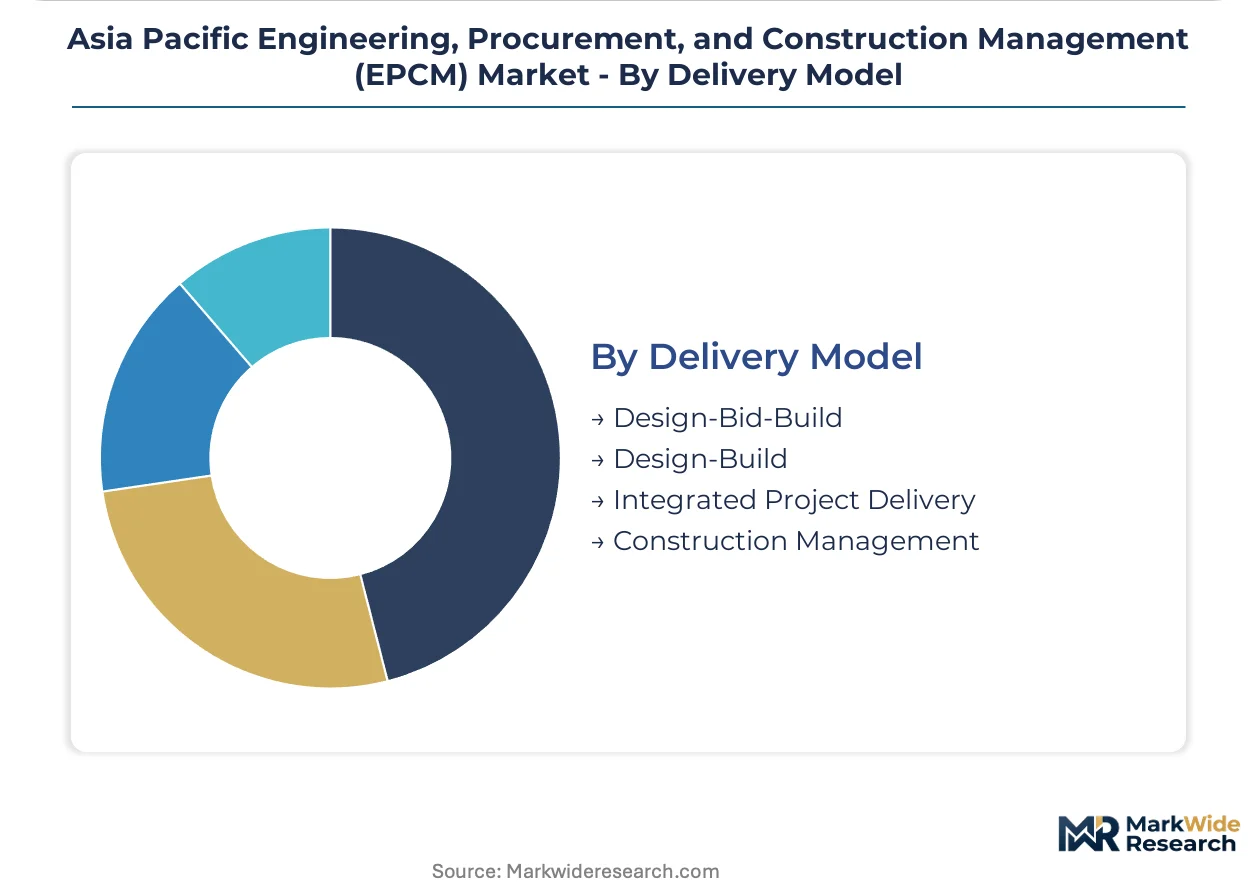
Delivery Model:
Risk allocation between owner and contractor shifts dramatically across contract variants, with integrated models compressing schedule at the cost of reduced owner control.
- Design-Bid-Build:Sequential phases with discrete contractor appointments and owner-managed interfaces. This traditional structure persists in public infrastructure where procurement regulations mandate competitive tendering.
- Design-Build:Single-point responsibility merging engineering and construction under unified contract. Petrochemical owners in China's coastal provinces favor this approach to compress field assembly time against MEE dual carbon deadlines.
- Integrated Project Delivery:Collaborative frameworks with shared risk-reward mechanisms and early contractor involvement. Digital twin technology convergence with prefabrication workflows opens white space for engineering firms with captive module yard access.
- Construction Management:Owner-retained design with construction-phase oversight by professional manager. This model suits owners with internal engineering capabilities seeking schedule and cost transparency.
Design-Build dominates energy sector awards. Integrated Project Delivery is gaining share fastest where digital construction methodologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia Pacific EPCM flows reflect a structural import dependence in specialized engineering services, with regional contractors exporting modular fabrication capacity while importing front-end design expertise from Western engineering groups.
China
Petrochemical owners in Shandong and Jiangsu provinces are accelerating modular construction adoption to meet MEE dual carbon compliance deadlines. The ministry's enforcement timelines compress feasibility study durations and elevate demand for low-carbon process design expertise. State-linked construction groups dominate domestic mega-projects through captive steel supply chains and preferential financing access.
Indonesia
Government-backed industrial corridor programs spanning Java and Sumatra are concentrating medium-scale EPCM awards for manufacturing infrastructure and utilities integration. Provincial regulatory relationships determine contract access outside the main island clusters. Samsung Engineering anchors large-scale LNG terminal contracts through module fabrication capacity deployed across coastal zones.
India
CEA domestic content mandates in power sector contracts force foreign EPCM firms to reconfigure vendor networks, adding compliance cost and schedule risk. Thermal and renewable generation projects drive sustained demand for construction execution capabilities. Regional specialists with localized labor relationships capture medium-scale manufacturing infrastructure awards in Gujarat and Maharashtra industrial zones.
South Korea
Offshore engineering capabilities concentrated among integrated construction groups extend into floating production facility integration for Southeast Asian energy projects. Hyundai Engineering & Construction leverages marine construction expertise to differentiate in regional LNG terminal competitions. The country's module fabrication yards supply prefabricated process skids to petrochemical owners across China's coastal provinces.
Australia
TGA-equivalent building codes and METI-aligned industrial facility standards add compliance layers that filter contractor access to mining and energy infrastructure projects. Carbon border adjustment preparation is creating premium service tiers for contractors with certified low-carbon construction methodologies. Western Australia and Queensland mining corridors sustain demand for bulk materials handling and remote site logistics expertise.
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated conglomerates with state-backed financing access and specialist contractors competing on modular fabrication or offshore engineering capabilities. The competitive terrain stratifies across three tiers: state-linked Asian construction groups with captive supply chains, Western engineering firms with process technology licensing relationships, and regional specialists with localized procurement networks. Dominant competitive moves include strategic partnerships to access module fabrication capacity and portfolio diversification into carbon-certified construction methodologies.
Among state-linked Chinese construction groups, China State Construction Engineering Corporation and China National Chemical Engineering Group occupy positions defined by domestic mega-project concentration and preferential financing access. Samsung Engineering represents the integrated Korean model, anchoring regional energy contracts through LNG module fabrication capacity. Within the Western engineering tier, Fluor Corporation and Bechtel Corporation exemplify firms competing on process complexity expertise and safety certification credentials across hydrocarbon verticals.
| Leading Market Players |
|---|
| Samsung Engineering |
| China State Construction Engineering Corporation |
| Hyundai Engineering & Construction |
| China National Chemical Engineering Group |
| China Petroleum Engineering & Construction Corporation |
| Fluor Corporation |
| Worley |
| Jacobs Engineering Group |
| Bechtel Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive steel supply chains controlled by state-linked construction groups in China concentrate upstream input pricing power, directing margin pools toward contractors with preferential financing access and in-house fabrication capacity. This upstream concentration compresses procurement flexibility for foreign bidders while elevating premium tiers for firms with certified low-carbon construction methodologies.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures tied to milestone completion percentages. Price differentiation stems from carbon certification tier under China's MEE dual carbon framework and modular fabrication capability scale. Cost compression in standard-tier construction execution is intensifying because state-backed competitors leverage captive steel sourcing. Foreign contractors show highest price sensitivity in domestic mega-project bidding, while integrated conglomerates with module yard access command premium positioning.
Supply Chain Analysis
Export-control regimes on advanced process simulation software and pressure vessel fabrication technology limit technology transfer into Southeast Asian module yards. Supply concentrates in China's Shandong and Jiangsu provinces for prefabricated process skids, South Korea for offshore engineering components, and Indonesia for localized civil works execution. Critical dependencies include high-grade structural steel, specialized welding consumables, and long-lead rotating equipment. Single-source vulnerability runs through China's captive steel networks. Distribution feeds from module fabrication yards through marine logistics to coastal terminal sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific EPCM is undergoing high-growth disruption as China's MEE dual carbon enforcement compresses project timelines and elevates demand for certified low-carbon construction methodologies. This regulatory inflection reconfigures contractor qualification criteria and procurement sourcing patterns across the region.
For Market Incumbents: Pre-empt margin erosion from state-backed competitors by deepening captive module fabrication capacity in Vietnam or Indonesia. Accelerate certification investment under Australia's TGA-equivalent building codes and Japan's METI industrial standards to capture premium service tiers. Lock in long-term steel supply agreements before China's domestic demand absorbs regional capacity.
For New Entrants and Emerging Players: Indonesia's industrial corridor projects outside Java present the most penetrable white space, where provincial regulatory relationships outweigh balance-sheet scale. Target medium-scale manufacturing infrastructure awards in Sumatra's emerging zones. Enter through design-build partnerships with domestic firms holding established owner relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward specialist contractors with localized procurement networks and captive module yard access in Southeast Asia. Long-term viability favors firms positioned at the intersection of modular fabrication scale and carbon-certified construction capability. Monitor India's CEA domestic content mandate enforcement as an inflection signal for procurement reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Scale-Up | Captive module yard access in Vietnam anchors Southeast Asian LNG terminal awards. |
| Carbon Certification Investment | MEE dual carbon compliance opens premium service tiers in China's coastal provinces. |
| Provincial Partnership Formation | Regulatory relationships in Sumatra unlock Indonesia's industrial corridor expansion. |
| Steel Supply Security | Long-term agreements mitigate China's captive supply chain concentration risk. |
| Digital Twin Integration | Prefabrication workflow convergence compresses front-end engineering timelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed contractors, MEE regulatory circulars, and IEA energy infrastructure databases. Primary interviews spanned EPC project directors, procurement leads at petrochemical owners, module fabrication yard managers, and power sector planning officers at India's CEA. Bottom-up contract value aggregation triangulates against top-down market sizing from national infrastructure investment programs.
Forecast inputs include capital expenditure trajectories across oil and gas, energy, and infrastructure verticals, segmented by project scale tier and delivery model. Modeled dimensions span service type, industry vertical, project size category, and regional regulatory cluster. CAGRs derive from trend extrapolation of contract award volumes and average contract values across the projection horizon. Specific inputs incorporate MEE dual carbon compliance timelines and CEA domestic content mandate enforcement patterns.
Practitioners should monitor carbon border adjustment implementation and local content rule expansion for early signals of contractor qualification revision. Forecasts reflect assumptions about regulatory enforcement consistency and financing availability for non-recourse project structures. Material shifts in China's steel export policy or India's CEA mandate scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Geophysical Services Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
Asia-Pacific Seismic Services Market
Engineering Services
Seismic Services Market
Engineering Services
North America Seismic Survey Market
Engineering Services
Bridge Inspection System Market
Engineering Services
Engineering Design Service Market
Engineering Services
China Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Pipeline Installation Services Market
Engineering Services
Engineering Services Outsourcing Market
Engineering Services
Plastic Injection Molding Outsourcing Services Market
Engineering Services
NDT Inspection Services Market
Engineering Services
Foundation Repair Services Market
Engineering Services
Well Cementing Services Market
Engineering Services
Bridge Inspection Services Market