
 Global Neuroscience Antibodies and Assays Market | 2026-2036
Global Neuroscience Antibodies and Assays Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neuroscience Antibodies and Assays Market Foresight
ISO 13485 certification for in vitro diagnostic reagents is rotating competitive access across the supplier base, forcing smaller producers toward contract manufacturing or private-label partnerships. Thermo Fisher Scientific leverages its vertically integrated antibody production and global distribution network to sustain pricing power in bulk reagent contracts. Abcam specializes in recombinant rabbit monoclonal antibodies, a sub-category where validation depth differentiates premium positioning against catalog competitors.
Neuroscience antibodies and assays comprise affinity-purified immunoglobulins and quantitative detection systems engineered for neural protein targets, with typical specificity thresholds exceeding 95% cross-reactivity clearance against homologous tissue lysates. These reagents enable biomarker quantification, receptor mapping, and pathway analysis across central nervous system research and clinical diagnostic workflows. Monoclonal antibodies command the largest value share due to batch consistency requirements in regulated diagnostic settings, while multiplex assay formats represent the fastest-expanding technology segment as researchers prioritize sample throughput over single-analyte Western blotting. Academic research centers anchor volume demand through National Institutes of Health and European Research Council grant cycles, though biopharmaceutical developers concentrate margin pools through custom antibody development contracts tied to neurodegenerative therapeutic pipelines.
FDA biomarker qualification programs and the EU IVDR framework are tightening analytical validation standards for antibodies used in companion diagnostic contexts, directly influencing R&D allocation toward CLIA-grade reagent documentation. China's NMPA has accelerated review pathways for innovative neurological diagnostics, creating dual compliance obligations for multinational suppliers serving both Western and Asian regulatory environments. Stakeholders must monitor how FDA-EU regulatory divergence on antibody lot-release testing reshapes regional manufacturing footprints and sourcing strategies.
Market Dynamics
ISO 13485 certification rotation is redistributing competitive access across antibody suppliers, compressing margins for uncertified producers while elevating contract manufacturing demand from smaller reagent developers seeking regulatory compliance pathways.
Growth Catalysts
- FDA Biomarker Qualification Programs:Accelerated validation pathways for Alzheimer's and Parkinson's diagnostic reagents are pulling investment toward CLIA-grade antibody documentation and companion diagnostic development workflows.
- Multiplex Assay Adoption:Academic research centers in Germany and the United States are prioritizing high-throughput neural protein quantification over traditional Western blotting, expanding procurement of panel-based detection systems.
- China NMPA Accelerated Review:Streamlined neurological diagnostic approvals are creating dual-registration incentives for multinational suppliers, expanding manufacturing footprints to serve Asian and Western regulatory environments simultaneously.
Market Restraints
- Recombinant Rabbit Hybridoma Input Costs:Specialized cell line development and serum-free culture media volatility are elevating production costs for high-specificity monoclonal antibodies used in regulated diagnostic settings.
- EU IVDR Transition Friction:Stricter analytical validation requirements for in vitro diagnostic reagents are extending compliance timelines and concentrating supply among vertically integrated manufacturers with dedicated regulatory affairs infrastructure.
- Cross-Reactivity Technical Ceiling:Homologous neural protein sequence conservation limits specificity thresholds in certain antibody classes, constraining assay performance in complex tissue lysate applications.
Strategic Opportunities
- Underpenetrated Chinese Academic Procurement:National Natural Science Foundation funding expansion for neuroscience infrastructure is opening bulk reagent contracts previously captured by domestic catalog suppliers.
- AI-Assisted Epitope Prediction:Machine learning convergence with recombinant antibody engineering is compressing development cycles for novel neural target reagents, enabling faster customization for biopharmaceutical therapeutic pipelines.
- Direct-to-Laboratory Digital Distribution:E-procurement platforms are disintermediating traditional distributor networks, allowing specialized antibody developers to capture margin previously allocated to regional supply intermediaries.
Industry Challenges
- Antibody Validation Skill Scarcity:Specialized expertise in mass spectrometry-based confirmatory testing and knockdown validation protocols remains concentrated among senior scientists, constraining quality assurance throughput.
- Dual Certification Capex Burden:Simultaneous FDA and NMPA facility qualification requires redundant cleanroom infrastructure and separate lot-release testing workflows, elevating capital intensity for multinational suppliers.
- Legacy Assay Integration Complexity:Multiplex platforms face technical friction when interfacing with established ELISA workflows and LIMS systems in academic core facilities, slowing adoption despite performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neuroscience Antibodies and Assays Market |
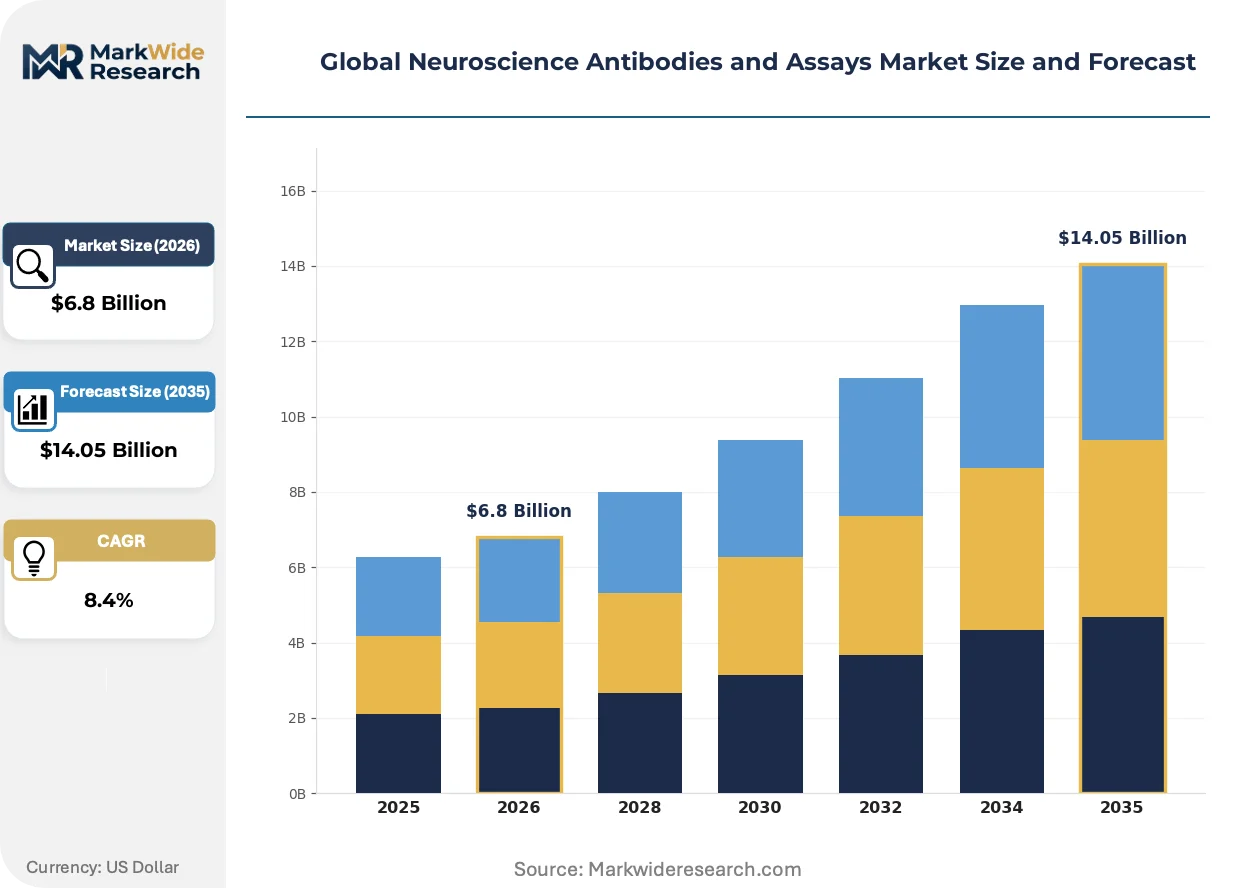
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Recombinant Antibodies, Sandwich Assays, Competitive Assays, Enzyme-linked Assays Application: Alzheimer’s Research, Parkinson’s Research, Neuroinflammation Studies, Neurodegenerative Diagnostics, Synaptic Protein Analysis, Neuropharmacology Testing End User: Academic Research Centers, Biopharmaceutical Developers, Diagnostic Laboratories, Neuroscience Institutes, Contract Research Organizations, Government Research Bodies Technology: ELISA, Western Blotting, Immunohistochemistry, Flow Cytometry, Multiplex Assays, Immunoprecipitation |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Merck KGaA, F. Hoffmann-La Roche, Cell Signaling Technology, Abcam, BioLegend, GenScript, Santa Cruz Biotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neuroscience Antibodies and Assays Market Shifts & Advancements
Recombinant antibody engineering is compressing traditional hybridoma dominance while regulatory convergence and procurement digitization are rewriting how reagents reach end-users across research and diagnostic workflows.
Single-cell B-cell receptor sequencing is fragmenting the traditional polyclonal antibody market by enabling direct cloning of validated immunoglobulin sequences from immunized rabbits. Contract research organizations in the United States and Germany are adopting this platform to compress custom antibody development timelines from months to weeks. The technology is fragmenting pricing power among catalog suppliers by reducing minimum order quantities and enabling boutique production runs for rare neural targets.
The EU IVDR framework is tightening post-market surveillance requirements for antibodies used in neurological diagnostic assays, mandating extended stability data and batch-to-batch consistency documentation. Manufacturers serving European clinical laboratories must now maintain dedicated quality management systems beyond ISO 13485, elevating compliance costs. This regulatory pressure is concentrating supply relationships among suppliers with established European notified body partnerships, disadvantaging newer market entrants.
Consolidated procurement through university system purchasing cooperatives is compressing vendor diversity in United States academic research. The University of California and Texas A&M Systems are negotiating enterprise-wide antibody contracts that prioritize validation depth and lot consistency over catalog breadth. This buyer concentration is visible most acutely in Alzheimer's research consortia, where standardized reagent procurement reduces experimental variability across multi-site studies.
Global Neuroscience Antibodies and Assays Market Segmentation
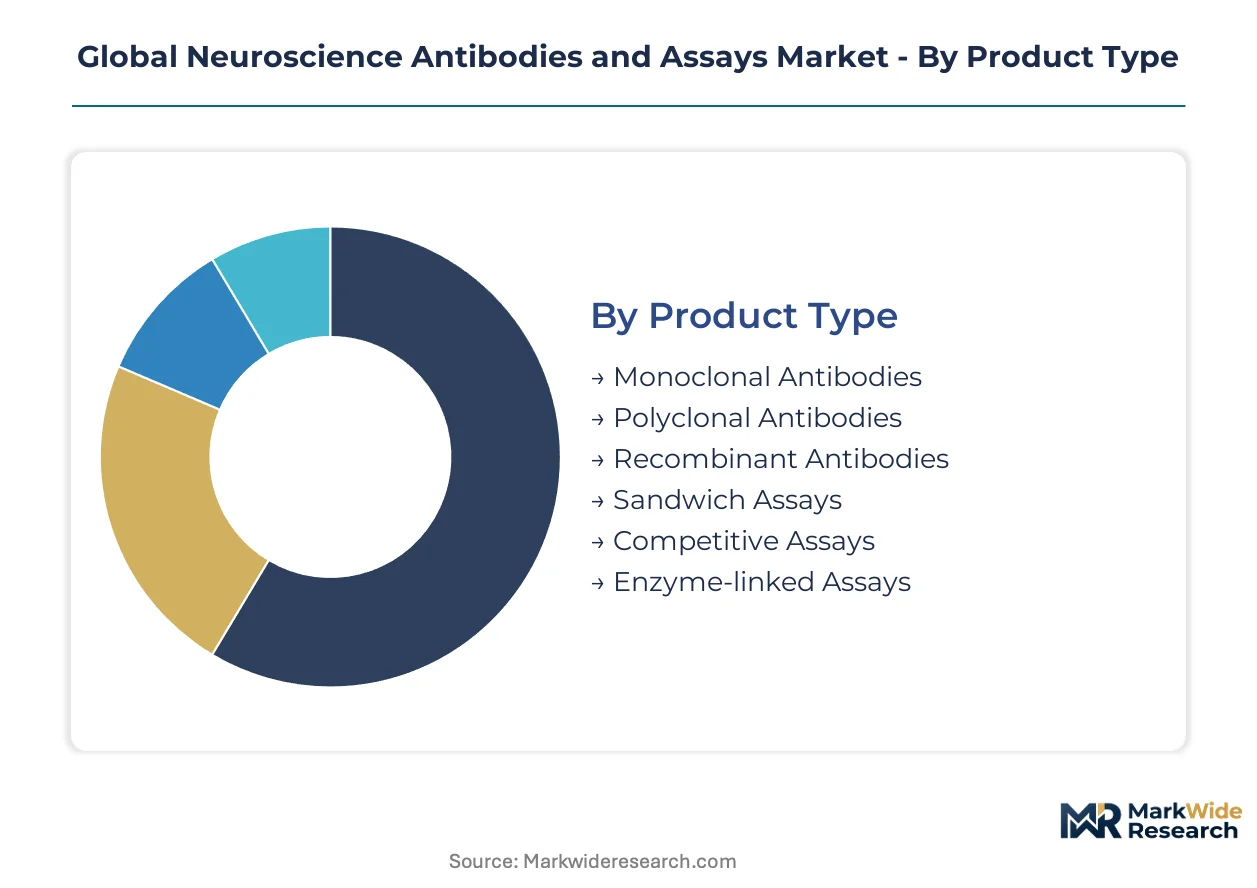
Neuroscience reagent procurement varies sharply by end-use context, with regulated diagnostic workflows demanding certified monoclonal batches while exploratory research tolerates polyclonal alternatives. Understanding these segment boundaries clarifies where pricing power concentrates and which technology transitions reshape supplier margins.
Product Type:
Monoclonal antibodies concentrate production in the United States and Germany where ISO 13485-certified facilities serve FDA and EU IVDR compliance requirements; polyclonal and recombinant formats show more dispersed manufacturing across China and India for research-grade supply.
- Monoclonal Antibodies:Affinity-purified immunoglobulins derived from single hybridoma clones deliver batch-to-batch consistency below 5% coefficient of variation. Demand clusters in diagnostic laboratories across the United States and Germany where FDA biomarker qualification programs mandate documented lot release testing for Alzheimer's companion diagnostic workflows.
- Recombinant Antibodies:Engineered sequences expressed in serum-free mammalian systems eliminate hybridoma instability while enabling humanization for therapeutic development. Biopharmaceutical developers in Boston and Basel prioritize these reagents for neurodegenerative pipeline target validation, accepting 40-60% cost premiums over traditional monoclonals.
- Polyclonal Antibodies:Heterogeneous immunoglobulin pools from immunized hosts retain broader epitope recognition for complex tissue lysate screening.
- Sandwich Assays:Dual-antibody capture-detection configurations dominate quantitative biomarker quantification in cerebrospinal fluid matrices.
- Competitive Assays:Small-molecule neurotransmitter detection relies on labeled ligand displacement from limited antibody binding sites.
- Enzyme-linked Assays:Chromogenic and chemiluminescent readout systems anchor high-throughput screening infrastructure in academic core facilities.
Monoclonal antibodies hold the largest share; momentum sits with recombinant antibodies as biopharmaceutical developers prioritize sequence-defined reagents for regulatory submission packages.
Application:
Alzheimer's research commands the steepest pricing tiers due to FDA qualification pathway investments, while neuroinflammation studies expand fastest in Chinese academic centers with National Natural Science Foundation infrastructure grants.
- Alzheimer's Research:Amyloid-beta and tau protein quantification drives demand for phosphorylation-state-specific antibodies with sub-nanomolar affinity. United States academic medical centers and biopharmaceutical consortia concentrate procurement through standardized reagent contracts that prioritize validation depth over catalog breadth.
- Neuroinflammation Studies:Microglial activation markers and cytokine profiling panels enable mechanistic exploration of neurodegenerative cascade initiation. German Max Planck Institutes and Chinese Academy of Sciences facilities are expanding multiplex assay procurement for high-throughput glial response characterization.
- Parkinson's Research:Alpha-synuclein oligomer-specific antibodies support Lewy body pathology investigation across European Research Council-funded consortia.
- Neurodegenerative Diagnostics:Clinical laboratory workflows require CLIA-grade reagents with extended stability documentation for routine testing.
- Synaptic Protein Analysis:Postsynaptic density protein quantification supports connectivity mapping in developmental neuroscience programs.
- Neuropharmacology Testing:Receptor occupancy assays guide CNS drug candidate selection in contract research organization screening pipelines.
Alzheimer's research commands premium pricing; neuroinflammation studies are climbing the fastest as funding priorities shift toward immune-neural interaction mechanisms.
End User:
Academic research centers anchor volume demand through NIH and ERC grant cycles, while biopharmaceutical developers concentrate margin pools through custom antibody development contracts with therapeutic pipeline tie-ins.
- Academic Research Centers:University core facilities and neuroscience departments procure catalog antibodies through system-wide purchasing cooperatives. The University of California and Texas A&M Systems negotiate enterprise contracts prioritizing lot consistency for multi-site Alzheimer's research reproducibility.
- Biopharmaceutical Developers:Therapeutic pipeline sponsors commission bespoke antibody generation against novel neural targets with exclusive licensing terms. Cambridge and Basel clusters drive custom recombinant antibody investment for neurodegenerative indication programs.
- Diagnostic Laboratories:Clinical testing facilities require IVDR-compliant reagents with validated analytical performance specifications.
- Neuroscience Institutes:Dedicated research institutes maintain specialized histology cores with immunohistochemistry-optimized antibody portfolios.
- Contract Research Organizations:Screening service providers demand high-throughput-compatible assay formats with rapid turnaround documentation.
- Government Research Bodies:National institute intramural programs sustain steady demand for reference standard antibodies.
Academic research centers dominate procurement volume; biopharmaceutical developers generate the steepest margin expansion through exclusive development agreements.
Technology:
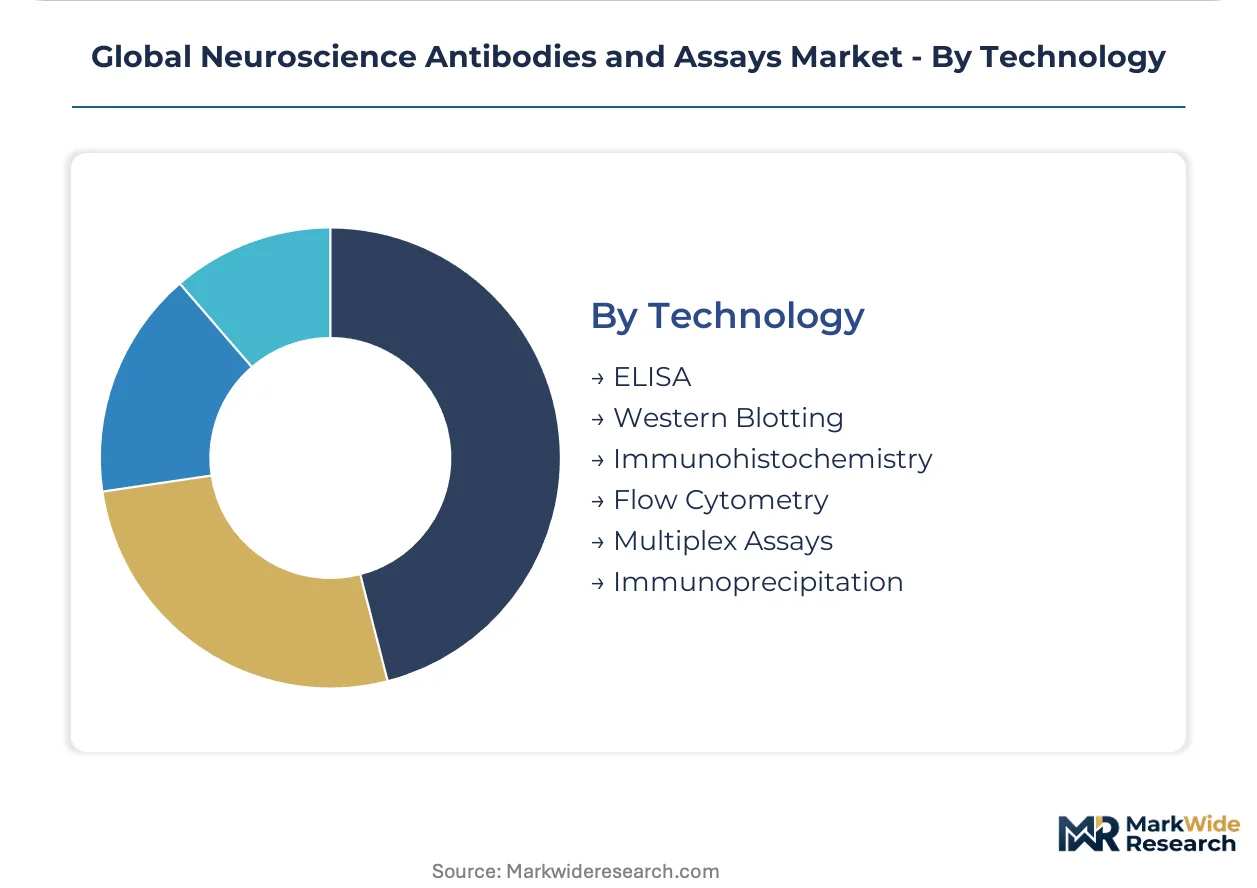
ELISA and Western blotting retain installed base dominance in legacy academic workflows, while multiplex assays displace single-analyte methods in Germany and United States centers prioritizing sample throughput.
- Multiplex Assays:Panel-based detection systems simultaneously quantify 10-50 neural protein targets from limited cerebrospinal fluid or tissue biopsy volumes. German academic centers and United States Alzheimer's Disease Research Centers are prioritizing Luminex and Meso Scale Discovery platforms for biomarker signature validation.
- Immunohistochemistry:Chromogenic and fluorescent tissue staining enables spatial protein localization with cellular resolution. Neuropathology laboratories in Boston and Munich maintain high antibody consumption for post-mortem diagnostic confirmation.
- ELISA:Enzyme-linked immunosorbent assay formats retain cost advantages for single-analyte quantification in high-volume screening.
- Western Blotting:Gel-based protein separation with antibody detection persists in exploratory research for novel target discovery.
- Flow Cytometry:Single-cell suspension analysis supports neural stem cell and microglial phenotyping applications.
- Immunoprecipitation:Target enrichment from complex lysates enables mass spectrometry-based interaction mapping.
ELISA holds the largest installed base; multiplex assays are gaining share fastest as throughput requirements reshape procurement priorities in funded neuroscience consortia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA biomarker qualification programs and the EU IVDR transition are redirecting procurement toward certified suppliers, while China's NMPA accelerated review pathways create dual-registration incentives for multinational reagent developers.
United States
NIH grant cycles and Alzheimer's Disease Research Center consortia sustain bulk antibody procurement through system-wide purchasing cooperatives. FDA companion diagnostic guidance mandates CLIA-grade documentation for tau and amyloid-beta reagents. Boston and San Diego biopharma clusters commission custom recombinant antibodies for neurodegenerative therapeutic pipelines.
Germany
Max Planck Institutes and European Research Council-funded neuroscience programs prioritize multiplex assay platforms for high-throughput glial response characterization. EU IVDR post-market surveillance requirements extend stability documentation obligations for clinical laboratory suppliers. Munich and Heidelberg anchor production of ISO 13485-certified monoclonal batches for regulated diagnostic workflows.
China
National Natural Science Foundation infrastructure grants expand academic procurement previously captured by domestic catalog suppliers. NMPA streamlined neurological diagnostic approvals compress registration timelines for innovative assay formats. Shanghai and Beijing biotech parks attract contract manufacturing investment from Western suppliers seeking dual-regulatory compliance.
United Kingdom
Medical Research Council neuroscience funding sustains demand for reference standard antibodies across academic core facilities. MHRA alignment with EU IVDR standards preserves market access for continental-certified reagents post-Brexit. Cambridge and Oxford therapeutic clusters drive custom antibody development for neurodegenerative indication programs.
Japan
PMDA neurological diagnostic reviews emphasize analytical validation for cerebrospinal fluid biomarker quantification. METI life science innovation programs subsidize recombinant antibody engineering capabilities for domestic suppliers. Tokyo and Osaka academic medical centers maintain specialized histology cores with immunohistochemistry-optimized portfolios.
Global Neuroscience Antibodies and Assays Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with captive antibody production infrastructure. Mid-scale catalog specialists and regional contract manufacturers occupy secondary tiers. Strategic archetypes include vertically integrated platform providers, recombinant engineering boutiques, and compliance-focused contract manufacturers. Competitive moves concentrate on M&A for regulatory certification assets and strategic partnerships for Asian distribution access.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA occupy positions sustained by global distribution networks and in-house hybridoma facilities. Abcam exemplifies the recombinant specialization archetype, with rabbit monoclonal validation depth differentiating premium positioning. Bio-Rad Laboratories anchors the analytical instrumentation-integrated segment, where assay platform installed bases drive recurring reagent pull-through. These three represent distinct competitive vectors: scale-driven supply security, sequence-defined product differentiation, and platform-locked consumable demand.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Merck KGaA |
| F. Hoffmann-La Roche |
| Cell Signaling Technology |
| Abcam |
| BioLegend |
| GenScript |
| Santa Cruz Biotechnology |
| Others |
Supply & Pricing Matrix
Recombinant rabbit hybridoma technology replacing traditional murine hybridoma systems is redistributing production capacity toward Germany and the United States while elevating input costs for serum-free culture media and specialized cell line development. This substitution dynamic compresses margins for uncertified catalog suppliers unable to absorb regulatory compliance investments, concentrating pricing power among ISO 13485-certified facilities serving FDA biomarker qualification and EU IVDR diagnostic workflows.
Pricing Analysis
Certification level creates the primary spread between CLIA-grade diagnostic reagents and research-grade catalog alternatives, with FDA-qualification-ready monoclonal antibodies commanding 40-60% premiums over uncertified equivalents. Three-tier pricing structure across premium recombinant, standard monoclonal, and economy polyclonal levels reflects validation depth and lot-to-lot consistency documentation. Cost compression in the polyclonal tier is intensifying because single-cell B-cell receptor sequencing enables boutique production runs that fragment traditional catalog pricing power. Academic research centers through NIH-funded consortia exhibit highest price sensitivity, while biopharmaceutical developers in Boston and Basel therapeutic clusters prioritize sequence-defined reagents regardless of cost premium.
Supply Chain Analysis
Inventory lead times for ISO 13485-certified monoclonal batches extend substantially beyond research-grade polyclonal alternatives due to lot-release testing and stability documentation requirements. Manufacturing concentrates in the United States, Germany, and China, with Munich and Heidelberg anchoring European clinical-grade production while Shanghai biotech parks attract contract manufacturing investment from Western suppliers seeking NMPA dual-registration. Supply chains draw from recombinant expression systems, serum-free culture media, and affinity chromatography resins as critical inputs. Single-source vulnerability around validated hybridoma cell lines creates concentration risk when academic consortia standardize on specific antibody clones. Distribution runs through university system purchasing cooperatives and direct-to-laboratory digital platforms that disintermediate traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global neuroscience antibodies and assays markets are entering a cyclical recovery phase as NIH and European Research Council grant cycles refresh following pandemic-era funding compression, with Alzheimer's Disease Research Center infrastructure investments providing the primary demand pulse.
For Market Incumbents: Compound defensive positioning through captive recombinant antibody engineering capabilities and exclusive biopharmaceutical development partnerships that lock in therapeutic pipeline tie-ins. Deepen backward integration into single-cell B-cell receptor sequencing platforms to compress custom development timelines from months to weeks, neutralizing emerging boutique competitors. Prioritize ISO 13485 certification maintenance and EU notified body relationship investment as IVDR post-market surveillance requirements extend compliance timelines for smaller rivals.
For New Entrants and Emerging Players: Anchor in underpenetrated Chinese academic procurement channels where National Natural Science Foundation infrastructure grants are expanding bulk reagent contracts previously captured by domestic catalog suppliers. Target neuroinflammation research applications as the fastest-climbing segment with multiplex assay format specialization. Pursue AI-assisted epitope prediction capabilities as the primary go-to-market angle, offering compressed development cycles for novel neural targets that incumbent hybridoma infrastructure cannot match.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract research organizations possessing validated antibody development platforms but lacking diagnostic-grade certification infrastructure. Five-to-ten year viability hinges on regulatory convergence between FDA biomarker qualification pathways and NMPA accelerated review frameworks creating dual-compliance value. Monitor EU IVDR notified body partnership announcements as the critical inflection signal for certification-constrained supply consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | ISO 13485 and EU IVDR compliance unlocks CLIA-grade diagnostic reagent contracts with Alzheimer's Disease Research Centers. |
| AI-Assisted Epitope Engineering | Machine learning convergence compresses recombinant antibody development cycles for biopharmaceutical therapeutic pipelines. |
| Direct-to-Laboratory Digital Distribution | E-procurement platforms disintermediate regional distributors, capturing margin previously allocated to supply intermediaries. |
| Dual-Registration Manufacturing Footprint | Simultaneous FDA and NMPA facility qualification enables access to United States and Chinese diagnostic markets. |
| Multiplex Assay Platform Integration | Panel-based detection systems align with German Max Planck Institute high-throughput procurement priorities. |
Research Methodology
A standing panel of antibody development scientists, regulatory affairs directors at IVD manufacturers, academic core facility procurement managers, and biopharmaceutical target validation leads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA biomarker qualification program filings, EU IVDR technical documentation databases, NIH RePORTER grant award records, and NMPA neurological diagnostic approval registries. Bottom-up segment sizing triangulated against top-down market envelope checks from trade customs data and life science distributor revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, application, end user, technology, and regional regulatory cluster as primary segmentation dimensions. CAGRs derived from grant funding trajectory analysis, therapeutic pipeline progression rates, and diagnostic laboratory capital expenditure patterns rather than simple trend extrapolation. Recombinant antibody adoption curves and multiplex assay displacement rates served as industry-specific forecast sensitivity inputs.
Material uncertainties — regulatory divergence between FDA and EU IVDR on antibody lot-release testing, serum-free culture media price volatility, and hybridoma cell line patent expiration schedules — sit outside the modeled envelope. Forecasts reflect assumptions about sustained NIH and European Research Council funding levels, NMPA review pathway stability, and biopharmaceutical neurodegenerative pipeline investment continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Global Organoids Market
Biomedical Technology
Cell Disrupters Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Antibody Library Technology Market
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
Global Cell Based Assays Market
Biomedical Technology
Northern Blotting Market
Biomedical Technology
Fluorescence in-Situ Hybridization Probe Market
Biomedical Technology
Strand Displacement Amplicon (SDA) Market
Biomedical Technology
Inhalable Biologics Market
Biomedical Technology
Bead-Based Flow Cytometry Market
Biomedical Technology
Bioadhesive Microspheres Market