
 Biobank Market | 2026-2036
Biobank Market Size, Share, and Industry Trends Forecast 2026-2036
Biobank Market Analytics
The EU Green Deal is broadening sustainability mandates for cold-chain biobank infrastructure across European research networks. Thermo Fisher Scientific leverages its cryogenic storage portfolio to anchor large-scale biorepository contracts in North America and Europe. Qiagen sustains competitive differentiation through integrated sample-to-insight workflows that span nucleic acid stabilization and analytics.
A biobank is a structured repository that collects, processes, stores, and distributes biological specimens and associated data under controlled conditions, typically maintaining samples at temperatures ranging from minus 196 degrees Celsius in liquid nitrogen to minus 80 degrees Celsius in mechanical freezers for long-term viability. Its primary purpose is to enable reproducible research, therapeutic development, and diagnostic validation by preserving specimen integrity and chain-of-custody documentation. Blood samples dominate current repository volumes due to routine collection protocols and broad analytical utility across disease research and clinical trials. Cryogenic storage commands premium infrastructure investment because liquid nitrogen systems deliver unmatched temperature stability for irreplaceable specimens, while ambient temperature technologies are gaining traction for DNA and RNA applications where ultralow cold chain costs prove prohibitive.
The US FDA, the European Medicines Agency, and ISO 20387 biobanking standards collectively govern specimen quality, informed consent protocols, and cross-border data transfer requirements that determine market access for repository operators and technology vendors. HIPAA in the United States and GDPR in Europe impose stringent de-identification and donor privacy obligations that shape biobank information system architecture and compliance spending. Stakeholders must monitor evolving AI governance frameworks and harmonization efforts between national biobank networks to anticipate where regulatory alignment or fragmentation will reshape competitive positioning.
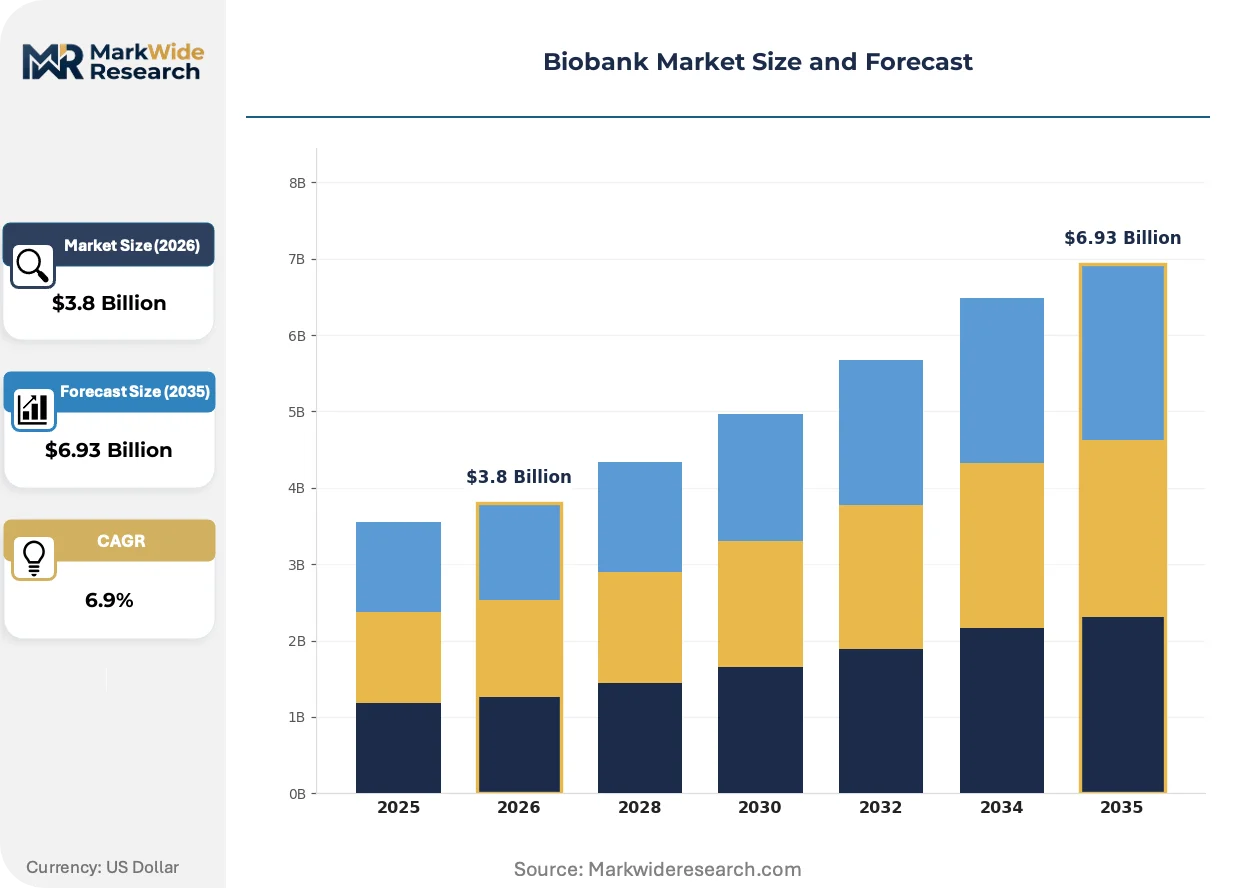
Market Dynamics
Pharmaceutical companies are expanding biobank utilization for precision drug pipelines, while the EU AI Act and GDPR compliance requirements are reshaping data governance frameworks for cross-border sample sharing.
Growth Catalysts
- Precision medicine pipelines:Pharmaceutical manufacturers require biorepository infrastructure to support biomarker-driven drug development and companion diagnostic validation.
- ISO 20387 standardization:Harmonized quality management protocols are reducing interoperability barriers between national biobank networks and accelerating specimen exchange.
- Population-scale cohort studies:Germany's centralized biobank networks are demonstrating operational models that other European research consortia are replicating.
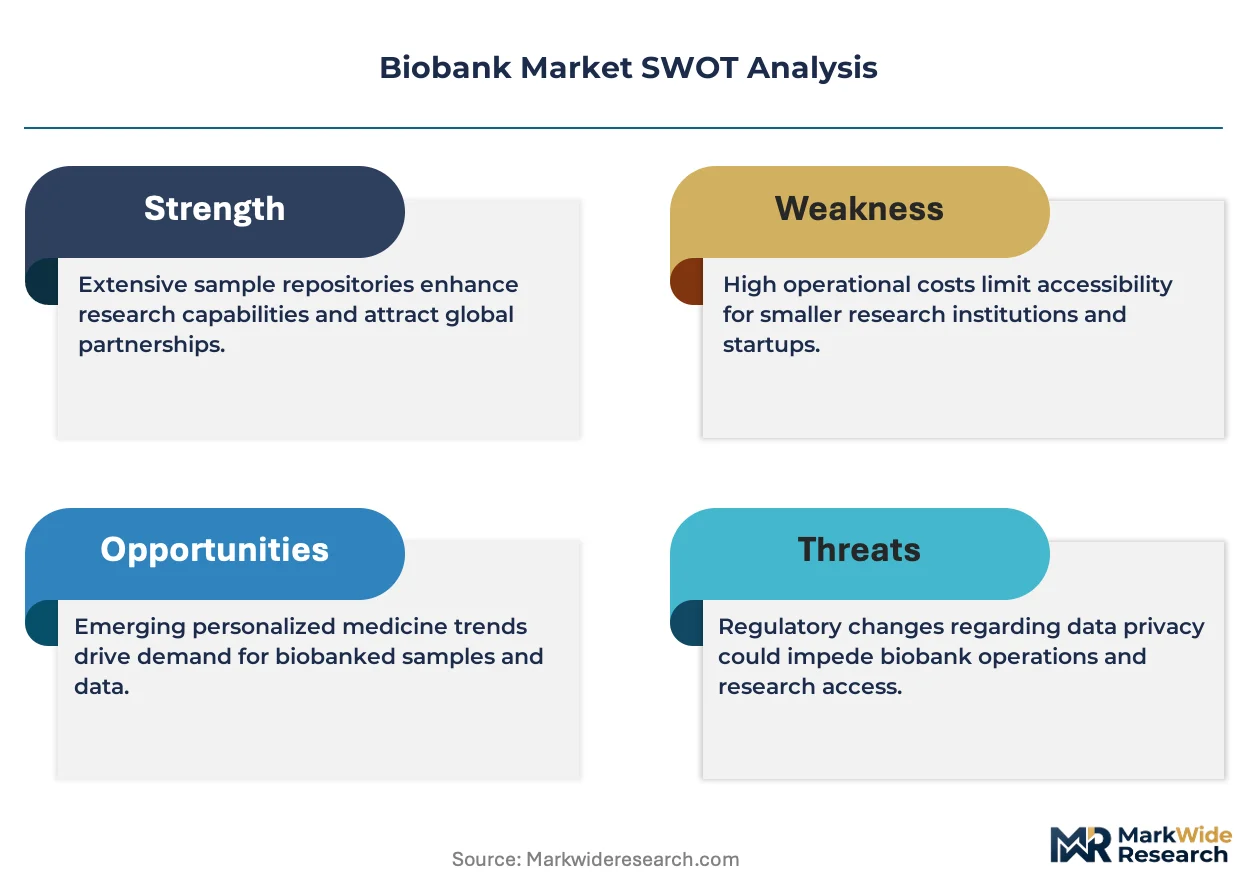
Market Restraints
- Liquid nitrogen supply volatility:Cryogenic infrastructure depends on industrial gas supply chains concentrated in limited production geographies, exposing operators to input cost fluctuations.
- Cross-border data friction:GDPR's strict data-localization requirements create structural barriers to multinational research collaborations requiring centralized bioinformatics analysis.
- Ambient temperature DNA storage:Dried biospecimen technologies are substituting ultralow cold-chain requirements for specific nucleic acid applications, compressing demand for mechanical freezer infrastructure.
Strategic Opportunities
- AI-enabled sample curation:Machine learning algorithms are converging with automated storage retrieval systems to optimize specimen selection for research queries.
- Emerging market biorepository buildout:India's CDSCO is establishing national biobank frameworks that create first-mover advantages for infrastructure providers.
- EU Green Deal cold-chain mandates:Sustainability requirements for research infrastructure are creating demand for energy-efficient cryogenic systems and carbon-neutral liquid nitrogen sourcing.
Industry Challenges
- Bioinformatics talent scarcity:The intersection of specimen science, data governance, and AI tool deployment requires hybrid skill sets that remain underrepresented in labor markets.
- Legacy system integration:Established biobanks operate decades-old inventory management platforms that resist seamless connection to modern LIMS and federated query networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biobank Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.93 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sample Type: Biospecimens, Blood Samples, Urine Samples, Tissue Samples Storage Technology: Liquid Nitrogen, Mechanical Freezers, Cryogenic Storage, Ambient Temperature End User: Research Institutions, Hospitals, Pharmaceutical Companies, Diagnostic Labs Application: Personalized Medicine, Drug Development, Disease Research, Clinical Trials |
| Companies Covered | Thermo Fisher Scientific, Qiagen, Merck KGaA, Becton, Dickinson and Company, Lonza Group AG, Stemcell Technologies, Guardant Health, PHC Holdings Corporation, Hamilton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biobank Market Evolving Landscape
Automation and artificial intelligence are transforming how biorepositories manage specimen integrity, inventory optimization, and researcher access. Three developments are compressing operational timelines and expanding analytical possibilities.
Automated sample handling systems are overtaking manual retrieval processes in high-throughput biorepositories. Academic medical centers and contract research organizations are deploying robotic storage and retrieval platforms to reduce freeze-thaw cycles. This technology is overtaking labor-intensive workflows while enabling 24-hour specimen access for distributed research teams.
The EU AI Act's risk-classification framework for medical AI is imposing new documentation burdens on biobanks supplying training data for diagnostic algorithms. Biorepository operators must now maintain enhanced provenance records for specimens used in machine-learning model development. European research networks are responding by embedding AI governance checkpoints into their existing ISO 20387 quality management systems.
Research institutions are consolidating procurement around integrated sample-to-insight service contracts rather than discrete storage rentals. This bundling displaces point-solution vendors and favors partners offering nucleic acid stabilization, sequencing, and bioinformatics analysis alongside physical infrastructure. The shift is most visible in North American academic medical centers where principal investigators face compressed grant timelines.
Biobank Market Segmentation
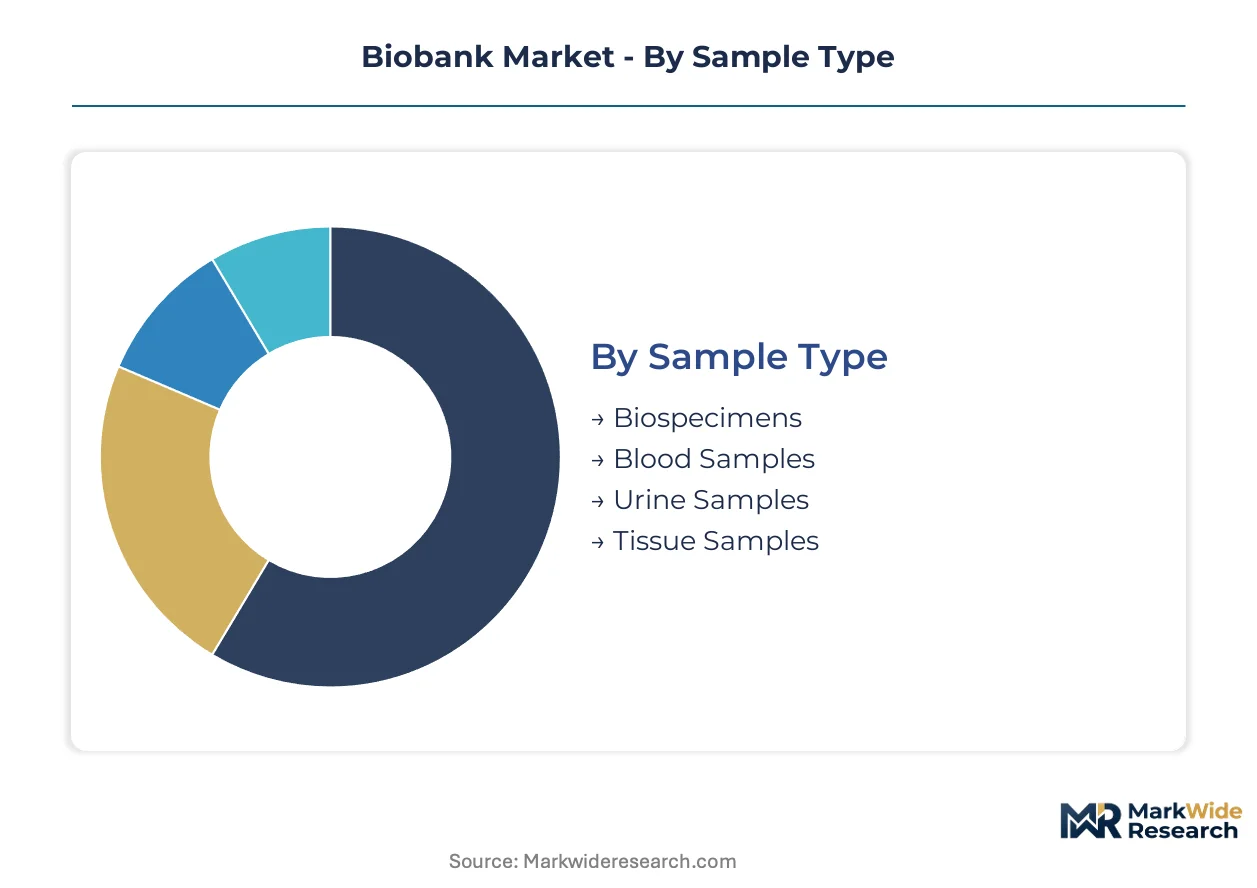
Biobank market segmentation reveals distinct operational models and value-chain positioning that determine procurement patterns and infrastructure investment priorities across specimen types, storage technologies, end users, and applications.
Sample Type:
Standalone repositories dominate high-volume blood and tissue banking, while embedded biobanks within academic medical centers concentrate urine and specialized biospecimen collections.
- Biospecimens:Umbrella category encompassing cells, DNA, RNA, and protein extracts preserved for genomic and proteomic analysis. Demand clusters in pharmaceutical biomarker programs requiring nucleic acid integrity for companion diagnostic development.
- Blood Samples:Plasma, serum, and whole blood constitute the highest-throughput repository category due to standardized collection protocols and broad analytical utility across immunology and hematology research. Germany's centralized biobank networks demonstrate population-scale operational efficiency with this specimen type.
- Urine Samples:Non-invasive collection drives metabolic and renal research applications. Academic medical centers in the United States embed these collections within longitudinal cohort studies.
- Tissue Samples:Solid tumor and normal tissue specimens require specialized fixation and processing workflows. Pathology departments at major hospitals maintain embedded repositories for oncology research.
Blood samples lead volumes today; biospecimens are gaining share fastest.
Storage Technology:
Cost tier differentiation separates premium cryogenic systems from standard mechanical freezing and emerging ambient alternatives.
- Liquid Nitrogen:Minus 196 degrees Celsius vapor-phase systems deliver unmatched temperature stability for irreplaceable cell lines and primary tissues. Long-term biorepositories at the US National Cancer Institute depend on this technology for irreplaceable legacy collections.
- Mechanical Freezers:Minus 80 degrees Celsius units serve high-throughput research operations with lower capital and operating costs than liquid nitrogen infrastructure. Contract research organizations favor these systems for clinical trial specimen management.
- Cryogenic Storage:Automated liquid nitrogen-based systems integrate robotic retrieval with inventory management for 24-hour specimen access. Thermo Fisher Scientific anchors large-scale contracts with this integrated infrastructure.
- Ambient Temperature:Dried biospecimen technologies eliminate cold-chain dependencies for DNA and RNA applications where ultralow storage costs prove prohibitive. India's CDSCO national biobank framework incorporates these systems for decentralized collection networks.
Mechanical freezers lead volumes today; ambient temperature solutions are climbing the fastest.
End User:
Customer type determines service model complexity, with pharmaceutical companies demanding integrated sample-to-insight contracts versus standalone storage rentals from academic institutions.
- Research Institutions:Universities and academic medical centers operate the largest installed base of legacy biorepositories. Principal investigators face compressed grant timelines that favor bundled procurement of stabilization, sequencing, and analysis services.
- Hospitals:Clinical biobanks embedded within healthcare systems prioritize diagnostic validation and translational research. European hospital networks under GDPR jurisdiction invest heavily in de-identification and chain-of-custody documentation systems.
- Pharmaceutical Companies:Biomarker-driven drug development requires biorepository infrastructure for companion diagnostic validation. Precision medicine pipelines at major manufacturers are expanding dedicated biobank utilization.
- Diagnostic Labs:Commercial laboratories maintain specimen collections for assay development and quality control. These operations concentrate in regulated markets with established ISO 20387 quality management adoption.
Research institutions lead volumes today; pharmaceutical companies are expanding most quickly.
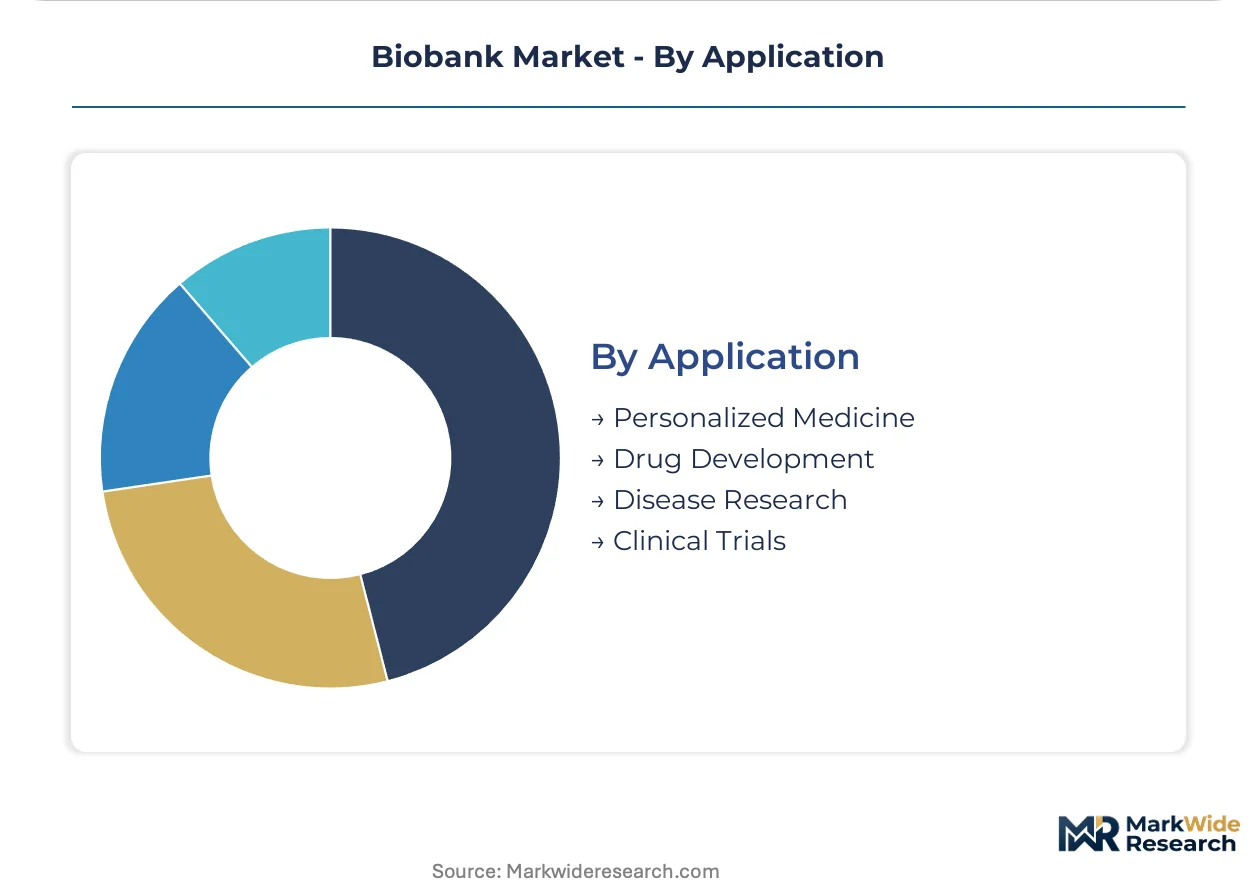
Application:
Maturity stage varies across applications, with disease research representing established practice while personalized medicine drives next-generation infrastructure requirements.
- Personalized Medicine:Patient stratification and targeted therapy selection require biobanks with linked clinical and genomic data. The EU AI Act imposes new documentation burdens on repositories supplying training data for diagnostic algorithms.
- Drug Development:Biomarker discovery and clinical pharmacology studies depend on longitudinal specimen collections with robust provenance tracking. Pharmaceutical manufacturers require ISO 20387-compliant networks for multinational trial support.
- Disease Research:Population-scale cohort studies and case-control collections constitute the foundational biobank application. Germany's centralized networks demonstrate operational models replicated across European research consortia.
- Clinical Trials:Phase I-IV studies require specimen logistics, processing, and storage under regulatory inspection readiness. Contract research organizations compete on integrated service bundling for sponsor biopharma clients.
Disease research leads volumes today; personalized medicine shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scientific workforce concentrations in Germany, the United States, Japan, and India anchor biobank infrastructure investment. Regulatory frameworks in each geography determine cross-border collaboration feasibility. Urban research clusters concentrate specimen processing capacity and bioinformatics talent.
Germany
Centralized biobank networks support population-scale cohort studies requiring standardized specimen protocols. The EU AI Act imposes documentation burdens on repositories supplying training data for diagnostic algorithms. Berlin and Heidelberg host embedded academic biorepositories integrating automated storage retrieval with longitudinal clinical data.
United States
Pharmaceutical manufacturers expand dedicated biobank utilization for biomarker-driven drug development pipelines. HIPAA mandates stringent de-identification and donor privacy obligations shaping information system architecture. The National Cancer Institute's biorepositories in Maryland and Texas depend on liquid nitrogen vapor-phase systems for irreplaceable legacy collections.
Japan
PMDA regulatory pathways accelerate specimen-based companion diagnostic validation for precision medicine applications. METI supports national biobank framework development harmonizing with ISO 20387 quality standards. Tokyo and Osaka academic medical centers deploy integrated sample-to-insight contracts bundling stabilization, sequencing, and bioinformatics analysis.
India
CDSCO establishes national biobank frameworks creating infrastructure opportunities for decentralized collection networks. Ambient temperature DNA storage technologies eliminate cold-chain dependencies for specific nucleic acid applications. Hyderabad and Bengaluru research clusters incorporate dried biospecimen systems for population-scale genomic studies.
United Kingdom
Research institutions consolidate procurement around bundled service contracts displacing point-solution vendors. GDPR strict data-localization requirements create structural barriers to multinational research collaborations requiring centralized bioinformatics analysis. Cambridge and London biorepositories embed AI governance checkpoints into existing quality management systems.
Biobank Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the biobank infrastructure landscape. The vendor base separates between integrated platform providers and specialized component suppliers. Three strategic archetypes dominate: diversified life science conglomerates anchoring large-scale contracts, workflow automation specialists, and cryogenic engineering purists. Competitive positioning depends on M&A activity consolidating sample-to-insight capabilities and strategic partnerships securing liquid nitrogen supply chain resilience.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA exemplify integrated platform strategies spanning cryogenic storage hardware through analytical reagents. Qiagen occupies a position representing workflow automation specialists with nucleic acid stabilization and analytics integration. These three entities anchor competitive dynamics as research institutions and pharmaceutical manufacturers consolidate procurement around bundled service contracts rather than discrete component purchases.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Qiagen |
| Merck KGaA |
| Becton, Dickinson and Company |
| Lonza Group AG |
| Stemcell Technologies |
| Guardant Health |
| PHC Holdings Corporation |
| Hamilton Company |
| Others |
Value Network & Pricing Analysis
Ambient temperature DNA storage technology is compressing cost economics for nucleic acid preservation while simultaneously fragmenting supply concentration away from cryogenic equipment manufacturers toward dried biospecimen chemistry providers. This dual shift reconfigures procurement power across research institutions and pharmaceutical sponsors evaluating infrastructure investments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates liquid nitrogen vapor-phase systems from mechanical freezers and ambient temperature alternatives. Price differentiation hinges on ISO 20387 certification grade and after-sales service bundling for automated retrieval systems. Cost compression in the mechanical freezer tier is intensifying because India's CDSCO framework validates ambient alternatives for population-scale collections. Academic medical centers exhibit highest price sensitivity; pharmaceutical manufacturers prioritize provenance documentation over unit cost.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and the EU Green Deal sustainability requirements are reshaping sourcing patterns for cryogenic infrastructure components. Manufacturing concentrates in Germany, the United States, and Japan for precision-engineered storage systems. Raw material dependencies span specialized aluminum alloys for vacuum insulation, industrial-grade liquid nitrogen, and robotic retrieval mechanisms. Single-source vulnerability persists in liquid nitrogen supply chains concentrated in limited production geographies. Distribution runs through direct manufacturer relationships with academic consortia and pharmaceutical procurement alliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where pharmaceutical precision medicine pipelines demand premium specimen integrity standards over commodity storage rentals. The shift toward biomarker-driven drug development elevates documentation and chain-of-custody specifications as primary procurement criteria.
For Market Incumbents: Acquire automated storage retrieval technology specialists to fortify integrated sample-to-insight positioning against workflow automation specialists. Invest in ISO 20387 certification infrastructure across European networks before GDPR-EU AI Act convergence tightens compliance thresholds. Establish captive liquid nitrogen supply agreements to mitigate industrial gas cost volatility threatening margin stability in cryogenic service contracts. For New Entrants and Emerging Players: Mid-tier contract research organizations in India offer the most penetrable buyer archetype for ambient temperature DNA storage solutions validated under CDSCO national biobank frameworks. Target decentralized collection networks requiring elimination of cold-chain dependencies for rural specimen logistics. Lead with dried biospecimen chemistry expertise rather than competing head-to-head with Thermo Fisher Scientific's cryogenic installed base. For Investors and Strategic Acquirers: Valuations sit cheapest among workflow automation specialists possessing nucleic acid stabilization IP but lacking physical infrastructure scale. Five-to-ten year viability favors platforms combining specimen science with AI governance documentation capabilities. Monitor EU AI Act implementation timelines as the inflection signal for enhanced provenance record-keeping demand across European research networks.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20387 Certification Investment | European biobank networks require harmonized quality management for cross-border specimen exchange under EMA guidelines. |
| AI Governance Checkpoint Integration | Repositories supplying training data for diagnostic algorithms must embed EU AI Act compliance into existing quality systems. |
| Liquid Nitrogen Supply Security | Long-term industrial gas agreements protect cryogenic operators from input cost fluctuations concentrated in limited geographies. |
| Ambient Temperature Portfolio Expansion | CDSCO-validated dried biospecimen technologies address cost prohibitions in India's decentralized collection networks. |
| Sample-to-Insight Service Bundling | Academic medical centers facing compressed grant timelines consolidate procurement around integrated stabilization-sequencing-analysis contracts. |
Research Methodology
Multiple input streams — biorepository operations directors, pharmaceutical biomarker program leads, regulatory affairs specialists at EMA-notified bodies, and cryogenic engineering procurement managers — were reconciled against secondary validation from FDA biorepository guidance documents, EMA quality management submissions, ISO 20387 certification registries, and ClinicalTrials.gov specimen collection protocols. Bottom-up facility capacity estimates and top-down pharmaceutical R&D spending allocations were cross-referenced to triangulate market sizing.
Historical capacity deployment patterns were cross-referenced against panel input from biobank network coordinators to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include specimen type, storage technology tier, end-user archetype, and application maturity stage. CAGRs were derived from pharmaceutical pipeline expansion trajectories and population-scale cohort study funding commitments. Forecast inputs incorporated EU AI Act implementation schedules and CDSCO national biobank framework rollout timelines.
Underlying measurement precision varies by segment; blood sample and mechanical freezer categories carry tighter precision than emerging ambient temperature applications. Forecasts reflect assumptions around regulatory harmonization progress and industrial gas supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
Biotech API Manufacturing Services Market
Biotechnology Services
Vaccine and Biologic Product Distribution Optimization Services Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
Global Downstream Processing Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Prokaryotic Expression Systems Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Drug Discovery Services Market
Biotechnology Services
Plant Tissue Culture Products Market