
 Luciferase Assay Market | 2026-2036
Luciferase Assay Market Size, Share, and Industry Trends Forecast 2026-2036
Luciferase Assay Market Analysis
Multi-source procurement of luciferase reagents is decoupling from traditional single-vendor contracts in large pharma workflows. Promega Corporation leverages its vertically integrated enzyme production to sustain kit consistency across global distribution channels. Thermo Fisher Scientific anchors its position through broad catalog breadth that spans detection systems and imaging hardware. Merck KGaA differentiates via stringent quality certifications that appeal to European regulatory environments.
A luciferase assay is a biochemical test that uses light-emitting enzymes—primarily firefly Photinus pyralis or engineered NanoLuc variants—to quantify ATP, reporter gene expression, or protein-protein interactions through photon detection with luminometers or CCD imaging systems. Firefly luciferase products dominate current revenue owing to decades of protocol standardization in drug discovery labs, while NanoLuc formats represent the fastest-expanding segment due to superior signal stability and smaller genetic footprint in cellular assays. Application demand skews heavily toward drug discovery workflows, where pharmaceutical companies and contract research organizations consume bulk reagent volumes for high-throughput screening campaigns.
The FDA enforces current Good Manufacturing Practice standards for assay components used in IND-enabling studies, compelling reagent suppliers to maintain batch-to-batch documentation. The EPA monitors chemical waste streams from bioluminescence imaging facilities, particularly aqueous reagent disposal protocols in high-volume screening centers. ISO 13485 certification requirements shape market access for vendors targeting in-vitro diagnostic applications. Stakeholders must track evolving EMA guidance on cell-based potency assays, as alignment across FDA and European standards will determine which detection platforms achieve broad regulatory acceptance.
Market Dynamics
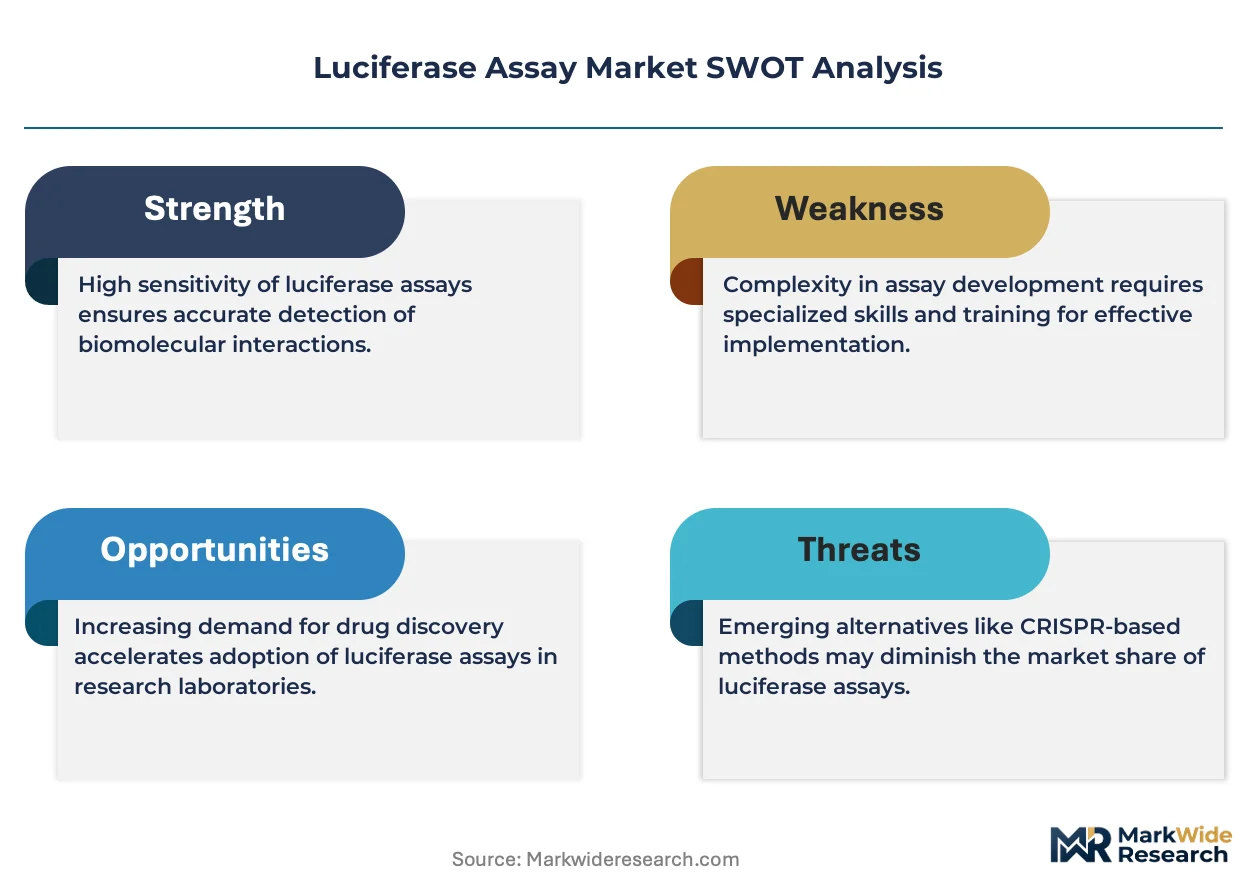
Pharmaceutical workflows are fragmenting their luciferase reagent sourcing away from sole-source agreements toward multi-vendor portfolios, destabilizing long-term contract economics while creating procurement complexity for high-throughput screening operations.
Growth Catalysts
- High-throughput screening expansion:Contract research organizations in Boston and San Diego biotech clusters are scaling automated detection infrastructure for drug discovery pipelines.
- FDA assay validation guidance:Updated cell-based assay standards are compelling standardized reagent kit adoption across IND-enabling studies.
- NanoLuc enzyme engineering:Smaller genetic footprint and superior signal stability are accelerating cellular assay protocol redesigns.
Market Restraints
- Enzyme production concentration:Captive supply chains for recombinant luciferase enzymes concentrate in specialized biomanufacturing hubs, exposing buyers to single-source risk.
- Batch-to-batch documentation burden:Current Good Manufacturing Practice standards for IND components impose compliance costs that squeeze mid-tier reagent vendors.
- Aqueous reagent disposal protocols:EPA monitoring of bioluminescence imaging waste streams adds operational friction for high-volume screening centers.
Strategic Opportunities
- In-vitro diagnostic certification pathway:ISO 13485 compliance unlocks clinical laboratory demand beyond research applications.
- EMA-FDA alignment on potency assays:Harmonized cell-based assay standards will favor detection platforms achieving dual regulatory acceptance.
- Protein-protein interaction screening:NanoLuc-based complementation assays are penetrating structural biology workflows previously served by fluorescence resonance energy transfer methods.
Industry Challenges
- Multi-vendor integration complexity:Decoupled procurement of enzymes, substrates, and detection hardware creates protocol standardization gaps in large pharma workflows.
- Biomanufacturing talent scarcity:Recombinant enzyme production requires specialized fermentation expertise that outpaces current training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luciferase Assay Market |
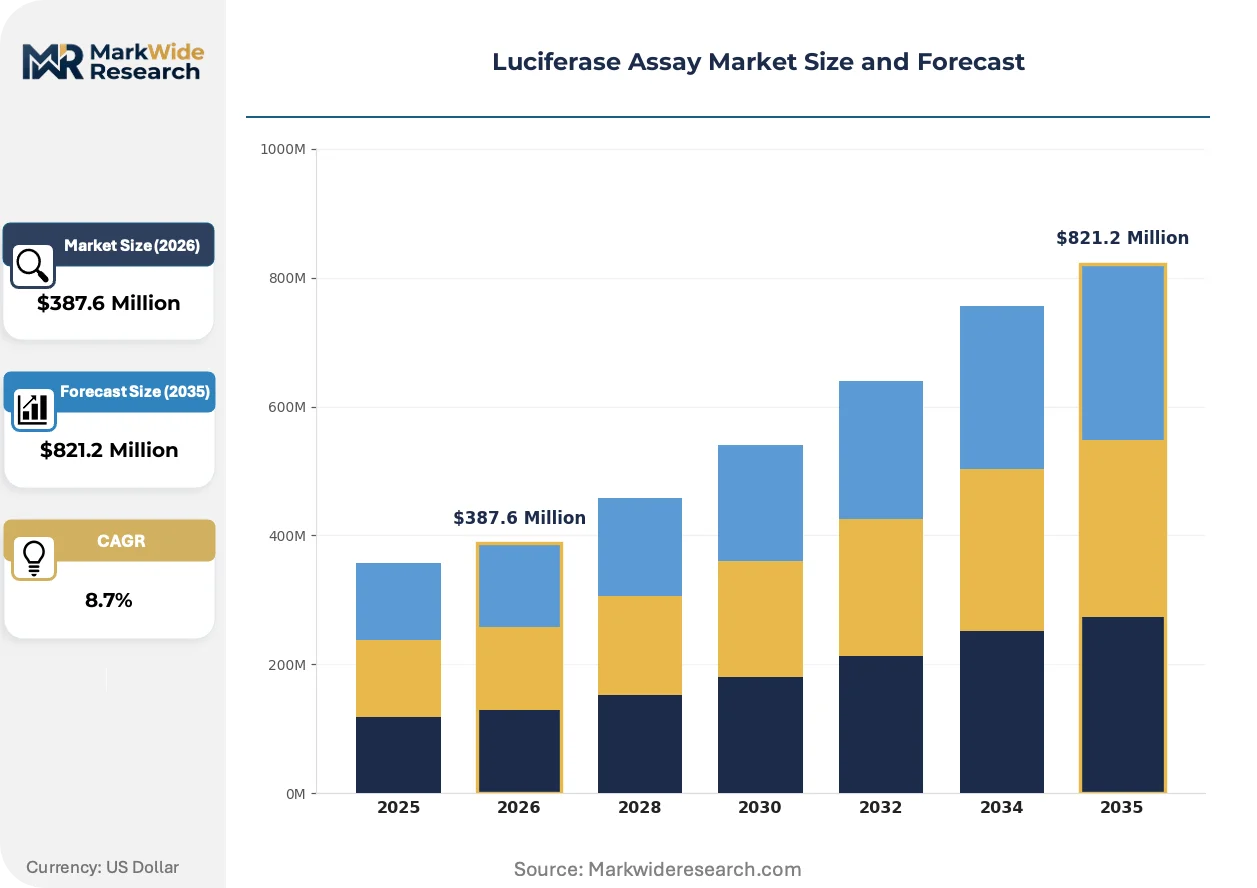
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firefly Luciferase, Renilla Luciferase, NanoLuc, Others Application: Drug Discovery, Bioluminescence Imaging, Gene Expression, Cellular Assays End User: Pharmaceutical Companies, Academic Institutes, Contract Research Organizations, Biotechnology Firms Technology: Detection Systems, High-Throughput Screening, Imaging Systems, Microplate Readers |
| Companies Covered | Promega Corporation, Thermo Fisher Scientific Inc., Merck KGaA, PerkinElmer Inc., Bio-Rad Laboratories, Inc., Takara Bio Inc., Abcam plc, BPS Bioscience, GeneCopoeia, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luciferase Assay Market Emerging Trajectories
Luciferase detection platforms are converging with imaging hardware and informatics infrastructure, compressing the traditional separation between reagent suppliers and instrumentation vendors while reshaping how screening data flows into decision systems.
NanoLuc variants are expanding into high-sensitivity applications requiring extended signal windows. Contract research organizations running 24-hour kinetic assays are adopting these engineered enzymes to reduce plate-reading frequency. The technology is expanding into single-cell analysis workflows previously dominated by fluorescent reporters, compressing the addressable market for legacy detection chemistries.
EMA guidance on cell-based potency assays is tightening documentation requirements for biologics development. European contract manufacturers must now demonstrate traceable reagent qualification across assay validation phases. This regulatory pressure is elevating demand for certified reference materials and audited supply chains, particularly in Germany and Switzerland where biologics production concentrates.
Large pharmaceutical buyers are unbundling reagent procurement from detection system contracts. Procurement teams now negotiate enzyme, substrate, and luminometer supply separately to optimize unit economics. This behavioral shift is most visible in United States biotech clusters, where multi-year sole-source agreements are giving way to annual competitive tenders with approved vendor lists.
Luciferase Assay Market Segmentation
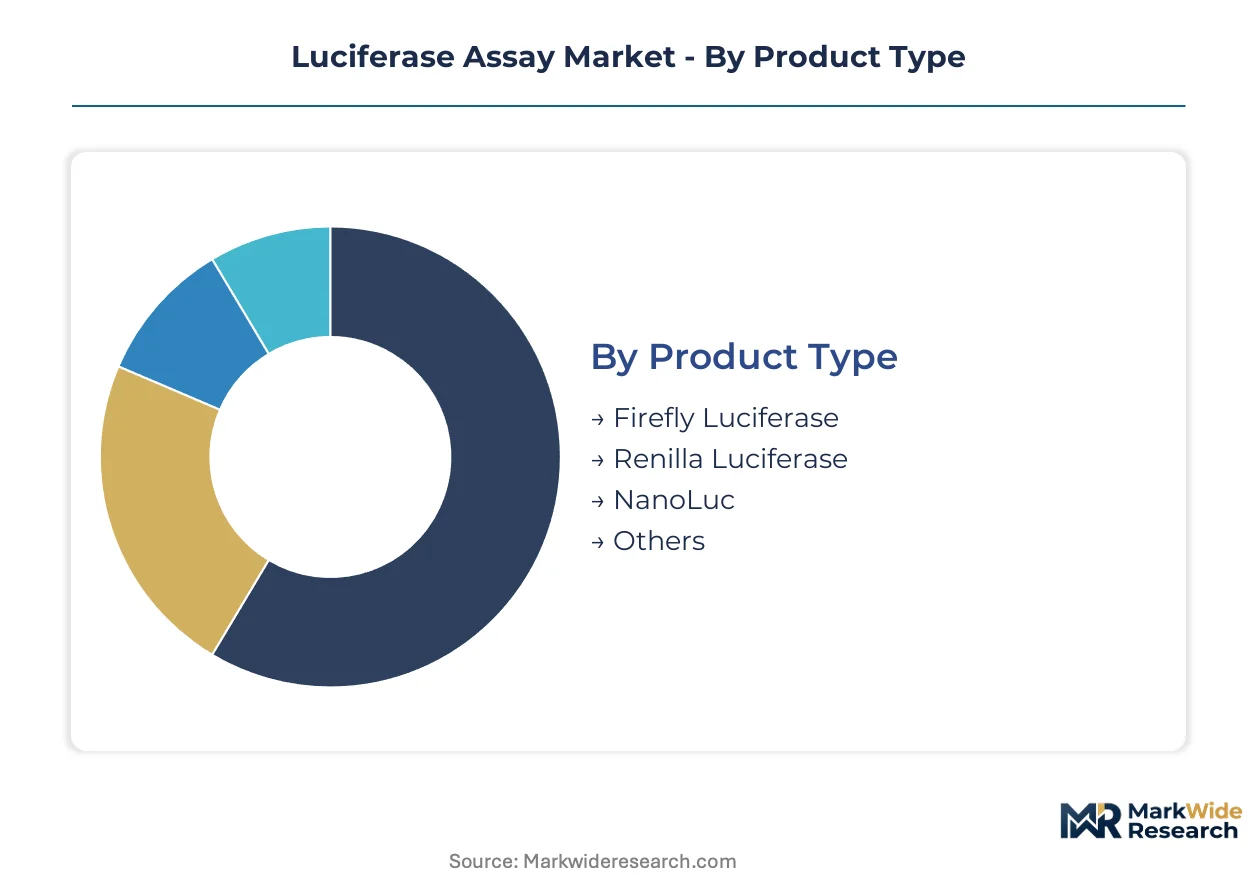
Luciferase assay segmentation reveals how procurement priorities diverge across research workflows. Product chemistry, application intensity, and detection infrastructure each create distinct buying centers with incompatible technical requirements.
Product Type:
Enzyme selection hinges on signal stability needs versus protocol migration costs for established labs.
- Firefly Luciferase:ATP-dependent bioluminescence from Photinus pyralis dominates legacy drug discovery protocols. Pharmaceutical screening centers in Boston and San Diego maintain bulk purchasing contracts for this chemistry due to decades of validated standard operating procedures.
- NanoLuc:Engineered 19 kDa variant delivers superior brightness and extended half-life with minimal genetic payload. Contract research organizations running 24-hour kinetic assays are accelerating adoption to reduce plate-reading frequency and enable single-cell resolution workflows.
- Renilla Luciferase:Sea pansy-derived enzyme serves dual-reporter normalization applications. Academic institutes favor this chemistry for co-transfection standardization in gene expression studies.
- Others:Click beetle and deep-sea shrimp variants occupy niche spectral multiplexing applications. Specialized biotechnology firms probe these alternatives for multi-analyte detection panels.
Firefly luciferase leads volumes today; NanoLuc is gaining share fastest.
Application:
Workflow complexity and regulatory exposure determine reagent grade and documentation depth.
- Drug Discovery:High-throughput screening campaigns consume industrial reagent volumes for target validation and lead optimization. FDA cell-based assay guidance is compelling standardized kit adoption across IND-enabling studies.
- Cellular Assays:NanoLuc complementation enables protein-protein interaction detection with smaller genetic footprint than fluorescence resonance energy transfer methods. Structural biology groups are migrating kinetic assays to this format.
- Bioluminescence Imaging:Whole-animal and tissue-section applications require substrate tissue permeability optimization. Preclinical imaging facilities balance signal depth against injection volume constraints.
- Gene Expression:Reporter constructs quantifying promoter activity depend on minimal basal expression backgrounds. Academic transcription factor research drives demand for low-background detection chemistries.
Drug discovery commands the largest reagent volumes; cellular assays are climbing the fastest.
End User:
Procurement scale and quality certification requirements separate institutional buyers.
- Pharmaceutical Companies:Multi-site screening operations negotiate annual competitive tenders with approved vendor lists. Batch-to-batch documentation under current Good Manufacturing Practice standards is non-negotiable for IND components.
- Contract Research Organizations:Boston and San Diego clusters scale automated detection infrastructure to serve sponsor pipelines. These buyers decouple enzyme, substrate, and hardware procurement to optimize unit economics.
- Academic Institutes:Grant-funded labs prioritize catalog breadth and technical support over volume discounts. Multi-investigator core facilities consolidate purchasing across departmental budgets.
- Biotechnology Firms:Emerging companies balance reagent consistency against cash runway constraints. ISO 13485 certification unlocks clinical laboratory demand for diagnostics-bound platforms.
Pharmaceutical companies anchor procurement value; contract research organizations are expanding fastest.
Technology:
Hardware-software integration depth defines platform switching costs and data workflow compatibility.
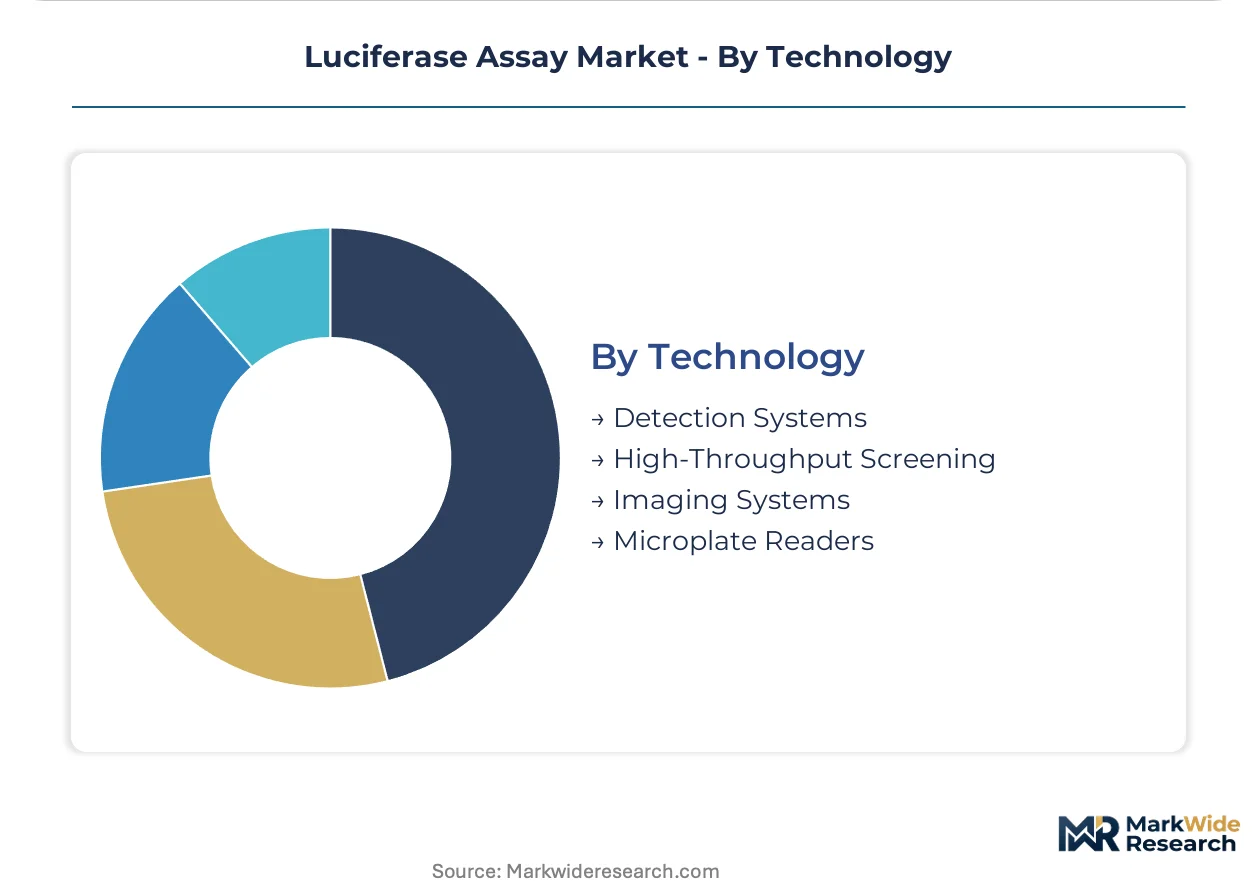
- Detection Systems:Photomultiplier tube and CCD-based luminometers span sensitivity ranges from single-cell to whole-plate throughput. Hardware vendors are converging with reagent suppliers to compress data-to-decision latency.
- Microplate Readers:96-through-1536 well formats dominate high-throughput screening infrastructure. Automated stacker integration enables unattended overnight kinetic acquisition.
- Imaging Systems:Bioluminescence imaging platforms combine cooled CCD cameras with light-tight enclosures for quantitative photon counting. Preclinical facilities require substrate pharmacokinetic validation for in vivo applications.
- High-Throughput Screening:Integrated robotics linking liquid handlers, incubators, and readers compress campaign timelines. Contract research organizations in United States biotech clusters drive bulk system procurement.
Microplate readers dominate installed base; high-throughput screening integration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redistributing luciferase reagent manufacturing toward jurisdictions with streamlined biologics oversight, while demand concentrates in established pharmaceutical clusters where FDA and EMA validation requirements create procurement premiums.
United States
FDA cell-based assay guidance and IND-enabling study volumes drive standardized kit demand. Boston and San Diego biotech clusters scale automated detection infrastructure for high-throughput screening campaigns. Pharmaceutical procurement teams negotiate annual competitive tenders with approved vendor lists to optimize unit economics.
Germany
EMA guidance on cell-based potency assays tightens documentation requirements for biologics contract manufacturers. Swissmedic-aligned certification standards elevate demand for audited supply chains in Baden-Württemberg and Bavaria production corridors. Heidelberg and Munich research institutes consolidate multi-investigator core facility purchasing.
Switzerland
Swissmedic stringent quality certifications attract vendors seeking European regulatory credibility for clinical laboratory applications. Basel and Zurich biologics production centers require traceable reagent qualification across assay validation phases. ISO 13485 compliance unlocks diagnostic-bound platform demand beyond research segments.
Japan
PMDA harmonization efforts with FDA standards favor detection platforms achieving dual regulatory acceptance. Tokyo and Osaka pharmaceutical R&D centers adopt NanoLuc formats for extended signal window applications. METI-supported biotechnology initiatives accelerate protein-protein interaction screening infrastructure deployment.
United Kingdom
Medicines and Healthcare products Regulatory Agency alignment with EMA post-Brexit protocols shapes reagent import documentation requirements. Cambridge and Oxford academic transcription factor research sustains demand for low-background detection chemistries. London-based contract research organizations decouple enzyme and substrate procurement to reduce screening operation costs.
Luciferase Assay Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized enzyme engineering and ISO 13485 certification pathways. The vendor base stratifies across integrated reagent-instrumentation platforms, pure-play enzyme suppliers, and diversified life science conglomerates. Three archetypes dominate: vertically integrated kit manufacturers, detection hardware specialists seeking reagent partnerships, and regional fermentation experts serving captive biomanufacturing demand. Consolidation pressure operates through M&A targeting complementary detection technologies and strategic partnerships linking substrate chemistry with imaging hardware.
Among diversified life science conglomerates, Thermo Fisher Scientific anchors the broad-catalog archetype spanning detection systems and imaging hardware. Promega Corporation exemplifies vertically integrated enzyme production with captive supply chain control over recombinant luciferase manufacturing. Merck KGaA occupies the stringent-certification tier, with German-origin quality systems appealing to European regulatory environments.
| Leading Market Players |
|---|
| Promega Corporation |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| PerkinElmer Inc. |
| Bio-Rad Laboratories, Inc. |
| Takara Bio Inc. |
| Abcam plc |
| BPS Bioscience |
| GeneCopoeia, Inc. |
| Others |
Supply Flow & Price Mechanics
Large pharmaceutical procurement teams negotiating annual competitive tenders with approved vendor lists anchor pricing power in the luciferase assay market. Their volume concentration and multi-source sourcing strategies compress margins for reagent suppliers while rewarding detection hardware vendors with platform lock-in.
Pricing Analysis
Distributor margins in the reagent tier range from 15 to 25 percent depending on certification grade and geographic delivery cost. Pricing stratifies across premium certified-reference tiers for IND-enabling studies, standard research-grade kits for academic workflows, and economy bulk formats for high-throughput screening campaigns. Cost compression in the economy tier is intensifying because contract research organizations decouple enzyme and substrate procurement to optimize unit economics. Academic institutes demonstrate highest price sensitivity due to grant-funded budget constraints, while pharmaceutical quality assurance teams prioritize batch-to-batch documentation over unit cost.
Supply Chain Analysis
Specialized fermentation expertise scarcity in Wisconsin and Bavaria biomanufacturing corridors constrains recombinant luciferase enzyme output. Supply concentrates in the United States, Germany, and Switzerland where ISO 13485-certified facilities serve clinical laboratory demand. Production draws from recombinant DNA construction, insect cell culture media, and luciferin substrate chemistry as critical inputs. Single-source vulnerability in engineered NanoLuc variant production exposes buyers to allocation risk during capacity constraints. Distribution runs through direct sales forces for large pharmaceutical accounts and specialized life science distributors serving academic and biotechnology segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The luciferase assay market functions as a regulatory compounder where FDA cell-based assay validation guidance and EMA potency assay alignment create sustained demand for certified detection platforms.
For Market Incumbents: Acquire ISO 13485-certified fermentation capacity in Swissmedic-aligned jurisdictions to defend against emerging entrants pursuing clinical laboratory certification pathways. Strengthen backward integration into recombinant enzyme production to offset biomanufacturing talent scarcity and secure captive supply chains against single-source disruption. For New Entrants and Emerging Players: Launch via contract research organization channel partnerships in Boston and San Diego biotech clusters where multi-vendor procurement policies create white-space for specialized enzyme suppliers. Target protein-protein interaction screening applications with NanoLuc complementation formats displacing legacy fluorescence resonance energy transfer methods in structural biology workflows. For Investors and Strategic Acquirers: Life science conglomerates seeking detection platform consolidation are the most active acquirer in this space, particularly those lacking bioluminescence imaging hardware capabilities. Over the medium-term horizon, acquisition value concentrates in audited supply chain operators with EMA-FDA dual regulatory acceptance. Watch for harmonized cell-based potency assay guidance publication as the signal indicating accelerated platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Pathway | Unlocks clinical laboratory demand beyond research applications for diagnostic-bound platforms. |
| EMA-FDA Regulatory Alignment Investment | Positions detection platforms for dual acceptance as European and US standards converge. |
| Backward Integration into Enzyme Production | Secures captive supply chains against biomanufacturing talent scarcity and single-source risk. |
| NanoLuc Format Portfolio Expansion | Captures protein-protein interaction screening workflows migrating from fluorescence methods. |
| Contract Research Organization Channel Partnership | Accesses Boston and San Diego biotech clusters where procurement is decoupling from sole-source agreements. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged drug discovery executives, regulatory affairs leads, reagent procurement managers, and contract research organization operations directors. Secondary sources included FDA guidance documents, EMA assessment reports, ISO certification registries, and pharmaceutical IND submission databases. Bottom-up reagent volume estimates and top-down detection system market sizing were triangulated to derive segment-level outputs.
Rate-of-change decomposition across the analysis window isolated volume drivers from price effects in each segment. The analytical framework modeled enzyme type, application intensity, end-user procurement scale, and technology integration depth as core segmentation dimensions. CAGRs were derived from fitted growth curves applied to validated baseline estimates. Forecast inputs incorporated high-throughput screening infrastructure deployment rates and regulatory guidance implementation timelines specific to cell-based assay validation.
Several conditions sit outside the modeled scope, including unforeseen regulatory guidance reversals, supply chain disruptions from geopolitical events, and technology substitution by non-bioluminescence detection methods. Forecasts reflect assumptions about continued pharmaceutical R&D expenditure stability and EMA-FDA harmonization progression. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
Research Antibodies and Reagents Market
Biotechnology Services
Electrophoresis Market
Biotechnology Services
Serine Protease Market
Biotechnology Services
Precast Agarose Gel Market
Biotechnology Services
Recombinant Factor C Assay Market
Biotechnology Services
Global Protein Purification and Isolation Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
DNA and RNA Sample Preparation Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Cell Line Development Services Market