
 Bio-Services Market | 2026-2036
Bio-Services Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Services Market Analysis
Biotech firms are redrawing demand patterns across the Bio-Services landscape, shifting procurement from fragmented academic laboratories toward integrated contract development partners. Moderna, Inc. leverages its mRNA platform expertise to anchor large-scale biomanufacturing partnerships. Syngene International sustains cost-competitive bioprocessing capacity from India. Kriya Therapeutics specializes in gene therapy manufacturing, differentiating through proprietary suspension cell culture systems.
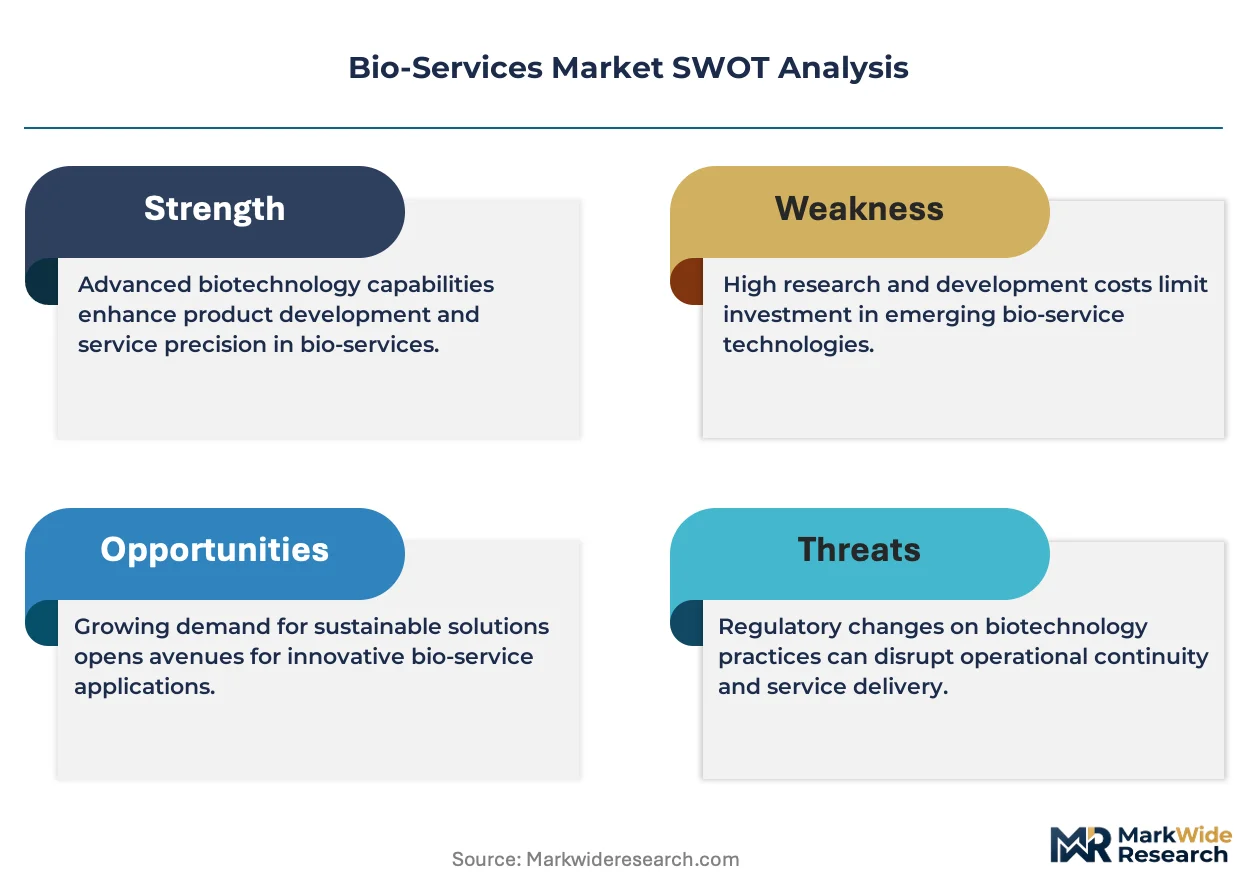
Bio-services encompass outsourced scientific and technical activities spanning biomanufacturing, contract research, bioprocessing, and quality control, typically executed under GMP conditions with batch release documentation and validated analytical methods. These services enable pharmaceutical and biotech companies to access specialized capabilities without capital-intensive infrastructure. Contract research commands substantial margin pools due to IP-intensive study design and regulatory submission support. Biomanufacturing segments are expanding fastest as cell and gene therapies require novel production platforms. Quality control services remain mature but essential, anchored by mandatory release testing under FDA and EMA guidelines.
FDA's GMP inspections and EMA's ATMP certification frameworks shape facility qualification standards and market access for cross-border service providers. The EU AI Act introduces algorithmic transparency requirements for AI-driven target identification and patient stratification tools, creating compliance differentiation among contract research organizations. Stakeholders must monitor how emerging platform technologies in cell culture and protein purification reshape vendor selection criteria and long-term partnership structures.
Market Dynamics
Biotech firms are consolidating procurement around integrated contract development partners as cell and gene therapy pipelines demand GMP biomanufacturing capacity that academic laboratories cannot provision. This shift toward outsourced infrastructure is concentrating vendor relationships among platform-specialized providers.
Growth Catalysts
- FDA Accelerated Approval:Expedited pathways for breakthrough therapies compress development timelines and expand demand for contract research organizations with regulatory submission expertise.
- Cell Culture Platform Advances:Suspension-based manufacturing systems for viral vectors reduce production costs and enable scalable gene therapy supply.
- Venture Capital Deployment:Deep funding pools in the United States sustain early-stage biotech pipelines that outsource discovery and manufacturing functions.
Market Restraints
- Specialized Facility Scarcity:ATMP-certified GMP capacity concentrates among limited European and North American contract manufacturers, creating queue bottlenecks.
- Plasmid DNA Supply Volatility:Critical raw material for mRNA and gene therapy production faces concentration among a handful of qualified suppliers.
- EU AI Act Compliance Burden:Algorithmic transparency mandates for AI-driven target identification impose documentation costs on contract research workflows.
Strategic Opportunities
- Indian Bioprocessing Expansion:Cost-competitive GMP capacity in Hyderabad and Bangalore attracts Western biotech firms seeking manufacturing diversification.
- Continuous Bioprocessing Convergence:Integration of perfusion cell culture with single-use downstream systems enables real-time quality monitoring and reduced facility footprints.
- Japan PMDA Regenerative Medicine Framework:Streamlined approval pathways for cell therapies create demand for local contract development and manufacturing partners.
Industry Challenges
- ATMP Manufacturing Talent Gap:Shortage of process engineers trained in viral vector production and closed-system aseptic processing limits facility expansion.
- Legacy Quality System Integration:Biotech sponsors struggle to harmonize electronic batch records between their own ERP platforms and contract manufacturer systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Services Market |
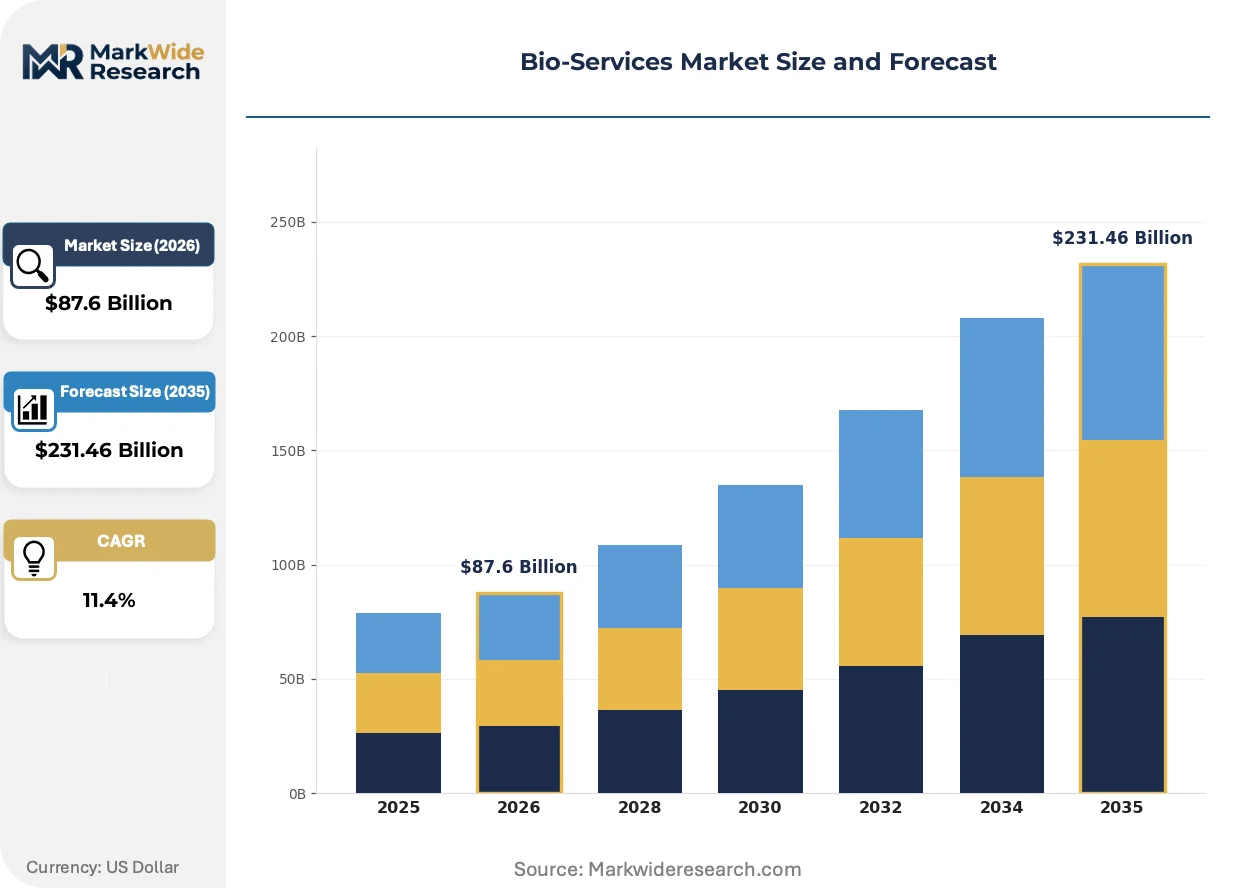
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Biomanufacturing, Contract Research, Bioprocessing, Quality Control Application: Pharmaceuticals, Diagnostics, Agricultural Biotechnology, Environmental Biotechnology End User: Pharmaceutical Companies, Research Institutions, Biotech Firms, Academic Laboratories Technology: Genetic Engineering, Cell Culture, Fermentation, Protein Purification |
| Companies Covered | FibroGen, Kriya Therapeutics, Syngene International, LEXEO Therapeutics, Rakuten Medical, Moderna, Inc., SAGE Therapeutics, Everest Medicines, Caris Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Services Market Emerging Trajectories
Digital and biological platform technologies are converging to reshape how biopharmaceutical services are contracted, executed, and validated. Automation and algorithmic tools are embedding into workflows that previously relied on manual scientific judgment.
Single-use bioreactor technology is decomposing stainless-steel infrastructure requirements for multi-product facilities. Mid-sized biotech sponsors now adopt disposable upstream systems to reduce cleaning validation burdens and enable rapid product changeovers. This shift compresses capital deployment timelines and expands accessible manufacturing capacity for niche indications.
The EU AI Act mandates algorithmic transparency for machine-learning models used in patient stratification and biomarker discovery. Contract research organizations must document training data provenance and model decision pathways for regulatory submission packages. European biotech sponsors are prioritizing vendors with pre-validated AI governance frameworks to preempt compliance delays.
Biotech procurement teams are consolidating vendor panels around full-service partners offering integrated discovery-through-manufacturing capabilities. Fragmented point-solution contracts for analytical testing or fill-finish operations are giving way to multi-year platform agreements with milestone-based pricing. This concentration is most pronounced among cell and gene therapy developers in the United States seeking to reduce technology transfer risks.
Bio-Services Market Segmentation
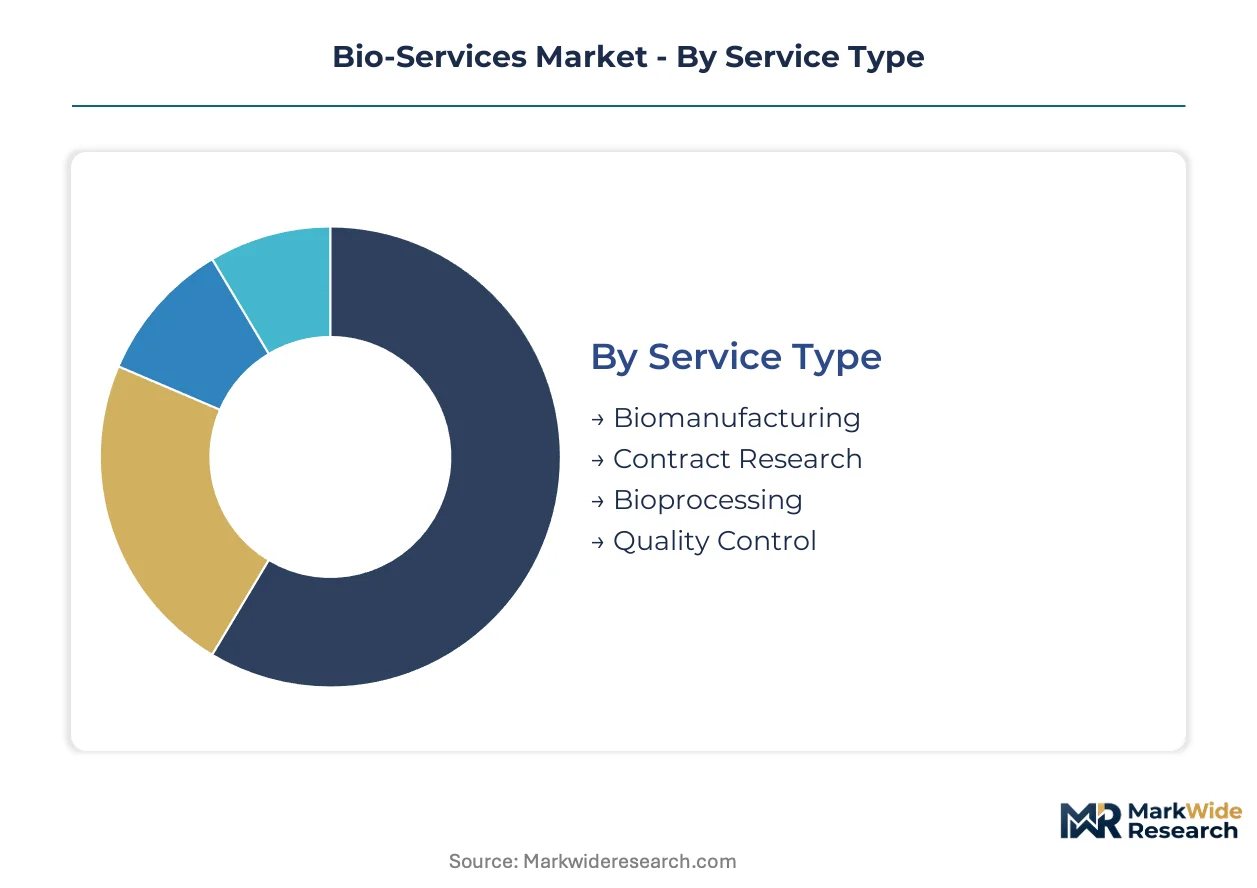
Segmentation in bio-services reveals how vendor capabilities align with diverging technical requirements across therapeutic modalities. Procurement teams select service tiers based on regulatory complexity, batch scale, and platform technology compatibility rather than price alone.
Service Type:
Substitution pressure concentrates in analytical and release testing services, where automated platforms displace manual laboratory workflows and erode traditional quality control margins.
- Biomanufacturing:GMP-grade production of biologics, viral vectors, and cell therapies under FDA and EMA batch release standards. Demand clusters around ATMP-certified facilities in the United States and Germany as gene therapy sponsors queue for limited capacity.
- Contract Research:IP-intensive study design, regulatory submission support, and clinical trial management. Sponsors in Massachusetts and California outsource discovery-phase toxicology to access specialized disease models and accelerate IND timelines.
- Bioprocessing:Upstream cell culture and downstream purification optimization. Single-use technology adoption reduces cross-contamination risks for multi-product CDMOs.
- Quality Control:Validated analytical methods, stability testing, and batch release documentation. Mandatory under FDA GMP inspections but facing automation-driven price compression.
Quality Control anchors the volume base while Biomanufacturing gains share at the steepest rate.
Application:
Cost tier stratification separates blockbuster-scale pharmaceutical contracts from niche environmental remediation projects with limited outsourcing budgets.
- Pharmaceuticals:Therapeutic protein production, monoclonal antibody manufacturing, and oligonucleotide synthesis. Cell and gene therapy developers in the United States drive premium pricing for GMP viral vector supply.
- Diagnostics:Reagent manufacturing, assay development, and companion diagnostic co-development. Molecular diagnostic firms outsource PCR enzyme production to access ISO 13485-certified capacity.
- Agricultural Biotechnology:Microbial strain engineering for biopesticides and crop protection agents. Lower regulatory burden attracts mid-sized contract manufacturers.
- Environmental Biotechnology:Bioremediation organism cultivation and industrial enzyme production. Limited commercial scale restricts contract service penetration.
Pharmaceuticals commands the revenue concentration while Diagnostics expands most quickly through companion diagnostic convergence.
End User:
Customer type determines contract structure, with large pharmaceutical companies demanding multi-year platform agreements and academic laboratories purchasing discrete analytical services.
- Pharmaceutical Companies:Integrated outsourcing of discovery through commercial manufacturing. Top-20 sponsors consolidate vendor panels to reduce technology transfer risks across global networks.
- Biotech Firms:Virtual and asset-light developers relying entirely on contract infrastructure. Venture-backed cell therapy startups in Boston and San Diego anchor demand for flexible GMP capacity.
- Research Institutions:Preclinical study execution and non-GMP material production. National institutes in Germany and the United Kingdom outsource specialized capabilities.
- Academic Laboratories:Fragmented demand for analytical testing and small-scale protein expression. Price-sensitive procurement limits contract value per engagement.
Pharmaceutical Companies anchor the volume base while Biotech Firms gains share at the steepest rate.
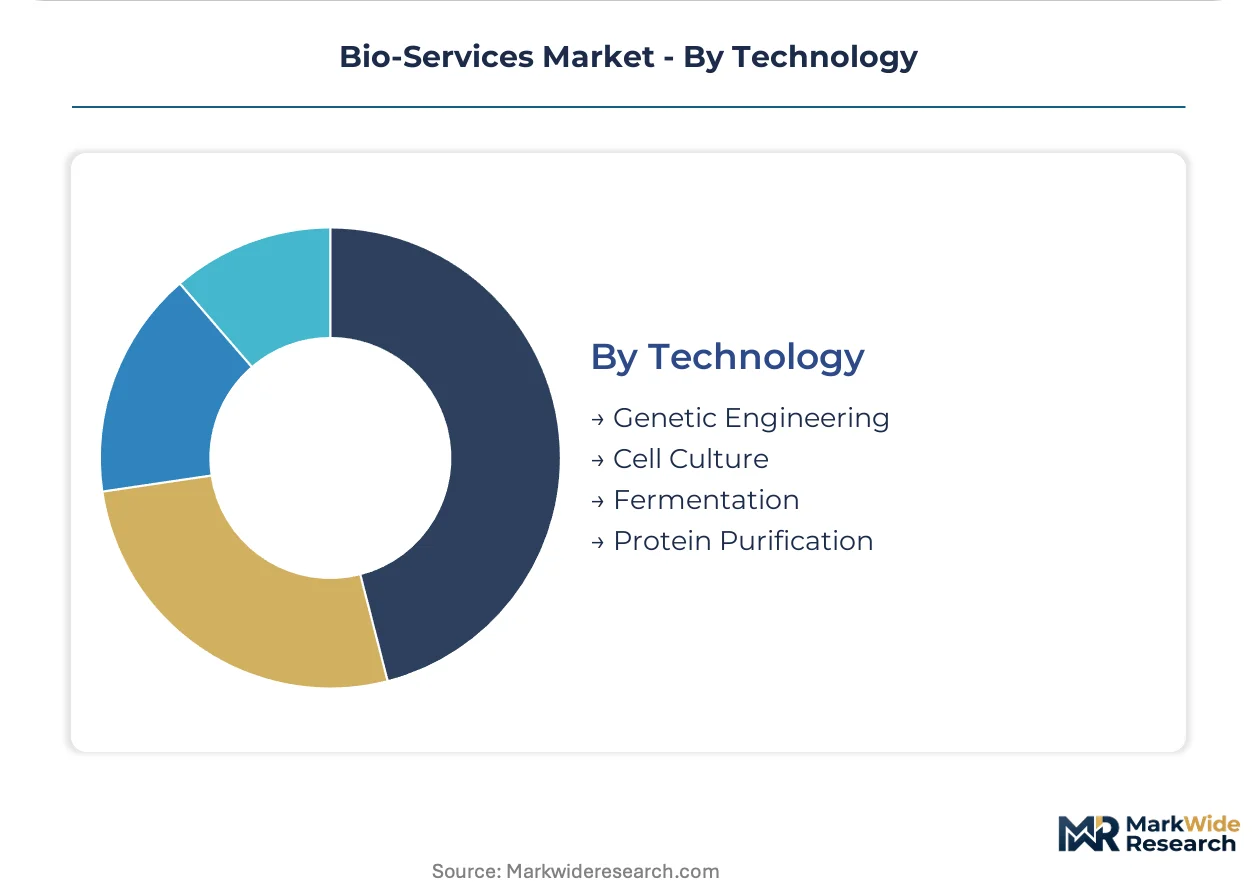
Technology:
Supply concentration in proprietary platform technologies creates vendor lock-in and limits substitution elasticity for sponsors committed to specific cell lines or expression systems.
- Genetic Engineering:CRISPR-based cell line development, viral vector design, and synthetic biology workflows. Contract research organizations in the United States differentiate through proprietary guide RNA libraries.
- Cell Culture:Suspension and adherent systems for biologics and gene therapy production. Perfusion technology adoption enables continuous manufacturing with reduced facility footprints.
- Fermentation:Microbial expression systems for insulin, enzymes, and vaccine antigens. Mature technology with established contract manufacturing capacity in India.
- Protein Purification:Chromatography and filtration-based downstream processing. Single-use membrane technologies reduce cleaning validation burdens for multi-product facilities.
Cell Culture anchors the volume base while Genetic Engineering gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian biomanufacturing exports to North American gene therapy developers are accelerating as Western sponsors seek cost-competitive GMP capacity. Contract research flows from the United States to European CROs are deepening under FDA-EMA mutual recognition frameworks. Cross-border service procurement now hinges on ATMP certification portability and algorithmic compliance under the EU AI Act.
United States
Venture-backed cell therapy developers in Boston and San Diego are queueing for limited viral vector manufacturing slots. FDA's accelerated approval pathways compress IND-to-Phase I timelines and expand demand for regulatory submission expertise. The Research Triangle and Seattle biotech clusters anchor contract research concentration.
Germany
EMA's ATMP certification frameworks shape facility qualification standards for cross-border service providers. The EU AI Act imposes algorithmic transparency mandates on AI-driven target identification tools used in patient stratification. Heidelberg and Munich host dense networks of GMP-certified viral vector manufacturers.
India
Cost-competitive bioprocessing capacity in Hyderabad and Bangalore attracts Western biotech firms seeking manufacturing diversification. CDSCO's evolving GMP inspection protocols align with FDA and EMA standards to enable export qualification. The Genome Valley cluster sustains fermentation and microbial expression infrastructure for global supply.
Japan
PMDA's regenerative medicine framework creates demand for local contract development and manufacturing partners. Streamlined approval pathways for cell therapies compress development timelines for domestic sponsors. The Kanto region around Tokyo anchors clinical trial execution and quality control services.
Switzerland
Swissmedic's alignment with EMA standards enables seamless cross-border service provision into EU markets. Basel and Zurich host specialized contract manufacturers serving monoclonal antibody and oligonucleotide production. The country's bilateral recognition agreements reduce regulatory friction for multi-site trials.
Bio-Services Market Vendor Landscape
Listed leaders compete with private specialists across platform technology ownership and GMP capacity access. The vendor base organizes into three tiers: integrated CDMOs with end-to-end capabilities, niche viral vector specialists, and cost-optimized bioprocessing providers in emerging geographies. Strategic differentiation hinges on ATMP certification status and proprietary cell culture systems. Competitive moves concentrate on multi-year platform agreements and geographic capacity expansion.
Within the gene therapy specialist tier, Kriya Therapeutics and LEXEO Therapeutics exemplify platform-focused positioning through proprietary suspension cell culture systems. Syngene International occupies a cost-leadership position among India-based contract manufacturers serving Western biotech sponsors. Moderna, Inc. anchors the mRNA platform segment through large-scale biomanufacturing partnerships that integrate discovery-through-commercial capabilities.
| Leading Market Players |
|---|
| FibroGen |
| Kriya Therapeutics |
| Syngene International |
| LEXEO Therapeutics |
| Rakuten Medical |
| Moderna, Inc. |
| SAGE Therapeutics |
| Everest Medicines |
| Caris Life Sciences |
| Others |
Supply Flow & Price Mechanics
FDA's ATMP certification framework gates both supply qualification and price differentiation simultaneously, restricting GMP viral vector manufacturing to a limited pool of qualified facilities while enabling premium pricing for certified capacity. Contract research organizations with pre-validated AI governance under the EU AI Act command further price premiums as biotech sponsors prioritize compliance-ready partners.
Pricing Analysis
Next-generation suspension cell culture systems for gene therapy production command 40-60% price premiums over legacy adherent-platform services, while prior-generation stainless-steel bioreactor capacity faces accelerating price erosion. Three-tier pricing structure across premium ATMP-certified, standard GMP, and non-GMP economy levels reflects certification grade and batch release documentation depth. Cost compression in quality control analytical services is intensifying because automated platforms displace manual laboratory workflows. Academic laboratories exhibit highest price sensitivity, while venture-backed cell therapy developers in Boston and San Diego prioritize speed over unit cost.
Supply Chain Analysis
Plasmid DNA supply concentration among qualified manufacturers in the United States, Germany, and South Korea creates a chokepoint that underwrites production scheduling risk for mRNA and gene therapy developers. Critical raw material dependencies include plasmid DNA, specialized cell culture media, and single-use bioreactor components. Single-source vulnerability in viral vector seed stock supply threatens batch continuity for ATMP manufacturers. Distribution runs through direct long-term platform agreements rather than spot-market transactions, with multi-year contracts locking in capacity allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ATMP-certified GMP manufacturing capacity operates at structural shortage against queued gene therapy pipelines, with process engineers trained in closed-system aseptic processing representing the critical talent gap constraining facility expansion.
For Market Incumbents: Consolidate vendor relationships around full-service platform partnerships that integrate discovery-through-manufacturing capabilities to reduce technology transfer risks. Acquire proprietary suspension cell culture systems to differentiate against emerging CDMOs with licensed platform access. Prioritize certification investment in EU AI Act-compliant AI governance frameworks to preempt compliance delays for European biotech sponsors. For New Entrants and Emerging Players: Anchor in cost-competitive GMP bioprocessing capacity in Hyderabad and Bangalore to serve Western biotech firms seeking manufacturing diversification. Target the environmental biotechnology application segment, where limited commercial scale has restricted contract service penetration and incumbent presence remains thin. Pursue joint development agreements with academic laboratories transitioning discovery programs toward IND-enabling studies. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across viral vector manufacturing as single-use technology adoption and continuous bioprocessing convergence demand facility redesign. Platform-specialized CDMOs with ATMP certification and proprietary cell culture systems represent the preferred acquisition archetype. Watch queue lengths at FDA-inspected viral vector facilities as the inflection indicator for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ATMP Certification Investment | EMA's certification frameworks enable cross-border service provision into EU gene therapy markets. |
| Proprietary Platform Acquisition | Suspension cell culture systems differentiate viral vector manufacturing capacity against commodity competitors. |
| AI Governance Framework Validation | Pre-validated algorithmic transparency documentation accelerates regulatory submission timelines for European sponsors. |
| Indian Manufacturing Footprint | CDSCO-aligned GMP capacity in Genome Valley attracts Western biotech procurement diversification. |
| Continuous Bioprocessing Integration | Perfusion cell culture with single-use downstream systems reduces facility footprints and enables real-time quality monitoring. |
Methodological Framework
A standing panel of drug development executives, regulatory affairs leads, GMP facility operators, and venture capital investors provided ongoing calibration against market developments throughout the study period. Primary interviews with contract research organization leadership and biotech procurement directors combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and CDSCO inspection protocols. Bottom-up service-type demand modeling and top-down market sizing triangulated volume and value estimates.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled include service type, therapeutic application, end-user archetype, and technology platform, with regional regulatory cluster as an additional biopharmaceutical-specific dimension. CAGRs derived from segment-level growth trajectory analysis incorporating cell and gene therapy pipeline expansion rates and venture capital deployment patterns.
Material uncertainties — regulatory inspection backlog delays, plasmid DNA supply disruptions, and EU AI Act enforcement variance — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding ATMP certification portability and cross-border service procurement continuity. Practitioners should keep alternative scenarios live as FDA accelerated approval pathway utilization and EMA digital health framework evolution reshape compliance requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Stable Cell Line Development Market
Biotechnology Services
Aptamers Market
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
TSG6 Antibody Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market
Biotechnology Services
Global Protein Binding Assay Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Plasma Feed Market
Biotechnology Services
Plasmid DNA Preparation Market