
 Global Qpcr Reagents Market | 2026-2036
Global Qpcr Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Qpcr Reagents Market Foresight
A shift from single-source to multi-source procurement is restructuring supply relationships across the qPCR reagents sector. Thermo Fisher Scientific leverages its integrated raw material-to-finished-reagent pipeline to sustain pricing power in master mixes. QIAGEN anchors European distribution through ISO-certified manufacturing sites in Germany. Bio-Rad Laboratories competes on thermal-cycler compatibility, extending reagent pull-through from installed instrument bases.
Quantitative PCR reagents comprise enzyme formulations, fluorescent probes, and optimized buffer systems designed to amplify and quantify target nucleic acid sequences through real-time fluorescence monitoring. SYBR Green-based formulations dominate routine screening applications due to lower per-reaction cost, while TaqMan probe chemistry commands premium positioning in infectious disease detection workflows where specificity requirements are non-negotiable. Research institutions represent the deepest volume pool, though pharmaceutical companies generate superior margins through validated-for-GMP product tiers. Agricultural biotechnology applications are expanding fastest as gene-editing regulation drives trait-verification testing.
The FDA oversees diagnostic reagent quality through its IVD regulatory pathway, while the EMA's IVDR transition in Europe demands expanded technical documentation from manufacturers seeking CE marking. ISO 13485 certification has become table stakes for market access, with WHO prequalification programs opening procurement channels in low-resource health systems. Stakeholders must monitor how decentralized testing authorization protocols reshape demand fragmentation between centralized reference labs and point-of-care molecular platforms.
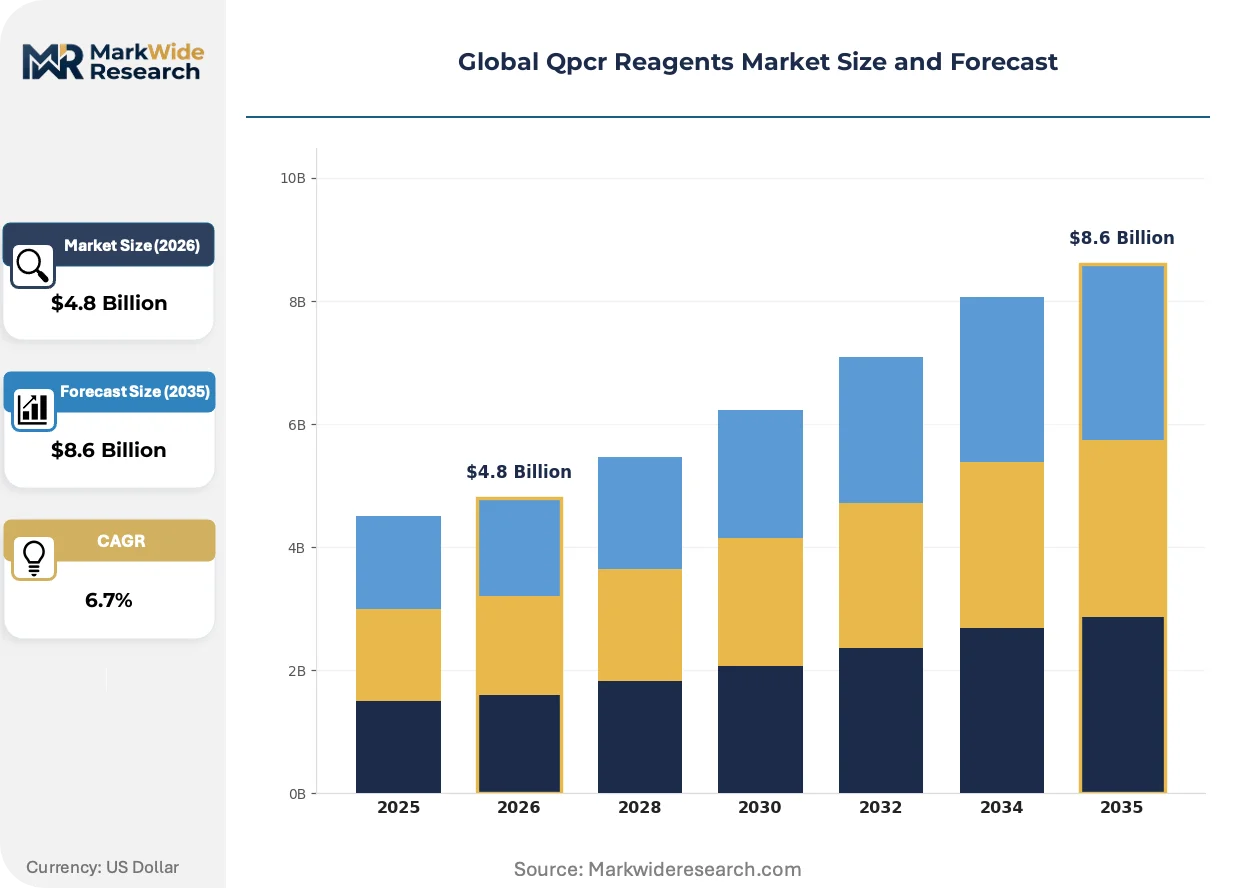
Market Dynamics
The qPCR reagents sector is experiencing a fundamental restructuring as multi-source procurement replaces long-term exclusive supply agreements, forcing manufacturers to demonstrate technical equivalence across enzyme lots while pharmaceutical buyers demand validated-for-GMP documentation tiers that bifurcate pricing structures.
Growth Catalysts
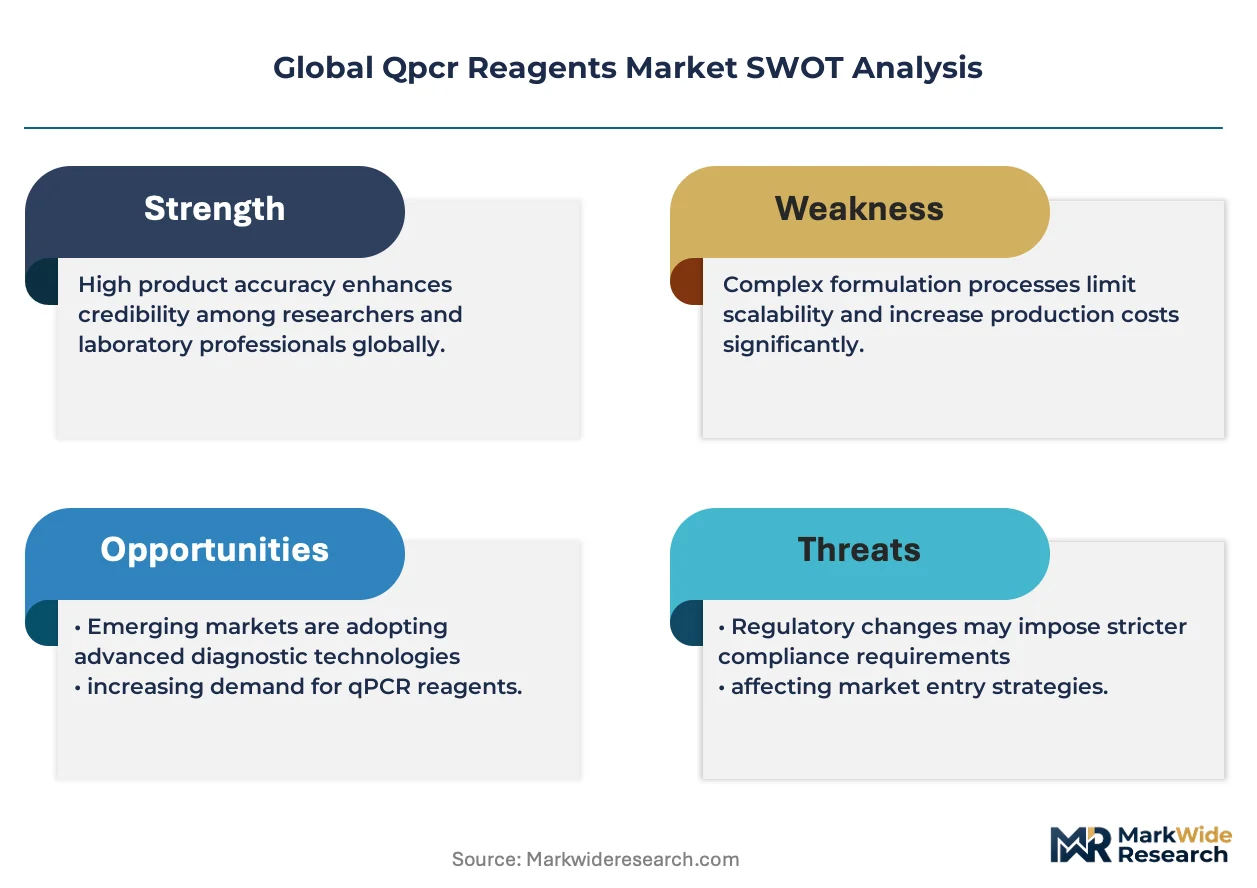
- Precision medicine pipelines:Pharmaceutical companies are expanding molecular testing infrastructure to support companion diagnostic development, creating sustained demand for high-fidelity probe chemistries.
- IVDR transition in Europe:The EMA's expanded technical documentation requirements for CE marking are accelerating replacement cycles among laboratories upgrading to compliant reagent systems.
- Gene-editing regulation:Agricultural biotechnology firms in Brazil and Argentina are scaling trait-verification testing to meet export certification standards for gene-edited crops.
Market Restraints
- Enzyme supply concentration:Thermostable DNA polymerase production concentrates among three specialized fermentation facilities in Germany and Switzerland, creating geographic vulnerability to energy price spikes.
- Fluorophore cost volatility:Rare earth elements and specialized dye chemistries face input cost pressure from Chinese export quota adjustments on precursor chemicals.
- ISO 13485 certification timelines:The 12-18 month approval window for quality management system certification creates barriers for mid-tier reagent formulators seeking WHO prequalification.
Strategic Opportunities
- Decentralized testing authorization:The FDA's evolving LDT oversight framework creates white space for point-of-care molecular platforms requiring lyophilized reagent formats with ambient stability.
- Digital PCR convergence:Partitioning technology integration with traditional qPCR workflows is opening new absolute quantification applications in liquid biopsy monitoring.
- India's diagnostic infrastructure:The country's PLI scheme for medical device manufacturing is attracting contract reagent production for Southeast Asian distribution.
Industry Challenges
- Assay standardization delays:The absence of universal reference materials for viral load quantification forces laboratories to maintain parallel validation studies across instrument platforms.
- Skill gap in bioinformatics:Clinical laboratories struggle to recruit personnel capable of interpreting multiplex probe data for complex infectious disease panels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Qpcr Reagents Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Master Mixes, Enzymes, Probes, Buffers, Standards, Controls Technology: SYBR Green, TaqMan, Molecular Beacon, Scorpion Probe, Sunrise, Others Application: Infectious Disease Detection, Genetic Disorder Identification, Cancer Research, Drug Development, Food Safety, Agricultural Biotechnology End User: Research Institutions, Pharmaceutical Companies, Forensic Labs, Academic Institutes, Diagnostic Centers, Biotechnology Firms |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, QIAGEN, F. Hoffmann-La Roche, Agilent Technologies, Merck KGaA, Promega Corporation, Takara Bio, Quantabio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Qpcr Reagents Market Shifts & Advancements
Real-time PCR chemistry is undergoing rapid diversification as digital detection methods converge with traditional fluorescence monitoring, while regulatory frameworks on both sides of the Atlantic impose new documentation burdens that favor integrated reagent-instrument systems over open-platform formulations.
Digital PCR partitioning technology is expanding into oncology monitoring workflows where absolute quantification of circulating tumor DNA demands sensitivity beyond standard curve-dependent methods. Major cancer centers in the United States and France are adopting droplet-based systems for minimal residual disease tracking. This expansion is compressing the addressable market for high-sensitivity qPCR assays in relapse monitoring applications.
Europe's IVDR implementation is mandating expanded clinical evidence packages for reagents claiming infectious disease detection, forcing manufacturers to retrospective-prove equivalence to predicate devices. German notified bodies are experiencing backlog delays exceeding fourteen months for technical documentation review. Smaller reagent houses are responding by withdrawing niche assay claims rather than absorbing compliance costs.
Pharmaceutical buyers are consolidating molecular testing procurement through centralized vendor management offices, displacing the historical pattern of individual research group autonomy. Contract research organizations are capturing reagent selection authority from principal investigators. This concentration is most visible in the Boston and San Diego biotech corridors where CROs manage reagent spend exceeding fifty million dollars annually.
Global Qpcr Reagents Market Segmentation
qPCR reagent purchasing splits across multiple technical and commercial dimensions, with procurement offices weighting compatibility against total cost per reaction. Segment boundaries blur where pharmaceutical buyers demand GMP-validated tiers that standard research grades cannot satisfy.
Product Type:
Supply concentration in thermostable polymerase fermentation shapes competitive dynamics across formulation categories.
- Master Mixes:Pre-formulated enzyme-buffer-dye combinations reduce lot-to-lot variability for high-throughput screening operations. Pharmaceutical quality assurance departments in the United States and Germany specify master mixes with documented CoA traceability for regulatory submissions.
- Enzymes:Thermostable DNA polymerases constitute the technical core of every amplification reaction, with hot-start modifications commanding premium positioning in low-copy detection workflows. Three specialized fermentation facilities in Germany and Switzerland supply the bulk of global enzyme demand, creating geographic vulnerability to energy price spikes.
- Probes:Fluorophore-quencher conjugates enable multiplexed target detection in clinical diagnostic panels.
- Buffers:Optimized salt and pH formulations stabilize enzyme activity across thermal cycling conditions.
- Standards:Quantified nucleic acid references calibrate absolute copy number determination.
- Controls:Positive and negative run controls validate assay performance per batch.
Master Mixes absorb the bulk of installed capacity; Agricultural Biotechnology applications are expanding most quickly.
Technology:
Cost tier differentiation separates routine screening from high-specificity clinical workflows.
- SYBR Green:Intercalating dye chemistry offers lower per-reaction economics for single-target amplification monitoring. Research institutions in India and Brazil deploy SYBR Green for preliminary screening where multiplexing is unnecessary.
- TaqMan:Hydrolysis probe design delivers target-specific fluorescence signal generation through 5' nuclease activity. Infectious disease reference laboratories in the United States and France require TaqMan chemistry for viral load quantification under FDA and EMA diagnostic pathways.
- Molecular Beacon:Stem-loop probe structure enables real-time genotyping applications.
- Scorpion Probe:Unimolecular design combines primer and probe for rapid assay development.
- Sunrise:Alternative probe architecture for specialized detection chemistries.
- Others:Emerging fluorescence resonance energy transfer systems and label-free detection methods.
TaqMan chemistry captures the highest value per reaction; SYBR Green formulations are climbing the fastest in absolute volume terms.
Application:
Customer type determines margin structure, with regulated diagnostics commanding validated-for-GMP pricing premiums.
- Infectious Disease Detection:Viral and bacterial pathogen quantification drives probe-based reagent consumption in centralized reference laboratories. Brazil's ANVISA and India's CDSCO are expanding molecular testing authorization for tuberculosis and HIV monitoring programs.
- Cancer Research:Circulating tumor DNA analysis and minimal residual disease tracking demand high-fidelity enzyme formulations. Major cancer centers in the United States and France are adopting droplet-based digital PCR for relapse monitoring, compressing addressable market for conventional qPCR in this segment.
- Genetic Disorder Identification:Inherited disease carrier screening and prenatal diagnostics.
- Drug Development:Pharmacokinetic biomarker analysis and companion diagnostic co-development.
- Food Safety:Pathogen detection in supply chain verification testing.
- Agricultural Biotechnology:Gene-editing trait verification for export certification compliance.
Infectious Disease Detection absorbs the bulk of installed capacity; Agricultural Biotechnology is gaining share fastest.
End User:
Volume concentration in research institutions contrasts with margin concentration in pharmaceutical procurement.
- Research Institutions:Academic medical centers and university core facilities generate the deepest reaction volume pools through open-platform instrument access. The National Institutes of Health-funded centers in Maryland and California maintain multi-thousand-reaction-per-day throughput for basic science applications.
- Pharmaceutical Companies:Validated-for-GMP documentation tiers bifurcate pricing structures for molecular testing in precision medicine pipelines. Contract research organizations in Boston and San Diego corridors now control reagent selection authority exceeding fifty million dollars in annual spend.
- Forensic Labs:DNA profiling and evidentiary sample analysis for criminal justice systems.
- Academic Institutes:Graduate training and exploratory research programs with budget-constrained purchasing.
- Diagnostic Centers:Clinical service laboratories performing reimbursable molecular testing.
- Biotechnology Firms:Mid-sized developers of proprietary assay platforms and reagent kits.
Research Institutions absorb the bulk of installed capacity; Pharmaceutical Companies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fermentation facilities in Germany and Switzerland anchor enzyme supply for the qPCR reagents sector, while demand concentrates in the United States, where academic medical centers and pharmaceutical companies scale molecular testing infrastructure.
United States
Academic medical centers in Maryland and California maintain multi-thousand-reaction-per-day throughput for basic science applications. The FDA's evolving LDT oversight framework is reshaping quality requirements for diagnostic reagent manufacturers. CROs in Boston and San Diego corridors now control reagent selection authority exceeding fifty million dollars in annual spend.
Germany
ISO-certified manufacturing sites anchor European distribution networks for master mix formulations. The EMA's IVDR transition demands expanded technical documentation from manufacturers seeking CE marking. Notified bodies in Berlin and Munich experience backlog delays exceeding fourteen months for technical documentation review.
Switzerland
Thermostable DNA polymerase production concentrates in specialized fermentation facilities serving global enzyme demand. Swissmedic maintains stringent oversight of diagnostic reagent quality for domestic distribution. Basel-area chemical manufacturers supply precursor chemistries for fluorescent probe synthesis.
India
The country's PLI scheme for medical device manufacturing attracts contract reagent production for Southeast Asian distribution. CDSCO expands molecular testing authorization for tuberculosis and HIV monitoring programs. Research institutions in Delhi and Bangalore deploy SYBR Green for preliminary screening where multiplexing is unnecessary.
Brazil
Agricultural biotechnology firms scale trait-verification testing to meet export certification standards for gene-edited crops. ANVISA expands molecular testing authorization for infectious disease detection workflows. São Paulo-based diagnostic laboratories upgrade to IVDR-compliant reagent systems for regional distribution.
Global Qpcr Reagents Market Competitive Landscape
Multi-source procurement dominates the current landscape as pharmaceutical buyers displace long-term exclusive supply agreements. The vendor base organizes into three tiers: integrated raw-material-to-finished-reagent pipelines, thermal-cycler-dependent pull-through specialists, and ISO-certified regional formulators. Strategic archetypes include backward-integrated enzyme producers, instrument-locked reagent houses, and GMP-validated documentation providers. Capacity expansion and portfolio diversification represent the dominant competitive moves as manufacturers demonstrate technical equivalence across enzyme lots.
Among integrated life science conglomerates, Thermo Fisher Scientific and QIAGEN exemplify archetypes spanning raw material control to finished reagent distribution. Thermo Fisher represents the backward-integrated enzyme producer model with captive fermentation capacity, while QIAGEN occupies a position as the ISO-certified regional manufacturing anchor for European distribution. Bio-Rad Laboratories sits within the instrument-locked reagent tier, where thermal-cycler compatibility drives reagent pull-through from installed bases.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| QIAGEN |
| F. Hoffmann-La Roche |
| Agilent Technologies |
| Merck KGaA |
| Promega Corporation |
| Takara Bio |
| Quantabio |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between GMP-validated and research-grade reagents splits both pricing power and supply chain configuration across the qPCR reagents sector. Pharmaceutical procurement offices pay substantial premiums for documented CoA traceability and ISO 13485 compliance, while academic buyers absorb lower per-reaction costs through unbundled SYBR Green formulations that sacrifice regulatory documentation.
Pricing Analysis
Warranty and technical support bundling separates premium master mix offerings from commodity enzyme sales in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and lot-to-lot consistency guarantees, with GMP-validated tiers commanding multiples over research grades. Pricing pressure stems from multi-source procurement mandates as pharmaceutical buyers force manufacturers to demonstrate technical equivalence across enzyme lots. Contract research organizations exhibit highest price sensitivity through centralized vendor management offices, while infectious disease reference laboratories show lowest sensitivity given non-negotiable specificity requirements for regulatory submissions.
Supply Chain Analysis
Specialized fermentation workforce availability in Germany and Switzerland anchors thermostable DNA polymerase production for global enzyme demand. Supply draws from rare earth element precursors facing Chinese export quota adjustments, fluorophore-quencher conjugates manufactured in Basel-area chemical facilities, and optimized buffer salt formulations produced regionally. Single-source vulnerability concentrates in three specialized fermentation facilities serving bulk enzyme demand. Distribution runs through ISO-certified manufacturing sites in Germany anchoring European networks, with Thermo Fisher's integrated pipeline sustaining North American supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The qPCR reagents sector sits in a technology-transition phase as digital PCR partitioning methods displace conventional qPCR for minimal residual disease tracking in oncology monitoring workflows.
For Market Incumbents: Deploy captive fermentation capacity as the defensive anchor against enzyme supply concentration risks. Thermo Fisher Scientific's backward-integrated model demonstrates how raw material-to-finished-reagent pipeline control sustains pricing power when multi-source procurement pressures margins. Incumbents must absorb IVDR compliance costs for CE marking retention while smaller competitors withdraw niche assay claims. For New Entrants and Emerging Players: Agricultural biotechnology firms in Brazil and Argentina represent an underserved buyer archetype scaling trait-verification testing for gene-edited crop export certification. Lyophilized reagent formats with ambient stability for point-of-care molecular platforms offer additional white space under FDA's evolving LDT oversight framework. Go-to-market positioning should emphasize IVDR-compliant documentation for regional distribution into Southeast Asian diagnostic infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with ISO-certified regional formulators given India's PLI scheme attracting contract reagent production for medical device manufacturing. Long-term viability over a five-to-ten year window favors manufacturers with demonstrated technical equivalence across enzyme lots and validated-for-GMP documentation tiers. The signal to watch is backlog duration at German notified bodies for technical documentation review, as fourteen-month delays indicate compliance cost absorption capacity separating viable acquisition targets from withdrawal candidates.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | CE marking retention under EMA's IVDR transition opens European procurement channels for GMP-validated tiers. |
| Lyophilized Reagent Format Development | Ambient stability enables point-of-care molecular platforms under FDA's evolving LDT oversight framework. |
| Multi-Source Procurement Compliance | Technical equivalence demonstration across enzyme lots satisfies pharmaceutical buyer consolidation mandates. |
| Backward Integration into Enzyme Fermentation | Captive thermostable DNA polymerase production mitigates geographic vulnerability to energy price spikes. |
| Digital PCR Convergence R&D | Partitioning technology integration captures absolute quantification applications in liquid biopsy monitoring. |
Research Methodology
Multi-period observation of reagent procurement patterns, regulatory submission timelines, and instrument platform adoption anchored the trend analysis, supplemented by interviews with molecular testing directors at academic medical centers, quality assurance leads at pharmaceutical companies, procurement managers at contract research organizations, and regulatory affairs specialists at diagnostic reagent manufacturers. Secondary validation drew from FDA IVD pathway filings, EMA IVDR technical documentation requirements, WHO prequalification program records, and ISO 13485 certification databases. Bottom-up reaction volume estimates across end-user segments triangulated with top-down market value reconstruction.
Input-output matrices mapped enzyme fermentation capacity, fluorophore precursor chemical flows, and finished reagent distribution through notified body jurisdictions across the projection horizon. Segmentation dimensions spanned product type, probe chemistry technology, application area, and end-user procurement authority. CAGRs were derived from growth rate reconciliation between demand-side expansion in precision medicine pipelines and supply-side constraints in specialized fermentation capacity. Forecast inputs incorporated IVDR implementation pace at German notified bodies and decentralized testing authorization protocols under FDA oversight.
Revisions become necessary when notified body backlog durations exceed eighteen months, Chinese export quota adjustments disrupt fluorophore precursor supply, or digital PCR partitioning costs compress qPCR addressable market in oncology monitoring faster than modeled. Material deviation in these triggers warrants pause and re-evaluation of manufacturer viability assessments and segment growth rate assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Aptamers Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Biobank Market
Biotechnology Services
Custom Assays Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
In-Vitro Fertilization Services Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Cell Lysis and Disruption Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Recombinant Proteins Manufacturing Services Market
Biotechnology Services
Global Cell Isolation/Cell Separation Market
Biotechnology Services
Recombinant Factor C Assay Market