
 Research Antibodies Market | 2026-2036
Research Antibodies Market Size, Share, and Industry Trends Forecast 2026-2036
Research Antibodies Market Intelligence
The capital-intensity divergence between in-house hybridoma facilities and outsourced recombinant production is bifurcating competitive positioning across the Research Antibodies Market. Thermo Fisher Scientific Inc. leverages its end-to-end reagent ecosystem to dominate bulk supply contracts with academic institutes. Cell Signaling Technology Inc. differentiates through phosphorylation-site specificity and rigorous batch validation protocols that sustain premium positioning among oncology researchers.
Research antibodies are immunoglobulin-based reagents produced through hybridoma culture, phage display, or single B cell cloning, typically purified by protein A/G chromatography and validated for specificity via Western blotting or knockout cell line confirmation; they serve as detection and quantification tools in protein analysis, diagnostic assay development, and therapeutic target validation. Monoclonal antibodies occupy the largest value share due to their batch-to-batch consistency and defined epitope specificity, while recombinant antibodies represent the fastest-expanding product category as synthetic antibody engineering enables humanization and reduced cross-reactivity risk. Within applications, immunohistochemistry and flow cytometry command the highest per-unit pricing as both require extensive tissue-specific validation and fluorophore-conjugated customization.
FDA oversight of antibody-based companion diagnostics, combined with EMA's MDR requirements for IVD-certified reagents and ISO 13485 quality management mandates, elevates compliance costs while simultaneously screening out low-validity suppliers. China's NMPA has accelerated review pathways for imported research-grade antibodies, altering import substitution dynamics for domestic hybridoma producers. Stakeholders must monitor regulatory convergence between diagnostic and research-use-only classifications, as reclassification would force additional clinical validation investments across entire antibody portfolios.
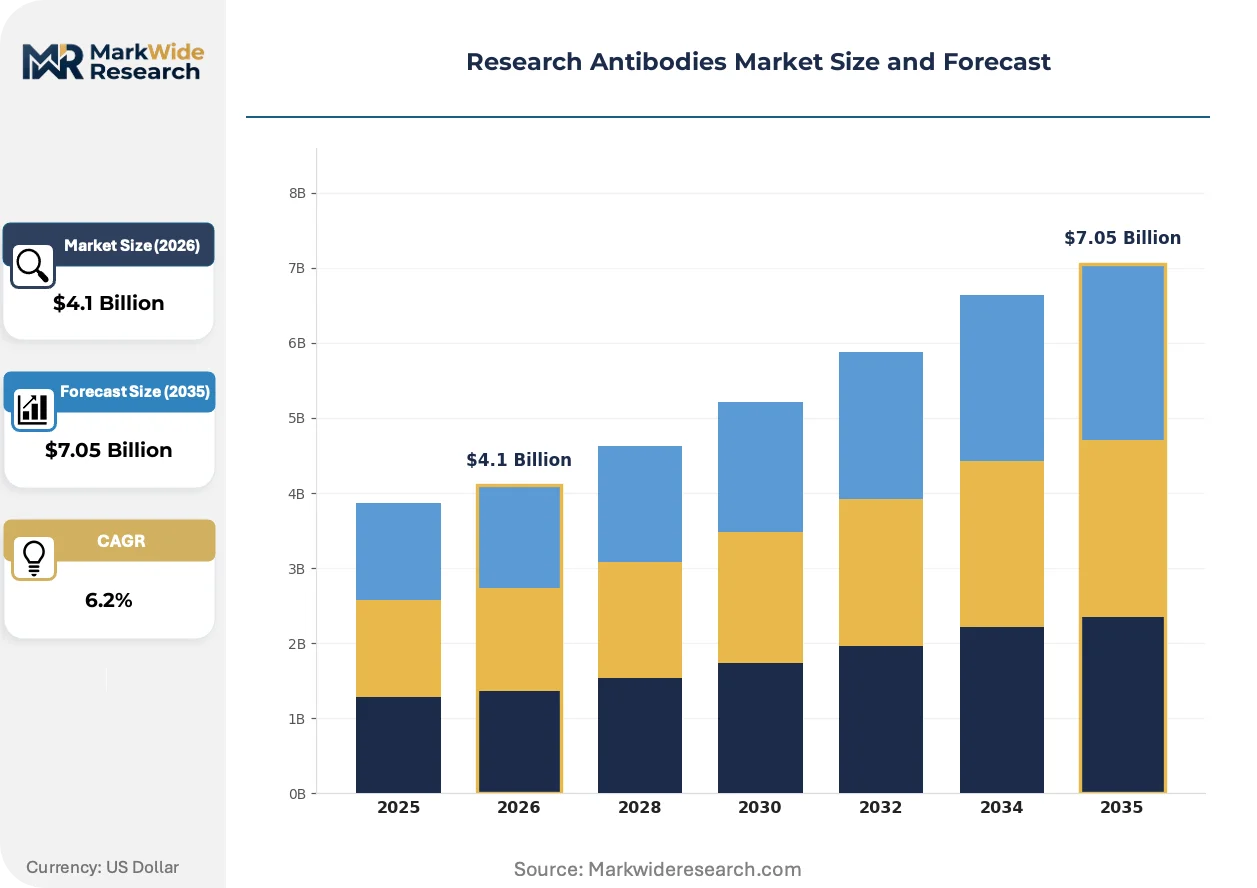
Market Dynamics
Precision medicine pipelines are maturing faster than hybridoma production capacity can adapt, forcing pharmaceutical manufacturers to expand recombinant antibody procurement budgets and triggering a bifurcation between in-house facilities and outsourced production networks.
Growth Catalysts
- FDA Biosimilar Guidance Evolution:Tighter validation requirements for antibody specificity are screening out low-validity suppliers and consolidating demand toward certified producers in the United States.
- Phosphorylation-Site Research:Oncology researchers require ever-more-specific detection reagents for signal transduction studies, pulling premium-priced validated antibodies into diagnostic assay development workflows.
- China NMPA Accelerated Review:Streamlined import pathways for research-grade antibodies are altering substitution dynamics for domestic hybridoma producers and expanding foreign supplier access.
Market Restraints
- Hybridoma Facility Capital Intensity:In-house monoclonal production requires protein A/G chromatography infrastructure and dedicated cleanroom space that locks capital for 7-10 year depreciation cycles.
- European MDR Compliance Burden:IVD-certified reagent mandates under EMA frameworks elevate batch validation costs and extend time-to-market for research-use-only antibody portfolios.
- Recombinant Platform Substitution Threat:Synthetic antibody engineering enables humanization and reduced cross-reactivity risk, compressing pricing power for traditional polyclonal suppliers.
Strategic Opportunities
- Single B Cell Cloning Convergence:Integration of microfluidic isolation with next-generation sequencing is opening white space in rare antibody discovery for infectious disease targets.
- Flow Cytometry Customization Demand:Fluorophore-conjugated antibody production for multiplexed cell analysis commands premium pricing and remains underpenetrated in academic core facilities.
- ISO 13485 Certification Tailwind:Quality management mandates for diagnostic-grade reagents create competitive moats for suppliers willing to absorb clinical validation investments.
Industry Challenges
- Knockout Cell Line Validation Expertise Gap:Confirming antibody specificity requires CRISPR-engineered negative controls that demand molecular biology skill sets scarce in traditional reagent vendors.
- Batch-to-Batch Consistency Certification Timelines:Western blot validation protocols for tissue-specific applications extend quality control cycles and strain working capital for mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Research Antibodies Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.05 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal, Polyclonal, Recombinant, Conjugated, Fragment Antibodies Application: Flow Cytometry, Western Blotting, Immunohistochemistry, ELISA, Immunoprecipitation End User: Academic Institutes, Contract Research Organizations, Diagnostic Labs, Pharmaceutical Manufacturers Technology: Hybridoma, Phage Display, Synthetic Antibody, Transgenic Animal, Single B Cell Technology |
| Companies Covered | Thermo Fisher Scientific Inc., Cell Signaling Technology Inc., Abcam Plc, Merck KGaA, Bio-Rad Laboratories Inc., Agilent Technologies Inc., BD (Becton, Dickinson and Company), Bio-Techne Corporation, Santa Cruz Biotechnology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Research Antibodies Market Strategic Shifts & Innovations
Recombinant antibody engineering is actively reshaping competitive positioning by compressing the cost premium between synthetic and hybridoma-derived reagents while simultaneously enabling humanization pathways previously inaccessible to research-grade suppliers.
Phage display technology is displacing traditional immunization-based antibody generation in therapeutic target validation workflows. Biopharma discovery groups are adopting synthetic libraries at 2-3x the pace of academic institutes, compressing the timeline from antigen identification to lead candidate selection from months to weeks and eroding the historical advantage of established hybridoma facilities.
EMA's MDR framework for IVD-certified reagents is elevating documentation requirements across European supply chains. Manufacturers must now maintain design history files and post-market surveillance systems previously reserved for clinical diagnostics, forcing research-use-only suppliers to either absorb compliance costs or exit the diagnostic adjacency entirely.
Core facility consolidation at major research universities is concentrating antibody procurement authority among fewer technical specialists with direct vendor relationships. This channel compression is visible most acutely in the United States and Germany, where centralized purchasing agreements with end-to-end reagent ecosystems are displacing fragmented catalog ordering through traditional distribution intermediaries.
Research Antibodies Market Segmentation
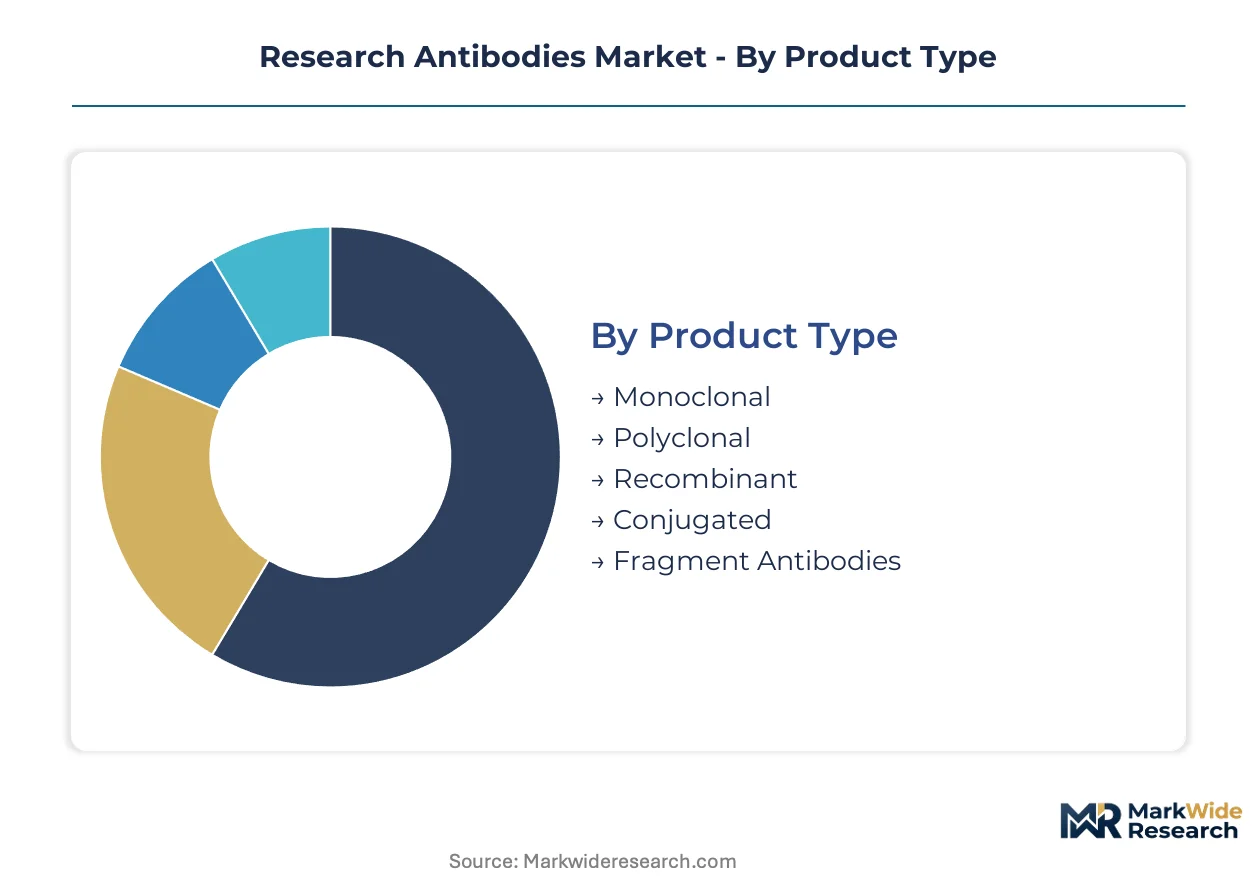
Antibody procurement decisions hinge on validation grade, production method, and downstream application requirements. Each segmentation axis carries distinct regulatory footprints and pricing architectures that reshape supplier selection criteria across pharmaceutical and academic channels.
Product Type:
FDA's evolving biosimilar guidance and Europe's MDR framework impose divergent specificity documentation requirements across antibody formats.
- Monoclonal:Derived from single B cell clones with defined epitope specificity and batch-to-batch consistency. Academic institutes in the United States concentrate procurement here for longitudinal studies requiring reproducible reagent performance.
- Recombinant:Engineered through synthetic gene expression enabling humanization and reduced immunogenicity risk. Pharmaceutical manufacturers in Germany and China are expanding procurement budgets fastest for this category as precision medicine pipelines mature.
- Polyclonal:Multi-epitope recognition from heterogeneous immunoglobulin pools; remains cost-effective for diagnostic assay development where absolute specificity is secondary.
- Conjugated:Fluorophore or enzyme-linked derivatives requiring additional purification validation; commands premium pricing in flow cytometry workflows.
- Fragment Antibodies:F(ab')2 or Fab constructs offering tissue penetration advantages; niche adoption in immunohistochemistry applications requiring reduced Fc-mediated background.
Monoclonal antibodies handle the majority of throughput; recombinant antibodies are climbing the fastest on share.
Application:
Pricing power concentrates where tissue-specific validation and fluorophore customization demands intersect.
- Immunohistochemistry:Tissue section staining requiring extensive cross-reactivity screening and antigen retrieval optimization. Diagnostic labs in the United States drive premium procurement for companion diagnostic development under FDA oversight.
- Flow Cytometry:Multiplexed cell surface marker detection using fluorophore-conjugated panels. Academic core facilities in Germany face underpenetrated supply for complex multiplex configurations.
- Western Blotting:Protein separation and detection via chemiluminescent or fluorescent secondary antibodies; remains volume leader in basic research workflows.
- ELISA:Quantitative antigen detection in microplate formats; standardized protocols favor polyclonal reagents for capture antibody roles.
- Immunoprecipitation:Native protein complex isolation requiring high-affinity capture; recombinant formats gain traction for reduced light chain contamination.
Western blotting maintains the largest installed base; flow cytometry posts the steepest expansion trajectory.
End User:
Procurement authority consolidation is bifurcating between centralized academic purchasing and fragmented CRO project-based ordering.
- Academic Institutes:Bulk supply contracts with end-to-end reagent ecosystems dominate as core facility consolidation concentrates technical specialist authority.
- Pharmaceutical Manufacturers:Recombinant antibody procurement budgets are expanding fastest as therapeutic target validation workflows absorb synthetic engineering capabilities.
- Contract Research Organizations:Project-based demand with rapid turnaround requirements; price-sensitive to batch validation timelines.
- Diagnostic Labs:IVD-certified reagent mandates under EMA MDR and FDA companion diagnostic guidance elevate compliance investment thresholds.
Academic institutes command the largest procurement volume; pharmaceutical manufacturers are gaining share fastest.
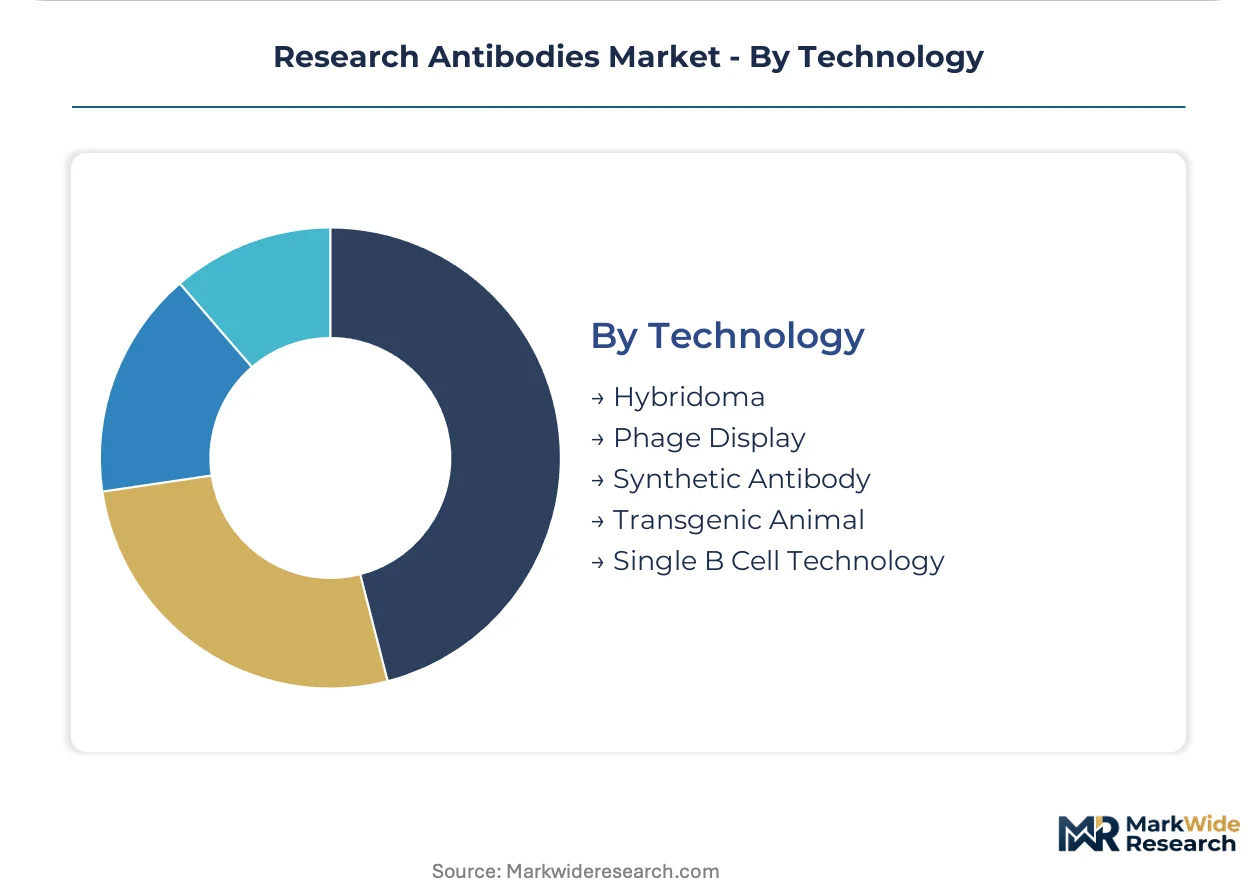
Technology:
Capital intensity divergence between in-house hybridoma infrastructure and outsourced recombinant production is reshaping competitive positioning.
- Hybridoma:Traditional mouse B cell immortalization requiring dedicated cleanroom space and protein A/G chromatography infrastructure; 7-10 year depreciation cycles lock capital.
- Phage Display:Synthetic library screening compressing lead candidate selection from months to weeks; biopharma discovery groups adopt at accelerated pace versus academic institutes.
- Single B Cell Technology:Microfluidic isolation paired with next-generation sequencing opens rare antibody discovery for infectious disease targets.
- Synthetic Antibody:Fully in vitro gene synthesis enabling rapid humanization; displacing immunization-based generation in target validation workflows.
- Transgenic Animal:Human immunoglobulin locus knock-in platforms for therapeutic-grade discovery; capital-intensive with limited research-grade penetration.
Hybridoma retains the dominant production base; phage display is expanding most quickly on adoption share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany while China captures volume expansion through accelerated import pathways. Translational research clusters in Boston and Heidelberg sustain premium procurement for validated reagents. Domestic hybridoma producers in Shanghai face substitution pressure from foreign suppliers accessing streamlined NMPA reviews.
United States
FDA companion diagnostic oversight and precision medicine pipeline maturation drive pharmaceutical procurement expansion. The agency's evolving biosimilar guidance tightens antibody specificity validation requirements. Boston-Cambridge and San Diego biotech corridors concentrate demand for phosphorylation-site-specific reagents among oncology researchers.
Germany
EMA MDR framework implementation elevates IVD-certified reagent compliance costs for diagnostic labs. Batch validation documentation and post-market surveillance systems extend time-to-market for research-use-only portfolios. Heidelberg and Munich academic core facilities consolidate purchasing authority through centralized agreements with end-to-end reagent ecosystems.
China
NMPA accelerated review pathways for imported research-grade antibodies alter domestic substitution dynamics. Pharmaceutical manufacturers in Shanghai and Suzhou expand recombinant antibody procurement budgets as therapeutic target validation workflows mature. Beijing-Tianjin research clusters absorb synthetic antibody engineering capabilities at compressed adoption timelines.
Japan
PMDA regulatory convergence with ICH guidelines shapes import validation requirements for foreign suppliers. Academic institutes in Kanto and Kansai regions maintain hybridoma-dependent procurement for longitudinal reproducibility studies. Osaka pharmaceutical manufacturing bases invest in recombinant platform substitution to reduce cross-reactivity risk in therapeutic development.
United Kingdom
Post-Brexit divergence from EMA frameworks creates parallel compliance pathways for antibody suppliers. London-Oxford-Cambridge golden triangle concentrates flow cytometry customization demand among academic core facilities. Manchester and Edinburgh diagnostic labs navigate dual regulatory obligations for IVD-certified reagent portfolios.
Research Antibodies Market Key Industry Players
Concentration sits with diversified life science conglomerates controlling end-to-end reagent ecosystems and specialized antibody producers commanding premium positioning through rigorous validation protocols. The vendor base stratifies across three tiers: integrated platform suppliers, specificity-focused boutiques, and catalog distributors. Dominant competitive moves include strategic partnerships with academic core facilities and portfolio expansion into conjugated reagent customization.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Merck KGaA occupy positions anchored by chromatography infrastructure and global distribution networks. Cell Signaling Technology Inc. exemplifies the specificity-focused archetype through phosphorylation-site validation expertise. These three entities represent divergent strategic postures: scale-driven ecosystem control versus premium-tier scientific differentiation versus hybrid production-distribution integration.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Cell Signaling Technology Inc. |
| Abcam Plc |
| Merck KGaA |
| Bio-Rad Laboratories Inc. |
| Agilent Technologies Inc. |
| BD (Becton, Dickinson and Company) |
| Bio-Techne Corporation |
| Santa Cruz Biotechnology Inc. |
| Others |
Cost & Logistics Intelligence
Protein A/G chromatography infrastructure concentration among established US and German suppliers locks in economies of scale that simultaneously elevate price floors for validated reagents and squeeze margin-compromised mid-scale hybridoma producers. This scale asymmetry bifurcates procurement authority toward end-to-end reagent ecosystems while fragmenting residual demand across catalog distributors.
Pricing Analysis
The customization-premium spread between fluorophore-conjugated flow cytometry panels and standard catalog antibodies commands 3-4x per-unit differentials based on tissue-specific validation depth and ISO 13485 certification tier. Three-tier pricing structure across premium, standard, and economy levels stratifies by batch validation rigor, with diagnostic-grade reagents bearing EMA MDR compliance premiums. Cost compression in polyclonal segments is intensifying because synthetic antibody engineering erodes hybridoma-derived pricing power. Contract Research Organizations exhibit highest price sensitivity due to project-based demand volatility, while pharmaceutical manufacturers absorb premium pricing for recombinant humanization pathways.
Supply Chain Analysis
Extended batch validation timelines for tissue-specific applications stretch antibody inventory cycles to 12-16 weeks, straining working capital for mid-scale producers dependent on Western blot confirmation protocols. Manufacturing gravity centers on the United States, Germany, and China, with hybridoma facilities concentrated in Boston-Cambridge and Heidelberg research corridors. Production draws from fetal bovine serum suppliers, recombinant protein expression systems, and fluorophore conjugation chemistries. Single-source vulnerability permeates CRISPR-engineered knockout cell line validation services, where molecular biology expertise concentrates among specialized boutiques. Distribution runs through academic core facility consolidation channels and direct pharmaceutical procurement agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through ISO 13485 certification and FDA companion diagnostic validation creates defensive moats that incumbent suppliers can deepen against synthetic antibody substitution threats.
For Market Incumbents: Consolidate phosphorylation-site specificity expertise and CRISPR validation capabilities through targeted capability acquisition, insulating premium positioning against phage display platform erosion. Absorb EMA MDR compliance costs to force research-use-only competitors toward diagnostic adjacency exits. Channel control through academic core facility partnerships remains the priority lever for volume retention. For New Entrants and Emerging Players: Anchor in single B cell cloning convergence for infectious disease targets, where microfluidic isolation paired with next-generation sequencing opens rare antibody discovery white space. Flow cytometry customization for multiplexed academic core facilities represents the most penetrable segment given underpenetrated supply for complex fluorophore configurations. Pursue direct technical specialist relationships rather than fragmented catalog distribution. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specificity-focused boutiques with rigorous batch validation protocols over scale-driven catalog distributors facing recombinant platform substitution. Long-term viability hinges on regulatory certification depth rather than production volume. The signal to watch is NMPA import pathway acceleration altering China domestic substitution dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Creates competitive moats against research-use-only suppliers under EMA MDR pressure. |
| Phosphorylation-Site Validation Expansion | Deepens premium positioning among oncology researchers in Boston-Cambridge corridor. |
| Single B Cell Cloning Capability Buildout | Captures rare antibody discovery demand for emerging infectious disease targets. |
| Academic Core Facility Partnership | Locks in bulk supply contracts as procurement authority concentrates among technical specialists. |
| Recombinant Humanization Platform | Reduces cross-reactivity risk for pharmaceutical therapeutic target validation workflows. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with antibody product managers, academic core facility directors, pharmaceutical target validation scientists, diagnostic lab procurement leads, and regulatory affairs specialists at IVD-certified reagent manufacturers. Secondary validation drew from FDA 510(k) filings for companion diagnostics, EMA MDR technical documentation, NMPA import registration databases, ClinicalTrials.gov antibody-dependent assay protocols, and ISO 13485 certification registries. Bottom-up segment sizing triangulated against top-down pharmaceutical R&D expenditure allocation models.
Across the analysis window, forecasts integrated product type segmentation by production technology, application-specific validation grade requirements, end-user procurement authority concentration, and geographic regulatory cluster divergence. CAGRs were derived from antibody procurement budget trajectories at major pharmaceutical manufacturers and academic institute reagent spending patterns. Modeling incorporated phage display adoption velocity, hybridoma facility depreciation cycles, and recombinant platform substitution elasticities.
Decision-makers should treat outputs as directional under sustained precision medicine pipeline maturation and stable regulatory convergence assumptions; material deviation in biosimilar guidance stringency or NMPA import pathway velocity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Western Blotting Market
Biotechnology Services
Global Downstream Processing Market
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Phospho-Specific Antibodies Market
Biotechnology Services
Precast Agarose Gel Market
Biotechnology Services
Cell Lysis and Disruption Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Biobank Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Global Qpcr Reagents Market