
 Phenoxy Resins Market | 2026-2036
Phenoxy Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Phenoxy Resins Market Intelligence
ISO 14001 environmental management certification is bifurcating the supplier base into qualified and non-qualified tiers. Mitsubishi Chemical Corporation leverages captive epichlorohydrin feedstock to sustain cost discipline across Asian production networks. Eastman Chemical Company differentiates through specialty solid-grade formulations aimed at North American aerospace primers. Kukdo Chemical Co., Ltd. anchors its position via backward integration into bisphenol-A supply chains serving Korean electronics molders.
Phenoxy resins are thermoplastic polyhydroxy ethers synthesized from bisphenol-A and epichlorohydrin, typically exhibiting molecular weights between 30,000 and 80,000 g/mol and glass transition temperatures ranging from 85°C to 100°C, functioning primarily as tough, flexible binders and adhesion promoters in protective coatings and structural composites. Solid-grade phenoxy resins dominate volume consumption in corrosion-resistant industrial coatings where long pot life and chemical resistance command premium positioning, while liquid variants represent the fastest-expanding category in electronics encapsulation applications requiring low-viscosity impregnation of miniaturized components. Water-soluble grades remain a niche but strategically important segment as formulators in the European Union pivot away from solvent-borne systems under tightening volatile organic compound mandates.
EPA emission standards under the Clean Air Act, REACH registration requirements administered by ECHA, and South Korea's K-REACH framework collectively constrain formulation chemistry and dictate regional product availability. These regulatory architectures elevate compliance costs for importers while creating protected markets for domestically certified producers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could displace incumbent coating chemistries and redirect specification toward phenoxy-based alternatives.
Market Dynamics
Automotive lightweighting mandates in Germany and Japan are compressing specification cycles for phenoxy-based composite binders, while semiconductor packaging miniaturization in South Korea pulls demand toward ultra-low viscosity grades. Supply concentration around captive epichlorohydrin producers in Asia is bifurcating procurement access.
Growth Catalysts
- REACH VOC thresholds:Tightening volatile organic compound limits under ECHA registration requirements are redirecting European coating formulators toward phenoxy-based alternatives from solvent-borne systems.
- Electronics encapsulation:Liquid-grade phenoxy resins are penetrating South Korean semiconductor packaging lines requiring low-viscosity impregnation of miniaturized components.
- Composite binder substitution:Automotive structural programs in Stuttgart and Nagoya are specifying phenoxy chemistry to replace incumbent epoxy-amine systems in carbon fiber prepregs.
Market Restraints
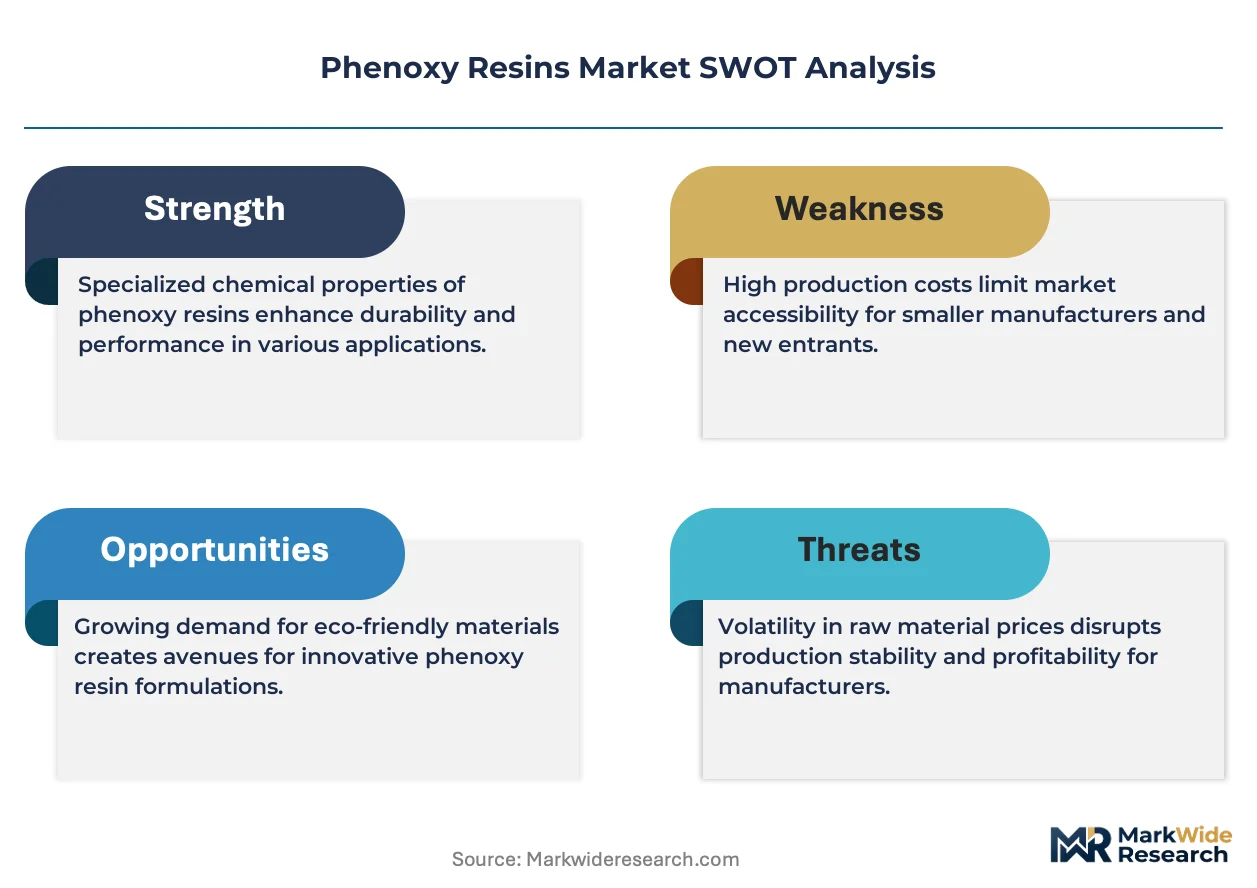
- Epichlorohydrin supply concentration:Captive production of this critical feedstock among Asian chemical conglomerates limits third-party access and elevates input cost volatility for non-integrated formulators.
- Bisphenol-A regulatory scrutiny:ECHA hazard classifications and state-level restrictions in California are constraining formulation flexibility and triggering reformulation costs.
- Polyimide substitution threat:High-temperature electronics applications above 150°C increasingly specify polyimide encapsulants, capping phenoxy penetration in advanced packaging nodes.
Strategic Opportunities
- Water-soluble grade expansion:EU Green Deal industrial transition incentives are accelerating R&D investment in aqueous phenoxy dispersions for architectural coating compliance.
- Aerospace primer specification:North American OEM qualification programs for solid-grade phenoxy primers on aluminum substrates present a white-space application beyond industrial maintenance coatings.
- PFAS displacement tailwind:Per- and polyfluoroalkyl substance restrictions under EPA and ECHA frameworks are redirecting specification toward phenoxy-based barrier coatings in food-contact and chemical-processing equipment.
Industry Challenges
- ISO 14001 certification backlog:Environmental management system audits are creating 12-18 month qualification delays for tier-two suppliers seeking automotive and electronics tier-one approval.
- Legacy coating line retrofit costs:Converting solvent-borne application equipment to handle water-soluble phenoxy grades requires capital expenditure that mid-sized job shops defer during interest rate elevation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenoxy Resins Market |
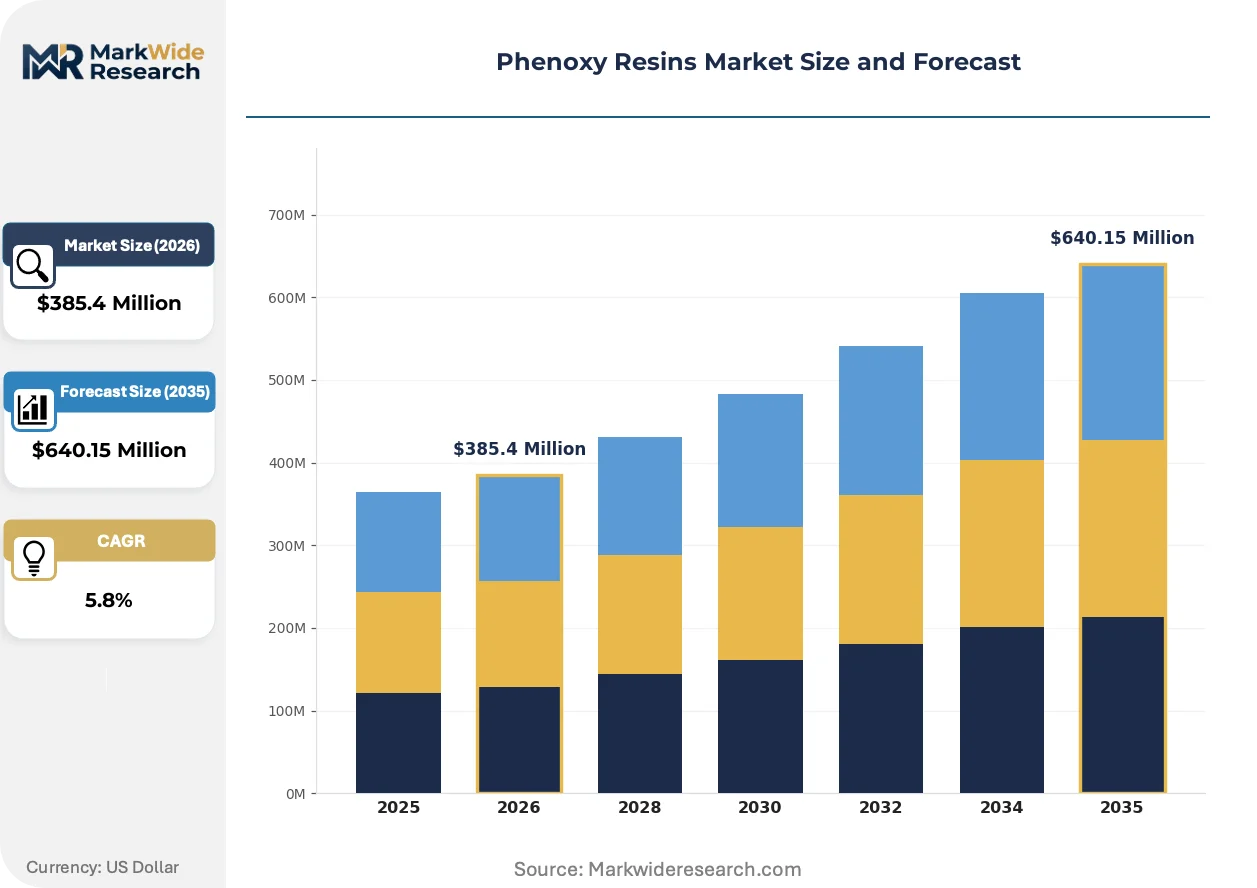
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid, Liquid, Water-Soluble, Low-Viscosity End Use Industry: Automotive, Adhesives, Coatings, Electronics Application: Encapsulation, Surface Coating, Composite, Ink Packaging Type: Drum, Bag, Tanker, Container |
| Companies Covered | Kukdo Chemical Co., Ltd., Eastman Chemical Company, Mitsubishi Chemical Corporation, Nan Ya Plastics Corporation, BASF SE, Huntsman International LLC, Hexion Inc., Showa Denko K.K., DIC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenoxy Resins Market Strategic Shifts & Innovations
Formulation chemistry is pivoting toward aqueous and ultra-low viscosity grades as regulatory thresholds tighten and electronics geometries shrink. Three distinct vectors are compressing development timelines and reshaping competitive positioning.
Ultra-low molecular weight liquid phenoxy resins are miniaturizing impregnation capabilities for advanced semiconductor packages below 10-micron feature sizes. Korean memory and logic foundries are adopting these grades at compressed qualification cycles. The technology is miniaturizing component geometries while maintaining adhesion and moisture barrier performance.
EPA Clean Air Act emission standards are forcing coating applicators in Ohio and Texas toward lower-VOC phenoxy formulations. Industrial maintenance and OEM finishing operations face compliance deadlines that compress reformulation windows. Automotive and aerospace segments in the US Southeast are responding with accelerated supplier audits and dual-source qualification.
Electronics molders in Gyeonggi Province are consolidating procurement around certified suppliers with captive bisphenol-A integration. Long-term supply agreements are replacing spot purchasing as packaging complexity elevates technical service requirements. This concentration is most visible in South Korea's semiconductor substrate manufacturing cluster.
Phenoxy Resins Market Segmentation
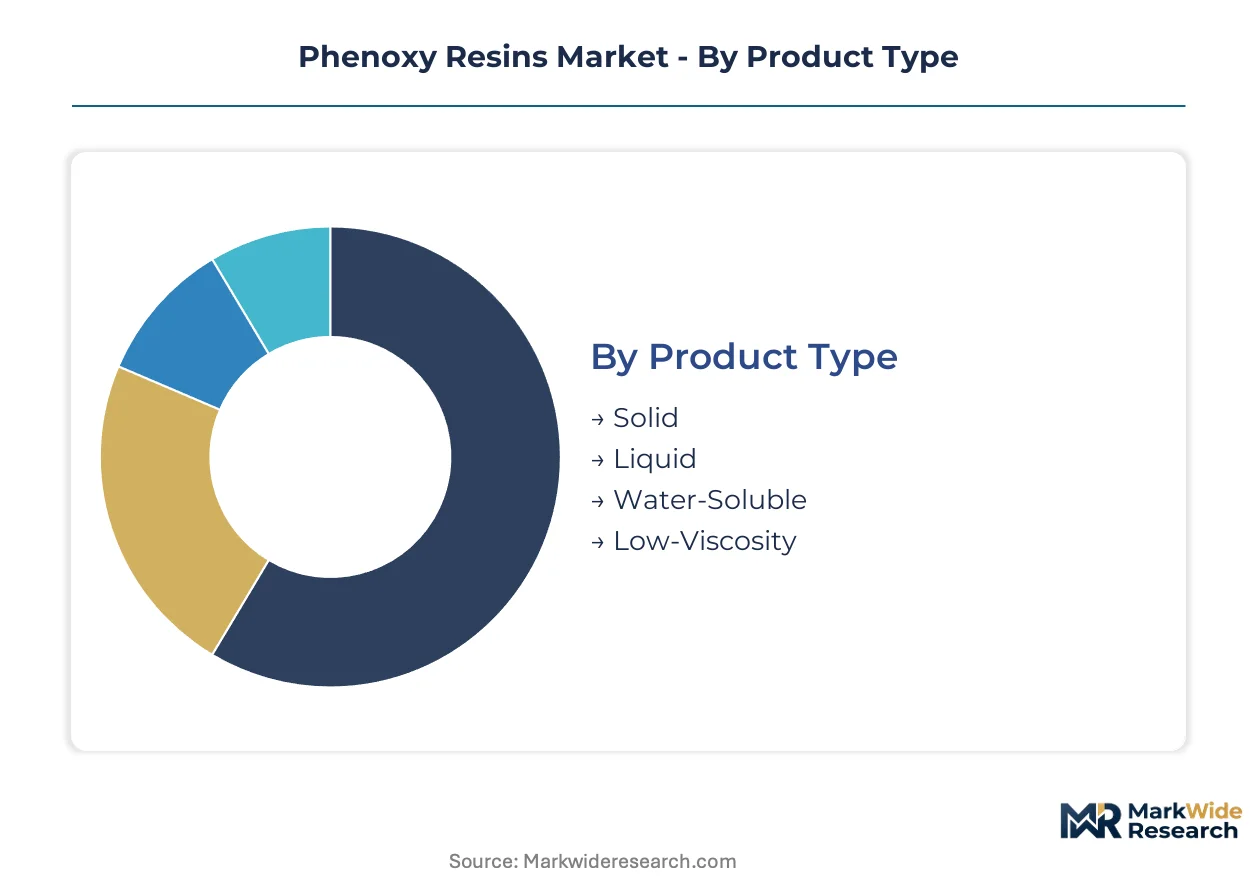
Phenoxy resin specifications diverge sharply across end-use requirements, with thermal stability demands in automotive composites contrasting against viscosity constraints in semiconductor encapsulation. Segmentation strategy determines feedstock allocation and captive production investments among integrated chemical producers.
Product Type:
Substitution pressure from polyimide and epoxy-amine systems concentrates most intensely on solid and standard liquid grades, while specialized low-viscosity and water-soluble variants defend niche positions through formulation lock-in.
- Solid:High molecular weight thermoplastic polyhydroxy ethers with glass transition temperatures between 85°C and 100°C serve corrosion-resistant industrial coatings and structural composite binders. Demand concentrates in German automotive lightweighting programs specifying phenoxy-based carbon fiber prepregs, though ECHA bisphenol-A hazard classifications constrain formulation flexibility.
- Liquid:Lower molecular weight variants offering reduced viscosity for spray and dip coating applications dominate North American aerospace primer specifications. Eastman Chemical Company targets this segment with specialty solid-grade formulations for aluminum substrate protection.
- Water-Soluble:Aqueous dispersions enable REACH-compliant architectural coatings as European formulators pivot from solvent-borne systems under tightening ECHA volatile organic compound mandates.
- Low-Viscosity:Ultra-low molecular weight grades penetrate South Korean semiconductor packaging lines requiring impregnation of miniaturized components below 10-micron feature sizes.
Solid grades anchor the volume base in industrial maintenance coatings while low-viscosity formulations gain share at the steepest rate through electronics miniaturization.
End Use Industry:
Cost tier stratification separates specification-intensive automotive and electronics applications from price-sensitive adhesive formulations.
- Automotive:Structural composite programs in Stuttgart and Nagoya specify phenoxy chemistry for carbon fiber prepregs replacing epoxy-amine systems under lightweighting mandates. Mitsubishi Chemical Corporation leverages captive epichlorohydrin feedstock to supply Asian automotive networks.
- Electronics:Semiconductor packaging miniaturization in Gyeonggi Province pulls demand toward ultra-low viscosity grades for advanced substrate encapsulation. Kukdo Chemical Co., Ltd. anchors supply through backward integration into bisphenol-A chains.
- Coatings:Industrial maintenance and OEM finishing operations face EPA Clean Air Act compliance deadlines compressing reformulation windows in Ohio and Texas.
- Adhesives:General-purpose bonding applications compete against lower-cost epoxy and polyurethane alternatives, constraining margin expansion.
Coatings command the broadest volume footprint across end-use industries while electronics applications expand most quickly through packaging complexity escalation.
Application:
Application maturity determines margin structure, with established surface coating protocols contrasting against emerging composite specifications.
- Surface Coating:Protective films for chemical-processing equipment and food-contact barriers benefit from per- and polyfluoroalkyl substance displacement tailwinds under EPA and ECHA frameworks.
- Encapsulation:Moisture barrier and adhesion promotion for semiconductor substrates drives Korean memory and logic foundry procurement consolidation around certified suppliers.
- Composite:Carbon fiber prepregs for automotive structural components require long pot life and chemical resistance specifications.
- Ink:Niche flexographic and gravure printing applications for packaging substrates.
Surface coating maintains the largest installed application base while encapsulation climbs the fastest through semiconductor packaging node advancement.
Packaging Type:
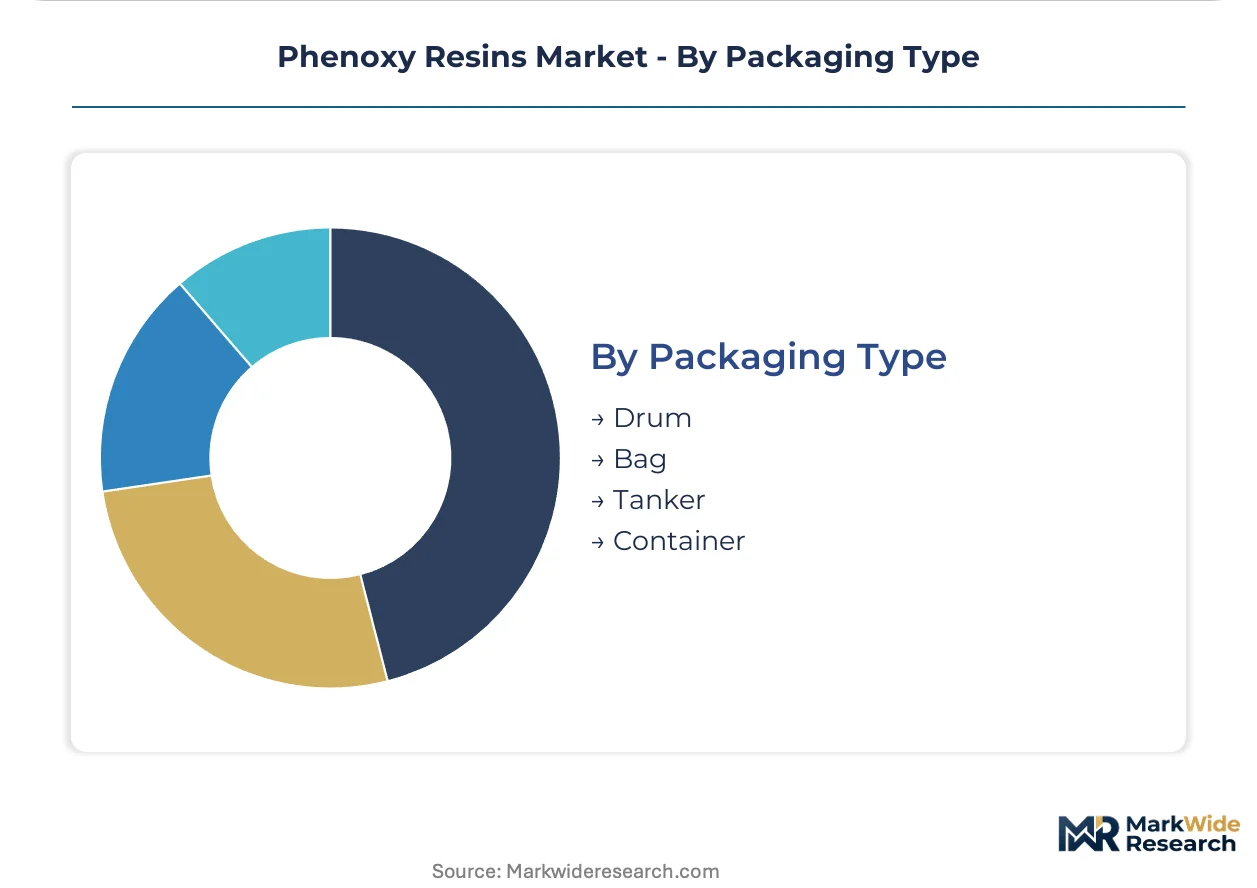
Supply chain configuration determines packaging economics, with bulk formats favored by integrated producers and unitized packaging serving fragmented formulator bases.
- Drum:Standard 200-liter steel containers dominate mid-volume coating formulator procurement across North American industrial maintenance sectors.
- Tanker:Bulk liquid transport serves high-throughput electronics molders in South Korean semiconductor clusters with dedicated supply agreements.
- Bag:Multi-layer paper and polymer sacks for solid-grade powder formulations in European architectural coating distribution.
- Container:Intermediate bulk containers and specialized totes for just-in-time adhesive compounder operations.
Drum packaging anchors procurement flexibility for tier-two formulators while tanker volumes expand fastest through Korean electronics supply chain concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's phenoxy resin distribution capacity, while the Kaohsiung harbor complex anchors Taiwanese electronics feedstock flows into East Asian semiconductor clusters.
Germany
Automotive lightweighting programs in Stuttgart specify phenoxy-based carbon fiber prepregs for structural composite applications. ECHA REACH registration requirements tighten volatile organic compound thresholds for coating formulations. The Rhine-Ruhr industrial corridor concentrates chemical production capacity serving domestic automotive OEMs.
United States
EPA Clean Air Act emission standards compress reformulation windows for industrial maintenance coatings in Ohio and Texas. Aerospace primer qualification programs in the Southeast pull demand toward solid-grade phenoxy formulations. The Gulf Coast petrochemical corridor maintains epichlorohydrin derivative production serving North American coating networks.
South Korea
Semiconductor packaging miniaturization in Gyeonggi Province drives ultra-low viscosity grade consumption for advanced substrate encapsulation. K-REACH framework compliance requirements constrain imported formulation chemistry. The Seoul Capital Area electronics cluster consolidates procurement around backward-integrated domestic suppliers.
Japan
Automotive composite specifications in Nagoya replace epoxy-amine systems with phenoxy chemistry under weight reduction mandates. METI industrial standards govern chemical substance handling in manufacturing processes. The Chubu region maintains specialty resin production capacity for precision electronics applications.
China
Dual carbon policy targets accelerate solvent-borne coating phase-outs in Yangtze River Delta manufacturing zones. MIIT industrial guidance promotes aqueous dispersion technologies for architectural applications. The Pearl River Delta electronics assembly cluster imports specialty grades for consumer device packaging.
Phenoxy Resins Market Key Industry Players
Listed leaders compete with private specialists across feedstock integration depth, with consolidated Asian chemical conglomerates facing fragmented Western formulation houses. Mitsubishi Chemical Corporation and Kukdo Chemical Co., Ltd. anchor the integrated tier through captive epichlorohydrin supply, while specialty distributors occupy non-integrated niches. Three archetypes dominate: backward-integrated feedstock owners, specialty grade formulators, and regional trading intermediaries. Capacity expansion and strategic partnerships represent the dominant competitive vectors as qualification timelines extend.
Among East Asian integrated producers, Mitsubishi Chemical Corporation exemplifies the captive feedstock archetype, Kukdo Chemical Co., Ltd. occupies a position within Korean electronics supply chains, and Eastman Chemical Company represents the specialty formulation tier targeting North American aerospace specifications. These three entities anchor distinct competitive positions without overlapping strategic territory.
| Leading Market Players |
|---|
| Kukdo Chemical Co., Ltd. |
| Eastman Chemical Company |
| Mitsubishi Chemical Corporation |
| Nan Ya Plastics Corporation |
| BASF SE |
| Huntsman International LLC |
| Hexion Inc. |
| Showa Denko K.K. |
| DIC Corporation |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements with Korean electronics molders lock in both bisphenol-A supply access and price visibility across the analysis window, insulating backward-integrated producers from epichlorohydrin spot volatility while constraining margin flexibility for non-integrated formulators facing REACH compliance cost escalation.
Pricing Analysis
Certification level creates the primary spread, with ISO 14001-qualified grades commanding premium positioning against uncertified alternatives in automotive and electronics procurement. Three-tier pricing structure across specialty solid-grade, standard liquid, and commodity adhesive tiers reflects formulation complexity and captive feedstock access. Cost compression in standard liquid grades is intensifying because polyimide substitution threats above 150°C cap specification expansion. General-purpose adhesive formulators exhibit highest price sensitivity, while aerospace primer buyers prioritize qualification stability over unit cost.
Supply Chain Analysis
Inventory buffers at Rotterdam chemical terminals currently cover 8-12 weeks of European coating demand, though Korean electronics clusters operate on just-in-time tanker deliveries. Production gravity centers on Japan, South Korea, and Germany, with captive epichlorohydrin facilities anchoring Asian supply. Feedstock chains draw from bisphenol-A and epichlorohydrin inputs, with caustic soda and propylene as secondary dependencies. Single-source vulnerability concentrates around Mitsubishi Chemical Corporation's Asian epichlorohydrin network. Distribution runs through bulk tanker contracts for integrated electronics molders and drum-based spot procurement for tier-two coating formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where ECHA REACH registration and K-REACH compliance create 12-18 month qualification barriers that protect incumbent positions from rapid competitive displacement.
For Market Incumbents: Consolidate feedstock security through captive bisphenol-A integration or long-term supply agreements with Korean electronics clusters, while accelerating ISO 14001 certification audits to preempt tier-two supplier encroachment. Polyimide substitution above 150°C and emerging aqueous dispersion competitors represent the primary threats requiring R&D counterinvestment in ultra-low viscosity grades. For New Entrants and Emerging Players: Lead with water-soluble grade specialization targeting EU Green Deal transition incentives, where solvent-borne phase-outs create procurement gaps unmet by established Asian producers. North American aerospace primer qualification presents the most penetrable white-space, with solid-grade formulations for aluminum substrates offering a defensible go-to-market angle against industrial coating saturation. For Investors and Strategic Acquirers: Specialty grade formulators with aerospace and electronics qualification track records offer the strongest acquisition profile, particularly those possessing pilot-scale aqueous dispersion capabilities. Long-term viability hinges on 5-10 year regulatory continuity in REACH and K-REACH frameworks. The signal to watch is EPA per- and polyfluoroalkyl substance restriction acceleration, which would redirect food-contact and chemical-processing equipment specification toward phenoxy-based barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol-A | Captive feedstock supply secures cost discipline for Korean electronics molders. |
| Aqueous Dispersion R&D Expansion | EU Green Deal compliance accelerates architectural coating specification shifts. |
| Long-term Supply Agreement | Korean semiconductor clusters consolidate procurement around certified suppliers. |
| ISO 14001 Certification Investment | Environmental management qualification unlocks automotive tier-one approval. |
| Aerospace Primer Qualification | North American OEM programs extend solid-grade applications beyond industrial maintenance. |
Research Approach
Initial hypotheses were tested against primary input from plant managers at integrated resin producers, procurement leads at downstream coating formulators, technical R&D directors, and distribution channel partners, then refined through secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates across the projection horizon.
Variance decomposition across product type, end-use industry, application format, and regional production hub dimensions shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers and industry-specific inputs including automotive lightweighting program timelines and semiconductor packaging node advancement curves throughout the forecast period.
Forecasts assume regulatory continuity in REACH, K-REACH, and EPA Clean Air Act regimes; material policy shifts would require re-modeling. Epichlorohydrin supply disruption, bisphenol-A hazard reclassification, or polyimide technology breakthroughs represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Resin Intermediate Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
Europe Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
South America Engineering Plastics Market
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
Ammonium Polyphosphate (Phase II) Market
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Southeast Asia Modified Polypropylene Market