
 Lead Encapsulants Market | 2026-2036
Lead Encapsulants Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Encapsulants Market Analytics
Specialty chemical distribution is reconfiguring as lead encapsulant suppliers consolidate channel partnerships with photovoltaic and electronics OEMs. Dow leverages its silicone portfolio to anchor high-reliability electronics applications across North America and Asia. Shin-Etsu Chemical sustains vertical integration from monomer synthesis through formulated encapsulants, controlling cost structures in optical-grade segments. Henkel competes through adhesive-encapsulant hybrid platforms that extend its automotive electronics footprint.
Lead encapsulants are polymeric barrier materials—typically silicone, epoxy, or ethylene-vinyl acetate formulations cured at 120–150°C—that shield semiconductor junctions and photovoltaic cells from moisture, thermal cycling, and ionic contamination. Thermal encapsulants dominate volume demand in power electronics where junction temperatures exceed 150°C, while UV-curable variants capture margin pools in precision photonics assembly by eliminating oven curing steps. Aerospace applications remain specialized and low-volume, with hybrid formulations penetrating military-grade reliability specifications.
EPA regulations on lead content in industrial materials constrain formulation flexibility in US manufacturing, while REACH authorization processes in Europe phase certain lead compounds from consumer-facing electronics. China's GB standards and MEE environmental enforcement tighten domestic production compliance, redirecting export-oriented capacity toward certified low-lead grades. Stakeholders must monitor evolving substance restrictions across these three regulatory spheres to anticipate reformulation timelines and qualify alternative chemistries before supply disruptions materialize.
Market Dynamics
Photovoltaic module manufacturers are consolidating encapsulant procurement around certified low-lead grades as dual carbon goals in China and IRA clean-energy incentives in the US accelerate solar deployment timelines. Formulation chemistry is pivoting toward ethylene-vinyl acetate and silicone alternatives that satisfy REACH authorization timelines while maintaining barrier performance.
Growth Catalysts
- IRA Production Tax Credits:US solar manufacturers are expanding domestic encapsulant offtake to capture inflation-adjusted incentives for domestic content qualification.
- Dual Carbon Policy Framework:China's MIIT enforcement of industrial carbon intensity targets is redirecting polysilicon and encapsulant capacity toward certified low-carbon production lines.
- Perovskite Tandem Cell Commercialization:Next-generation photovoltaic architectures require moisture-barrier encapsulants with enhanced thermal stability, pulling specialty formulation demand.
Market Restraints
- Optical-Grade Silicone Monomer Concentration:Shin-Etsu Chemical and Dow control critical methyl silicone precursor supply, constraining independent formulator cost structures.
- REACH Authorization Friction:ECHA's sunset date extensions for certain lead stabilizers are compressing reformulation windows while alternative chemistries remain unqualified.
- Thermal Curing Energy Intensity:Oven-based curing at 120–150°C consumes natural gas-intensive process heat, exposing margins to European and Asian carbon pricing mechanisms.
Strategic Opportunities
- India PLI Scheme Absorption:Domestic solar module manufacturing incentives are creating first-mover encapsulant qualification opportunities for suppliers establishing local blending operations.
- UV-Curable Precision Photonics:Elimination of thermal curing steps enables electronics assemblers to integrate encapsulation into continuous surface-mount lines, collapsing process footprint.
- Automotive Power Electronics Expansion:Silicon carbide inverter deployment in electric vehicles is pulling high-temperature encapsulant demand for junction temperatures exceeding 175°C.
Industry Challenges
- Cross-Regional Certification Stacking:Simultaneous UL, VDE, and GB standard qualification timelines extend product launch cycles by 18–24 months.
- Formulation Talent Scarcity:Polymer chemists with dual expertise in photovoltaic reliability and semiconductor packaging command premium compensation, constraining R&D team scaling.
- Legacy Equipment Retrofit Complexity:Thermal curing lines require substantial capital redeployment to accommodate UV-curable or moisture-cure chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Encapsulants Market |
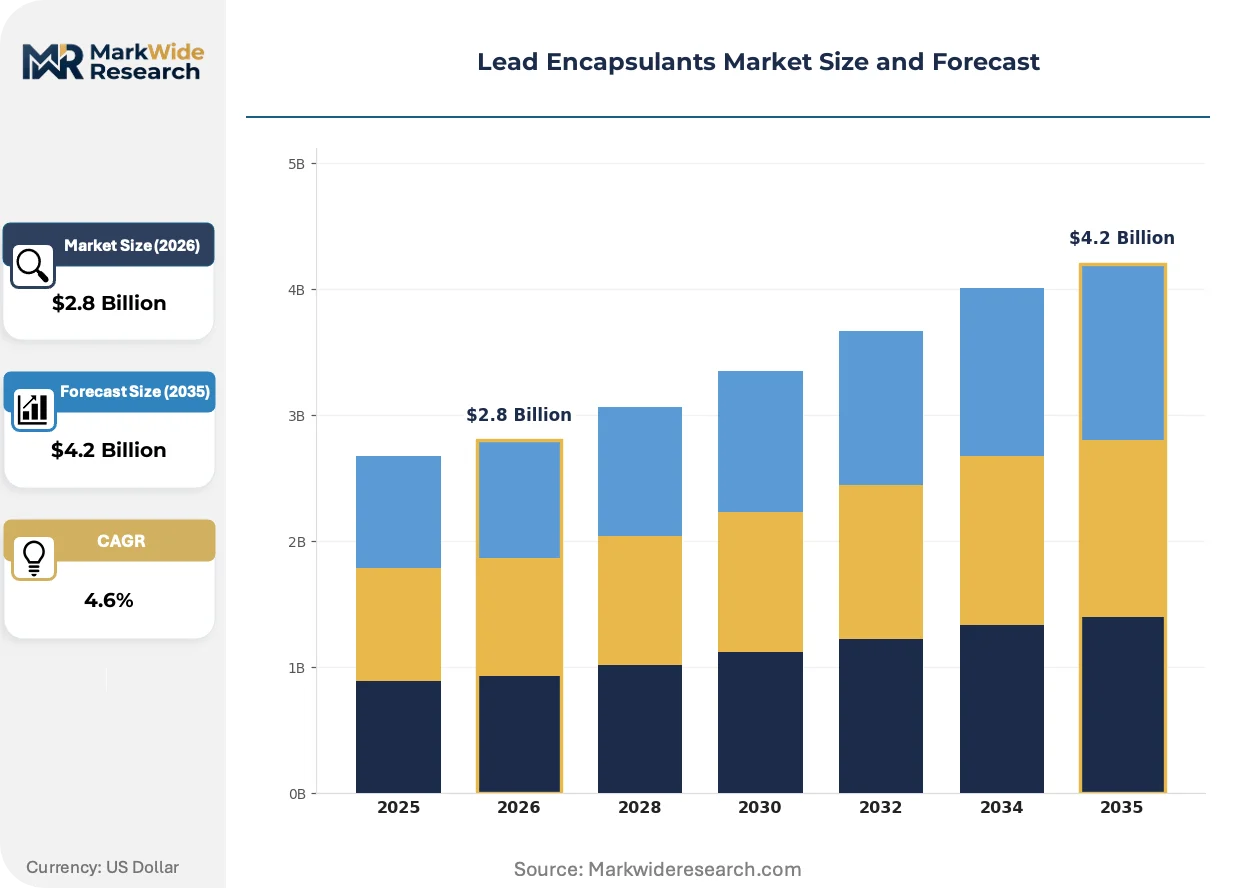
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal, Optical, UV-Curable, Hybrid Application: Electronics, Photovoltaics, Automotive, Aerospace End User: Manufacturers, Contractors, Laboratories, Research Institutions Form: Pre-Mixed, Liquid, Powder, Paste |
| Companies Covered | Dow, Shin-Etsu Chemical, Henkel, BASF, DuPont, H.B. Fuller Company, Hitachi Chemical, Panasonic, NuSil Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Encapsulants Market Evolving Landscape
Encapsulant chemistry is bifurcating between commodity ethylene-vinyl acetate for utility-scale photovoltaics and specialty silicone-epoxy hybrids for reliability-critical electronics. Three forces are compressing incumbent positioning and opening formulation white space.
UV-curable silicone encapsulants are collapsing the traditional thermal curing bottleneck in precision photonics assembly. Medical device and LiDAR manufacturers are adopting these materials to eliminate oven infrastructure and enable inline processing. The structural consequence is a compression of capital requirements for new encapsulation lines, enabling mid-scale electronics assemblers to bring barrier coating in-house rather than outsourcing to qualified contract manufacturers.
REACH authorization processes are forcing lead compound phase-out timelines that outpace alternative chemistry qualification. ECHA's sunset date mechanisms for certain stabilizer categories are compressing formulation windows while silicone and tin-based alternatives remain under toxicological review. Photovoltaic encapsulant suppliers serving European OEMs are responding by accelerating ethylene-vinyl acetate formulation shifts and pre-qualifying materials for dual REACH-RoHS compliance.
Buyer concentration among tier-one photovoltaic module manufacturers is consolidating procurement leverage around annual volume commitments. Long-term offtake agreements with specified lead-content thresholds are displacing spot-market purchasing in the solar supply chain. This pattern is most visible in China, where domestic panel production absorbs significant regional encapsulant supply and qualification timelines favor incumbent relationships.
Lead Encapsulants Market Segmentation
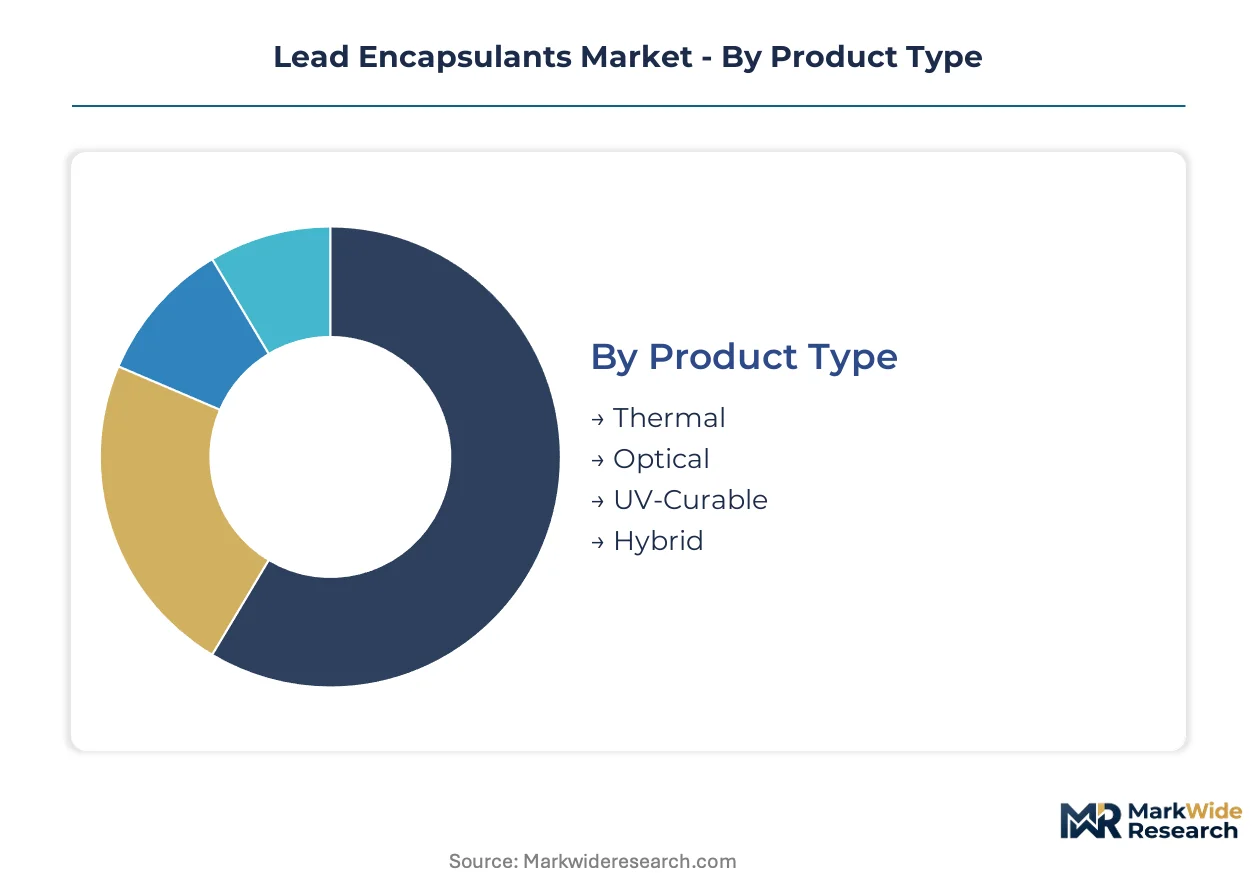
Encapsulant procurement patterns diverge sharply across formulation chemistry, application stress profiles, and customer scale. Understanding these segmentation boundaries clarifies where formulation investments concentrate and which qualification pathways determine supplier selection.
Product Type:
Cost tier stratification separates commodity formulations from specialty grades commanding formulation premiums.
- Thermal:Silicone and epoxy formulations engineered for continuous operation above 150°C dominate power electronics packaging. Junction reliability requirements in silicon carbide inverters are pulling demand toward boron-nitride-filled grades that manage heat dissipation without compromising dielectric strength.
- Optical:Methyl silicone precursors with refractive index matching and yellowing resistance specifications serve precision photonics and display applications. Shin-Etsu Chemical and Dow control critical monomer supply, constraining independent formulator participation in high-margin segments.
- UV-Curable:Acrylated silicone oligomers eliminate oven curing infrastructure, enabling inline encapsulation for medical device and LiDAR manufacturers.
- Hybrid:Silicone-epoxy copolymers balance thermal stability with moisture barrier performance for military-grade reliability specifications.
Thermal encapsulants hold installed capacity across power electronics foundries. UV-curable formulations are rotating up the share rankings in precision assembly operations.
Application:
Application stress profiles dictate barrier performance requirements and qualification timelines.
- Photovoltaics:Ethylene-vinyl acetate sheets and silicone gels protect cells from moisture ingress and potential-induced degradation. China's MIIT enforcement of dual carbon targets is redirecting encapsulant procurement toward certified low-carbon production lines serving domestic module assembly.
- Electronics:Semiconductor packaging demands ionic purity below 10 ppm and coefficient of thermal expansion matching silicon substrates. REACH authorization timelines for lead stabilizers are compressing reformulation windows while tin-based alternatives remain under ECHA toxicological review.
- Automotive:Under-hood temperatures exceeding 175°C in silicon carbide traction inverters require encapsulants with thermal conductivity above 2 W/m·K and glass transition temperatures above 200°C.
- Aerospace:Outgassing specifications per ASTM E595 and radiation resistance requirements constrain qualified material lists to hybrid formulations from established suppliers.
Photovoltaics holds installed capacity across utility-scale deployment pipelines. Automotive power electronics is rotating up the share rankings as electric vehicle production scales.
End User:
Customer scale determines procurement leverage and formulation customization depth.
- Manufacturers:Tier-one photovoltaic module producers and semiconductor foundries negotiate annual volume commitments with specified lead-content thresholds, displacing spot-market purchasing.
- Contractors:Installation and maintenance providers source pre-mixed encapsulants for field repair of damaged photovoltaic modules and electronics enclosures.
- Laboratories:R&D facilities and pilot lines purchase small-batch specialty grades for process development and reliability testing.
- Research Institutions:Academic and government laboratories drive early-stage formulation innovation, particularly for perovskite tandem cell barrier requirements.
Manufacturers hold installed capacity across qualified supplier relationships. Research institutions are rotating up the share rankings as next-generation cell architectures advance toward commercialization.
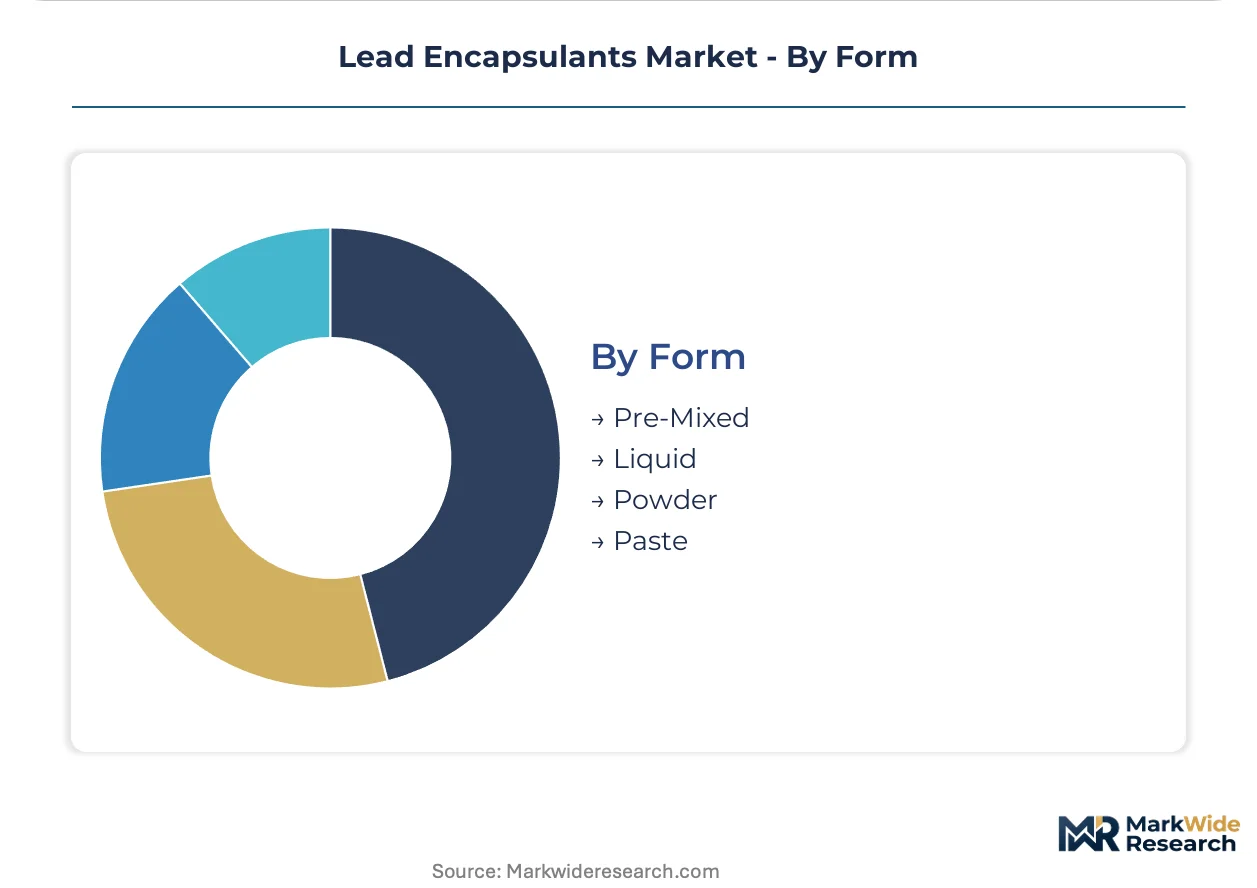
Form:
Physical state determines application equipment compatibility and mixing precision requirements.
- Pre-Mixed:One-component silicone pastes and epoxy resins eliminate metering errors and pot-life constraints in high-volume electronics assembly.
- Liquid:Low-viscosity silicone oils and solvent-dispersed epoxies enable vacuum impregnation of complex geometries in transformer and coil applications.
- Powder:Solid epoxy and phenolic formulations require elevated temperature and pressure for compression molding of high-voltage insulators.
- Paste:Thixotropic silicone compounds maintain vertical stability during dispense operations for gap-filling in power module substrates.
Pre-mixed formulations hold installed capacity across automated dispense lines. Paste consistency grades are rotating up the share rankings in power electronics gap-filling applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater ports and high-voltage grid interconnections underpin China's dominance in photovoltaic encapsulant consumption. Germany's Rhine corridor chemical logistics infrastructure anchors European formulation capacity. The US Gulf Coast petrochemical pipeline network supports domestic silicone precursor supply.
China
Domestic module manufacturers absorb substantial regional encapsulant supply as polysilicon capacity expands along the Yangtze River. MIIT enforcement of dual carbon targets redirects procurement toward certified low-carbon production lines. Wuxi and Suzhou industrial clusters concentrate optical-grade silicone formulation operations serving tier-one panel producers.
United States
IRA production tax credits accelerate domestic solar manufacturing buildout across the Southwest and Southeast. EPA regulations on lead content constrain formulation flexibility for electronics applications. Texas Gulf Coast petrochemical complexes anchor methyl silicone monomer production feeding encapsulant blenders.
Germany
Automotive power electronics demand pulls high-temperature encapsulant procurement from silicon carbide inverter suppliers. REACH authorization timelines for lead stabilizers compress reformulation windows for electronics OEMs. BASF's Ludwigshafen complex anchors European formulation R&D and specialty chemical distribution.
Japan
Precision photonics and LiDAR assembly drive UV-curable encapsulant adoption in medical device and automotive sensor supply chains. METI industrial decarbonization roadmaps pressure thermal curing energy intensity. Osaka-Kobe industrial corridor concentrates hybrid silicone-epoxy formulation expertise for aerospace reliability specifications.
India
PLI scheme incentives for domestic solar module manufacturing create first-mover encapsulant qualification opportunities. BIS certification requirements extend product launch timelines for imported formulations. Gujarat and Rajasthan industrial zones concentrate photovoltaic assembly capacity with growing local blending operations.
Lead Encapsulants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in monomer and precursor supply. The market structure consolidates around diversified chemical conglomerates with captive silicone supply and independent formulators dependent on merchant monomer procurement. Two strategic archetypes dominate: vertically integrated polymer producers controlling cost structures through backward integration into methyl silicone precursors, and adhesive-encapsulant hybrid platforms leveraging automotive electronics relationships. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for IRA and PLI scheme qualification windows.
Within the integrated chemical conglomerate tier, Dow and Shin-Etsu Chemical exemplify archetypes of upstream-controlled supply structures. Dow leverages its silicone portfolio across North American and Asian electronics applications. Shin-Etsu Chemical sustains in-house production from monomer synthesis through formulated encapsulants. Henkel occupies a position in the adhesive-encapsulant hybrid space, extending its automotive electronics footprint through formulation platforms that bridge bonding and barrier functions.
| Leading Market Players |
|---|
| Dow |
| Shin-Etsu Chemical |
| Henkel |
| BASF |
| DuPont |
| H.B. Fuller Company |
| Hitachi Chemical |
| Panasonic |
| NuSil Technology |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta freight corridors carry methyl silicone monomers from Wuxi formulation plants to domestic photovoltaic module manufacturers, with container rates and port congestion feeding directly into both supplier concentration effects and downstream tiered pricing for REACH-compliant grades versus standard formulations.
Pricing Analysis
Three-tier pricing structure across optical-grade silicone, certified low-lead EVA, and commodity thermal formulations separates premium barrier performance from mid-tier REACH compliance and economy-grade domestic supply. Price differentiation rests on ECHA authorization status and volume-commitment scale, with annual offtake contracts commanding 15-20 point spreads over spot procurement. Cost compression in commodity EVA intensifies as Chinese polysilicon expansion absorbs regional encapsulant capacity. Tier-one photovoltaic manufacturers exhibit lowest price sensitivity due to IRA domestic-content qualification requirements, while independent electronics assemblers face acute margin pressure from optical-grade silicone oligopoly.
Supply Chain Analysis
Extended payment terms from Shin-Etsu Chemical and Dow to qualified blenders stretch working capital cycles across the merchant formulator tier, concentrating financial leverage with upstream monomer producers. Geographic supply concentration centers on China, Japan, and the US Gulf Coast, with methyl silicone precursor production drawing from petrochemical feedstocks and chlorosilane cracking capacity. Raw material dependencies include methyl chloride, silicon metal, and platinum catalyst systems. Single-source vulnerability runs through optical-grade monomer supply. Distribution runs through direct technical sales to tier-one OEMs and specialty chemical distributors serving mid-scale electronics assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists with dual expertise in photovoltaic reliability and semiconductor packaging command premium compensation that constrains R&D team scaling, creating structural bottlenecks for suppliers attempting to accelerate REACH-compliant product launches.
For Market Incumbents: Entrench supplier relationships through pre-qualified dual REACH-RoHS material portfolios and captive methyl silicone precursor supply. Backward integration into monomer production defends margin structures against merchant feedstock volatility. Accelerate UV-curable formulation R&D to capture precision photonics assembly demand from medical device and LiDAR manufacturers. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme qualification window by building local blending operations in Gujarat or Rajasthan ahead of BIS certification requirements. Target automotive power electronics segment for silicon carbide inverter encapsulant demand. Pursue joint development agreements with tier-two photovoltaic module manufacturers seeking dual-carbon certified supply alternatives. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors adhesive-encapsulant hybrid platforms bridging bonding and barrier functions in automotive electronics. Long-term viability hinges on qualification timelines for perovskite tandem cell architectures requiring enhanced moisture-barrier performance. Watch ECHA sunset date extensions for lead stabilizer categories as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive methyl silicone production insulates margin structures from Shin-Etsu and Dow pricing power. |
| REACH-RoHS Dual Certification Investment | Pre-qualified material portfolios compress European OEM product launch cycles by 12-18 months. |
| UV-Curable Formulation Platform Launch | Elimination of thermal curing infrastructure enables mid-scale electronics assemblers to bring barrier coating in-house. |
| India PLI Scheme Local Blending Operation | Domestic formulation capacity captures first-mover qualification windows for solar module manufacturing incentives. |
| Perovskite Tandem Cell Barrier Development | Next-generation photovoltaic architectures pull specialty encapsulant demand with enhanced thermal stability specifications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with formulation R&D directors, photovoltaic procurement managers, and specialty chemical distribution executives; and secondary validation through customs trade data, ECHA authorization registers, SEC chemical segment disclosures, and MIIT dual-carbon compliance filings. Bottom-up encapsulant volume estimates triangulated against top-down solar deployment forecasts and power electronics packaging demand models.
Forecast inputs considered formulation chemistry grade, application stress profile, end-user scale tier, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level growth rate synthesis anchored in IRA production tax credit absorption timelines, PLI scheme manufacturing buildout, and perovskite commercialization roadmaps. Modeled variables included thermal curing energy cost exposure under EU and Asian carbon pricing mechanisms.
Sensitivities concentrate around ECHA sunset date extensions for lead stabilizers, MIIT enforcement intensity on dual-carbon targets, and optical-grade monomer supply disruptions. Forecasts assume documented qualification timelines and regulatory compliance pathways. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Melamine Based Adhesives Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
Melamine Formaldehyde (MF) Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
France Adhesives Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
Canada Sealants Market
Adhesives & Sealants
Polyurethane (PU) Hot-Melt Adhesive Market