
 North America Epoxy Resins Market | 2026-2036
North America Epoxy Resins Market Size, Share, and Industry Trends Forecast 2026-2036
North America Epoxy Resins Market Analytics
EPA Tier 3 VOC limits on industrial coatings is recalibrating the cost-of-entry calculus for new epoxy resin suppliers across North America. Olin Corporation leverages its integrated chlorine-caustic chain to sustain feedstock cost advantages along the Gulf Coast. Huntsman Corporation anchors its position through specialized amine hardener technology serving aerospace laminators. Covestro AG competes by extending its high-performance specialty epoxy portfolio into electronics-grade applications.
Epoxy resins are thermosetting polymers formed by reacting epichlorohydrin with bisphenol-A or bisphenol-F, yielding cross-linked networks with tensile strengths exceeding 10,000 psi and glass transition temperatures ranging from 120°C to 220°C depending on curing agent selection; these materials function primarily as high-performance matrices for fiber-reinforced composites, protective coatings, and structural adhesives requiring chemical resistance and dimensional stability. Liquid epoxy dominates volume flows into wind blade manufacturing and marine coatings, where long pot life and vacuum infusion compatibility command premium positioning. Specialty epoxy grades serving semiconductor encapsulation and aerospace prepregs capture disproportionate margin pools despite smaller tonnages. Waterborne epoxy is gaining formulation share in architectural and industrial maintenance coatings as VOC compliance tightens across US states.
The EPA regulates air emissions from coating operations under NESHAP standards, while OSHA enforces workplace exposure limits for epichlorohydrin and amine curing agents in manufacturing facilities; Health Canada and PMRA coordinate parallel chemical assessments affecting cross-border product registrations. California's South Coast Air Quality Management District imposes the strictest regional VOC limits, effectively pre-approving compliant formulations for broader North American distribution. Stakeholders must monitor evolving state-level chemical restriction proposals and position R&D spending toward bio-based epoxy precursors before regulatory thresholds harden.
Market Dynamics
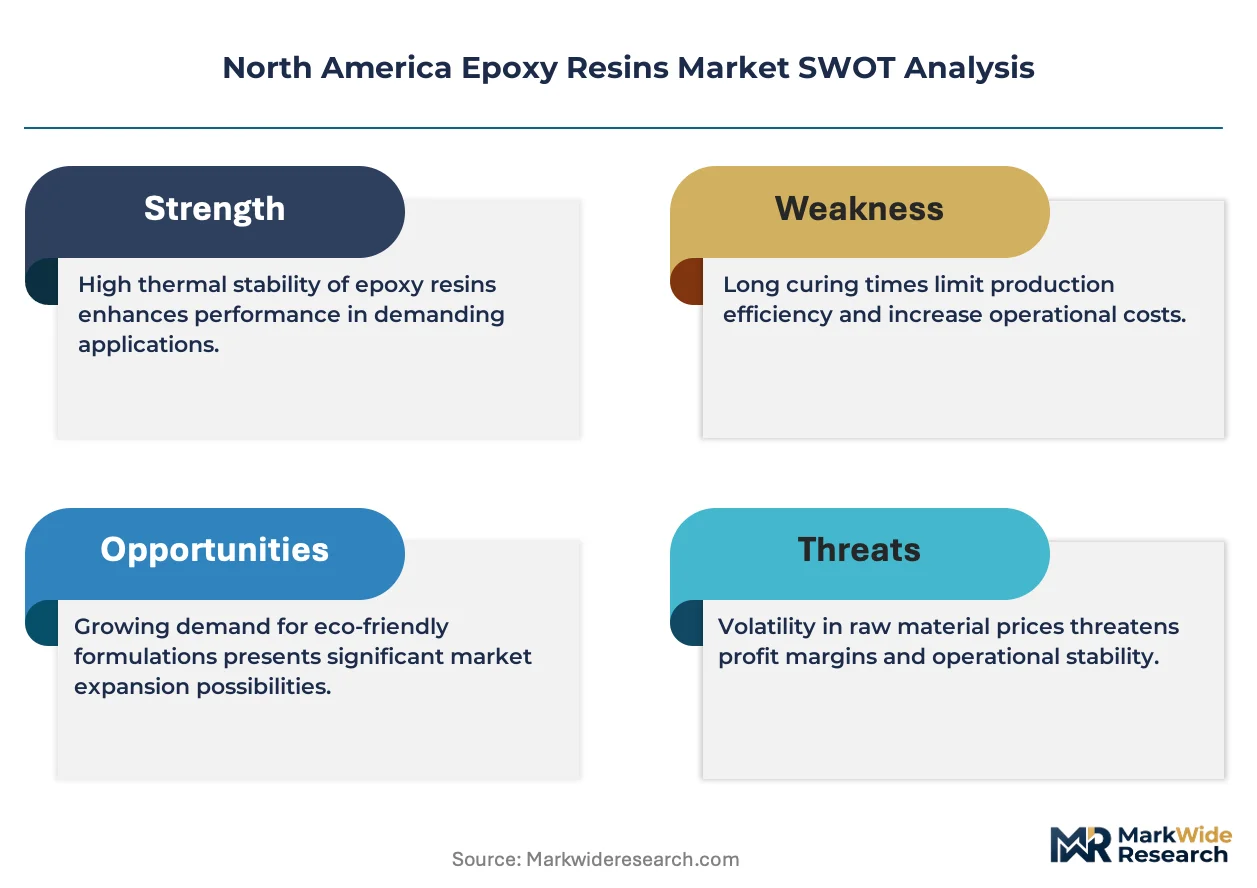
EPA Tier 3 VOC limits on industrial coatings are recalibrating formulation economics across the United States and Canada, forcing suppliers to re-engineer solvent-based systems toward waterborne alternatives or exit high-emission segments entirely.
Growth Catalysts
- Wind blade manufacturing expansion:Texas and Great Plains turbine installation programs are pulling structural composite formulations into multi-year supply contracts.
- California SCAQMD pre-approval pathway:Compliant coatings formulations cleared under South Coast Air Quality Management District rules gain automatic distribution access across US states.
- Semiconductor encapsulation demand:Electronics-grade specialty epoxies serving advanced packaging applications command premium positioning despite smaller tonnages.
Market Restraints
- Epichlorohydrin feedstock volatility:Chlorine-alkali chain input costs fluctuate with Gulf Coast petrochemical corridor capacity utilization rates.
- Amine hardener supply concentration:Specialized curing agent production clusters in Texas and Louisiana create geographic vulnerability for aerospace laminators.
- Bio-based precursor performance gap:Plant-derived epoxy alternatives currently fail to match bisphenol-A systems on glass transition temperature specifications.
Strategic Opportunities
- Canadian cross-border registration alignment:Health Canada and PMRA coordinated chemical assessments allow simultaneous US-Canada product launches.
- Marine coatings waterborne conversion:Shipyard maintenance programs in US Gulf and Pacific Northwest ports are specifying low-VOC systems for dry-dock applications.
- Digital formulation platforms:AI-accelerated curing agent selection tools compress R&D cycles for custom industrial coating specifications.
Industry Challenges
- Vacuum infusion technician scarcity:Wind blade manufacturing growth outpaces trained composite laminator availability in Texas and Oklahoma.
- Dual EPA-OSHA compliance complexity:Coating operations must simultaneously satisfy NESHAP air emission standards and workplace epichlorohydrin exposure limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Epoxy Resins Market |
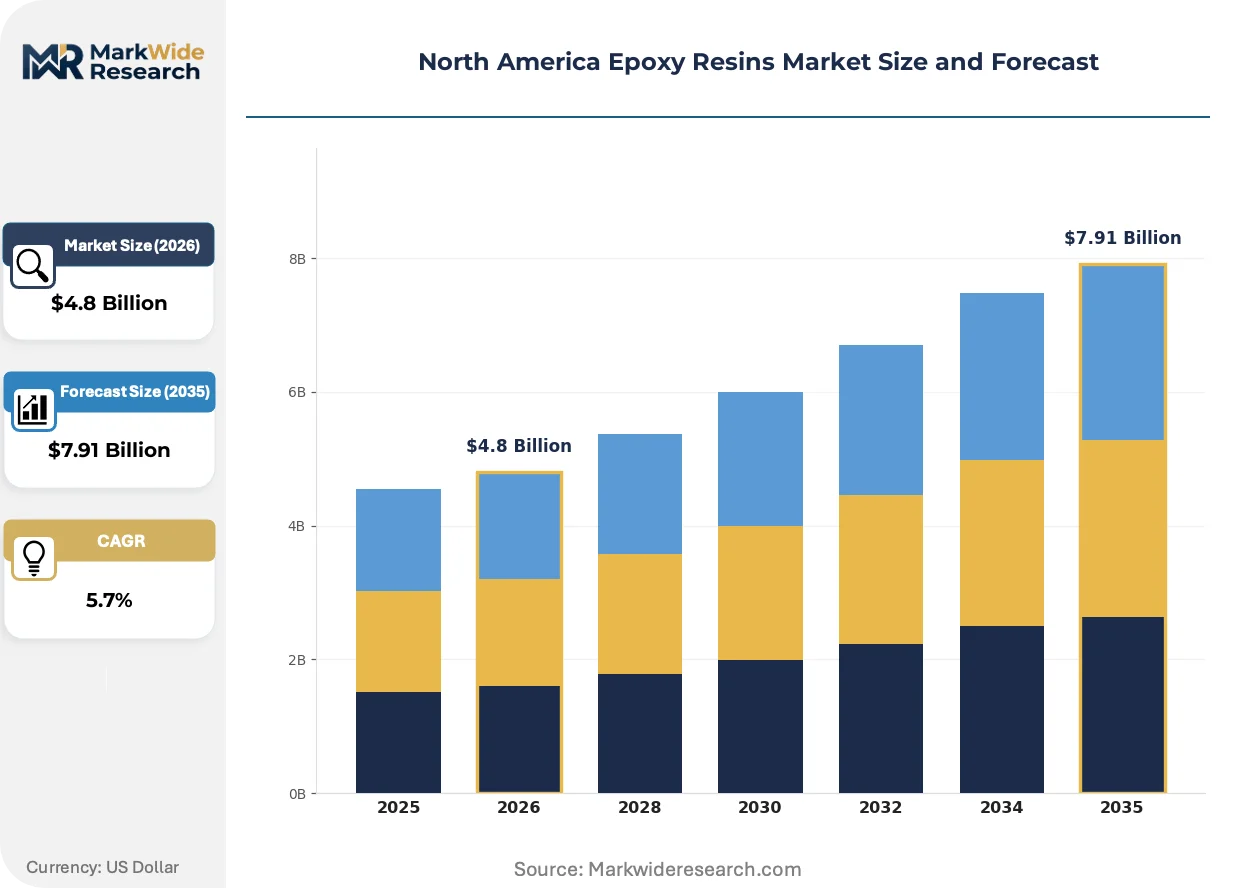
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Epoxy, Solid Epoxy, Waterborne Epoxy, Specialty Epoxy End User: Construction, Automotive, Electronics, Aerospace Application: Coatings, Adhesives, Composites, Electrical Insulation Form: Prepreg, Powder, Flexible Sheets, Gel |
| Companies Covered | BASF SE, Olin Corporation, 3M, Aditya Birla Chemicals, Hexion, DuPont de Nemours, Inc., Covestro AG, Daicel Corporation, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Epoxy Resins Market Evolving Landscape
Formulation chemistry and regulatory compliance architectures are converging to reshape competitive positioning across the North American epoxy value chain, with sustainability specifications now driving R&D allocation decisions.
Bio-based epoxy precursors derived from lignin and vegetable oil feedstocks are expanding into architectural coatings and consumer electronics housings. Formulators in California and Pacific Northwest states are adopting these systems to preempt tightening state-level chemical restriction proposals. The technology is expanding into mid-tier industrial maintenance segments previously locked into petroleum-based formulations.
EPA NESHAP standards for hazardous air pollutants from coating operations are forcing capital expenditure into emission control equipment across US manufacturing facilities. Smaller formulators in the Midwest and Northeast are consolidating or exiting rather than absorbing scrubber installation costs. California's SCAQMD Rule 1113 amendments are accelerating waterborne epoxy penetration in metal finishing and automotive refinishing applications.
Direct procurement relationships between wind turbine OEMs and epoxy formulators are displacing traditional distributor intermediaries in the Great Plains and Texas corridors. Blade manufacturers are specifying pot life, viscosity, and cure kinetics in multi-year supply agreements rather than purchasing commodity grades. This pattern concentrates most visibly in the United States Gulf Coast petrochemical corridor where integrated producers can guarantee feedstock traceability.
North America Epoxy Resins Market Segmentation
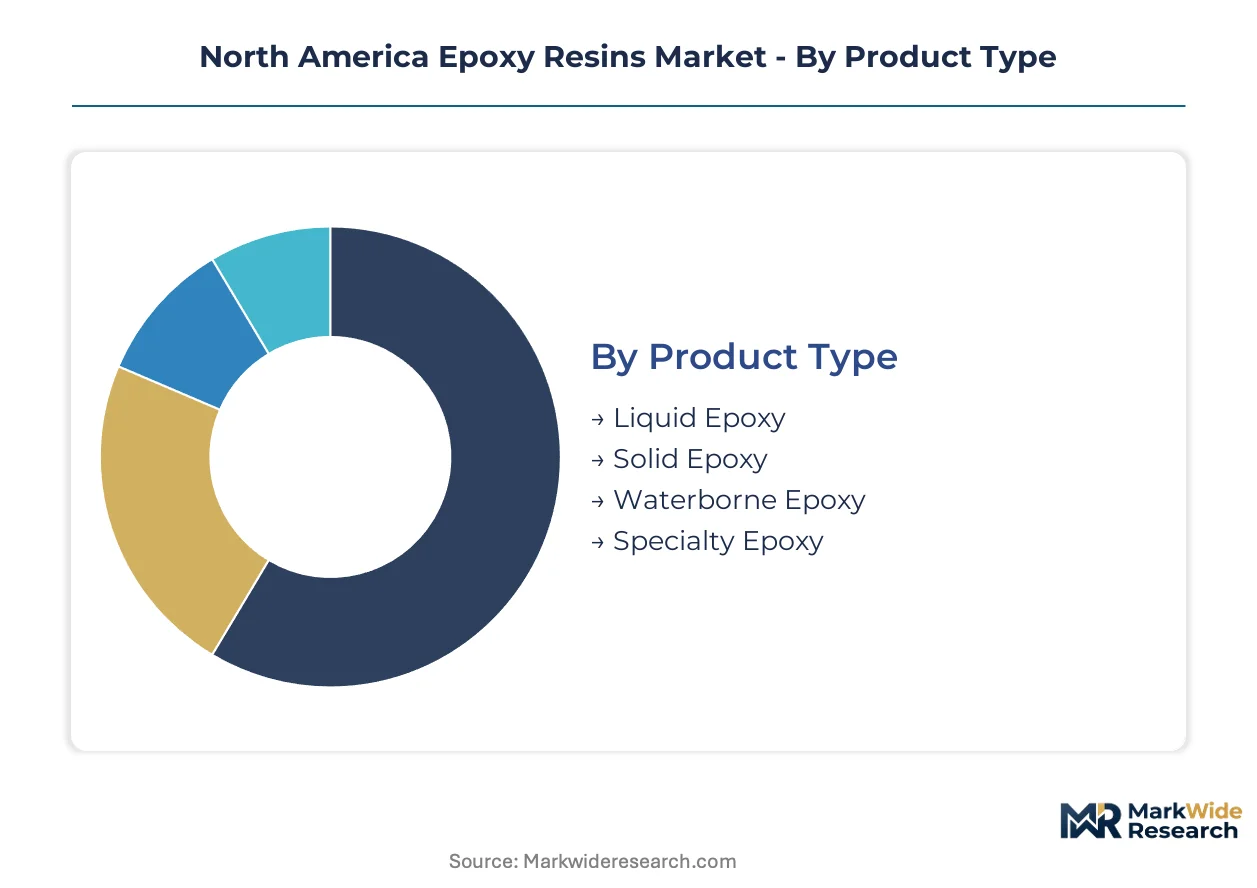
Epoxy resin formulations diverge sharply across industrial end-uses, with curing kinetics and thermal specifications dictating product selection. Manufacturers align production assets to specific segment requirements rather than pursuing horizontal coverage.
Product Type:
Replacement cycles in industrial coatings and composite manufacturing drive upgrade decisions toward higher-performance formulations with extended service intervals.
- Liquid Epoxy:Low-viscosity formulations enable vacuum infusion processes for wind blade laminates and marine hull construction. Demand clusters along the Texas Gulf Coast where turbine OEMs specify pot life and exotherm profiles in multi-year supply agreements.
- Specialty Epoxy:High-purity grades serve semiconductor encapsulation and aerospace prepregs requiring glass transition temperatures above 180°C. Electronics manufacturers in California and Arizona pay premiums for ionic contamination controls and low-alpha particle specifications.
- Solid Epoxy:Powder coatings and fusion-bonded pipe applications utilize these higher-molecular-weight grades for corrosion protection in oilfield infrastructure.
- Waterborne Epoxy:EPA Tier 3 VOC compliance pushes architectural and industrial maintenance coatings toward these low-emission systems.
Volume placements concentrate in Liquid Epoxy; the faster expansion belongs to Specialty Epoxy.
End User:
Customer procurement sophistication varies dramatically, with aerospace and electronics buyers imposing qualification protocols that lock out commodity suppliers.
- Construction:Infrastructure rehabilitation and commercial flooring absorb bulk volumes of solvent-free and waterborne systems. State transportation departments in California and New York specify epoxy overlays for bridge deck protection.
- Electronics:Advanced packaging substrates and PCB laminates demand ultra-low chloride grades with precise dielectric constants. Arizona and Texas semiconductor fabrication facilities source through qualified distributor networks with cleanroom handling capabilities.
- Automotive:Structural adhesives for electric vehicle battery enclosures and lightweight body-in-white applications drive specification changes.
- Aerospace:FAA-certified prepregs for primary structure applications require extensive qualification testing and traceable batch records.
Procurement sophistication peaks in Electronics; Construction maintains the deepest volume footprint.
Application:
Performance requirements scale with asset replacement value, pushing high-reliability segments toward premium formulation tiers.
- Composites:Fiber-reinforced matrices for wind blades, pressure vessels, and sporting goods require tailored viscosity and gel time windows. Great Plains turbine installation programs pull structural formulations into dedicated supply corridors.
- Coatings:Protective and marine applications dominate tonnage, with EPA NESHAP standards forcing capital investment into emission control equipment at Midwest and Northeast manufacturing facilities.
- Adhesives:Structural bonding in transportation and civil engineering applications demands lap shear strengths exceeding 3,000 psi.
- Electrical Insulation:Transformer and motor encapsulation grades must pass IEEE thermal aging protocols.
Coatings capture the widest volume base; Composites show the steepest expansion trajectory.
Form:
Processing method constraints determine form selection, with automation compatibility and shelf stability driving manufacturing investment.
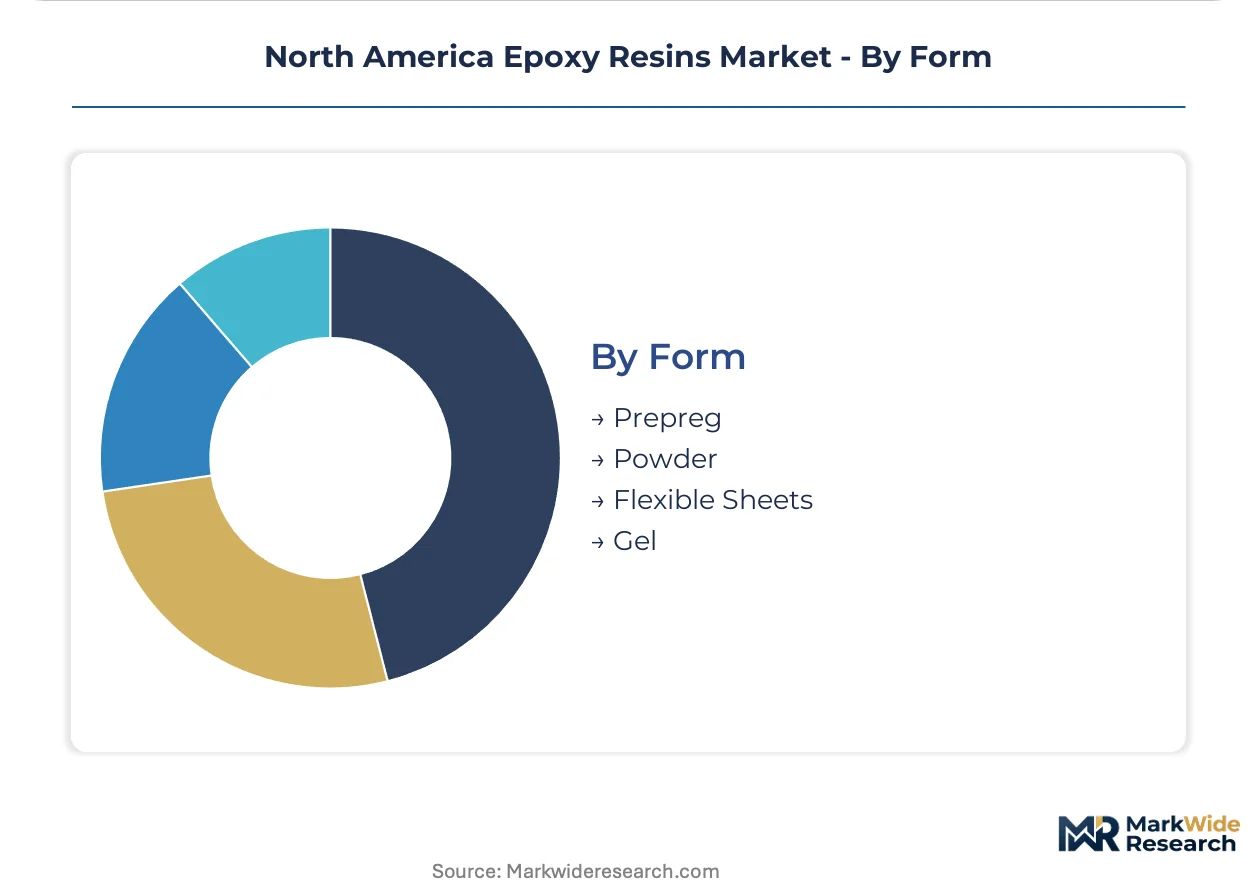
- Prepreg:B-staged resin films on carbon or glass fiber carriers enable automated layup for aerospace primary structures. Boeing and Lockheed Martin suppliers in Washington and California maintain frozen storage distribution networks.
- Powder:Electrostatic spray applications in pipeline and rebar coating favor these solvent-free systems for environmental compliance.
- Flexible Sheets:Flooring and waterproofing membranes utilize these roll-good formats for rapid installation.
- Gel:Thixotropic formulations for vertical surface coating and crack injection applications.
Prepreg commands the highest value per kilogram; Powder scales most broadly across industrial users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Gulf Coast petrochemical corridor anchors North American epoxy resin production through integrated feedstock access and specialized manufacturing infrastructure clustered around Houston and Baton Rouge.
United States
Texas wind blade manufacturing and California semiconductor packaging pull divergent epoxy grades into dedicated supply corridors. EPA Tier 3 VOC limits force waterborne formulation conversions across industrial coatings segments. Houston and Beaumont host integrated producers supplying vacuum infusion systems to Great Plains turbine OEMs.
Canada
Cross-border chemical registration alignment with US regulators enables simultaneous product launches into construction and electronics segments. Health Canada and PMRA coordinated assessments reduce time-to-market for compliant formulations. Ontario and Quebec manufacturing facilities serve aerospace laminators through frozen-prepreg distribution networks.
Mexico
Automotive assembly expansion in Nuevo León and Bajío drives structural adhesive demand for electric vehicle battery enclosures. Mexican environmental regulations gradually tighten VOC limits in industrial coatings applications. Monterrey and Guanajuato industrial corridors attract formulators serving tier-one automotive suppliers.
North America Epoxy Resins Market Competitive Landscape
Gulf Coast integrated producers anchor one tier; specialized amine hardener and electronics-grade specialists hold differentiated positions. Market structure concentrates around feedstock-advantaged chlor-alkali operators and formulation technology licensors. Three archetypes dominate: integrated petrochemical producers, specialty hardener technology holders, and electronics-purity refiners. Capacity expansion and strategic partnerships represent the primary competitive moves reshaping supply relationships.
Among Germany-based chemical conglomerates, BASF SE and Covestro AG occupy positions spanning commodity and specialty epoxy tiers. Olin Corporation exemplifies the integrated producer archetype through its Gulf Coast chlorine-caustic chain. Huntsman Corporation represents the specialized hardener technology segment serving qualified aerospace and electronics laminators.
| Leading Market Players |
|---|
| BASF SE |
| Olin Corporation |
| 3M |
| Aditya Birla Chemicals |
| Hexion |
| DuPont de Nemours, Inc. |
| Covestro AG |
| Daicel Corporation |
| Huntsman Corporation |
| Others |
Value Network & Pricing Analysis
Captive integration into Gulf Coast chlorine-alkali operations anchors pricing power for epoxy resin producers serving wind blade and electronics laminators. Olin Corporation's backward control over epichlorohydrin feedstock insulates margin structures from commodity volatility that squeezes non-integrated formulators.
Pricing Analysis
Short lead-time premiums command substantial markups from Texas turbine OEMs facing compressed blade delivery schedules, while spot inventory of standard liquid grades trades at discounts. Contract-based long-term offtake dominates volume flows, with price differentiation resting on certification tier and volume scale. Pricing pressure stems from EPA compliance costs forcing waterborne conversion investments. Construction buyers exhibit highest price sensitivity; aerospace laminators show least.
Supply Chain Analysis
FAA and semiconductor-grade qualification gates lock out commodity suppliers from aerospace prepreg and electronics encapsulation segments. Production concentrates in the United States, Canada, and Mexico, with raw material dependencies on chlorine-alkali outputs, bisphenol-A, and specialty amine curing agents. Single-source vulnerability clusters around Texas and Louisiana hardener production. Distribution runs through qualified distributor networks with frozen-prepreg cold chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America epoxy resins market sits in a formulation technology transition, with waterborne systems displacing solvent-based coatings under EPA Tier 3 pressure.
For Market Incumbents: Anchor Gulf Coast feedstock advantages through capacity debottlenecking in Houston and Beaumont corridors. Defend against bio-based epoxy substitutes by accelerating R&D in lignin-derived precursors that close glass transition temperature gaps. Prioritize certification investment for semiconductor-grade ionic contamination controls. For New Entrants and Emerging Players: Capture marine coatings waterborne conversion opportunities at Pacific Northwest and Gulf port dry-dock programs. The most penetrable white-space sits in AI-accelerated curing agent selection platforms for custom industrial specifications. Pursue direct procurement relationships with mid-tier wind blade manufacturers bypassing traditional distributor layers. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty hardener technology holders serving qualified aerospace laminators. Long-term viability favors electronics-purity refiners with cleanroom distribution infrastructure. Watch for inflection in California SCAQMD rule amendments accelerating metal finishing waterborne adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Feedstock | Olin Corporation's captive epichlorohydrin supply locks in cost position against volatile Gulf Coast petrochemical corridor utilization swings. |
| Waterborne Formulation Platform Launch | EPA Tier 3 compliance investments open California SCAQMD pre-approval pathways for broader North American architectural coatings distribution. |
| Long-term Supply Agreement with Wind OEMs | Texas and Great Plains turbine manufacturers specify pot life and viscosity in multi-year contracts displacing commodity grade purchases. |
| Electronics-Grade Purity Refinement | Arizona and Texas semiconductor fabs pay premiums for low-alpha particle ionic contamination controls in advanced packaging substrates. |
| Joint Venture in Bio-Based Precursor Development | Lignin-derived epoxy partnerships with Pacific Northwest formulators preempt tightening state-level chemical restriction proposals. |
Research Methodology
Document review covered EPA NESHAP filings, ACC industry reports, and SEC 10-K disclosures, complemented by interviews with plant managers at Gulf Coast integrated producers, procurement leads at Texas wind blade OEMs, distribution channel partners, and technical R&D directors at specialty hardener suppliers. Bottom-up volume triangulation against top-down value estimates validated segment splits across product type, end user, application, and form dimensions.
Volume and value trajectories across the projection horizon reflect modeled interactions between wind installation programs, EPA regulatory phase-ins, and semiconductor capital expenditure cycles. Segmentation dimensions included grade tier, end-use industry, curing kinetics specification, and regional production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating feedstock cost pass-through assumptions and qualification timeline lags for aerospace and electronics grades.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bio-based precursor performance breakthroughs and California SCAQMD rule expansion timing. A model refresh is warranted upon material change in EPA Tier 3 enforcement intensity or Gulf Coast chlorine-alkali capacity utilization shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Closed Cell Polyurethane Foam Market
Polymers & Resins
Cathodic Acrylic Market
Polymers & Resins
Conductive Polymers Market
Polymers & Resins
Nylon 66 Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
Polystyrene Market
Polymers & Resins
Gel Polymer Electrolytes Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
UV Stabilized Thermoplastic Elastomer for Automotive Market
Polymers & Resins
Global Polymeric Adsorbents Market