
 Polyhydroxy Butyrate Market | 2026-2036
Polyhydroxy Butyrate Market Size, Share, and Industry Trends Forecast 2026-2036
Polyhydroxy Butyrate Market Intelligence
The division between large-scale fermentation capacity and niche application development is collapsing as the material gains commercial traction. Kaneka leverages its significant biopolymer production scale to serve high-volume packaging and consumer goods markets. In contrast, TianAn Biologic Materials specializes in specific PHB grades for food service ware and agricultural films in Asia. Global chemical firm BASF competes through its broad portfolio of certified compostable polymers and extensive global distribution network.
Polyhydroxy butyrate (PHB) is a biopolymer, specifically a polyester, produced through bacterial fermentation of renewable feedstocks like sugar or lipids. It possesses thermoplastic properties comparable to polypropylene and is fully biodegradable in soil, freshwater, and marine environments. The packaging application segment, particularly for food containers and disposable cutlery, constitutes the largest share of volume. Medical implants and drug delivery systems represent a high-value niche, where PHB's biocompatibility and controlled bioresorption are critical performance attributes.
Regulatory frameworks such as the EU's directives on single-use plastics and packaging waste directly stimulate market substitution for fossil-based materials. In the United States, FDA clearance for food-contact applications and adherence to ASTM standards for biodegradability define market access. The key decision for stakeholders is whether to focus on high-volume, lower-margin commodity applications or specialized, high-performance medical and technical uses.
Market Dynamics
The central structural force is a global regulatory clampdown on single-use plastics, exemplified by the EU Green Deal and China's dual carbon goals. This creates a mandatory substitution market, pulling PHB from niche applications into mainstream commercial consideration.
Growth Catalysts
- Regulatory Mandates:The European Union's Single-Use Plastics Directive directly compels member states to reduce consumption of certain fossil-based products, creating a protected market space for biodegradable alternatives like PHB in food service and retail packaging.
- End-Use Demand:The food service industry is actively seeking packaging materials that comply with ASTM standards for biodegradability to meet corporate sustainability goals and consumer expectations for environmentally responsible disposable cutlery and containers.
- National Industrial Policy:China's strategic policy framework, including its dual carbon goals, provides significant state-level support for scaling up domestic PHB production capacity and promoting its use in agricultural films and consumer goods.
Market Restraints
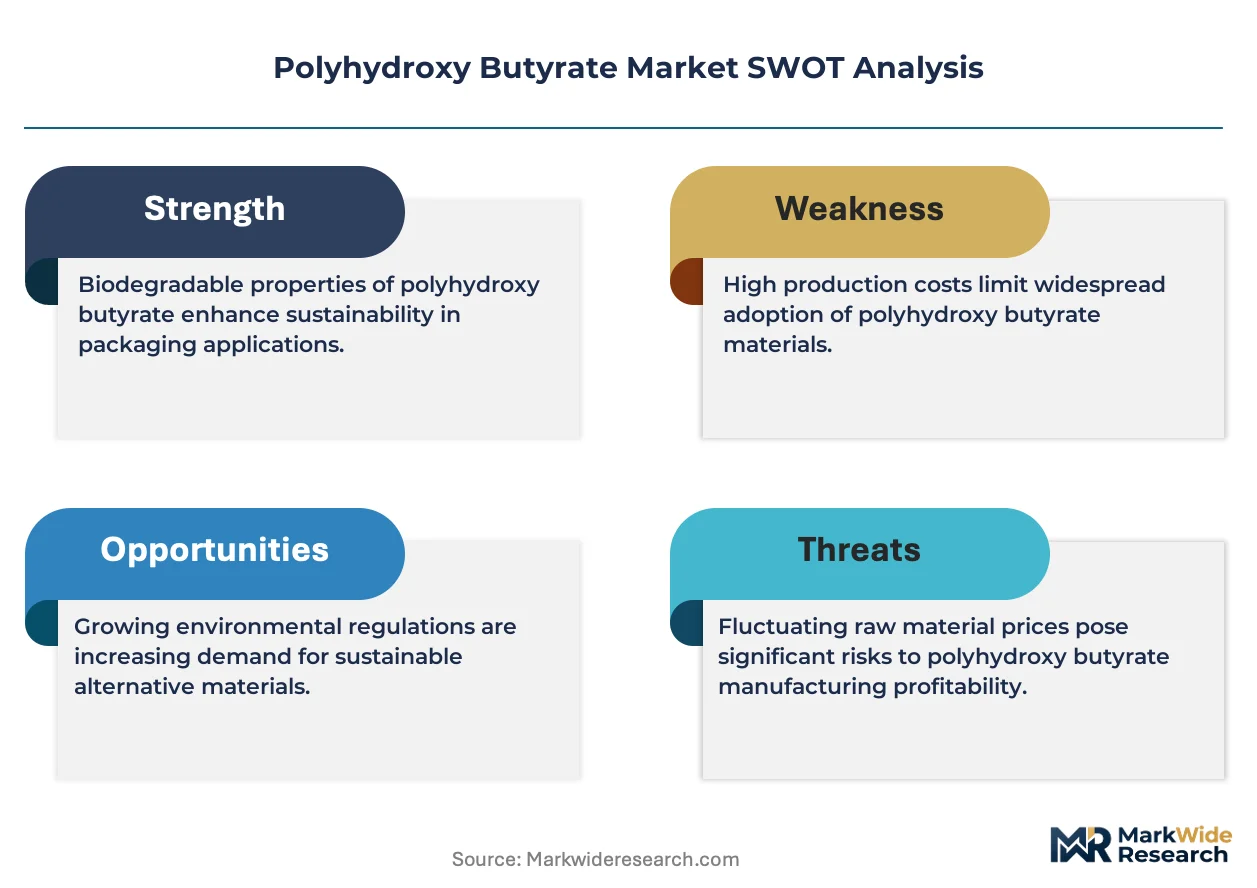
- Cost Disparity:PHB production costs remain significantly higher than those for conventional thermoplastics like polypropylene, primarily due to the expense of renewable feedstocks and the energy intensity of the bacterial fermentation and purification processes.
- Supply Chain Concentration:A substantial portion of new and planned large-scale fermentation capacity is concentrating in China, exposing global supply chains to potential geopolitical risks, trade friction, and logistical vulnerabilities for buyers in Europe and North America.
- Technical Processing Limits:PHB exhibits a narrower thermal processing window and lower melt strength compared to incumbent polymers, often requiring specialized equipment or modifications to existing manufacturing lines, which presents an adoption barrier for converters.
Strategic Opportunities
- Medical Device Innovation:High-purity PHB grades offer significant potential in high-value medical applications, including biocompatible surgical sutures, controlled-release drug delivery systems, and bioresorbable orthopedic implants, leveraging the material's unique biological properties.
- Geographic Expansion:Underpenetrated markets in South America, particularly Brazil and Colombia, represent a key growth opportunity as national and municipal regulations targeting plastic pollution create new demand for compostable and biodegradable materials.
- Copolymer Development:Formulating PHB with other comonomers to produce copolymers like PHBV (polyhydroxybutyrate-co-valerate) enhances flexibility and impact resistance, opening up new applications in flexible films, coatings, and non-woven fabrics.
Industry Challenges
- Standardization Gaps:A lack of globally harmonized testing protocols and certification labels for biodegradability across different environments (soil, marine, industrial compost) creates market confusion, complicates compliance, and enables greenwashing claims.
- Capital Intensity:The construction of new world-scale PHB production plants requires substantial capital investment in bioreactors, downstream processing equipment, and sterile handling systems, posing a significant financial hurdle for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyhydroxy Butyrate Market |
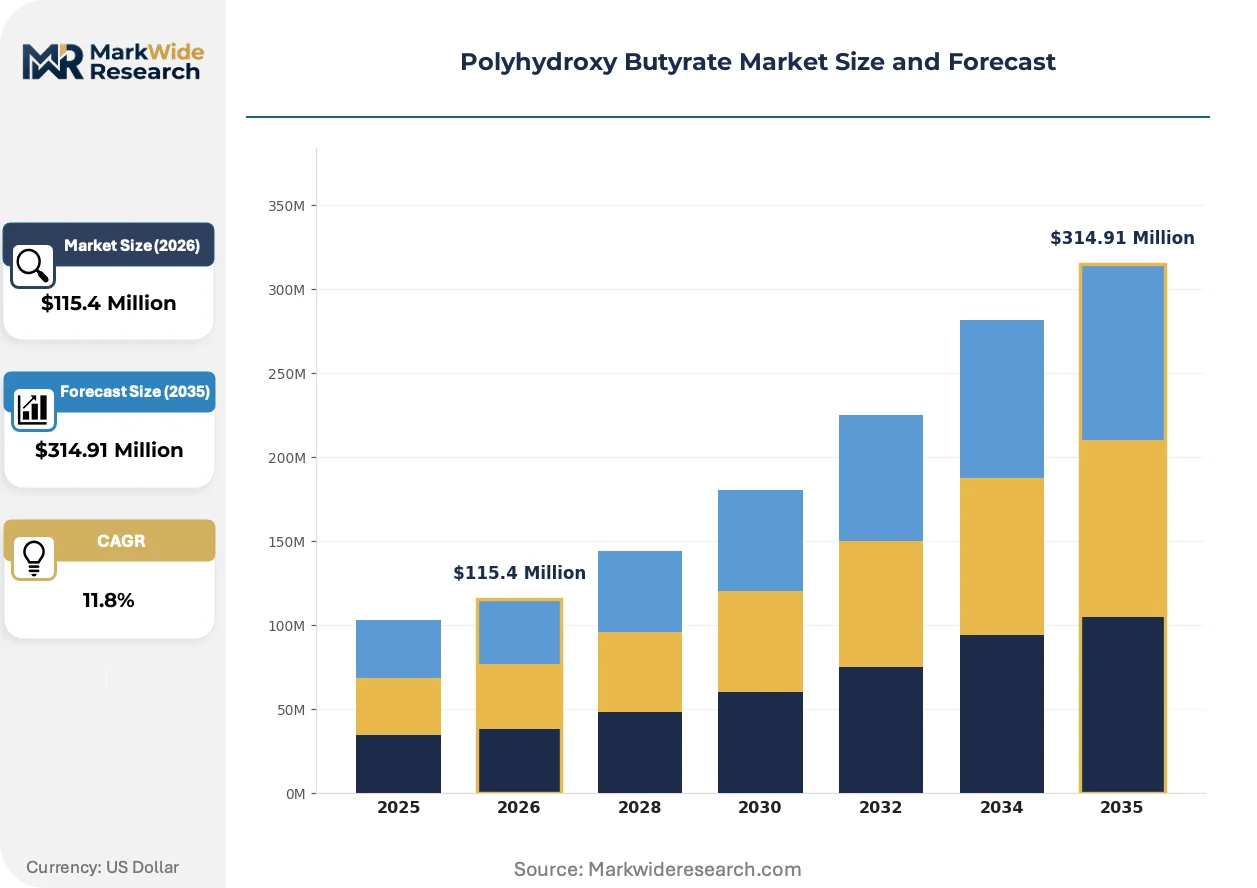
| Market Size in 2026 | $115.4 Million |
| Market Size in 2035 | $314.91 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyhydroxybutyrate, Polyhydroxyvalerate, Copolymers, Bio-based Polymers Form: Granules, Powder, Film, Sheets Application: Packaging, Agricultural Films, Medical Implants, Consumer Goods End User Industry: Packaging Manufacturers, Agricultural Suppliers, Medical Device Producers, Household Product Companies |
| Companies Covered | TianAn Biologic Materials, Tepha, BASF, Biome Technologies, Telles, Biomer, Wacker Chemie, Kaneka, PHB Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyhydroxy Butyrate Market Strategic Shifts & Innovations
A convergence of policy mandates and material science advancements is transitioning polyhydroxy butyrate from a specialty biopolymer to a viable mainstream alternative. This shift is most visible in applications where end-of-life biodegradability is a critical performance requirement.
Advanced polyhydroxy butyrate formulations offer a direct, biodegradable alternative to conventional plastics. The food packaging and disposable consumer goods sectors are accelerating adoption for single-use items. This material is decomposing the market position of non-biodegradable incumbents like polypropylene in applications where end-of-life environmental impact is a primary concern.
The EU's Packaging and Packaging Waste Regulation (PPWR) establishes stringent targets for recyclability and compostability. This policy forces a systemic shift away from materials that lack a clear circular pathway. The food-contact packaging segment is most affected, redesigning containers and films to meet new European Union mandates for compostable solutions.
Certification-driven sourcing is replacing simple price-based procurement for bioplastics. Consumer packaged goods companies now mandate suppliers provide PHB grades with specific credentials, such as BPI certification or TÜV Austria's OK compost labels. This shift is most prominent in North American and Western European consumer markets.
Polyhydroxy Butyrate Market Segmentation
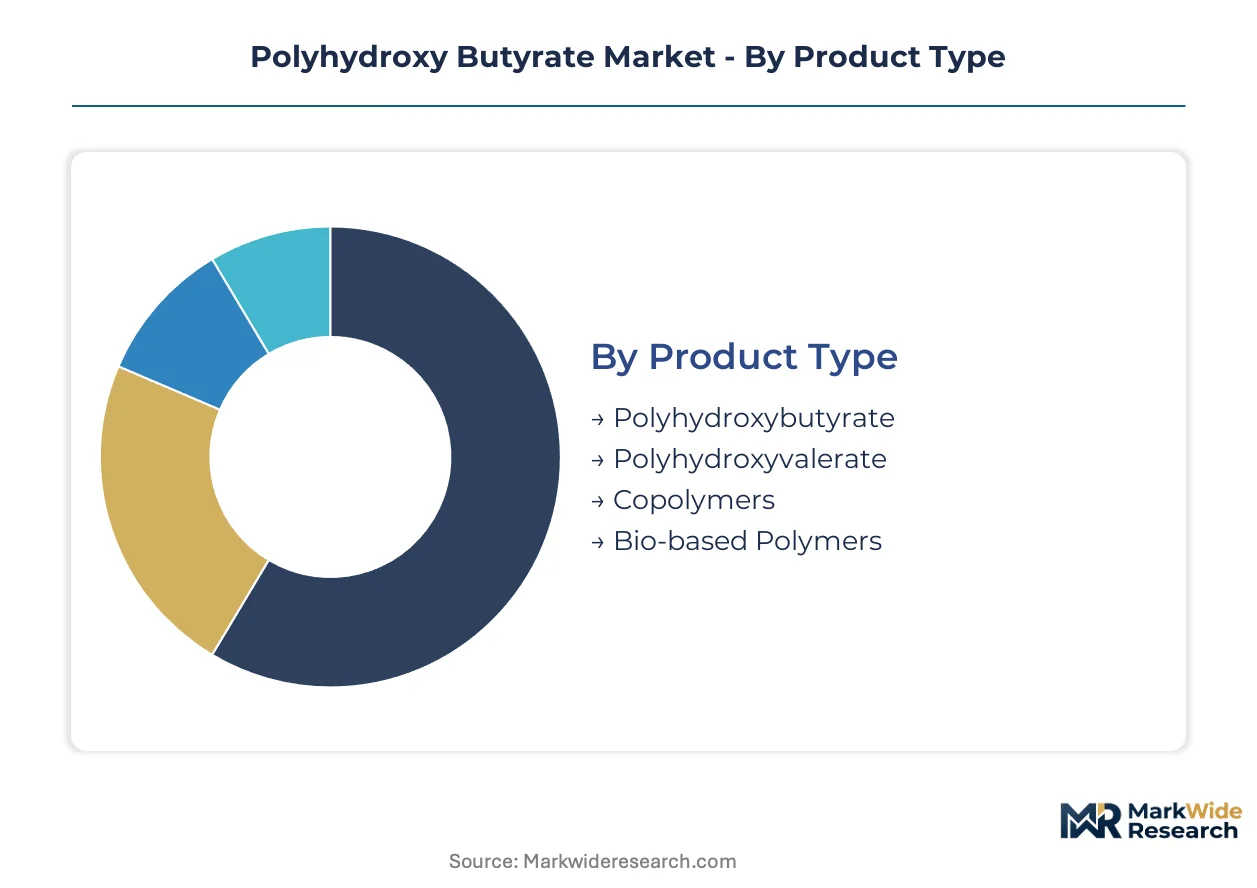
The Polyhydroxy Butyrate Market is segmented to provide a granular view of demand drivers and material specifications across different product forms, applications, and end-user industries. This segmentation highlights the distinct commercial pathways for PHB, from high-volume commodity substitutes to specialized, high-value performance materials.
Product Type:
Regulatory mandates like the EU Green Deal are driving the demand for specific PHB product types, necessitating clear differentiation based on biodegradability profiles and performance characteristics.
- Polyhydroxybutyrate:This homopolymer is the foundational PHB material, derived from bacterial fermentation of renewable feedstocks. Its thermoplastic properties are comparable to polypropylene, making it suitable for direct substitution in applications where full biodegradability in diverse environments is required by regulations such as the EU Single-Use Plastics Directive.
- Polyhydroxyvalerate:This homopolymer is less common on its own but is a key component in PHBV copolymers, contributing to improved material ductility.
- Copolymers:These materials combine PHB with other hydroxyalkanoates like valerate (PHBV) to improve flexibility, impact strength, and processability. This modification extends their utility into applications requiring enhanced mechanical properties, often driven by specific performance standards for compostability and durability in packaging.
- Bio-based Polymers:This broad category includes PHB and other polymers derived from biomass, emphasizing their renewable origin rather than just biodegradability.
Established volume favors Polyhydroxybutyrate; emerging adoption favors Copolymers.
Form:
The physical form of PHB dictates its processing methods and suitability for various manufacturing operations, directly impacting its adoption across diverse end-use sectors.
- Granules:This is the most common commercial form, allowing for standard thermoplastic processing techniques such as injection molding, extrusion, and blow molding. Manufacturers use granules to produce a wide array of products, from disposable cutlery to packaging containers, aligning with the growing demand for compostable alternatives in consumer goods.
- Powder:PHB in powder form finds specialized applications in coatings, 3D printing, and as an additive to other polymer matrices for property modification.
- Film:PHB films offer a biodegradable solution for flexible packaging, agricultural mulching, and protective layers, leveraging the material's barrier properties. Regulatory pressures, particularly in Europe, for compostable food-contact films drive significant innovation and adoption in this segment.
- Sheets:These are used for thermoforming applications, producing trays, containers, and other rigid packaging items.
Demand for Granules remains strong, while Film exhibits expanding use.
Application:
The diverse applications of PHB reflect a spectrum of performance requirements and value propositions, ranging from high-volume, cost-sensitive markets to specialized, high-performance niches.
- Packaging:This segment constitutes the largest volume share, driven by a global shift towards biodegradable alternatives for food containers, disposable cutlery, and flexible wraps. Regulatory frameworks, such as the EU's Packaging and Packaging Waste Regulation, directly accelerate the substitution of conventional plastics in this sector.
- Agricultural Films:These films, used for mulching and crop protection, benefit from PHB's biodegradability, reducing plastic waste accumulation in soil.
- Medical Implants:PHB's excellent biocompatibility and bioresorbability make it ideal for high-value medical applications, including surgical sutures, controlled-release drug delivery systems, and bone tissue engineering scaffolds. FDA clearance for specific medical devices highlights the material's critical performance attributes in this specialized field.
- Consumer Goods:This category includes disposable household items, toys, and personal care packaging, where demand for eco-friendly materials is increasing.
High-volume applications are dominated by Packaging, whereas Medical Implants represents a high-value niche.
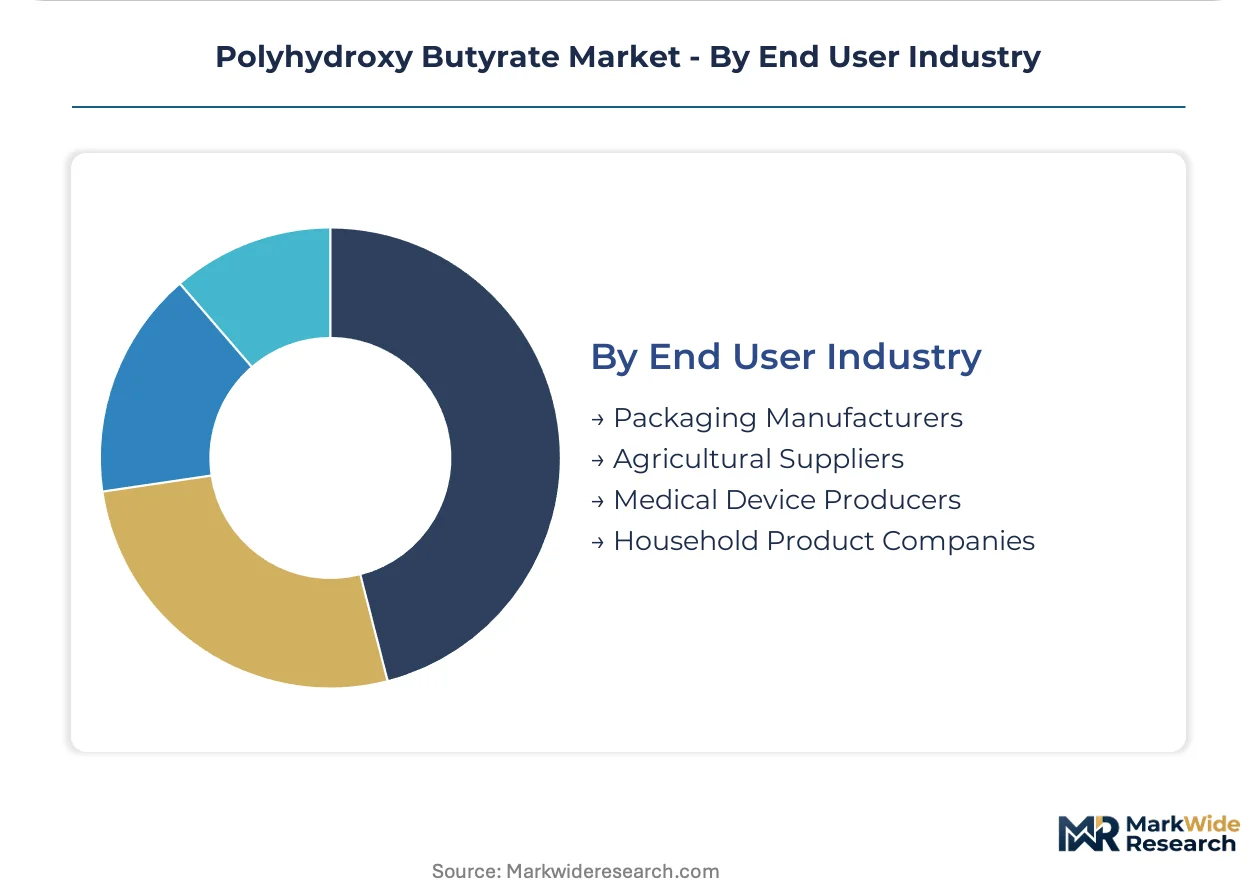
End User Industry:
The end-user industries for PHB are characterized by varying supply chain dynamics and procurement strategies, influencing material specifications and adoption rates.
- Packaging Manufacturers:These companies represent the primary demand source for PHB, integrating the biopolymer into their production lines for bottles, films, and containers. Their procurement decisions are heavily influenced by client mandates for certified compostable materials and compliance with regional packaging waste regulations.
- Agricultural Suppliers:These entities procure PHB for manufacturing biodegradable mulching films and other farming aids, driven by environmental regulations and sustainable farming practices.
- Medical Device Producers:This industry demands high-purity, biocompatible PHB grades for precision manufacturing of implants and drug delivery systems. Their sourcing is driven by stringent regulatory approvals, such as those from the FDA or EMA, and the need for materials with predictable bioresorption profiles.
- Household Product Companies:Manufacturers of consumer goods utilize PHB for eco-friendly packaging and disposable product components, responding to consumer demand for sustainable options.
The largest procurement volumes originate from Packaging Manufacturers, with Medical Device Producers showing significant growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power for polyhydroxy butyrate exhibits asymmetry, with production concentration in China influencing global supply dynamics. Demand centers in Europe and North America drive premium pricing for certified biodegradable solutions. This creates a divergence in market value capture across continents.
China
China's industrial policy strongly supports polyhydroxy butyrate production for agricultural films and consumer goods. The nation's dual carbon goals provide significant state-level backing for domestic capacity expansion. Large-scale manufacturing facilities in the Yangtze River Delta are rapidly increasing PHB output.
Germany
German demand for PHB stems from stringent packaging regulations and a strong consumer preference for sustainable materials. The EU Green Deal and PPWR compel manufacturers to seek compostable alternatives. Chemical firms in Bavaria are actively developing new PHB formulations and processing techniques.
United States
United States demand for PHB is driven by the food service industry's need for biodegradable packaging and disposable items. FDA clearance for food-contact applications and ASTM standards define market access. Biotech innovation hubs in California are exploring high-purity PHB grades for specialized uses.
Brazil
Brazil presents a significant growth opportunity for PHB, particularly in packaging and compostable materials. National and municipal regulations targeting plastic pollution are creating new demand. Manufacturers in the São Paulo industrial region are exploring PHB integration into consumer product lines.
Japan
Japanese consumers and industries seek PHB for eco-friendly consumer goods and flexible packaging solutions. METI initiatives support the development and adoption of bio-based plastics. Major manufacturers in the Kanto region are investing in PHB production and advanced material science research.
Polyhydroxy Butyrate Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the polyhydroxy butyrate market. The market exhibits a tiered structure, with established chemical giants alongside specialized biopolymer producers and emerging biotech firms. Three strategic archetypes emerge: large-scale commodity producers, high-purity niche specialists, and integrated solution providers. Companies are pursuing capacity expansion and strategic partnerships to secure feedstock and optimize downstream processing.
Within the high-volume commodity segment, Kaneka exemplifies a biopolymer producer leveraging significant production scale for packaging and consumer goods. Global chemical firm BASF occupies a position as an integrated solution provider, offering a broad portfolio of certified compostable polymers. TianAn Biologic Materials represents a specialized biopolymer producer, focusing on specific PHB grades for food service ware and agricultural films in Asia. These companies anchor distinct market strategies based on scale, portfolio breadth, and regional specialization.
| Leading Market Players |
|---|
| TianAn Biologic Materials |
| Tepha |
| BASF |
| Biome Technologies |
| Telles |
| Biomer |
| Wacker Chemie |
| Kaneka |
| PHB Industrial |
| Others |
Cost & Logistics Intelligence
The EU's Packaging and Packaging Waste Regulation directly gates supply qualification for PHB materials and influences price differentiation across European markets. This regulatory framework compels manufacturers to seek certified compostable alternatives, thereby defining acceptable supply and premium pricing for compliant solutions.
Pricing Analysis
Configured-to-order PHB grades for medical applications command premium pricing, contrasting with the contract-based long-term offtake model prevalent for commodity volumes. Price differentiation stems from rigorous certification levels, such as BPI or TÜV Austria's OK compost labels, and the degree of material customization. Pricing pressure originates from the significant cost disparity compared to conventional fossil-based polymers, primarily due to expensive renewable feedstocks. High-volume packaging manufacturers exhibit greater price sensitivity, while medical device producers prioritize performance over cost for specialized PHB grades.
Supply Chain Analysis
Inbound logistics costs are influenced by container availability and port congestion along major trade lanes connecting Asia to Europe and North America. Supply concentration centers heavily in China, which provides large-scale production capacity, alongside emerging facilities in Germany and Japan. The supply chain relies on renewable feedstocks like sugar and lipids, which are subject to agricultural commodity price volatility. Geopolitical risks and potential trade friction with China represent a significant structural supply chain vulnerability for global buyers. Distribution runs through direct sales channels to large industrial buyers and specialized distributors for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyhydroxy butyrate market is experiencing a buyer-power-shift, driven by consolidating consumer packaged goods companies demanding certified, sustainable materials from their suppliers.
For Market Incumbents: Consolidate existing production capacity through strategic alliances to mitigate feedstock price volatility and improve economies of scale. Invest in advanced bioprocessing R&D to reduce production costs and diversify feedstock sources, addressing the persistent cost disparity threat. Expand capacity in strategic regions like China to leverage government support and manufacturing scale, securing a dominant position in high-volume segments.
For New Entrants and Emerging Players: Lead with high-purity PHB grades targeting specialized, high-value applications like medical implants and controlled-release drug delivery systems. The underpenetrated markets in South America, particularly Brazil, offer a significant white-space opportunity due to evolving plastic pollution regulations. A focused go-to-market angle emphasizing biocompatibility and specific regulatory clearances, such as FDA approval, can differentiate offerings.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the biopolymer production segment, driven by the need for world-scale fermentation plants. Target specialized biopolymer producers with proprietary fermentation technologies or unique feedstock conversion capabilities for acquisition. The successful scale-up and commercialization of new production facilities, particularly those achieving cost parity with conventional plastics, serve as a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Large-scale manufacturers like Kaneka can achieve superior cost efficiencies and meet high-volume packaging demand. |
| Copolymer Development | BASF can enhance material properties, extending PHB's utility into flexible films and non-woven fabrics. |
| Bioprocessing R&D Investment | TianAn Biologic Materials can reduce production costs, making PHB more competitive against fossil-based polymers. |
| Medical Device Certification | Tepha can unlock high-value applications, leveraging PHB's biocompatibility for regulated healthcare markets. |
| Geographic Market Entry | PHB Industrial can capture demand in underpenetrated regions like Brazil, driven by local plastic regulations. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews to gather qualitative insights and validate quantitative data. Engaged stakeholders included R&D directors at material science firms, procurement leads at packaging manufacturers, brand managers at consumer goods companies, and regulatory affairs specialists. Secondary data sources, such as customs data, regulatory filings with the FDA and EMA, and bioplastics industry association reports, provided comprehensive market intelligence. This approach ensured robust bottom-up and top-down triangulation of market estimates.
The forecasting window spans across the analysis horizon, employing a robust analytical framework that models market dynamics. Segmentation dimensions include product type, application, end-user industry, and regional production hubs, such as East Asia. Compound annual growth rates were derived by integrating historical market performance with projected adoption rates and technological advancements. Key industry-specific forecast inputs include feedstock price trends and regulatory compliance rates.
Forecasts assume regulatory continuity in the EU Green Deal and China's dual carbon goals; material policy shifts would require re-modeling. The analysis reflects current market structures and anticipated technological trajectories. Outcomes outside this envelope, such as unforeseen geopolitical disruptions or rapid breakthroughs in competing materials, would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Bio-PET Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Global Bioplastic Market
Bioplastics
Biodegradable Microbeads Market
Bioplastics
Bioplastic Textile Market
Bioplastics
Bioplastics and Biopolymers Market
Bioplastics
US Bioplastics Market
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
Cellulose Bioplastic Market
Bioplastics
Global Bioplastic Composites Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Canada Bioplastics Market
Bioplastics
Asia-Pacific Polylactic Acid (PLA) Market