
 Extruded Polystyrene Market | 2026-2036
Extruded Polystyrene Market Size, Share, and Industry Trends Forecast 2026-2036
Extruded Polystyrene Market Analysis
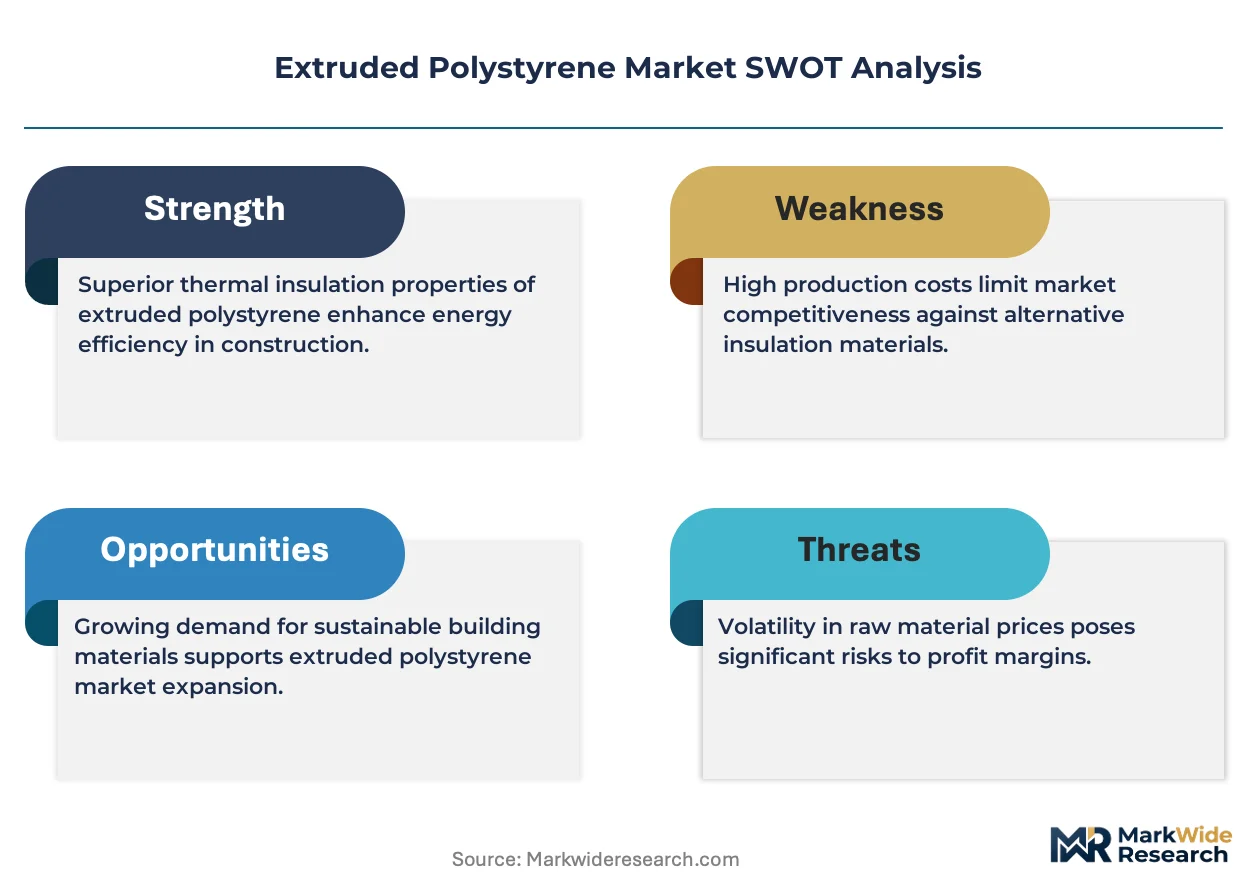
Asset-light leasing models for extrusion equipment is fragmenting competitive entry barriers across the insulation supply chain. BASF leverages captive styrene supply chains to sustain margin control in high-performance grades. Owens Corning anchors North American distribution through contractor-direct channels. Saint-Gobain differentiates via building-envelope system integration rather than commodity board sales.
Extruded polystyrene is a closed-cell thermoplastic foam produced through continuous extrusion of polystyrene resin with blowing agents, yielding rigid boards with compressive strength typically exceeding 300 kPa and thermal conductivity near 0.035 W/m·K for building thermal insulation. The regular product type dominates volume in emerging construction markets where cost sensitivity overrides performance premiums, while laminated configurations command margin pools in commercial roofing where multi-layer moisture barriers justify specification upgrades. High-performance grades are gaining specification share in passive-house and near-zero-energy building envelopes across Northern Europe.
REACH restrictions on HBCD flame retardants and the EU F-Gas Regulation's phase-down of HFC blowing agents are reformulating product chemistry and reshaping certification requirements for European manufacturers. The US EPA Significant New Alternatives Policy program evaluates next-generation blowing agent transitions, creating compliance lead-time advantages for early reformulators. Stakeholders must monitor polymer feedstock cost volatility and blowing agent transition timelines to calibrate capacity commitments and product mix decisions.
Market Dynamics
The EU F-Gas Regulation's HFC phase-down is forcing manufacturers to reformulate blowing agent chemistry while retrofit contractors in Germany absorb premium pricing for certified boards.
Growth Catalysts
- Cold-chain logistics expansion:Refrigerated packaging demand from pharmaceutical distributors and fresh-food e-commerce operators is pulling high-performance extruded polystyrene into insulated shipping containers and thermal pallet shrouds.
- REACH-compliant flame retardant transitions:HBCD replacement chemistries cleared by ECHA are unlocking specification wins in public infrastructure projects where fire-safety certification gates procurement.
- German building stock renovation:The federal government's building efficiency mandates are concentrating demand for thick-board insulation in multi-family housing retrofits across Berlin and the Ruhr industrial belt.
Market Restraints
- Styrene monomer cost volatility:Feedstock prices tied to benzene-cracker output swings compress margin stability for non-integrated board producers.
- Polyurethane spray foam substitution:Liquid-applied insulation systems are capturing share in irregular cavity applications where rigid board cutting waste disadvantages extruded polystyrene.
- EU F-Gas compliance timelines:Accelerated HFC phase-down schedules are stranding capital equipment before depreciation cycles complete, pressuring mid-scale extrusion lines.
Strategic Opportunities
- Passive-house envelope specification:Near-zero-energy building codes in Austria and Belgium are creating premium-grade demand pools where lambda-values below 0.030 W/m·K command price multiples.
- Direct-to-contractor digital channels:Building material platforms are disintermediating traditional distributor markups for midsize roofing and foundation contractors.
- Carbon-accounting integration:Embodied-carbon disclosure requirements under the EU Green Deal are favoring manufacturers with verified lifecycle data and recycled-content feedstocks.
Industry Challenges
- Blowing agent transition engineering:Reformulating extrusion lines for next-generation hydrocarbon or hydrofluoroolefin systems demands process engineering talent scarce in legacy polystyrene operations.
- Multi-certification stacking:Simultaneous compliance with F-Gas, REACH, CE marking, and national fire-classification regimes extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extruded Polystyrene Market |
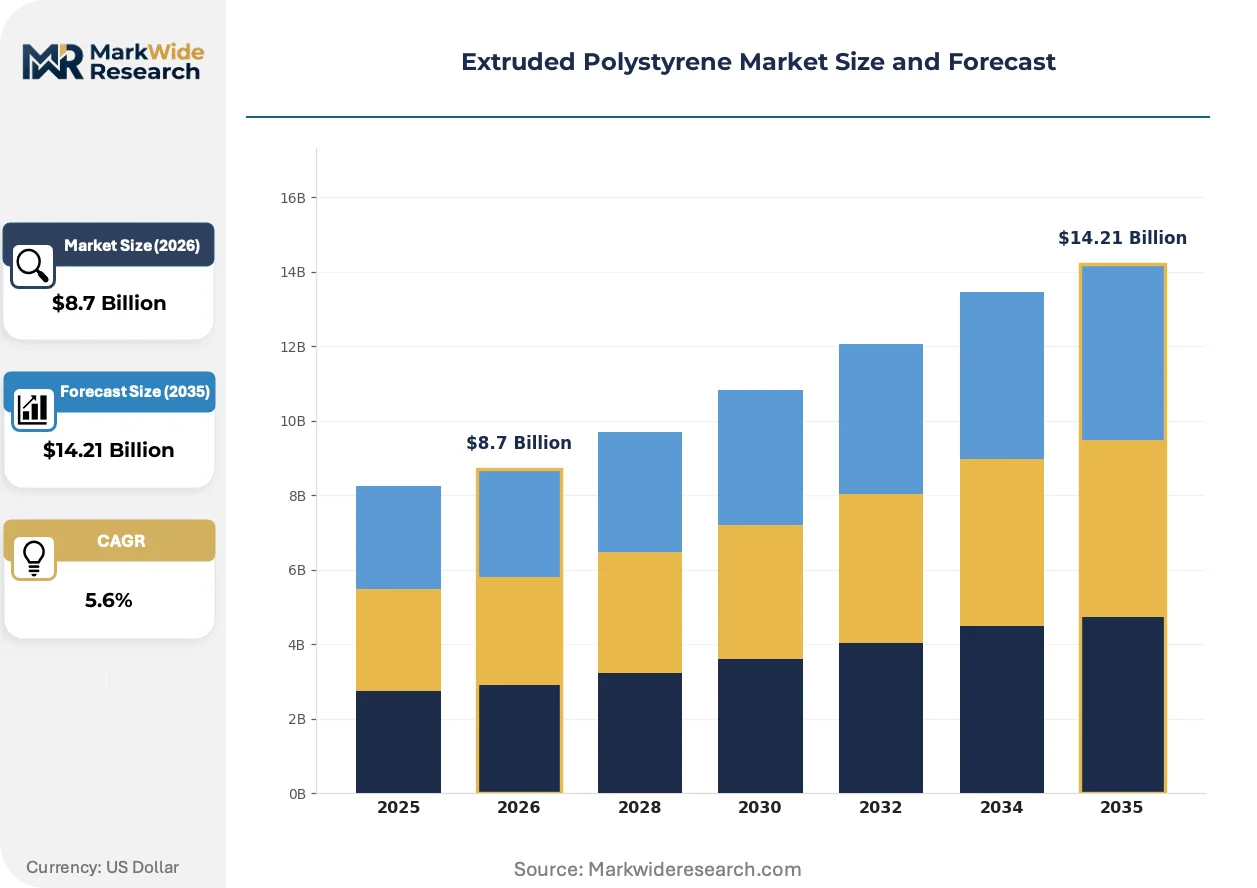
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, High Performance, Laminated, Coated End Use Industry: Construction, Packaging, Appliances, Transportation Thickness: 20mm, 30mm, 40mm, 50mm Form: Sheets, Panels, Blocks, Foam |
| Companies Covered | BASF, Austrotherm, DuPont, Synthos, Knauf Insulation, Saint-Gobain, Kingspan Group, TECHNONICOL, Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extruded Polystyrene Market Emerging Trajectories
Reformulation chemistry and distribution digitization are compressing legacy competitive advantages while regulatory disclosure requirements reshape buyer qualification criteria.
Next-generation hydrofluoroolefin blowing agents are collapsing the thermal-performance gap between extruded polystyrene and vacuum-insulated panels in commercial roofing assemblies. Passive-house consultants in Scandinavia are specifying these reformulated boards for parapet and balcony envelope continuity where thermal bridging penalties dominate energy modeling. The technology is collapsing premium pricing power for specialty vacuum-panel suppliers in Northern European markets.
The EU F-Gas Regulation's stepped phase-down schedule is mandating HFC-content reductions of 55% by 2030 and 95% by 2050 against baseline levels. Extrusion equipment operators are retrofitting lines for hydrocarbon or hydrofluoroolefin alternatives ahead of compliance deadlines to avoid stranded-asset risk. German and Austrian manufacturers with early reformulation certifications are capturing specification lock-in for public-sector retrofit tenders.
Building contractors are consolidating procurement through digital material platforms that aggregate price transparency and delivery scheduling across multiple insulation categories. Traditional two-step distribution through regional building-material wholesalers is losing share to contractor-direct fulfillment models. France and the Netherlands exhibit the fastest platform penetration where midsize roofing contractors prioritize inventory velocity over distributor credit terms.
Extruded Polystyrene Market Segmentation
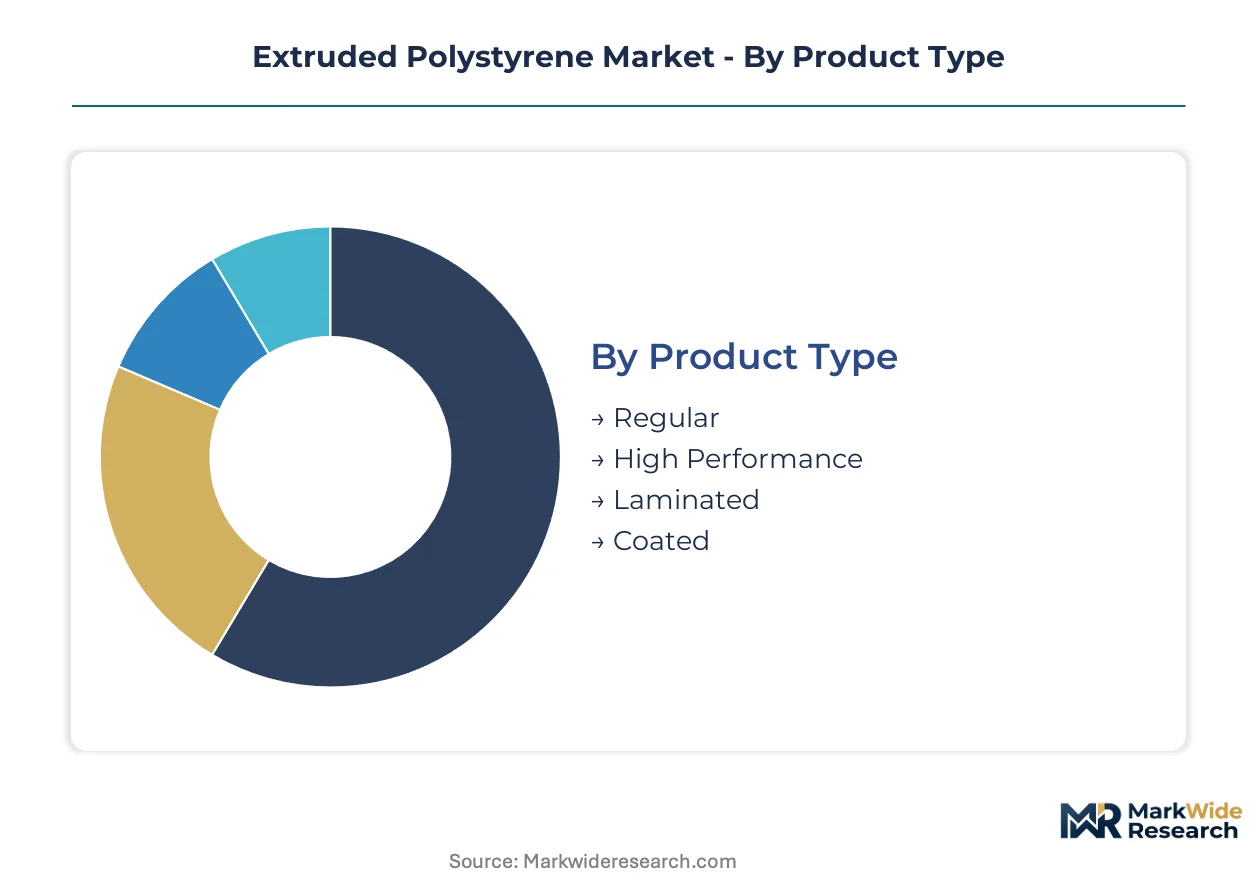
Segmentation in extruded polystyrene isolates where margin pools concentrate versus where volume commoditizes. Product chemistry and dimensional specifications determine certification requirements, while end-use selection dictates channel strategy and pricing power.
Product Type:
Cost tier separates commodity board from performance-graded material with reformulated blowing agents and enhanced compressive strength.
- Regular:Standard-density boards produced with conventional HFC or transitioning hydrocarbon blowing agents serve cost-sensitive construction markets. Demand concentrates in emerging economies where building codes prioritize thermal conductivity over passive-house certification. Margin compression intensifies as Chinese extruders expand export capacity.
- High Performance:Reformulated grades with hydrofluoroolefin blowing agents achieve lambda values below 0.030 W/m·K for near-zero-energy envelopes. German and Austrian retrofit contractors specify these boards for public-sector tenders where F-Gas compliance gates procurement.
- Laminated:Multi-layer configurations with factory-applied facers serve commercial roofing where moisture barriers justify specification premiums.
- Coated:Surface-treated boards with enhanced UV or abrasion resistance target exposed applications in transportation and outdoor infrastructure.
Regular grade holds installed capacity. High Performance is rotating up the share rankings.
End Use Industry:
Application determines specification intensity, with building envelopes demanding multi-certification compliance while logistics applications prioritize thermal performance per unit weight.
- Construction:Thermal insulation for walls, roofs, and foundations dominates volume, with German building stock renovation concentrating demand for thick-board retrofits. REACH-compliant flame retardant transitions unlock public infrastructure specification wins where fire-safety certification gates procurement.
- Packaging:Cold-chain logistics operators specify high-performance extruded polystyrene for refrigerated pharmaceutical containers and fresh-food thermal shrouds. E-commerce fulfillment networks in France and the Netherlands are standardizing insulated box-in-box configurations for temperature-sensitive deliveries.
- Appliances:Refrigerator and freezer cabinet insulation employs thinner boards with precise dimensional tolerances for automated assembly lines.
- Transportation:Lightweight structural cores for refrigerated trucks and shipping containers balance thermal performance against payload optimization.
Construction absorbs capacity concentration. Packaging is climbing the fastest in share rankings.
Thickness:
Dimensional specification correlates directly with thermal resistance requirements and regional building code stringency.
- 20mm:Thin boards serve interior insulation upgrades and appliance manufacturing where space constraints dominate design.
- 30mm:Mid-range thickness balances material cost with R-value for standard residential construction in moderate climates.
- 40mm:Specified for exterior wall systems in Northern European markets where energy efficiency mandates drive envelope performance. German federal renovation programs concentrate demand in multi-family housing retrofits across Berlin and the Ruhr.
- 50mm:Maximum standard thickness targets passive-house and deep-retrofit applications where thermal bridge elimination justifies material volume. Austrian and Belgian near-zero-energy codes create premium demand pools.
40mm holds installed capacity. 50mm is gaining share fastest in specification-driven segments.
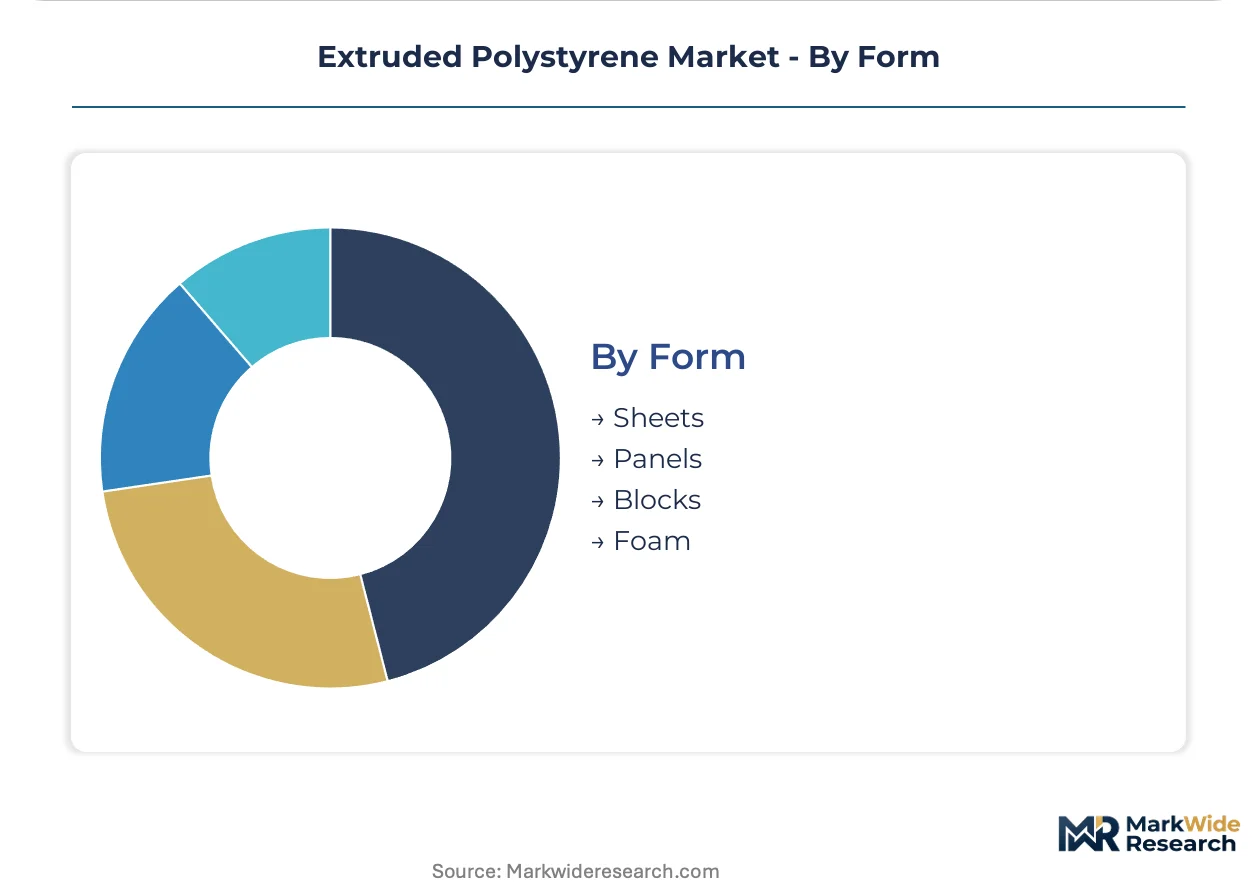
Form:
Physical configuration determines manufacturing equipment requirements and downstream processing economics.
- Sheets:Continuous extruded sheets serve high-volume construction markets where on-site cutting accommodates variable dimensions. Digital material platforms are disintermediating traditional distribution for midsize roofing contractors in France and the Netherlands.
- Panels:Pre-cut dimensional boards with factory-finished edges accelerate installation in modular construction and prefabricated wall systems.
- Blocks:Large-format billets enable custom fabrication for specialized industrial insulation and marine flotation applications.
- Foam:Loose-fill or molded shapes serve void-filling and contour-matching applications where rigid board geometry creates cutting waste.
Sheets hold installed capacity. Panels is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German and Austrian extrusion lines increasingly serve retrofit contractors across Northern Europe, while import dependency for styrene feedstock shapes margin structures in board-producing economies without integrated petrochemical bases.
Germany
Federal building efficiency mandates concentrate demand for thick-board insulation in multi-family housing retrofits across Berlin and the Ruhr industrial belt. The EU F-Gas Regulation's HFC phase-down forces manufacturers to reformulate blowing agent chemistry ahead of compliance deadlines. Munich-based contractors absorb premium pricing for REACH-compliant boards certified under national fire-safety regimes.
United States
Refrigerated packaging demand from pharmaceutical distributors and fresh-food e-commerce operators pulls high-performance boards into insulated shipping containers. The EPA Significant New Alternatives Policy program evaluates next-generation blowing agent transitions, creating compliance lead-time advantages for early reformulators. Contractor-direct digital channels in Texas and Florida disintermediate traditional distributor markups for midsize roofing specialists.
China
Cost-sensitive construction markets in second-tier cities prioritize standard-density boards where thermal conductivity specifications override passive-house certification. The country's national chemical safety regulator monitors flame retardant transitions as REACH-equivalent standards emerge. Zhejiang and Jiangsu extrusion clusters expand export capacity into Southeast Asian building material supply chains.
France
Digital material platforms achieve fastest penetration in the Paris Basin and Lyon corridor where midsize roofing contractors prioritize inventory velocity over distributor credit terms. The EU Green Deal's embodied-carbon disclosure requirements favor manufacturers with verified lifecycle data. Public infrastructure tenders specify HBCD-replacement chemistries cleared by ECHA for fire-safety certification gates.
Austria
Near-zero-energy building codes in Vienna and Salzburg create premium-grade demand pools where lambda-values below 0.030 W/m·K command price multiples. Early reformulation certifications for hydrofluoroolefin blowing agents capture specification lock-in for public-sector retrofit tenders. Alpine construction clusters specify high-performance boards for thermal bridge elimination in deep-retrofit applications.
Extruded Polystyrene Market Vendor Landscape
On the supply side, the industry is consolidating around integrated petrochemical players and specialized insulation fabricators with captive distribution networks. Three strategic archetypes dominate: styrene-integrated chemical conglomerates controlling upstream feedstock, building-envelope system integrators bundling insulation with moisture barriers, and regional extrusion specialists serving contractor-direct channels. Capacity expansion and certification pre-positioning for F-Gas compliance deadlines represent the dominant competitive moves.
Among European-based chemical conglomerates, BASF and Saint-Gobain exemplify divergent strategic positioning within the same regulatory environment. BASF anchors the styrene-integrated archetype through captive supply chain control, while Saint-Gobain occupies the system-integration tier where building-envelope bundling displaces commodity board sales. Owens Corning represents North American channel architecture, anchoring contractor-direct fulfillment models that bypass traditional two-step distribution.
| Leading Market Players |
|---|
| BASF |
| Austrotherm |
| DuPont |
| Synthos |
| Knauf Insulation |
| Saint-Gobain |
| Kingspan Group |
| TECHNONICOL |
| Owens Corning |
| Others |
Supply Flow & Price Mechanics
Styrene monomer cost volatility tied to benzene-cracker output swings compresses margin stability for non-integrated board producers while simultaneously widening spreads between captive-supply conglomerates and merchant extruders. This feedstock dependency determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic clustering of extrusion capacity around integrated petrochemical complexes.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for appliance and transportation applications where dimensional tolerances and batch consistency justify premium positioning. Price differentiation separates REACH-compliant high-performance grades with hydrofluoroolefin blowing agents from commodity HFC-based boards still transitioning under EU F-Gas deadlines. Cost compression in the regular grade tier is intensifying as Chinese extruders expand export capacity into Southeast Asian supply chains. Merchant producers without captive styrene supply exhibit the highest price sensitivity, while German retrofit contractors demonstrate inelastic demand for certified boards in public-sector tenders.
Supply Chain Analysis
Contract manufacturing concentration among German, Austrian, and Zhejiang extrusion clusters holds installed capacity for both standard and reformulated product grades. Feedstock supply draws from integrated petrochemical bases in Germany, China, and the US Gulf Coast, with benzene-cracker output volatility transmitting directly to board production economics. Single-source vulnerability concentrates in blowing agent supply chains where HFC phase-down schedules strand legacy equipment before depreciation cycles complete. Distribution runs through contractor-direct digital platforms in France and the Netherlands alongside traditional two-step building-material wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's HFC phase-down mandates represent a technological inflection that will consolidate competitive position around early reformulators with certified hydrofluoroolefin production lines. This regulatory compression creates asymmetric upside for stakeholders positioned ahead of compliance deadlines.
For Market Incumbents: Insulate specification lock-in by accelerating hydrocarbon and hydrofluoroolefin reformulation certifications ahead of 2030 F-Gas milestones. BASF and Saint-Gobain should deepen backward integration into captive styrene supply to defend margin control against merchant feedstock volatility. Channel control through contractor-direct digital platforms in France and the Netherlands displaces distributor markups and captures inventory velocity preferences among midsize roofing specialists. For New Entrants and Emerging Players: Build out regional extrusion capacity in Poland and Czechia to serve German retrofit contractors facing thick-board demand concentration in Berlin and the Ruhr industrial belt. The penetrable white space sits in cold-chain logistics packaging where pharmaceutical distributors and fresh-food e-commerce operators standardize insulated container specifications. A go-to-market angle emphasizing embodied-carbon disclosure and recycled-content feedstocks aligns with EU Green Deal procurement criteria. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors styrene-integrated specialists with F-Gas pre-certification. Long-term viability over the next decade hinges on process engineering talent access for blowing agent transitions and multi-certification stacking capabilities. Acquisition targets should demonstrate verified lifecycle data and public-sector tender track records in Germany and Austria. The signal to watch is stranded-asset announcements from mid-scale extruders missing reformulation deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Styrene Feedstock | BASF's captive supply chain control sustains margin stability against benzene-cracker volatility. |
| Hydrofluoroolefin Reformulation Certification | Early ECHA clearance unlocks specification lock-in for German public-sector retrofit tenders. |
| Contractor-Direct Digital Channel Buildout | Platform disintermediation in France and the Netherlands captures inventory velocity preferences. |
| Embodied-Carbon Disclosure Program | Verified lifecycle data aligns procurement qualification with EU Green Deal requirements. |
| Regional Capacity Expansion in Poland | Proximity to German demand clusters reduces logistics costs for thick-board retrofit shipments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, Cefic chemical industry reports, SEC 10-K filings, and EU regulatory submission databases. Interviews with plant managers at extrusion facilities, procurement leads at cold-chain logistics operators, distribution channel partners, and technical R&D directors informed capacity and specification trends. Bottom-up volume estimates from named production clusters triangulate against top-down demand modeling from construction retrofit programs and packaging standardization initiatives.
Forecast inputs incorporate grade tier differentiation, end-use industry application intensity, thickness specification clustering, and regional regulatory compliance timelines across the analysis window. The analytical framework models product chemistry transitions, channel structure evolution, and feedstock cost transmission mechanisms. CAGRs derive from segmented demand elasticity and capacity expansion announcements rather than macroeconomic extrapolation alone. Blowing agent transition timelines and REACH flame retardant certification schedules constitute critical industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese export-oriented extruders or accelerated F-Gas phase-down schedules would shift outcomes beyond modeled ranges. Quarterly review of ECHA certification announcements, German federal renovation program allocations, and benzene-cracker operating rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Propylene Terpolymer Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Biaxially Oriented Polypropylene Market