
 Ammonium Polyphosphate (Phase II) Market | 2026-2036
Ammonium Polyphosphate (Phase II) Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Polyphosphate (Phase II) Market Outlook
Market Context
Advanced phosphorus chemistry is reconfiguring how flame retardant formulators design intumescent coating systems for steel and polymer substrates. Budenheim leverages its integrated phosphate rock supply chain to sustain cost advantages across European construction markets. Clariant differentiates through halogen-free additive portfolios that align with tightening environmental standards in plastics compounding. ICL Group dominates bulk fertilizer-grade production while extending technical service capabilities into specialty fire-safety applications.
Technical Profile and Segment Structure
Ammonium Polyphosphate (Phase II) is a crystalline inorganic salt with a linear polyphosphate chain structure and higher thermal stability than Phase I grades, manufactured through controlled condensation of ammonium orthophosphate at elevated temperature under precise moisture conditions. Its primary commercial purpose is to serve as a non-halogenated flame retardant and slow-release nitrogen-phosphorus fertilizer source. The powder product format leads volume due to ease of dry blending into intumescent paints and polymer masterbatches, while coated variants command margin premiums for moisture-sensitive agricultural applications. Flame retardant applications are expanding fastest as construction codes in multiple jurisdictions mandate enhanced fire resistance for insulation foams and structural steel coatings.
Regulatory Environment and Outlook
REACH restrictions on halogenated flame retardants and the EU Green Deal's chemical sustainability targets are redirecting formulation R&D toward phosphorus-based alternatives across European manufacturing. EPA assessments under the Toxic Substances Control Act and China's GB standards for building materials are similarly elevating product testing and certification requirements in their respective markets. Stakeholders must monitor evolving substance restriction lists and certification protocols to anticipate qualification timelines for next-generation intumescent systems.
Market Dynamics
Construction code revisions across industrialized economies are compressing qualification timelines for intumescent coating formulators, forcing simultaneous reformulation of phosphorus-based additive packages and accelerated third-party fire-resistance testing.
Growth Catalysts
- REACH substance restrictions:ECHA's ongoing assessments of halogenated flame retardants are mandating substitution timelines that directly elevate Phase II procurement volumes from European polymer compounders.
- Steel protection coatings:Commercial builders in China and Germany are specifying APP-based intumescent systems for structural fireproofing as building height regulations tighten.
- Phosphate rock integration:Captive upstream control over phosphorus raw material is insulating integrated producers from orthophosphate price volatility affecting merchant market participants.
Market Restraints
- Phosphate rock supply concentration:Moroccan and Chinese state-controlled mining entities dominate extractive capacity, exposing non-integrated flame retardant manufacturers to geopolitical supply disruptions.
- Thermal decomposition threshold:Phase II APP degrades above 275°C, limiting deployment in high-temperature polymer processing applications where aluminum phosphinates substitute.
- Moisture sensitivity:Uncoated powder grades require climate-controlled logistics infrastructure that elevates landed costs for agricultural fertilizer distributors in humid subtropical markets.
Strategic Opportunities
- Coated microencapsulation:Moisture-barrier surface treatments are opening controlled-release fertilizer applications in Southeast Asian rice cultivation where conventional APP hydrolyzes prematurely.
- EU Green Deal taxonomy:Sustainable finance classification criteria are channeling institutional capital toward phosphorus recycling projects that secure circular feedstock for specialty chemical producers.
- Electric vehicle battery housings:Thermal runaway containment specifications for lithium-ion pack enclosures are creating specification pull from automotive tier-one suppliers seeking halogen-free intumescent layers.
Industry Challenges
- Intumescent formulation chemistry:Shortage of experienced fire-retardant polymer scientists is extending R&D cycles for coating developers attempting to match multi-hour fire ratings with reduced additive loadings.
- Certification body backlog:UL and Intertek testing queues for ASTM E119 and EN 1363-1 compliance are stretching commercialization timelines by eight to fourteen months for new intumescent product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Polyphosphate (Phase II) Market |
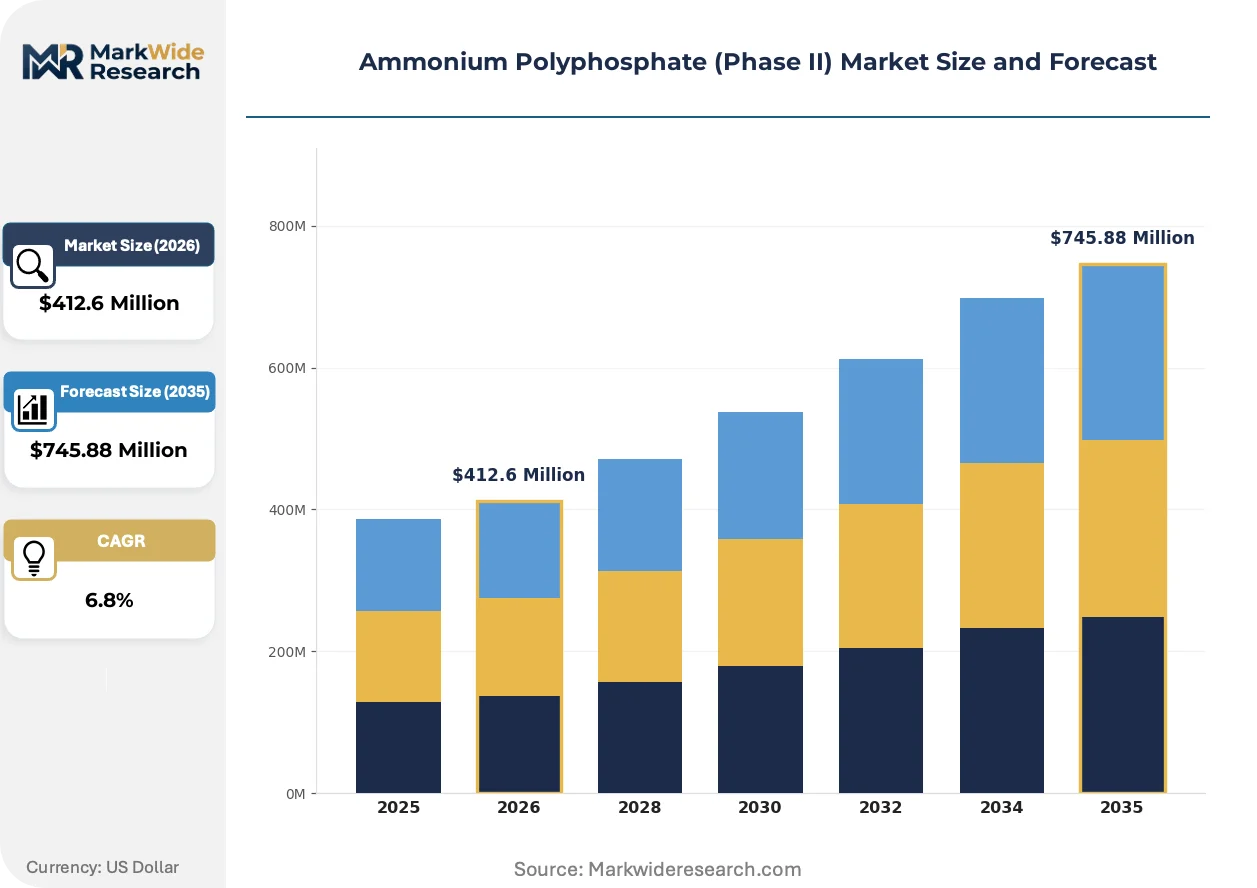
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powder, Coated Application: Fertilizers, Flame Retardants, Agrochemicals, Food Additives End Use Industry: Agriculture, Construction, Plastics, Food & Beverage Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | Budenheim, Zhejiang Longyou GD Chemical, Clariant, Perimeter Solutions, Sichuan Shifang Weifeng Chemical, ICL Group, Oceanchem Group, Chuanjun Imp. & Exp. Trading Co., JLS Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Polyphosphate (Phase II) Market Strategic Shifts
Digital formulation platforms and accelerated materials screening are compressing development cycles for next-generation phosphorus-based fire safety systems. These capabilities are redistributing competitive advantage toward data-integrated specialty chemical operations.
Microencapsulation technology using melamine-formaldehyde or silica shell architectures is virtualizing moisture protection for APP particles without sacrificing phosphorus release kinetics. Coating compounders in Germany and Japan are adopting these grades for exterior architectural applications where humidity cycling previously excluded unprotected APP. The technology is virtualizing geographic market access for producers previously constrained by climate-specific product limitations.
EPA assessments under the Toxic Substances Control Act are elevating data requirements for pre-manufacture notifications of novel flame retardant substances. Chemical manufacturers are responding by prioritizing existing chemical substance designations for APP rather than pursuing new molecular entities. North American building product suppliers are accelerating third-party certifications to preempt potential state-level restrictions modeled on Washington's Safer Products program.
Specification consolidation among multinational construction chemical distributors is compressing supplier qualification from multi-year engagements to eighteen-month vendor onboarding cycles. Buyers are unbundling technical service from material supply, procuring formulation support through separate engineering consultancies. This pattern is most pronounced in Chinese commercial real estate development where state-owned developers centralize procurement through designated trading platforms.
Ammonium Polyphosphate (Phase II) Market Segmentation
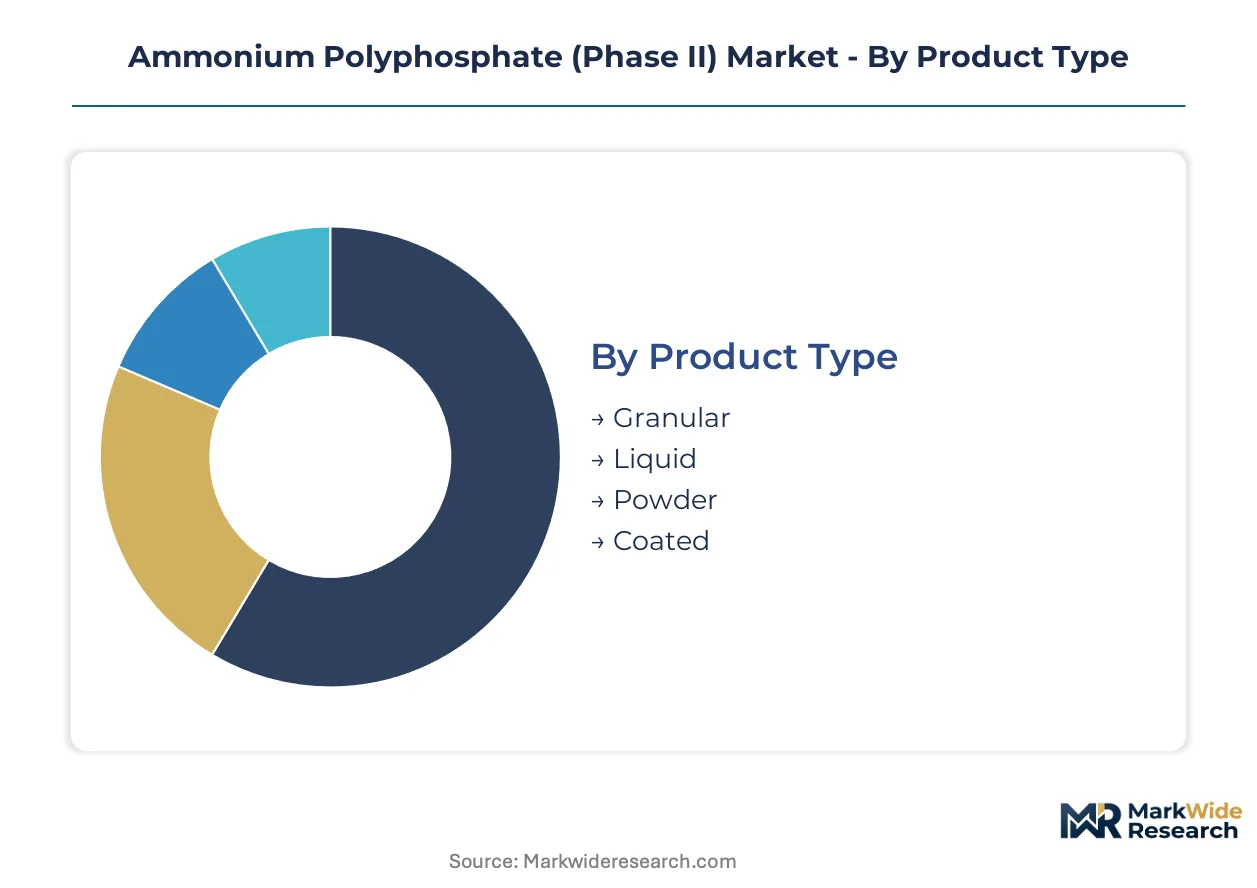
Segmentation in Ammonium Polyphosphate (Phase II) reveals divergent technical requirements across flame retardant compounding versus agricultural nutrient delivery. Manufacturers configure crystallinity, particle size, and surface treatment specifications to match end-use thermal stability and solubility demands.
Product Type:
Mature powder formats dominate volume, while emerging coated variants capture margin expansion through moisture protection.
- Powder:Standard crystalline Phase II APP with linear polyphosphate chains serves as the baseline for intumescent coating dry-blending and polymer masterbatch incorporation. Construction chemical formulators in Germany and China specify this grade for steel protection systems where thermal activation above 275°C triggers char formation. Powder retains volume leadership; coated holds the steepest expansion curve.
- Coated:Microencapsulated particles using melamine-formaldehyde or silica shell architectures deliver humidity resistance for tropical fertilizer applications and exterior architectural coatings. Southeast Asian rice cultivation markets drive specification pull where unprotected APP hydrolyzes prematurely in monsoon conditions.
- Granular:Compacted agglomerates optimize bulk handling for mechanized fertilizer spreading equipment.
- Liquid:Aqueous suspensions serve specialized textile flame retardant finishing operations requiring pumpable delivery systems.
Powder retains volume leadership; coated holds the steepest expansion curve.
Application:
Application segmentation tracks divergent regulatory pressures, with construction fire codes elevating flame retardant procurement while agricultural nutrient efficiency standards reshape fertilizer formulation.
- Flame Retardants:Intumescent systems for steel structural protection and polymer insulation foams represent the technology's highest-value deployment. REACH substance restrictions and China's GB building material standards mandate phosphorus-based substitution for halogenated alternatives in commercial high-rise construction.
- Fertilizers:Controlled-release nitrogen-phosphorus nutrient sources leverage Phase II APP's gradual solubility kinetics compared to orthophosphate alternatives. Humid subtropical distribution corridors require coated variants to prevent caking and nutrient lock-up during storage.
- Agrochemicals:Specialty formulations incorporate APP as a phosphorus source in foliar feeds and soil amendments.
- Food Additives:Leavening acid applications in bakery products utilize food-grade APP meeting FCC purity specifications.
Flame retardants command premium pricing tiers; fertilizers sustain baseline volume throughput.
End Use Industry:
Industry segmentation reflects supply chain concentration, with construction and agriculture consuming divergent product specifications through distinct procurement channels.
- Construction:Intumescent coating formulators procure technical-grade APP for ASTM E119 and EN 1363-1 certified steel protection systems. German commercial builders and Chinese state-owned developers centralize procurement through designated trading platforms, compressing supplier qualification timelines.
- Agriculture:Fertilizer blenders and distributors specify powder or coated grades based on regional humidity exposure and application equipment requirements.
- Plastics:Polymer compounders integrate APP into polyolefin and thermoset formulations for electrical enclosure and transportation interior applications.
- Food & Beverage:Industrial bakeries and prepared food manufacturers utilize food-grade APP as a slow-acting leavening acid in refrigerated dough systems.
Construction drives specification innovation; agriculture anchors production scale.
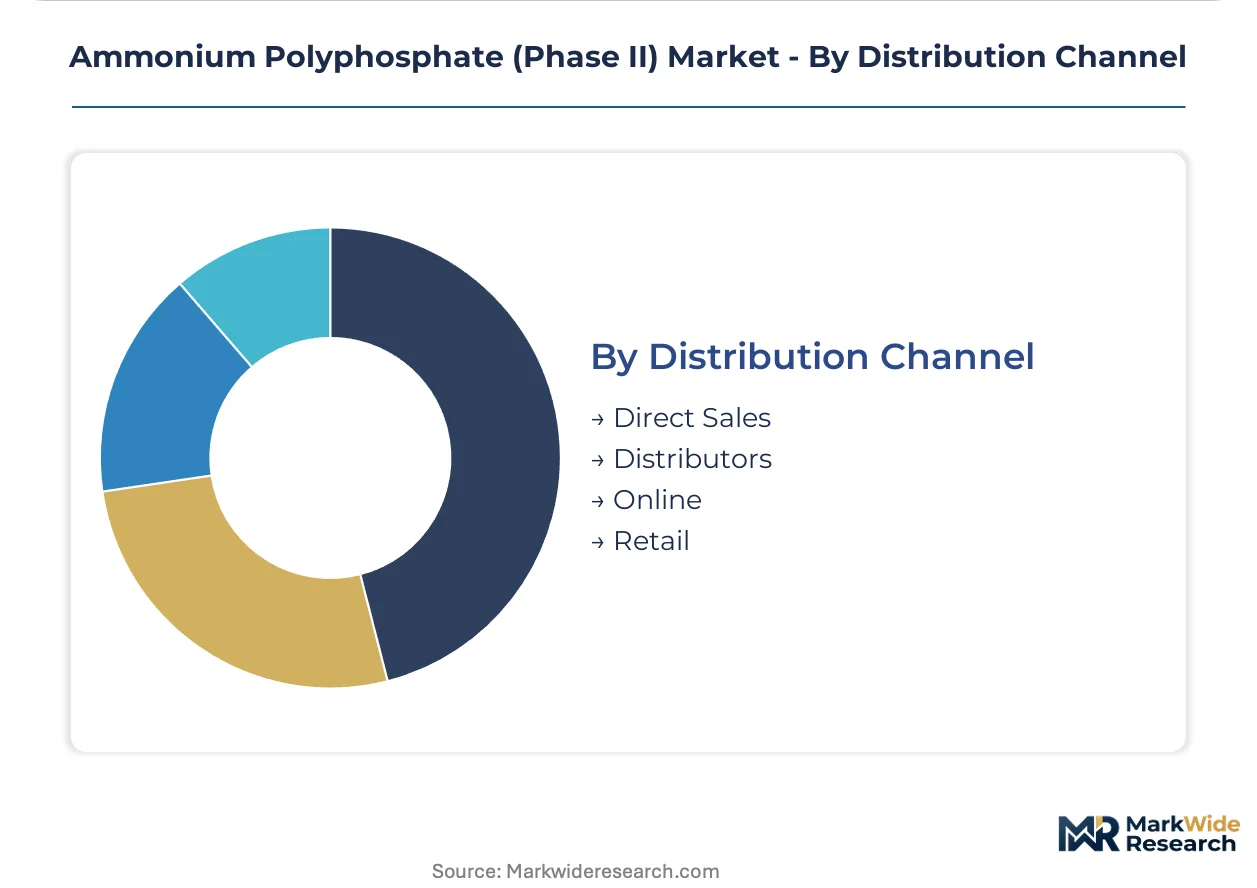
Distribution Channel:
Channel segmentation tracks procurement unbundling trends, with technical service separating from material supply across construction chemical markets.
- Distributors:Regional chemical distributors stock standard powder grades for construction coating formulators and agricultural blenders, providing climate-controlled warehousing where moisture sensitivity demands environmental management.
- Direct Sales:Integrated phosphate rock producers supply bulk flame retardant manufacturers through long-term offtake agreements, bypassing merchant market price volatility.
- Online:E-procurement platforms serve small-scale agricultural cooperatives and specialty chemical purchasers with standardized product configurations.
- Retail:Garden center and farm supply outlets package consumer-grade fertilizer formulations for hobbyist cultivation markets.
Distributors retain channel dominance; direct sales capture integrated supply contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flame retardant formulators and fertilizer distributors concentrate procurement decisions in five national markets where building codes and agricultural policy reshape specification requirements.
China
State-owned developers in Beijing and Shanghai specify APP-based intumescent coatings for high-rise steel protection under tightening GB standards for building materials. The Ministry of Ecology and Environment enforces dual carbon goals that elevate phosphorus recycling projects. Sichuan and Shandong provinces host integrated phosphate producers serving domestic construction chemical platforms.
Germany
Commercial builders in Munich and Frankfurt procure halogen-free flame retardant systems as REACH substance restrictions mandate substitution timelines. ECHA assessments of brominated alternatives accelerate Phase II procurement from polymer compounders. The North Rhine-Westphalia chemical cluster concentrates formulation R&D for ASTM E119-certified steel coatings.
United States
Construction chemical distributors in Texas and California stock powder grades for intumescent coating dry-blending as EPA TSCA assessments elevate data requirements. Washington state's Safer Products program drives third-party certification urgency. The Gulf Coast petrochemical corridor integrates APP into polyolefin masterbatches for electrical enclosure applications.
India
Fertilizer blenders in Maharashtra and Gujarat specify coated APP variants for rice cultivation under humid monsoon conditions where unprotected grades hydrolyze. BIS standards for building materials gradually elevate fire-resistance testing requirements. The Gujarat chemical cluster hosts import-dependent flame retardant formulators seeking supply security.
Japan
Automotive tier-one suppliers in Nagoya and Tokyo evaluate APP for lithium-ion battery housing thermal containment under METI safety guidelines. JIS standards for polymer flame retardancy elevate phosphorus-based formulation. The Osaka-Kobe industrial zone concentrates electrical enclosure manufacturing requiring halogen-free additive integration.
Ammonium Polyphosphate (Phase II) Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market that concentrates around integrated phosphate rock producers and technical-grade formulators. Three archetypes dominate: vertically integrated mining-to-chemical operations, construction-focused flame retardant specialists, and agricultural nutrient distributors with climate-controlled logistics capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Among German and Swiss chemical conglomerates, Budenheim and Clariant occupy positions exemplifying phosphate supply chain integration and halogen-free portfolio specialization respectively. Chinese producers including Zhejiang Longyou GD Chemical and Sichuan Shifang Weifeng Chemical represent the scale-driven manufacturing tier serving domestic construction and agricultural procurement platforms. ICL Group anchors the integrated mining-to-specialty-chemical archetype with captive upstream phosphorus control.
| Leading Market Players |
|---|
| Budenheim |
| Zhejiang Longyou GD Chemical |
| Clariant |
| Perimeter Solutions |
| Sichuan Shifang Weifeng Chemical |
| ICL Group |
| Oceanchem Group |
| Chuanjun Imp. & Exp. Trading Co. |
| JLS Chemical |
| Others |
Value Chain & Pricing Dynamics
Overcapacity signals from Sichuan and Shandong phosphate producers are compressing spot margins for unintegrated flame retardant manufacturers while reinforcing the pricing power of captive rock holders. This utilization divergence shapes procurement negotiations across European construction chemical platforms and Asian fertilizer distribution networks.
Pricing Analysis
Cost-plus contracts indexed to Moroccan phosphate rock benchmarks dominate long-term offtake agreements between integrated producers and construction chemical formulators. Price differentiation separates UL-certified technical grades for steel protection coatings from standard fertilizer powders, with certification tier and volume scale as primary levers. Pricing pressure stems from Chinese state-owned producers absorbing margin compression to maintain operating rates. Agricultural blenders in humid subtropical markets exhibit highest price sensitivity due to coated-grade premiums, while German intumescent coating formulators prioritize supply security over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates risk calculations for North American flame retardant distributors sourcing technical-grade powder. Supply concentrates in Morocco, China, and Russia for phosphate rock extraction, with downstream APP production clustering in Sichuan, Shandong, and the German North Rhine-Westphalia chemical corridor. The supply chain draws from sulfur, ammonia, and phosphate rock feedstocks, with single-source vulnerability concentrated in Moroccan state-controlled mining entities. Distribution runs through regional chemical distributors providing climate-controlled warehousing for moisture-sensitive grades, supplemented by direct sales from integrated producers to bulk compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for intumescent formulation support are expanding faster than commodity powder sales as construction chemical buyers unbundle engineering consultancy from material procurement. This service-attach dynamic elevates recurring-revenue quality for producers investing in fire-resistance certification capabilities.
For Market Incumbents: Insulate margin structure through captive phosphate rock supply and accelerated UL/Intertek certification investments to exploit testing body backlogs. Aluminum phosphinate substitution in high-temperature polymer processing threatens Phase II volume in automotive applications; defend position through microencapsulation R&D for battery housing specifications. Backward integration into phosphorus recycling projects aligns with EU Green Deal taxonomy incentives. For New Entrants and Emerging Players: Build out coated-grade production capacity targeting Southeast Asian rice cultivation markets where humidity-driven hydrolysis creates specification pull. The Indian fertilizer blender segment offers most penetrable entry point given import-dependent supply security concerns. Partner with German engineering consultancies to bypass multi-year qualification barriers in European construction chemical distribution. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with long-term offtake agreements and technical service capabilities. Five-to-ten year viability favors mining-to-chemical operations with captive upstream control over Moroccan or Chinese phosphate rock. Acquisition target archetype: mid-cap flame retardant specialists with UL-certified product portfolios and underutilized microencapsulation capacity. Monitor ECHA substance restriction timelines as inflection signal for Phase II substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive phosphate rock supply insulates margin from orthophosphate price volatility affecting merchant competitors. |
| Microencapsulation Capacity Expansion | Moisture-barrier surface treatments open Southeast Asian fertilizer markets previously excluded due to hydrolysis risk. |
| Third-Party Certification Acceleration | UL and Intertek testing queue compression creates first-mover advantage for ASTM E119-compliant steel coating formulations. |
| Phosphorus Recycling Investment | EU Green Deal taxonomy alignment channels institutional capital toward circular feedstock security for specialty chemical production. |
| Technical Service Unbundling | Separate engineering consultancy contracts from material supply capture margin from construction chemical procurement centralization. |
Study Parameters
A standing panel of intumescent coating formulators, phosphate rock procurement leads, fertilizer distribution channel partners, and fire-resistance certification specialists provided ongoing calibration throughout the study. Primary interviews with construction chemical technical directors and agricultural blender operations managers combined with secondary validation from customs/trade data, ECHA substance restriction assessments, SEC 10-K filings from listed chemical producers, and GB standards documentation for Chinese building materials. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Scenario-bracketing around regulatory acceleration timelines and phosphate rock supply disruption probabilities bounded the projection range across the analysis window. Segmentation dimensions modeled include product format tier, end-use industry, surface treatment specification, and regional production hub. CAGRs derived from historical growth rate analysis adjusted for substitution elasticity and certification backlog duration. Industry-specific forecast inputs incorporated REACH substance restriction implementation schedules and Chinese dual carbon policy enforcement intensity.
Stress conditions across Moroccan mining output variability, ECHA assessment acceleration, and Chinese environmental compliance enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding substitution timelines and supply concentration persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Global Polyanionic Cellulose (PAC) Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Water-Borne Epoxy Resins Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
Polyvinyl Alcohol (PVA) Market
Polymers & Resins
Geopolymer Market
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market
Polymers & Resins
Resin Cement for Luting Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Synthetic Latex Polymers Market