
 Global Narcolepsy Drugs Market | 2026-2036
Global Narcolepsy Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Narcolepsy Drugs Market Foresight
Buyer concentration among specialty sleep clinics is repositioning procurement patterns across the narcolepsy therapeutics landscape. Jazz Pharmaceuticals plc leverages its established sodium oxybate franchise to dominate the branded segment. Takeda Pharmaceutical Company Limited anchors its presence through deep ties with Japanese neurological centers. Harmony Biosciences differentiates via pitolisant distribution across U.S. academic medical centers.
Narcolepsy drugs comprise pharmaceutical agents targeting orexin/hypocretin pathway dysfunction, with sodium oxybate formulations requiring controlled-substance manufacturing protocols and refrigerated supply chains to maintain chemical stability. These therapeutics restore sleep-wake architecture and reduce cataplexy frequency in patients with confirmed hypocretin deficiency. Sodium oxybate products command the largest revenue pool due to premium pricing and chronic administration requirements, while pitolisant segments gain traction among clinicians prioritizing non-scheduled alternatives. Oral delivery mode occupies the dominant share, though subcutaneous formulations are emerging for patients with swallowing difficulties or absorption variability.
The FDA's Risk Evaluation and Mitigation Strategy for sodium oxybate shapes distribution access, while the EMA's orphan drug incentives accelerate European development timelines. Japan's PMDA maintains distinct pharmacovigilance requirements for central nervous system agents that influence trial design. Stakeholders must monitor evolving controlled-substance scheduling decisions and orexin-targeting pipeline candidates to anticipate portfolio displacement risks.
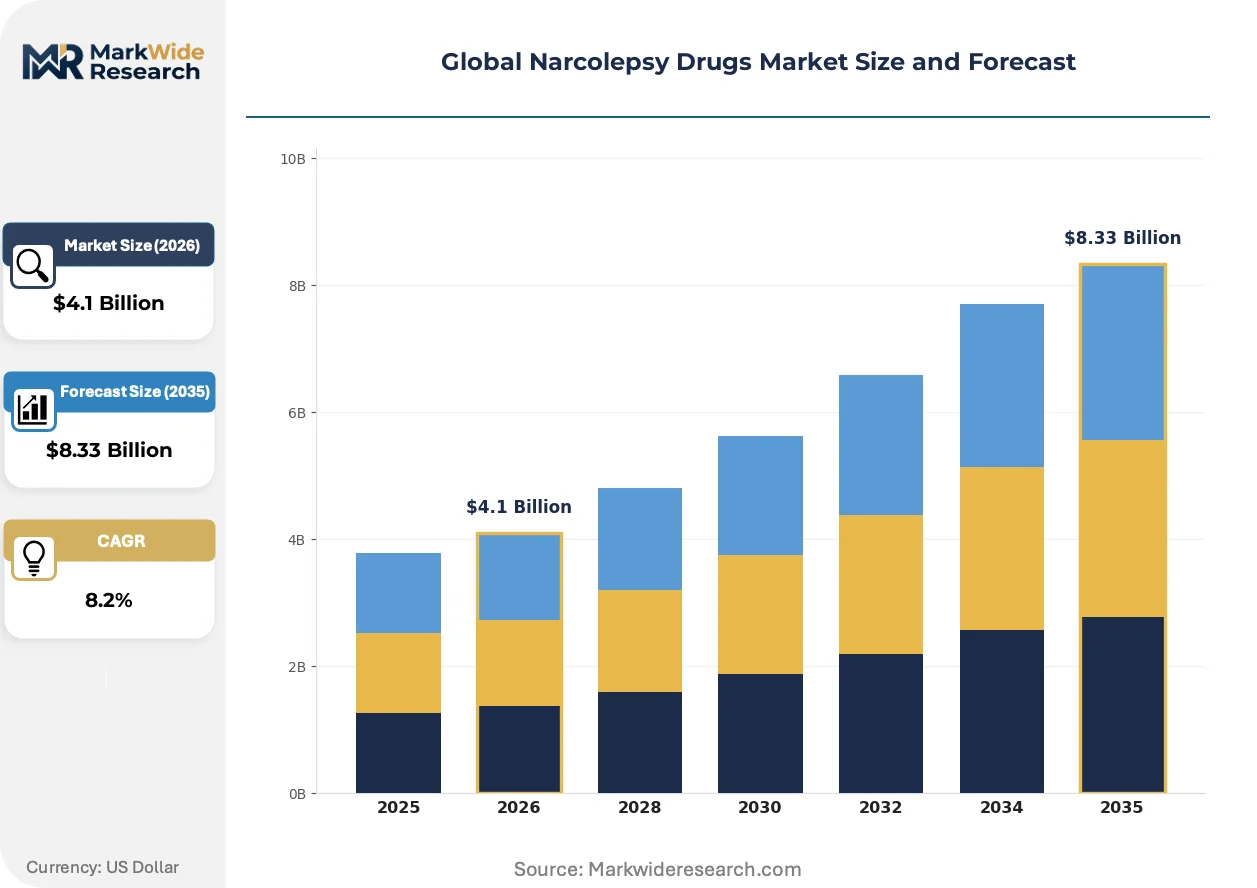
Market Dynamics
Controlled-substance scheduling for sodium oxybate formulations concentrates manufacturing capacity among DEA-registered facilities, creating supply-side bottlenecks that reshape competitive positioning across the narcolepsy therapeutics landscape.
Growth Catalysts
- EMA Orphan Drug Incentives:The European framework accelerates clinical trial protocols for orexin-targeting candidates, compressing development timelines for novel therapeutics entering the pipeline.
- Specialty Sleep Clinic Expansion:Academic medical centers across the United States are establishing dedicated narcolepsy protocols, driving protocol-driven demand for pitolisant and sodium oxybate formulations.
- Diagnostic Biomarker Advancement:Hypocretin deficiency testing is integrating into standard neurological workups, reducing historical under-recognition and expanding the addressable patient population.
Market Restraints
- DEA Scheduling Friction:Sodium oxybate's Schedule III classification imposes distribution lock-in through the FDA's Risk Evaluation and Mitigation Strategy, limiting pharmacy access and patient onboarding velocity.
- Cold Chain Concentration:Refrigerated logistics requirements for chemical stability restrict manufacturing to a narrow base of qualified contract organizations, amplifying supply vulnerability.
- Generic Sodium Oxybate Entry:Authorized generic formulations are compressing branded pricing power and forcing portfolio diversification toward non-scheduled alternatives.
Strategic Opportunities
- German Neurological Center Networks:Underpenetrated diagnostic capacity in Bavaria and North Rhine-Westphalia presents white-space expansion for pitolisant detailing and patient identification programs.
- Subcutaneous Delivery Convergence:The intersection of wearable pump technology and orexin-targeting peptides is opening chronic administration pathways for patients with swallowing difficulties.
- Japan PMDA Fast-Track Pathway:The regulator's priority review system for central nervous system agents offers accelerated market entry for novel mechanisms addressing unmet cataplexy control needs.
Industry Challenges
- Controlled-Substance Compliance Expertise:Shortage of professionals trained in DEA quota management and REMS administration is constraining operational scale-up for new market entrants.
- Refrigerated Capacity Capex:Expansion of GMP-certified cold storage infrastructure demands capital deployment that mid-cap developers struggle to fund without partnership structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Narcolepsy Drugs Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.33 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Oxybate, Modafinil, Armodafinil, Pitolisant Therapy Area: Hypernarcolepsy, Idiopathic Narcolepsy, Secondary Narcolepsy, Others Delivery Mode: Oral, Intravenous, Subcutaneous, Inhalation End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions |
| Companies Covered | Jazz Pharmaceuticals plc, Teva Pharmaceutical Industries Ltd., Harmony Biosciences, Avadel Pharmaceuticals plc, Axsome Therapeutics Inc., Takeda Pharmaceutical Company Limited, Novartis AG, Bioprojet Pharma, Ligand Pharmaceuticals Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Narcolepsy Drugs Market Shifts & Advancements
Orexin-targeting mechanisms are displacing legacy dopaminergic approaches as the dominant R&D focus, while regulatory frameworks and procurement models co-evolve to accommodate precision neurology therapeutics.
Dual orexin receptor antagonist reversal agents are integrating into clinical development pipelines as next-generation wake-promoting alternatives. Specialty sleep clinics in the United States are adopting these candidates for treatment-resistant cases, compressing the market window for traditional stimulant-based protocols. The technology is integrating prescriber education requirements into academic medical center training programs, reshaping how neurologists approach hypocretin deficiency management.
The FDA's Risk Evaluation and Mitigation Strategy for sodium oxybate is tightening distribution access requirements while expanding prescriber certification mandates. This regulatory compression is forcing manufacturers to invest in hub-and-spoke pharmacy networks rather than traditional wholesale channels. Branded sodium oxybate formulations are responding by building direct-to-specialist sales infrastructure that bypasses general neurology practices.
Academic medical centers are consolidating narcolepsy treatment protocols under single-specialty pharmacy arrangements, displacing fragmented retail distribution. This channel concentration is compressing formulary access for newer entrants while privileging established relationships with large sleep clinic networks. The shift is most visible across the United States, where integrated delivery systems in Pennsylvania and California are piloting exclusive distribution agreements for pitolisant and sodium oxybate products.
Global Narcolepsy Drugs Market Segmentation
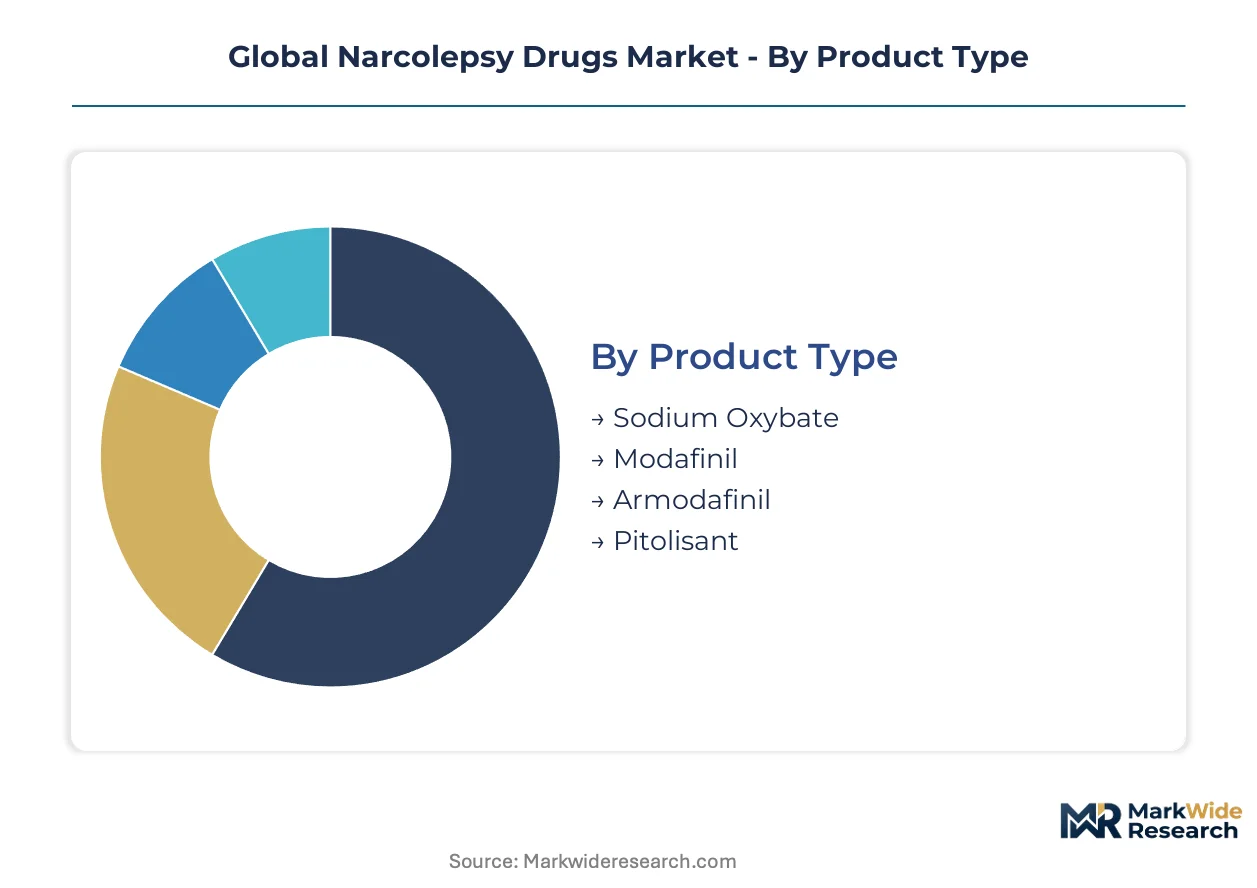
Narcolepsy therapeutics segment across four intersecting dimensions that determine pricing power, distribution access, and prescriber preference. Product type and delivery mode classifications most directly shape manufacturing requirements and regulatory pathways.
Product Type:
Sodium oxybate formulations command premium pricing and chronic administration protocols, while pitolisant segments expand through non-scheduled positioning.
- Sodium Oxybate:Controlled-substance formulations manufactured under DEA quota systems with refrigerated stability requirements. Demand concentrates in U.S. academic medical centers where REMS-certified prescribers manage cataplexy-resistant patients. Cold chain concentration limits contract manufacturing options.
- Pitolisant:Histamine H3 receptor inverse agonist requiring no controlled-substance handling. German neurological centers and Japanese sleep clinics prioritize this mechanism for patients with substance abuse histories or pharmacy access constraints.
- Modafinil:Wake-promoting agent with established generic availability.
- Armodafinil:R-enantiomer formulation with longer half-life for once-daily dosing.
Mature deployment sits with sodium oxybate in cataplexy-dominant cases. Newer deployment is concentrated in pitolisant for clinicians seeking formulary flexibility.
Therapy Area:
Diagnostic specificity determines reimbursement coding and treatment duration across narcolepsy subtypes.
- Hypernarcolepsy:Excessive daytime sleepiness with confirmed hypocretin deficiency drives longest treatment persistence. U.S. specialty sleep clinics and Japanese neurological centers concentrate diagnostic capacity for biomarker-confirmed cases.
- Idiopathic Narcolepsy:Symptom-based diagnosis without hypocretin testing standardization. German ambulatory neurology practices manage volume here with protocol-driven pitolisant initiation.
- Secondary Narcolepsy:Symptomatic cases from traumatic brain injury or hypothalamic lesions.
- Others:Atypical presentations and comorbid sleep-wake disorders.
Mature deployment sits with idiopathic narcolepsy in general neurology. Newer deployment is concentrated in hypernarcolepsy at academic biomarker centers.
Delivery Mode:
Patient adherence constraints and absorption variability shape route selection beyond simple convenience factors.
- Oral:Dominant administration pathway with immediate-release and extended-release formulations. Sodium oxybate oral solutions require bedtime dosing protocols that homecare settings struggle to maintain consistently.
- Subcutaneous:Emerging wearable pump compatibility for patients with dysphagia or gastric motility disorders. Japanese development programs target this modality for orexin peptide candidates.
- Intravenous:Hospital-restricted administration for acute cataplexy status or perioperative management.
- Inhalation:Experimental delivery for rapid-onset wake promotion in shift-work adaptations.
Mature deployment sits with oral formulations across all settings. Newer deployment is concentrated in subcutaneous programs targeting swallowing-impaired populations.
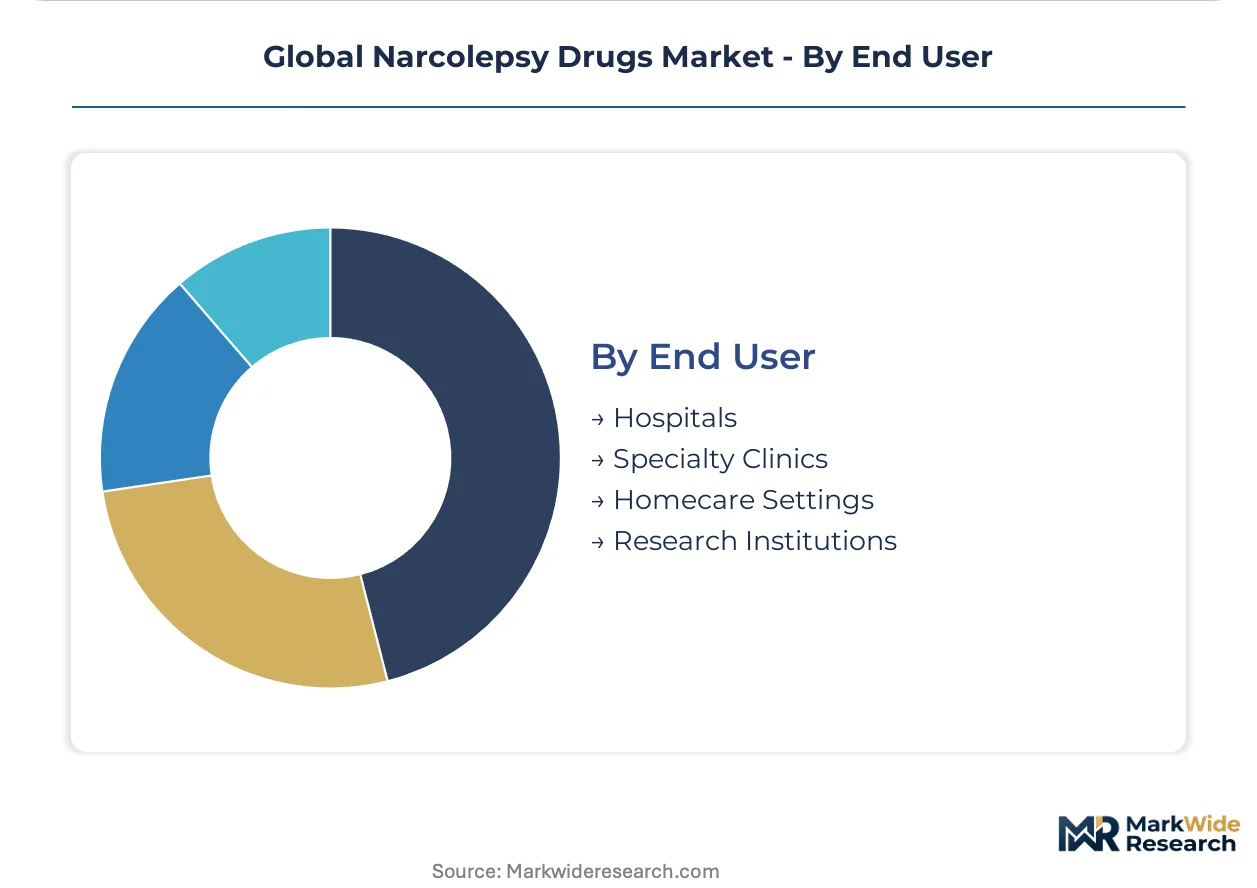
End User:
Procurement authority and reimbursement pathways diverge sharply between institutional and outpatient channels.
- Specialty Clinics:Dedicated sleep medicine centers with REMS certification and hypocretin testing capacity. U.S. integrated delivery systems in Pennsylvania and California consolidate purchasing through single-specialty pharmacy arrangements.
- Hospitals:Inpatient initiation for severe cataplexy or diagnostic workup with polysomnography. German university hospitals anchor regional referral networks.
- Homecare Settings:Long-term sodium oxybate administration with nursing support for bedtime dosing compliance.
- Research Institutions:Clinical trial sites for orexin-targeting pipeline candidates.
Mature deployment sits with hospital-based diagnosis and initiation. Newer deployment is concentrated in specialty clinic consolidation for chronic disease management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty sleep clinics concentrate diagnostic capacity in the United States, Germany, and Japan, where reimbursement frameworks and biomarker testing infrastructure sustain the highest treatment penetration rates globally.
United States
Academic medical centers in Pennsylvania and California consolidate narcolepsy protocols under single-specialty pharmacy arrangements, driving protocol-driven demand for sodium oxybate and pitolisant. The FDA's Risk Evaluation and Mitigation Strategy tightens distribution access while expanding prescriber certification mandates. Boston and New York clusters anchor the largest REMS-certified prescriber networks.
Germany
Neurological centers in Bavaria and North Rhine-Westphalia manage substantial idiopathic narcolepsy volume through protocol-driven pitolisant initiation. EMA orphan drug incentives accelerate clinical trial protocols for orexin-targeting candidates entering European development. University hospitals in Berlin and Munich anchor regional referral networks with integrated hypocretin testing capacity.
Japan
Deep ties between Takeda Pharmaceutical and Japanese neurological centers sustain concentrated demand for established therapeutic protocols. The PMDA maintains distinct pharmacovigilance requirements for central nervous system agents that influence trial design and post-market surveillance. Tokyo and Osaka metropolitan areas host the highest density of sleep medicine specialists.
United Kingdom
Specialist sleep services within the National Health Service concentrate narcolepsy diagnosis in London and regional neuroscience centers, creating pooled procurement leverage for formulary negotiations. NICE technology appraisals shape reimbursement access for novel therapeutics entering the market. The Cambridge-Oxford corridor anchors clinical research activity for orexin-targeting pipeline candidates.
Switzerland
Swissmedic's streamlined orphan drug review pathway attracts development program registrations for central nervous system therapeutics addressing unmet cataplexy control needs. Basel and Zurich clusters host contract research organizations supporting European narcolepsy trial execution. The country's precision medicine infrastructure supports biomarker-driven patient stratification for targeted therapy selection.
Global Narcolepsy Drugs Market Competitive Landscape
United States producers anchor the branded therapeutics tier; European and Japanese specialists hold differentiated positions through regional regulatory relationships and manufacturing capabilities. Market structure concentrates around sodium oxybate formulations requiring DEA-registered manufacturing capacity and cold chain distribution expertise. Three archetypes dominate: established franchise holders with REMS infrastructure, emerging biotechs with novel mechanisms, and generic manufacturers exploiting patent cliff opportunities. Competitive moves center on portfolio diversification toward non-scheduled alternatives and hub-and-spoke pharmacy network construction.
Within the established franchise tier, Jazz Pharmaceuticals plc and Takeda Pharmaceutical Company Limited exemplify geographic anchoring strategies—Dublin-headquartered Jazz leverages sodium oxybate distribution infrastructure across U.S. academic centers, while Osaka-based Takeda sustains deep integration with Japanese neurological referral networks. Harmony Biosciences occupies a position representing the emerging biotech archetype, with its pitolisant focus illustrating non-scheduled mechanism differentiation.
| Leading Market Players |
|---|
| Jazz Pharmaceuticals plc |
| Teva Pharmaceutical Industries Ltd. |
| Harmony Biosciences |
| Avadel Pharmaceuticals plc |
| Axsome Therapeutics Inc. |
| Takeda Pharmaceutical Company Limited |
| Novartis AG |
| Bioprojet Pharma |
| Ligand Pharmaceuticals Incorporated |
| Others |
Supply & Pricing Matrix
DEA-certified chemist concentrations in New Jersey and North Carolina create labor-cost differentials that widen pricing-tier spreads between branded sodium oxybate formulations and authorized generic alternatives. Cold chain logistics specialists command wage premiums that concentrate high-value manufacturing in these corridors, compressing margins for mid-tier entrants while insulating premium-tier incumbents.
Pricing Analysis
Volume concentrates in authorized generic sodium oxybate while margins persist in branded formulations with REMS infrastructure. Three-tier pricing structure across premium, standard, and economy levels differentiates by DEA certification tier and cold chain compliance grade. Pricing pressure stems from generic entry and formulary exclusion battles at integrated delivery systems. Academic medical centers exhibit lowest price sensitivity; homecare settings with nursing support requirements face highest cost scrutiny.
Supply Chain Analysis
Workforce availability for controlled-substance handling concentrates manufacturing in the United States, Ireland, and Japan where DEA-equivalent certification programs operate. Active pharmaceutical ingredient supply draws from specialized fermentation facilities in these same jurisdictions. Single-source vulnerability pervades the sodium oxybate precursor market where one FDA-registered supplier dominates. Distribution runs through hub-and-spoke pharmacy networks bypassing traditional wholesale channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The narcolepsy therapeutics market functions as a cost-of-compliance story where the FDA's Risk Evaluation and Mitigation Strategy creates a barrier-to-entry moat that rewards players with certified infrastructure investments.
For Market Incumbents: To counter authorized generic sodium oxybate erosion, deepen formulary lock-in through exclusive single-specialty pharmacy arrangements with Pennsylvania and California integrated delivery systems. Prioritize backward integration into DEA-registered API manufacturing to capture margin leakage from external precursor supply. For New Entrants and Emerging Players: Capture white-space expansion in German neurological centers across Bavaria and North Rhine-Westphalia where diagnostic capacity outpaces pitolisant detailing presence. Lead with subcutaneous delivery development programs targeting dysphagia populations underserved by oral sodium oxybate protocols. For Investors and Strategic Acquirers: The window for entry favors emerging biotechs with novel orexin-targeting mechanisms and fast-track regulatory designations. Acquisition targets should demonstrate PMDA engagement or EMA orphan drug incentives. Watch for FDA scheduling decisions on next-generation wake-promoting agents as inflection indicators for portfolio displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Investment | DEA certification creates defensible distribution control against generic erosion. |
| Subcutaneous Delivery Development | Wearable pump compatibility opens chronic administration for swallowing-impaired patients. |
| Orphan Drug Designation Pursuit | EMA and FDA fast-track pathways compress development timelines for novel mechanisms. |
| Single-Specialty Pharmacy Partnership | Exclusive arrangements with academic medical centers displace fragmented retail distribution. |
| Cold Chain Capacity Expansion | GMP-certified refrigerated storage infrastructure secures chemical stability compliance. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with FDA filings, EMA submissions, ClinicalTrials.gov entries, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation validated segment-level estimates across the projection horizon.
Granularity-level modeling operated at the intersection of product type, therapy area, delivery mode, and end-user channel dimensions. CAGRs derived from epidemiological trend analysis, pricing trajectory assumptions, and regulatory approval probability weighting. Forecast inputs incorporated hypocretin testing penetration curves and REMS prescriber certification expansion rates throughout the forecast period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA scheduling decisions, generic entry timing, and orexin-targeting pipeline advancement. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Contraceptives Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Erdosteine Market
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Oral Antiviral Market
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market
Pharmaceuticals
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Latin America Meglitinide Market