
 Testosterone Nasal Gels Market | 2026-2036
Testosterone Nasal Gels Market Size, Share, and Industry Trends Forecast 2026-2036
Testosterone Nasal Gels Market Analytics
Endocrinology specialist availability is bifurcating market access between metropolitan corridors and underserved regions. Acerus Pharmaceuticals Corporation leverages its intranasal delivery expertise to sustain a differentiated position in non-invasive testosterone administration. Endo Pharmaceuticals Inc. anchors its portfolio through established urology channel relationships, while Antares Pharma competes via self-injection platforms that overlap with patient populations considering nasal alternatives.
Testosterone nasal gels constitute metered-dose intranasal formulations designed for systemic absorption through the nasal mucosa, typically incorporating testosterone USP in a hydroalcoholic gel base with permeation enhancers to achieve therapeutic serum concentrations. The primary commercial purpose centers on restoring eugonadal testosterone levels in hypogonadal males while avoiding first-pass hepatic metabolism and injection-related complications. Testosterone gel formulations dominate current revenue contribution due to established physician familiarity and dosing precision, though intranasal delivery is gaining traction among patients seeking discretion and reduced skin transfer risk. Hormonal therapy applications anchor volume demand, while sexual dysfunction indications represent a concentrated margin pool where payers demonstrate favorable coverage.
FDA oversight through the Division of Bone, Reproductive and Urologic Products shapes labeling requirements and post-market surveillance obligations for testosterone replacement therapies. The Drug Enforcement Administration's Schedule III classification constrains distribution channels and prescribing protocols, while USP monograph standards govern assay and impurity specifications for compounded alternatives. Stakeholders must monitor evolving cardiovascular safety communications and their downstream impact on prescriber confidence and prior authorization stringency.
Market Dynamics
FDA cardiovascular safety communications have compressed prescriber confidence in testosterone replacement therapies, forcing manufacturers to intensify post-market surveillance and differentiate through delivery mechanism innovation rather than efficacy claims alone.
Growth Catalysts
- Non-invasive delivery preference:Hypogonadal patients increasingly reject intramuscular injections, driving demand for intranasal formulations that eliminate needle anxiety and tissue damage risks.
- DEA Schedule III distribution controls:Tighter federal oversight on controlled substances paradoxically advantages metered-dose nasal systems with built-in tamper resistance and precise dosing accountability.
- Metropolitan urology clinic expansion:Endocrinology and urology specialty practices concentrate in urban corridors, creating dense prescribing networks that accelerate product uptake through physician familiarity.
Market Restraints
- API supply concentration:Testosterone USP manufacturing clusters in Indian and Chinese pharmaceutical chemical hubs, exposing formulators to geopolitical friction and import inspection delays.
- Permeation enhancer technical ceiling:Nasal mucosa absorption limits cap bioavailability at approximately 10-15%, constraining dose efficiency versus subcutaneous depot formulations.
- Cardiovascular outcome study mandates:FDA post-market requirements for long-term safety data extend development timelines and inflate clinical trial budgets for new entrants.
Strategic Opportunities
- Underserved rural endocrinology access:Telemedicine-integrated nasal gel prescribing models can penetrate non-metropolitan markets where specialist density remains critically low.
- Pediatric delayed puberty applications:Off-label expansion into adolescent hypogonadism represents a concentrated prescriber segment with limited competing modalities.
- USP compounding pharmacy channel:Customized dosing formulations through 503A/503B facilities offer margin-rich alternatives to mass-manufactured commercial products.
Industry Challenges
- Formulation chemist scarcity:Nasal mucosal drug delivery expertise concentrates within a narrow pool of pharmaceutical scientists, inflating recruitment costs and R&D cycle times.
- Stability validation complexity:Hydroalcoholic gel shelf-life testing under ICH guidelines demands extended real-time and accelerated aging protocols before commercial release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testosterone Nasal Gels Market |
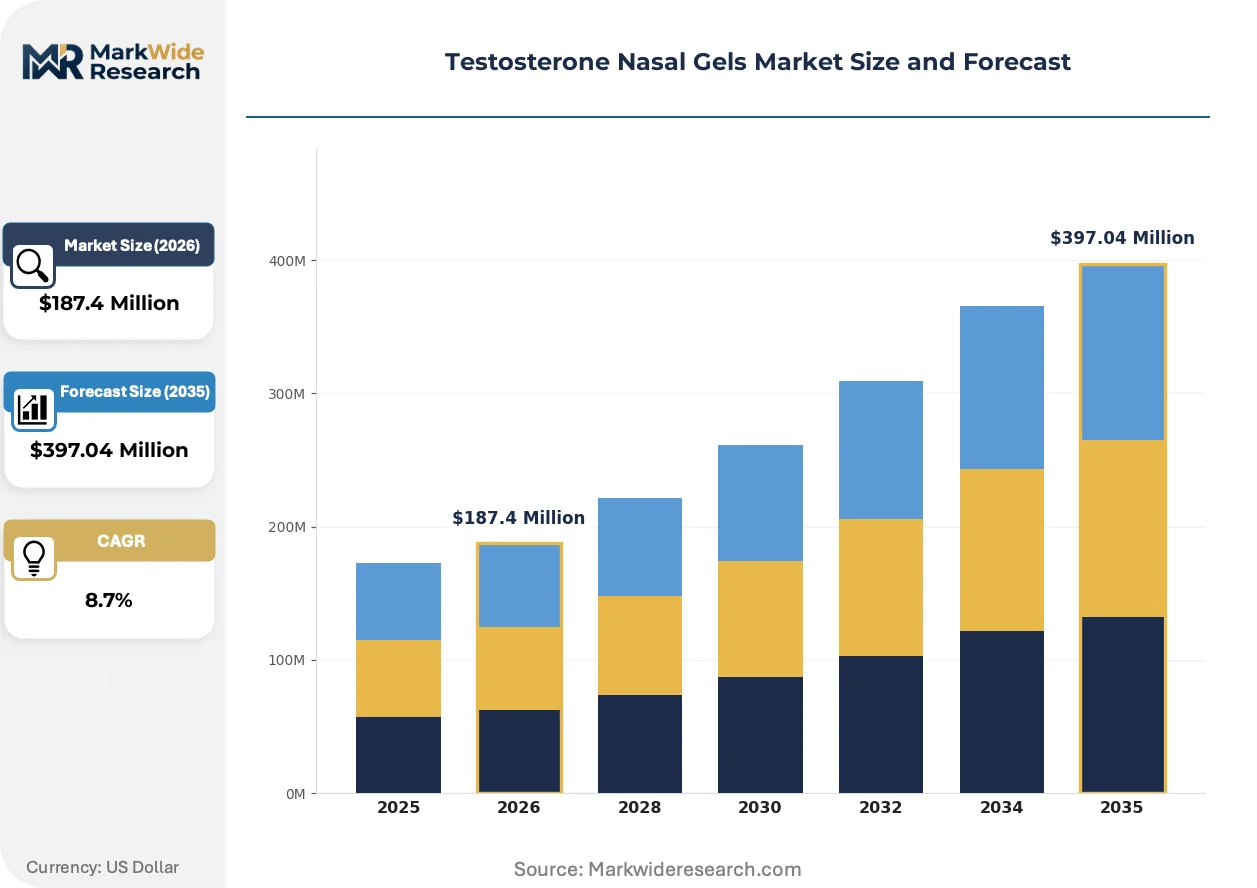
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Testosterone Gel, Testosterone Spray, Testosterone Solution, Testosterone Cream End User: Clinics, Hospitals, Homecare, Pharmacies Delivery Mode: Topical, Intranasal, Injectable, Oral Application: Hormonal Therapy, Weight Management, Muscle Recovery, Sexual Dysfunction |
| Companies Covered | Acerus Pharmaceuticals Corporation, Hyundai Pharm Co., Endo Pharmaceuticals Inc., AbbVie Inc., Bristol-Myers Squibb, Aceto Corporation, Noven Pharmaceuticals, Inc., Antares Pharma, Tolmar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testosterone Nasal Gels Market Evolving Landscape
Intranasal testosterone delivery is undergoing rapid formulation refinement as manufacturers compete to minimize skin transfer risks and optimize pharmacokinetic profiles. Three intersecting developments are compressing competitive timelines and reshaping prescriber selection criteria.
Microemulsion-based permeation systems are displacing conventional hydroalcoholic gel matrices in next-generation development pipelines. Urology-focused contract research organizations report accelerated enrollment for bioequivalence studies comparing lipid-nanoparticle carriers against standard formulations. This displacement is compressing the window for first-generation products to establish clinical evidence libraries before superior-absorption alternatives reach market.
EMA's evolving stance on transdermal hormone replacement safety is forcing European manufacturers to pre-emptively adopt cardiovascular monitoring protocols that exceed current FDA guidance. The industrial consequence manifests as harmonized clinical trial designs spanning both jurisdictions, inflating development costs but enabling simultaneous US-EU regulatory submissions. Small-cap specialty pharmaceutical firms without EU regulatory affairs infrastructure face effective exclusion from this convergence.
Direct-to-patient pharmacy fulfillment is disrupting traditional wholesale distribution through urology clinics. Patients in Texas and Florida increasingly receive metered-dose nasal systems via specialty pharmacy home delivery rather than clinic-based dispensing. This channel compression eliminates inventory carrying costs for physician practices while capturing adherence data through connected packaging technologies.
Testosterone Nasal Gels Market Segmentation
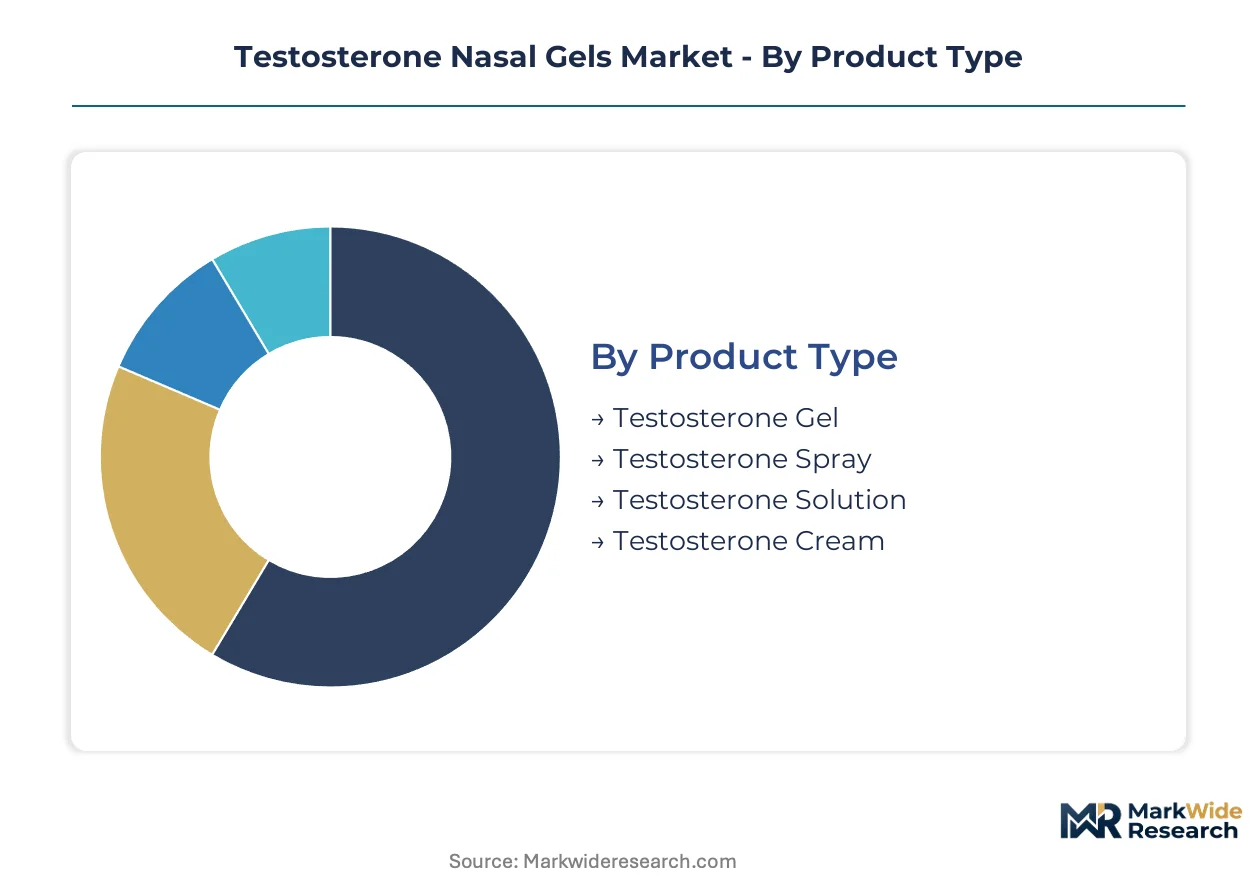
Segmentation in testosterone nasal gels reveals how formulation chemistry, delivery physics, and prescriber channel preferences fragment commercial opportunity. Each dimension carries distinct regulatory burdens and reimbursement codes that reshape competitive positioning.
Product Type:
FDA's Division of Bone, Reproductive and Urologic Products applies differentiated bioequivalence standards across these formulation classes, with hydroalcoholic gels facing the most mature—and therefore most stringent—comparative efficacy requirements.
- Testosterone Gel:Hydroalcoholic matrices incorporating permeation enhancers like oleic acid derivatives achieve 10-15% nasal bioavailability. Demand concentrates in metropolitan urology corridors where physician familiarity with metered-dose systems accelerates prescribing confidence.
- Testosterone Spray:Aqueous-based atomized formulations reduce mucosal irritation versus alcohol-heavy alternatives. Adoption climbs fastest among homecare patients prioritizing discretion and reduced skin transfer risk in shared living environments.
- Testosterone Solution:Lower viscosity liquid preparations suit patients with chronic nasal dryness or septal deviation. Compounding pharmacies in Texas and Florida drive volume through customized osmolality adjustments.
- Testosterone Cream:Oil-in-water emulsions offer extended mucosal contact time but slower absorption kinetics. Pediatric endocrinology applications favor this format for titration precision in delayed puberty protocols.
Established volume favors Testosterone Gel; emerging adoption favors Testosterone Spray.
End User:
Reimbursement density and DEA Schedule III dispensing controls concentrate margin in channel types with specialized handling infrastructure and controlled-substance licensing.
- Clinics:Urology and endocrinology specialty practices anchor prescription volume through direct patient monitoring and serum testosterone follow-up protocols. Urban corridor concentration creates network effects that accelerate new product uptake.
- Hospitals:Inpatient hypogonadism management and perioperative testosterone optimization drive formulary inclusion. Academic medical centers generate clinical evidence that shapes community prescriber behavior.
- Homecare:Direct-to-patient pharmacy fulfillment models disrupt traditional clinic dispensing in Texas and Florida. Connected packaging technologies capture adherence data that payers increasingly require for prior authorization renewal.
- Pharmacies:Retail and specialty pharmacy channels handle the majority of refill volume. 503B compounding facilities capture margin through customized dosing for patients with absorption variability.
Prescription concentration favors Clinics; channel expansion favors Homecare.
Delivery Mode:
Pharmacokinetic profiles and first-pass metabolism avoidance create sharp efficacy and tolerability distinctions that reshape patient selection criteria.
- Topical:Transdermal patches and gels dominate historical volume but carry skin transfer risk and clothing staining liabilities. Dermatology consultation requirements for irritation management add friction to long-term adherence.
- Intranasal:Direct systemic absorption bypasses hepatic first-pass metabolism with discrete administration. DEA Schedule III distribution controls advantage metered-dose systems with built-in tamper resistance and dosing accountability.
- Injectable:Subcutaneous and intramuscular depot formulations achieve superior bioavailability but trigger needle anxiety and tissue damage concerns. Antares Pharma's self-injection platforms compete for overlapping patient populations.
- Oral:Testosterone undecanoate capsules require fatty meal co-administration for lymphatic absorption. Hepatic strain and variable pharmacokinetics limit prescriber enthusiasm despite patient preference for pill formats.
Historical dominance favors Injectable; patient preference displacement favors Intranasal.
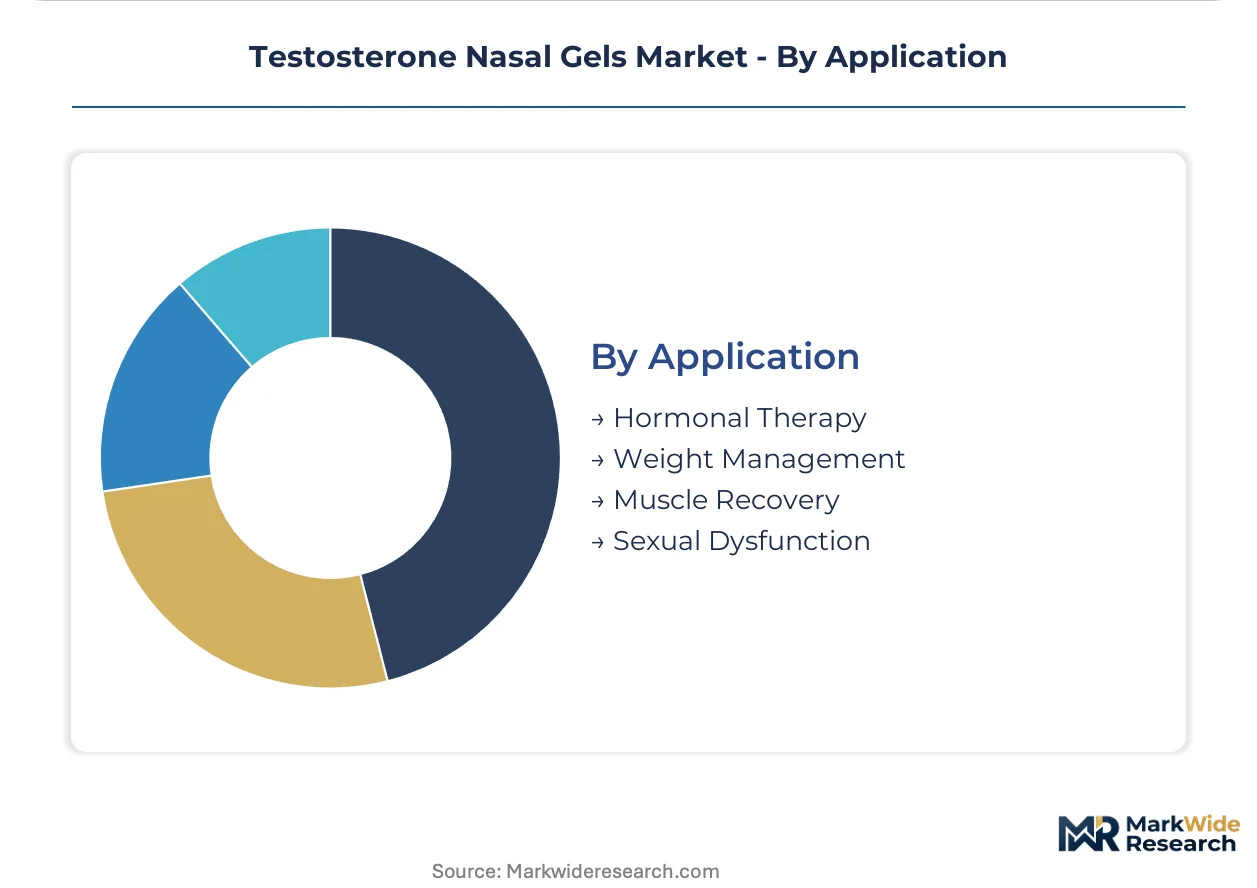
Application:
Payer coverage stringency and outcome documentation requirements fragment profitability across these clinical indications.
- Hormonal Therapy:Primary hypogonadism and androgen deficiency syndromes anchor diagnostic coding and insurance authorization pathways. Serum testosterone monitoring protocols standardize across endocrinology practices.
- Weight Management:Off-label metabolic applications in sarcopenic obesity attract cash-pay patients outside traditional reimbursement. Wellness clinic channels drive demand without prior authorization friction.
- Muscle Recovery:Post-surgical and injury rehabilitation protocols incorporate testosterone for nitrogen retention. Orthopedic and sports medicine practices generate episodic prescribing with limited long-term adherence.
- Sexual Dysfunction:Erectile dysfunction and libido restoration indications command concentrated margin where payers demonstrate favorable coverage. Urology clinic relationships prioritize this application for revenue per prescription.
Volume concentration favors Hormonal Therapy; margin density favors Sexual Dysfunction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prescription patterns diverge sharply across geographies, with the United States favoring metered-dose nasal systems while European markets retain stronger injectable traditions and Asian clinics experiment with compounded alternatives.
United States
Aging demographics and established reimbursement pathways concentrate demand in metropolitan urology corridors. The FDA's Division of Bone, Reproductive and Urologic Products enforces stringent post-market cardiovascular surveillance requirements. Texas and Florida lead direct-to-patient pharmacy fulfillment models that bypass traditional clinic dispensing.
Germany
Endocrinology specialist density in urban centers drives prescription volume for non-invasive alternatives. The EMA's evolving transdermal hormone replacement safety protocols force preemptive cardiovascular monitoring adoption. Bavaria's pharmaceutical manufacturing cluster hosts formulation development for next-generation permeation systems.
Japan
Aging male populations and cultural aversion to injectable therapies accelerate intranasal adoption. The PMDA maintains rigorous stability validation standards for hydroalcoholic gel formulations. Tokyo's academic medical centers generate clinical evidence that shapes regional prescriber behavior.
United Kingdom
Integrated care systems prioritize cost-effective hormone delivery modalities in formulary decisions. The MHRA aligns post-Brexit regulatory frameworks with EMA safety communications. London's specialist endocrinology networks concentrate prescribing authority and serum monitoring protocols.
India
Expanding private healthcare infrastructure and rising hypogonadism diagnosis rates create nascent demand. The CDSCO's evolving controlled substance classification shapes distribution channel development. Mumbai and Bangalore pharmaceutical hubs supply API and formulation expertise for regional manufacturers.
Testosterone Nasal Gels Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes through delivery mechanism differentiation rather than molecular innovation. The upper tier commands urology channel relationships and DEA Schedule III distribution infrastructure, while mid-cap players concentrate on permeation chemistry and nasal mucosal formulation expertise. Three archetypes dominate: intranasal delivery specialists, established urology portfolio anchors, and self-injection platform competitors seeking overlapping patient populations. Consolidation pressure intensifies through strategic partnerships for bioequivalence study execution and capacity expansion for metered-dose manufacturing.
Within the intranasal specialist tier, Acerus Pharmaceuticals Corporation represents concentrated expertise in non-invasive testosterone administration, while Endo Pharmaceuticals Inc. anchors established urology channel relationships. Antares Pharma occupies a competitive position through self-injection platforms that target patient populations considering nasal alternatives, illustrating how delivery mechanism diversity fragments prescribing decisions.
| Leading Market Players |
|---|
| Acerus Pharmaceuticals Corporation |
| Hyundai Pharm Co. |
| Endo Pharmaceuticals Inc. |
| AbbVie Inc. |
| Bristol-Myers Squibb |
| Aceto Corporation |
| Noven Pharmaceuticals, Inc. |
| Antares Pharma |
| Tolmar Inc. |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day API inventory buffers at Indian and Chinese testosterone USP manufacturers compress pricing leverage for North American formulators while amplifying exposure to import inspection delays. This lead-time band concentrates margin pressure on metered-dose nasal gel producers who cannot pass through excipient cost volatility without formulary exclusion risk.
Pricing Analysis
Long-term offtake agreements between urology clinic networks and specialty pharmaceutical distributors anchor pricing stability for commercial testosterone nasal gel products, while spot procurement through 503B compounding pharmacies introduces variability for customized formulations. Price differentiation separates FDA-approved metered-dose systems from compounded alternatives through bioequivalence certification and DEA Schedule III compliance infrastructure. Cost compression in the compounded tier is intensifying because API import inspection backlogs extend fulfillment timelines and force cash-flow concessions. Cash-pay wellness clinic patients demonstrate highest price sensitivity, whereas academic medical center formularies prioritize clinical evidence libraries over unit cost.
Supply Chain Analysis
Ninety-day stability validation cycles for hydroalcoholic gel formulations extend lead times before commercial release, tethering inventory planning to ICH guideline compliance sequencing. Testosterone USP manufacturing concentrates in India and China, while metered-dose device assembly clusters in Germany and the United States. Raw material dependencies include pharmaceutical-grade ethanol, oleic acid permeation enhancers, and precision nasal actuator components. Single-source vulnerability in permeation enhancer supply exposes formulators to batch failure cascades. Distribution runs through specialty pharmacy direct-to-patient fulfillment models that bypass traditional wholesale channels in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as self-injection platforms from Antares Pharma capture overlapping patient populations with superior bioavailability claims. The threat trajectory demands preemptive positioning before long-acting injectable formulations achieve cardiovascular safety data parity.
For Market Incumbents: Compound clinical evidence libraries around mucosal absorption pharmacokinetics to differentiate against subcutaneous depot alternatives. Deepen backward integration into permeation enhancer supply through captive relationships with Indian pharmaceutical chemical manufacturers. Prioritize DEA Schedule III distribution infrastructure investments that create dispensing control advantages over emerging competitors lacking controlled-substance licensing depth.
For New Entrants and Emerging Players: Differentiate on telemedicine-integrated prescribing models that penetrate rural endocrinology deserts where specialist density remains critically low. Target adolescent delayed puberty applications where titration precision requirements favor oil-in-water emulsion formats and prescriber concentration limits competitive density. Pursue 503B compounding pharmacy partnerships as the most penetrable channel for customized dosing formulations with reduced FDA bioequivalence study burdens.
For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents seeking to divest non-core urology assets amid portfolio rationalization pressures. Five-to-ten-year viability hinges on delivery mechanism innovation rather than molecular patent protection, favoring intranasal formulation expertise over generic testosterone asset accumulation. Monitor FDA cardiovascular safety communication frequency as the critical inflection indicator for prescriber confidence trajectories and prior authorization stringency.
| Strategic Initiative | Industry Significance |
|---|---|
| Microemulsion Permeation System Development | Lipid-nanoparticle carriers achieve superior absorption kinetics versus hydroalcoholic gel matrices. |
| DEA Schedule III Distribution Infrastructure Expansion | Controlled-substance licensing creates dispensing accountability advantages for metered-dose nasal systems. |
| Telemedicine-Integrated Prescribing Model Deployment | Virtual endocrinology consultations penetrate non-metropolitan markets with limited specialist density. |
| 503B Compounding Pharmacy Channel Partnership | Customized dosing formulations capture margin-rich segments outside commercial product constraints. |
| Cardiovascular Outcome Study Execution | Long-term safety data libraries satisfy FDA post-market surveillance and defend against injectable substitution. |
Research Methodology
Operator-level perspectives from urology clinic administrators, endocrinology practice managers, specialty pharmacy procurement directors, and DEA-licensed wholesale distributors anchored the qualitative base. These primary engagements combined with secondary validation through FDA Division of Bone, Reproductive and Urologic Products filings, EMA transdermal hormone replacement safety communications, ClinicalTrials.gov enrollment data, and USP monograph standards. Bottom-up prescription volume modeling and top-down therapeutic category sizing provided triangulation across independent analytical paths.
Sensitivity analysis around API import inspection delay scenarios and cardiovascular safety communication frequency shaped probabilistic forecast bands across the projection horizon. Segmentation dimensions modeled include formulation chemistry class, delivery mode, end-user channel type, and regional regulatory cluster. CAGRs derived from patent expiry timelines, prescriber adoption curve slopes, and reimbursement pathway maturation. Forecast inputs incorporated DEA Schedule III distribution control evolution and telemedicine regulatory accommodation trajectories.
The analysis sits within stated boundaries; outcomes outside sustained FDA post-market surveillance requirements or major API supply disruption would require recalibration. Forecasts reflect documented assumptions regarding prescriber confidence stability and payer prior authorization stringency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Global Lifestyle Drugs Market
Pharmaceuticals
Listeria Monocytogenes Treatment Market
Pharmaceuticals
Erdosteine Market
Pharmaceuticals
Flunarizine Hydrochloride Market
Pharmaceuticals
Global Shingles Vaccine Market