
 Tuberculosis Therapeutics Market | 2026-2036
Tuberculosis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Tuberculosis Therapeutics Market Analytics
Public health procurement is rotating toward direct government tenders as the dominant buyer archetype in tuberculosis therapeutics. Johnson & Johnson sustains technology leadership in bedaquiline-based regimens for multidrug-resistant strains. Sanofi leverages its manufacturing scale to anchor supply security for first-line combination therapies across endemic regions. Lupin competes aggressively on cost-engineered oral generics, while Novartis specializes in niche injectable formulations for extensively drug-resistant cases.
Tuberculosis therapeutics comprise pharmaceutical agents designed to eliminate Mycobacterium tuberculosis infection through bactericidal or bacteriostatic action, typically administered as multi-drug regimens spanning six to twenty-four months depending on resistance profile. These formulations serve the primary purpose of curing active disease, preventing latent infection progression, and interrupting transmission in high-burden populations. First-line drugs occupy the largest volume share due to standardized global procurement for drug-sensitive cases, while combination therapy represents the fastest-expanding segment as fixed-dose formulations simplify adherence and reduce resistance emergence. Injectable delivery modes retain importance for drug-resistant protocols despite growing preference for oral alternatives that enable outpatient management.
FDA, WHO prequalification standards, and national regulatory authorities in India and South Africa govern product registration, bioequivalence requirements, and procurement eligibility for tuberculosis medicines. These frameworks shape demand by restricting market access to quality-assured manufacturers and mandating stability data for tropical storage conditions. Stakeholders must monitor evolving EMA and FDA guidance on novel regimen approvals while calibrating manufacturing investments against shifting procurement criteria from the Global Drug Facility and bilateral health programs.
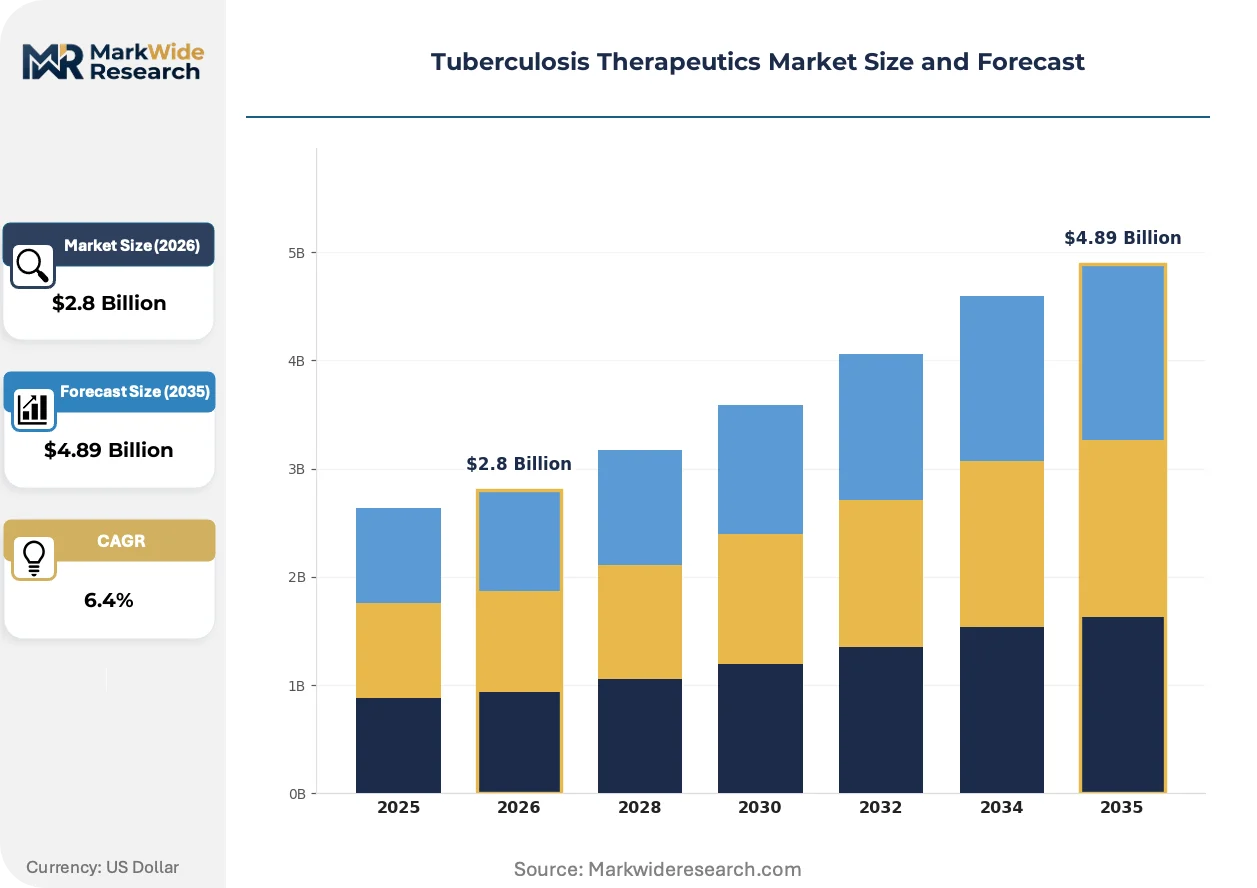
Market Dynamics
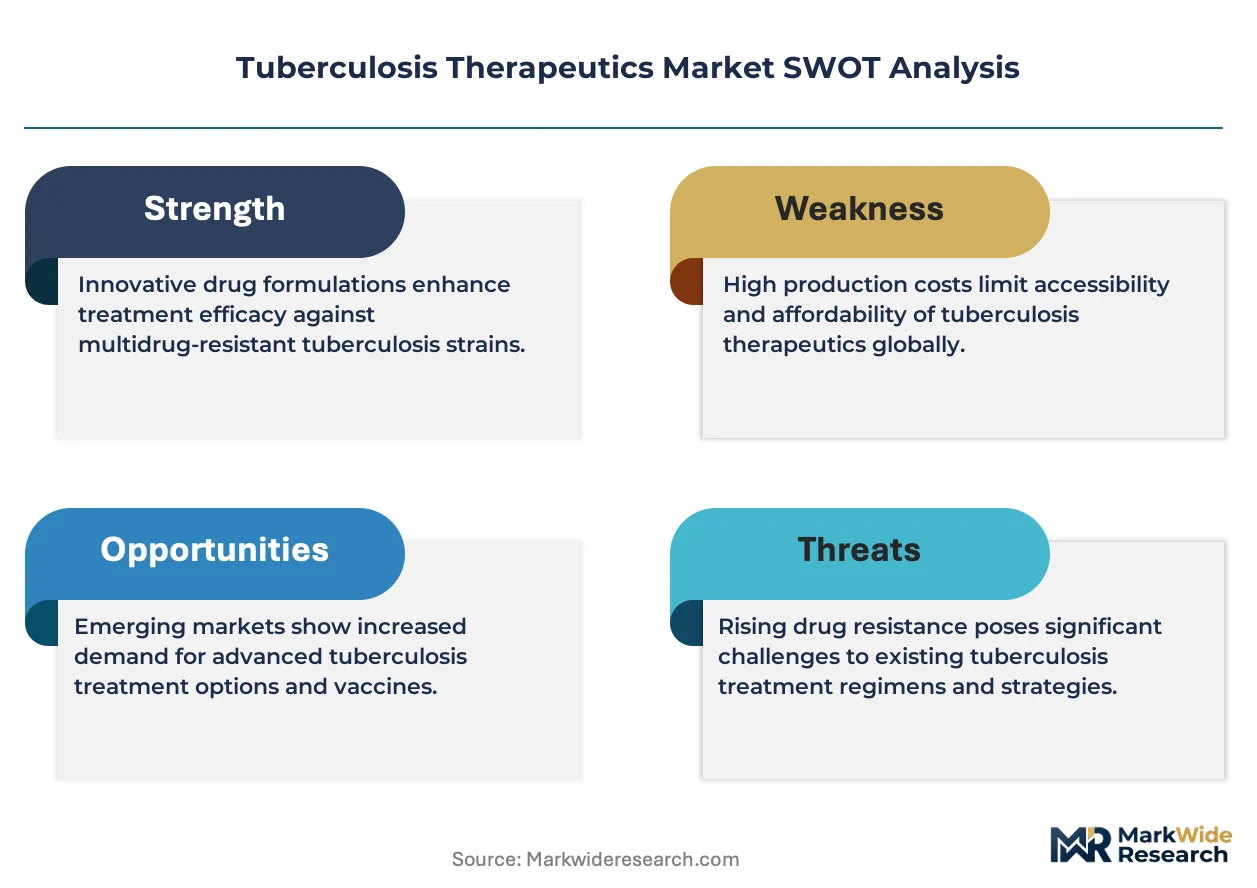
Government procurement concentration is restructuring tuberculosis therapeutics into direct-tender markets where WHO prequalification functions as the primary market access gate, compressing margins for non-prequalified manufacturers while securing volume pipelines for approved suppliers.
Growth Catalysts
- India's National TB Elimination Program:Volume procurement targets for 2025 are accelerating demand for first-line combination therapies across public health facilities.
- WHO Prequalification Pathway:Streamlined assessment protocols for fixed-dose formulations are expanding supplier eligibility for Global Drug Facility tenders.
- Injectable-to-oral transition:Novel bedaquiline and delamanid tablet formulations are enabling outpatient management of multidrug-resistant cases.
Market Restraints
- Active pharmaceutical ingredient concentration:China and India supply over 80 percent of TB drug raw materials, creating single-source vulnerability for pyrazinamide and ethambutol precursors.
- Cold chain requirements for biologics:Mycobacterium tuberculosis vaccine candidates require 2-8°C storage infrastructure absent in last-mile distribution networks across sub-Saharan Africa.
- Lengthy bioequivalence protocols:CDSCO mandates 36-month stability data for tropical climate zones, extending registration timelines for generic rifampicin formulations.
Strategic Opportunities
- Sub-Saharan Africa latent TB prophylaxis:Isoniazid preventive therapy expansion for HIV-positive populations represents underpenetrated demand in Nigeria and Kenya.
- Digital adherence technologies:Smartphone-enabled medication monitors are creating reimbursement pathways for tech-integrated regimens in South African national programs.
- EMA's PRIME designation:Accelerated assessment for novel regimen combinations is compressing development timelines for shorter-course therapies.
Industry Challenges
- Specialized formulation expertise:Fixed-dose combination manufacturing requires simultaneous dissolution profiling for four active ingredients, constraining supplier base to established multi-drug facilities.
- Good Manufacturing Practice remediation costs:WHO prequalification inspections frequently identify deficiencies in pharmaceutical quality systems, requiring capital-intensive facility upgrades for African and Asian manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tuberculosis Therapeutics Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: First-Line Drugs, Second-Line Drugs, Combination Therapy, Vaccine End User: Hospitals, Clinics, Research Institutions, Homecare Delivery Mode: Oral, Injectable, Inhalational, Intravenous Therapy Area: Latent TB Infection, Drug-Sensitive TB, Drug-Resistant TB, Tuberculosis Prophylaxis |
| Companies Covered | Sanofi, Eli Lilly and Company, Johnson & Johnson, Otsuka Pharmaceutical, Lupin, AstraZeneca, Novartis, Merck & Co., Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tuberculosis Therapeutics Market Evolving Landscape
Oral drug development is displacing injectable protocols across drug-resistant tuberculosis treatment, while regulatory convergence on quality-assured procurement standards is consolidating supplier bases toward prequalified manufacturers.
Fixed-dose combination formulations is bifurcating tuberculosis therapeutics into streamlined six-month regimens for drug-sensitive cases versus complex 18-24 month protocols for resistant strains. National programs in India and South Africa are adopting four-drug single-pill combinations to simplify adherence monitoring. This technology is bifurcating procurement volumes toward high-volume standardized regimens while compressing demand for individualized second-line cocktails.
EMA's conditional marketing authorization pathway for antimicrobials is accelerating review timelines for novel tuberculosis drugs addressing unmet resistance profiles. The framework permits approval based on Phase IIb efficacy data with post-market confirmatory trials. Extensively drug-resistant tuberculosis therapies and shorter-course regimens are most affected, with developers prioritizing European registration to anchor global pricing benchmarks.
Direct government tendering is consolidating tuberculosis medicine procurement away from intermediary distributors toward national central medical stores. The Global Drug Facility's pooled purchasing mechanism is displacing bilateral agreements in 25 high-burden countries. This concentration is most visible in India's state-level tender consolidation, where Karnataka and Maharashtra have shifted to centralized rate-contract frameworks eliminating district-level supplier fragmentation.
Tuberculosis Therapeutics Market Segmentation
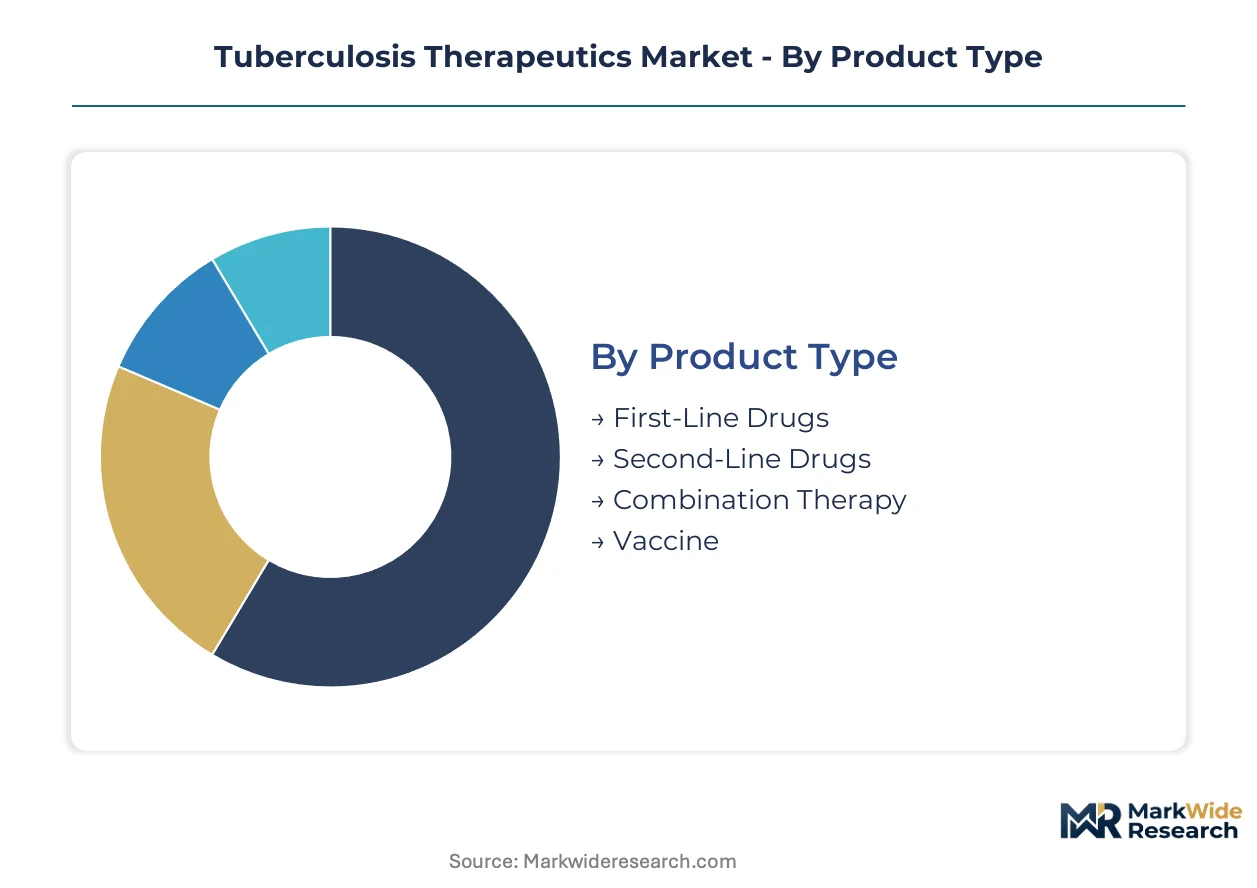
Tuberculosis therapeutics segmentation reflects divergent procurement patterns across public health systems. Product type and delivery mode categories map directly to India's domestic volume concentration versus export-oriented specialty manufacturing. End user and therapy area splits reveal where outpatient transition is reshaping channel economics.
Product Type:
Domestic procurement in India and South Africa concentrates on standardized regimens, while export demand flows toward complex multidrug-resistant formulations requiring specialized manufacturing.
- First-Line Drugs:Rifampicin, isoniazid, pyrazinamide, and ethambutol constitute the WHO-recommended four-drug backbone for drug-sensitive cases. Indian state medical services departments procure these as bulk single-ingredient tablets for in-house compounding into patient kits.
- Second-Line Drugs:Fluoroquinolones, injectable aminoglycosides, and cycloserine derivatives target multidrug-resistant strains with extended treatment durations. Export demand from South Africa's centralized tender system drives volume for prequalified manufacturers.
- Combination Therapy:Fixed-dose formulations compress multiple actives into single tablets to simplify adherence and reduce resistance emergence.
- Vaccine:Bacillus Calmette-Guérin products for neonatal immunization and investigatory candidates for latent infection prevention.
First-Line Drugs holds the largest share; momentum sits with Combination Therapy.
End User:
Cost-tier stratification separates centralized hospital procurement from decentralized clinic dispensing, with homecare representing the emerging reimbursement frontier.
- Hospitals:Tertiary referral centers manage drug-resistant cases requiring inpatient observation for injectable protocols and adverse event monitoring. India's district hospital networks anchor public sector volume.
- Clinics:Primary health centers and urban DOTS facilities administer directly observed therapy for standard six-month regimens. South Africa's clinic-based HIV-TB integration programs drive demand for co-formulated preventive therapy.
- Research Institutions:Clinical trial sites and national reference laboratories evaluate novel regimen efficacy.
- Homecare:Outpatient oral regimens enable patient-managed treatment with digital adherence support.
Hospitals dominate value capture; clinics represent the steepest expansion trajectory as oral therapies enable decentralization.
Delivery Mode:
Volume concentration favors oral solid dosage forms manufactured at scale, while margin accrues to complex parenteral formulations requiring aseptic fill-finish capabilities.
- Oral:Tablets and capsules enable self-administered therapy with simplified cold chain requirements. Novel bedaquiline and delamanid tablet formulations are displacing injectable protocols for multidrug-resistant cases.
- Injectable:Intramuscular aminoglycosides and capreomycin retain importance for extensively drug-resistant tuberculosis requiring therapeutic drug monitoring. Manufacturing concentrates at WHO-prequalified facilities with dedicated antibiotic production lines.
- Inhalational:Dry powder and nebulized formulations for localized drug delivery to pulmonary lesions.
- Intravenous:Hospital-administered formulations for severe disseminated disease or malabsorption states.
Oral commands procurement volume; Injectable retains pricing power in resistant-strain protocols.
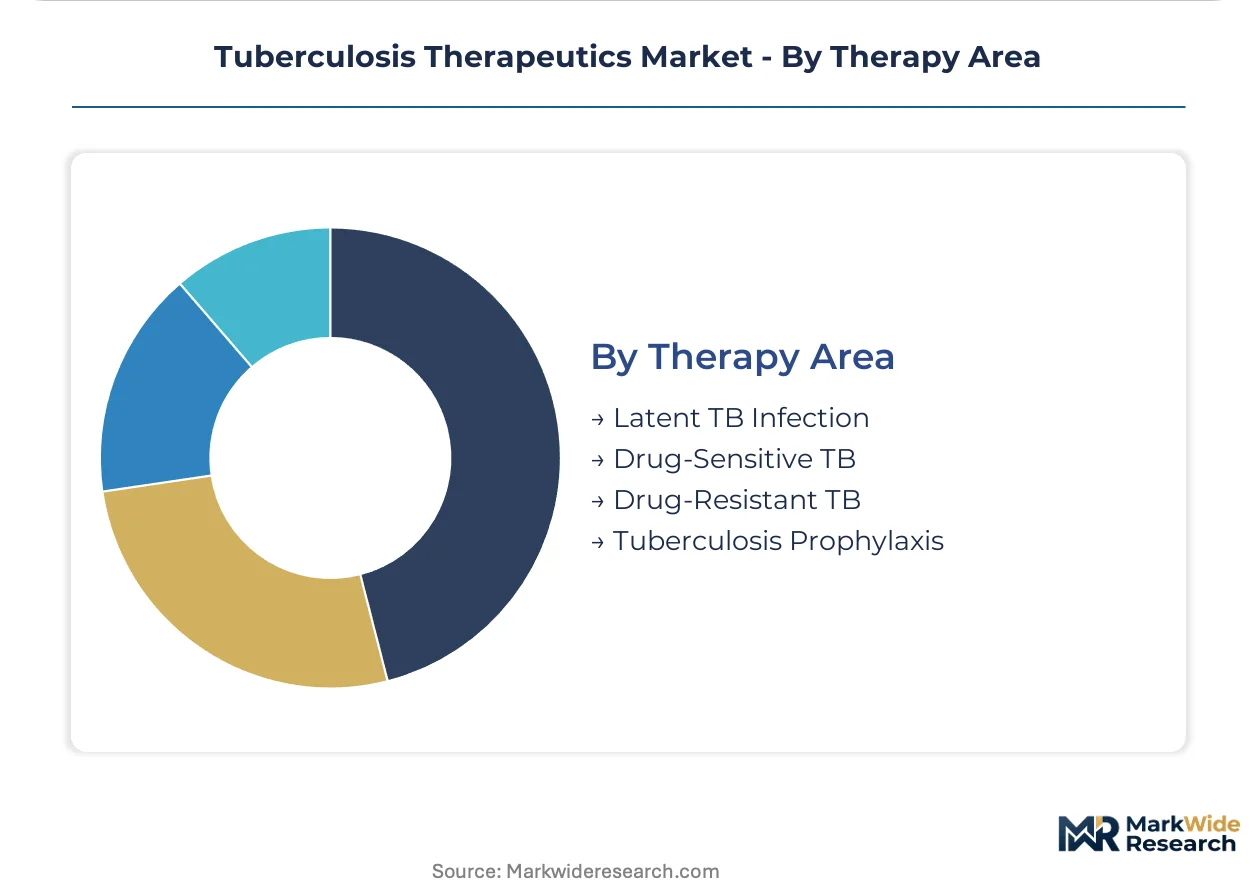
Therapy Area:
Application maturity separates established drug-sensitive treatment protocols from emerging preventive therapy segments targeting HIV-coinfected populations.
- Latent TB Infection:Isoniazid preventive therapy and shorter rifamycin-based regimens target high-risk populations before progression to active disease. Kenya's national program expansion for HIV-positive patients drives demand growth.
- Drug-Sensitive TB:Standard six-month rifampicin-containing regimens represent the procurement baseline across all high-burden national programs.
- Drug-Resistant TB:Individualized 18-24 month protocols combining second-line drugs, novel agents, and surgical intervention for extensively resistant strains.
- Tuberculosis Prophylaxis:Pre-exposure approaches for healthcare workers and household contacts in high-transmission settings.
Drug-Sensitive TB anchors procurement volume; Latent TB Infection is climbing the fastest as prevention frameworks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Mumbai anchors pharmaceutical export flows for tuberculosis therapeutics across the Indian Ocean rim, while the Trans-African Highway network enables last-mile distribution into East African high-burden zones.
India
Domestic volume procurement through the National TB Elimination Program and state-level rate contracts drives demand for rifampicin and isoniazid formulations. CDSCO mandates 36-month tropical stability data for generic registration, extending timelines for new market entrants. Manufacturing clusters in Hyderabad and Ahmedabad concentrate fixed-dose combination production for domestic kits and Global Drug Facility exports.
South Africa
Centralized tendering through the National Department of Health and HIV-TB integration programs sustains demand for second-line drugs and preventive therapy. The South African Health Products Regulatory Authority enforces WHO prequalification alignment for public sector eligibility. Industrial activity clusters in Gauteng province, where Pretoria-based facilities coordinate regional distribution into neighboring Lesotho and Eswatini.
Brazil
Federal procurement through the Ministry of Health and state-level tuberculosis control programs generates demand for first-line combination therapies. ANVISA harmonizes bioequivalence requirements with WHO standards for prequalification pathway access. São Paulo's pharmaceutical corridor houses formulation facilities serving the Mercosur regional market.
United States
FDA breakthrough therapy designation for novel bedaquiline regimens and NIH-funded research infrastructure supports clinical development for drug-resistant protocols. The President's Emergency Plan for AIDS Relief channels procurement into high-burden partner countries. Boston-Cambridge and Research Triangle Park clusters concentrate Phase IIb trial sites for shorter-course therapy candidates.
Kenya
Isoniazid preventive therapy expansion for HIV-positive populations and donor-funded procurement through the Global Fund drive latent TB infection segment growth. The Pharmacy and Poisons Board adopts WHO prequalification lists for public sector tender eligibility. Nairobi's industrial zone hosts regional packaging and distribution hubs for East African Community markets.
Tuberculosis Therapeutics Market Competitive Landscape
Concentration sits with vertically integrated pharmaceutical conglomerates possessing WHO-prequalified manufacturing facilities and established government tender relationships. The supplier base stratifies across three tiers: multinational innovators with novel drug portfolios, large-scale generic manufacturers with cost-engineered formulations, and regional specialists in niche injectable or fixed-dose combinations. Competitive dynamics revolve around prequalification maintenance costs and capacity expansion into high-burden African and Asian markets.
Among the established innovators, Johnson & Johnson and Sanofi occupy positions representing technology leadership in novel regimens and manufacturing scale for standardized therapies respectively. Novartis sits within the specialty tier, anchoring complex formulation capabilities for extensively drug-resistant cases. These three entities exemplify the archetype segmentation shaping procurement eligibility and pricing power across direct government tenders.
| Leading Market Players |
|---|
| Sanofi |
| Eli Lilly and Company |
| Johnson & Johnson |
| Otsuka Pharmaceutical |
| Lupin |
| AstraZeneca |
| Novartis |
| Merck & Co. |
| Pfizer |
| Others |
Value Network & Pricing Analysis
Fixed-dose combination manufacturing at scale in Hyderabad and Ahmedabad creates steep entry barriers that compress price floors for non-prequalified suppliers while securing premium positioning for WHO-approved facilities serving Global Drug Facility tenders.
Pricing Analysis
Volume-discount tiering structures separate procurement into three levels: premium WHO-prequalified suppliers command rate-contract premiums from national central medical stores, mid-tier domestic manufacturers compete on state-level tenders with partial prequalification, and economy-tier regional compounders serve district-level kits with minimal quality assurance. Price differentiation hinges on WHO prequalification status and tropical stability certification from CDSCO, with the latter adding 18-24 months to registration timelines. Cost compression in the economy tier is intensifying as India's state governments consolidate rate contracts and eliminate district-level fragmentation. National central medical stores exhibit lowest price sensitivity due to total-cost-of-ownership frameworks that weight adherence outcomes against unit cost, while district-level procurement shows highest sensitivity to per-dose pricing.
Supply Chain Analysis
Jawaharlal Nehru Port Trust transit underwrites API import flows for pyrazinamide and ethambutol precursors that feed formulation clusters in Gujarat and Telangana. Active pharmaceutical ingredient supply draws from China and India for over 80 percent of TB drug raw materials, creating single-source vulnerability for rifampicin intermediates. Distribution runs through the Global Drug Facility's pooled purchasing mechanism displacing bilateral agreements across 25 high-burden countries, with last-mile delivery depending on cold chain infrastructure absent in sub-Saharan Africa's clinic networks. Tariff exposure on Chinese API imports represents the dominant structural risk as procurement concentrates toward direct government tendering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oral bedaquiline and delamanid tablet formulations are compressing multidrug-resistant treatment durations from 18-24 months to 9-12 months, disrupting procurement patterns and creating first-mover advantages for developers with EMA conditional marketing authorization.
For Market Incumbents: Consolidate manufacturing scale advantages by expanding WHO-prequalified capacity in Hyderabad and Ahmedabad to capture volume from India's state-level tender consolidation. Anchor backward integration into pyrazinamide and ethambutol API production to mitigate single-source exposure from Chinese suppliers. Secure rate-contract renewals with the Global Drug Facility before novel oral regimens displace injectable protocols entirely. For New Entrants and Emerging Players: Anchor in Kenya's isoniazid preventive therapy expansion for HIV-positive populations, where donor-funded procurement through the Global Fund creates accessible volume without prequalification barriers. Target Nigeria's latent TB infection segment with digital adherence technologies bundled into patient support programs, leveraging smartphone penetration rates that enable reimbursement pathways in South African national programs as a reference model. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among WHO-prequalified manufacturers with locked rate contracts across multiple national central medical stores, offering visibility through procurement cycles that outlast patent cliffs on novel agents. Acquisition targets should display established government tender relationships in India and South Africa alongside fixed-dose combination formulation expertise. Watch EMA PRIME designation announcements for novel regimen combinations as the signal indicating which developers will anchor global pricing benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Streamlined assessment protocols expand supplier eligibility for Global Drug Facility tenders across endemic regions. |
| Fixed-Dose Combination Manufacturing Scale-Up | Simultaneous dissolution profiling for four actives constrains supply base to established multi-drug facilities. |
| EMA Conditional Marketing Authorization | Accelerated review timelines compress development cycles for shorter-course drug-resistant TB therapies. |
| Digital Adherence Technology Integration | Smartphone-enabled medication monitors create reimbursement pathways in South African national programs. |
| API Backward Integration | In-house production of pyrazinamide and ethambutol precursors mitigates single-source vulnerability from Chinese suppliers. |
Research Methodology
Operator-level perspectives from regulatory affairs leads at WHO-prequalified manufacturers, formulary directors at India's National TB Elimination Program, hospital procurement managers in South African district networks, and payer access specialists at the Global Drug Facility anchored the qualitative base. These primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and CDSCO registration databases. Bottom-up and top-down triangulation cross-checked manufacturer capacity data against national procurement volumes reported through the Global Drug Facility.
Sensitivity analysis tested forecast robustness across alternative scenarios for WHO prequalification timeline acceleration and oral-to-injectable transition velocity. The analytical framework modeled segmentation across treatment line, dosage form, administration route, and regional regulatory cluster throughout the forecast period. CAGRs derived from regression analysis of historical procurement volumes against national elimination program targets and novel regimen adoption curves. Industry-specific inputs included CDSCO stability data requirements and EMA PRIME designation pipeline tracking.
Material uncertainties — API supply disruptions from Chinese manufacturing consolidation, cold chain infrastructure gaps in sub-Saharan Africa, and regulatory divergence on bioequivalence protocols — sit outside the modeled envelope. Forecasts reflect assumptions about continued Global Drug Facility funding levels and WHO prequalification pathway accessibility. Practitioners should keep alternative scenarios live as EMA conditional marketing authorization precedents and India's state-level tender consolidation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Global Heparin Sodium Market
Pharmaceuticals
Global Female Contraceptive Market
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
Drug Allergy Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Energy-Based Therapeutics Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Obsessive Compulsive Disorder (OCD) Drug Market
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
Europe Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market
Pharmaceuticals
Short-Acting Insulin Market