
 Sarcoidosis Drugs Market | 2026-2036
Sarcoidosis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Sarcoidosis Drugs Market Analysis
Maintenance therapy subscription programs for chronic sarcoidosis management is expanding how pharmaceutical firms monetize patient relationships beyond acute prescriptions. Pfizer leverages its respiratory and immunology infrastructure to sustain broad prescriber access across pulmonology networks. Novartis anchors its position through deep specialization in interstitial lung disease adjacent indications, competing on clinical data depth rather than volume. AbbVie differentiates via rheumatology cross-selling capabilities that extend its immunology franchise into granulomatous disease protocols.
Sarcoidosis drugs comprise pharmaceutical agents targeting granulomatous inflammation, principally corticosteroids for acute suppression, immunosuppressants for steroid-sparing maintenance, and biologics refractory to first-line intervention. These formulations modulate T-cell and macrophage signaling cascades to halt fibrotic progression in lungs, skin, cardiac, and neurologic tissues. Corticosteroids and immunosuppressants still occupy the majority of prescription volume, though biologics command disproportionate margin pools as relapse treatment and chronic phase protocols shift toward targeted cytokine inhibition. Injectable and intravenous administration routes concentrate value in hospital and clinic settings, while oral maintenance regimens sustain homecare volume.
The FDA orphan drug program and EMA's parallel designation framework shape trial design incentives and exclusivity timelines for sarcoidosis developers. Health Canada and the FDA both enforce Good Manufacturing Practice standards that dictate biologic production facility investment thresholds, filtering market access to capitalized manufacturers. Stakeholders must monitor how payer consolidation in the United States and reference pricing mechanics in Europe reshape reimbursement for biologic maintenance therapy against generic immunosuppressant alternatives.
Market Dynamics
The FDA's orphan drug designation incentives and breakthrough therapy pathways are accelerating clinical trial investment while reshaping how pharmaceutical firms allocate R&D capital toward rare inflammatory indications.
Growth Catalysts
- EMA Parallel Designation Framework:Developers gain harmonized exclusivity timelines across transatlantic markets, reducing regulatory duplication costs for biologic candidates targeting refractory sarcoidosis populations.
- Hospital Infusion Center Expansion:Pulmonology and rheumatology departments are building dedicated biologic administration capacity, creating physical infrastructure for maintenance therapy subscription models.
- T-Cell Signaling Modulation:Next-generation cytokine inhibitors demonstrate steroid-sparing efficacy in Phase II protocols, pulling prescribing protocols toward targeted immunology.
Market Restraints
- Biologic Production Facility Capital Thresholds:Good Manufacturing Practice compliance for injectable formulations requires facility investments that filter market access to capitalized manufacturers.
- Reference Pricing Mechanics:European reimbursement systems compress biologic maintenance therapy margins against generic immunosuppressant alternatives.
- Steroid-Sparing Protocol Adoption Lag:First-line corticosteroid prescribing patterns in community pulmonology resist rapid displacement despite biologic efficacy data.
Strategic Opportunities
- Cardiac and Neurologic Sarcoidosis Indications:Underpenetrated organ-specific protocols offer expansion vectors beyond pulmonary-first development programs.
- Homecare Oral Maintenance Regimens:Distribution innovation toward specialty pharmacy channels captures patient relationships outside hospital infusion dependency.
- Health Technology Assessment Integration:Payers in Germany and France increasingly require real-world evidence generation, creating first-mover advantage for firms with established patient registries.
Industry Challenges
- Specialist Referral Network Complexity:Sarcoidosis diagnosis requires coordination between pulmonology, rheumatology, and organ-specific consultants, fragmenting prescribing influence.
- Biologic Cold Chain Integrity:Injectable maintenance therapies require temperature-controlled logistics that strain distribution infrastructure in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sarcoidosis Drugs Market |
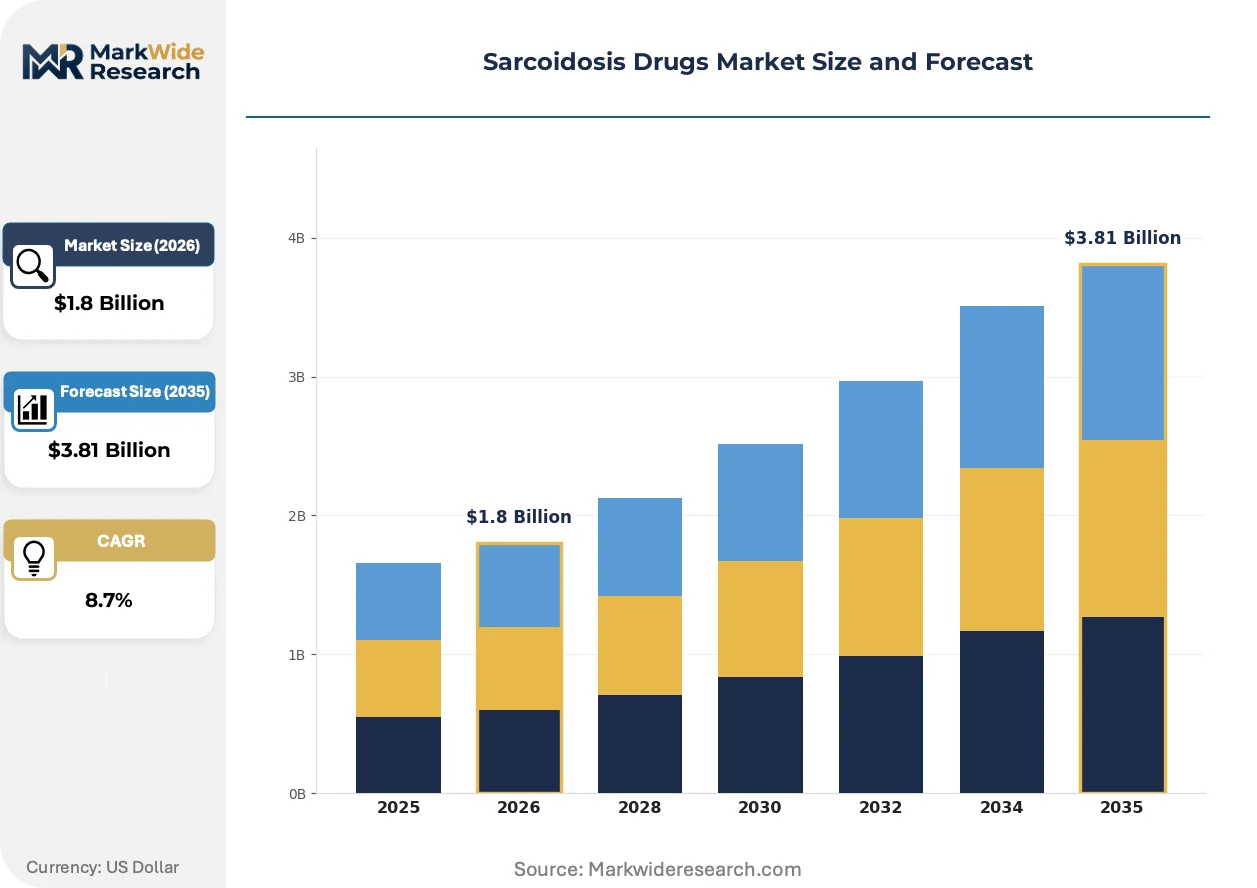
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Biologics, Antimalarials Administration Route: Oral, Injectable, Intravenous, Inhalation End User: Hospitals, Clinics, Homecare, Research Institutions Treatment Stage: Acute Phase, Chronic Phase, Maintenance Therapy, Relapse Treatment |
| Companies Covered | aTyr Pharma, Kinevant Sciences, Pfizer, AbbVie, Kyorin Pharmaceutical, Novartis, Xentria, Relief Therapeutics, United Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sarcoidosis Drugs Market Emerging Trajectories
Granulomatous inflammation research is crossing into adjacent interstitial lung disease protocols, blurring traditional indication boundaries and reshaping clinical trial design strategies across immunology portfolios.
Janus kinase inhibition is converging with interleukin-6 pathway blockade in next-generation sarcoidosis protocols. Academic medical centers in the United States and Germany are piloting combination biologic regimens for refractory cases. This convergence is compressing development timelines as sponsors leverage mechanistic overlap with approved rheumatoid arthritis and lupus indications.
REACH registration requirements for novel immunosuppressant substances are tightening environmental exposure documentation for manufacturing facilities. EMA's expanded pharmacovigilance mandates now require post-market fibrosis progression tracking. European biologic sponsors are responding by embedding digital biomarker collection into Phase IV commitment protocols.
Commercial payer coverage decisions in the United States are tightening prior authorization requirements for biologic step-therapy protocols. Hospital systems are consolidating formulary control through centralized pharmacy and therapeutics committees, displacing individual prescriber discretion. This concentration is most visible in the Northeast and Midwest, where integrated delivery networks command dominant market share.
Sarcoidosis Drugs Market Segmentation
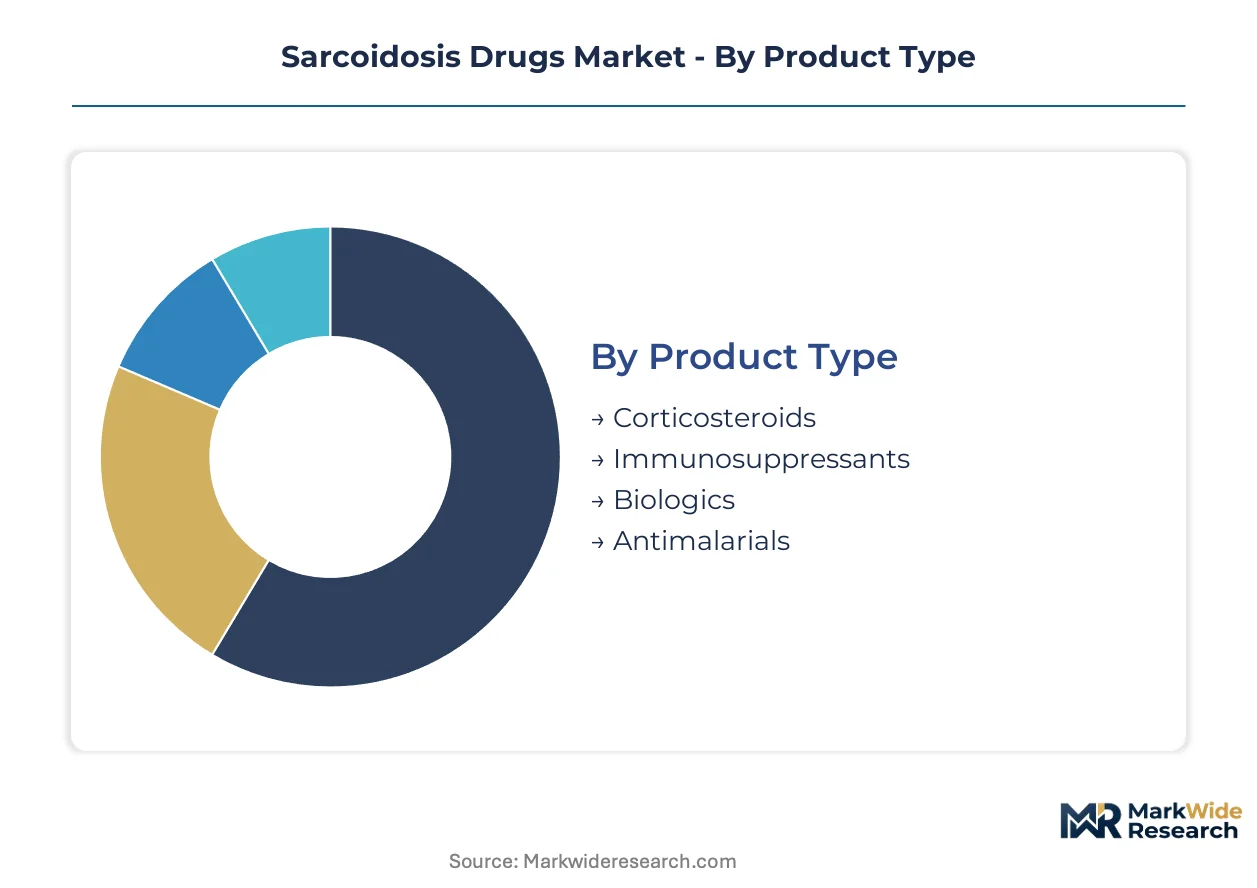
Sarcoidosis drug segmentation reveals how regulatory pathways and clinical settings fragment commercial opportunity across formulation types and care delivery models. Each dimension carries distinct certification burdens and margin structures that reshape competitive positioning.
Product Type:
EMA orphan designation and FDA breakthrough therapy pathways impose divergent approval timelines across these therapeutic classes, with biologics facing the steepest manufacturing compliance thresholds.
- Corticosteroids:First-line acute suppression agents including prednisone and methylprednisolone modulate broad anti-inflammatory cascades. Prescription volume concentrates in United States community pulmonology practices where generic pricing dominates maintenance protocols, though steroid-sparing pressure from payers is compressing long-term utilization.
- Biologics:Targeted cytokine inhibitors such as tumor necrosis factor antagonists and emerging interleukin pathway blockers interrupt granulomatous signaling. Hospital infusion centers in Germany and France are expanding administration capacity for refractory cases, with real-world evidence requirements from Health Technology Assessment bodies shaping post-market commitment structures.
- Immunosuppressants:Steroid-sparing agents including methotrexate and azathioprine bridge acute and chronic management.
- Antimalarials:Hydroxychloroquine addresses cutaneous and articular manifestations with distinct ophthalmologic monitoring protocols.
Corticosteroids sit at the top of the volume ranking, with biologics climbing the fastest.
Administration Route:
Route selection dictates distribution infrastructure investment, with cold chain requirements and site-of-care economics creating tiered margin profiles across delivery modalities.
- Intravenous:Hospital-based biologic infusion requires temperature-controlled logistics and specialized nursing protocols. REACH registration mandates for novel immunosuppressant substances tighten environmental exposure documentation for European manufacturing facilities serving this channel.
- Oral:Maintenance therapy for chronic phase management travels through specialty pharmacy networks. United States commercial payers are consolidating prior authorization control through centralized pharmacy and therapeutics committees, displacing individual prescriber discretion in integrated delivery networks.
- Injectable:Subcutaneous formulations enable clinic-based administration with reduced infusion center dependency.
- Inhalation:Pulmonary-targeted delivery remains investigational with limited approved indications.
Oral formulations retain the highest prescription frequency, while intravenous biologics capture the steepest expansion trajectory in revenue terms.
End User:
Care setting concentration determines contracting leverage, with hospital system consolidation in the United States and national health service procurement in Europe creating divergent purchasing dynamics.
- Hospitals:Academic medical centers in the United States and Germany pilot combination biologic regimens for refractory sarcoidosis. FDA Good Manufacturing Practice standards and EMA parallel designation frameworks shape which manufacturers can supply these infusion-dependent protocols.
- Homecare:Specialty pharmacy distribution captures patient relationships outside hospital dependency for oral maintenance regimens. Medicare Part B and commercial payer coverage decisions in the United States increasingly require step-therapy documentation before biologic authorization.
- Clinics:Community rheumatology and pulmonology practices manage stable patients with established protocols.
- Research Institutions:Academic centers generate the real-world evidence that German and French HTA bodies now mandate for continued reimbursement.
Hospitals command the largest biologic revenue share, with homecare gaining share fastest as oral maintenance protocols expand.
Treatment Stage:
Stage-specific protocols create distinct competitive arenas, with acute phase commoditization contrasting against chronic phase subscription monetization opportunities.
- Maintenance Therapy:Long-term immunosuppression and biologic subscription programs sustain pharmaceutical firm revenue beyond acute intervention. European reference pricing mechanics compress biologic margins against generic immunosuppressant alternatives, while United States commercial payer networks retain broader advanced therapy access.
- Relapse Treatment:Escalation to biologics or combination regimens addresses corticosteroid failure. Cardiac and neurologic sarcoidosis indications offer expansion vectors beyond pulmonary-first development programs, with underpenetrated organ-specific protocols commanding premium positioning.
- Acute Phase:Initial corticosteroid suppression remains protocol-standard despite biologic efficacy data.
- Chronic Phase:Steroid-sparing transition defines the competitive battleground between immunosuppressants and biologics.
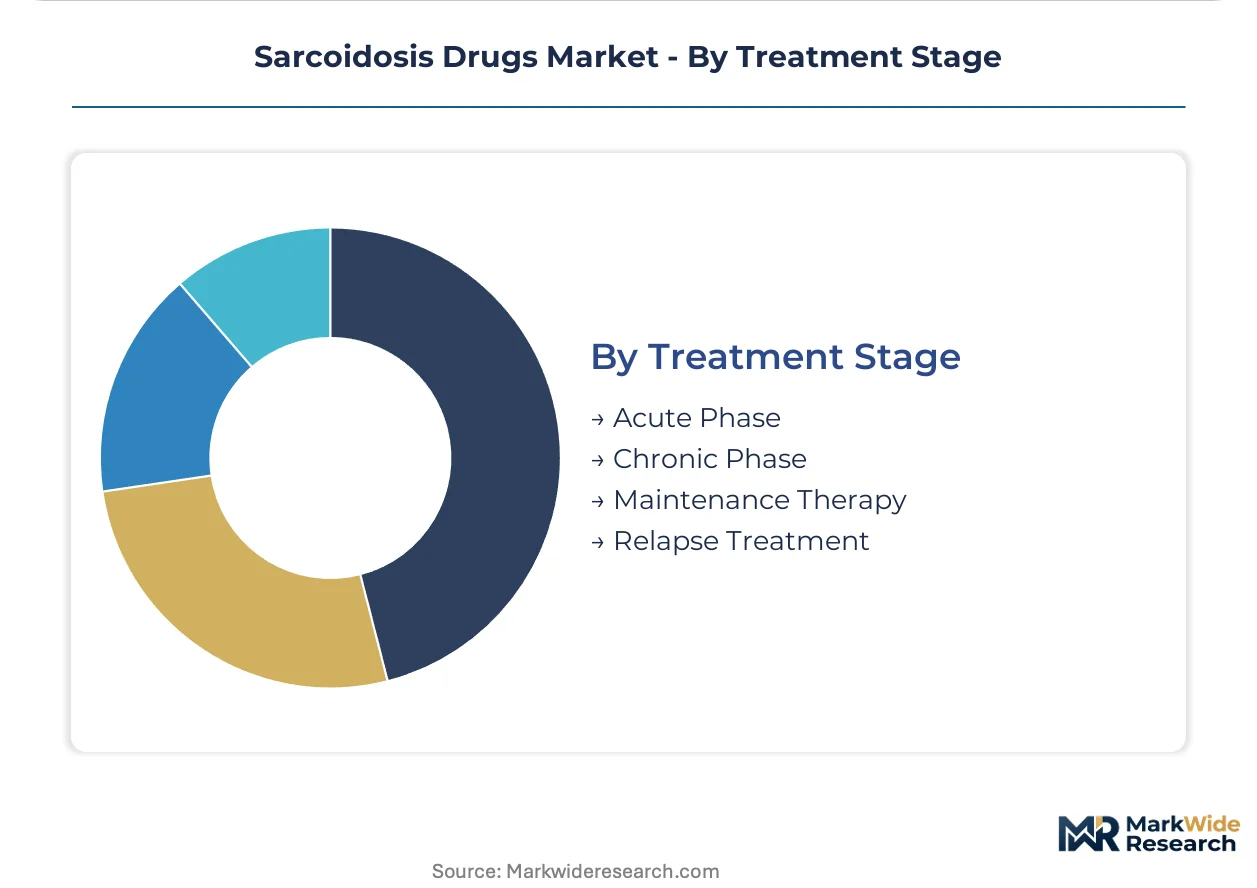
Maintenance therapy sits at the top of the volume ranking, with relapse treatment climbing the fastest as biologic step-therapy protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where sarcoidosis drug development concentrates, as manufacturers migrate clinical trial investment toward jurisdictions offering accelerated approval pathways and orphan drug exclusivity premiums that offset compliance costs.
United States
FDA breakthrough therapy designation and orphan drug incentives pull Phase II and III trial sponsorship toward Boston and San Francisco biotech clusters. Medicare Part B reimbursement for hospital-based biologic infusion sustains prescriber access in the Northeast and Midwest integrated delivery networks. The FDA's Good Manufacturing Practice enforcement for injectable formulations filters market participation to capitalized manufacturers with dedicated biologic production facilities.
Germany
Health Technology Assessment bodies in Berlin and Cologne mandate real-world evidence generation for continued biologic reimbursement, embedding digital biomarker collection into post-market protocols. EMA parallel designation frameworks harmonize exclusivity timelines with transatlantic markets, reducing regulatory duplication costs for sponsors. Academic medical centers in Munich and Heidelberg pilot combination biologic regimens for refractory pulmonary and cardiac sarcoidosis cases.
France
ANSM pharmacovigilance mandates require post-market fibrosis progression tracking for novel immunosuppressant substances, tightening environmental exposure documentation for manufacturing facilities. The country's national health service procurement concentrates purchasing leverage through centralized hospital formulary committees in Paris and Lyon. Reference pricing mechanics compress biologic maintenance therapy margins against generic immunosuppressant alternatives.
Japan
PMDA sakigake designation accelerates review timelines for sarcoidosis candidates demonstrating steroid-sparing efficacy, attracting development investment from domestic and foreign sponsors. METI industrial policy supports biologic cold chain infrastructure expansion in the Kanto and Kansai regions to enable hospital infusion center growth. Tokyo and Osaka academic centers generate the clinical data that German and French HTA bodies increasingly reference for cross-border reimbursement decisions.
Switzerland
Swissmedic alignment with EMA standards enables streamlined market access for biologics approved through centralized European procedures, while domestic pricing remains negotiated outside reference pricing systems. Basel and Zurich host contract manufacturing organizations serving global biologic sponsors seeking GMP-compliant production capacity. The country's pharmaceutical cluster benefits from proximity to German and French patient populations while operating outside EU reimbursement compression mechanics.
Sarcoidosis Drugs Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical conglomerates commanding biologic maintenance therapy revenue while generic manufacturers absorb corticosteroid volume compression. Market structure concentrates around three archetypes: respiratory-immunology diversified majors, rare disease pure-plays, and biologic production service providers. Competitive moves center on hospital infusion center partnerships and real-world evidence registry establishment to secure HTA body favor.
Within the diversified pharmaceutical tier, Pfizer and Novartis exemplify contrasting strategic positioning—Pfizer leveraging respiratory infrastructure for broad prescriber access, Novartis competing on interstitial lung disease clinical data depth. AbbVie anchors the rheumatology cross-selling archetype, extending immunology franchise relationships into granulomatous disease protocols. Among rare disease specialists, aTyr Pharma and Kinevant Sciences occupy positions defined by mechanism-focused development programs targeting refractory populations.
| Leading Market Players |
|---|
| aTyr Pharma |
| Kinevant Sciences |
| Pfizer |
| AbbVie |
| Kyorin Pharmaceutical |
| Novartis |
| Xentria |
| Relief Therapeutics |
| United Therapeutics |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialty pharmacy networks now control biologic distribution channels across the United States, concentrating purchasing leverage and forcing manufacturers toward subscription-based contracting that locks in volume commitments against reference pricing erosion in European markets.
Pricing Analysis
Capacity additions in Germany and Switzerland are reshaping price floors for GMP-compliant biologic manufacturing, compressing margins on older TNF inhibitors while preserving premium positioning for next-generation interleukin pathway blockers. Three-tier pricing structure across originator biologics, biosimilar alternatives, and generic immunosuppressants dominates contract negotiations, with FDA breakthrough therapy designation and EMA orphan exclusivity serving as the primary quality-grade differentiators. Pricing pressure stems from Medicare Part B reimbursement compression and European reference pricing mechanics that anchor biologic maintenance therapy to generic methotrexate baselines. Community pulmonology practices exhibit the highest price sensitivity due to formulary committee consolidation, while academic medical centers retain flexibility for refractory case protocols.
Supply Chain Analysis
Active pharmaceutical ingredient supply rests on Swiss and German contract manufacturing organizations, with fill-finish capacity concentrating in Ireland and Singapore for transatlantic distribution. Cold chain logistics for injectable biologics draw from specialized temperature-controlled networks anchored in Frankfurt, Chicago, and Tokyo hub airports. Single-source vulnerability pervades the monoclonal antibody production tier, where dedicated bioreactor suites at individual facilities service multiple sponsor programs. Distribution runs through hospital-based infusion centers for intravenous formulations and specialty pharmacy direct-to-patient channels for oral maintenance regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in sarcoidosis therapeutics hinges on steroid-sparing protocol adoption pulling prescribing toward higher-value biologics, while manufacturing scale efficiencies in GMP-certified facilities compress per-unit production costs across maintenance therapy portfolios.
For Market Incumbents: Extend hospital infusion center partnerships into exclusive biologic administration agreements that lock out biosimilar competitors, while embedding real-world evidence collection into Phase IV commitment protocols to satisfy German and French HTA body requirements. Deepen backward integration into GMP-certified production capacity to defend against Swiss and Irish contract manufacturing bottlenecks. For New Entrants and Emerging Players: Specialty pharmacy networks offer the most penetrable channel for oral maintenance regimen launches, particularly in United States Medicare Part D and commercial payer segments where step-therapy documentation creates entry points for steroid-sparing alternatives. Cardiac and neurologic sarcoidosis indications remain underpenetrated organ-specific protocols with limited competing development programs. For Investors and Strategic Acquirers: Valuations sit cheapest among rare disease pure-plays with mechanism-focused pipelines targeting refractory populations, as diversified respiratory-immunology majors trade at premiums reflecting cross-selling optionality. Long-term viability over the coming decade depends on successful navigation of EMA expanded pharmacovigilance mandates and FDA breakthrough therapy pathway conversion. Watch for Health Technology Assessment body decisions in Germany and France as the critical inflection signal for biologic maintenance therapy reimbursement sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Registry Establishment | Embedded digital biomarker collection satisfies ANSM and BfArM post-market tracking mandates for continued reimbursement. |
| Hospital Infusion Center Partnership | Exclusive administration agreements with academic medical centers in Boston and Heidelberg lock in biologic volume against biosimilar displacement. |
| Oral Maintenance Regimen Development | Specialty pharmacy distribution reduces cold chain dependency and captures patient relationships outside hospital settings. |
| Cardiac Sarcoidosis Indication Expansion | Underpenetrated organ-specific protocols command premium positioning beyond pulmonary-first development programs. |
| GMP Manufacturing Scale-Up | Dedicated biologic production facilities in Switzerland and Ireland filter market access to capitalized sponsors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down market sizing triangulated across the analysis window.
Historical reference periods anchored the projection horizon to observed corticosteroid, immunosuppressant, and biologic adoption curves across treatment stages, administration routes, and regional regulatory clusters. CAGRs derived from segmented growth trajectory modeling incorporating patient prevalence estimates, step-therapy protocol maturation timelines, and reimbursement decision velocity from HTA bodies.
Revisions become necessary when FDA breakthrough therapy designation conversions stall, EMA orphan exclusivity timelines compress, or biologic cold chain infrastructure investments lag patient volume growth in target markets. A small set of named triggers—Medicare Part B reimbursement rate adjustments, German G-BA benefit assessment outcomes, and biosimilar entry velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Indonesia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Pharmaceuticals Preservative Market
Pharmaceuticals
Unit Dose Manufacturing Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Leuprolide Acetate Market
Pharmaceuticals
Neurological Disorder Drugs Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Inhalable Drug Market
Pharmaceuticals
Seropositive Rheumatoid Arthritis Drug Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Global Caspofungin Market