
 Europe Contraceptives Market | 2026-2036
Europe Contraceptives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Contraceptives Market Foresight
Public healthcare procurement across European national health services is pivoting toward centralized tender frameworks for long-acting reversible contraceptives. Bayer AG leverages its integrated pharmaceutical-device manufacturing footprint to sustain contract competitiveness with major hospital buyers. Teva Pharmaceutical Industries Ltd anchors its position through generic oral contraceptive portfolios that compete aggressively on price in reimbursement-driven markets.
Contraceptives encompass pharmaceutical formulations, barrier devices, and implantable systems engineered to prevent pregnancy through hormonal suppression, physical obstruction, or spermicidal action, with specifications ranging from ethinyl estradiol dosages in oral pills to copper surface areas in intrauterine devices. Their primary purpose centers on enabling voluntary fertility management within clinical and consumer self-care contexts. Oral pills retain the largest volume share across European reimbursement schemes, while intrauterine devices command premium positioning due to extended duration of action and higher clinician involvement. Implants represent the fastest-expanding category as healthcare providers shift toward set-and-forget modalities that reduce patient adherence failure.
The European Medicines Agency oversees centralized marketing authorization for hormonal contraceptives, while the EU Medical Device Regulation mandates strengthened clinical evaluation for implantable and long-acting products, effectively raising barriers for new entrants. France's national drug safety agency ANSM and Germany's Federal Institute for Drugs and Medical Devices enforce additional post-market surveillance protocols that shape product labeling and risk communication requirements. Stakeholders must monitor evolving reimbursement tier classifications across European national health services as these directly determine patient access elasticity and manufacturer margin structures.
Market Dynamics
The EU Medical Device Regulation is compressing product development timelines for implantable contraceptives while simultaneously elevating clinical evidence requirements that favor established manufacturers with deep regulatory affairs capabilities.
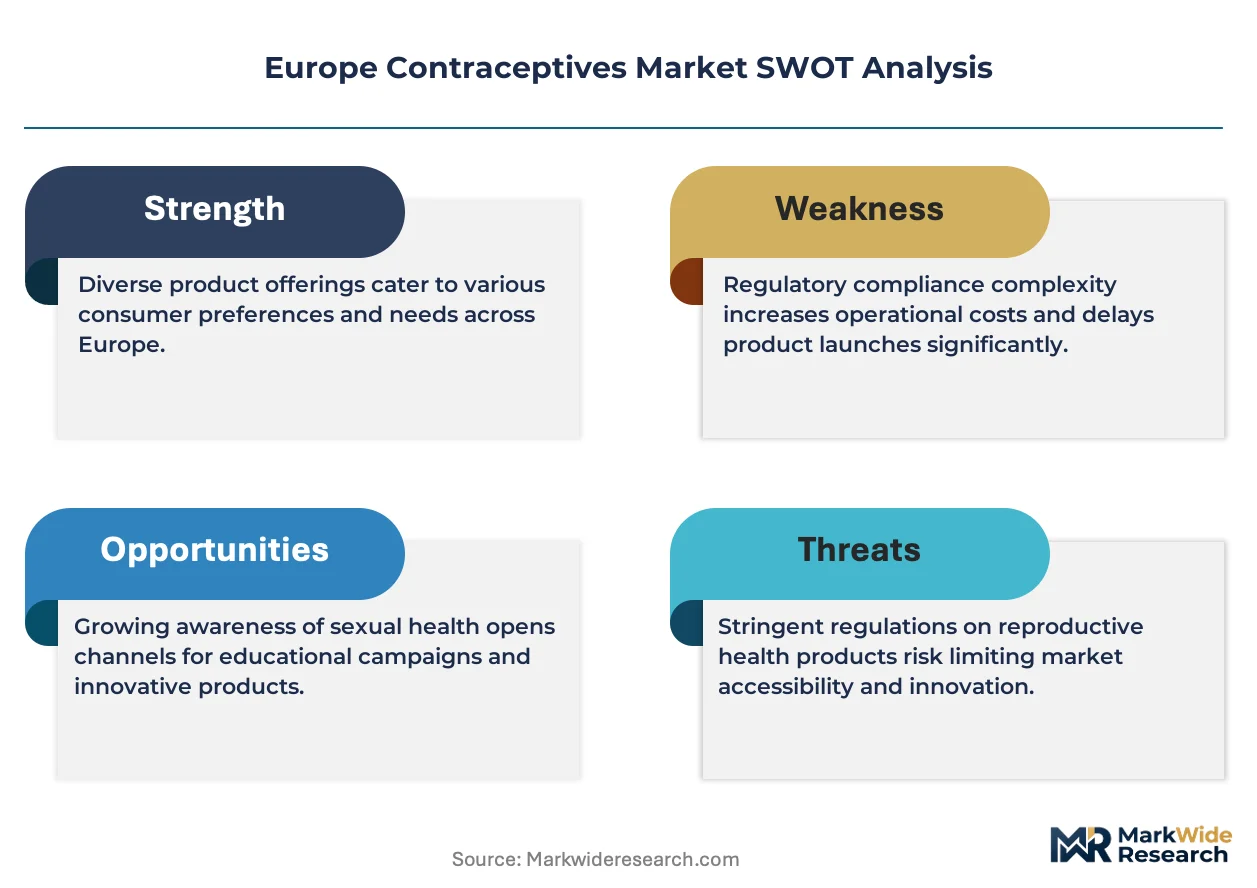
Growth Catalysts
- EU MDR harmonization:Centralized clinical evaluation standards under the EU Medical Device Regulation streamline cross-border market access for compliant manufacturers, reducing redundant national filings.
- Long-acting reversible contraceptive preference:Healthcare providers across Germany, France, and the United Kingdom are shifting patient counseling toward intrauterine devices and subdermal implants to minimize adherence failure.
- Urban clinic expansion:Young adult women in metropolitan sexual health clinics represent a concentrated demand node that pharmaceutical-device manufacturers target with dedicated field forces.
Market Restraints
- Copper and hormone API concentration:Active pharmaceutical ingredient supply for hormonal contraceptives concentrates among a limited set of European and Asian chemical manufacturers, creating input vulnerability.
- Post-market surveillance burden:France's ANSM and Germany's BfArM enforce mandatory adverse event reporting systems that elevate compliance costs for implantable device sponsors.
- Generic oral contraceptive substitution:Reimbursement-driven markets prioritize bioequivalent hormonal pills over branded alternatives, compressing margin structures for originator portfolios.
Strategic Opportunities
- Centralized tender frameworks:National health services in Italy and Spain are consolidating procurement for long-acting reversible contraceptives into single-buyer contracts that reward manufacturing scale.
- Digital contraceptive counseling platforms:Telehealth integration with prescription fulfillment is opening direct-to-patient channels that bypass traditional general practitioner gatekeeping.
- Biodegradable implant materials:Convergence of polymer science with contraceptive delivery systems enables next-generation subdermal products with simplified removal protocols.
Industry Challenges
- Clinical investigator capacity:The EU MDR's expanded clinical evidence requirements strain the pool of qualified European investigators capable of running contraceptive device trials.
- Legacy distribution reconfiguration:Wholesale pharmaceutical distributors face margin pressure as hospital systems and clinic chains consolidate purchasing through direct manufacturer agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Contraceptives Market |
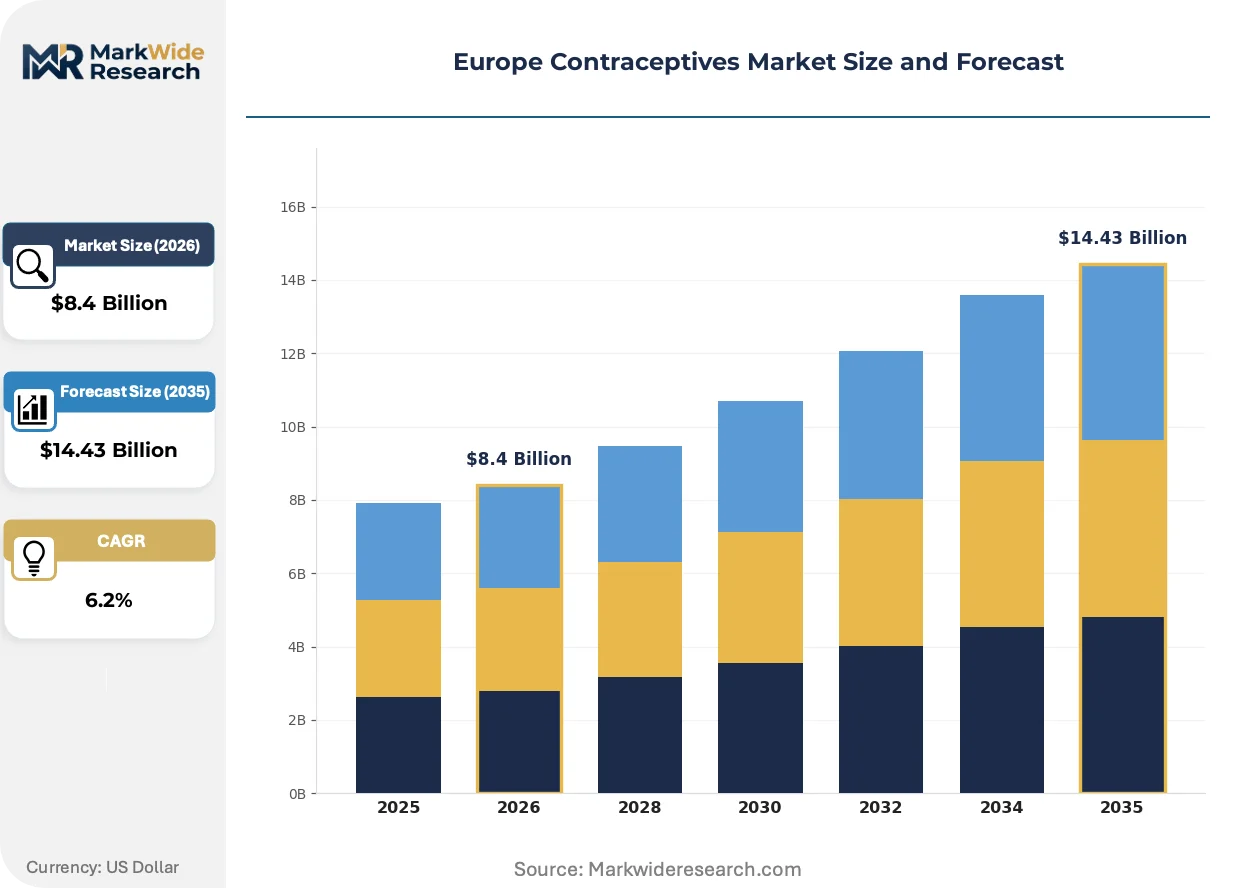
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condoms, Oral Pills, Intrauterine Devices, Implants Delivery Mode: Prescription, Over-the-Counter, Online, Direct Sales End User: Individuals, Couples, Healthcare Providers, Pharmacies Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Bayer AG, Pfizer Inc, Teva Pharmaceutical Industries Ltd, Merck & Co., Inc., CooperSurgical, Inc., Mithra Pharmaceuticals, Church & Dwight Co., Inc., Reckitt Benckiser Group plc, HRA Pharma, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Contraceptives Market Shifts & Advancements
Hormonal delivery mechanisms and procurement architectures are undergoing parallel transformation across European markets, with implications for manufacturing investment priorities and commercial field deployment.
Biodegradable polymer implants are electrifying long-acting contraceptive development by eliminating explantation requirements. Women's health clinics in Stockholm and Amsterdam have piloted these systems since 2023. The technology is electrifying competitive positioning by collapsing the traditional trade-off between duration and reversibility that has structured the implant category.
EMA's centralized marketing authorization pathway for fixed-dose combination hormonal products is harmonizing bioequivalence standards across member states. This regulatory convergence reduces redundant clinical work for sponsors but elevates documentation requirements for generic applicants. Oral contraceptive manufacturers are responding by consolidating European regulatory affairs functions into single hubs in the Netherlands or Belgium.
Self-administered subcutaneous contraceptive injections are capturing share from clinic-dependent depot formulations. Pharmacy chains in the United Kingdom and Ireland now stock these products for patient pickup, displacing traditional nurse-administered models. This channel shift is most visible among women aged 25-34 in urban catchment areas where pharmacy accessibility exceeds clinic appointment availability.
Europe Contraceptives Market Segmentation
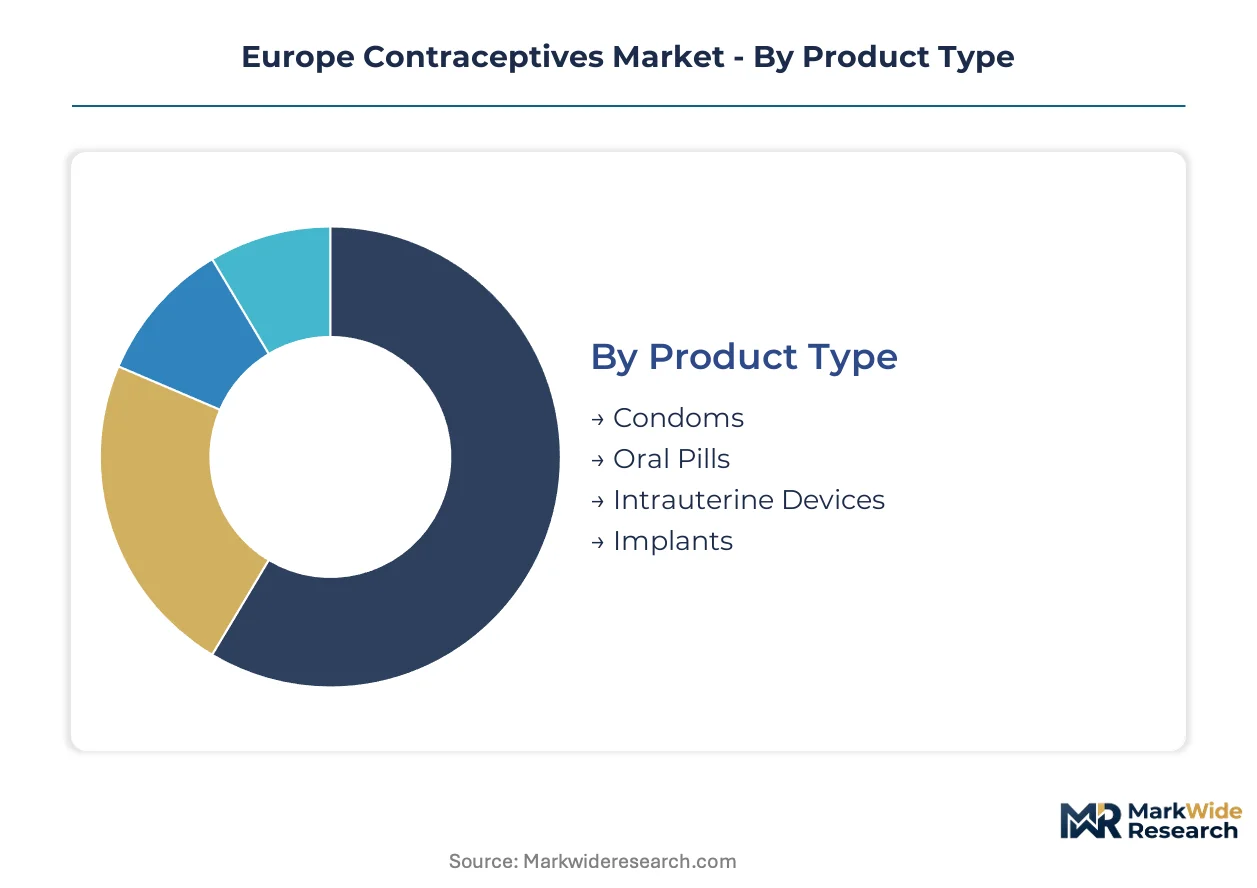
Contraceptive purchasing decisions in Europe split across clinical prescription pathways and consumer self-selection channels, with reimbursement status and regulatory classification determining which segments manufacturers prioritize for field force deployment versus digital marketing investment.
Product Type:
Standardization dominates at the commodity end while premium tiers demand customization through clinician fitting and personalized hormonal profiling.
- Oral Pills:Fixed-dose and phased combination formulations containing ethinyl estradiol with progestin variants. Germany's statutory health insurance funds reimburse these most generously, though generic substitution rules in France and Spain compress branded margins.
- Intrauterine Devices:Copper-bearing and hormonal-releasing systems requiring clinical insertion with speculum examination. Demand concentrates in the United Kingdom's NHS sexual health clinics and Dutch general practitioner practices where long-acting methods receive preferential counseling.
- Condoms:Latex and synthetic polymer barrier devices sold without prescription across European pharmacy and grocery retail.
- Implants:Subdermal rods releasing etonogestrel or levonorgestrel over multi-year durations.
Most installed capacity flows through Oral Pills. Expansion is steepest in Implants.
Delivery Mode:
Channel economics vary sharply across markets where pharmacy monopoly laws in Italy and Greece constrain direct access relative to Nordic deregulation.
- Prescription:Clinician-mediated dispensing following medical consultation and contraindication screening. France's ANSM mandates specific training certificates for hormonal contraceptive prescribers, creating regional access disparities between Parisian clinics and rural practices.
- Over-the-Counter:Pharmacy-sold products without mandatory physician consultation, covering emergency contraception and barrier methods. Ireland and Portugal expanded OTC emergency contraceptive access, shifting volume from prescription channels.
- Online:Telehealth-integrated prescription fulfillment and direct-to-consumer shipping. United Kingdom pharmacy chains and Dutch digital health platforms capture urban women aged 25-34 seeking appointment avoidance.
- Direct Sales:Manufacturer-to-institution contracting for hospital and clinic system procurement.
Prescription channels retain the largest volume base. Online channels are climbing the fastest.
End User:
Decision-making authority fragments between individual consumers, partnered negotiations, and institutional gatekeepers with divergent incentive structures.
- Healthcare Providers:Gynecologists, general practitioners, and specialized sexual health clinicians who counsel method selection and administer long-acting products. Sweden's midwife-led contraceptive clinics demonstrate non-physician provider expansion.
- Individuals:Single women making autonomous purchasing decisions, particularly for oral pills and barrier methods. Urban German women exhibit highest self-directed switching behavior between methods.
- Couples:Joint decision-making units evaluating shared contraceptive responsibility and fertility planning timelines.
- Pharmacies:Retail dispensaries acting as both fulfillment point and counseling access, particularly where clinician shortages delay appointments.
Healthcare Providers handle the most complex fittings. Individual self-selection is gaining share fastest.
Price Tier:
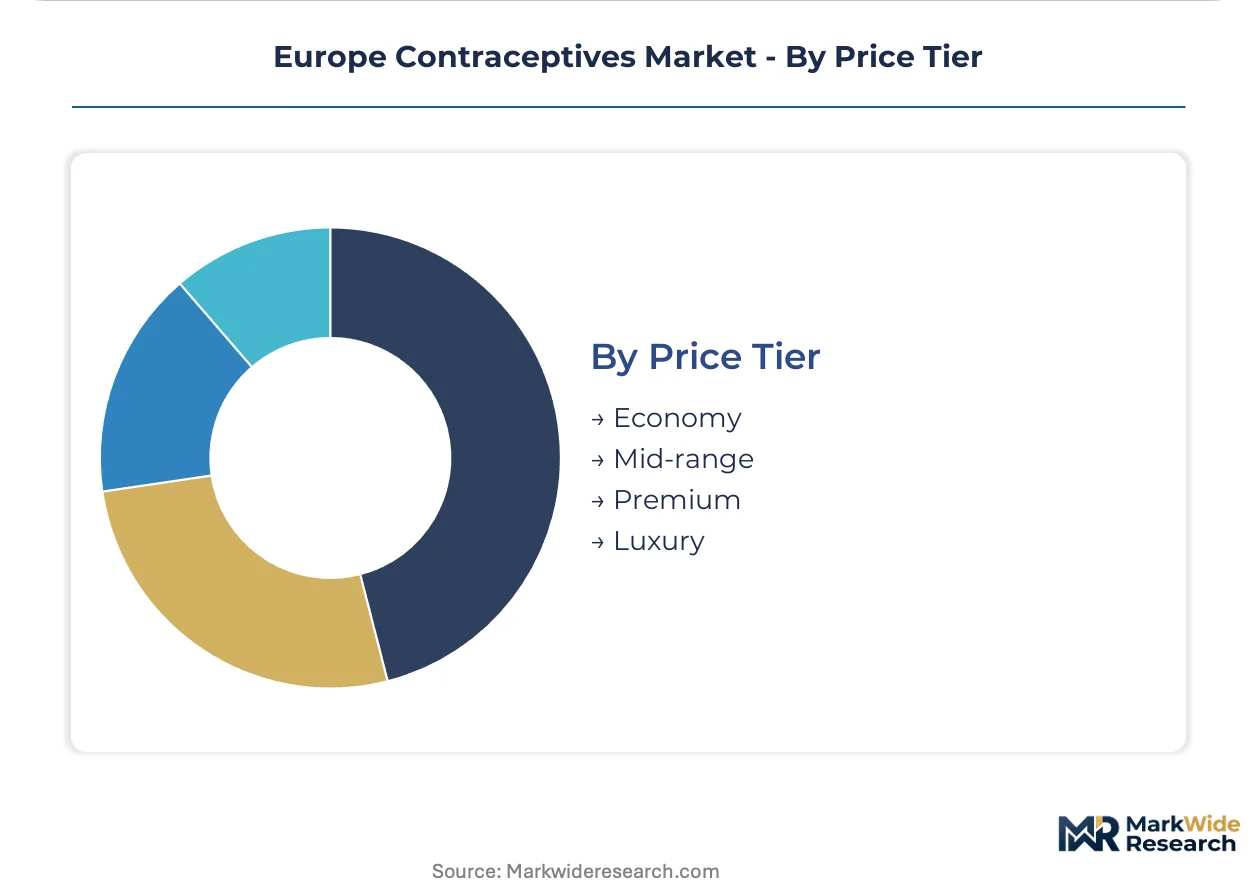
Reimbursement ceilings and out-of-pocket tolerance create four distinct commercial zones with minimal cross-shopping between economy and premium tiers.
- Economy:Bioequivalent generic oral contraceptives and standard latex condoms priced at reimbursement floors. Teva Pharmaceutical Industries and regional generic houses dominate tenders in Poland and Romania.
- Mid-range:Branded oral pills with established safety profiles and differentiated copper IUDs from established European device manufacturers.
- Premium:Hormonal IUDs with localized progesterone delivery and subdermal implants requiring specialized insertion training. Bayer AG and Organon hold concentrated positions here.
- Luxury:Biodegradable polymer implants and customized hormonal profiling with concierge clinical access. Stockholm and Amsterdam clinics pilot these services for affluent urban segments.
Economy tiers capture the largest prescription volumes. Premium tiers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance funds reimburse oral contraceptives more generously than France's generic substitution rules allow, creating divergent margin environments for pharmaceutical sponsors across these neighboring markets.
Germany
Federal Institute for Drugs and Medical Devices (BfArM) enforces stringent post-market surveillance for implantable devices, while statutory health insurance funds maintain favorable reimbursement tiers for long-acting reversible contraceptives. Berlin and Munich host concentrated sexual health clinic networks where healthcare providers actively counsel patients toward intrauterine devices and subdermal implants.
France
National drug safety agency ANSM mandates specific training certificates for hormonal contraceptive prescribers, generating regional access disparities between Parisian clinics and rural practices. Île-de-France concentrates demand from young adult women in metropolitan sexual health clinics, while the national reimbursement scheme prioritizes bioequivalent generic oral contraceptives over branded alternatives.
United Kingdom
NHS sexual health clinics drive concentrated demand for copper and hormonal intrauterine devices, with procurement consolidating through centralized tender frameworks. London and Manchester anchor urban clinic expansion targeting women aged 25-34, while pharmacy chains capture self-administered subcutaneous contraceptive injection volume through telehealth-integrated fulfillment.
Italy
National health service procurement is consolidating long-acting reversible contraceptive purchasing into single-buyer contracts that reward manufacturing scale. Lombardy and Emilia-Romagna host the densest networks of gynecological practices, where clinician counseling patterns increasingly favor set-and-forget modalities over daily adherence-dependent methods.
Netherlands
Digital health platforms in Amsterdam and Rotterdam capture urban women seeking appointment avoidance through online prescription fulfillment integrated with telehealth consultation. General practitioner practices maintain preferential counseling positions for long-acting methods, while pharmacy monopoly laws constrain direct access relative to Nordic deregulation models.
Europe Contraceptives Market Competitive Landscape
German and Swiss producers anchor the premium-device tier; Israeli and American specialists hold positions in generic pharmaceutical supply. The vendor base splits between consolidated pharmaceutical-device integrators and fragmented regional generic houses. Three archetypes dominate: integrated pharma-device manufacturers with captive regulatory affairs capabilities, pure-play generic oral contraceptive suppliers competing on tender price, and specialized device sponsors focused on long-acting delivery systems. Competitive moves concentrate on manufacturing scale investments for centralized tender participation and backward integration into active pharmaceutical ingredient supply.
Within the integrated manufacturer tier, Bayer AG and Merck & Co., Inc. exemplify archetypes combining pharmaceutical formulation expertise with device engineering capabilities. Among generic-focused suppliers, Teva Pharmaceutical Industries Ltd anchors positions through bioequivalent oral contraceptive portfolios. These three entities represent distinct strategic postures: captive manufacturing integration, price-driven tender competition, and hybrid pharma-device development.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc |
| Teva Pharmaceutical Industries Ltd |
| Merck & Co., Inc. |
| CooperSurgical, Inc. |
| Mithra Pharmaceuticals |
| Church & Dwight Co., Inc. |
| Reckitt Benckiser Group plc |
| HRA Pharma |
| Others |
Supply & Pricing Matrix
Premium-to-economy bifurcation between biodegradable polymer implants and generic oral contraceptives manifests in divergent margin structures and supply chain configurations across European markets. Bayer AG and Organon capture value through specialized clinician networks and captive manufacturing integration, while Teva Pharmaceutical Industries and regional generic houses compete on tender price floors sustained by concentrated API sourcing from Indian and Chinese chemical manufacturers.
Pricing Analysis
Capacity additions in Eastern European manufacturing hubs are reshaping price floors for generic oral contraceptives as Polish and Romanian facilities expand bioequivalent production. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence under EU MDR compliance tiers. Cost compression in economy oral pills intensifies because statutory health insurance funds enforce generic substitution rules. Hospital procurement committees exhibit highest price sensitivity, while luxury-tier biodegradable implant buyers demonstrate minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for hormonal API inbound flows from Indian and Chinese chemical manufacturers. Active pharmaceutical ingredient supply draws from concentrated European and Asian producers, with copper and hormone precursors representing critical input dependencies. Single-source vulnerability elevates risk exposure for etonogestrel and levonorgestrel API supply. Distribution runs through wholesale pharmaceutical networks facing margin pressure from direct manufacturer-to-hospital contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Contraceptives Market represents a late-cycle quality story as demand shifts toward premium long-acting reversible methods with extended duration and reduced adherence failure profiles.
For Market Incumbents: Extend regulatory affairs capabilities to defend implantable device positions against EU MDR compliance barriers that favor established sponsors with deep clinical evidence resources. Deepen backward integration into hormone API supply to mitigate input concentration risk from Asian chemical manufacturers. Consolidate European regulatory affairs functions into single Netherlands or Belgium hubs to exploit EMA centralized authorization pathway efficiencies. For New Entrants and Emerging Players: Launch via telehealth-integrated prescription fulfillment platforms targeting urban women aged 25-34 in United Kingdom and Dutch markets where appointment avoidance drives channel switching. Biodegradable polymer implant development offers the most penetrable white-space opportunity, collapsing traditional duration-reversibility trade-offs. Partner with Stockholm and Amsterdam pilot clinics for clinical validation and premium-tier positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where generic oral contraceptive portfolios face margin compression from reimbursement-driven substitution rules. Five-to-ten year viability favors integrated pharma-device manufacturers with captive regulatory affairs and manufacturing scale for centralized tender participation. Watch biodegradable implant removal protocol simplification as inflection indicator for next-generation product adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Investment | Clinical evidence capabilities determine implantable device market access under tightened EMA evaluation standards. |
| Biodegradable Polymer Development | Elimination of explantation requirements collapses traditional trade-offs in subdermal implant category positioning. |
| Telehealth Platform Integration | Direct-to-patient channels bypass general practitioner gatekeeping in United Kingdom and Dutch urban markets. |
| API Backward Integration | Captive hormone supply mitigates concentration risk from Indian and Chinese chemical manufacturer dependencies. |
| Centralized Tender Participation | Manufacturing scale rewards consolidate procurement for long-acting reversible contraceptives in Italy and Spain. |
Research Methodology
Bottom-up patient volume modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with gynecologists, sexual health clinic directors, hospital procurement managers, and pharmaceutical regulatory affairs specialists combined with secondary validation from EMA centralized marketing authorization filings, EU MDR technical documentation databases, national health service tender records, and hospital procurement databases. Triangulation across stakeholder perspectives and documentary sources ensures cross-verified demand and supply-side estimates.
Historical trendline analysis of oral contraceptive reimbursement patterns and long-acting reversible contraceptive insertion rates established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, delivery mode, end user decision authority, and price tier positioning alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves adjusted for EU MDR implementation timelines and centralized tender framework adoption patterns. Forecast inputs included clinician counseling preference shifts and pharmacy channel deregulation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under API supply disruption scenarios or accelerated biodegradable implant regulatory approval pathways. Outputs reflect documented assumptions regarding reimbursement tier stability and EU MDR enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Mucosolvan (Ambroxol) Market
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
US Hormone Replacement Therapy Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Listeria Monocytogenes Treatment Market
Pharmaceuticals
Nesiritide Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Marine Derived Pharmaceuticals Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Levothyroxine Sodium Market