
 North America Healthcare Machine Vision System Market | 2026-2036
North America Healthcare Machine Vision System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Healthcare Machine Vision System Market Analytics
Buyer concentration among hospital networks is pivoting as integrated delivery systems consolidate purchasing decisions across multistate footprints. Cognex Corporation leverages its industrial vision heritage to compete in regulated healthcare environments. Keyence Corporation anchors its position through direct sales channels that bypass distributor markups. Teledyne DALSA specializes in high-resolution sensor architectures for surgical imaging applications.
Healthcare machine vision systems integrate cameras, optics, illumination, and software algorithms to capture, process, and interpret visual data for clinical decision support, typically operating at frame rates exceeding 30 fps and resolutions above 2 megapixels for diagnostic-grade outputs. 3D vision systems command premium positioning due to depth-perception requirements in robotic surgery and volumetric tissue analysis. Deep learning technology segments attract disproportionate R&D allocation as neural network architectures displace rule-based inspection in pathology and radiology workflows.
FDA premarket review under 21 CFR 892 and HIPAA privacy safeguards shape product development roadmaps and data governance obligations for vendors serving US healthcare providers. The EPA and OSHA maintain secondary influence through medical device manufacturing environmental standards and workplace laser safety protocols. Stakeholders must monitor evolving FDA guidance on AI/ML-based SaMD as classification determinations will gate market access for next-generation platforms.
Market Dynamics
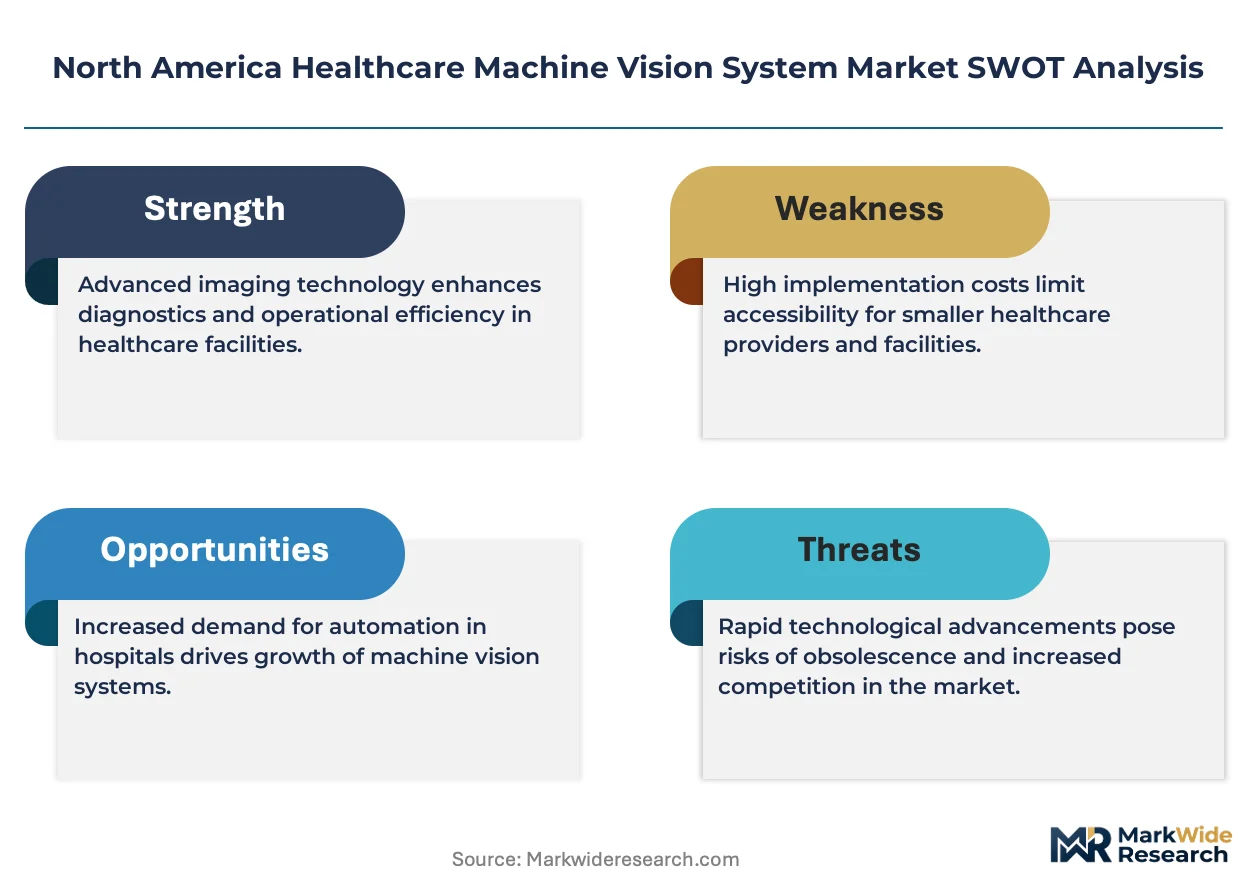
FDA premarket pathways for AI-enabled Software as a Medical Device are compressing commercialization timelines for vision system vendors, while hospital network consolidation concentrates purchasing power across multistate integrated delivery systems. This dual pressure is forcing product architecture decisions toward modular, upgradeable platforms.
Growth Catalysts
- 21 CFR 892 pathway streamlining:FDA's evolving guidance on AI/ML-based SaMD reduces clearance uncertainty for diagnostic-grade machine vision, accelerating vendor time-to-revenue for surgical navigation and pathology applications.
- Robotic surgery depth-perception requirements:3D vision systems command premium positioning as da Vinci and competing surgical platforms integrate stereoscopic imaging for volumetric tissue analysis.
- Northeast corridor academic concentration:Boston and New York City research hospitals cluster drives early adoption of experimental vision architectures, creating reference sites for national rollout.
Market Restraints
- High-resolution sensor supply concentration:CMOS and CCD sensor fabrication concentrates among Asian foundries, exposing North American system integrators to geopolitical supply disruptions and lead time volatility.
- HIPAA data governance friction:Privacy safeguards under 45 CFR 164 impose encryption and audit requirements that extend development cycles and limit cloud-based processing architectures.
- Rule-based algorithm displacement costs:Deep learning migration requires complete retraining datasets and validation protocols, creating sunk-cost barriers for installed base upgrades.
Strategic Opportunities
- US Southeast hospital construction wave:Florida and Texas health system expansions offer greenfield deployment opportunities without legacy imaging infrastructure retrofit constraints.
- OSHA laser safety protocol convergence:Workplace safety standardization creates certification harmonization opportunities for surgical illumination vendors across state jurisdictions.
- Edge-AI and 5G convergence:On-device inference paired with low-latency wireless is enabling real-time patient monitoring outside traditional OR environments, opening ambulatory surgery center applications.
Industry Challenges
- Computational pathology skill scarcity:Dual expertise in histopathology and neural network architecture remains rare, constraining validation team scaling for FDA submissions.
- Legacy PACS integration complexity:Hospital radiology workflows built on DICOM standards require costly middleware development to ingest machine vision outputs without disrupting existing reading room protocols.
- Multi-site clinical trial coordination:FDA-mandated prospective studies for SaMD clearance demand synchronized data collection across dispersed hospital networks with incompatible EMR systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Healthcare Machine Vision System Market |
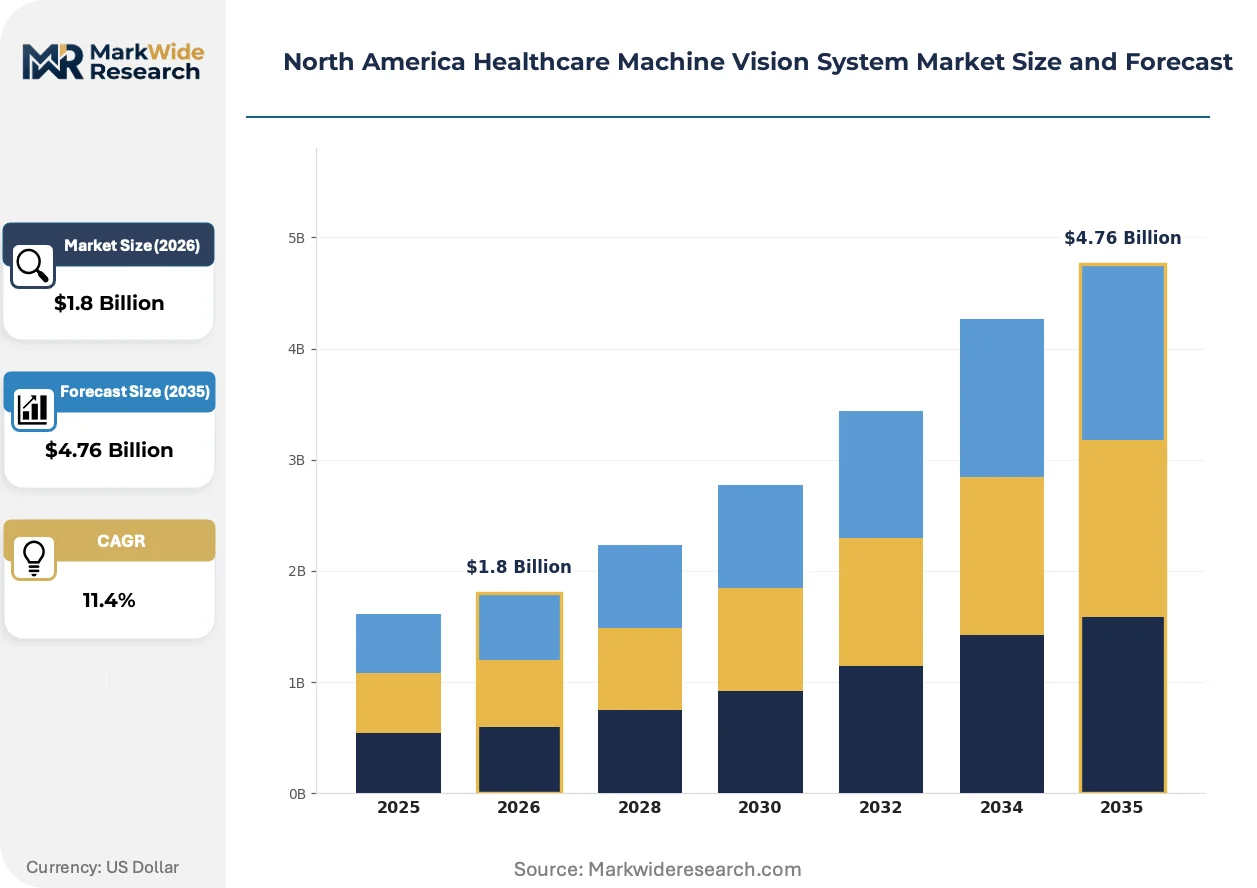
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Vision Systems, 3D Vision Systems, Smart Cameras, Image Processing Software Application: Quality Inspection, Surgical Assistance, Patient Monitoring, Imaging Systems End User: Hospitals, Diagnostic Centers, Research Labs, Surgical Institutions Technology: Artificial Intelligence, Deep Learning, Optical Coherence Tomography, Machine Learning |
| Companies Covered | Cognex Corporation, Keyence Corporation, Teledyne DALSA, Basler AG, National Instruments Corporation, Flir Systems Inc, Datalogic SpA, Teledyne Technologies, Sick AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Healthcare Machine Vision System Market Evolving Landscape
Deep learning architectures are actively displacing deterministic image processing pipelines across diagnostic workflows, while regulatory frameworks race to keep pace with autonomous algorithm performance claims. Vendor differentiation is narrowing to data quality and annotation depth rather than hardware specifications alone.
Hyperspectral imaging is electrifying tissue classification accuracy beyond visible-spectrum limitations. Academic medical centers in Massachusetts and New York are piloting intraoperative systems that discriminate cancer margins in real time. This capability is compressing reoperation rates and shifting purchasing criteria toward spectral resolution metrics.
EPA medical device manufacturing environmental standards are tightening solvent and waste disposal requirements for vision system production facilities. California and Washington state implementations exceed federal baselines, forcing component suppliers to reformulate cleaning processes. Northeast-based vendors with existing green chemistry investments capture preferential supplier status with sustainability-mandated hospital networks.
Integrated delivery systems are consolidating imaging equipment procurement under centralized capital committees, displacing individual hospital radiology department autonomy. Banner Health and Kaiser Permanente models now mandate enterprise-wide platform standardization, compressing vendor count per network. This concentration is most visible in California and Arizona markets where IDN market share exceeds sixty percent of acute care beds.
North America Healthcare Machine Vision System Market Segmentation
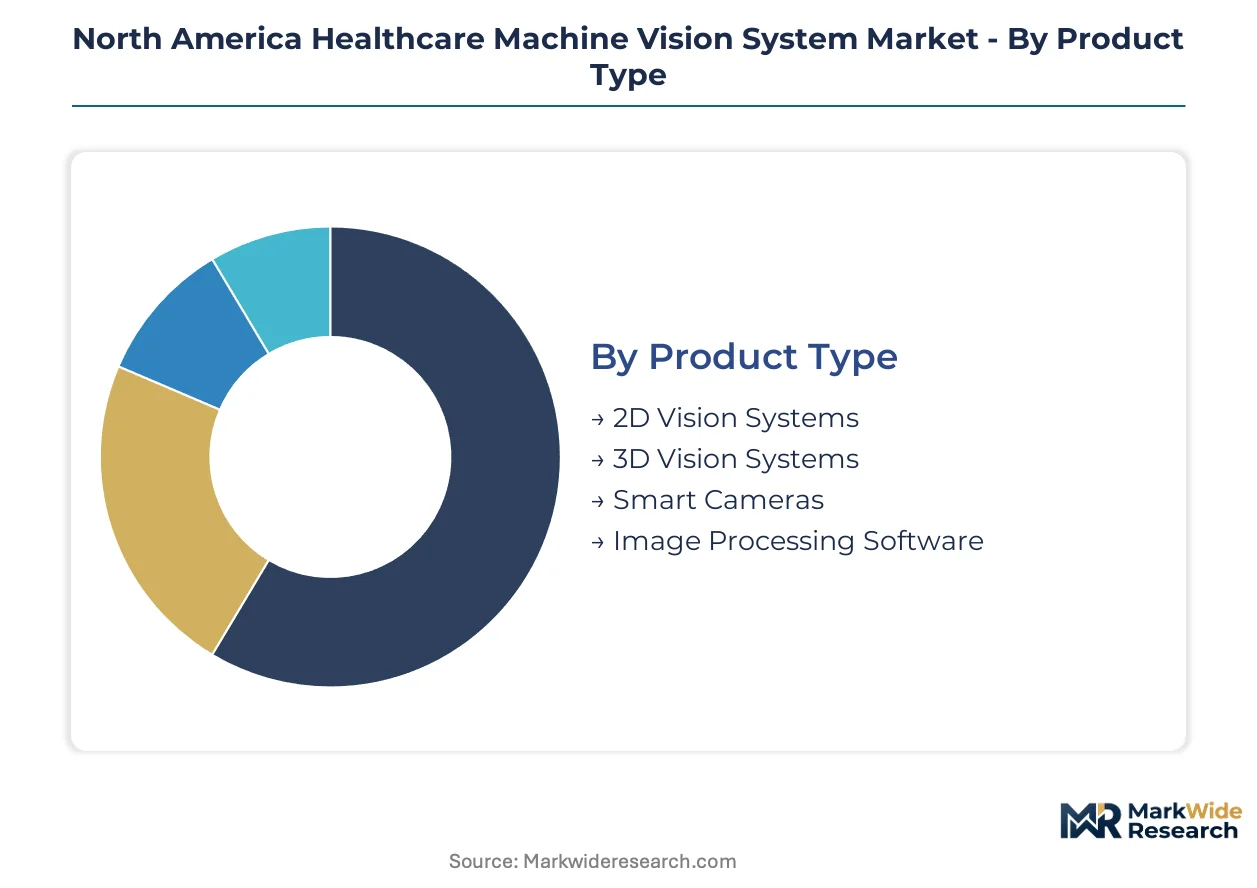
Product architecture choices in healthcare machine vision reflect divergent paths between standardized platforms for broad deployment and specialized configurations for high-acuity settings. Segmentation reveals where vendor R&D investments concentrate and which customer workflows command premium positioning.
Product Type:
Customization intensity varies sharply across this category, with configurable software layers enabling standardization at the hardware level while surgical applications demand bespoke optical configurations.
- 3D Vision Systems:Stereoscopic camera arrays with depth-perception algorithms enable volumetric tissue analysis and robotic surgery navigation. Demand concentrates in academic medical centers along the US Northeast corridor where da Vinci platform integrations require sub-millimeter spatial accuracy. FDA 21 CFR 892 clearance pathways for stereoscopic diagnostic outputs extend development timelines but protect premium pricing.
- 2D Vision Systems:Planar imaging architectures dominate high-throughput quality inspection and routine patient monitoring deployments. Standardized CMOS sensor configurations allow Massachusetts and New York research hospitals to pilot experimental algorithms without proprietary hardware lock-in.
- Smart Cameras:Edge-computing devices with embedded processors enable real-time inference without external computing infrastructure. Compact form factors suit ambulatory surgery center retrofit installations.
- Image Processing Software:Algorithmic layers for enhancement, segmentation, and classification deploy across heterogeneous camera hardware. HIPAA 45 CFR 164 encryption requirements constrain cloud-native architectures.
Most installed capacity flows through 2D Vision Systems. Expansion is steepest in 3D Vision Systems.
Application:
Volume concentration tracks procedure reimbursement rates, with Medicare fee schedules directly influencing capital equipment allocation across hospital service lines.
- Surgical Assistance:Real-time image guidance for navigation, margin assessment, and instrument tracking integrates with robotic platforms and fluoroscopy systems. Boston and New York City academic centers drive adoption of experimental augmented-reality overlays for complex oncology procedures.
- Quality Inspection:Automated verification of medical device manufacturing, pharmaceutical packaging, and sterile supply integrity leverages high-speed line-scan cameras. EPA medical device manufacturing environmental standards shape solvent-handling protocols for vision system cleaning processes.
- Patient Monitoring:Continuous visual surveillance for fall detection, mobility assessment, and ICU deterioration warning deploys privacy-preserving edge architectures. OSHA workplace laser safety protocols govern illumination intensity for bedside installations.
- Imaging Systems:Diagnostic-grade capture for pathology, dermatology, and ophthalmology requires color-calibrated sensors with medical-grade certification. Legacy PACS integration complexity constrains middleware development timelines.
Quality Inspection absorbs the largest share of unit volume. Surgical Assistance is climbing the fastest as robotic platform penetration deepens.
End User:
Procurement authority concentration determines contract structure, with centralized capital committees displacing departmental autonomy across integrated delivery networks.
- Hospitals:Acute care facilities with multistate footprints negotiate enterprise-wide platform standardization, compressing vendor diversity per network. Banner Health and Kaiser Permanente procurement models mandate interoperability with existing EMR infrastructures.
- Surgical Institutions:Dedicated outpatient surgery centers and specialty hospitals prioritize compact, mobile vision systems for procedure-room flexibility. Greenfield construction in Florida and Texas health system expansions bypass legacy retrofit constraints.
- Diagnostic Centers:Independent imaging facilities and hospital-affiliated radiology departments demand rapid throughput and DICOM-native output formats. Reimbursement pressure accelerates interest in AI-augmented reading workflows.
- Research Labs:Academic and commercial R&D operations pilot hyperspectral and experimental architectures before clinical translation. Massachusetts and New York clusters provide reference sites for national rollout.
Hospitals command the dominant share of capital expenditure. Research Labs are gaining share fastest as preclinical validation requirements expand.
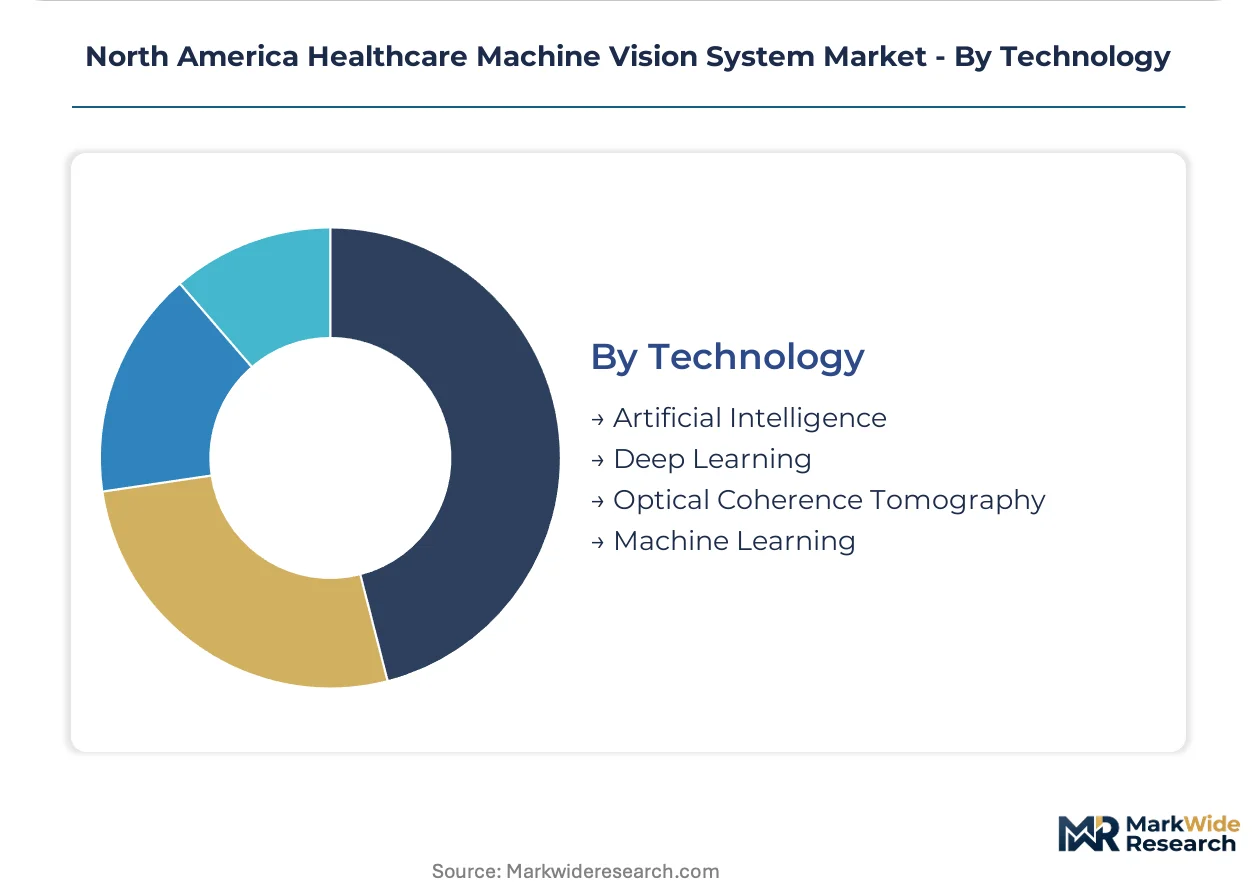
Technology:
Algorithmic sophistication tiers separate rule-based legacy deployments from neural network architectures requiring specialized validation protocols.
- Deep Learning:Convolutional and transformer-based neural networks displace deterministic pipelines in pathology and radiology workflows. Computational pathology skill scarcity constrains validation team scaling for FDA submissions.
- Artificial Intelligence:Broad category encompassing expert systems, computer vision, and autonomous decision support. FDA evolving guidance on AI/ML-based SaMD creates classification uncertainty for next-generation platforms.
- Machine Learning:Traditional supervised and unsupervised methods with interpretable feature engineering persist in regulated environments requiring algorithmic transparency. Rule-based algorithm displacement costs create sunk-cost barriers for installed base upgrades.
- Optical Coherence Tomography:Interferometric depth-resolved imaging for ophthalmology and intravascular applications demands specialized light sources and detection hardware. Premium positioning reflects component complexity and indication-specific regulatory pathways.
Machine Learning represents the largest installed base. Deep Learning is expanding most quickly as neural network architectures mature for clinical deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Computational pathology and surgical robotics talent clusters anchor North American demand, with FDA-cleared AI/ML SaMD pathways accelerating commercialization timelines for vision system vendors serving hospital networks.
United States Northeast Corridor
Academic medical centers in Boston and New York City drive early adoption of experimental vision architectures for real-time cancer margin assessment. FDA 21 CFR 892 premarket review pathways for diagnostic-grade stereoscopic outputs protect premium positioning for surgical navigation systems. Massachusetts General Hospital and Memorial Sloan Kettering serve as reference sites for hyperspectral imaging pilots before national rollout.
United States Southeast
Florida and Texas health system expansions create greenfield deployment opportunities without legacy PACS infrastructure retrofit constraints. OSHA workplace laser safety protocols govern illumination intensity for new ambulatory surgery center installations. Tampa General Hospital and Houston Methodist anchor regional procurement committees standardizing platform selections across multistate footprints.
United States West Coast
California EPA medical device manufacturing environmental standards exceed federal baselines for solvent-handling and waste disposal protocols. Stanford Medicine and Cedars-Sinai pilot edge-AI architectures for ICU deterioration warning systems. Sustainability-mandated hospital networks in the state prefer vendors with existing green chemistry investments.
Canada
Health Canada SaMD guidance alignment with FDA precedents reduces regulatory friction for US-certified vision system vendors entering the market. Ontario and Quebec health authorities consolidate imaging equipment procurement under provincial purchasing cooperatives. Toronto's University Health Network and McGill University Health Centre validate neural network architectures before Health Canada licensing submissions.
North America Healthcare Machine Vision System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered positioning levels, with industrial vision heritage players leveraging manufacturing scale against healthcare-native entrants building regulatory expertise. The vendor base separates into three strategic archetypes: industrial automation crossovers, medical imaging incumbents, and AI-native diagnostic startups. Consolidation pressure from integrated delivery network procurement standardization favors modular platform architectures. Dominant competitive moves include strategic partnerships with robotic surgery platform vendors and portfolio diversification into edge-computing form factors.
Within the industrial crossover tier, Cognex Corporation and Keyence Corporation exemplify manufacturing vision specialists extending into regulated healthcare environments. Teledyne DALSA anchors the high-resolution sensor architecture segment for surgical imaging applications. These three entities occupy positions reflecting divergent channel strategies—direct sales forces, distributor networks, and component supply relationships—each representing a distinct approach to hospital network penetration.
| Leading Market Players |
|---|
| Cognex Corporation |
| Keyence Corporation |
| Teledyne DALSA |
| Basler AG |
| National Instruments Corporation |
| Flir Systems Inc |
| Datalogic SpA |
| Teledyne Technologies |
| Sick AG |
| Others |
Value Network & Pricing Analysis
Computational pathology skill scarcity in Boston and New York City research corridors drives labor-cost differentials that widen pricing-tier spreads between premium 3D surgical navigation systems and standard 2D quality inspection platforms.
Pricing Analysis
Bundled hardware-software service contracts dominate enterprise hospital network procurement, while unbundled component sales persist among research labs piloting experimental architectures. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared surgical navigation systems from CE-marked diagnostic cameras and uncertified industrial vision repurposing. Price differentiation hinges on certification tier and after-sales service intensity. Cost compression in the standard tier is intensifying because integrated delivery networks consolidate purchasing power across multistate footprints. Research labs exhibit highest price sensitivity due to grant-funded capital constraints, while IDN procurement committees prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
High-resolution CMOS and CCD sensor supply rests on Taiwanese and South Korean foundry operations, with Japanese specialty optics producers anchoring precision lens fabrication. Raw material dependencies include rare-earth phosphors for illumination systems, medical-grade aluminum housings, and FPGA processors for edge inference. Distribution runs through authorized distributor networks for hospital sales and direct manufacturer relationships for research institution procurement. Single-source vulnerability concentrates in advanced sensor node fabrication, exposing North American system integrators to geopolitical disruption risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's evolving 21 CFR 892 guidance on AI/ML-based Software as a Medical Device functions as a regulatory compounder, accelerating commercialization timelines for diagnostic-grade vision systems and concentrating procurement authority among early-clearance holders.
For Market Incumbents: Anchor market position through backward integration into high-resolution sensor supply relationships, mitigating Taiwanese foundry concentration risk. Deepen certification moats by pursuing parallel FDA and Health Canada SaMD submissions ahead of guidance finalization. Defend against AI-native diagnostic startups by acquiring edge-computing form factor specialists with ambulatory surgery center channel relationships.
For New Entrants and Emerging Players: Begin with greenfield hospital construction corridors in Florida and Texas, where legacy PACS retrofit constraints do not disadvantage new platform architectures. Target surgical institutions with compact smart camera offerings that bypass enterprise procurement committee standardization mandates. Pursue reference site partnerships with Massachusetts and New York academic medical centers to establish clinical validation credibility before national IDN expansion.
For Investors and Strategic Acquirers: Industrial automation conglomerates with healthcare regulatory expertise are the most active acquirer in this space, seeking machine vision specialists with FDA-cleared product portfolios. Long-term viability favors platform vendors with modular software architectures capable of absorbing algorithmic paradigm shifts without hardware displacement. Watch Health Canada SaMD guidance alignment with FDA precedents as inflection indicator for cross-border market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA SaMD Submission Acceleration | 21 CFR 892 clearance compresses time-to-revenue for surgical navigation vendors serving IDN procurement committees. |
| Hospital System Partnership | Banner Health and Kaiser Permanente enterprise standardization mandates favor vendors with EMR interoperability investments. |
| Software Companion Development | HIPAA-compliant edge-AI architectures enable real-time ICU monitoring outside traditional operating room environments. |
| Backward Integration into Sensors | Captive supply of CMOS arrays insulates against Taiwanese foundry lead time volatility and geopolitical disruption. |
| Reimbursement Strategy | Medicare fee schedule alignment for AI-augmented pathology workflows accelerates hospital capital allocation decisions. |
Research Methodology
Coverage spans the United States Northeast corridor, Southeast construction zones, West Coast sustainability-mandated networks, and Canadian provincial purchasing cooperatives, with primary inputs from each. Primary interviews with hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and computational pathology researchers combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and SEC 10-K equipment supplier disclosures. Bottom-up unit deployment estimates triangulated against top-down healthcare capital expenditure flows.
Rate-of-change decomposition across the analysis window separates volume effects from pricing dynamics and technology substitution patterns. Segmentation dimensions modeled include product architecture tier, application acuity level, end-user procurement authority concentration, and algorithmic sophistication tier. CAGRs derived from logistic diffusion curves for robotic surgery platform penetration and S-curve adoption patterns for deep learning diagnostic workflows. Industry-specific forecast inputs incorporate da Vinci system install base expansion rates and FDA SaMD clearance velocity trends.
Several conditions sit outside the modeled scope, including unforeseen regulatory classification reversals, sensor supply chain geopolitical disruptions, and hospital network bankruptcy restructuring events. Forecasts reflect documented assumptions about FDA guidance finalization timing and IDN consolidation trajectories. A small set of named triggers warrants ongoing watch: Health Canada guidance divergence from FDA precedents, EPA medical device manufacturing standard tightening beyond California baselines, and OSHA laser safety protocol harmonization failure across state jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Specialty Medical Chairs Market
Healthcare Equipment
North America Nurse Call Systems Market
Healthcare Equipment
Middle East and Africa Ultrasound Probe Disinfection Market
Healthcare Equipment
Microbiological Safety Cabinets Market
Healthcare Equipment
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
Medical Chairs Market
Healthcare Equipment
Emergency Hospital Beds Market
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
US Medical Cold Storage Market
Healthcare Equipment
Bedpan Washer Disinfectors Market
Healthcare Equipment
Middle East and Africa Hospital Furniture Market
Healthcare Equipment
Healthcare Cold Chain Monitoring Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Ophthalmic Examination Chairs Market