
 Global Depyrogenated Sterile Empty Vials Market | 2026-2036
Global Depyrogenated Sterile Empty Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Depyrogenated Sterile Empty Vials Market Foresight
EU MDR is consolidating the cost-of-entry calculus for sterile packaging suppliers by mandating enhanced traceability and validated sterilization documentation across the supply chain. Gerresheimer leverages its vertical glass-forming operations to control quality from tubing to finished vial. SCHOTT sustains technology leadership through its FIOLAX borosilicate platform, which dominates high-parenteral applications. Thermo Fisher Scientific anchors North American supply through its integrated distribution network serving CMOs and biopharma directly.
Depyrogenated sterile empty vials are glass or polymer containers rendered free of pyrogenic substances through validated dry-heat depyrogenation at temperatures exceeding 250°C, then terminally sterilized to meet USP <71> sterility assurance levels; they serve as primary packaging for injectable drugs, biologics, and diagnostic reagents where endotoxin contamination risks patient safety. Type I Borosilicate vials dominate margin pools due to their chemical durability and thermal shock resistance in lyophilization cycles, while Plastic Vials represent the fastest-growing structural category as cyclic olefin polymers displace glass in protein-based therapies requiring reduced surface interaction. Capacity segmentation clusters around 2 ml and 10 ml formats, reflecting the prevalence of single-dose biologics and vaccine presentations.
FDA enforcement of USP <85> and <161> endotoxin standards, alongside EMA's Annex 1 revision on sterile manufacturing, compels vial suppliers to maintain validated depyrogenation tunnels and environmental monitoring documentation. ISO 15378 pharmaceutical packaging quality management systems further tighten supplier qualification requirements, favoring manufacturers with integrated quality laboratories. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on container closure integrity testing, as harmonized standards will reshape competitive positioning for suppliers serving dual-territory drug programs.
Market Dynamics
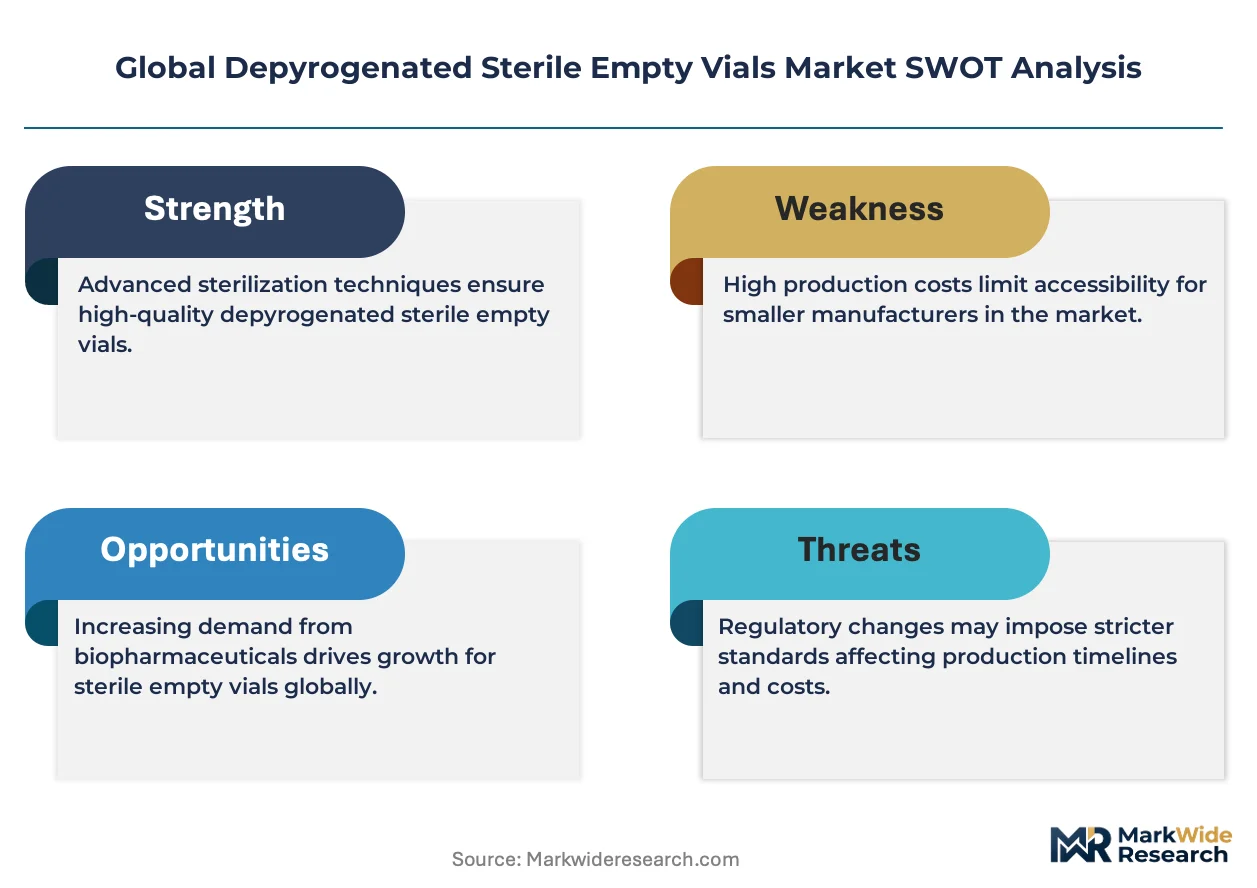
FDA's tightened endotoxin testing protocols under USP <85> and <161> are compressing supplier qualification timelines while biopharmaceutical firms accelerate their shift toward ready-to-use vial formats to eliminate in-house depyrogenation bottlenecks.
Growth Catalysts
- EMA Annex 1 Revision:The European Medicines Agency's sterile manufacturing overhaul mandates validated container closure integrity documentation, forcing drug sponsors toward pre-validated vial suppliers with established quality laboratories.
- mRNA Platform Scale-Up:Cell therapy and vaccine manufacturers in the United States require unprecedented volumes of sterile containment for lipid nanoparticle formulations and personalized medicine production.
- Cyclic Olefin Polymer Migration:Protein-based therapy developers are adopting plastic vials to minimize surface-protein interactions, creating fresh demand for depyrogenated polymer formats previously confined to glass.
Market Restraints
- Borosilicate Glass Supply Concentration:Germany and China host the dominant tubing furnaces for FIOLAX-grade glass, exposing buyers to geopolitical disruption and energy cost volatility in European manufacturing clusters.
- Validation Cost Burden:ISO 15378 certification and FDA-compliant depyrogenation tunnel documentation require multi-million-dollar capital outlays that exclude smaller packaging converters from commercial viability.
- Ready-to-Fill Syringe Substitution:Prefilled syringe formats for biologics are capturing indications previously served by vial-and-needle kits, compressing addressable volume in diabetes and autoimmune segments.
Strategic Opportunities
- Indian CMO Expansion:Contract manufacturing organizations in India are building sterile fill-finish capacity for export markets, creating demand for validated depyrogenated vial supply with local regulatory alignment through CDSCO.
- Point-of-Care Diagnostic Integration:Lyophilized reagent vials for decentralized PCR and immunoassay platforms represent an underpenetrated application with shorter qualification cycles than pharmaceutical-grade supply.
- WHO Prequalification Pathway:Vaccine suppliers targeting Gavi and UNICEF procurement channels require WHO-prequalified packaging, favoring manufacturers with established global health agency dossiers.
Industry Challenges
- Endotoxin Testing Talent Scarcity:The Limulus Amebocyte Lysate assay expertise required for USP <85> compliance sits concentrated among aging specialist technicians, constraining quality laboratory expansion.
- Legacy Equipment Retrofit Complexity:Dry-heat depyrogenation tunnels installed before 2015 lack the data logging and environmental monitoring capabilities demanded by current FDA inspection protocols.
- Cross-Border Documentation Harmonization:Divergent container closure integrity testing standards between FDA and EMA create duplicate validation studies for suppliers serving dual-territory drug programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Depyrogenated Sterile Empty Vials Market |
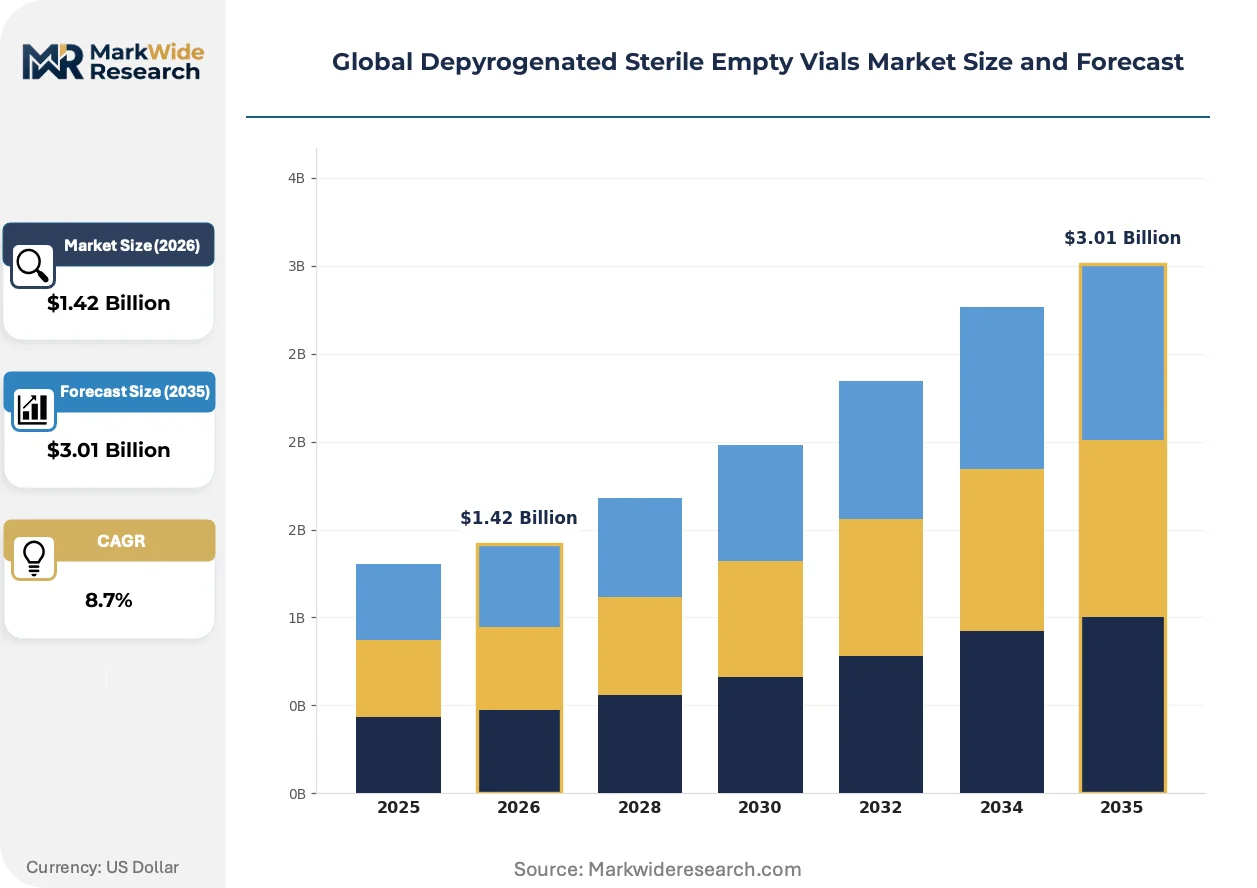
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type I Borosilicate, Type III Soda Lime, Type II Treated, Plastic Vials, Others Capacity: 2 ml, 5 ml, 10 ml, 20 ml, 50 ml Application: Pharmaceuticals, Biotechnology, Diagnostics, Cosmetics, Research Laboratories End User: Contract Manufacturing Organizations, Biopharmaceutical Firms, Diagnostics Laboratories, Cosmetic Manufacturers |
| Companies Covered | Gerresheimer, SGD Pharma, SCHOTT, APG Pharma, Nipro PharmaPackaging, Corning Incorporated, Thermo Fisher Scientific, DWK Life Sciences, Stevanato Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Depyrogenated Sterile Empty Vials Market Shifts & Advancements
Material science breakthroughs and regulatory documentation convergence are compressing product development cycles while reshaping how sterile packaging suppliers compete on validation depth rather than unit cost alone.
Cyclic olefin polymer vials with plasma-treated barrier coatings are rewriting the competitive map for protein-based biologics. Biopharmaceutical formulators at mid-sized innovators are adopting these formats at 18-month switching cycles to eliminate glass delamination risks in high-value antibody therapies. The technology is compressing the traditional glass-dominated premium tier by enabling polymer alternatives in lyophilization applications previously reserved for borosilicate.
EU MDR traceability mandates now require Unique Device Identification serialization on primary pharmaceutical packaging, extending beyond finished devices to sterile empty vials when supplied as device constituents. Manufacturers serving European markets must deploy laser-etched datamatrix codes and maintain electronic records for 15-year lifecycles. High-parenteral applications in oncology and ophthalmology face the steepest compliance ramps as notified bodies tighten technical documentation reviews.
Consolidated procurement desks at top-ten biopharmaceutical firms are unbundling sterile vial supply from traditional distribution intermediaries, establishing direct quality agreements with converters. This disintermediation concentrates purchasing power among three to four global buyers while squeezing regional distributors into logistics-only roles. The United States exhibits the most advanced procurement centralization, with Boston and San Francisco clusters leading the shift toward supplier-managed inventory programs tied to fill-finish scheduling systems.
Global Depyrogenated Sterile Empty Vials Market Segmentation
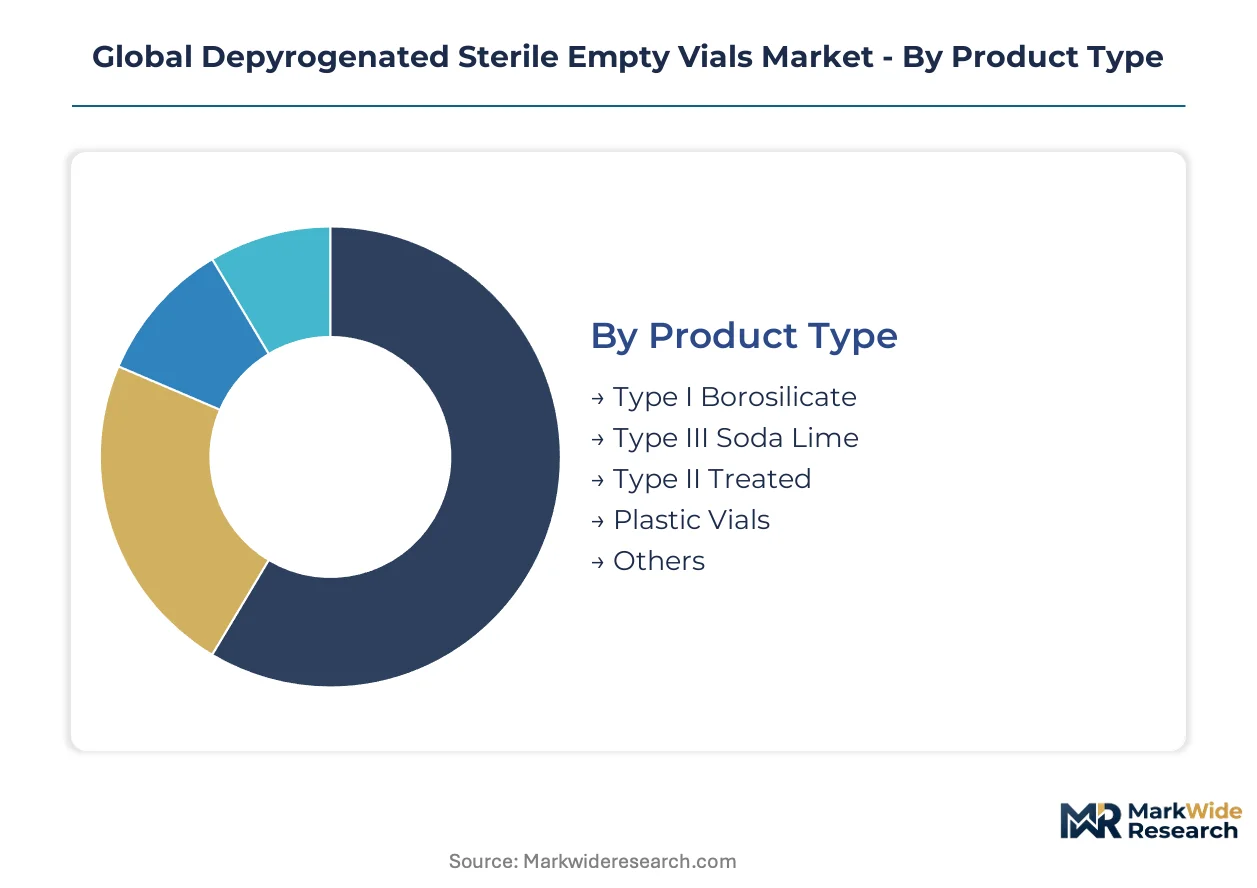
Segmentation in depyrogenated sterile vials reflects divergent technical requirements across fill-finish operations. Material selection, capacity sizing, and end-use sterility standards create distinct procurement workflows that suppliers must navigate simultaneously.
Product Type:
Material chemistry dictates thermal stability, surface interaction profiles, and regulatory qualification burden for drug sponsors.
- Type I Borosilicate:Chemically inert borosilicate glass withstands lyophilization thermal shock and aggressive pH formulations. Demand concentrates in United States oncology and ophthalmology fill-finish operations where FDA sterility assurance requirements are most stringent.
- Plastic Vials:Cyclic olefin polymers and copolymers reduce protein adsorption for monoclonal antibody formulations. Biopharmaceutical innovators in Germany and Switzerland are adopting these formats fastest to eliminate glass delamination risks in high-value biologics.
- Type III Soda Lime:Standard soda lime glass serves diagnostic reagents and veterinary applications with moderate chemical resistance requirements.
- Type II Treated:Surface-treated soda lime variants offer intermediate performance for parenteral generics with limited thermal cycling needs.
- Others:Specialty coated and composite vial structures address niche containment challenges in cell therapy logistics.
Type I Borosilicate leads on scale; Plastic Vials lead on momentum.
Capacity:
Volume selection tracks dosing regimens and manufacturing line automation compatibility across fill-finish suites.
- 2 ml:Standard single-dose presentation for vaccines and potent biologics requiring precise unit dosing. United States mRNA vaccine manufacturers and Boston-area cell therapy developers drive procurement volume for this format.
- 10 ml:Multidose and diluent applications dominate hospital and clinical trial supply chains. German CMOs and Indian export-oriented fill-finish facilities specify this capacity for flexible batch sizing.
- 5 ml:Pediatric and ophthalmic formulations favor this mid-range format for reduced waste and controlled dosing.
- 20 ml:Lyophilized bulk APIs and diagnostic master mixes require larger containment with maintained sterility assurance.
- 50 ml:Industrial-scale media preparation and reference standard storage utilize this capacity for non-patient-facing applications.
2 ml commands the largest installed base; 10 ml shows the steepest expansion trajectory in CMO outsourcing contracts.
Application:
End-use sterility classification determines validation depth and documentation requirements for vial suppliers.
- Pharmaceuticals:Injectable small molecules and biologics demand USP <71> sterility and USP <85> endotoxin compliance. FDA and EMA inspections drive supplier qualification intensity for this segment.
- Biotechnology:Cell and gene therapy manufacturing requires closed-system processing compatibility. United States CDMOs in Maryland and North Carolina specify vial formats integrating with isolator and restricted access barrier systems.
- Diagnostics:PCR reagents and immunoassay components need depyrogenated containment without full pharmaceutical-grade documentation.
- Cosmetics:Ampoule-based skincare formulations utilize sterile vials for premium positioning and preservative-free claims.
- Research Laboratories:Preclinical and analytical applications tolerate broader sterility assurance levels with reduced batch certification.
Pharmaceuticals anchor revenue concentration; Biotechnology is climbing the fastest on cell therapy capacity buildouts.
End User:
Procurement sophistication varies sharply between integrated biopharma and outsourced manufacturing arrangements.
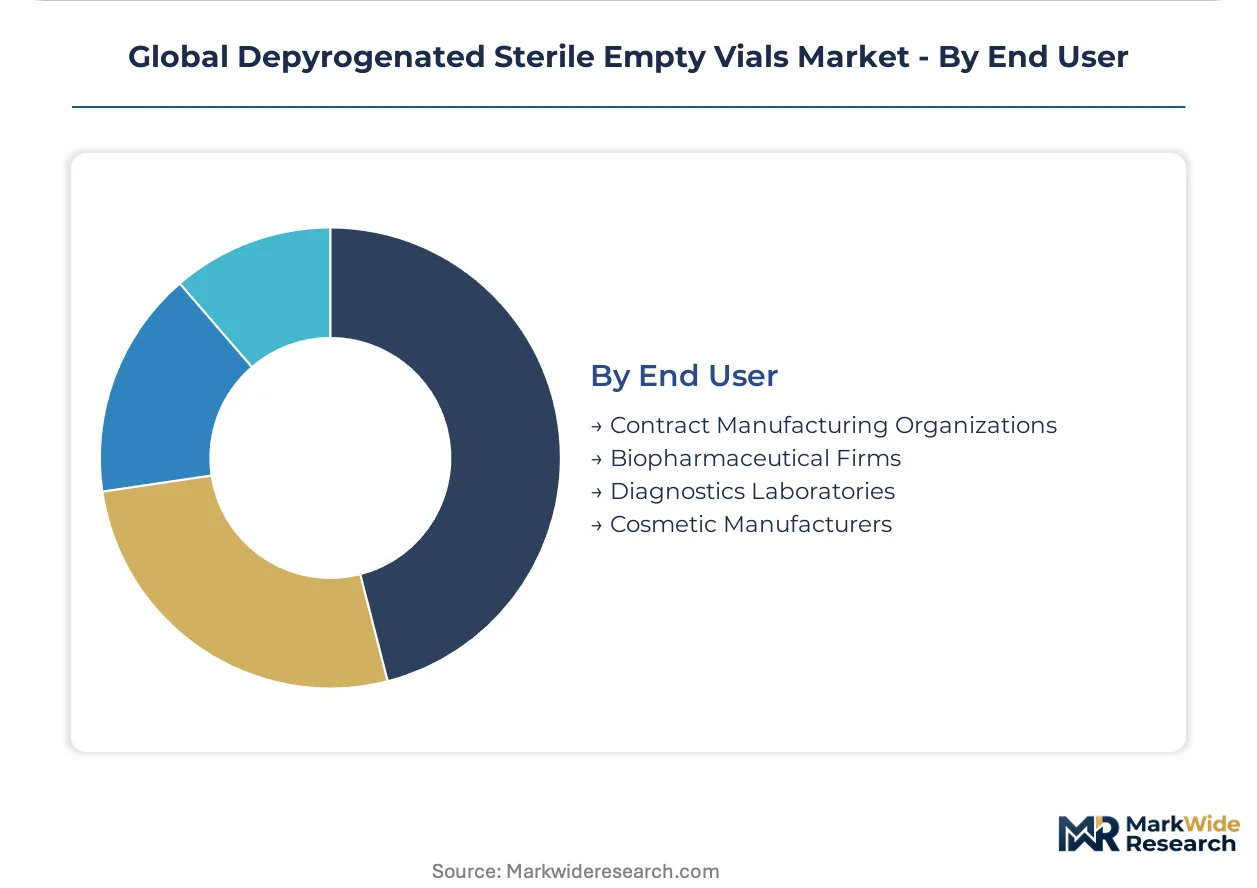
- Biopharmaceutical Firms:Integrated drug developers maintain direct quality agreements with vial converters. Top-ten United States and European sponsors consolidate purchasing through supplier-managed inventory programs tied to fill-finish scheduling.
- Contract Manufacturing Organizations:CMOs serve multiple sponsors with divergent specification requirements. Indian CMOs expanding for export markets are creating fresh demand for CDSCO-aligned depyrogenated vial supply with documented sterilization validation.
- Diagnostics Laboratories:Decentralized testing networks and reference labs procure through distribution intermediaries with shorter qualification cycles.
- Cosmetic Manufacturers:Premium skincare brands specify sterile vials for ampoule formats, prioritizing aesthetic presentation over pharmaceutical-grade documentation.
Biopharmaceutical Firms dominate absolute volume; Contract Manufacturing Organizations are gaining share fastest on outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized technicians capable of Limulus Amebocyte Lysate assay execution concentrate in established pharmaceutical manufacturing corridors, anchoring regional supply capabilities to workforce availability rather than raw material proximity alone.
United States
mRNA vaccine platforms and cell therapy production in Maryland and North Carolina drive unprecedented sterile containment procurement. FDA enforcement of USP <85> and <161> endotoxin standards compresses supplier qualification timelines for domestic fill-finish operations. Boston-area biotech clusters specify ready-to-use vial formats to eliminate in-house depyrogenation bottlenecks.
Germany
FIOLAX-grade borosilicate glass manufacturing anchors European supply security, though energy cost volatility strains furnace economics. EMA Annex 1 revision on sterile manufacturing mandates validated container closure integrity documentation across Bavarian and North Rhine-Westphalian production zones. German CMOs favor 10 ml formats for flexible batch sizing in export-oriented contracts.
India
Contract manufacturing organizations in Maharashtra and Gujarat build sterile fill-finish capacity targeting regulated export markets. CDSCO alignment requirements for depyrogenated vial supply create qualification pathways distinct from FDA or EMA protocols. Indian CMOs seek documented sterilization validation from converters with established global health agency dossiers.
Switzerland
Protein-based therapy developers in Basel and Zurich accelerate adoption of cyclic olefin polymer formats to minimize surface-protein interactions. Swissmedic maintains stringent equivalence requirements for polymer alternatives displacing glass in high-value antibody applications. Local biopharmaceutical innovators execute 18-month switching cycles for lyophilization-compatible polymer vials.
China
Borosilicate tubing furnace capacity concentrates in manufacturing clusters serving domestic biopharmaceutical expansion. NMPA tightening of pharmaceutical packaging quality management systems parallels ISO 15378 implementation timelines. Yangtze River Delta fill-finish facilities source depyrogenated vials for monoclonal antibody and vaccine production scaling.
Global Depyrogenated Sterile Empty Vials Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Consolidated procurement desks at top-ten biopharmaceutical sponsors compress vendor counts while ISO 15378 certification requirements exclude smaller converters. Three strategic archetypes dominate: integrated glass-forming conglomerates with captive tubing supply, specialized pharmaceutical packaging converters with validated depyrogenation infrastructure, and diversified laboratory supply distributors leveraging existing biopharma relationships. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with direct quality agreements displacing traditional distribution intermediaries.
Among Germany-based specialists, Gerresheimer and SCHOTT exemplify the integrated glass-forming archetype through vertical control from tubing to finished vial. Thermo Fisher Scientific represents the diversified laboratory supply model, anchoring North American distribution through integrated networks serving CMOs and biopharma directly. These three occupy positions reflecting divergent strategic bets on supply chain depth versus geographic coverage breadth.
| Leading Market Players |
|---|
| Gerresheimer |
| SGD Pharma |
| SCHOTT |
| APG Pharma |
| Nipro PharmaPackaging |
| Corning Incorporated |
| Thermo Fisher Scientific |
| DWK Life Sciences |
| Stevanato Group |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap converters in Italy and France maintain pricing discipline through selective capacity allocation rather than volume chasing, while private-equity-rolled-up specialists in North America pursue EBITDA expansion through SKU rationalization and backward integration into depyrogenation tunnel assets. This ownership divergence creates bifurcated supply behavior: European family firms prioritize long-term pharmaceutical relationships with documented sterilization validation, whereas financial sponsors optimize for contract manufacturing organization procurement desks demanding supplier-managed inventory programs.
Pricing Analysis
The bundled-vs-unbundled service split separates vial converters offering integrated quality laboratory support from logistics-only distributors. Three-tier pricing structure across premium, standard, and economy levels reflects USP <85> endotoxin certification grade and ISO 15378 quality management system documentation. Cost compression in standard-tier glass vials is intensifying because Indian CMOs negotiate volume scale discounts for export-oriented fill-finish contracts. Contract manufacturing organizations exhibit highest price sensitivity due to sponsor pass-through economics, while integrated biopharmaceutical firms in Boston and San Francisco clusters prioritize validation depth over unit cost.
Supply Chain Analysis
Specialized technicians capable of Limulus Amebocyte Lysate assay execution concentrate in German glass-forming clusters and United States pharmaceutical corridors, anchoring regional supply capabilities to workforce availability rather than borosilicate sand proximity. FIOLAX-grade tubing furnaces in Germany and China draw from high-purity silica deposits and energy-intensive manufacturing economics. Single-source vulnerability runs through German FIOLAX supply given energy cost volatility in European manufacturing zones. Distribution runs through direct quality agreements with top-ten biopharmaceutical sponsors, squeezing regional distributors into logistics-only roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The depyrogenated sterile empty vials market reads as a late-cycle quality story, with mRNA vaccine platforms and cell therapy production in Maryland and North Carolina driving demand-shift toward USP <161> endotoxin-compliant premium specifications.
For Market Incumbents: Anticipate prefilled syringe substitution in diabetes and autoimmune indications by deepening validation documentation for lyophilization-compatible polymer formats. Secure backward integration into cyclic olefin polymer resin supply through long-term offtake agreements with Mitsui Chemicals or TOPAS Advanced Polymers. ISO 15378 certification investment remains the priority lever for excluding smaller converters from commercial viability. For New Entrants and Emerging Players: Indian CMOs expanding sterile fill-finish capacity for export markets represent the most penetrable buyer archetype, requiring CDSCO-aligned depyrogenated vial supply with documented sterilization validation. Target point-of-care diagnostic integration for lyophilized reagent vials in decentralized PCR platforms, where qualification cycles compress versus pharmaceutical-grade supply. WHO prequalification pathway offers go-to-market angle for Gavi and UNICEF procurement channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional packaging converters with validated depyrogenation infrastructure but limited geographic coverage breadth. Long-term viability over the projection horizon hinges on consolidation into three-tier supply structures serving dual-territory FDA and EMA drug programs. Watch for harmonized container closure integrity testing standards as inflection indicator for quality laboratory scalability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Supply | Secures captive supply of cyclic olefin polymers for protein-based biologics formats. |
| ISO 15378 Certification Investment | Excludes smaller converters from commercial viability in FDA and EMA regulated markets. |
| Supplier-Managed Inventory Programs | Aligns vial supply with Boston and San Francisco fill-finish scheduling systems. |
| WHO Prequalification Pathway | Unlocks Gavi and UNICEF procurement channels for vaccine packaging supply. |
| Legacy Equipment Retrofit | Adds data logging capabilities demanded by current FDA inspection protocols. |
Research Methodology
Coverage spans United States, Germany, India, Switzerland, and China, with primary inputs from each region combining structured interviews with fill-finish operations directors, quality assurance leads at biopharmaceutical sponsors, regulatory affairs specialists managing FDA and EMA submissions, and procurement managers at contract manufacturing organizations. Secondary validation draws from FDA 483 inspection observations, EMA Annex 1 revision guidance documents, ISO 15378 certification registries, and USP <85> endotoxin standard updates. Bottom-up and top-down triangulation cross-references vial volume demand from mRNA vaccine manufacturers against borosilicate tubing furnace capacity disclosures.
Granularity-level framing models material type at chemistry-grade resolution, capacity at individual SKU level, and end-use application at sterility classification tier. Segmentation dimensions include Type I borosilicate versus cyclic olefin polymer material chemistry, 2 ml through 50 ml capacity formats, and pharmaceutical versus biotechnology versus diagnostic sterility standards. CAGRs derive from regression analysis against biologics pipeline expansion and fill-finish capacity buildouts across the analysis window. Industry-specific inputs incorporate EMA Annex 1 container closure integrity documentation mandates and FDA enforcement patterns for USP <161> endotoxin testing protocols.
Underlying measurement precision varies by segment; Type I borosilicate pharmaceutical applications carry tighter precision than diagnostic reagent categories due to documented sterilization validation requirements. Forecasts reflect assumptions regarding mRNA platform scale-up continuity and cell therapy manufacturing automation adoption. Material deviation in FIOLAX-grade glass supply security or endotoxin testing technician availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
India Contract Manufacturing Organization (CMO) Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Automated Drug Kiosk Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
Pharmaceutical Coating Equipment Market
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Refrigerators and Freezers Market
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
Fill-Finish Pharmaceutical Contract Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market