
 Middle East and Africa Insulin Pens Market | 2026-2036
Middle East and Africa Insulin Pens Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Insulin Pens Market Foresight
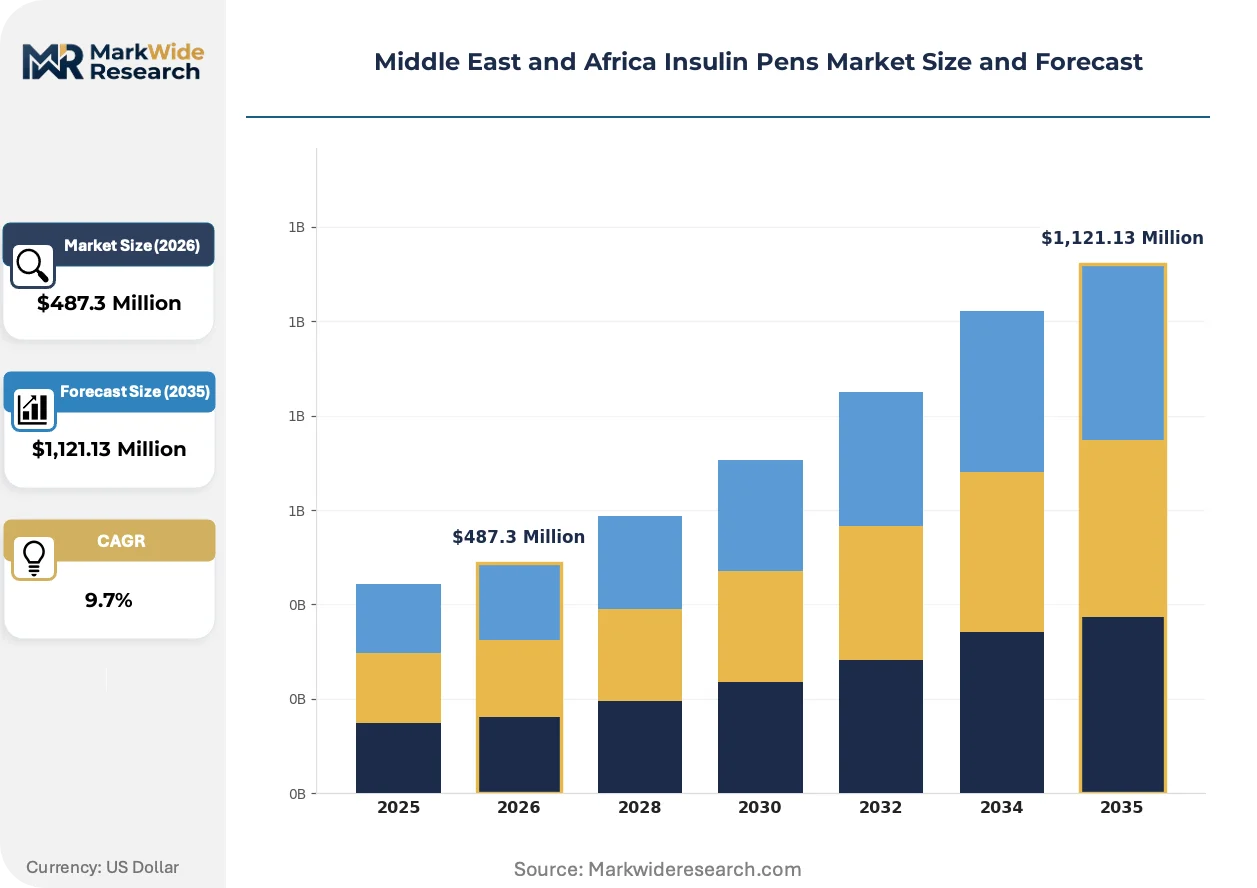
Connected delivery technology is narrowing the gap between conventional dosing and real-time glucose management in the Middle East and Africa insulin pens landscape. Novo Nordisk leverages its biosimilar manufacturing depth to sustain supply continuity across Gulf markets. Eli Lilly and Company anchors its regional position through distribution partnerships with hospital procurement networks. Julphar competes on cost-efficient reusable pen production from its UAE manufacturing base.
An insulin pen is a handheld injection device comprising a cartridge reservoir, dose dial mechanism, and disposable needle attachment, engineered to deliver precise insulin units subcutaneously with minimal user training. Pre-filled pens dominate commercial volumes due to convenience in hospital and homecare settings, while smart pens represent the fastest-expanding segment as Bluetooth-enabled dose logging gains traction among endocrinology clinics. Reusable pens retain stronghold in price-sensitive markets where cartridge replacement economics outperform disposable alternatives.
SFDA, MOHAP, and WHO prequalification standards collectively shape product registration timelines and clinical evidence requirements for manufacturers entering Gulf and North African markets. South Africa's health products regulator enforces parallel stability testing protocols that extend market access lead times for imported devices. Stakeholders must weigh connected device investments against reimbursement fragmentation as public health systems modernize diabetes management protocols across the region.
Market Dynamics
Connected pen technology is digitizing dose tracking across Gulf endocrinology clinics, compressing the gap between injection administration and glycemic control while SFDA and MOHAP tighten premarket evidence requirements.
Growth Catalysts
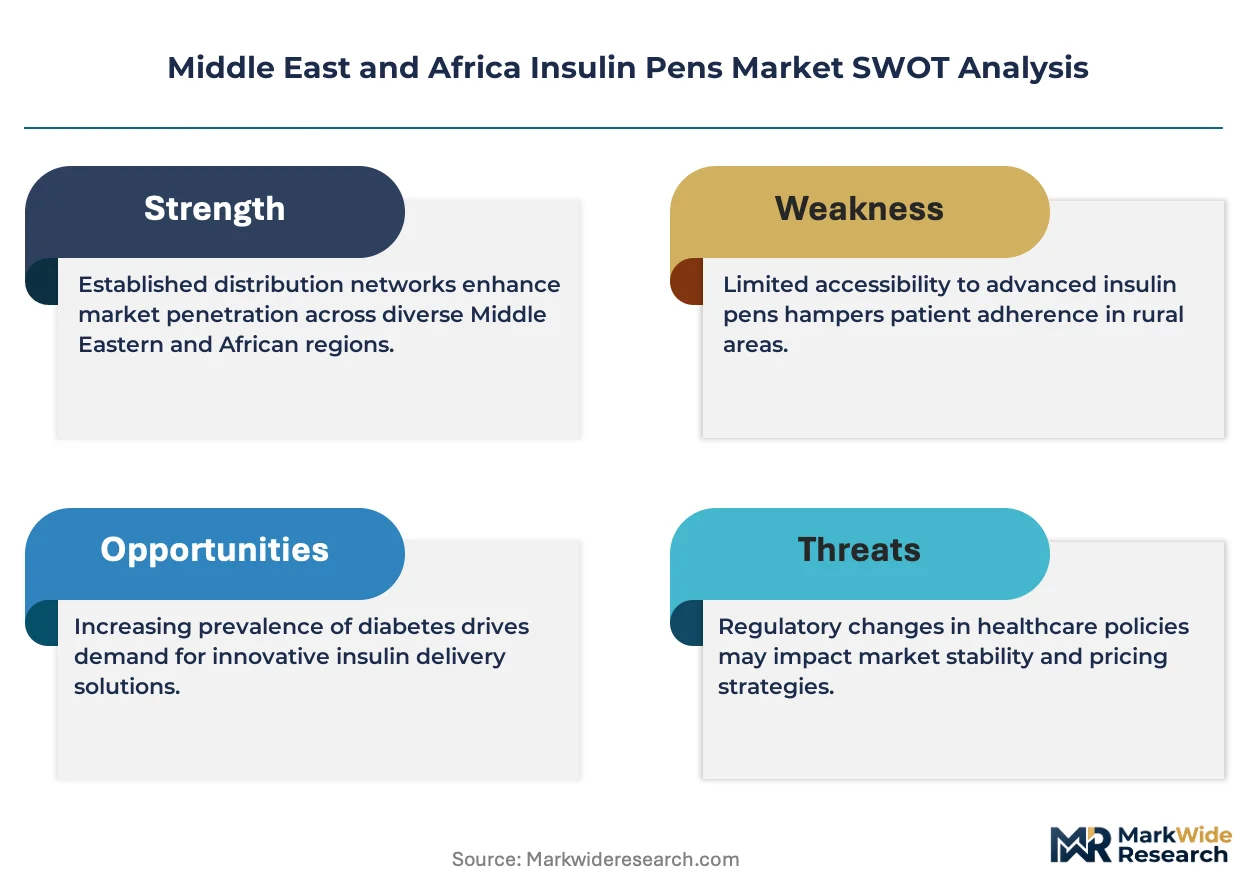
- SFDA Biosimilar Pathway Expansion:Saudi Arabia's streamlined approval framework for biosimilar insulin formulations accelerates patient access to affordable analog therapies in hospital and homecare channels.
- Homecare Migration:Diabetes management protocols across South Africa and Egypt are shifting stable Type 2 patients from outpatient clinics to self-administration, expanding pen-based delivery volumes.
- Bluetooth-Enabled Dose Logging:Smart pen adoption in UAE and Kuwaiti private healthcare networks is narrowing glycemic variability through real-time data capture integrated with continuous glucose monitors.
Market Restraints
- Import Dependency for Active Pharmaceutical Ingredients:Regional manufacturers rely on concentrated Asian supply bases for insulin API, exposing formulation continuity to geopolitical freight disruptions and currency volatility.
- Extended Stability Testing Protocols:South Africa's health products regulator mandates parallel climatic zone studies that add 18-24 months to registration timelines for temperature-sensitive delivery devices.
- Reusable Pen Durability Thresholds:Mechanical dose-dial mechanisms in multi-use devices face accelerated wear rates in high-temperature storage environments, limiting cartridge replacement cycles.
Strategic Opportunities
- Underpenetrated North African Markets:Morocco and Algeria present whitespace for pre-filled pen distribution as national diabetes registries expand reimbursement eligibility for analog therapies.
- Public Hospital Procurement Centralization:Saudi Arabia's NUPCO and UAE's MOHAP are consolidating device purchasing into framework agreements, creating volume aggregation points for compliant manufacturers.
- WHO Prequalification Alignment:Manufacturers pursuing WHO PQ status gain accelerated access to UN procurement channels serving conflict-affected and refugee populations across the Horn of Africa.
Industry Challenges
- Cold Chain Integrity Gaps:Last-mile distribution networks in rural Egypt and Sudan lack validated temperature monitoring, risking insulin degradation before patient administration.
- Connected Device Cybersecurity Certification:Bluetooth-enabled pens require SFDA medical device software validation that exceeds traditional hardware timelines, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Insulin Pens Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-filled Pens, Reusable Pens, Disposable Pens, Smart Pens End User: Hospitals, Clinics, Homecare, Pharmacies Delivery Mode: Subcutaneous, Intramuscular, Intravenous, Others Injection Technology: Pen Needle, Auto-Injector, Syringe, Jet Injector |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly and Company, Julphar, Biocon, Wockhardt, Becton Dickinson and Company, Ypsomed, Medtronic, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Insulin Pens Market Shifts & Advancements
Digital integration is redefining how insulin delivery data flows between patients and care teams across Middle East and African healthcare systems. Three concurrent developments are reshaping product development priorities and go-to-market strategies.
Smart pen platforms are digitizing injection logging through embedded sensors and mobile application pairing. Private diabetes centers in Dubai and Riyadh are piloting these devices for adolescent Type 1 cohorts where adherence tracking proves critical. The technology is digitizing the traditional patient-reported outcome model, enabling clinicians to identify missed doses before HbA1c deterioration.
MOHAP's 2024 medical device software guidance now mandates cybersecurity documentation for connected delivery systems seeking UAE market authorization. This regulatory evolution is forcing manufacturers to embed encryption protocols and post-market surveillance capabilities during design phases rather than retrofitting compliance. Pre-filled pen portfolios without digital connectivity face accelerated margin compression in Gulf procurement tenders.
Hospital pharmacy committees are consolidating insulin purchasing into therapeutic category management frameworks. Group procurement organizations in Saudi Arabia and South Africa are replacing fragmented ward-level ordering with centralized formulary decisions that prioritize total cost of ownership over unit price. This behavioral shift is most visible in Johannesburg's academic hospital networks where smart pen contracts now bundle device supply with data analytics subscriptions.
Middle East and Africa Insulin Pens Market Segmentation
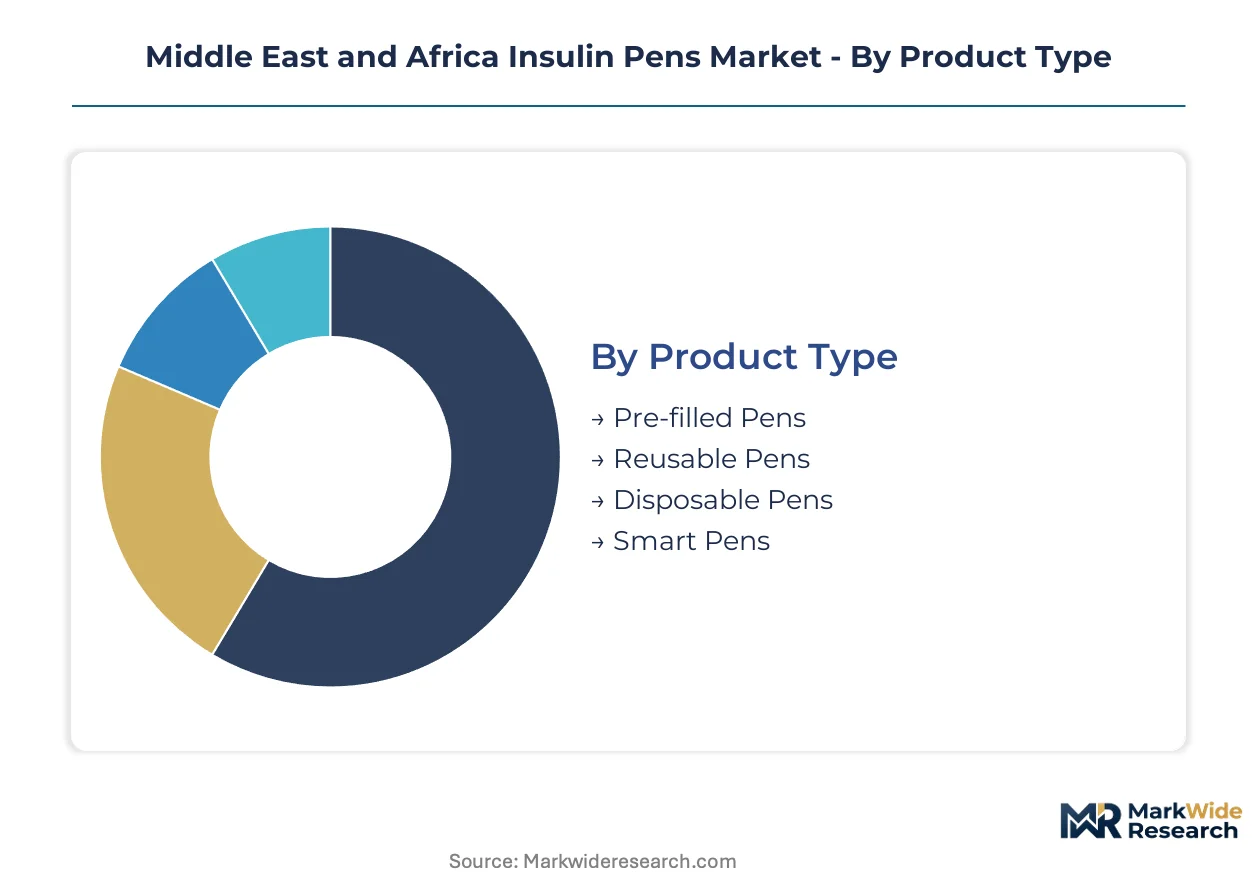
Insulin pen segmentation in the Middle East and Africa reflects divergent patient economics, clinical infrastructure maturity, and digital adoption curves across Gulf and sub-Saharan markets. Product form factors, delivery settings, and injection technologies each create distinct competitive battlegrounds for manufacturers navigating SFDA and MOHAP regulatory pathways.
Product Type:
Cost tier determines patient access and procurement channel concentration across regional healthcare systems.
- Pre-filled Pens:Single-use devices arrive factory-loaded with insulin cartridges, eliminating patient handling of vial transfers. Demand concentrates in Saudi hospital procurement networks where NUPCO framework agreements prioritize sealed-unit sterility for inpatient glycemic management.
- Reusable Pens:Durable mechanical housings accommodate replaceable insulin cartridges over multi-year service lives. These devices dominate Egyptian and Algerian retail pharmacy channels where out-of-pocket cost sensitivity drives cartridge replacement economics over disposable alternatives.
- Disposable Pens:Fully integrated single-use units combining reservoir and mechanism in one sealed assembly. These products serve emergency and travel use cases in UAE private clinics.
- Smart Pens:Bluetooth-enabled devices with embedded dose sensors and mobile application integration. Adolescent Type 1 diabetes programs in Dubai and Riyadh are piloting these platforms for adherence monitoring.
Pre-filled pens hold installed capacity. Smart pens are rotating up the share rankings.
End User:
Application setting dictates device specification requirements and purchasing authority structures.
- Hospitals:Acute care facilities require high-volume insulin delivery systems with standardized dosing protocols. Saudi Arabia's Ministry of Health central procurement through NUPCO aggregates demand for pre-filled pens across tertiary care centers in Riyadh, Jeddah, and Dammam.
- Homecare:Self-administration settings demand intuitive dose-dial mechanisms and minimal training requirements. South Africa's shifting Type 2 diabetes protocols are migrating stable patients from outpatient clinics to home-based pen therapy, expanding volumes in Johannesburg and Cape Town metropolitan areas.
- Clinics:Outpatient endocrinology practices balance device cost against patient education burdens. Private diabetes centers in Kuwait City favor reusable pen systems for long-term patient relationships.
- Pharmacies:Retail distribution points serve cash-pay patients without prescription coverage. Moroccan pharmacy networks are expanding analog insulin pen availability as national reimbursement registries broaden eligibility.
Hospital procurement concentrates purchasing power. Homecare is climbing the fastest as a volume contributor.
Delivery Mode:
Injection depth and tissue targeting define pharmacokinetic performance and clinical indication alignment.
- Subcutaneous:Fatty tissue deposition enables slow, sustained insulin absorption matching basal and prandial glucose control needs. This mode dominates all insulin pen designs across Middle East and African markets due to patient self-administration feasibility.
- Intramuscular:Muscle tissue injection accelerates insulin onset for emergency hyperglycemic management. Hospital crash carts in South African academic medical centers stock intramuscular-capable devices for diabetic ketoacidosis protocols.
- Intravenous:Direct vascular delivery enables immediate bioavailability for critical care scenarios. ICU settings in UAE private hospital networks maintain IV-capable pen systems for perioperative glucose management.
- Others:Alternative delivery modes including intradermal and peritoneal routes serve specialized clinical research applications.
Subcutaneous delivery holds installed capacity. Intravenous is rotating up the share rankings in critical care segments.
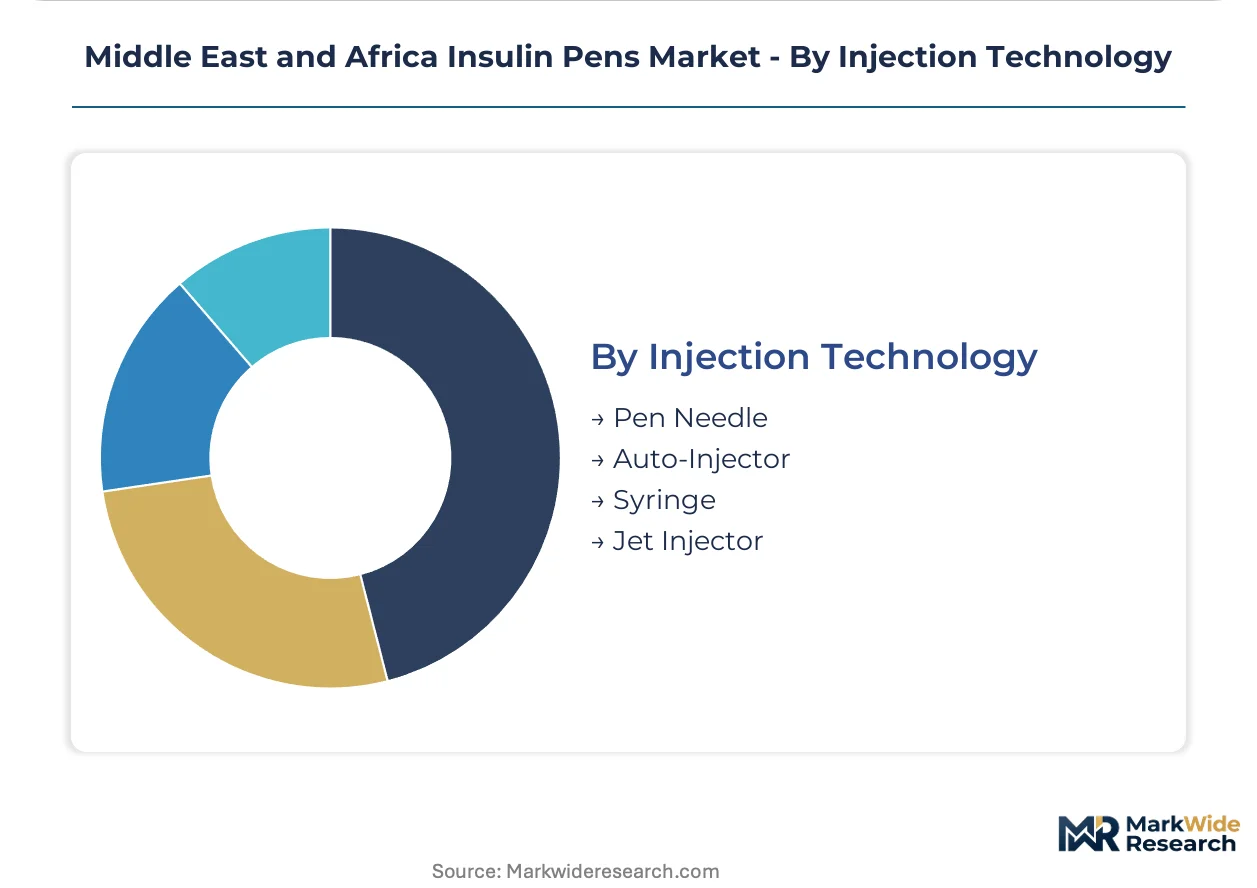
Injection Technology:
Needle mechanics and patient interface design determine pain perception, dosing accuracy, and waste generation profiles.
- Pen Needle:Fine-gauge disposable attachments screw onto pen devices for subcutaneous puncture. Egyptian and Sudanese markets show expanding demand for ultra-fine 4mm and 5mm needle lengths reducing injection anxiety in pediatric populations.
- Auto-Injector:Spring-loaded mechanisms automate needle insertion and medication delivery with single-button activation. These devices serve needle-phobic patients in Gulf private healthcare networks where premium pricing tolerates mechanical complexity.
- Syringe:Traditional vial-and-syringe administration persists in resource-constrained settings. Rural clinics in Ethiopia and Kenya continue syringe-based insulin delivery where pen device procurement budgets remain constrained.
- Jet Injector:Needle-free systems using high-pressure fluid streams penetrate skin for medication deposition. These technologies occupy niche cosmetic and research applications in South African academic centers.
Pen needle systems hold installed capacity. Auto-injector platforms are gaining share fastest among premium private pay segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE-manufactured insulin pens flow into Saudi hospital procurement networks while South African distributors serve as the primary gateway for sub-Saharan African markets. Trade corridors link Gulf production hubs with North African demand centers through temperature-controlled logistics chains.
Saudi Arabia
NUPCO framework agreements aggregate hospital demand for pre-filled pens across tertiary care centers in Riyadh and Jeddah. SFDA biosimilar pathways accelerate registration timelines for analog insulin formulations. The Eastern Province manufacturing corridor hosts formulation facilities supplying domestic and Gulf export markets.
United Arab Emirates
MOHAP quality mandates tighten software validation requirements for connected pen devices entering private healthcare networks. Dubai's diabetes centers pilot Bluetooth-enabled adherence monitoring for adolescent Type 1 cohorts. Julphar's Sharjah production base supplies cost-efficient reusable pens across North African export markets.
South Africa
Johannesburg academic hospital networks consolidate insulin purchasing into therapeutic category management frameworks. The national health products regulator enforces parallel climatic zone stability testing that extends device registration timelines. Cape Town metropolitan clinics drive homecare migration for stable Type 2 diabetes patients.
Egypt
Retail pharmacy channels in Cairo and Alexandria dominate reusable pen distribution for out-of-pocket paying patients. Cold chain integrity gaps persist in rural Upper Egypt distribution networks. Government diabetes registry expansion broadens analog insulin reimbursement eligibility.
Morocco
National health insurance reforms create whitespace for pre-filled pen market entry as reimbursement coverage widens. Casablanca serves as the Maghreb distribution hub for European and Gulf-sourced devices. Private endocrinology clinics in Rabat favor premium auto-injector systems for needle-phobic patient segments.
Middle East and Africa Insulin Pens Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways. Gulf hospital networks favor consolidated framework agreements while North African retail channels fragment across pharmacy-level purchasing. Three archetypes dominate: multinational pharmaceutical conglomerates with biosimilar manufacturing depth, regional generic manufacturers competing on cartridge replacement economics, and medical device specialists supplying pen needle and auto-injector components. Competitive moves concentrate on distribution partnership consolidation and connected device cybersecurity certification.
Within the multinational tier, Novo Nordisk and Eli Lilly and Company anchor regional positioning through contrasting channel strategies. Novo Nordisk leverages biosimilar manufacturing depth to sustain supply continuity across Gulf markets. Eli Lilly and Company exemplifies hospital procurement network anchoring through centralized tender participation. Julphar occupies a position as the regional cost-efficient manufacturer, with its UAE base serving export markets where reusable pen economics outperform disposable alternatives.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| Julphar |
| Biocon |
| Wockhardt |
| Becton Dickinson and Company |
| Ypsomed |
| Medtronic |
| Others |
Supply & Pricing Matrix
Jebel Ali Port's temperature-controlled freight corridors impose cost premiums that cascade through Gulf distribution networks, concentrating supply power among manufacturers with captive cold-chain infrastructure while fragmenting downstream price tiers between hospital procurement networks and retail pharmacy channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-enabled smart pens from conventional pre-filled devices and basic reusable alternatives. Certification grade under SFDA and MOHAP pathways, combined with volume scale in NUPCO framework agreements, drives price differentiation between compliant and non-compliant suppliers. Pricing pressure stems from cartridge replacement economics in Egyptian and Algerian retail channels where out-of-pocket patients optimize lifetime device costs. Homecare settings in South Africa exhibit highest price sensitivity, while UAE private clinic networks tolerate premium positioning for connected adherence monitoring.
Supply Chain Analysis
Import dependency for active pharmaceutical ingredients between concentrated Asian manufacturing bases and regional formulation facilities dominates supply risk architecture for Middle East and African insulin pen markets. API production concentrates in China, India, and South Korea, with device assembly anchored in UAE, Saudi Arabia, and South Africa. Insulin crystal formulations, precision-machined dose-dial mechanisms, and medical-grade polymers constitute critical input dependencies. Single-source vulnerability in temperature-sensitive API freight exposes formulation continuity to geopolitical disruption. Distribution runs through hospital procurement organizations in Gulf markets and fragmented pharmacy wholesale networks in North Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected pen technology is disrupting traditional dosing paradigms across Middle East and African diabetes care, with SFDA's 2024 software validation mandates accelerating competitive separation between cybersecurity-capable manufacturers and legacy hardware suppliers.
For Market Incumbents: Build regulatory moats through accelerated SFDA and MOHAP cybersecurity certification for Bluetooth-enabled platforms before compliance timelines harden. Defend hospital procurement network positioning by embedding data analytics subscriptions within NUPCO and MOHAP framework agreements. Julphar's regional manufacturing scale and Novo Nordisk's biosimilar depth represent template defensive postures against emerging connected-device specialists. For New Entrants and Emerging Players: Build out distribution partnerships in Morocco and Algeria where national health insurance reforms are expanding analog insulin reimbursement eligibility. North African retail pharmacy channels offer lowest competitive density for pre-filled pen market entry. Target adolescent Type 1 diabetes programs in Dubai and Riyadh with pilot-focused smart pen offerings that demonstrate adherence outcomes before scaling procurement negotiations. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical parents seeking to divest legacy mechanical pen portfolios amid connected-device R&D prioritization. Long-term viability hinges on software-enabled recurring revenue models replacing transactional device sales. Watch for SFDA cybersecurity enforcement acceleration as inflection signal separating compliant from stranded manufacturing assets.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Cybersecurity Certification | Accelerates market access timelines for Bluetooth-enabled dose logging devices in Saudi hospital networks. |
| MOHAP Framework Agreement Participation | Consolidates purchasing power for compliant manufacturers across UAE's centralized hospital procurement system. |
| North African Distribution Partnership | Captures whitespace in Moroccan and Algerian retail pharmacy channels expanding analog insulin access. |
| Smart Pen Data Analytics Bundling | Transforms device economics from unit sales to subscription revenue in Johannesburg academic hospital networks. |
| API Supply Diversification | Reduces formulation continuity risk from concentrated Asian manufacturing bases facing geopolitical freight disruption. |
Research Methodology
A spread of perspectives from endocrinology clinic directors, hospital procurement managers, GPO contracts specialists, and regulatory affairs leads at SFDA and MOHAP converged on the working assumptions shaping this analysis. Primary field engagement combined with secondary validation from FDA filings, EMA submissions, hospital procurement databases, and GPO contract disclosures established foundational demand and supply parameters. Bottom-up patient volume modeling and top-down healthcare expenditure triangulation cross-verified segmentation outputs across product type, end user, and delivery mode dimensions.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with patient migration from hospital to homecare settings and connected device adoption curves constituting primary demand drivers. Segmentation modeling incorporated product form factor, application setting, injection technology, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to base-year estimates validated against procurement volume disclosures and distributor shipment data. Insulin analog formulation trends, cold-chain infrastructure development, and reimbursement registry expansion provided industry-specific forecast inputs.
Sensitivities concentrate around SFDA software validation timeline acceleration, MOHAP cybersecurity enforcement intensity, and API freight corridor stability throughout the forecast period. Forecasts reflect documented assumptions regarding patient adherence improvement from connected devices and public hospital procurement centralization trajectories. Macroeconomic currency volatility, regulatory pathway modification, or connected device technology disruption would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market
Diabetes Care
Spain Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market
Diabetes Care
Saudi Arabia Diabetes Care Devices Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
Australia Blood Glucose Monitoring Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Korea Continuous Glucose Monitoring Devices Market
Diabetes Care
Diabetic Footwear Market
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
Germany Digital Diabetes Management Market