
 Asia Pacific Hair Loss Treatment Products Market | 2026-2036
Asia Pacific Hair Loss Treatment Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Hair Loss Treatment Products Market Outlook
Premium biologic formulations and mass-market minoxidil solutions is decoupling across pricing, distribution, and clinical positioning in the Asia Pacific Hair Loss Treatment Products Market. Procter & Gamble Co leverages its retail scale to dominate over-the-counter topical shelves in Southeast Asian pharmacies. Shiseido Co., Ltd. anchors its position through R&D intensity in cellular scalp therapies targeted at Japanese consumers. Taisho Pharmaceutical Holdings Co. Ltd. specializes in oral finasteride combinations distributed through physician channels.
Asia Pacific hair loss treatment products encompass pharmacological agents, surgical interventions, and energy-based devices designed to arrest follicular miniaturization or restore hair density through modulation of androgenic pathways, vascularization, or stem-cell signaling. Minoxidil and finasteride remain the backbone of medical management, though low-level laser therapy gains traction as a non-invasive adjunct with measurable increases in terminal hair count. Among end users, males occupy the largest volume share due to higher androgenetic alopecia prevalence, while clinics capture expanding margin pools as procedural therapies migrate from hospital settings. Device-based delivery modes represent the fastest-growing structural segment, propelled by South Korean manufacturing clusters and Chinese regulatory streamlining for home-use laser caps.
Japan's PMDA enforces stringent stability testing for topical combinations, while China's NMPA accelerates approvals for Class II laser devices under revised medical device catalogs. India's CDSCO requires bioequivalence documentation for generic finasteride imports, shaping formulation sourcing decisions for multinational suppliers. Stakeholders must monitor divergence between pharmaceutical-grade registration pathways and cosmetic-tier positioning as regulators recategorize active-ingredient thresholds.
Market Dynamics
Device-based delivery modes are decoupling from pharmaceutical protocols as South Korean manufacturing clusters scale low-level laser therapy production for home-use applications, creating parallel treatment ecosystems that bypass traditional clinic gatekeepers.
Growth Catalysts
- China's NMPA Class II laser device pathway:Streamlined approvals under revised medical device catalogs accelerate market entry for home-use laser caps, reducing registration timelines for domestic and foreign manufacturers targeting tier-one city consumers.
- Japanese male pattern baldness awareness campaigns:Dermatology chains in Tokyo and Osaka report elevated clinic visit rates as educational initiatives normalize early intervention, expanding the addressable patient base beyond severe cases.
- Low-level laser therapy manufacturing clusters:Concentrated production capabilities in Gyeonggi Province drive unit cost reductions and supply reliability for regional distribution networks.
Market Restraints
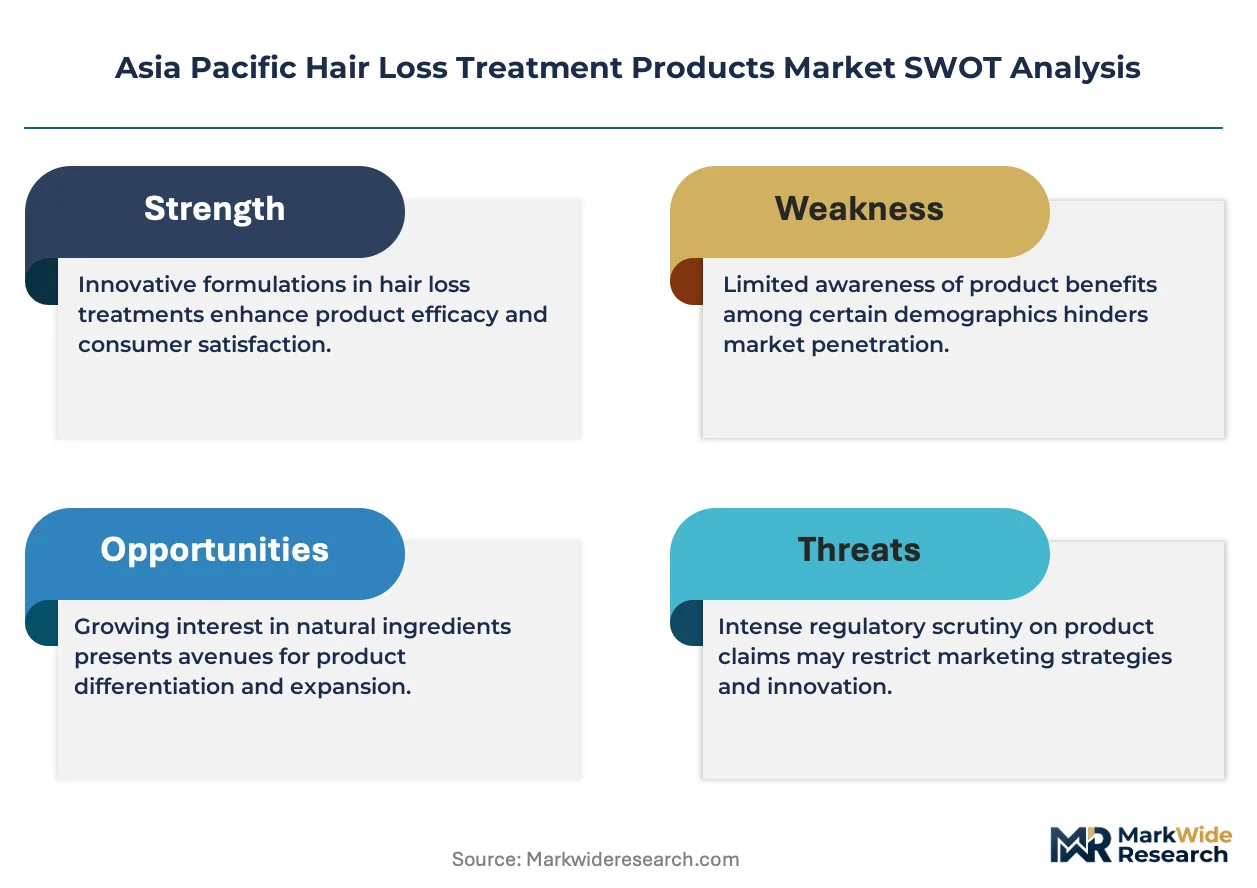
- Active pharmaceutical ingredient concentration thresholds:Divergent cosmetic-tier versus pharmaceutical-grade categorization across national regulators creates formulation complexity and compliance duplication costs for topical combination products.
- Import dependency for generic finasteride:India's CDSCO bioequivalence documentation requirements constrain sourcing flexibility for multinational suppliers, concentrating supply risk with approved contract manufacturers.
- Limited follicular stem-cell signaling modulation:Cellular scalp therapies face reproducibility challenges in terminal hair count outcomes, restricting clinical positioning against established pharmacological benchmarks.
Strategic Opportunities
- Indonesia's underpenetrated pharmacy retail network:Over-the-counter topical shelves in Jakarta and Surabaya remain dominated by basic minoxidil formulations, creating white space for differentiated biologic positioning.
- Combination therapy regulatory convergence:Japan's PMDA stability testing frameworks for topical combinations, once satisfied, enable accelerated dossier reuse across ASEAN mutual recognition pathways.
- Telemedicine-enabled prescription channels:Digital health platforms in Australia and Singapore are expanding physician-supervised oral finasteride distribution beyond traditional clinic footprints.
Industry Challenges
- Trichology specialist scarcity:Qualified practitioners for device-based procedural therapies remain concentrated in Seoul and Tokyo, constraining clinic network expansion into secondary Chinese cities.
- Cross-border e-commerce compliance fragmentation:Divergent cosmetic-versus-medical device classifications for laser caps create customs clearance delays and post-purchase regulatory exposure for direct-to-consumer shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Hair Loss Treatment Products Market |
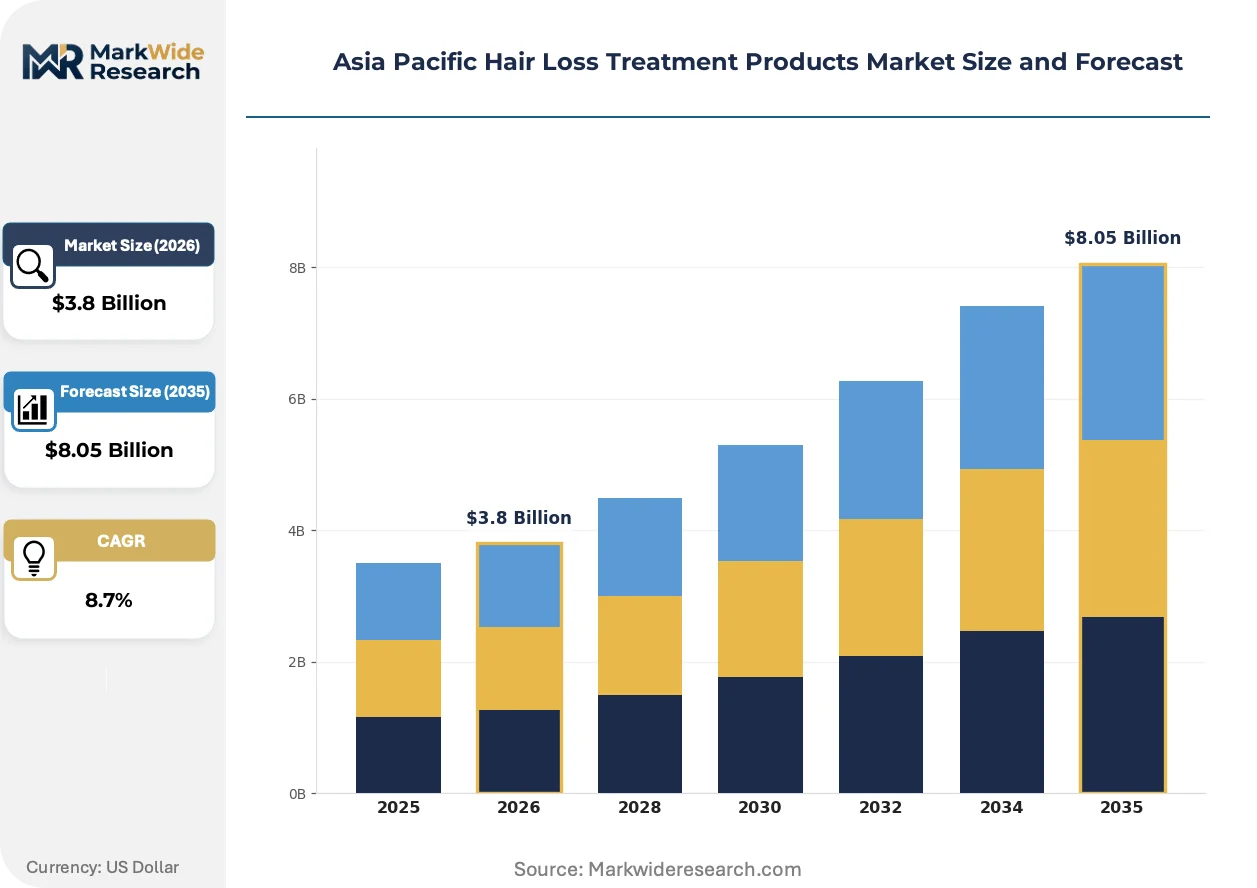
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minoxidil, Finasteride, Hair Transplant, Low-Level Laser Therapy End User: Males, Females, Clinics, Home Users Delivery Mode: Topical, Oral, Device-Based, Injectable Ingredient Type: Natural, Synthetic, Herbal, Others |
| Companies Covered | Procter & Gamble Co, The Himalaya Drug Company, Shiseido Co., Ltd., Taisho Pharmaceutical Holdings Co. Ltd., Merck & Co., Inc., Sun Pharmaceutical Industries Ltd, Johnson & Johnson Services, Inc., Dr. Reddy’s Laboratories Ltd, L'Oréal S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Hair Loss Treatment Products Market Strategic Shifts
Convergence between energy-based devices and biologic delivery systems is redefining treatment protocols across the Asia Pacific region, with manufacturers and clinics competing to integrate hardware and formulation into unified therapeutic regimens.
Low-level laser therapy is expanding into home-use applications as South Korean manufacturers achieve cost parity with clinic-based devices. Middle-income consumers in China's tier-two cities now represent the fastest-adopting segment for laser cap purchases. This technology is compressing the traditional clinic-centric treatment model by enabling unsupervised maintenance protocols between professional visits.
PMDA's stability testing requirements for topical combination products are forcing reformulation investments among Japanese manufacturers. The industrial consequence is extended registration timelines for novel delivery vehicles, but accelerated post-approval market exclusivity periods. Combination therapy developers targeting the Japanese market are responding by front-loading clinical endpoint documentation to offset regulatory friction.
Subscription-based replenishment models for topical solutions are displacing episodic pharmacy purchases in Australia's major metropolitan areas. Direct-to-consumer platforms are capturing recurring revenue streams previously controlled by retail pharmacy chains. This behavioral shift is most visible among male consumers aged 25-40 in Sydney and Melbourne, where convenience positioning outweighs price sensitivity.
Asia Pacific Hair Loss Treatment Products Market Segmentation
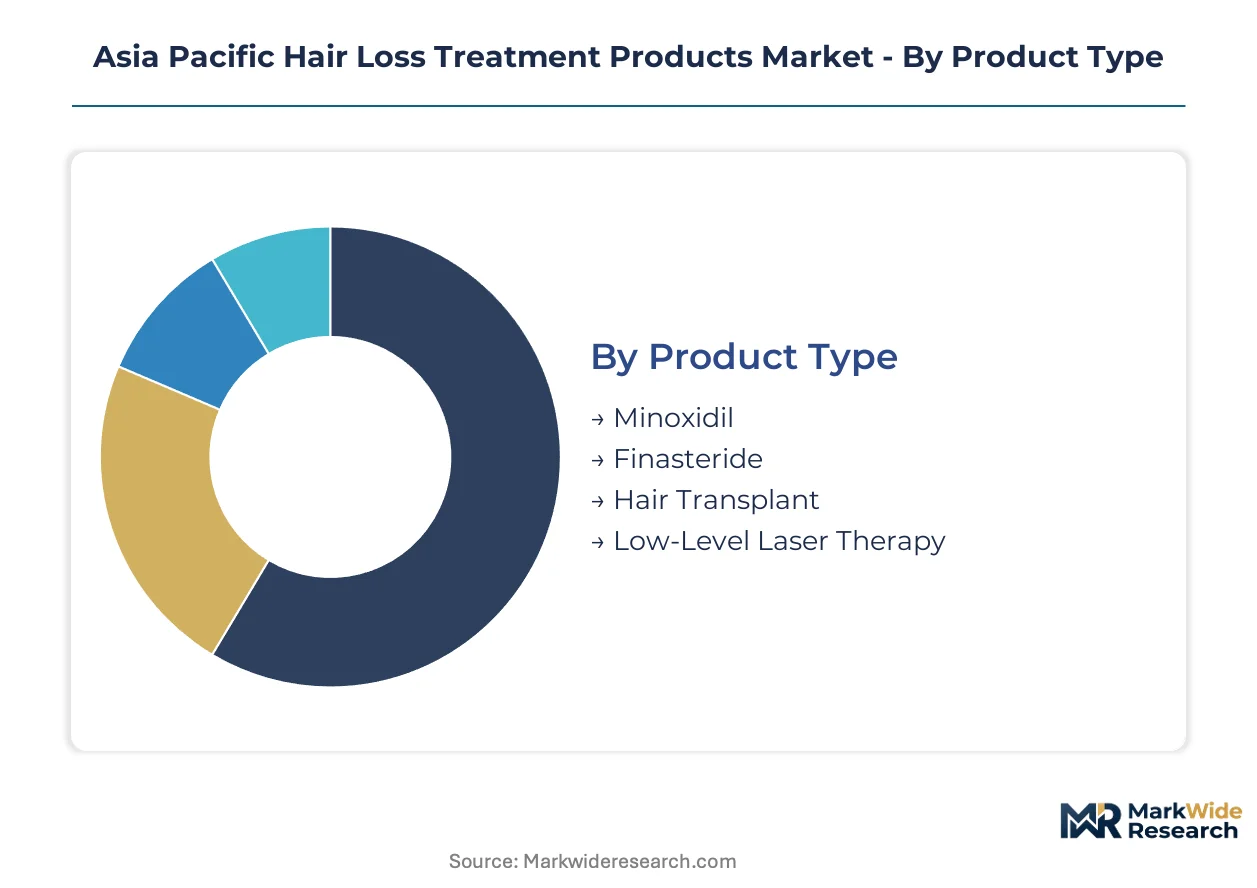
Segmentation across the Asia Pacific hair loss treatment products market reveals divergent regulatory pathways and pricing architectures. Product categories face distinct certification burdens from PMDA, NMPA, and CDSCO, while end-user channels determine margin capture and distribution complexity.
Product Type:
Certification requirements fragment sharply across this category: pharmaceutical-grade minoxidil and finasteride demand NMPA drug approvals with bioequivalence documentation, while low-level laser therapy navigates Class II medical device pathways and hair transplant procedures fall under surgical practice licensure.
- Minoxidil:Topical vasodilator formulations dominate pharmacy shelves across Southeast Asia. Demand concentrates in China's tier-one cities where male pattern baldness awareness campaigns drive early intervention purchases through retail channels.
- Low-Level Laser Therapy:Photobiomodulation devices stimulate follicular vascularization through coherent light emission. South Korean manufacturing clusters in Gyeonggi Province supply regional distributors as home-use laser caps gain traction among middle-income consumers in tier-two Chinese cities.
- Finasteride:5-alpha-reductase inhibitor requiring prescription oversight through physician channels in Japan and Australia.
- Hair Transplant:Follicular unit extraction procedures concentrated in Seoul and Tokyo clinic networks.
Minoxidil sits at the top of the volume ranking, with low-level laser therapy climbing the fastest.
End User:
Customer archetypes determine pricing elasticity and channel strategy, with males and clinics representing divergent margin pools and home users emerging as a disruptive force bypassing traditional gatekeepers.
- Males:Primary volume driver due to androgenetic alopecia prevalence. Australian metropolitan markets show subscription-based replenishment behavior displacing episodic pharmacy purchases among consumers aged 25-40.
- Clinics:Dermatology chains in Tokyo and Osaka capture procedural therapy margins as device-based treatments migrate from hospital settings. Trichology specialist scarcity constrains network expansion into secondary Chinese cities.
- Females:Telogen effluvium and pattern hair loss indications requiring differentiated formulation positioning.
- Home Users:Direct-to-consumer laser cap adoption accelerating through cross-border e-commerce platforms.
Males command the largest revenue share, though home users are expanding most quickly through digital channels.
Delivery Mode:
Route of administration shapes manufacturing investment and regulatory friction, with device-based modalities decoupling from pharmaceutical supply chains to establish parallel ecosystems.
- Device-Based:Low-level laser therapy and radiofrequency systems manufactured in South Korean clusters achieve cost parity with clinic equipment. NMPA's revised medical device catalogs streamline Class II approvals for regional manufacturers targeting domestic Chinese consumers.
- Topical:Solutions and foams face PMDA stability testing requirements for combination formulations, extending Japanese registration timelines but securing extended market exclusivity post-approval.
- Oral:Finasteride tablets distributed through physician-supervised channels with CDSCO bioequivalence documentation for Indian imports.
- Injectable:Platelet-rich plasma and cellular therapies limited by reproducibility challenges in terminal hair outcomes.
Topical formulations maintain volume leadership, while device-based delivery gains share fastest through home-use penetration.
Ingredient Type:
Source classification determines cosmetic-versus-pharmaceutical tier positioning across national regulators, with synthetic actives facing stricter concentration thresholds than botanical derivatives.
- Synthetic:Minoxidil and finasteride formulations subject to pharmaceutical-grade registration with full clinical documentation requirements in Japan and Australia.
- Natural:Saw palmetto and peptide extracts positioned in cosmetic-tier channels with reduced regulatory burden but limited clinical claim latitude.
- Herbal:Traditional Chinese medicine-derived ingredients prevalent in Indonesia's underpenetrated pharmacy retail network.
- Others:Stem-cell signaling modulators and exosome preparations facing reproducibility constraints in commercial applications.
Synthetic ingredients anchor revenue concentration, with natural formulations expanding fastest through clean-label positioning in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trichology specialists cluster in Seoul and Tokyo, anchoring procedural therapy capacity across the Asia Pacific region while manufacturing gravity shifts toward South Korean device production hubs.
China
Male pattern baldness awareness campaigns in Beijing and Shanghai accelerate clinic visits among professionals aged 25-40. NMPA's revised medical device catalogs streamline Class II approvals for home-use laser caps, compressing registration timelines for domestic and foreign manufacturers. Manufacturing activity concentrates in Shenzhen and Suzhou, where contract assemblers scale production of photobiomodulation devices for tier-one city distribution.
Japan
Dermatology chains in Tokyo and Osaka report elevated procedural volumes as educational initiatives normalize early intervention for androgenetic alopecia. PMDA enforces stringent stability testing requirements for topical combination products, extending registration timelines but securing extended market exclusivity post-approval. Osaka-based formulation houses invest in front-loaded clinical endpoint documentation to offset regulatory friction.
South Korea
Gyeonggi Province manufacturing clusters achieve cost parity between home-use and clinic-grade low-level laser therapy equipment. MFDS oversees medical device registration for laser caps targeting domestic and export markets. Seoul's clinic networks drive adoption of device-based therapies, with trichology specialists concentrated in Gangnam and Seocho districts.
Australia
Subscription-based replenishment models for topical solutions displace episodic pharmacy purchases in Sydney and Melbourne among male consumers aged 25-40. TGA regulates pharmaceutical-grade minoxidil and finasteride distribution through physician-supervised channels. Telemedicine platforms expand prescription access beyond traditional clinic footprints in metropolitan markets.
India
Generic finasteride imports face CDSCO bioequivalence documentation requirements, constraining sourcing flexibility for multinational suppliers. Mumbai and Bangalore anchor pharmaceutical formulation activity for domestic and export markets. Physician-channel distribution of oral 5-alpha-reductase inhibitors concentrates in urban dermatology networks.
Asia Pacific Hair Loss Treatment Products Market Competitive Environment
Capital-heavy producers compete with asset-light designers across pharmaceutical, device, and cosmetic-tier positioning. The market structures around three tiers: multinational consumer goods conglomerates with retail pharmacy scale, pharmaceutical specialists with physician-channel access, and device manufacturers with South Korean production clusters. Strategic moves concentrate on portfolio diversification into combination therapies and geographic expansion through regulatory dossier reuse across ASEAN mutual recognition pathways.
Among pharmaceutical specialists, Taisho Pharmaceutical Holdings Co. Ltd. and Sun Pharmaceutical Industries Ltd. exemplify the physician-channel archetype with oral finasteride positioning. Shiseido Co., Ltd. anchors the premium cosmetic-tier segment through cellular scalp therapy investments. These three occupy distinct competitive spaces defined by distribution mode rather than direct product confrontation.
| Leading Market Players |
|---|
| Procter & Gamble Co |
| The Himalaya Drug Company |
| Shiseido Co., Ltd. |
| Taisho Pharmaceutical Holdings Co. Ltd. |
| Merck & Co., Inc. |
| Sun Pharmaceutical Industries Ltd |
| Johnson & Johnson Services, Inc. |
| Dr. Reddy's Laboratories Ltd |
| L'Oréal S.A. |
| Others |
Value Chain & Pricing Dynamics
Trichology specialist concentration in Seoul and Tokyo creates labor-cost differentials that widen pricing-tier spreads between procedural clinic therapies and home-use device alternatives. South Korean manufacturing clusters compress hardware production costs, enabling mid-market laser caps to undercut Japanese clinic-based service bundles while maintaining margin structures.
Pricing Analysis
The bundled-versus-unbundled service split separates premium clinic protocols from direct-to-consumer hardware purchases. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service intensity. Cost compression in economy-tier minoxidil formulations is intensifying because of pharmacy retail consolidation in Southeast Asia. Home users aged 25-40 in Australian metropolitan markets show least price sensitivity due to subscription convenience positioning, while Indonesian pharmacy shoppers remain most responsive to unit-price differentials.
Supply Chain Analysis
Reverse-logistics flows for home-use laser caps remain underdeveloped, creating warranty-service bottlenecks that constrain brand loyalty building. Manufacturing concentrates in South Korea, China, and Japan, with Gyeonggi Province anchoring photobiomodulation device assembly and Shenzhen housing contract electronics assemblers. Semiconductor laser diodes and medical-grade plastics draw from Taiwan and Japan, exposing producers to single-source vulnerability in precision optical components. Distribution runs through dermatology chain procurement offices in Tokyo and cross-border e-commerce platforms serving Chinese tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NMPA's streamlined Class II medical device pathway for laser caps accelerates demand generation through compressed approval timelines.
For Market Incumbents: Anticipate margin compression in topical minoxidil segments as private-label pharmacy brands proliferate across Indonesia's underpenetrated retail network. Defensive consolidation through backward integration into South Korean laser diode supply chains secures component cost control against Taiwanese supplier concentration. Certification investment in PMDA stability testing frameworks enables dossier reuse across ASEAN mutual recognition pathways, extending effective exclusivity periods for combination formulations. For New Entrants and Emerging Players: Telemedicine-enabled prescription platforms represent the most penetrable technology-first wedge for oral finasteride distribution beyond traditional clinic footprints in Australia and Singapore. White-space targets concentrate in Indonesia's pharmacy retail network and India's generic formulation export channels. A physician-partnership go-to-market angle bypasses retail pharmacy gatekeepers while capturing recurring revenue through compliance monitoring services. For Investors and Strategic Acquirers: Consumer health conglomerates with existing dermatology portfolios are the most active acquirer in this space, seeking device-formulation combination capabilities. Long-term viability hinges on regulatory dossier asset durability and manufacturing cluster access rather than brand equity alone. Acquisition target archetypes include South Korean laser device specialists with MFDS registration assets and Japanese formulation houses with front-loaded clinical documentation. Monitor NMPA medical device catalog revisions for early signals of home-use laser cap reclassification risk.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Reuse Across ASEAN | PMDA stability testing documentation accelerates MFDS and NMPA parallel submissions for combination therapies. |
| Backward Integration Into Laser Diode Supply | Captive semiconductor sourcing from Taiwanese foundries reduces exposure to single-source optical component constraints. |
| Telemedicine Platform Partnership | Digital health licensing in Australia expands physician-supervised finasteride access beyond Sydney clinic footprints. |
| Clinic Network Acquisition in Secondary Chinese Cities | Trichology specialist scarcity in Chengdu and Hangzhou creates first-mover advantage in procedural therapy capacity. |
| Subscription Replenishment Model Deployment | Recurring revenue capture among Melbourne consumers aged 25-40 displaces episodic pharmacy purchase behavior. |
Study Parameters
Direct dialogue with dermatology chain procurement directors, trichology clinic operators, pharmaceutical regulatory affairs leads, and medical device distribution managers anchored qualitative assessment. Secondary validation drew from NMPA medical device registration databases, PMDA approval documentation, MFDS filings, CDSCO bioequivalence records, and customs trade data for laser device components. Bottom-up demand modeling across end-user segments triangulated against top-down manufacturer capacity assessments.
Segmentation outputs span product type, delivery mode, ingredient classification, and geographic regulatory cluster across the projection horizon. CAGRs derived from regression analysis of historical approval velocity, clinic visit trend data, and device shipment records through manufacturing clusters. Forecast inputs incorporate NMPA catalog revision impacts on registration timelines and PMDA stability testing burden effects on formulation launch schedules.
The model holds under stable regulatory classification frameworks; deviation in laser cap cosmetic-versus-medical device recategorization would shift channel economics and margin structures. Practitioners should monitor ASEAN mutual recognition pathway harmonization progress and CDSCO generic finasteride import documentation changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Hair Restoration Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Foot Insole Market
Personal Health
Tick Repellent Market
Personal Health
Medical Wellness Market
Personal Health
Interdental Brush Market
Personal Health
Disposable Underwear Market
Personal Health
Reusable Face Mask Market
Personal Health
Sexual Wellness Market
Personal Health
OTC Health Products Market
Personal Health
Europe Hair Loss Treatment Products Market
Personal Health
North America Workplace Wellness Market
Personal Health
Menopause Wellness Market
Personal Health
Menstrual Cup Market
Personal Health
Asia Health Check-Ups Market
Personal Health
Parents-In-Waiting: Global Prenatal Market