
 Latin America Pharmaceutical Glass Vials and Ampoules Market | 2026-2036
Latin America Pharmaceutical Glass Vials and Ampoules Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Pharmaceutical Glass Vials and Ampoules Market Insights
A capital-intensity divergence between players is unwinding competitive dynamics across the region. Gerresheimer AG leverages its Querétaro facility to anchor high-volume borosilicate production for export markets. Stevanato Group sustains differentiation through integrated inspection and packaging systems tailored to biologics containment. Vitro Glass Containers competes on regional logistics advantages, supplying mid-tier pharmaceutical companies with standardized vial formats.
Pharmaceutical glass vials and ampoules are tubular or molded containers fabricated from borosilicate or soda-lime glass, engineered to meet USP Type I through Type III chemical durability standards for parenteral drug storage. Their primary commercial purpose is to provide inert, impermeable barriers that maintain sterility and chemical stability for injectable pharmaceuticals, vaccines, and biologics throughout shelf life. Vials and ampoules occupy the core volume position, driven by universal compatibility with liquid and lyophilized drug formulations across the product lifecycle. Cartridges are gaining structural momentum as pre-filled delivery systems displace traditional syringe-ampoule workflows in insulin and biologic administration.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce pharmacopeial compliance for glass primary packaging, with ANVISA's recent updates mandating extractables and leachables documentation for all imported containers. These frameworks elevate quality thresholds, filtering out uncertified suppliers and consolidating procurement toward validated manufacturers. Stakeholders must monitor how evolving bioequivalence requirements for generic injectables reshape container qualification timelines and supplier switching costs.
Market Dynamics
ANVISA's extractables and leachables documentation mandate for imported containers is forcing supply base consolidation across Brazil, Mexico, and Colombia. This regulatory compression is elevating switching costs for pharmaceutical manufacturers while filtering uncertified glass suppliers from procurement pools.
Growth Catalysts
- mRNA therapy expansion:Biotechnology firms are scaling borosilicate containment for temperature-sensitive nucleic acid therapeutics, creating specialized demand for USP Type I vials with enhanced thermal stability profiles.
- COFEPRIS traceability frameworks:Mexico's pharmaceutical regulator is mandating serialized packaging documentation, accelerating investments in integrated glass-inspection systems across Baja California manufacturing clusters.
- Pre-filled cartridge adoption:Insulin and biologics manufacturers are displacing traditional syringe-ampoule workflows with glass-cartridge delivery systems, restructuring primary packaging procurement specifications.
Market Restraints
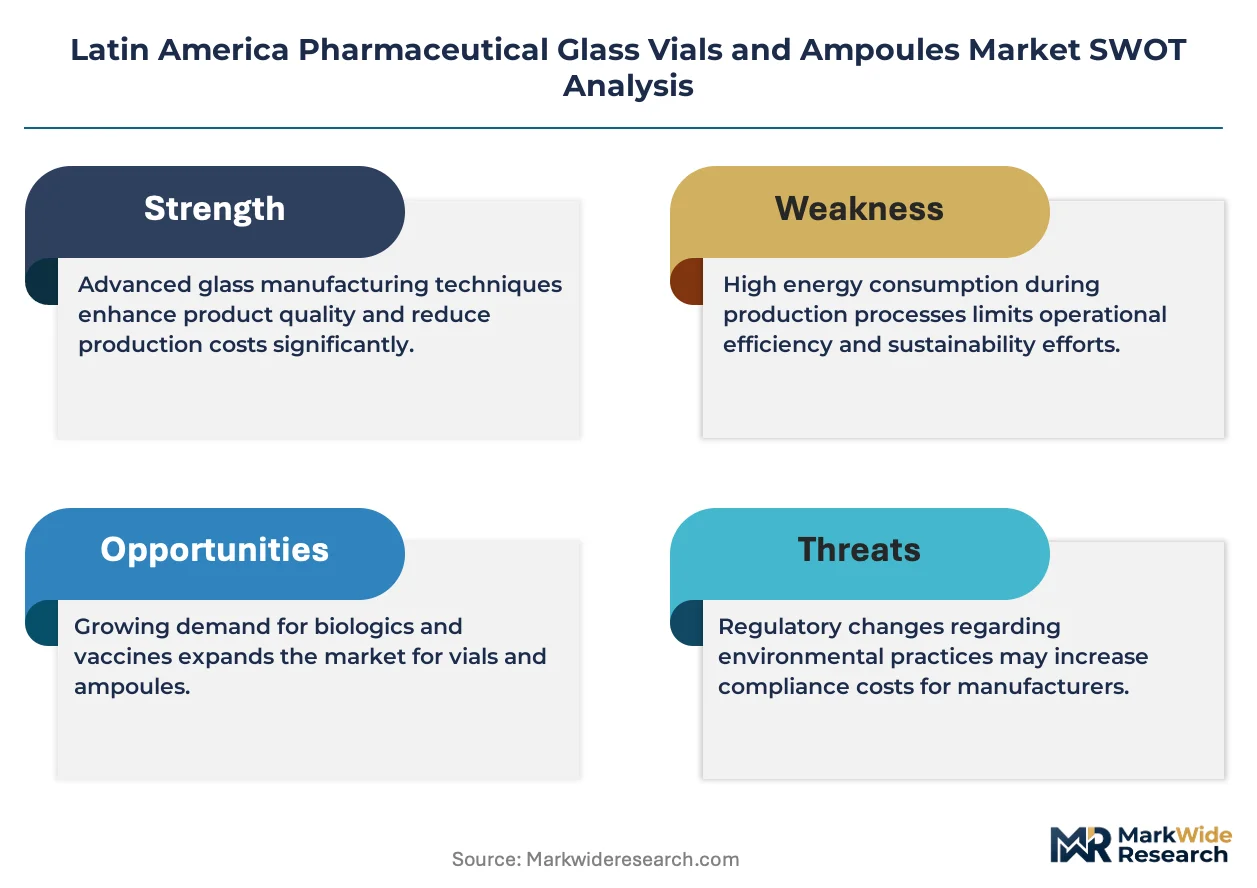
- High-purity silica sand concentration:Raw material supply concentrates in limited geographic sources outside Latin America, exposing converters to currency volatility and freight cost spikes.
- Energy-intensive melting operations:Natural gas and electricity inputs constitute substantial production cost structures, compressing margins when regional energy tariffs fluctuate.
- Plastic polymer substitution:Cyclic olefin polymers and copolymers are penetrating non-biologic injectable segments, threatening soda-lime glass volume in standard parenteral applications.
Strategic Opportunities
- Colombian generic injectables:INVIMA's bioequivalence pathway streamlining is opening container qualification opportunities for mid-tier manufacturers serving Andean pharmaceutical markets.
- Lyophilization-ready formats:Freeze-dried biologics demand is driving specialized vial geometries with optimized headspace and closure integrity specifications.
- Nearshoring manufacturing corridors:Multinational pharmaceutical firms are relocating fill-finish operations to Mexico and Brazil, creating captive demand for regional glass sourcing.
Industry Challenges
- Specialized furnace engineering talent:Borosilicate glass melting requires precise thermal control expertise that concentrates in aging workforce pools across the region.
- USP Type I certification timelines:Container qualification protocols for high-purity biologics extend validation cycles, delaying revenue recognition for new production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Pharmaceutical Glass Vials and Ampoules Market |
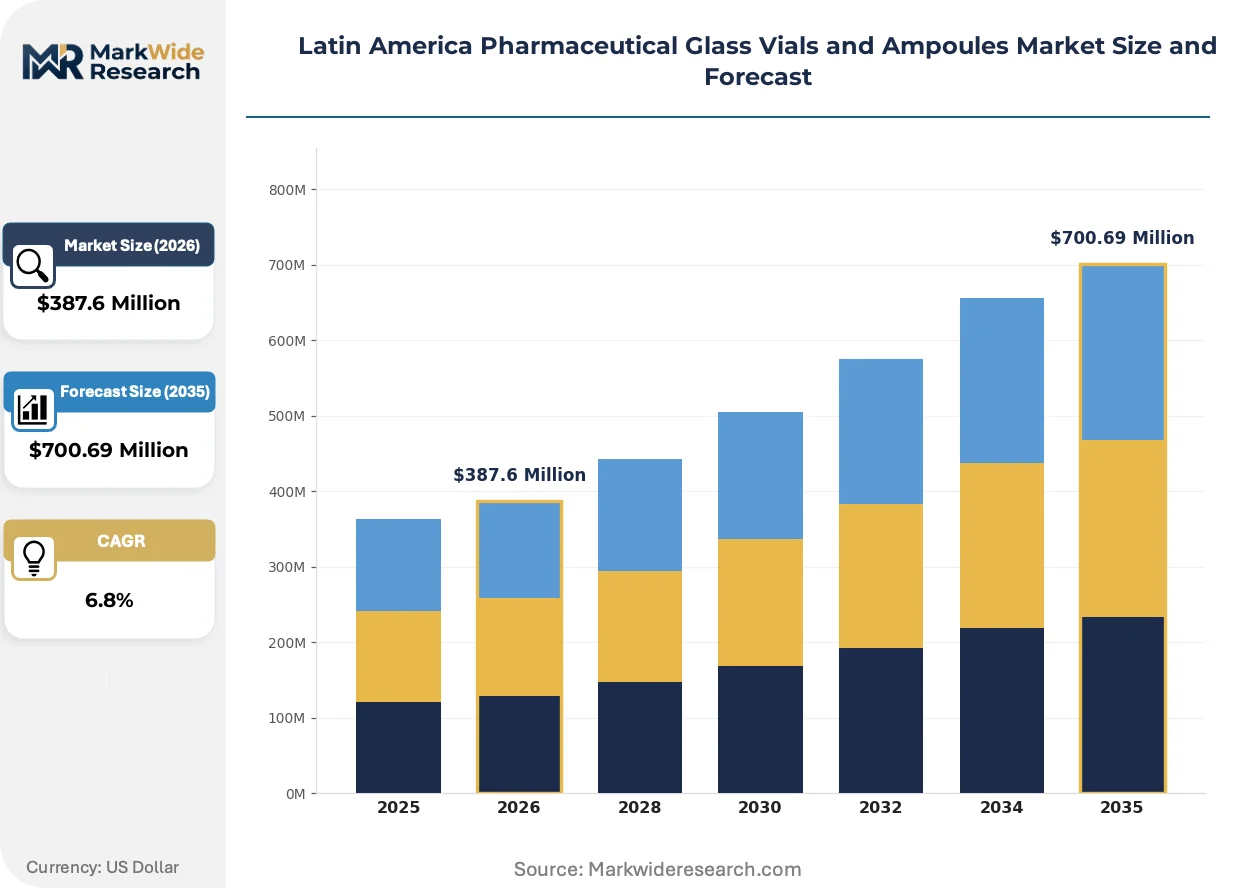
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Cartridges, Bottles End User: Pharmaceutical Companies, Biotechnology Firms, Contract Manufacturing Organizations, Research Institutions Closure Type: Rubber Stoppers, Plastic Caps, Screw Caps, Crimped Seals Capacity: 1 mL, 5 mL, 10 mL, 20 mL |
| Companies Covered | Gerresheimer AG, Scott Pharma, Stevanato Group, Nipro Corporation, SGD Pharma, Schott AG, Vitro Glass Containers, West Pharmaceutical Services, Inc., Gerresheimer Querétaro S.A., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Pharmaceutical Glass Vials and Ampoules Market Trends and Innovations
Container engineering is converging with drug delivery system integration, blurring traditional boundaries between primary packaging and administration devices. This fusion is compressing supplier value chains while elevating technical performance thresholds.
Ready-to-use (RTU) vial formats pre-sterilized and pre-sealed in nested packaging are miniaturizing cleanroom footprint requirements for pharmaceutical fill-finish operations. Contract manufacturing organizations in Mexico's Baja California corridor are adopting these formats to accelerate line changeovers and reduce particulate contamination risks. The technology is compressing capital deployment timelines for new biologics manufacturing facilities.
ANVISA's updated pharmaceutical packaging standards in Brazil are tightening material traceability requirements from raw batch to finished container. This regulatory compression is forcing importers to maintain comprehensive extractables documentation and supplier audit trails. Generic injectable manufacturers are responding by consolidating procurement toward validated regional converters with established compliance infrastructures.
Pharmaceutical buyers are unbundling container supply from inspection and packaging equipment procurement, creating discrete vendor relationships for each function. This purchasing pattern shift is disrupting integrated system suppliers while opening specialized niches for standalone glass converters. The behavior is most visible among mid-tier biotechnology firms in São Paulo and Mexico City seeking operational flexibility.
Latin America Pharmaceutical Glass Vials and Ampoules Market Segmentation
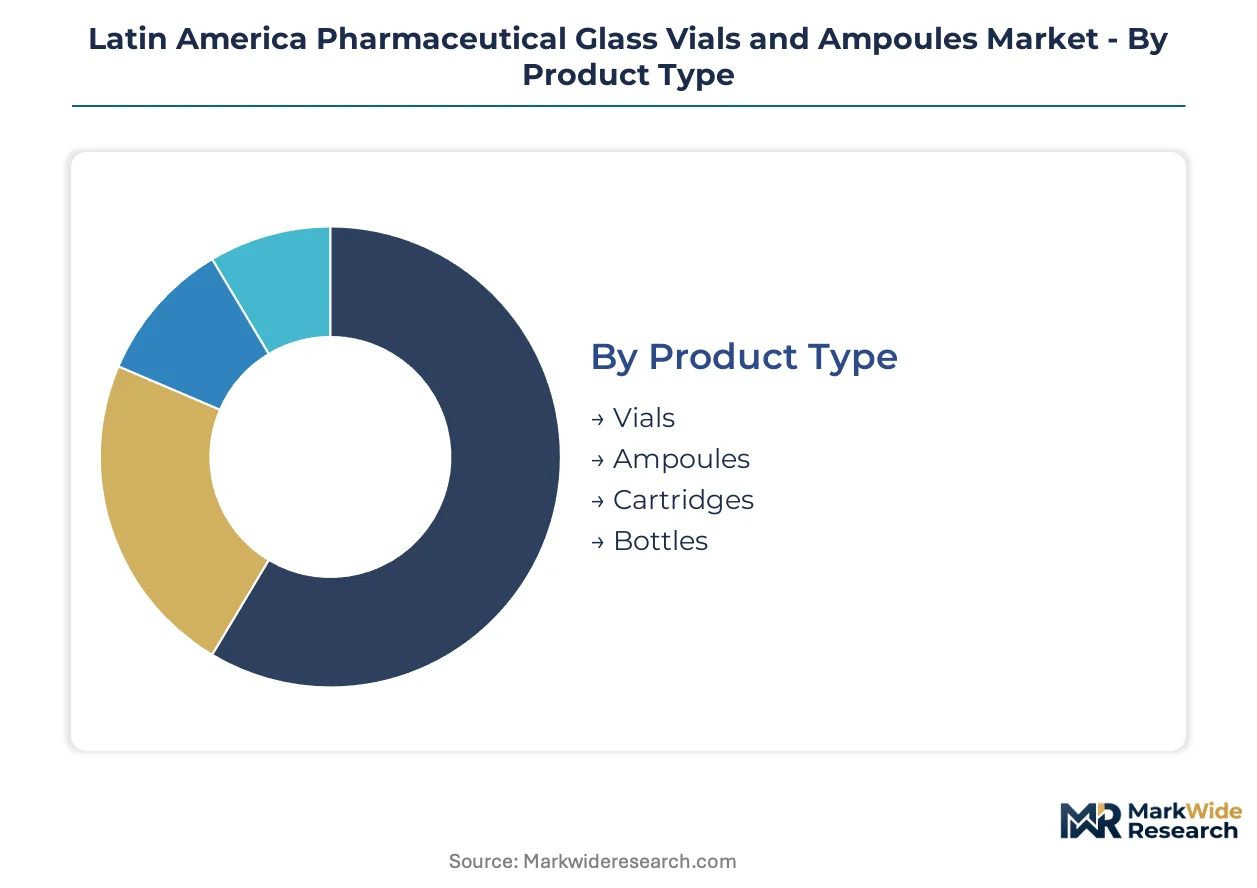
Segmentation in Latin American pharmaceutical glass packaging reveals how regulatory stringency and drug modality evolution reshape procurement priorities. Container selection increasingly hinges on extractables documentation, thermal stability requirements, and integration with automated fill-finish lines.
Product Type:
Substitution pressure from cyclic olefin polymers and copolymers concentrates in lower-performance segments, forcing glass converters to defend share through USP Type I certification and biologics compatibility.
- Vials:Tubular or molded borosilicate containers engineered for USP Type I, II, and III chemical durability standards. Demand concentrates among generic injectable manufacturers in Brazil's São Paulo corridor, where ANVISA's updated packaging standards mandate comprehensive extractables documentation for all imported containers.
- Cartridges:Pre-fillable glass cylinders designed for pen-injector and auto-injector integration. Biotechnology firms in Mexico's Baja California manufacturing cluster are displacing traditional syringe-ampoule workflows with these formats for insulin and biologic administration.
- Ampoules:Single-dose glass containers with score-break necks for immediate drug access. Standard parenteral applications in mid-tier Colombian pharmaceutical companies sustain residual demand despite polymer substitution threats.
- Bottles:Larger-format molded glass containers for oral and topical pharmaceutical liquids. Regional logistics advantages support procurement from mid-volume converters serving Andean markets with standardized formats.
Vials anchor the volume base while cartridges gain share at the steepest rate.
End User:
Customer concentration patterns reveal divergent technical requirements across the pharmaceutical value chain, with biologics manufacturers demanding the most stringent container qualification protocols.
- Pharmaceutical Companies:Integrated drug developers and generic manufacturers purchasing bulk volumes for parenteral and oral liquid portfolios. Procurement in Brazil consolidates toward validated suppliers with established ANVISA compliance infrastructures.
- Biotechnology Firms:Specialized developers of mRNA therapeutics, monoclonal antibodies, and cell therapies. These end users drive demand for borosilicate containment with enhanced thermal stability profiles and nested ready-to-use formats.
- Contract Manufacturing Organizations:Third-party fill-finish operators serving multiple drug sponsors. Mexico's Baja California corridor hosts expanding CMO capacity adopting pre-sterilized nested vials to compress cleanroom footprints and accelerate line changeovers.
- Research Institutions:Academic and clinical trial sponsors requiring small-batch, flexible-format containment. Procurement emphasizes rapid qualification timelines and lower minimum order quantities from regional converters.
Pharmaceutical companies dominate procurement volumes while biotechnology firms command the highest unit value premiums.
Closure Type:
Closure selection directly determines container integrity performance, with crimped and rubber-stoppered formats commanding premium positioning against lower-cost alternatives facing polymer displacement.
- Crimped Seals:Aluminum-band closures providing hermetic sealing for parenteral vials and ampoules. Biologics manufacturers in São Paulo specify these formats for lyophilized drug stability throughout extended shelf life.
- Rubber Stoppers:Elastomeric closures engineered for needle penetration and resealability. Demand concentrates in multi-dose vial applications where COFEPRIS traceability frameworks mandate serialized packaging documentation.
- Screw Caps:Threaded plastic or metal closures for oral liquid bottles. Mid-tier Colombian pharmaceutical companies favor these formats for cost-sensitive generic portfolios with shorter distribution cycles.
- Plastic Caps:Injection-molded polypropylene closures for non-parenteral pharmaceutical bottles. Standard oral applications in regional markets sustain volume despite limited technical differentiation.
Crimped seals secure the highest value per unit while rubber stoppers maintain the broadest application base.
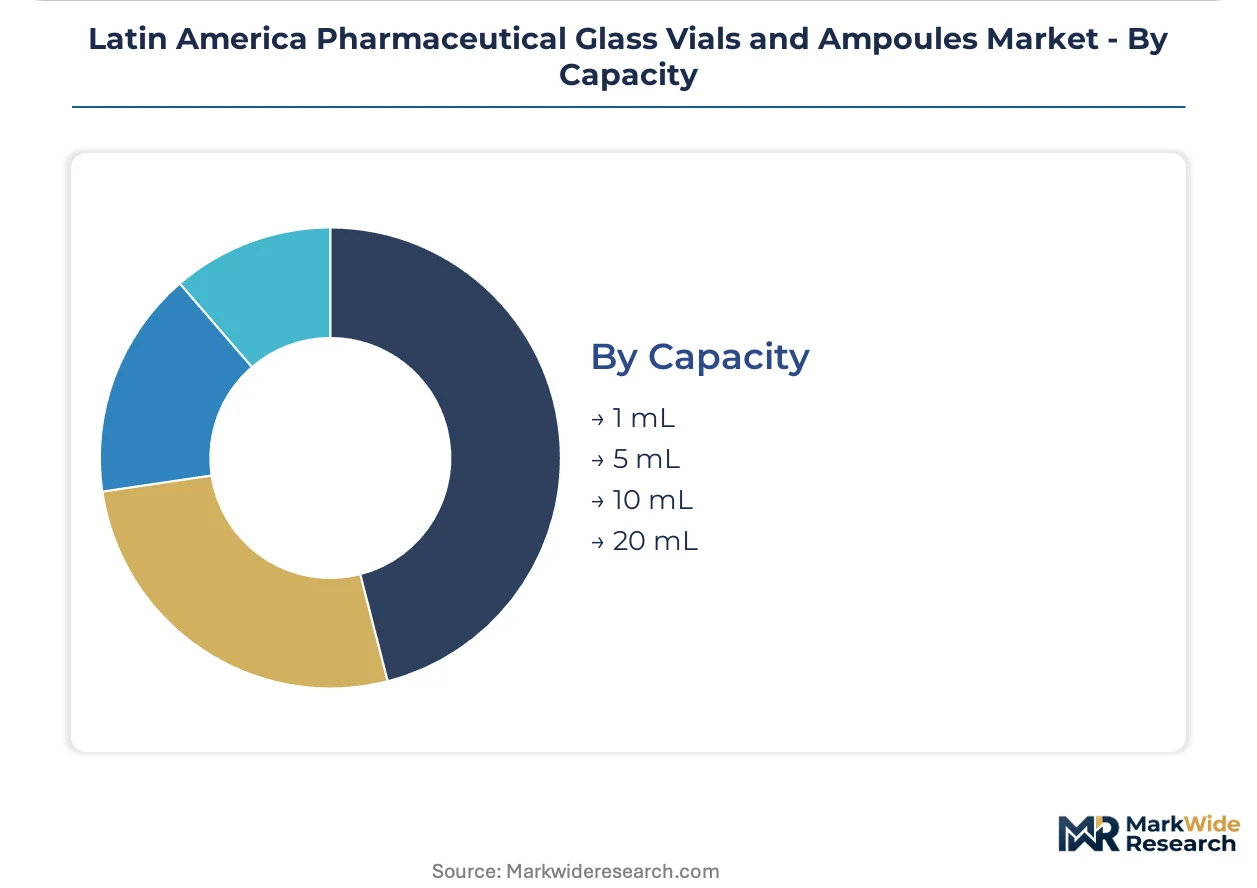
Capacity:
Volume scaling reflects dosing regimen standardization, with intermediate capacities capturing the majority of injectable applications across vaccine, insulin, and biologic categories.
- 10 mL:Standard vial capacity for multi-dose vaccine and biologic formulations. Brazil's expanded immunization programs and regional insulin production sustain concentrated demand for this format.
- 5 mL:Intermediate volume supporting single-dose injectables and diagnostic reagents. Biotechnology firms in Mexico City specify 5 mL borosilicate vials for temperature-sensitive nucleic acid therapeutics.
- 1 mL:Micro-volume format for high-potency biologics and pediatric vaccines. Limited production runs and specialized filling equipment requirements constrain supplier participation.
- 20 mL:Large-capacity format for diluents, infusion solutions, and veterinary applications. Regional logistics economics favor localized production for these lower-value, higher-weight containers.
10 mL formats anchor procurement volumes while 5 mL capacities expand most quickly through biologics adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Generic injectable manufacturers in Colombia exhibit acute price sensitivity, while São Paulo-based biologics developers absorb substantial premiums for USP Type I certification and nested ready-to-use formats.
Brazil
ANVISA's extractables and leachables mandate compresses procurement pools toward validated suppliers with established compliance infrastructures. São Paulo anchors national demand through its concentration of generic injectable manufacturers and biologics developers. Gerresheimer AG leverages its regional facility network to serve export-oriented pharmaceutical clusters.
Mexico
COFEPRIS traceability frameworks accelerate investment in integrated glass-inspection systems across contract manufacturing organizations. Baja California's pharmaceutical corridor hosts expanding fill-finish capacity adopting pre-sterilized nested vials to compress cleanroom footprints. Nearshoring momentum from multinational drug sponsors generates captive demand for regional borosilicate sourcing.
Colombia
INVIMA's streamlined bioequivalence pathway opens container qualification opportunities for mid-tier manufacturers serving Andean markets. Bogotá-based generic injectable producers sustain residual ampoule demand despite polymer substitution pressure. Regional logistics economics favor standardized vial formats from nearby converters over premium imported alternatives.
Argentina
Buenos Aires pharmaceutical manufacturers navigate currency volatility through localized procurement of soda-lime containers for oral liquid portfolios. The national pharmaceutical regulator enforces pharmacopeial compliance standards that elevate quality thresholds for imported primary packaging. Pilar industrial parks host mid-volume converters supplying cost-sensitive generic drug producers.
Chile
Santiago biotechnology firms drive specialized demand for borosilicate containment with enhanced thermal stability profiles for temperature-sensitive therapeutics. The national health authority maintains alignment with international pharmacopeial standards for parenteral packaging. Valparaíso logistics corridors facilitate import distribution to regional pharmaceutical manufacturing clusters.
Latin America Pharmaceutical Glass Vials and Ampoules Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Latin American pharmaceutical glass vials and ampoules market. Integrated system suppliers with inspection and packaging capabilities command premium positioning against standalone converters competing on logistics proximity and volume scale. Three archetypes dominate: multinational specialists with captive regional production, mid-tier regional converters with ANVISA/COFEPRIS compliance infrastructure, and logistics-focused suppliers serving price-sensitive generic markets. Competitive moves concentrate on capacity expansion in Mexican manufacturing corridors and strategic partnerships with biotechnology firms for nested ready-to-use formats.
Within the multinational specialist tier, Gerresheimer AG and Stevanato Group exemplify divergent strategic positions. Gerresheimer AG represents the scale-driven archetype with anchored regional production capacity. Stevanato Group occupies the integrated-systems position, bundling containment with inspection technologies. Vitro Glass Containers sits within the regional logistics-focused segment, supplying standardized formats to mid-tier pharmaceutical companies across Andean markets.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Scott Pharma |
| Stevanato Group |
| Nipro Corporation |
| SGD Pharma |
| Schott AG |
| Vitro Glass Containers |
| West Pharmaceutical Services, Inc. |
| Gerresheimer Querétaro S.A. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Brazilian generic injectable manufacturers and certified borosilicate converters lock in supply access while anchoring price visibility against raw material volatility. These contractual structures concentrate procurement power among ANVISA-validated suppliers, compressing margins for uncertified competitors while insulating qualified converters from spot-market energy cost spikes.
Pricing Analysis
After-sales revenue from technical qualification support and extractables documentation drives lifetime value for containment suppliers serving biotechnology firms. Three-tier pricing structure across premium, standard, and economy levels separates USP Type I certified borosilicate from soda-lime alternatives and polymer substitutes. Pricing pressure stems from cyclic olefin copolymer penetration in non-biologic segments, forcing glass converters to absorb certification costs. Generic manufacturers in Colombia exhibit acute price sensitivity, while São Paulo-based biologics developers absorb substantial premiums for nested ready-to-use formats.
Supply Chain Analysis
Strategic stockpiling of high-purity silica sand and boron compounds dominates inventory strategy among Latin American converters buffering against freight cost volatility. Raw material supply concentrates in the United States, Germany, and Turkey, exposing regional glass manufacturers to currency fluctuation and ocean freight spikes. Borosilicate melting operations hinge on natural gas inputs from Argentine and Bolivian sources, creating tariff exposure at import points. Distribution runs through pharmaceutical manufacturing corridors in São Paulo, Baja California, and Bogotá with validated cold-chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment creates formidable switching costs for pharmaceutical manufacturers. ANVISA's extractables documentation mandate locks in validated supplier relationships, making container qualification timelines a structural barrier to competitive displacement.
For Market Incumbents: Secure ANVISA and COFEPRIS certification renewals ahead of bioequivalence pathway expansions for generic injectables. Deepen backward integration into boron compound sourcing to buffer against raw material volatility from Turkish and German suppliers. Expand ready-to-use vial capacity in Querétaro and Baja California corridors to capture nearshoring fill-finish migration from multinational drug sponsors.
For New Entrants and Emerging Players: Anchor in Colombian mid-tier generic markets where INVIMA's streamlined pathways reduce qualification barriers for soda-lime containers. Target research institutions and clinical trial sponsors in Santiago and Mexico City requiring small-batch flexibility with rapid turnaround. Differentiate through nested pre-sterilized formats miniaturizing cleanroom footprints for emerging biotechnology contract manufacturers.
For Investors and Strategic Acquirers: Regional converters with established ANVISA compliance infrastructure and captive furnace capacity represent the most defensible acquisition archetype. Long-term viability rests on regulatory entrenchment deepening through successive pharmacopeial updates across Brazil, Mexico, and Colombia. Revision becomes warranted when polymer substitution rates in standard parenteral applications cross thresholds that compress glass volume sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| USP Type I Certification Investment | ANVISA's extractables mandate elevates compliance thresholds, filtering uncertified competitors from procurement pools. |
| Ready-to-Use Vial Capacity Expansion | Nested pre-sterilized formats compress cleanroom footprints for Baja California contract manufacturing organizations. |
| Backward Integration into Boron Sourcing | Captive supply of high-purity compounds buffers Brazilian converters against Turkish and German export volatility. |
| Biotechnology Firm Partnership | mRNA therapy developers in São Paulo drive specialized demand for thermal-stable borosilicate containment. |
| Nearshoring Corridor Positioning | Mexico's Baja California fill-finish migration generates captive regional demand for borosilicate sourcing. |
Research Methodology
A standing panel of regulatory affairs directors, pharmaceutical procurement managers, glass furnace operations engineers, and biotechnology supply chain leads provided ongoing calibration across primary fieldwork. Secondary validation drew from ANVISA regulatory filings, COFEPRIS traceability documentation, USP pharmacopeial standards, and Brazilian pharmaceutical import customs records. Bottom-up volume modeling triangulated against top-down market sizing from converter capacity disclosures and end-user procurement surveys.
Consistency checks validated volume and value outputs against external benchmarks including regional energy consumption data for borosilicate melting operations and pharmaceutical packaging trade flows. Segmentation dimensions spanned product type, end-user archetype, closure mechanism, and capacity tier across the modeling period. CAGRs derived from regression analysis of historical volume trajectories and projected biologics pipeline expansion, with specific weighting for mRNA therapy manufacturing scale-up and insulin cartridge adoption curves.
Material uncertainties — regulatory timeline acceleration, polymer substitution breakthroughs, silica sand supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding ANVISA enforcement consistency and nearshoring momentum sustainability. Revision becomes warranted when cyclic olefin polymer penetration in standard injectables crosses thresholds that structurally compress glass demand trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Drug Infusion System Market
Pharmaceutical Equipment
Pharmaceutical Equipment Testing Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market
Pharmaceutical Equipment
Global Pharmacy Automation Systems Market
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Global Pharmaceutical Membrane Filtration Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
Small Molecule CDMO Market
Pharmaceutical Equipment
North America and Europe Pharmaceutical Stability & Storage Services Market
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market
Pharmaceutical Equipment
Global Central Fill Pharmacy Automation Market
Pharmaceutical Equipment
India Contract Manufacturing Organization (CMO) Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market