
 Tablet Press Market | 2026-2036
Tablet Press Market Size, Share, and Industry Trends Forecast 2026-2036
Tablet Press Market Analytics
Project finance and equipment leasing is tilting competitive dynamics toward mid-sized pharmaceutical manufacturers that previously faced capital barriers to automated tablet production. Fette Compacting leverages its German engineering heritage to sustain premium positioning in high-speed rotary press systems. ACG anchors South Asian supply chains through integrated tablet press and tooling operations. GEA Group differentiates via modular press architectures that allow pharmaceutical clients to scale output without full line replacement.
A tablet press is a mechanical device that compresses powdered or granulated material into uniform solid tablets through controlled punch-and-die action, typically achieving compression forces between 4 and 100 kilonewtons depending on formulation density. Rotary press configurations dominate commercial pharmaceutical manufacturing due to throughput advantages exceeding one million tablets per hour, while single punch units retain utility in early-stage development and clinical batch production. Direct compression technology leads volume deployment for moisture-sensitive actives, though wet granulation persists where powder flow properties demand preprocessing. Contract manufacturers represent the fastest-growing end user segment as pharmaceutical companies divest in-house tableting capacity to asset-light operating models.
The US FDA enforces Current Good Manufacturing Practice regulations under 21 CFR Parts 210 and 211, mandating installation qualification and process validation that extend tablet press procurement cycles and elevate documentation burdens for suppliers. India's CDSCO aligns with ICH Q7 guidelines for active pharmaceutical ingredient and finished dosage form equipment qualification, creating dual compliance obligations for exporters serving regulated markets. The EU's MDR framework extends quality system expectations to tableting equipment used in medicinal product manufacturing. Stakeholders must monitor evolving data integrity requirements from regulators and assess whether connected press architectures with real-time release testing capabilities justify accelerated capital deployment.
Market Dynamics
Contract manufacturers are consolidating tablet press procurement through multi-year equipment leasing arrangements that transfer validation liability to machinery suppliers and compress capital deployment cycles for mid-tier pharmaceutical producers.
Growth Catalysts
- CDSCO alignment with ICH Q7:Indian generic drug makers accelerate rotary press qualification to serve regulated export markets, expanding domestic equipment demand.
- Direct compression technology:Moisture-sensitive active pharmaceutical ingredients favor dry granulation methods that reduce preprocessing infrastructure requirements.
- Contract manufacturing expansion:Pharmaceutical companies divest in-house tableting capacity, creating sustained demand for high-throughput rotary configurations.
Market Restraints
- Stainless steel and tungsten carbide tooling costs:Punch-and-die wear parts require frequent replacement, elevating total cost of ownership for continuous operations.
- Validation documentation burdens:FDA 21 CFR Part 211 mandates extend procurement cycles and elevate supplier qualification costs.
- Single-punch press substitution:Early-stage development and clinical batch production retain demand for lower-capacity units, limiting rotary press penetration in R&D segments.
Strategic Opportunities
- Brazil and Mexico pharmaceutical manufacturing:ANVISA regulatory convergence with ICH standards creates upgrade demand for validated compression equipment.
- Real-time release testing integration:Connected press architectures with in-line weight and hardness monitoring enable continuous process verification.
- Equipment-as-a-service models:Leasing structures with bundled maintenance and validation support expand access for emerging market manufacturers.
Industry Challenges
- Process analytical technology integration:Retrofitting legacy rotary presses with PAT sensors requires mechanical redesign and software validation.
- Installation qualification timelines:FDA-mandated IQ/OQ/PQ protocols delay commercial production startup by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablet Press Market |
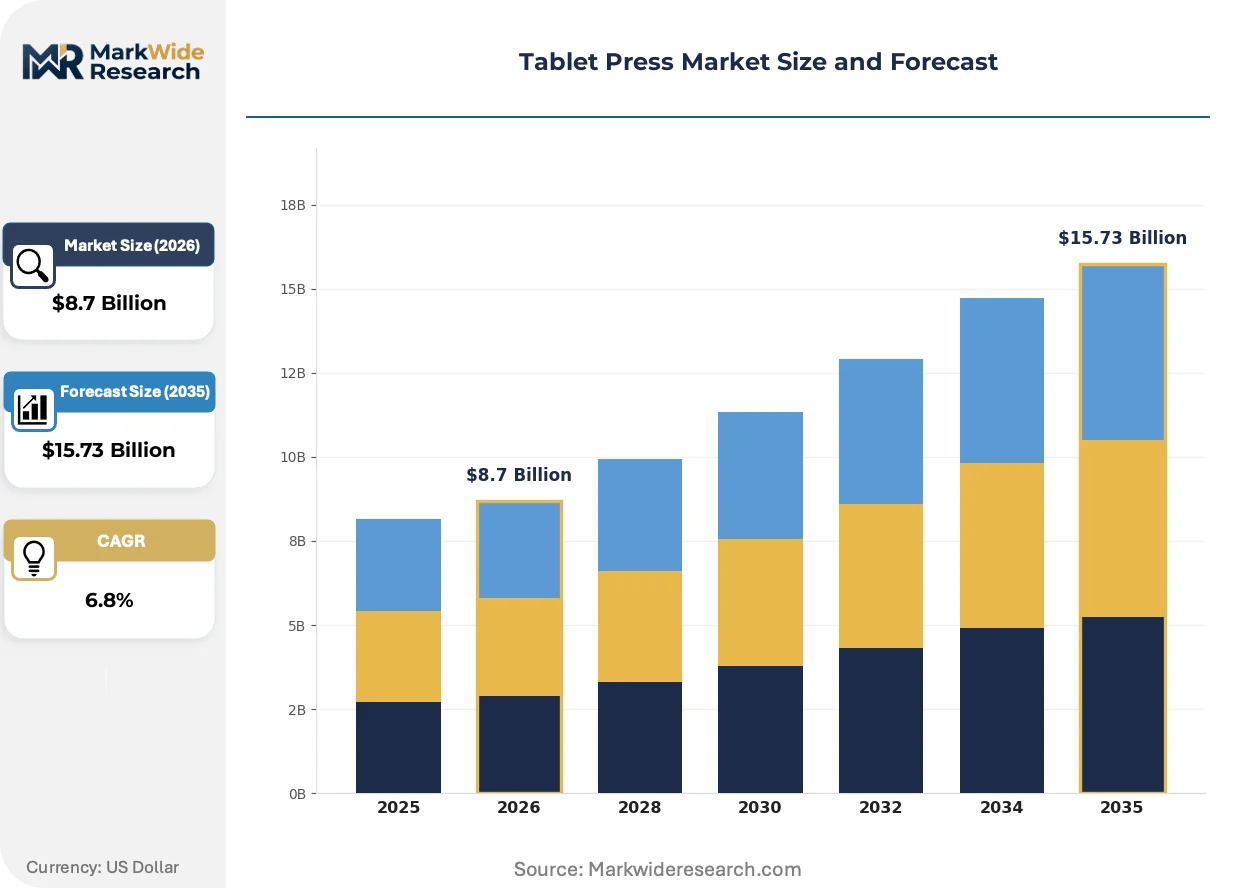
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Punch, Rotary Press, Multipress, Modular Press Technology: Compression, Direct Compression, Binder Granulation, Wet Granulation End User: Pharmaceutical Manufacturers, Nutraceutical Companies, Contract Manufacturers, Research Institutions Application: Tablets, Coated Tablets, Complex Tablets, Orally Disintegrating Tablets |
| Companies Covered | GEA Group, ACG, Fette Compacting, Natoli Engineering, Romaco Kilian, KORSCH AG, Syntegon Technology, Aligned, IMA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablet Press Market Evolving Landscape
Tablet press architectures are converging with process analytical technology and modular scale-out designs that enable pharmaceutical manufacturers to adapt output without full line replacement.
Continuous manufacturing is migrating from batch-oriented tableting toward integrated direct compression lines that combine powder feeding, compression, and coating in unified flow paths. Large-scale generic producers in India are piloting these systems to reduce intermediate handling and accelerate batch release timelines. This migration is compressing the competitive advantage of traditional batch-scale equipment suppliers.
The EU's MDR framework extends quality system expectations to tableting equipment used in medicinal product manufacturing, mandating enhanced documentation of design controls and post-market surveillance. Machinery suppliers must maintain technical files for each press configuration sold into the European Economic Area. High-speed rotary press vendors serving multinational pharmaceutical companies face the steepest compliance cost increases.
Service unbundling is fragmenting traditional equipment procurement as pharmaceutical buyers separate hardware acquisition from validation support and aftermarket maintenance. Contract manufacturers in North America increasingly source presses from German engineering houses while contracting validation documentation to specialized third-party consultants. This pattern is most pronounced among mid-sized CDMOs seeking to preserve capital for facility expansion rather than technical staffing.
Tablet Press Market Segmentation
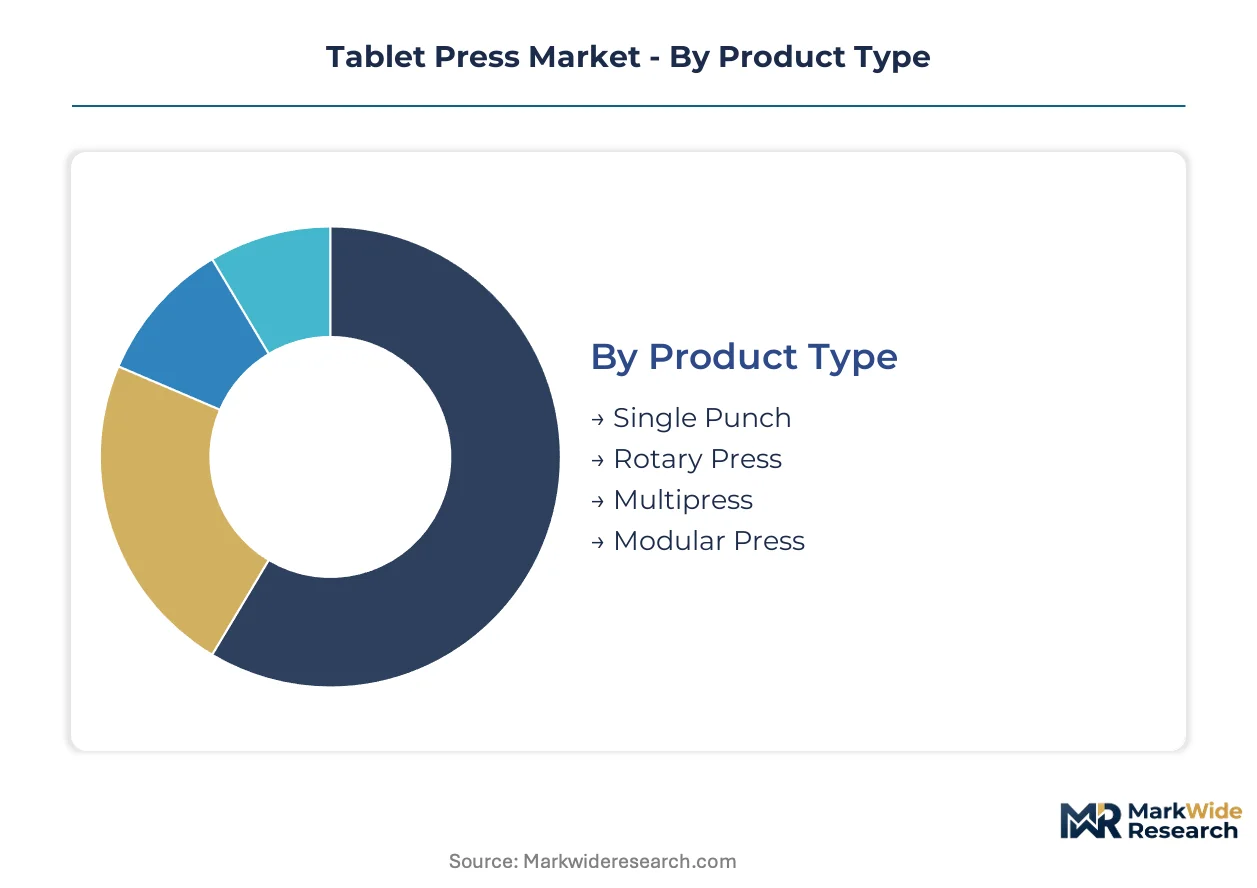
Segmentation in tablet press procurement reveals divergent equipment lifecycles and capital intensity patterns across pharmaceutical manufacturing tiers. Compression technology choices and end-user operating models create distinct replacement rhythms that suppliers must align against.
Product Type:
Rotary press configurations turn over fastest in high-volume generic operations, while single punch units persist for decades in R&D settings with minimal runtime hours.
- Rotary Press:Multi-station turret designs deliver throughput exceeding one million tablets hourly through synchronized punch-and-die rotation. Indian generic drug manufacturers in Hyderabad and Ahmedabad drive replacement demand as these facilities scale to serve FDA-regulated export markets with validated equipment.
- Single Punch:Eccentric-driven compression with single upper and lower punch pair suits early-stage formulation development and clinical batch production. Research institutions and emerging biotechs in Boston and Basel retain these units for decades due to low utilization rates and minimal wear.
- Multipress:Twin-turret architectures enable simultaneous compression of two tablet layers or distinct formulations.
- Modular Press:Scale-out designs permit capacity expansion through station addition rather than full line replacement.
Rotary press anchors the volume base while modular press gains share at the steepest rate.
Technology:
Technology selection stratifies by preprocessing infrastructure investment and moisture sensitivity of active pharmaceutical ingredients.
- Direct Compression:Powder blends flow directly into compression chambers without granulation, eliminating drying stages and thermal exposure. Facilities in Switzerland and Germany specializing in moisture-sensitive oncology actives favor this method for its reduced processing steps and faster batch release.
- Wet Granulation:Liquid binder addition and subsequent drying produces uniform granule flow properties for poorly compressible APIs. Legacy facilities in India and China maintain these lines for established products where reformulation costs exceed equipment replacement economics.
- Compression:Conventional dry granulation with roller compaction preceding tablet formation.
- Binder Granulation:Dry binder incorporation without liquid phase for intermediate flow improvement.
Wet granulation retains the largest installed base while direct compression expands most quickly among new facility investments.
End User:
End-user segments separate by capital access, technical staffing depth, and regulatory exposure tolerance.
- Contract Manufacturers:Asset-light operating models and multi-client flexibility requirements drive leasing structures and rapid equipment refresh cycles. CDMOs in North Carolina and New Jersey compress procurement timelines through bundled validation services from machinery suppliers.
- Pharmaceutical Manufacturers:Captive tableting operations within integrated drug makers prioritize equipment longevity and single-source supplier relationships. Multinational headquarters in New Jersey and Basel centralize procurement decisions for global facility networks.
- Nutraceutical Companies:Dietary supplement producers with lower regulatory stringency requirements.
- Research Institutions:Academic and government labs with minimal production scale and extended replacement horizons.
Pharmaceutical manufacturers anchor the volume base while contract manufacturers climb the fastest as outsourcing accelerates.
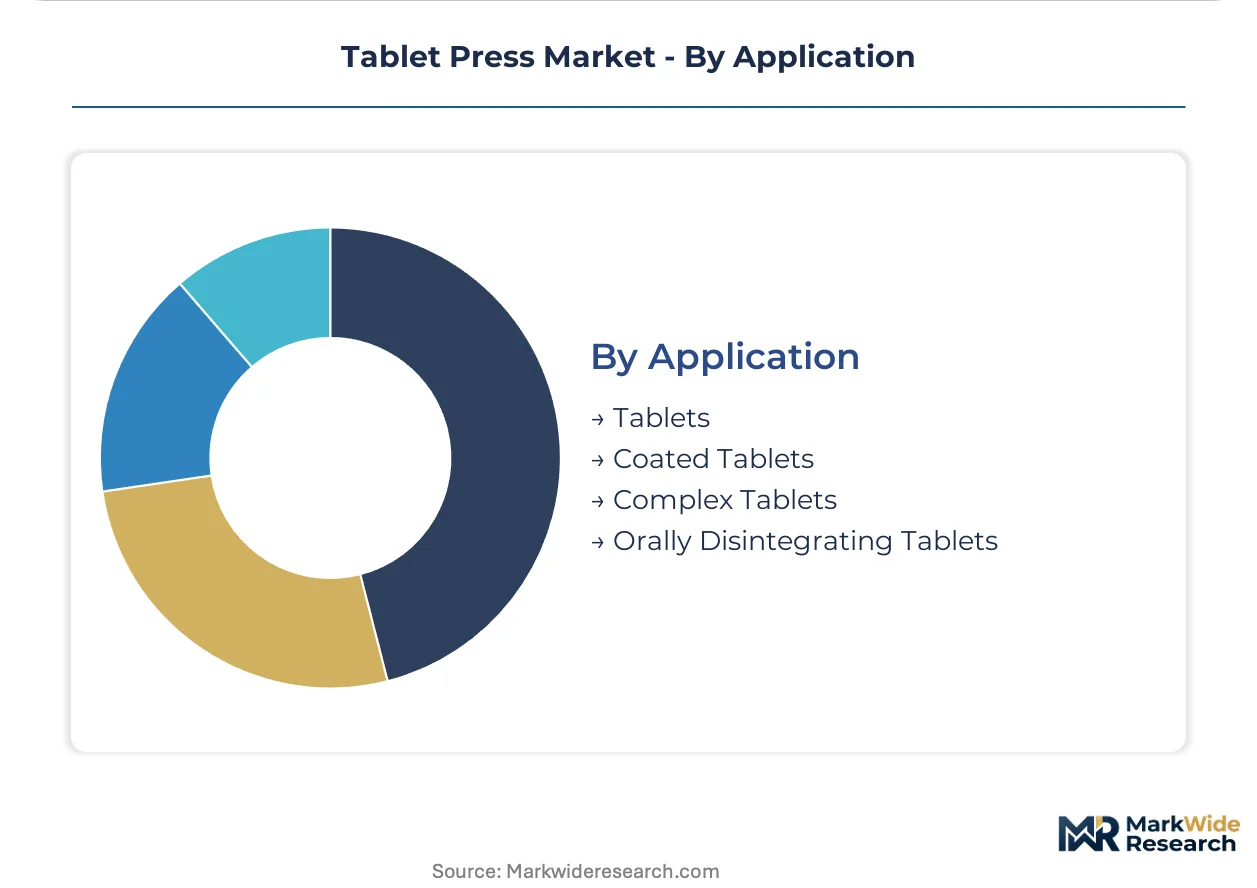
Application:
Application complexity determines tooling changeover frequency and press configuration specialization requirements.
- Tablets:Standard uncoated dosage forms represent the baseline compression application with broadest equipment compatibility. Generic producers in India deploy high-speed rotary presses for these products at maximum turret speeds to minimize unit costs.
- Orally Disintegrating Tablets:Rapid-dissolve formulations require specialized compression forces and moisture-controlled environments to preserve friability and disintegration profiles. Pediatric and geriatric specialists in Germany and Japan drive qualification of presses with enhanced in-process monitoring for these sensitive products.
- Coated Tablets:Film-coated or sugar-coated dosage forms with compression preceding coating operations.
- Complex Tablets:Multi-layer, core-in-core, or other geometrically intricate configurations.
Standard tablets anchor the volume base while orally disintegrating tablets gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German-engineered high-speed rotary systems, while Indian contract manufacturers extract value through volume procurement of mid-tier equipment. This asymmetry shapes regional deployment strategies across pharmaceutical manufacturing clusters.
United States
FDA 21 CFR Part 211 enforcement elevates validation documentation costs for compression equipment procurement. CDMOs in North Carolina and New Jersey favor leasing structures that transfer compliance liability to machinery suppliers. The Research Triangle Park cluster anchors domestic demand for continuous manufacturing-ready press configurations.
Germany
Moisture-sensitive oncology actives drive direct compression technology adoption among precision pharmaceutical manufacturers. The EU MDR framework mandates enhanced design control documentation for tableting equipment sold into the European Economic Area. Baden-Württemberg's industrial belt concentrates high-speed rotary press engineering expertise and premium tooling operations.
India
CDSCO alignment with ICH Q7 guidelines accelerates rotary press qualification for regulated export markets. Domestic generic drug makers in Hyderabad and Ahmedabad scale equipment fleets to serve FDA-inspected facilities. The Gujarat pharmaceutical corridor anchors the fastest-growing procurement volume for validated compression systems.
China
NMPA regulatory convergence with international GMP standards creates upgrade demand for automated tablet production lines. State-backed pharmaceutical consolidation favors domestic equipment suppliers with integrated validation support capabilities. The Yangtze River Delta cluster concentrates contract manufacturing expansion and associated press procurement.
Brazil
ANVISA regulatory alignment with ICH standards drives equipment modernization among domestic generic producers. Pharmaceutical manufacturing growth in São Paulo and Minas Gerais attracts multinational machinery suppliers establishing localized service networks. The São Paulo industrial corridor anchors Latin American demand for mid-speed rotary press configurations.
Tablet Press Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in tooling and precision machining. The vendor base stratifies across three tiers: German engineering houses with century-long pharmaceutical heritage, South Asian integrated suppliers combining equipment and consumables, and modular architecture specialists enabling scale-out capacity expansion. Strategic moves center on validation bundling to compress procurement cycles and geographic service densification to support installed base maintenance.
Within the integrated South Asian tier, ACG anchors combined tablet press and tooling operations serving regional contract manufacturers. Fette Compacting GmbH occupies the premium engineering position associated with high-speed rotary heritage. GEA Group exemplifies modular platform strategy through architectures permitting pharmaceutical clients to expand output without full line replacement. These three anchors represent distinct competitive vectors: bundled consumables, precision heritage, and scalable configurability.
| Leading Market Players |
|---|
| GEA Group |
| ACG |
| Fette Compacting |
| Natoli Engineering |
| Romaco Kilian |
| KORSCH AG |
| Syntegon Technology |
| Aligned |
| IMA Group |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's container cost dynamics amplify supply concentration effects in precision-engineered tablet press components, compressing margins for mid-tier manufacturers while enabling German engineering houses to sustain premium positioning through configured-to-order delivery models that Indian contract manufacturers cannot replicate at scale.
Pricing Analysis
The customization-premium spread separates Fette Compacting's configured rotary press systems from ACG's standard catalog offerings by a factor reflecting validation documentation bundling and tungsten carbide tooling grade. Pricing stratifies across premium German-engineered high-speed configurations, standard South Asian integrated equipment, and economy-tier domestic Chinese units with limited FDA qualification support. Cost compression in the standard tier intensifies as Indian CDMOs consolidate procurement through multi-year leasing arrangements. Contract manufacturers exhibit highest price sensitivity due to capital-light operating models, while integrated multinational pharmaceutical manufacturers prioritize equipment longevity over unit cost.
Supply Chain Analysis
Export-control restrictions on precision machining equipment under German and Swiss dual-use technology regimes limit tungsten carbide punch-and-die manufacturing transfers to emerging markets, constraining supply expansion. Manufacturing concentrates in Germany, India, and China, with Baden-Württemberg anchoring high-speed rotary press engineering and Gujarat housing integrated tooling operations. Raw material dependencies span specialty alloy steel from Sweden, tungsten carbide inserts from Austria, and precision bearings from Japan. Single-source vulnerability concentrates in German-engineered control systems. Distribution runs through machinery suppliers with captive validation service arms rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among North American contract manufacturers that consolidate procurement through multi-year equipment leasing, fragmenting traditional supplier relationships and compressing validation service margins across the vendor base.
For Market Incumbents: Entrench position through backward integration into precision tooling manufacturing to capture replacement revenue streams and defend against modular architecture specialists. Expand validation service capacity in the Research Triangle Park cluster to serve consolidating CDMO procurement. Counter GEA Group's scale-out threat by embedding process analytical technology sensors in legacy press retrofit programs. For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANVISA-aligned equipment upgrade cycle by offering bundled IQ/OQ/PQ documentation with mid-speed rotary configurations. Target Mexico's pharmaceutical manufacturing corridor with localized maintenance networks that German engineering houses cannot support economically. Pursue equipment-as-a-service licensing through pharmaceutical private equity platforms seeking asset-light CDMO acquisitions. For Investors and Strategic Acquirers: EU MDR's enhanced design control documentation requirements reshape the acquisition landscape toward machinery suppliers with established technical file management systems and post-market surveillance infrastructure. Long-term viability favors targets with integrated tooling operations and regulatory qualification bundling capabilities. Watch FDA 21 CFR Part 211 enforcement intensity as the signal for validation service demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Process Analytical Technology Integration | Retrofitting legacy rotary presses with in-line weight monitoring satisfies FDA continuous process verification mandates. |
| Equipment-as-a-Service Launch | Leasing structures with bundled validation support expand access for emerging market manufacturers lacking technical staffing. |
| Modular Platform Expansion | Scale-out press architectures enable pharmaceutical clients to expand output without full line replacement or extended IQ timelines. |
| Precision Tooling Backward Integration | In-house punch-and-die production captures recurring replacement revenue and reduces tungsten carbide supply vulnerability. |
| ANVISA Qualification Partnership | Localized validation documentation accelerates Brazilian generic manufacturer equipment modernization and service network densification. |
Research Methodology
Desk research of FDA 483 inspection observations, CDSCO equipment qualification guidelines, and EU MDR technical file requirements preceded structured interviews with rotary press engineering directors, CDMO procurement heads, and validation consultants across Hyderabad, Basel, and North Carolina. Primary fieldwork with maintenance technicians and tooling specialists informed wear-part replacement cycle assumptions. Secondary sources incorporated SEC filings from GEA Group and IMA Group, customs data on pharmaceutical machinery trade flows, and patent filings related to continuous manufacturing press architectures. Bottom-up equipment procurement forecasts triangulated against top-down pharmaceutical manufacturing capacity expansion estimates.
Assumptions held fixed include CDSCO-ICH Q7 alignment enforcement intensity, FDA 21 CFR Part 211 validation documentation requirements, and stainless steel alloy pricing bands. Variables stress-tested encompass ANVISA regulatory convergence pace, tungsten carbide supply disruptions, and contract manufacturing outsourcing acceleration. Segmentation modeling incorporated press type, compression technology, end-user operating model, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from equipment replacement cycle analysis and pharmaceutical manufacturing capacity expansion trajectories, with specific inputs from moisture-sensitive API formulation growth and orally disintegrating tablet qualification demand.
Stress conditions across FDA inspection intensity, EU MDR transition timelines, and Indian generic export market access were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor weightings. Material shifts in FDA enforcement posture toward data integrity requirements for connected press architectures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Middle East and Africa Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Europe Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market
Pharmaceutical Equipment
Global Pharmaceutical Membrane Filtration Market
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Isolator Market
Pharmaceutical Equipment
China Pharmaceutical Warehousing Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Asia-Pacific Pharmacy Automation Market
Pharmaceutical Equipment
Drug Infusion System Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
North America Pharmaceutical Isolator Market
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market