
 Asia-Pacific Pharmaceutical Isolator Market | 2026-2036
Asia-Pacific Pharmaceutical Isolator Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pharmaceutical Isolator Market Outlook
Stainless steel is rebalancing toward polymer-composite enclosures in mid-tier isolator lines, cutting unit weight and simplifying decontamination cycles. Tofflon Science and Technology leverages its domestic supply chain to dominate standardized positive pressure systems across Chinese pharmaceutical plants. SKAN anchors European-origin engineering credibility for high-containment aseptic lines sold into Japanese biologics facilities. Azbil Corporation specializes in automation-integrated isolators that align with Tokyo-area manufacturers' robotics roadmaps.
Pharmaceutical isolators are sealed containment workstations engineered to ISO 14644-1 Class 5 or better air cleanliness, using unidirectional HEPA-filtered airflow and glove-port access to shield sterile products from human-borne contamination. Positive pressure isolators lead unit shipments for aseptic filling applications, while robotic isolators represent the fastest-expanding margin pool as Japanese and South Korean manufacturers automate vial handling to reduce operator intervention. Contract manufacturing organizations drive hybrid deployment configurations that blend on-premises hardware with cloud-based environmental monitoring dashboards.
Japan's PMDA enforces strict PIC/S GMP compliance for isolator-based sterile processing, while China's NMPA mandates continuous particle monitoring under revised Annex 1 interpretations. South Korea's MFDS aligns with ICH Q9 quality risk management, pushing biotech firms toward validated containment systems ahead of product licensing. Stakeholders must weigh regulatory divergence against platform standardization when configuring multi-country manufacturing networks.
Market Dynamics
The Asia-Pacific pharmaceutical isolator market pivots on regulatory stringency divergence between Japan's PMDA PIC/S enforcement and China's NMPA Annex 1 revisions, forcing manufacturers to engineer multi-jurisdictional containment platforms rather than single-market designs.
Growth Catalysts
- Cell therapy manufacturing expansion:South Korean biotechnology firms are scaling GMP-grade isolator installations to support CAR-T and iPSC-derived product pipelines ahead of MFDS licensing milestones.
- NMPA Annex 1 compliance mandates:China's revised sterile manufacturing annex requires continuous viable and non-viable particle monitoring, compelling domestic facilities to replace open cleanroom operations with closed isolator systems.
- Robotics integration in aseptic processing:Japanese pharmaceutical manufacturers are deploying gloveless robotic isolators to eliminate human intervention during vial filling, driven by PMDA contamination risk guidelines.
Market Restraints
- Stainless steel input cost volatility:Grade 316L stainless steel price fluctuations compress margin stability for enclosure fabricators serving mid-tier Chinese pharmaceutical plants.
- European component supply concentration:Critical HEPA filtration media and glove port assemblies rely on German and Swiss suppliers, exposing lead time vulnerability to trans-Eurasian logistics friction.
- Polymer-composite temperature limitations:Mid-tier polymer isolator enclosures face thermal degradation constraints during hydrogen peroxide decontamination cycles above sixty degrees Celsius.
Strategic Opportunities
- Vietnam pharmaceutical manufacturing emergence:Greenfield biologics facilities in Ho Chi Minh City's industrial corridors present first-mover positioning for isolator vendors ahead of formal GMP harmonization.
- Cloud-integrated environmental monitoring:Contract manufacturing organizations across Singapore and Australia are adopting hybrid hardware-dashboard configurations enabling real-time batch release documentation.
- MFDS-ICH Q9 risk management alignment:South Korea's quality risk framework is accelerating demand for validated containment systems with embedded process analytical technology.
Industry Challenges
- Cross-border qualification timeline compression:Japanese and Australian pharmaceutical manufacturers face extended FAT/SAT protocols when sourcing isolators from Chinese fabricators due to divergent acceptance criteria.
- Legacy SCADA integration complexity:Older Japanese pharmaceutical plants require bespoke middleware development to connect new isolator PLCs with existing Yokogawa or Hitachi distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pharmaceutical Isolator Market |
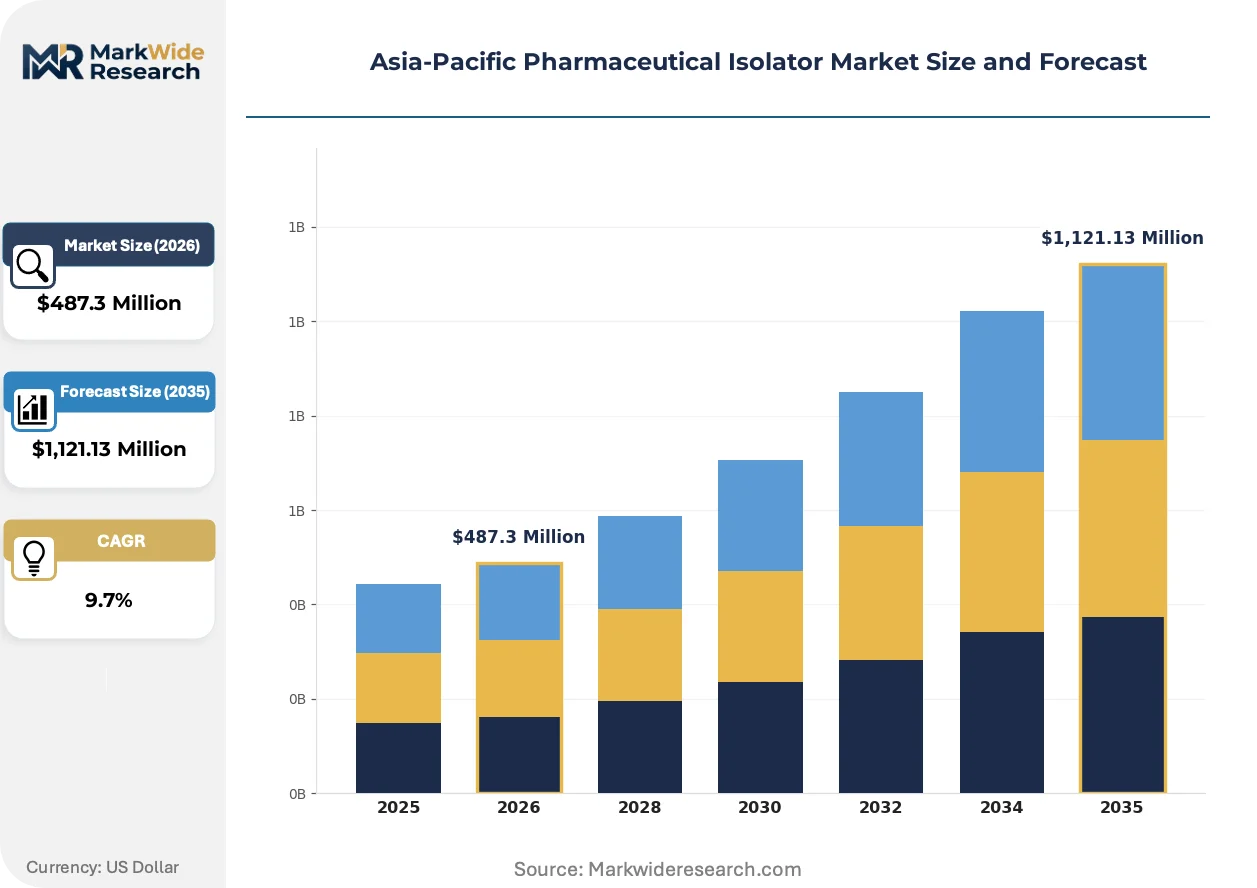
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Negative Pressure Isolators, Positive Pressure Isolators, Restricted Access Barriers, Robotic Isolators End User: Pharmaceutical Manufacturers, Research Laboratories, Contract Manufacturing Organizations, Biotechnology Firms Deployment: On-Premises, Cloud-Based, Hybrid, Locally Hosted Application: Aseptic Processing, Sterilization, Sampling, Animal Handling |
| Companies Covered | Winteam, Weike, Tofflon Science and Technology, Gelman Singapore Pte Ltd, Hosokawa Micron Ltd., Chiyoda Corporation, TAILIN Bioengineering, SKAN, Azbil Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pharmaceutical Isolator Market Strategic Shifts
Automation architecture and material science are converging to redefine containment economics across the Asia-Pacific pharmaceutical manufacturing base. Three developments are compressing competitive differentiation.
Polymer-composite enclosure technology is consolidating market positioning in mid-tier aseptic filling lines. These structures reduce unit mass by forty percent versus stainless steel equivalents while simplifying decontamination cycle validation. Chinese and Indian contract manufacturers are adopting polymer isolators for oral solid dose and ophthalmic applications where thermal sterilization demands remain moderate.
Japan's PMDA has tightened PIC/S GMP interpretation for isolator-based sterile processing, mandating continuous pressure differential logging and automated alarm escalation. This regulatory posture is forcing domestic innovators to retrofit existing installations with redundant monitoring architectures. South Korean biologics facilities are preemptively aligning with these standards to secure export equivalence into Japanese supply chains.
Service unbundling is fragmenting traditional isolator procurement patterns across Australian and Singaporean contract manufacturing organizations. Buyers are separating hardware acquisition from validation protocol development and ongoing environmental monitoring subscriptions. This disaggregation compresses upfront capital outlays while shifting lifecycle revenue toward software-enabled service tiers.
Asia-Pacific Pharmaceutical Isolator Market Segmentation
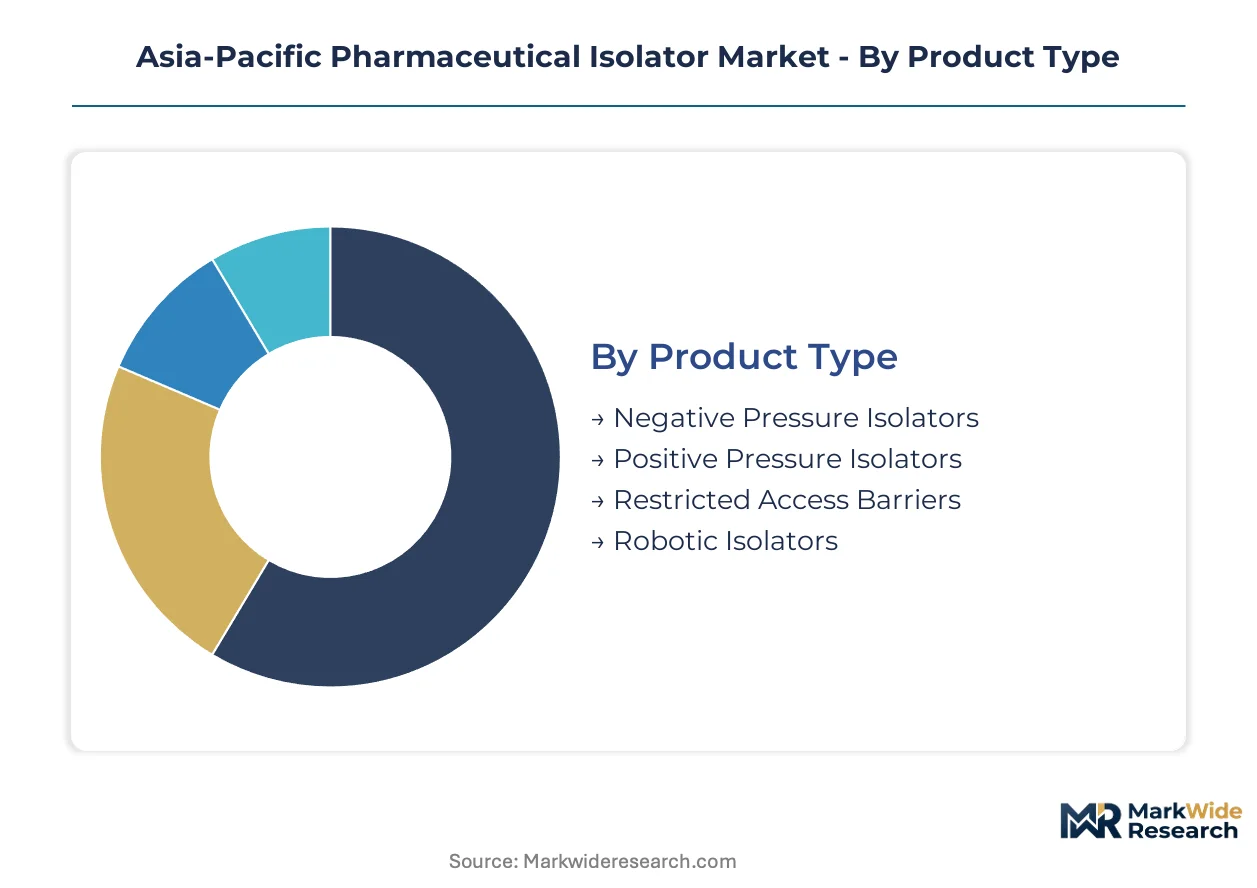
Pharmaceutical isolator procurement patterns diverge sharply across containment architectures and operational environments. Segment-level purchasing decisions in the Asia-Pacific region track regulatory jurisdiction, automation maturity, and facility vintage.
Product Type:
Upgrade cycles in Japanese and South Korean facilities favor next-generation containment architectures over legacy stainless steel enclosures. Replacement timelines compress where PMDA and MFDS guidance tighten sterile processing validation requirements.
- Positive Pressure Isolators:Unidirectional HEPA-filtered airflow systems maintain ISO Class 5 environments through physical barrier separation. Japanese pharmaceutical manufacturers in the Kanto corridor deploy these for aseptic filling of biologics vials, driven by PMDA contamination risk mandates for high-value parenteral products.
- Robotic Isolators:Gloveless automation platforms eliminate operator intervention through articulated arm systems for material handling. South Korean biotechnology firms scaling CAR-T manufacturing adopt these to meet MFDS quality risk management standards while reducing human-borne contamination exposure during cell therapy processing.
- Negative Pressure Isolators:Containment workstations protect external environments from hazardous materials through inward airflow directionality. Chinese active pharmaceutical ingredient producers install these for potent compound handling under NMPA occupational exposure guidelines.
- Restricted Access Barriers:Partial enclosure systems provide intermediate containment between open cleanrooms and full isolators. Southeast Asian contract manufacturers favor these for cost-sensitive oral solid dose operations where complete isolation remains economically prohibitive.
Positive pressure isolators sit at the top of the volume ranking, with robotic isolators climbing the fastest.
End User:
Customer procurement authority concentrates in organizations with direct regulatory licensing exposure and capital deployment flexibility. Budget scale and validation expertise determine technology tier selection across the Asia-Pacific manufacturing base.
- Pharmaceutical Manufacturers:Integrated drug producers with in-house sterile processing capabilities. Domestic innovators across Japan's pharmaceutical corridor invest in automation-integrated isolators to align with PMDA PIC/S GMP enforcement timelines.
- Contract Manufacturing Organizations:Third-party production specialists serving multiple sponsor clients. Singaporean and Australian CMOs drive hybrid deployment configurations blending on-premises hardware with cloud-based environmental monitoring dashboards.
- Biotechnology Firms:Cell therapy and gene therapy developers requiring GMP-grade containment for clinical and commercial manufacturing. South Korean biotechs expanding cleanroom capacity ahead of MFDS product licensing milestones.
- Research Laboratories:Academic and preclinical facilities with lower throughput requirements. Chinese institutional buyers prioritize polymer-composite enclosures for cost containment in non-commercial development settings.
Pharmaceutical manufacturers command the largest installed base, while contract manufacturing organizations expand most aggressively.
Deployment:
Data architecture decisions reflect facility IT maturity and batch documentation automation requirements. Cloud connectivity penetration varies with national data sovereignty regulations and pharmaceutical sector digital infrastructure investment.
- On-Premises:Local server infrastructure for environmental monitoring and batch records. Dominant in legacy Japanese facilities with established Yokogawa or Hitachi distributed control architectures requiring bespoke middleware integration.
- Hybrid:Blended local processing with cloud-based analytics and remote monitoring capabilities. Australian CMOs adopt this model to enable real-time batch release documentation while maintaining on-site critical control system redundancy.
- Cloud-Based:Fully hosted environmental monitoring with subscription-based dashboard access. Emerging preference among Southeast Asian greenfield facilities lacking legacy SCADA integration burdens.
- Locally Hosted:Single-facility server installations without external connectivity. Retained by Chinese domestic pharmaceutical plants under data localization preferences and NMPA documentation audit trail requirements.
On-premises deployment retains volume leadership, though hybrid configurations gain share fastest among new installations.
Application:
Process-specific containment requirements determine isolator specification complexity and validation protocol scope. Application selection correlates with product sterility assurance level and operator exposure risk.
- Aseptic Processing:Sterile product handling through filling, stoppering, and capping operations. Japanese biologics manufacturers deploy positive pressure and robotic isolators here under PMDA continuous pressure differential logging mandates.
- Sterilization:Decontamination cycle execution using vaporized hydrogen peroxide or other agents. Polymer-composite enclosures face thermal degradation constraints above sixty degrees Celsius, limiting adoption in high-temperature sterilization applications.
- Sampling:Representative material extraction for quality control testing. Active across Chinese API facilities requiring containment during potent compound characterization under revised Annex 1 interpretations.
- Animal Handling:Containment for laboratory animal procedures and biohazard work. Niche deployment in Australian research institutions with specific biocontainment certification requirements.
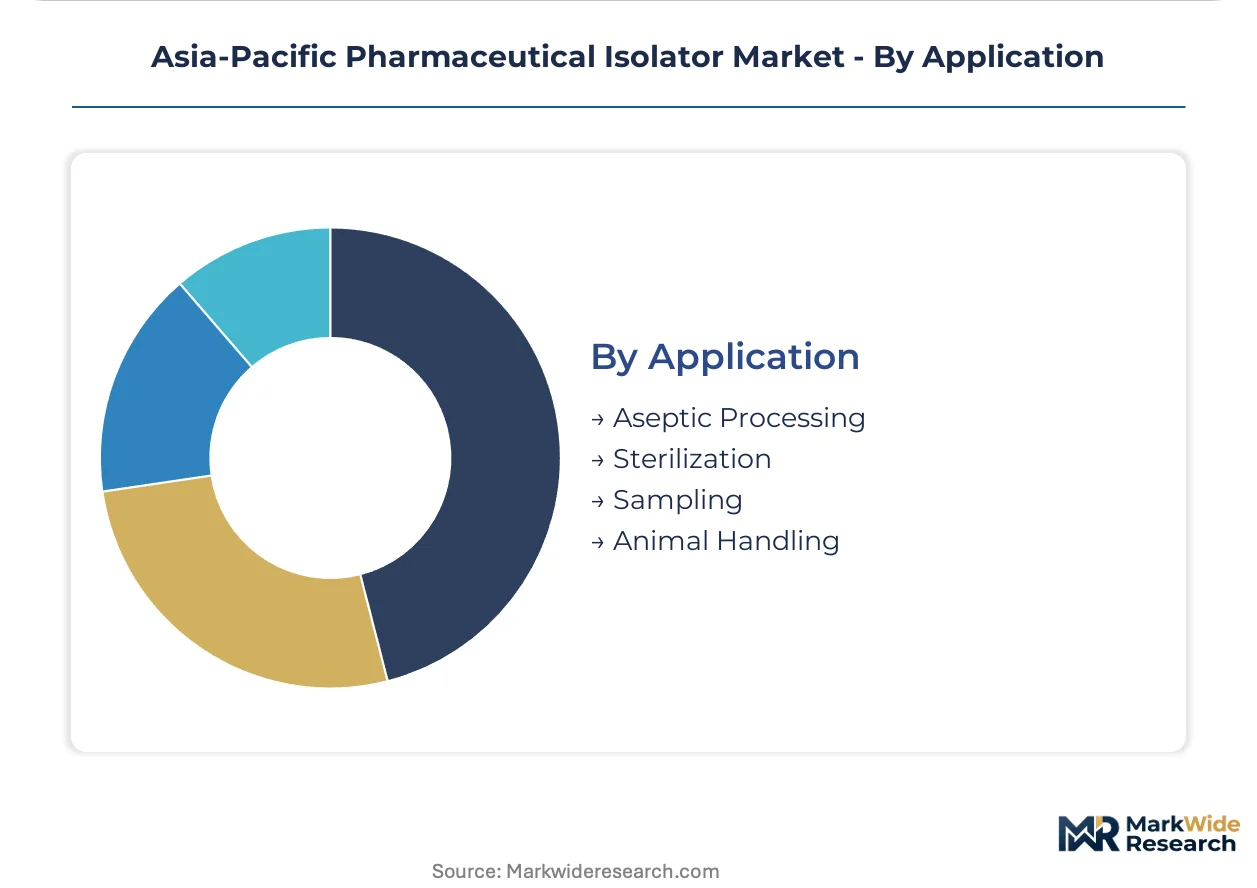
Aseptic processing dominates installed capacity, with sterilization applications showing steepest expansion trajectory amid Annex 1 compliance upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Kanto pharmaceutical corridor anchors isolator procurement intensity across the Asia-Pacific region. Domestic biologics innovators in Tokyo and surrounding prefectures drive demand for advanced containment systems under tightening PMDA oversight.
Japan
PMDA enforcement of PIC/S GMP standards compels domestic manufacturers to retrofit existing sterile processing lines with redundant pressure differential monitoring. The Kanto corridor concentrates investment in gloveless robotic isolators for vial filling operations. Tokyo-area facilities prioritize automation-integrated systems that align with METI robotics roadmaps.
China
NMPA Annex 1 revisions mandate continuous viable and non-viable particle monitoring for sterile manufacturing, forcing facility upgrades from open cleanrooms to closed isolator architectures. Domestic pharmaceutical plants in the Yangtze River Delta and Pearl River Delta dominate standardized positive pressure system procurement. Tofflon Science and Technology leverages its domestic supply chain to capture standardized system deployments.
South Korea
MFDS alignment with ICH Q9 quality risk management accelerates validated containment system adoption ahead of product licensing milestones. Seoul Capital Area biotechnology firms scale CAR-T and iPSC-derived manufacturing capacity using GMP-grade isolator installations. Busan-Ulsan industrial complexes see parallel demand from contract manufacturing expansion.
Australia
TGA guidance on sterile product manufacturing pushes contract manufacturing organizations toward hybrid deployment configurations. Sydney and Melbourne facilities blend on-premises isolator hardware with cloud-based environmental monitoring dashboards for real-time batch release documentation. Data sovereignty preferences favor locally hosted critical control system redundancy.
Singapore
The national pharmaceutical regulator enforces stringent containment standards for biologics manufacturing that align with PIC/S principles. Tuas Biomedical Park and surrounding industrial zones attract isolator vendors serving multi-national sponsor clients. Service unbundling trends fragment traditional procurement patterns as buyers separate hardware acquisition from validation protocol development.
Asia-Pacific Pharmaceutical Isolator Market Competitive Environment
Capacity expansion dominates the current landscape as vendors scale fabrication facilities to meet NMPA-driven upgrade cycles across Chinese pharmaceutical plants. The vendor base stratifies across three tiers: European-origin engineering specialists, domestic Chinese fabricators with supply chain proximity advantages, and Japanese automation-integrated specialists. Competitive positioning hinges on regulatory qualification speed, decontamination cycle validation support, and legacy SCADA integration capabilities. Strategic partnerships between enclosure fabricators and HEPA filtration suppliers compress lead times for critical components.
Among Asia-Pacific-based fabricators, Tofflon Science and Technology exemplifies the domestic Chinese archetype with standardized positive pressure system penetration, while Azbil Corporation occupies a position within the automation-integrated tier serving Tokyo-area robotics roadmaps. SKAN represents European-origin engineering credibility for high-containment aseptic lines. These three anchors illustrate how competitive differentiation converges on regulatory jurisdiction expertise and supply chain configuration rather than pure technology specification.
| Leading Market Players |
|---|
| Winteam |
| Weike |
| Tofflon Science and Technology |
| Gelman Singapore Pte Ltd |
| Hosokawa Micron Ltd. |
| Chiyoda Corporation |
| TAILIN Bioengineering |
| SKAN |
| Azbil Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between PMDA-validated Japanese installations and NMPA-compliant Chinese standardized systems manifests in parallel pricing stratification and supply chain fragmentation. Premium robotic isolators bound for Tokyo-area biologics facilities command substantial engineering validation premiums, while mid-tier polymer-composite enclosures for Yangtze River Delta pharmaceutical plants optimize around domestic fabrication economics and simplified decontamination protocols.
Pricing Analysis
Grade 316L stainless steel cost pass-through from European mills compresses margin stability for enclosure fabricators serving mid-tier Chinese pharmaceutical plants. Three-tier pricing structure across premium, standard, and economy levels tracks automation integration depth and regulatory qualification scope. Cost compression in standardized positive pressure systems intensifies as Tofflon Science and Technology scales domestic supply chain capture. Biotechnology firms scaling CAR-T manufacturing in South Korea exhibit lowest price sensitivity due to MFDS licensing milestone pressures, while Southeast Asian contract manufacturers prioritize economy-tier polymer isolators for oral solid dose applications.
Supply Chain Analysis
Refurbishment flows for legacy stainless steel isolators from Japanese pharmaceutical corridor retrofits create secondary supply channels into Vietnamese and Indonesian emerging facilities. Critical HEPA filtration media and glove port assemblies draw from German and Swiss suppliers, exposing lead time vulnerability to trans-Eurasian logistics friction. Single-source concentration in European filtration specialists amplifies tariff exposure risk for Chinese fabricators assembling NMPA-compliant systems. Distribution runs through direct vendor-engineer relationships for complex robotic installations, while standardized positive pressure systems flow through regional equipment distributors serving domestic pharmaceutical plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific pharmaceutical isolator market reads as a late-cycle quality story as PMDA PIC/S enforcement and NMPA Annex 1 revisions elevate specification floors across sterile manufacturing corridors. Demand is concentrating in validated containment systems with embedded process analytical technology and redundant monitoring architectures.
For Market Incumbents: Hedge margin erosion in standardized positive pressure systems by deepening backward integration into polymer-composite enclosure fabrication and captive HEPA filtration media supply. European-origin engineering specialists face emerging entrant pressure from Chinese domestic fabricators with supply chain proximity advantages; defend positioning through accelerated regulatory qualification speed for multi-jurisdictional platforms and legacy SCADA integration capabilities for Yokogawa and Hitachi distributed control architectures in aging Japanese facilities.
For New Entrants and Emerging Players: Capture white-space positioning in Vietnam's Ho Chi Minh City industrial corridors ahead of formal GMP harmonization, where greenfield biologics facilities lack incumbent vendor relationships. Australian and Singaporean contract manufacturing organizations present penetrable demand for hybrid deployment configurations blending on-premises hardware with cloud-based environmental monitoring dashboards; enter through service unbundling plays separating hardware acquisition from validation protocol development and ongoing subscription tiers.
For Investors and Strategic Acquirers: Consolidation pressure builds where European component supply concentration meets NMPA-driven upgrade cycle volume surges across Chinese pharmaceutical plants. Long-term viability favors vendors with regulatory jurisdiction expertise spanning PMDA, NMPA, and MFDS frameworks alongside in-house decontamination cycle validation capabilities. Monitor MFDS product licensing milestone timelines for South Korean biotechnology firms as inflection indicators for GMP-grade isolator installation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Qualification Acceleration | Compresses FAT/SAT timelines for PMDA and NMPA multi-jurisdictional platform approvals. |
| Polymer-Composite Enclosure Scale-Up | Reduces unit mass forty percent versus stainless steel for mid-tier aseptic filling lines. |
| Cloud-Integrated Environmental Monitoring | Enables real-time batch release documentation for Australian and Singaporean CMOs. |
| Backward Integration into Filtration Media | Mitigates European single-source vulnerability for critical HEPA component supply. |
| Legacy SCADA Middleware Development | Unlocks retrofit opportunities in Japanese facilities with Yokogawa control architectures. |
Study Parameters
Multiple input streams — regulatory filing analysis, equipment procurement databases, and primary stakeholder engagement — were reconciled through bottom-up and top-down triangulation. Primary interviews with sterile manufacturing directors, regulatory affairs leads at biotechnology firms, validation engineers, and GMP facility planners were cross-referenced against secondary validation from NMPA Annex 1 guidance documents, PMDA PIC/S GMP enforcement notices, MFDS ICH Q9 alignment circulars, and customs records for isolator component trade flows.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include containment architecture type, automation maturity tier, end-user category, deployment data architecture, and regional regulatory cluster. CAGRs were derived through installed base replacement cycle analysis, facility expansion pipeline tracking, and technology substitution elasticity estimates for robotic versus glove-port isolator platforms.
Underlying measurement precision varies by segment; standardized positive pressure systems carry tighter precision than emerging robotic isolator categories due to established procurement pattern visibility. Forecasts reflect assumptions regarding NMPA enforcement consistency, stainless steel input cost stability, and trans-Eurasian logistics friction persistence. Practitioners should monitor MFDS product licensing milestone announcements, NMPA facility inspection outcome publications, and PMDA PIC/S GMP interpretation updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Inhalation CDMO Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
Global Fill Finish Manufacturing Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Serum Vials Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
Pharmaceutical Glass Ampoules Market
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
Automated Drug Kiosk Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market