
 Dental Implants and Prosthetics Contract Manufacturing Market | 2026-2036
Dental Implants and Prosthetics Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Implants and Prosthetics Contract Manufacturing Market Analytics
ISO 13485-certified production is bifurcating the competitive landscape into qualified and non-qualified supplier tiers. Cendres+Métaux Medtech leverages its Swiss heritage to dominate high-precision zirconia milling for European dental OEMs. Halder GmbH anchors German demand through validated titanium machining lines that sustain long-term supply agreements with major implant brands. Elos Medtech AB competes from Scandinavia with specialized surface treatment capabilities that differentiate its contract offerings.
Dental implants and prosthetics contract manufacturing encompasses the outsourced fabrication of endosseous implants, abutments, and superstructures from biocompatible alloys and ceramics, typically requiring Ra surface finishes below 0.8 micrometers and fatigue strength exceeding 600 MPa to ensure osseointegration and long-term masticatory function. Titanium abutments machined to ISO 5832-3 specifications remain the mature revenue base, while 3D-printed cobalt-chrome and PEEK frameworks represent the fastest-growing margin pool as dental laboratories adopt chairside digital workflows. CAD/CAM technology leads unit volume across European contract manufacturers, though surface treatment segments command premium pricing due to proprietary electropolishing and anodizing protocols required for hydrophilic implant surfaces.
The EU MDR and CE marking framework enforce clinical evidence requirements that reshape supplier qualification timelines, while FDA 510(k) pathways govern US market access for contract-manufactured devices sold under private labels. ISO 13485 and ISO 10993 biocompatibility standards function as baseline gating criteria that filter smaller machine shops from OEM procurement lists. Stakeholders must monitor regulatory divergence between the EU MDR's stricter post-market surveillance and the FDA's evolving predicate device policies when selecting contract manufacturing partners for multi-region product lines.
Market Dynamics
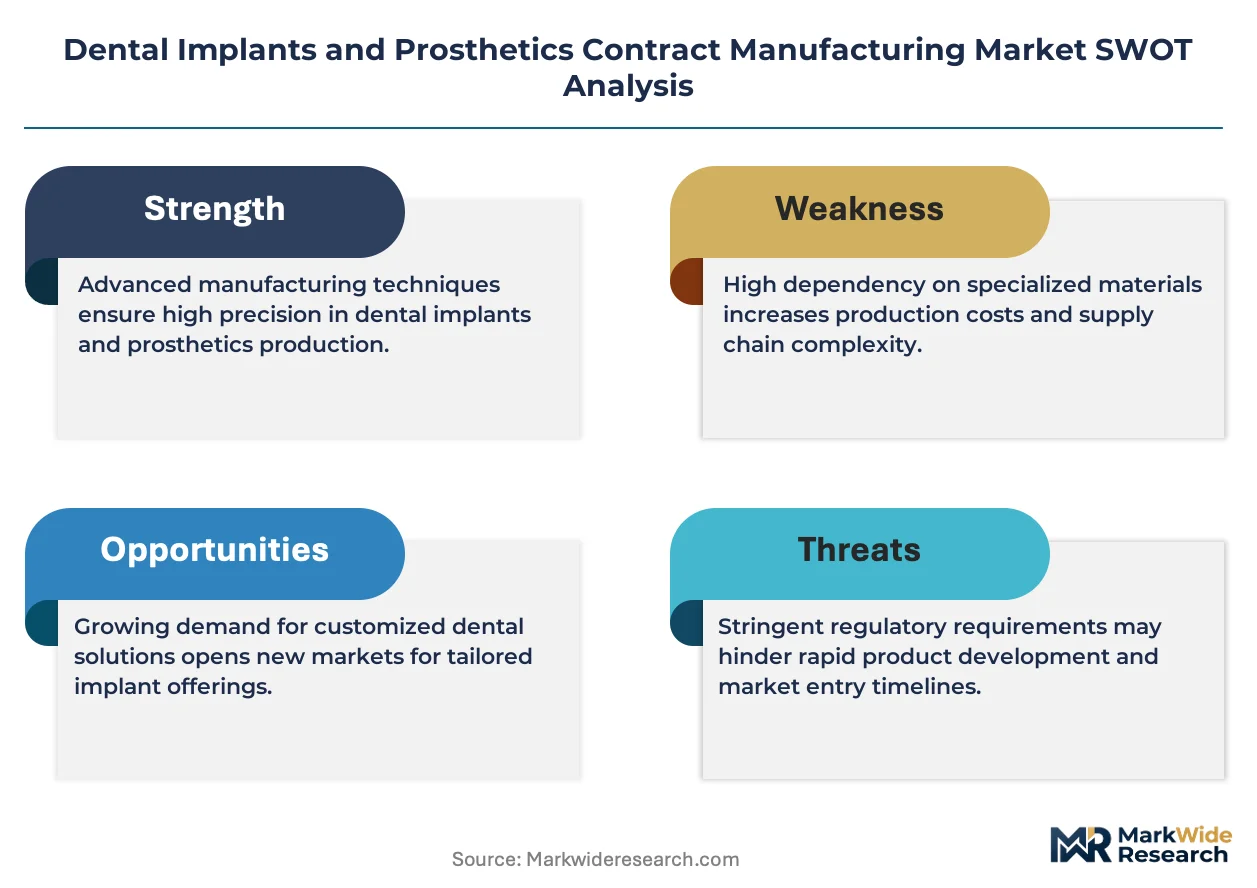
EU MDR's tightened clinical evidence requirements for titanium and zirconia implants are forcing dental OEMs to consolidate supplier relationships around ISO 13485-certified contract manufacturers with validated regulatory dossiers.
Growth Catalysts
- CE marking under EU MDR:Dental clinics in Germany, France, and Switzerland are expanding procurement of outsourced implant components as quality requirements tighten for biocompatible devices.
- CAD/CAM fabrication:Chairside digital workflows in dental laboratories are accelerating demand for precision-machined abutments and computer-aided prosthetics.
- Surface treatment protocols:Proprietary electropolishing and anodizing capabilities are creating pull for contract manufacturers with hydrophilic implant surface expertise.
Market Restraints
- Titanium alloy input costs:Volatility in ISO 5832-3 compliant titanium billet pricing compresses margins for precision machining operations.
- Supplier concentration in German-speaking Europe:Swiss and German contract manufacturers dominate high-precision zirconia milling, limiting buyer negotiating leverage.
- 3D-printed framework substitution:Direct metal laser sintering of cobalt-chrome prosthetics threatens traditional subtractive machining volumes for standard abutments.
Strategic Opportunities
- Scandinavian surface treatment specialization:Electropolishing and anodizing capabilities concentrated in Sweden and Denmark offer differentiation for osseointegration-focused implants.
- PEEK framework adoption:Polyetheretherketone's biocompatibility and radiolucency are opening chairside digital workflow applications in aesthetic dentistry.
- FDA 510(k) pathway expansion:Private-label contract manufacturing for US market access creates dual-qualification revenue streams beyond EU MDR compliance.
Industry Challenges
- ISO 13485 certification timelines:The 12-18 month qualification period for quality management system audits delays new entrant market entry.
- Multi-region regulatory divergence:Contract manufacturers must maintain parallel compliance with EU MDR post-market surveillance and FDA predicate device policies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Implants and Prosthetics Contract Manufacturing Market |
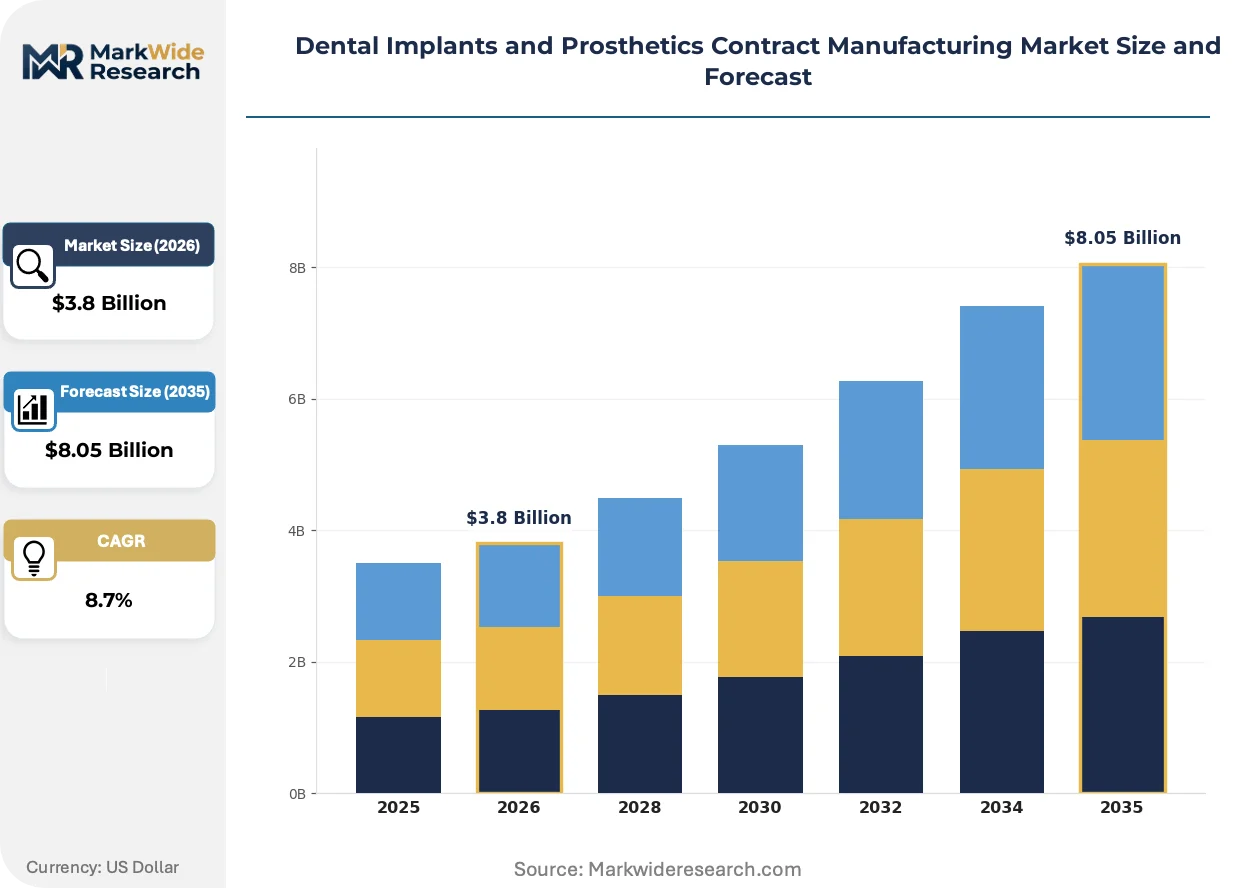
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Implants, Abutments, Prosthetic Components, Accessories Material: Titanium, Zirconia, Acrylic, Stainless Steel Technology: CAD/CAM, 3D Printing, Machining, Surface Treatment End User: Dental Clinics, Hospitals, Research Institutions, Laboratories |
| Companies Covered | Halder GmbH, Cendres+Métaux Medtech, Elos Medtech AB, Tectri SA, Acrotec Medtech, BIOPLATE, Micron Products INC, Wesley Coe Ltd, ARCH Medical Solutions Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Implants and Prosthetics Contract Manufacturing Market Evolving Landscape
Digital dentistry workflows are compressing production cycles from weeks to days, forcing contract manufacturers to integrate real-time design feedback and same-day fabrication capabilities.
Additive manufacturing of cobalt-chrome superstructures is miniaturizing batch economics for dental laboratories. Mid-sized labs in Germany and Switzerland are adopting compact metal 3D printers for chairside framework production. This technology is miniaturizing the minimum viable order size from 50-unit production runs down to single-patient same-day fabrication.
EU MDR's post-market clinical follow-up requirements are extending supplier liability windows for contract manufacturers. Device history records must now span 15-year implant lifecycles rather than the previous 10-year standard. Titanium abutment suppliers with validated long-term fatigue data under ISO 5832-3 specifications are capturing expanded OEM mandates.
Group purchasing organizations at dental clinic chains are consolidating component sourcing around qualified contract manufacturers. Independent practices in France and Belgium are losing price leverage as procurement centralizes through DSO procurement platforms. Germany's KZBV-contracted laboratories are experiencing the most visible concentration pressure.
Dental Implants and Prosthetics Contract Manufacturing Market Segmentation
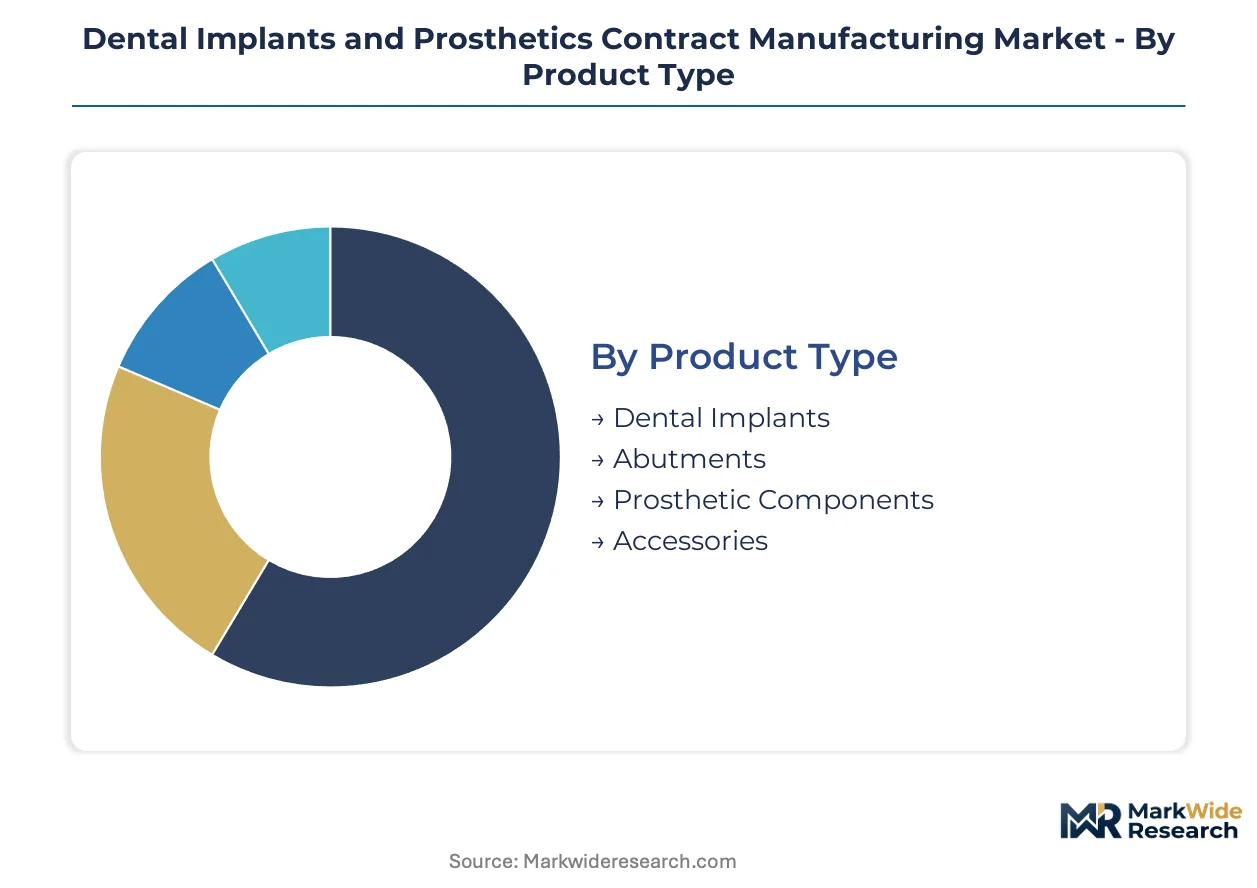
Segmentation in dental contract manufacturing reveals where OEM procurement budgets flow and where regulatory compliance creates supplier stickiness. Each dimension—product, material, technology, and end user—carries distinct margin profiles and qualification barriers that reshape competitive positioning.
Product Type:
Premium margins concentrate in components requiring validated fatigue data and long-term implant lifecycle documentation.
- Abutments:Precision-machined titanium and zirconia connectors machined to ISO 5832-3 specifications with Ra surface finishes below 0.8 micrometers. German and Swiss dental clinics dominate procurement as CE marking under EU MDR tightens quality requirements for these load-bearing components.
- Prosthetic Components:CAD/CAM-fabricated crowns, bridges, and superstructures represent the fastest-expanding revenue pool as chairside digital workflows compress production cycles. French and Belgian dental laboratories are consolidating sourcing around qualified contract manufacturers with validated regulatory dossiers.
- Dental Implants:Endosseous fixtures requiring proprietary surface treatment protocols for osseointegration.
- Accessories:Healing caps, impression copings, and surgical instruments with lower regulatory burden.
The dominant share belongs to abutments, while prosthetic components are gaining share fastest.
Material:
Input cost volatility and biocompatibility certification requirements stratify supplier tiers across material categories.
- Titanium:ISO 5832-3 compliant alloys remain the mature revenue base for fatigue strength exceeding 600 MPa. Swiss and German contract manufacturers anchor European demand through validated machining lines that sustain long-term supply agreements with major implant brands.
- Zirconia:High-precision milling for aesthetic dentistry applications commands premium pricing due to CE marking requirements under EU MDR. Cendres+Métaux Medtech leverages Swiss heritage to dominate this segment for European dental OEMs.
- Acrylic:Temporary prosthetics and diagnostic wax-ups with shorter regulatory pathways.
- Stainless Steel:Surgical instruments and auxiliary components with baseline ISO 10993 requirements.
Titanium retains the largest procurement volume, though zirconia shows the steepest margin expansion trajectory.
Technology:
Capital intensity and proprietary know-how determine which production methods sustain pricing power against commoditization.
- Surface Treatment:Electropolishing and anodizing protocols for hydrophilic implant surfaces command premium pricing due to proprietary expertise concentrated in Sweden and Denmark. Elos Medtech AB competes from Scandinavia with specialized capabilities that differentiate contract offerings for osseointegration-focused implants.
- CAD/CAM:Computer-aided design and manufacturing leads unit volume across European contract manufacturers as digital dentistry workflows compress production cycles from weeks to days.
- 3D Printing:Direct metal laser sintering of cobalt-chrome and PEEK frameworks miniaturizes batch economics for mid-sized laboratories in Germany and Switzerland.
- Machining:Subtractive precision manufacturing for titanium abutments with established ISO 13485-certified production lines.
CAD/CAM dominates unit output, yet surface treatment captures the highest value per component.
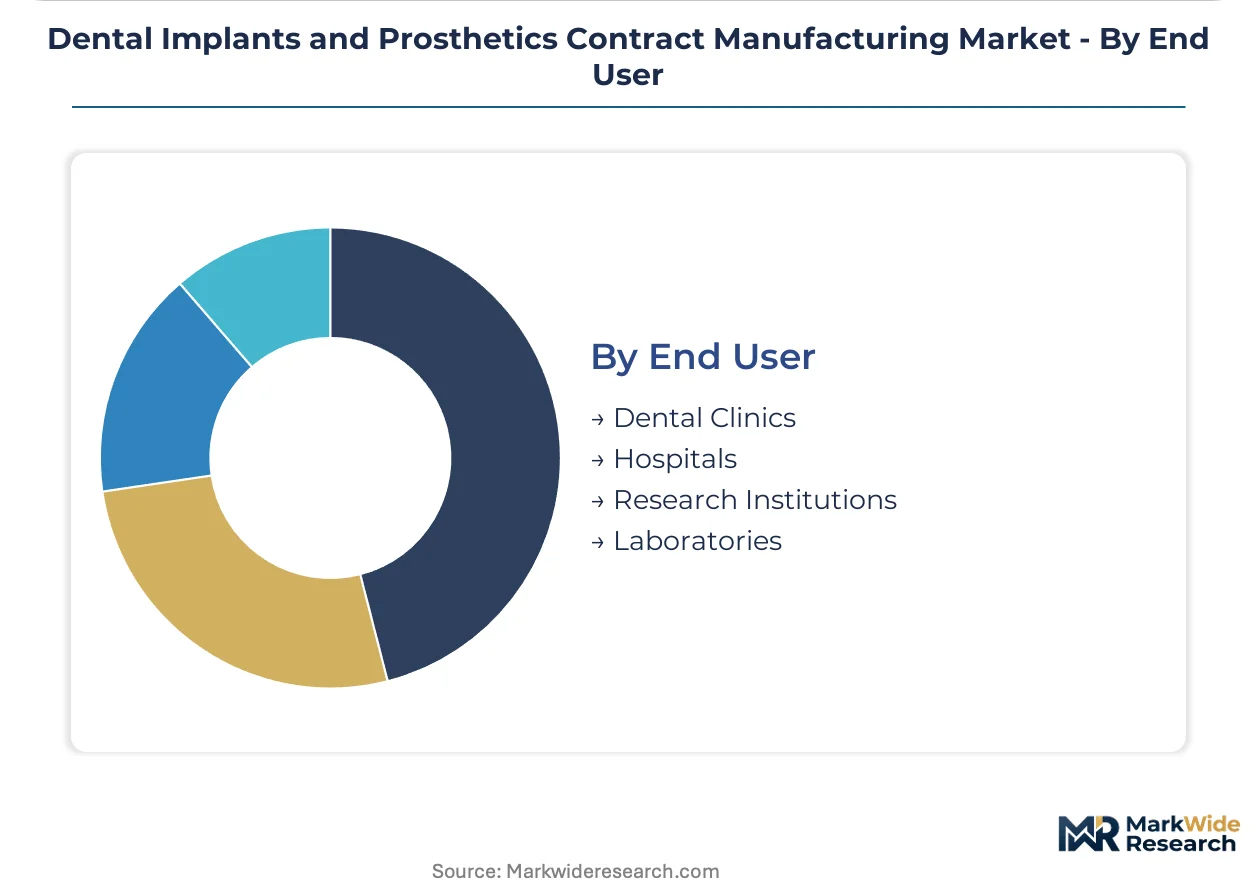
End User:
Procurement centralization through group purchasing organizations is restructuring demand concentration across customer types.
- Dental Clinics:Germany's KZBV-contracted laboratories and independent practices in France and Belgium are experiencing concentration pressure as procurement centralizes through DSO platforms. Swiss clinics maintain direct relationships with premium contract manufacturers.
- Laboratories:Mid-sized German and Swiss labs adopting compact metal 3D printers for chairside framework production are shifting from 50-unit production runs toward single-patient same-day fabrication.
- Hospitals:Academic medical centers with implant dentistry programs requiring 15-year device history records under EU MDR post-market surveillance.
- Research Institutions:Preclinical and clinical investigation sites with specialized biocompatibility testing needs.
Dental clinics command the largest procurement volume, while laboratories are shifting their buying patterns most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in precision-machined dental components favor established European manufacturing clusters. Germany and Switzerland maintain trade surpluses in titanium abutments and zirconia prosthetics, while import dependence characterizes emerging demand centers seeking ISO 13485-certified supply.
Germany
Dental clinics across Bavaria and Baden-Württemberg are consolidating procurement through KZBV-contracted laboratory networks. CE marking under EU MDR tightens quality requirements for titanium devices, extending supplier qualification timelines. The Stuttgart precision engineering corridor hosts validated machining lines sustaining long-term supply agreements with major implant brands.
Switzerland
Swiss dental clinics maintain direct relationships with premium contract manufacturers for high-precision zirconia milling. Swissmedic enforces clinical evidence standards that parallel EU MDR requirements for biocompatible devices. The Jura Arc watchmaking region repurposes micron-level machining expertise toward dental abutment fabrication.
France
Independent practices in Île-de-France and Auvergne-Rhône-Alpes are losing price leverage as procurement centralizes through dental service organization platforms. ANSM oversees post-market surveillance alignment with EU MDR post-market clinical follow-up rules. The Lyon medical device cluster concentrates CAD/CAM fabrication capacity for chairside digital workflows.
Sweden
Scandinavian demand concentrates on surface treatment capabilities for osseointegration-focused implants. The Swedish Medical Products Agency enforces ISO 10993 biocompatibility standards as baseline market entry criteria. The Gothenburg life sciences corridor specializes in electropolishing and anodizing protocols for hydrophilic implant surfaces.
United States
Private-label contract manufacturing for FDA 510(k) pathway clearance creates dual-qualification revenue streams beyond EU compliance. The FDA's predicate device policies govern market access for titanium and zirconia implants sold under OEM brands. The Minneapolis medical device cluster and Boston biotechnology corridor concentrate regulatory expertise for multi-region product lines.
Dental Implants and Prosthetics Contract Manufacturing Market Competitive Landscape
Concentration sits with ISO 13485-certified precision manufacturers holding validated regulatory dossiers. Swiss and German fabricators anchor European supply for titanium abutments and zirconia prosthetics, while Scandinavian specialists differentiate through surface treatment protocols. Three archetypes define competitive positioning: heritage precision engineers with micron-level machining legacy, medical device specialists with parallel orthopedic expertise, and surface treatment innovators with proprietary electropolishing capabilities. Capacity expansion and strategic partnerships dominate competitive moves as OEMs consolidate supplier relationships under tightened EU MDR requirements.
Among Swiss heritage fabricators, Cendres+Métaux Medtech and Tectri SA occupy positions reflecting the Jura Arc's precision engineering tradition. Halder GmbH anchors German demand through validated production infrastructure. Elos Medtech AB exemplifies Scandinavian specialization in surface treatment differentiation. These three represent distinct competitive archetypes: micron-level zirconia milling heritage, established titanium machining scale, and proprietary osseointegration surface protocols.
| Leading Market Players |
|---|
| Halder GmbH |
| Cendres+Métaux Medtech |
| Elos Medtech AB |
| Tectri SA |
| Acrotec Medtech |
| BIOPLATE |
| Micron Products INC |
| Wesley Coe Ltd |
| ARCH Medical Solutions Corp |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German dental OEMs and Swiss contract manufacturers lock in titanium billet supply access while providing 12-18 month price visibility against ISO 5832-3 alloy volatility. These contracts bundle precision machining capacity with regulatory dossier maintenance, insulating qualified suppliers from spot market pressure while exposing non-certified competitors to margin compression.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in dental contract manufacturing. Premium tiers capture ISO 13485-certified production with validated fatigue data under EU MDR requirements, while standard tiers serve laboratories with CE-marked but non-specialized components. Price differentiation hinges on certification grade and surface treatment sophistication, with electropolishing protocols commanding substantial premiums. Cost compression in economy tiers is intensifying because 3D-printed cobalt-chrome frameworks displace subtractive machining volumes. Independent dental clinics in France and Belgium exhibit highest price sensitivity, whereas German KZBV-contracted laboratories prioritize supply security over unit cost.
Supply Chain Analysis
Germany and Switzerland anchor precision-machined titanium abutment fabrication, while Sweden and Denmark concentrate electropolishing and anodizing capabilities for hydrophilic implant surfaces. The supply chain draws from ISO 5832-3 compliant titanium billet, zirconia ceramic feedstock, and specialized cutting tool consumables. Single-source vulnerability characterizes high-precision zirconia milling, where Cendres+Métaux Medtech and limited Swiss heritage fabricators dominate validated production lines. Distribution runs through dental service organization procurement platforms that consolidate component sourcing for clinic chains, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental contract manufacturing functions as a substitution defense against additive manufacturing of cobalt-chrome and PEEK frameworks that threaten traditional subtractive machining volumes. Incumbents must navigate this displacement while tightening EU MDR requirements extend supplier liability windows.
For Market Incumbents: Consolidate supplier relationships around ISO 13485-certified production infrastructure with validated 15-year device history records. Acquire surface treatment capabilities in Scandinavia to differentiate against commoditized machining, as Elos Medtech AB has demonstrated with proprietary electropolishing protocols. Backward integration into titanium billet sourcing mitigates input cost volatility from ISO 5832-3 alloy pricing. For New Entrants and Emerging Players: Anchor in Scandinavian surface treatment specialization where electropolishing and anodizing expertise remains concentrated among few qualified suppliers. Target mid-sized German and Swiss dental laboratories adopting compact metal 3D printers for chairside framework production, as these buyers shift from volume procurement toward single-patient same-day fabrication partnerships. Pursue FDA 510(k) pathway dual-qualification to access private-label contract manufacturing beyond EU MDR compliance. For Investors and Strategic Acquirers: Capital is best deployed toward ISO 13485-certified precision manufacturers with validated regulatory dossiers and established OEM supply agreements. The acquisition target archetype combines micron-level machining heritage with parallel orthopedic device expertise, enabling cross-industry quality system leverage. Watch FDA predicate device policy evolution as inflection indicator for US market access viability of European contract manufacturing assets.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management system audits filter smaller machine shops from OEM procurement lists under tightened EU MDR requirements. |
| Surface Treatment Capability Acquisition | Proprietary electropolishing and anodizing protocols command premium pricing for hydrophilic implant surfaces in Sweden and Denmark. |
| FDA 510(k) Dual-Qualification | Private-label contract manufacturing for US market access creates revenue streams beyond EU MDR compliance constraints. |
| CAD/CAM Workflow Integration | Real-time design feedback and same-day fabrication capabilities compress production cycles from weeks to days for German laboratories. |
| Long-Term Supply Agreement Structuring | Validated titanium machining lines sustain procurement relationships with major implant brands through 15-year device history records. |
Research Methodology
A standing panel of contract manufacturing executives, dental OEM procurement directors, regulatory affairs specialists, and laboratory operations managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EU MDR guidance documents, FDA 510(k) clearance databases, ISO 13485 audit registries, and dental industry trade association publications. Bottom-up component demand modeling triangulated against top-down OEM procurement budget analysis.
Consistency checks validated volume and value outputs against external benchmarks including customs trade flows for precision-machined dental components, GPO contract disclosure filings, and hospital procurement database extracts. Segmentation dimensions spanned product type, material grade, production technology, and end-user procurement channel across the projection horizon. CAGRs were derived from regression analysis of historical qualification timelines and OEM supplier consolidation patterns, with titanium alloy pricing volatility and regulatory audit frequency as industry-specific forecast inputs.
Material uncertainties — EU MDR post-market surveillance enforcement intensity, FDA predicate device policy shifts, and additive manufacturing substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification timeline stability and OEM supplier consolidation continuity. Recalibration cycles align with material shifts in regulatory audit protocols and dental laboratory digital workflow adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
APAC Ablation Devices Market
Medical Devices
Global Artificial Organ Market
Medical Devices
Smart Syringe Market
Medical Devices
Global Gynecological Dilators Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
US Electrosurgical Generators Market
Medical Devices
Electric Handpiece Market
Medical Devices
Global Biopsy Punch Market
Medical Devices
North America 3D Printing in Healthcare Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Global Aneurysm Clips Market