
 Medical Device Analytical Testing Outsourcing Market | 2026-2036
Medical Device Analytical Testing Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Analytical Testing Outsourcing Market Intelligence
North American laboratory capacity expansion is reconfiguring competitive dynamics in outsourced analytical testing. SGS leverages its network of ISO 17025-accredited facilities to anchor quality control workflows for implantable device sponsors. WuXi AppTec competes through integrated biocompatibility and sterility testing suites that span early-phase through commercial batches.
Medical device analytical testing outsourcing covers the delegation of physicochemical, biological, and functional validation activities to third-party laboratories, typically performed under GLP conditions with documented chain-of-custody protocols. The practice enables manufacturers to access specialized mass spectrometry and liquid chromatography platforms without capital investment in captive infrastructure. Biocompatibility testing commands premium pricing due to ISO 10993 series complexity and the scarcity of laboratories holding dual accreditation for both cytotoxicity and sensitization studies. Sterility testing represents a mature, high-volume segment where automation and rapid microbial methods are displacing traditional fourteen-day incubation cycles.
FDA 21 CFR Part 820 quality system regulations and the EU Medical Device Regulation's notified body requirements shape outsourcing demand by mandating independent analytical verification for substantial equivalence and CE marking submissions. The FDA's Center for Devices and Radiological Health intensifies scrutiny of computational modeling claims, pushing manufacturers toward outsourced finite element analysis validation. Stakeholders must weigh captive laboratory investment against the flexibility of multi-site outsourcing contracts as regulatory divergence between FDA and EMA biocompatibility endpoints widens.
Market Dynamics
FDA cybersecurity guidance for connected devices is forcing cardiovascular and neuromodulation manufacturers to expand analytical testing budgets beyond traditional biocompatibility validation.
Growth Catalysts
- ISO 10993-1 Biological Evaluation Framework:The FDA's harmonization with this international standard accelerates outsourcing demand from polymer-coated stent developers seeking streamlined submission pathways.
- Mass spectrometry platform specialization:Extractables and leachables testing for combination products drives sponsor reliance on third-party laboratories with captive LC-MS/MS infrastructure.
- United States Class III device concentration:The clustering of PMA innovators in Massachusetts and California sustains premium outsourcing relationships for preclinical validation.
Market Restraints
- Dual-accreditation scarcity:Laboratories holding both ISO 17025 and GLP certifications for cytotoxicity and sensitization studies command 40-60% pricing premiums, compressing sponsor margins.
- Reference standard supply concentration:Certified reference materials for extractables profiling originate from fewer than twelve qualified suppliers globally, creating input bottlenecks.
- EU MDR notified body capacity:The contraction of designated bodies under the Medical Device Regulation extends analytical verification timelines for European market entry.
Strategic Opportunities
- India CDSCO regulatory alignment:The country's medical device rules convergence with IMDRF standards creates outsourcing demand from domestic manufacturers seeking export certification.
- Rapid microbial methods:ATP bioluminescence and flow cytometry adoption displaces fourteen-day sterility incubation, enabling laboratories to capture volume from automated manufacturing lines.
- Computational modeling validation:FDA CDRH scrutiny of finite element analysis claims for orthopedic implants opens specialized service lines combining physical and in-silico verification.
Industry Challenges
- GLP study director certification:The twelve-to-eighteen-month qualification timeline for toxicology study directors constrains laboratory expansion velocity.
- Legacy LIMS integration:Sponsor quality systems built on decade-old laboratory information management platforms resist API connectivity with outsourced data workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Analytical Testing Outsourcing Market |
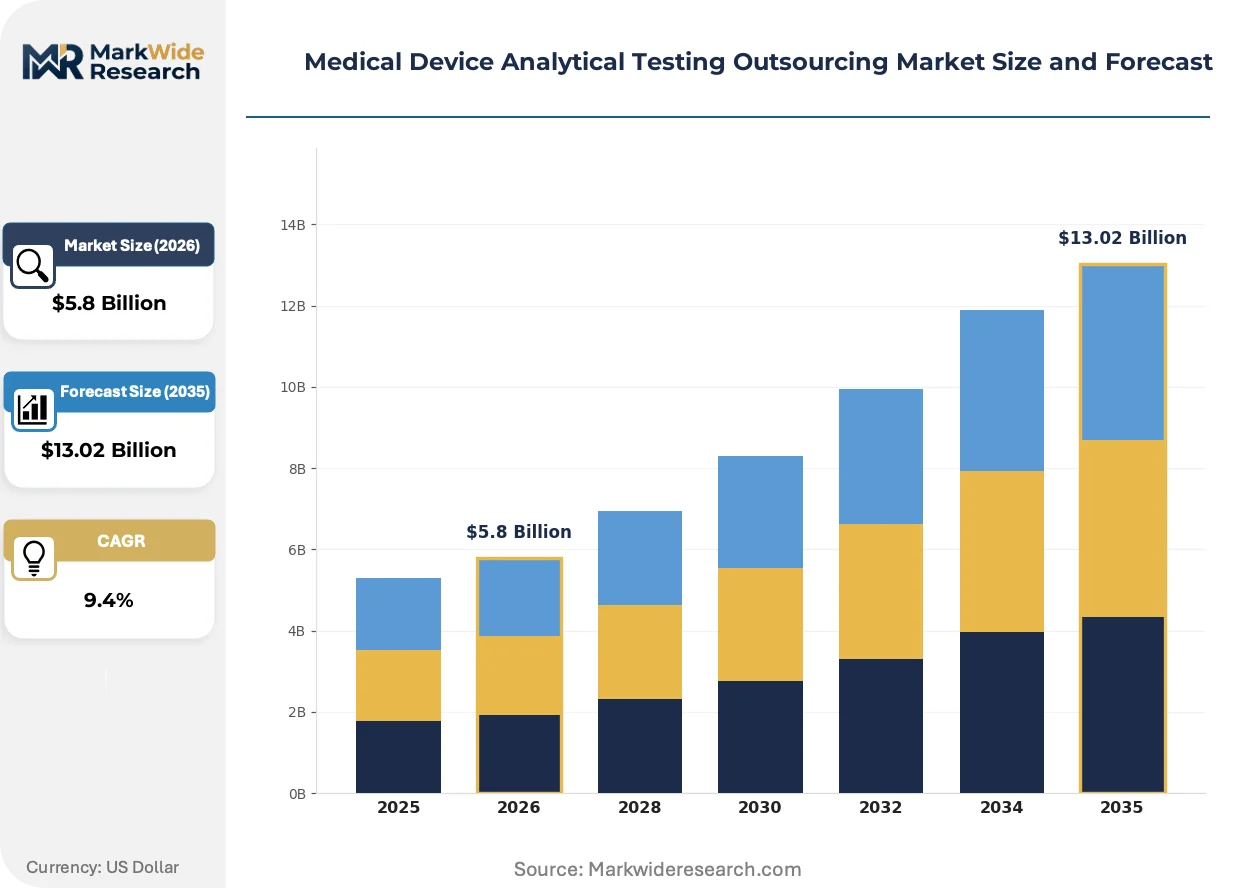
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Stability Testing, Sterility Testing, Biocompatibility Testing, Functionality Testing End User: Hospitals, Laboratories, Medical Device Manufacturers, Research Institutions Technology: Liquid Chromatography, Mass Spectrometry, Spectrophotometry, Electrophoresis Application: Quality Control, Regulatory Compliance, Research & Development, Product Development |
| Companies Covered | SGS, Eurofins Scientific, Toxikon, Pace Analytical Services, Intertek Group, WuXi AppTec, Charles River Laboratories, NAMSA, Nelson Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Analytical Testing Outsourcing Market Strategic Shifts & Innovations
Digital twin architectures and automated microbial detection systems are compressing analytical testing cycles while regulatory divergence between FDA and EMA biocompatibility endpoints fragments outsourcing strategies.
Computational toxicology platforms using QSAR modeling and read-across methodologies are virtualizing traditional animal-based biocompatibility screening. Cardiovascular implant manufacturers in the United States and Germany adopt these in-silico approaches for early-phase material qualification. The technology is virtualizing the front-end of ISO 10993 testing programs, reducing sponsor reliance on in-vivo studies for initial polymer selection.
The EU Medical Device Regulation's Annex I general safety and performance requirements intensify scrutiny of analytical verification documentation for legacy devices undergoing recertification. Notified bodies demand expanded chemical characterization data beyond what was acceptable under the Medical Device Directive. Orthopedic and dental implant portfolios with decades-old material specifications face the steepest compliance burden, driving renewal outsourcing to specialized European laboratories.
Original equipment manufacturers now unbundle analytical testing from full-service development contracts, establishing direct relationships with ISO 17025-accredited laboratories for recurring quality control batches. This disintermediation of contract research organizations concentrates volume with testing-only providers in the United States and Switzerland. The shift is most pronounced among mid-cap neuromodulation developers seeking transparent unit economics for PMA-supporting studies.
Medical Device Analytical Testing Outsourcing Market Segmentation
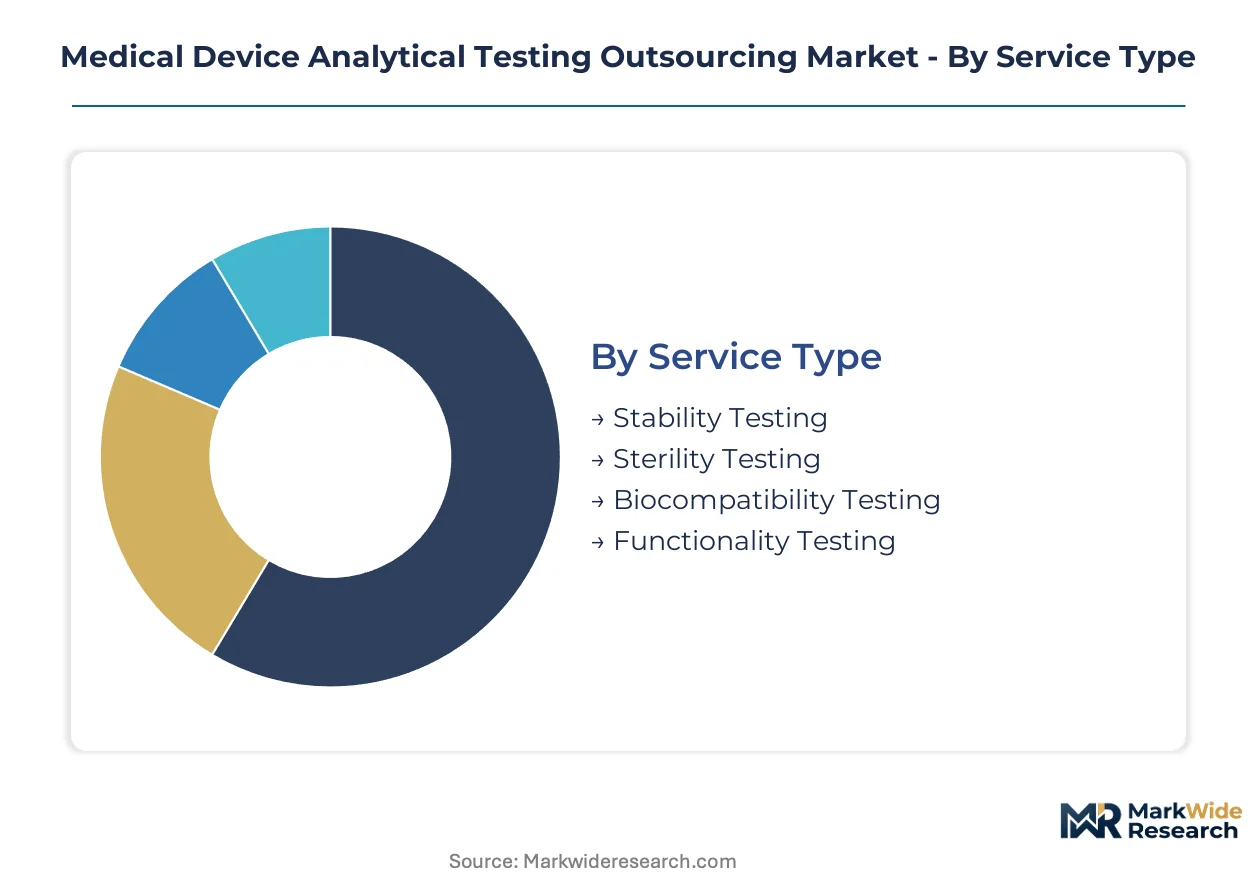
Testing complexity and regulatory stringency fragment the outsourcing landscape across service modalities, analytical platforms, and sponsor categories. Each dimension carries distinct margin profiles and capacity constraints that reshape procurement strategies for cardiovascular and orthopedic device developers.
Service Type:
Mature, high-volume segments compete alongside emerging specialties where accreditation scarcity sustains pricing power.
- Stability Testing:Accelerated aging protocols and real-time storage condition monitoring validate shelf-life claims for polymer-based delivery systems. Demand concentrates among implantable device sponsors in Massachusetts and California seeking FDA PMA submission support, driven by the Agency's intensified scrutiny of long-term material degradation data.
- Sterility Testing:Terminal sterilization validation and aseptic processing verification dominate volume, though rapid microbial methods are compressing traditional fourteen-day incubation cycles. European notified bodies under the EU MDR extend timelines for legacy device recertification, creating backlog demand for outsourced capacity.
- Biocompatibility Testing:ISO 10993-1 biological evaluation frameworks govern cytotoxicity, sensitization, and irritation screening for novel coatings.
- Functionality Testing:Mechanical performance, electrical safety, and software verification validate device-specific essential performance requirements.
Sterility Testing handles the majority of throughput; Biocompatibility Testing is the fastest mover on share.
End User:
Customer sophistication and regulatory exposure stratify outsourcing relationships from transactional batch testing to embedded partnership models.
- Medical Device Manufacturers:Original equipment sponsors unbundle analytical testing from full-service CRO contracts, establishing direct ISO 17025 laboratory relationships for recurring quality control. Mid-cap neuromodulation developers in the United States drive this disintermediation, seeking transparent unit economics for PMA-supporting studies.
- Laboratories:Reference laboratories and hospital-based testing facilities outsource specialized mass spectrometry and extractables profiling beyond captive capability.
- Hospitals:Point-of-care device validation and in-house sterilization monitoring create intermittent demand for third-party verification.
- Research Institutions:Academic medical centers and government laboratories contract GLP-compliant toxicology for early-phase material qualification.
Medical Device Manufacturers command the largest outsourcing spend; Research Institutions are expanding most quickly as computational toxicology platforms virtualize traditional screening.
Technology:
Platform specialization and capital intensity determine which analytical modalities remain captive versus outsourced.
- Mass Spectrometry:LC-MS/MS and GC-MS platforms enable extractables and leachables profiling for combination products with polymer-drug interfaces. Cardiovascular stent developers depend on third-party laboratories with captive infrastructure, as FDA guidance on container-closure systems tightens chemical characterization requirements.
- Liquid Chromatography:HPLC and UPLC systems separate and quantify active pharmaceutical ingredients, residual solvents, and degradation products in device coatings.
- Spectrophotometry:UV-Vis and FTIR techniques identify material composition and confirm coating uniformity across implant batches.
- Electrophoresis:Gel and capillary methods analyze protein binding and surface charge characteristics for biologic-device combinations.
Mass Spectrometry absorbs the highest outsourcing premiums; Liquid Chromatography shows the steepest expansion trajectory as combination product portfolios proliferate.
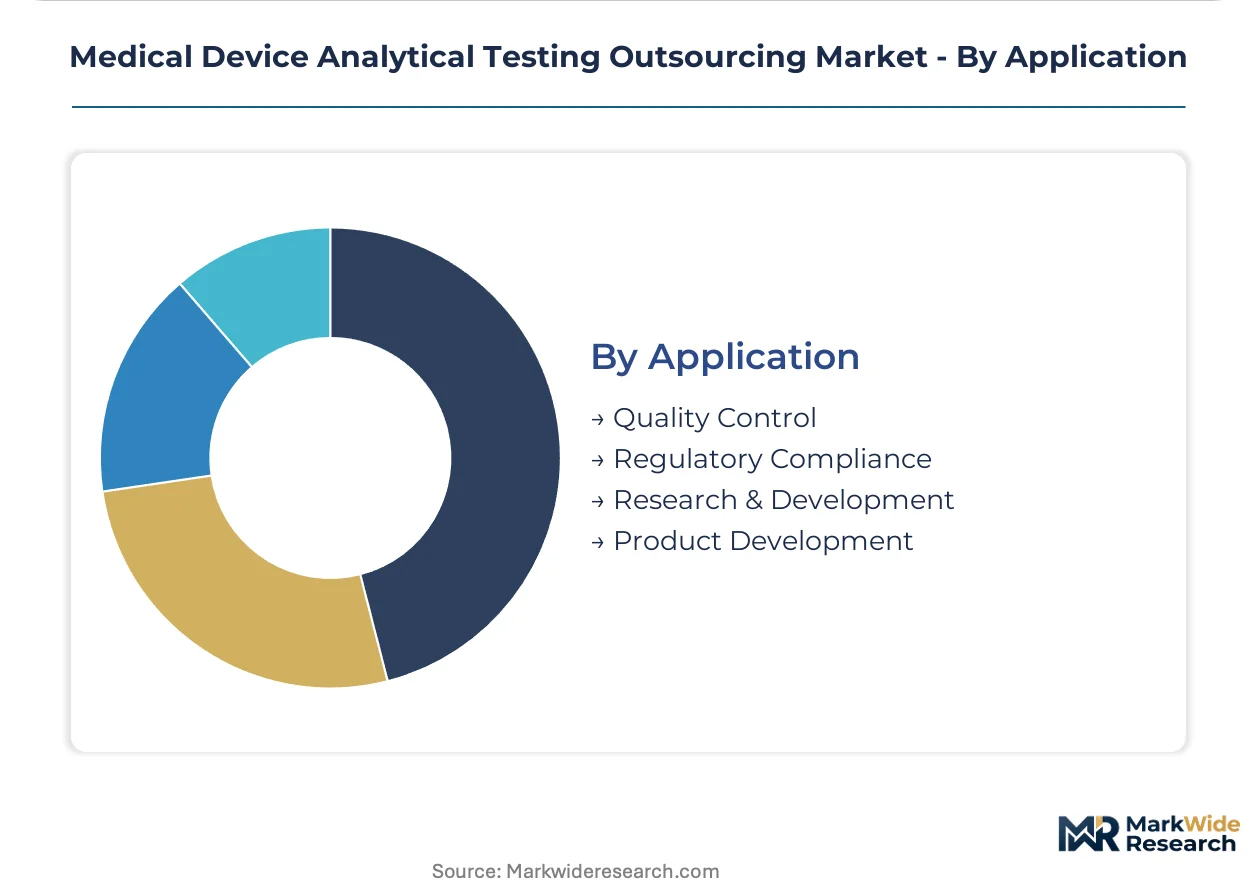
Application:
Regulatory milestone timing and documentation burden differentiate commercial-phase testing from development-phase screening.
- Regulatory Compliance:FDA 21 CFR Part 820 quality system verification and EU MDR notified body submissions mandate independent analytical documentation. Orthopedic and dental implant portfolios with decades-old specifications face the steepest compliance burden under expanded Annex I general safety requirements.
- Quality Control:Release testing and incoming raw material verification sustain recurring revenue relationships with high-volume manufacturers.
- Research & Development:Early-phase material selection and prototype screening utilize computational modeling and in-silico toxicology to reduce animal study burden.
- Product Development:Design verification and process validation bridge engineering iterations toward regulatory submission readiness.
Quality Control generates the most predictable outsourcing volume; Regulatory Compliance is climbing the fastest as MDR recertification deadlines concentrate demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States sponsors concentrate analytical spend on preclinical validation for PMA submissions, while German manufacturers emphasize MDR recertification documentation and Indian domestic producers prioritize export certification alignment.
United States
Class III device innovators in Massachusetts and California sustain premium outsourcing relationships for biocompatibility and sterility validation. FDA 21 CFR Part 820 quality system regulations mandate independent analytical verification for substantial equivalence claims. The FDA's Center for Devices and Radiological Health intensifies scrutiny of computational modeling claims, pushing sponsors toward outsourced finite element analysis.
Germany
Orthopedic and dental implant portfolios with decades-old specifications face steep compliance burdens under EU MDR Annex I general safety requirements. The EU Medical Device Regulation's notified body capacity contraction extends analytical verification timelines, creating backlog demand for specialized European laboratories. Stuttgart and Munich host clusters of ISO 17025-accredited facilities serving recertification campaigns.
Switzerland
Mid-cap neuromodulation developers establish direct relationships with testing-only providers for transparent unit economics on PMA-supporting studies. Swissmedic requirements for analytical documentation sustain demand for independent verification services. Basel and Zurich laboratories capture volume from disintermediated contract research organization relationships.
India
Domestic manufacturers seek export certification as CDSCO regulatory alignment with IMDRF standards accelerates. The country's medical device rules convergence creates outsourcing demand for biocompatibility validation supporting CE marking and FDA submissions. Hyderabad and Bengaluru clusters house emerging analytical capacity serving both domestic and international sponsors.
China
Combination product developers with polymer-drug interfaces require extractables and leachables profiling for NMPA submissions. GB standards and SAMR oversight tighten chemical characterization requirements for cardiovascular stent coatings. Shanghai and Suzhou laboratories build captive LC-MS/MS infrastructure to serve domestic and multinational sponsors.
Medical Device Analytical Testing Outsourcing Market Key Industry Players
Capability concentration sits with laboratories holding dual ISO 17025 and GLP accreditations for cytotoxicity and sensitization studies; scale advantage sits with networks spanning multiple jurisdictions for sponsor quality control workflows. The market structures around three tiers: global accreditation networks, integrated biocompatibility-sterility suites, and specialized rapid microbial method providers. Dominant competitive moves include ISO 17025 facility expansion in high-demand clusters and unbundling of analytical services from full-service development contracts.
Within the global accreditation network tier, SGS anchors quality control workflows through its ISO 17025-accredited facility network. WuXi AppTec occupies a position exemplifying the integrated suite archetype, spanning early-phase through commercial batch services. Eurofins Scientific represents the European-centered capacity expansion vector, serving MDR recertification demand from notified body backlog.
| Leading Market Players |
|---|
| SGS |
| Eurofins Scientific |
| Toxikon |
| Pace Analytical Services |
| Intertek Group |
| WuXi AppTec |
| Charles River Laboratories |
| NAMSA |
| Nelson Labs |
| Others |
Cost & Logistics Intelligence
Reference standard supply concentration from fewer than twelve qualified suppliers globally determines both tiered pricing spreads across ISO 17025-accredited laboratories and the geographic shape of outsourcing networks. Cardiovascular implant manufacturers face compressed margins as dual-accreditation scarcity for cytotoxicity and sensitization studies amplifies cost differentials between premium and standard service tiers.
Pricing Analysis
United States laboratories command 40-60% premiums over European counterparts for biocompatibility validation supporting FDA PMA submissions. Three-tier pricing structure across premium, standard, and economy levels separates dual-accredited GLP-ISO 17025 facilities from single-accreditation providers and unaccredited regional laboratories. Pricing pressure stems from rapid microbial method adoption compressing traditional sterility testing margins. Mid-cap neuromodulation developers exhibit highest price sensitivity, seeking transparent unit economics through disintermediated direct laboratory relationships, while Class III cardiovascular sponsors prioritize accreditation tier over cost.
Supply Chain Analysis
Certified reference materials for extractables profiling feed from United States, Germany, and Japan, with polymer standards and chromatographic reagents anchoring upstream dependencies. LC-MS/MS platform components and high-purity solvents draw from specialized chemical manufacturers in Switzerland and the Netherlands. Single-source vulnerability concentrates around ion mobility spectrometry calibration standards from limited qualified vendors. Distribution runs through ISO 17025-accredited facility networks rather than traditional distributor channels, with sponsor quality systems demanding direct chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical device analytical testing outsourcing market sits in early-cycle expansion as FDA cybersecurity guidance for connected devices forces cardiovascular and neuromodulation manufacturers to expand validation budgets beyond traditional biocompatibility scopes.
For Market Incumbents: Build dual-accreditation moats by securing concurrent ISO 17025 and GLP certifications for cytotoxicity and sensitization studies before regulatory divergence between FDA and EMA endpoints widens further. Add captive LC-MS/MS capacity in Massachusetts and California clusters to capture combination product extractables demand from stent developers. Consolidate position against emerging rapid microbial method specialists by automating fourteen-day sterility incubation cycles internally. For New Entrants and Emerging Players: Build out computational modeling validation capabilities in Stuttgart and Munich to serve EU MDR recertification backlogs for orthopedic implant portfolios with decades-old specifications. Target Indian CDSCO-aligned export certification demand from domestic manufacturers in Hyderabad and Bengaluru seeking CE marking and FDA submission support. Lead with transparent project-based pricing to disintermediate full-service CRO relationships among mid-cap neuromodulation developers. For Investors and Strategic Acquirers: EU MDR notified body capacity contraction reshapes the acquisition landscape toward specialized European laboratories with Annex I general safety documentation expertise. The five-to-ten-year viability window favors testing-only providers over integrated CROs as OEM unbundling accelerates. Target acquisition candidates with rapid microbial method platforms and ATP bioluminescence capabilities. Watch FDA CDRH scrutiny of finite element analysis claims as the signal for computational modeling service line inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Accreditation Facility Expansion | ISO 17025 and GLP certification scarcity commands 40-60% pricing premiums from cardiovascular sponsors. |
| Rapid Microbial Method Adoption | ATP bioluminescence and flow cytography displace fourteen-day sterility incubation for automated manufacturing lines. |
| Computational Modeling Validation | FDA CDRH scrutiny of finite element analysis claims opens specialized service lines for orthopedic implants. |
| Direct Laboratory Relationships | Mid-cap neuromodulation developers disintermediate CROs for transparent PMA-supporting study economics. |
| India Export Certification Alignment | CDSCO convergence with IMDRF standards creates biocompatibility demand for CE marking and FDA submissions. |
Research Approach
Desk research of FDA 21 CFR Part 820 guidance documents, EU MDR Annex I technical specifications, ISO 10993 series standards, and notified body designation records preceded structured interviews with GLP study directors, regulatory affairs managers at cardiovascular device sponsors, quality control executives at contract laboratories, and procurement leads at mid-cap neuromodulation developers. Primary fieldwork combined with secondary validation from hospital procurement databases, GPO contracts, and CMS Medicare device reimbursement data. Bottom-up testing volume estimates triangulated against top-down market sizing from accreditation body facility counts.
Assumptions held fixed across the modeling period include sustained FDA-EMA regulatory divergence on biocompatibility endpoints and continued concentration of Class III device innovators in Massachusetts and California. Variables modeled across service type, technology platform, end-user category, and application phase generated segment-level CAGRs. Industry-specific inputs incorporated extractables testing demand from polymer-drug combination products and rapid microbial method displacement rates for traditional sterility protocols.
Stress conditions across EU MDR notified body capacity recovery timelines, reference standard supply chain disruptions, and GLP study director certification bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including cybersecurity guidance expansion to additional device categories and computational toxicology platform maturation. Cross-checking against accreditation body facility expansion announcements and sponsor capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Bleeding Disorders Testing Market
Testing Services
Asia-Pacific Newborn Screening Market
Testing Services
Cholesterol Testing Services Market
Testing Services
At-Home Testing Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Mask Bacterial Filtration Efficiency Tester Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Blood Sugar Tester Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Global Nitric Oxide Test Market