
 Germany Continuous Glucose Monitoring Market | 2026-2036
Germany Continuous Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Continuous Glucose Monitoring Market Insights
The Germany Continuous Glucose Monitoring Market is consolidating around a sharp split between premium closed-loop systems and commodity sensor-only offerings. Abbott Laboratories leverages its vertically integrated manufacturing to sustain cost leadership in disposable sensors. Dexcom differentiates through algorithm-intensive transmitters that anchor high-margin recurring revenue streams.
Continuous glucose monitoring comprises wearable electrochemical sensors that measure interstitial glucose concentrations via enzymatic reactions, transmitting data to receivers or smartphones for real-time glycemic management. Sensor segments dominate installed base volumes while integrated devices capture disproportionate margin pools through bundled software-analytics platforms. Diabetes Management applications lead clinical uptake, though Home Monitoring is expanding fastest as patient self-management protocols gain statutory reimbursement under Germany's Digital Care Act frameworks.
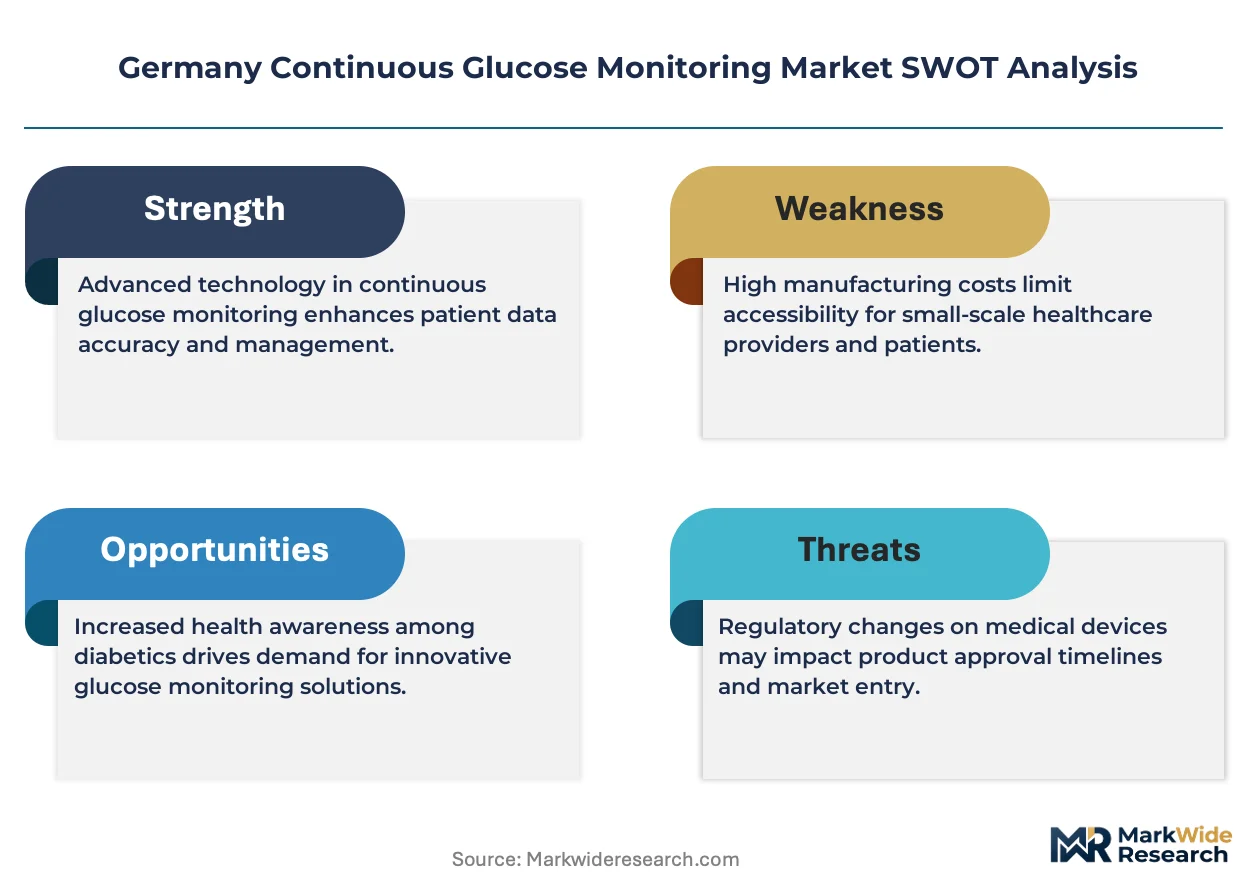
Regulatory oversight from BfArM, the EU Medical Device Regulation, and Germany's DiGA approval process shapes product commercialization timelines and reimbursement eligibility. BfArM's digital health application assessment criteria directly determine which connected CGM systems qualify for statutory insurance coverage. Stakeholders must monitor evolving EU MDR conformity requirements and regional reimbursement parity negotiations between statutory health insurers and device manufacturers.
Market Dynamics
Reimbursement pathway fragmentation between statutory health insurers and private payers is compressing commercial timelines for connected diabetes devices. Manufacturers must navigate parallel approval tracks through BfArM's DiGA process and regional sickness fund negotiations simultaneously.
Growth Catalysts
- DiGA Fast-Track Reimbursement:Germany's Digital Care Act framework accelerates statutory coverage decisions for algorithm-enabled glucose sensors, reducing time-to-market for connected devices by eliminating sequential approval steps.
- Home Monitoring Protocol Expansion:Patient self-management reimbursement codes now cover real-time data transmission to ambulatory care networks, shifting clinical validation from hospital settings to domestic environments.
- Metropolitan Hospital Consolidation:Bavaria and North Rhine-Westphalia health networks are standardizing procurement specifications across integrated care systems, creating volume concentration for compliant device vendors.
Market Restraints
- Sensor Manufacturing Input Concentration:Enzyme electrode production depends on captive glucose oxidase supply chains concentrated in Swiss and Dutch specialty chemical facilities.
- EU MDR Conformity Bottlenecks:Notified body capacity constraints extend technical documentation review timelines for electrochemical wearable classifications beyond historical CE-marking cycles.
- Optical Glucose Sensing Substitution:Non-invasive spectroscopic monitoring technologies under development at Dutch and Austrian research institutes threaten enzymatic sensor incumbency in pre-diagnostic applications.
Strategic Opportunities
- Underpenetrated Eastern States:Saxony and Thuringia exhibit lower CGM penetration rates relative to western Länder, presenting whitespace for ambulatory care network expansion.
- Algorithm-Insulin Pump Convergence:Integration between predictive glucose forecasting and automated insulin delivery creates bundled reimbursement opportunities under integrated care contracts.
- Telemedicine Platform Partnerships:Direct API connections to statutory insurer patient portals enable bypass of traditional durable medical equipment distribution channels.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time signal processing and machine learning model deployment for edge computing in wearable form factors requires specialized competencies concentrated in Munich and Berlin startup ecosystems.
- Clinical Evidence Generation Burden:BfArM's DiGA assessment criteria mandate prospective studies demonstrating measurable care pathway improvements, extending pre-commercialization investment horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Continuous Glucose Monitoring Market |
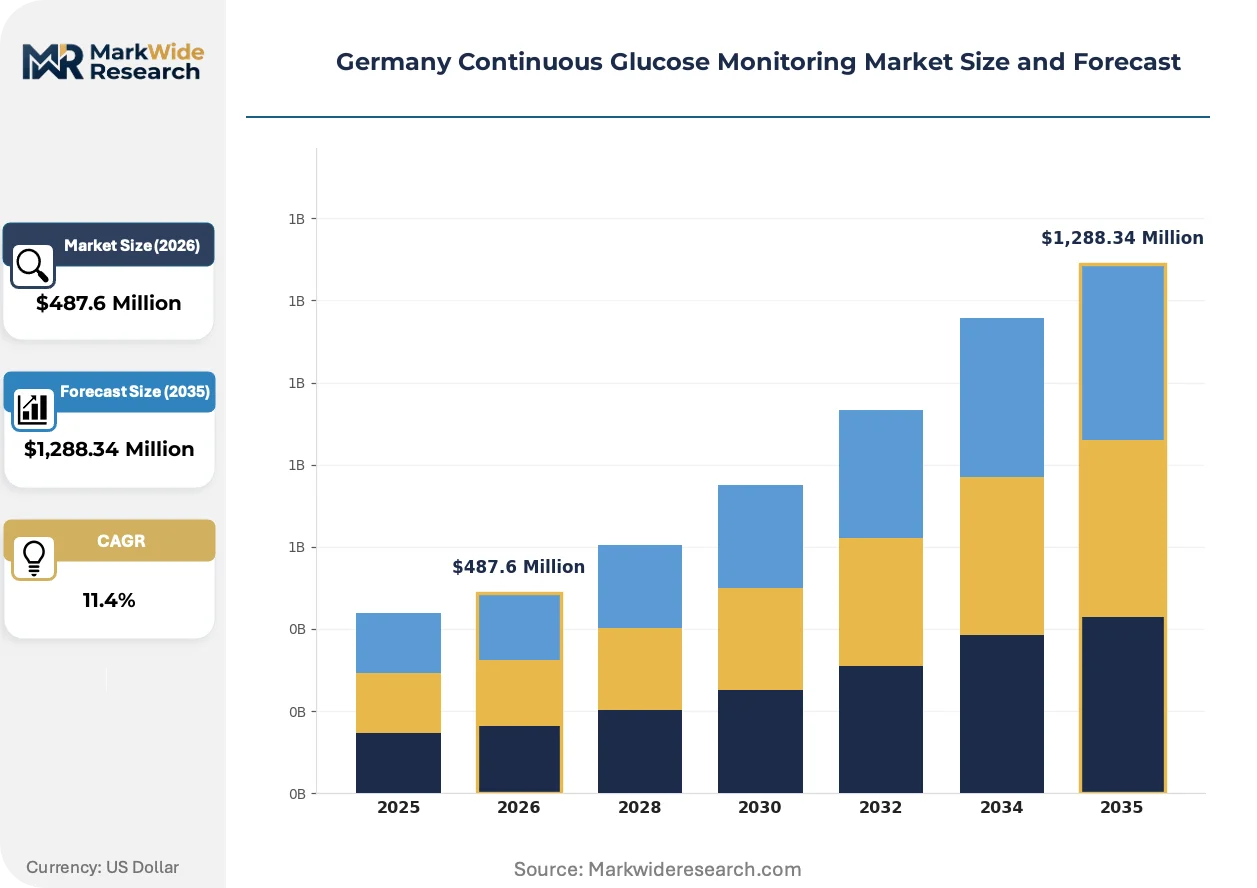
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor, Transmitter, Receiver, Integrated Device Application: Diabetes Management, Sports Health, Critical Care, Home Monitoring End User: Hospitals, Healthcare Professionals, Patients, Pharmacies Distribution Channel: Online, Retail, Medical Supplies wholesaler, Direct Sales |
| Companies Covered | Abbott Laboratories, Dexcom, Medtronic, Ascensia Diabetes Care, F. Hoffmann-La Roche, GlySens, Senseonics, Insulet, Ypsomed, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Continuous Glucose Monitoring Market Trends and Innovations
Algorithmic personalization is displacing one-size-fits-all glucose threshold alerts across German diabetes management protocols. Manufacturers are embedding machine learning inference directly on transmitter hardware to reduce latency and cloud dependency.
Factory-calibrated electrochemical sensors are electrifying patient onboarding workflows by eliminating fingerstick calibration requirements. Endocrinology practices in Hamburg and Cologne are adopting these devices for insulin-naïve Type 2 populations. The technology is compressing the clinical training burden and expanding addressable patient segments beyond intensive insulin users.
BfArM's evolving digital health application assessment criteria are tightening evidence standards for algorithm-driven therapeutic recommendations. Manufacturers must now submit prospective real-world data demonstrating HbA1c reduction or hypoglycemia prevention. Class IIb electrochemical wearables with predictive dosing suggestions face heightened scrutiny relative to basic monitoring-only configurations.
Subscription-based device provisioning is displacing capital purchase models in statutory insurance contracts. Sickness funds in Baden-Württemberg are piloting all-inclusive per-patient-per-month arrangements covering sensors, transmitters, and cloud analytics. This procurement evolution is compressing upfront revenue recognition and shifting manufacturer priorities toward retention metrics and consumable attach rates.
Germany Continuous Glucose Monitoring Market Segmentation
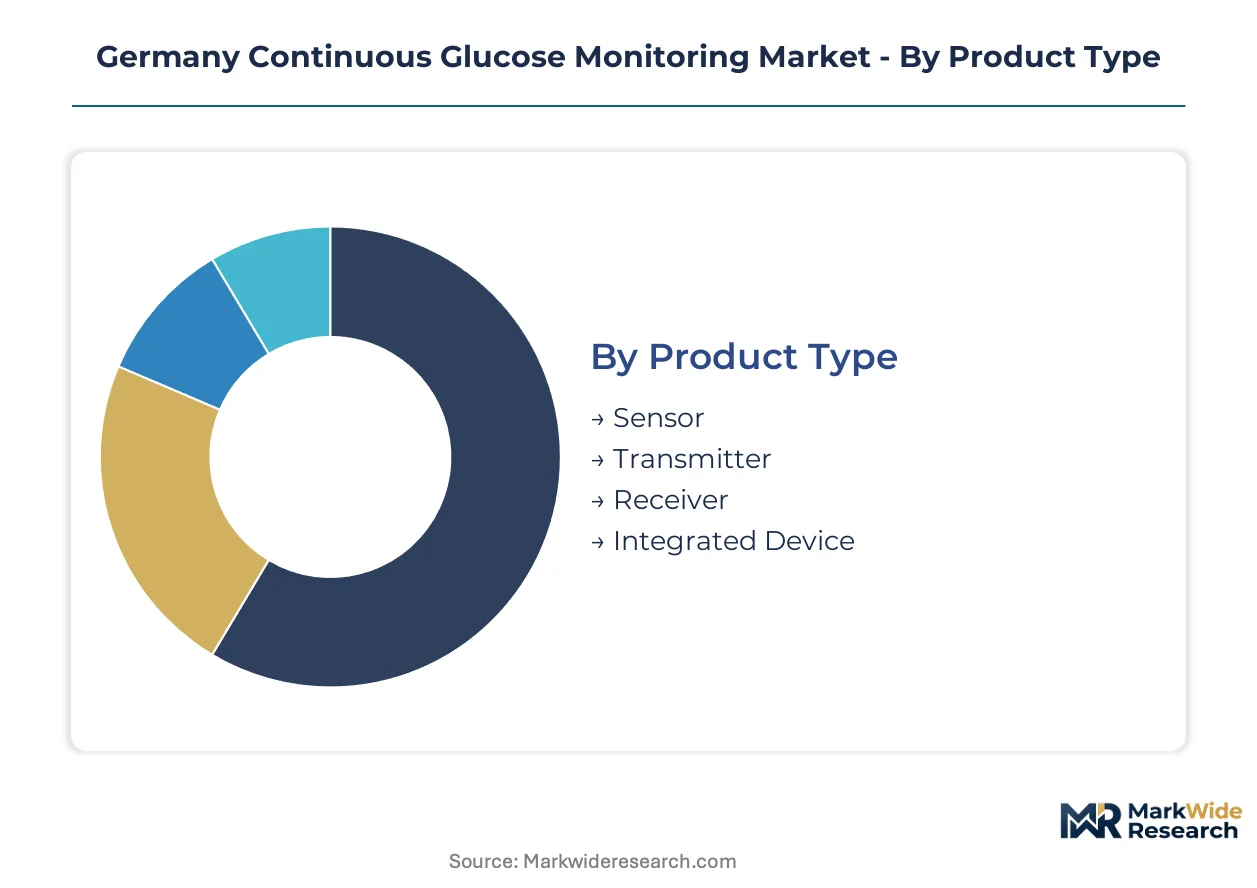
CGM market segmentation in Germany reveals divergent capital requirements across hardware tiers. Sensor manufacturing demands specialized electrochemical fabrication facilities, while software-analytics platforms require lower fixed costs but higher ongoing R&D commitment.
Product Type:
Capital intensity varies sharply across hardware layers, with electrochemical sensor production requiring the heaviest upfront manufacturing investment.
- Sensor:Disposable enzymatic electrodes dominate installed base volumes through factory-calibrated designs eliminating fingerstick calibration. Bavarian hospital networks are consolidating procurement around these single-use components for Type 1 populations.
- Transmitter:Algorithm-intensive hardware anchors recurring revenue streams via embedded machine learning inference reducing cloud dependency. Dexcom and Abbott differentiate through proprietary signal processing architectures in this segment.
- Receiver:Dedicated display units are ceding ground to smartphone integration, though elderly populations in rural Saxony retain preference for standalone devices with simplified interfaces.
- Integrated Device:Closed-loop systems combining sensor-transmitter-pump functionality command premium reimbursement under integrated care contracts in North Rhine-Westphalia.
Sensor production absorbs the bulk of installed manufacturing capacity; integrated devices are climbing the fastest as algorithm-insulin pump convergence accelerates.
Application:
Clinical validation requirements create divergent regulatory burdens across use cases, with therapeutic claims demanding heavier evidence generation than monitoring-only deployments.
- Diabetes Management:Intensive insulin therapy protocols drive statutory reimbursement eligibility through BfArM's DiGA assessment pathway. Endocrinology practices in Hamburg and Cologne standardize these devices for glycemic control.
- Home Monitoring:Patient self-management reimbursement codes now cover real-time data transmission to ambulatory networks. This segment is gaining share fastest as the Digital Care Act expands domestic coverage.
- Sports Health:Wellness-oriented glucose tracking for athletic performance optimization operates outside statutory insurance frameworks, relying on direct-to-consumer channels.
- Critical Care:ICU glycemic monitoring applications face stringent EU MDR Class IIb conformity requirements extending technical documentation review timelines.
Diabetes Management commands the dominant reimbursement pool; Home Monitoring shows the steepest expansion trajectory as self-management protocols gain statutory coverage.
End User:
Procurement authority concentration varies sharply, with hospital networks exercising centralized purchasing power while patient-directed channels fragment across statutory insurer portals.
- Hospitals:Metropolitan health networks in Bavaria and North Rhine-Westphalia standardize specifications across integrated care systems, creating volume concentration for compliant vendors.
- Healthcare Professionals:Endocrinology practices serve as gatekeepers for initial device prescriptions, with reimbursement eligibility determinations flowing through their clinical assessments.
- Patients:Direct statutory insurer portal access is displacing traditional durable medical equipment distribution for home-based populations in Baden-Württemberg.
- Pharmacies:Retail dispensing channels retain relevance for sensor resupply transactions, particularly in eastern Länder with lower telemedicine platform penetration.
Hospitals anchor the largest procurement volumes; direct patient channels are expanding most quickly as DiGA reimbursement bypasses traditional distribution.
Distribution Channel:
Channel economics reflect reimbursement pathway fragmentation, with statutory insurance contracts favoring direct provisioning models over retail markups.
- Online:Telemedicine platform partnerships enable API connections to statutory insurer patient portals, compressing traditional durable medical equipment margins.
- Retail:Pharmacy-based dispensing retains importance for cash-pay wellness segments and sensor resupply in regions with lower digital health adoption.
- Medical Supplies Wholesaler:Hospital procurement consortia leverage these intermediaries for volume aggregation across integrated care networks.
- Direct Sales:Manufacturer field forces target specialized endocrinology practices for initial prescription conversion and clinical training support.
Online channels are capturing the fastest growth as DiGA reimbursement integrates with statutory insurer portals; wholesale relationships retain hospital network dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors Germany's CGM manufacturing corridor through its concentration of embedded firmware engineering talent and proximity to Bavarian hospital procurement networks.
Bavaria
Metropolitan hospital networks in Munich and Nuremberg standardize procurement specifications across integrated care systems. BfArM's DiGA assessment pathway determines reimbursement eligibility for algorithm-enabled sensors in these networks. The Munich startup ecosystem supplies specialized talent for real-time signal processing and machine learning model deployment in wearable form factors.
North Rhine-Westphalia
Cologne and Düsseldorf health networks concentrate demand for closed-loop systems combining sensor-transmitter-pump functionality. The Digital Care Act framework accelerates statutory coverage decisions for connected devices in this industrial heartland. Endocrinology practices in these cities drive initial prescription conversion for factory-calibrated electrochemical sensors.
Baden-Württemberg
Sickness funds in Stuttgart and Mannheim pilot all-inclusive per-patient-per-month arrangements covering sensors, transmitters, and cloud analytics. Statutory insurer patient portals enable direct API connections, compressing traditional durable medical equipment distribution channels. Stuttgart's industrial base supports precision manufacturing for enzymatic electrode components.
Hamburg
Endocrinology practices in this northern port city standardize devices for insulin-naïve Type 2 populations through factory-calibrated designs. The city's telemedicine infrastructure facilitates real-time data transmission to ambulatory care networks under expanded Home Monitoring reimbursement codes. Hamburg's logistics hub function supports sensor resupply distribution to northern Länder.
Saxony
Lower CGM penetration rates relative to western Länder present whitespace for ambulatory care network expansion in Dresden and Leipzig. Pharmacy-based dispensing retains importance for sensor resupply in regions with lower telemedicine platform penetration. The state's emerging digital health adoption curve lags Bavarian and North Rhine-Westphalian benchmarks.
Germany Continuous Glucose Monitoring Market Competitive Landscape
Premium-margin players sit above commodity-margin players across algorithm sophistication and reimbursement tier access. The market consolidates around vertically integrated sensor manufacturers and algorithm-intensive transmitter specialists. Two strategic archetypes dominate: integrated closed-loop system vendors capturing bundled reimbursement contracts, and disposable sensor specialists optimizing manufacturing scale. Competitive moves center on DiGA approval acceleration and metropolitan hospital network procurement consolidation.
Within the integrated system tier, Abbott Laboratories and Dexcom occupy positions as archetype anchors. Abbott Laboratories exemplifies the vertically integrated manufacturer archetype through its captive supply of enzymatic electrode components. Dexcom represents the algorithm-intensive transmitter specialist model, embedding machine learning inference directly on hardware to reduce latency. Medtronic sits within the closed-loop convergence category, though its specific strategic positioning remains contingent on regulatory approval timelines and integrated care contract penetration.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom |
| Medtronic |
| Ascensia Diabetes Care |
| F. Hoffmann-La Roche |
| GlySens |
| Senseonics |
| Insulet |
| Ypsomed |
| Others |
Pricing and Supply Chain Analysis
Captive glucose oxidase supply chains concentrated in Swiss and Dutch specialty chemical facilities anchor Abbott Laboratories' cost leadership in disposable enzymatic electrodes. This backward integration into enzyme electrode production simultaneously secures input cost predictability and compresses competitor pricing headroom at the commodity sensor tier.
Pricing Analysis
Outcome-linked reimbursement through BfArM's DiGA assessment pathway anchors value-based pricing for algorithm-enabled glucose sensors. Three-tier pricing structure across premium closed-loop systems, standard transmitter-sensor bundles, and economy sensor-only configurations stratifies the market. Cost compression in the sensor tier intensifies because factory-calibrated designs eliminate fingerstick calibration and commoditize manufacturing scale. Statutory health insurers exhibit highest price sensitivity, while private payers in metropolitan hospital networks absorb premium markups for integrated care contracts.
Supply Chain Analysis
Dual-sourcing mandates from Bavarian hospital procurement networks require qualified suppliers for both enzymatic electrode substrates and algorithm-intensive transmitter hardware. Manufacturing draws from Swiss specialty chemical facilities for glucose oxidase enzymes, Dutch precision fabrication for electrode membranes, and German industrial bases for transmitter assembly. Single-source vulnerability concentrates in the enzyme supply tier where proprietary fermentation processes limit supplier substitution. Distribution runs through statutory insurer patient portals in Baden-Württemberg and medical supplies wholesalers for hospital network consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzyme electrode manufacturing capacity constraints prop pricing power for vertically integrated incumbents, while algorithm firmware talent scarcity in Munich and Berlin bottlenecks transmitter innovation cycles.
For Market Incumbents: Lock in captive glucose oxidase supply through long-term offtake agreements with Swiss and Dutch specialty chemical facilities. Expand embedded firmware engineering capacity in Munich's startup ecosystem to defend algorithm-intensive transmitter margins against optical glucose sensing substitution threats from Dutch and Austrian research institutes. For New Entrants and Emerging Players: Non-invasive spectroscopic monitoring technologies under development present a technology-first wedge into pre-diagnostic applications outside statutory reimbursement frameworks. Target direct-to-consumer sports health segments in Saxony and Thuringia where telemedicine platform penetration lags western Länder benchmarks, leveraging pharmacy-based dispensing relationships for initial market access. For Investors and Strategic Acquirers: Exit pathways concentrate in algorithm-insulin pump convergence plays with integrated care contract penetration in North Rhine-Westphalia. Long-term viability favors manufacturers with demonstrated BfArM DiGA approval velocity and statutory insurer portal API integration. Watch optical glucose sensing technical milestones as inflection indicators threatening enzymatic sensor incumbency.| Strategic Initiative | Industry Significance |
|---|---|
| DiGA Fast-Track Submission | BfArM approval accelerates statutory reimbursement eligibility for connected glucose sensors. |
| Algorithm-Insulin Pump Integration | Predictive glucose forecasting bundled with automated insulin delivery commands premium reimbursement tiers. |
| Embedded Firmware Talent Acquisition | Munich and Berlin startup ecosystem recruitment secures real-time signal processing capabilities. |
| Telemedicine Platform API Partnership | Direct statutory insurer portal connections bypass traditional durable medical equipment distribution margins. |
| Factory-Calibrated Sensor Scale-Up | Elimination of fingerstick calibration requirements expands addressable patient segments beyond intensive insulin users. |
Research Methodology
Multi-period observation of BfArM DiGA approval timelines, statutory insurer reimbursement code expansions, and metropolitan hospital procurement specifications anchored the trend analysis, supplemented by interviews with endocrinology practice administrators, biomedical engineers at Bavarian health networks, GPO contracts managers, and regulatory affairs specialists at notified bodies. Secondary validation drew from EU MDR technical documentation filings, hospital procurement databases, statutory health insurer portal integration disclosures, and customs records of enzymatic electrode substrate imports. Bottom-up installed base estimates triangulated against top-down reimbursement expenditure flows.
Segment-weighting across product type, application, end user, and distribution channel dimensions structured the analytical framework across the analysis window. CAGRs derived from curve-fitting historical reimbursement expansion rates against projected DiGA pathway volume eligibility. Industry-specific forecast inputs incorporated EU MDR notified body capacity constraints and Digital Care Act framework implementation velocity in distinct Länder.
Several conditions sit outside the modeled scope, including pre-commercial optical glucose sensing technology maturation timelines and potential EU MDR classification reassignments for predictive dosing algorithms. Forecasts reflect assumptions of continued statutory reimbursement parity negotiations and BfArM digital health assessment criteria stability. Deviation in enzyme electrode input cost volatility or firmware engineering talent migration patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
China Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
Global Non-Invasive Glucose Meter Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market