
 Pharmaceutical Fine Chemicals Market | 2026-2036
Pharmaceutical Fine Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Fine Chemicals Market Intelligence
The EU Green Deal's pharmaceutical sustainability criteria is rebalancing procurement weights toward carbon-accounted fine chemical supply chains. Merck KGaA leverages its integrated Darmstadt manufacturing complex to sustain European API precursor output. Evonik Industries anchors North American specialty excipient capacity through its Alabama operations. Albemarle Corporation dominates lithium-based reagent supply for psychiatric active pharmaceutical ingredients.
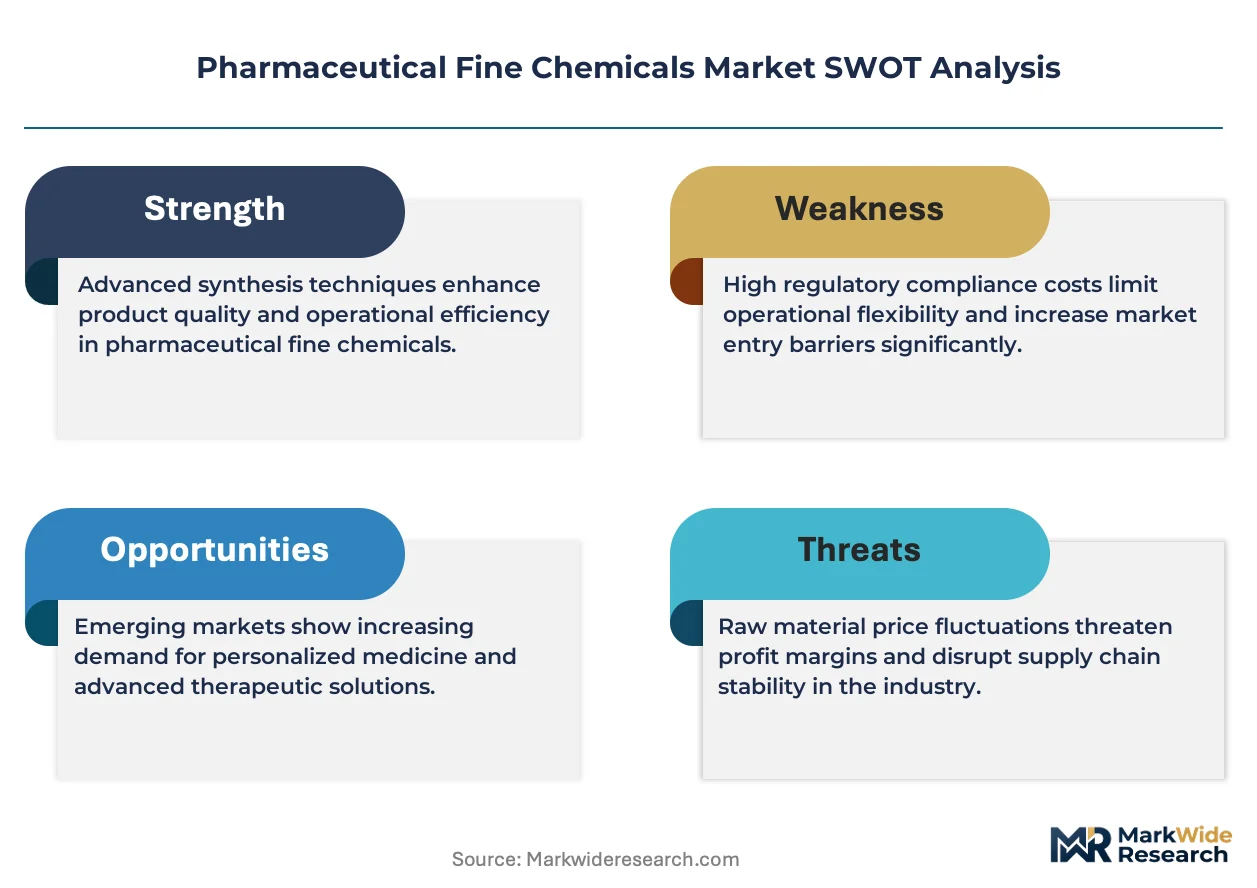
Pharmaceutical fine chemicals comprise high-purity organic and inorganic compounds synthesized under cGMP conditions, typically achieving purity thresholds above 99.5 percent through multi-step catalytic or enzymatic processes, serving as building blocks for drug substances and formulation components. Active pharmaceutical ingredients command the largest value pool due to patent-protected synthesis complexity and regulatory filing requirements. Intermediates represent the fastest-expanding category as biotech firms outsource early-stage route development. Oncology applications concentrate margin pools owing to cytotoxic handling protocols and containment infrastructure costs.
FDA enforces ICH Q7 cGMP guidelines for active pharmaceutical ingredient manufacture, while EMA's REACH and F-Gas Regulation constrain solvent selection and emission profiles across European production sites. India's CDSCO mandates BIS-aligned impurity specifications for imported reference standards, tightening market access for non-compliant suppliers. Contract manufacturers must monitor evolving dual-use chemical controls and precursor tracking mandates that reshape cross-border procurement decisions.
Market Dynamics
ICH Q3D impurity profiling mandates are forcing contract manufacturers to rebuild analytical capabilities and supplier qualification protocols, compressing margins for non-specialized intermediates while concentrating procurement power among certified high-purity producers.
Growth Catalysts
- EMA F-Gas Regulation:Solvent emission caps are accelerating capital deployment into closed-loop recovery systems across European API precursor facilities, creating technology differentiation among compliant suppliers.
- Oncology pipeline expansion:Cytotoxic antibody-drug conjugates require containment-grade fine chemical infrastructure that commands premium pricing and long-term offtake agreements.
- India PLI scheme:Production-linked incentives for KSM and DMF manufacturing are pulling multinational procurement offices from legacy European suppliers toward Hyderabad and Visakhapatnam clusters.
Market Restraints
- Lithium reagent volatility:Psychiatric API manufacturers face input cost instability from concentrated South American brine processing and Chinese carbonate refining.
- Single-source catalyst dependence:Noble metal hydrogenation catalysts for chiral intermediate synthesis remain captive to limited German and Japanese specialty chemical suppliers.
- REACH authorization timelines:ECHA's substance evaluation delays for novel process solvents extend route development cycles by 18-24 months.
Strategic Opportunities
- Continuous flow manufacturing:Microreactor technology convergence with real-time analytical release is enabling relocatable production units for high-potency compounds.
- EU Green Deal pharmaceutical criteria:Carbon-accounted supply chain certification is opening preferred supplier status for European manufacturers with verified Scope 3 reductions.
- Brazil ANVISA alignment:Emerging local registration requirements for imported reference standards create captive manufacturing incentives for regional KSM production.
Industry Challenges
- Containment engineering talent scarcity:Isolator design and high-potency facility commissioning expertise concentrates among retired Big Pharma engineers, constraining greenfield project timelines.
- Legacy ERP integration:Electronic batch record systems from 1990s-era plants resist interface with modern cloud-based supplier quality management platforms.
- Patent thicket navigation:Generic API route selection requires freedom-to-operate analysis across overlapping crystallization and salt-form intellectual property estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Fine Chemicals Market |
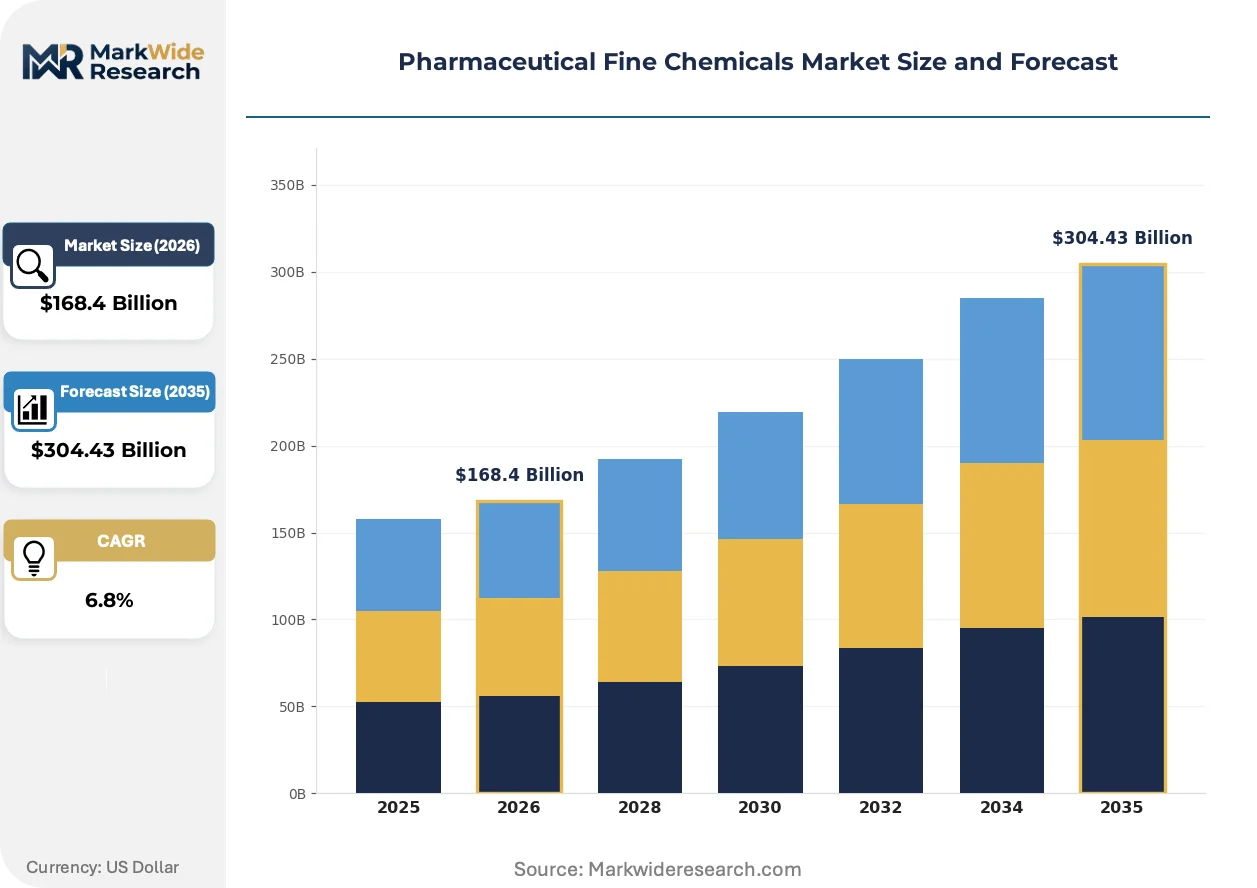
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $304.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Pharmaceutical Ingredients, Intermediates, Excipients, Other Chemicals Application: Antibiotics, Hormones, Oncology, Cardiovascular End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Manufacturers Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail Outlets |
| Companies Covered | Hengli Petrochemical, Merck KGaA, Shin-Etsu Chemical, Albemarle Corporation, DSM, Syngenta Group, Evonik Industries, Eastman Chemical, Wanhua Chemical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Fine Chemicals Market Strategic Shifts & Innovations
Process analytical technology and closed-system manufacturing are compressing batch release timelines while regulatory digitization is redefining supplier qualification protocols across the value chain.
Continuous manufacturing platforms are automating real-time impurity detection and adaptive parameter control in API precursor synthesis. Mid-scale contract manufacturers in India and Germany are retrofitting legacy batch reactors with plug-flow microreactors for high-energy intermediate steps. This automation is collapsing traditional in-process testing intervals from hours to minutes, enabling just-in-time release for clinical trial supply chains.
EMA's revised Annex 1 sterile manufacturing guidelines extend environmental monitoring requirements into fine chemical isolation suites, mandating continuous viable particle detection. European producers are rebuilding Grade C corridors with isolator-integrated sampling ports, while Asian exporters face re-qualification audits for EU market access. Parenteral API categories bear the heaviest compliance burden, with containment infrastructure capex rising substantially for cytotoxic compound handling.
Biotech sponsors are consolidating procurement through platform technology agreements that bundle route development, GMP scale-up, and commercial supply into single-source arrangements. Virtual pharmaceutical companies lack internal process chemistry capabilities, driving preference for integrated CDMO partners over discrete fine chemical vendors. This concentration is most pronounced in Boston and San Francisco innovation clusters, where sponsor technical due diligence teams prioritize end-to-end accountability over unit cost optimization.
Pharmaceutical Fine Chemicals Market Segmentation
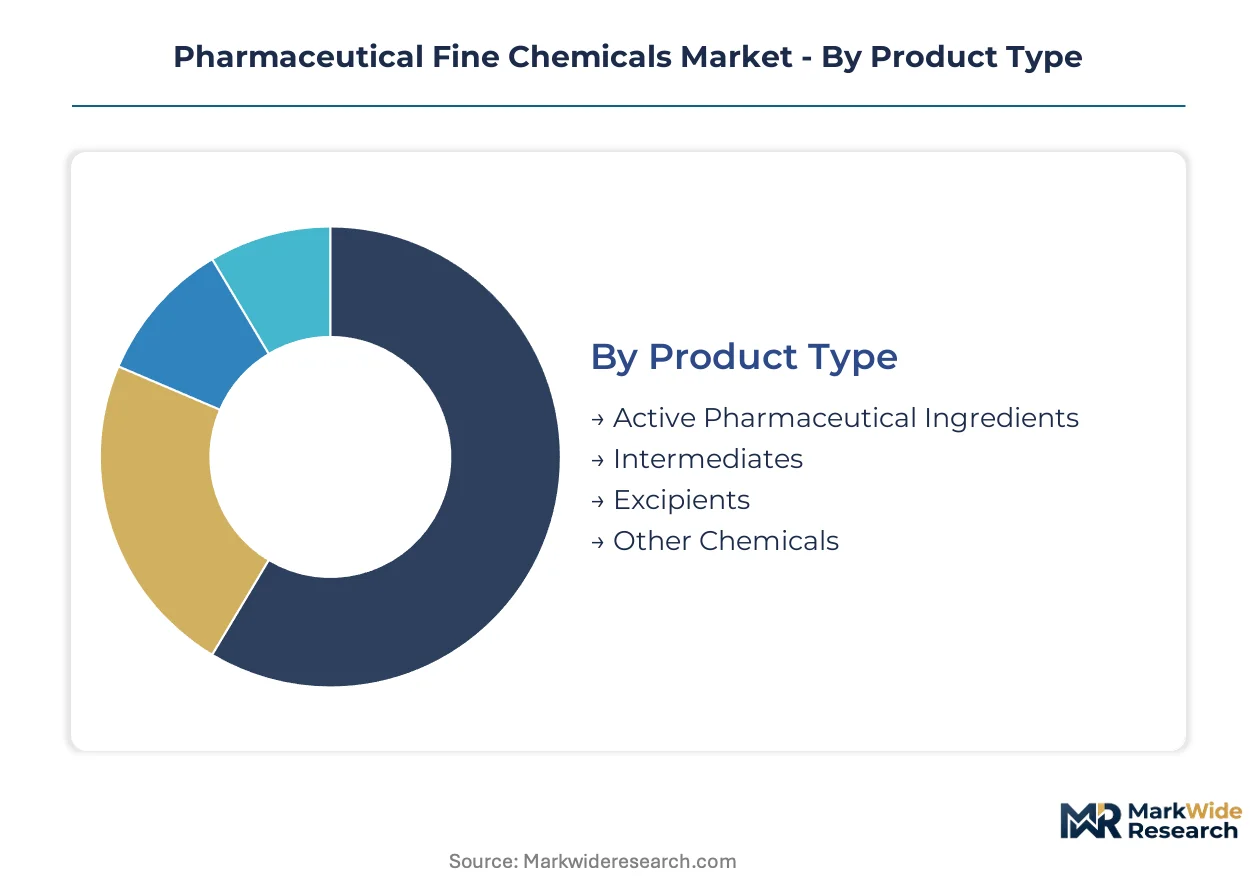
Segmentation in pharmaceutical fine chemicals reveals how regulatory stringency, synthesis complexity, and containment requirements fragment procurement decisions across buyer types. Contract manufacturers prioritize high-purity intermediates with documented impurity profiles, while research institutions optimize for route flexibility over scale economies.
Product Type:
Standardization dominates commodity-grade excipients, whereas active pharmaceutical ingredients demand bespoke synthesis protocols tailored to specific drug master files.
- Active Pharmaceutical Ingredients:Patent-protected synthesis routes achieve purity thresholds above 99.5 percent through multi-step catalytic processes. Demand concentrates among oncology and cardiovascular drug developers in Germany and Switzerland, where EMA filing requirements mandate dedicated containment infrastructure.
- Intermediates:Early-stage route development compounds serve as building blocks for final API assembly. Biotechnology firms in Boston and San Francisco innovation clusters drive procurement, outsourcing GMP scale-up to integrated CDMO partners rather than discrete chemical vendors.
- Excipients:Formulation components including binders, fillers, and coatings meet pharmacopeial standards with lower regulatory burden.
- Other Chemicals:Solvents, reagents, and catalysts support synthesis operations without entering final drug substance composition.
Most installed capacity flows through Active Pharmaceutical Ingredients. Expansion is steepest in Intermediates as virtual pharmaceutical companies proliferate.
Application:
Margin structures diverge sharply across therapeutic areas, with cytotoxic handling protocols and containment capex creating premium pricing tiers in high-potency categories.
- Oncology:Cytotoxic antibody-drug conjugates and high-potency compounds require isolator-integrated manufacturing suites and continuous viable particle detection. CDMOs in Hyderabad and Visakhapatnam command long-term offtake agreements from multinational sponsors seeking dedicated containment capacity.
- Cardiovascular:Large-volume statin and antihypertensive APIs operate at commodity margins with intense price competition among Indian and Chinese manufacturers.
- Antibiotics:Fermentation-derived and semi-synthetic antibacterial compounds face tightening environmental scrutiny under EPA and MEE discharge regulations.
- Hormones:Steroid and peptide hormone synthesis requires specialized biocatalytic capabilities and controlled substance licensing.
Cardiovascular commands the largest volume throughput. Oncology delivers the steepest margin expansion trajectory as pipeline complexity intensifies.
End User:
Procurement sophistication varies by organizational scale, with Big Pharma maintaining captive manufacturing networks while virtual companies rely entirely on external synthesis partners.
- Contract Manufacturers:CDMOs and CMOs consolidate procurement across multiple sponsor programs, achieving volume leverage in high-purity intermediate purchasing. India's PLI scheme incentives attract multinational sourcing shifts toward Hyderabad clusters for KSM and DMF manufacturing.
- Pharmaceutical Companies:Integrated innovators like Merck KGaA sustain European API precursor output through captive Darmstadt manufacturing complexes.
- Biotechnology Firms:Virtual and asset-light developers lack internal process chemistry capabilities, driving preference for platform technology agreements bundling route development through commercial supply.
- Research Institutions:Academic and government laboratories prioritize analytical reference standards and small-scale route exploration over GMP-scale procurement.
Contract Manufacturers absorb the majority of merchant market volume. Biotechnology Firms are expanding procurement budgets fastest as clinical pipeline density increases.
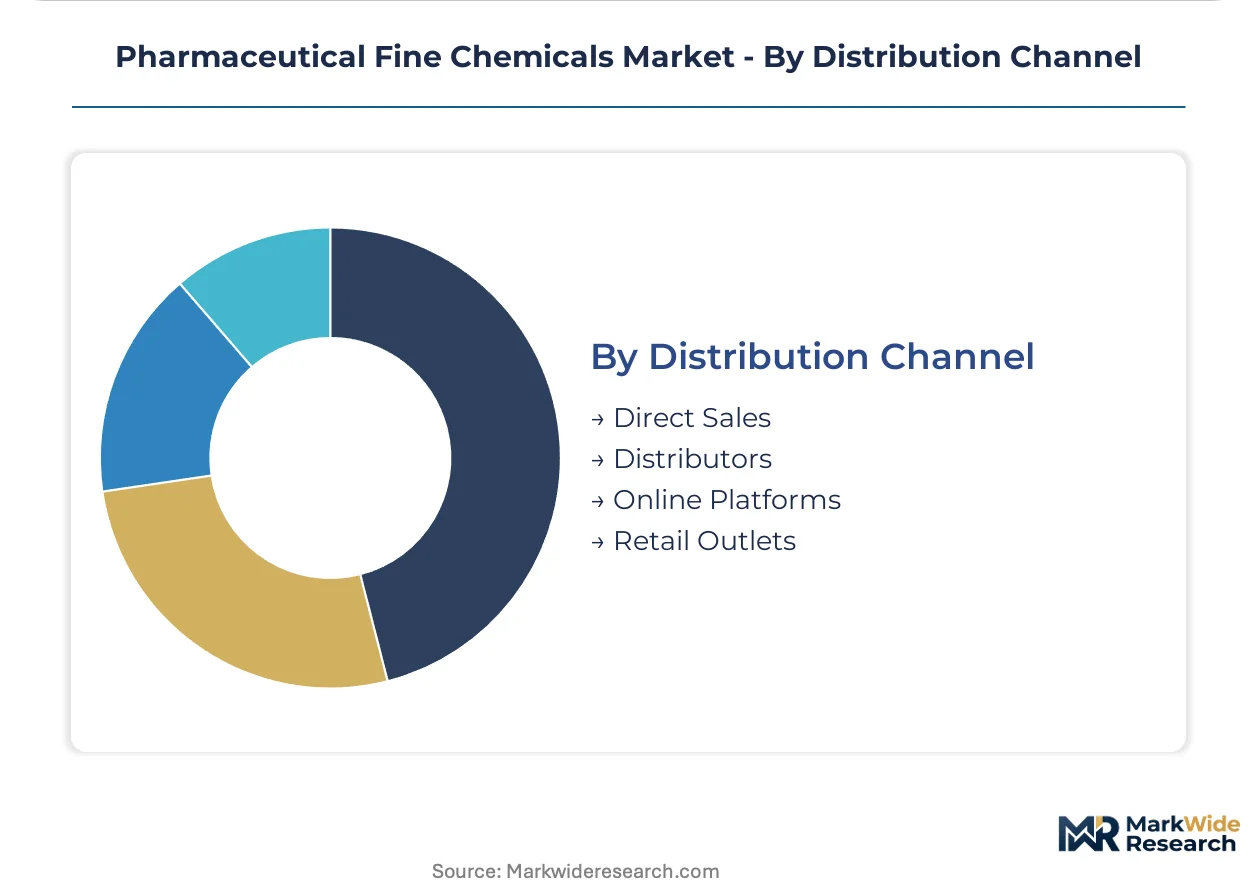
Distribution Channel:
Channel selection reflects order size, certification requirements, and the need for technical support in specification alignment.
- Direct Sales:Large-volume API and intermediate contracts bypass intermediaries to secure supply security and custom specification negotiation. Evonik Industries anchors North American specialty excipient capacity through direct relationships with formulation sponsors.
- Distributors:Regional chemical distributors stock catalog excipients and solvents for mid-tier pharmaceutical manufacturers requiring shorter lead times than transoceanic direct shipment.
- Online Platforms:Digital procurement portals serve research institutions and early-stage biotech with small-quantity reference standards and catalog intermediates.
- Retail Outlets:Limited relevance for pharmaceutical-grade fine chemicals due to GMP documentation and chain-of-custody requirements.
Direct Sales channels handle the majority of value throughput. Online Platforms are climbing fastest as virtual pharmaceutical company formation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical fine chemicals production traces its modern lineage to Swiss and German dye chemistry of the late nineteenth century, later migrating to US pharmaceutical corridors during mid-century antibiotic expansion, and now concentrating in Asian manufacturing clusters under twenty-first century regulatory harmonization.
United States
Oncology pipeline sponsors in Boston and San Francisco drive demand for high-potency containment capacity. FDA enforces ICH Q7 cGMP guidelines through intensified pre-approval inspection protocols. The Greater Philadelphia corridor hosts legacy API precursor facilities now retrofitting for continuous manufacturing platforms.
Germany
Specialty excipient and catalyst manufacturers serve EMA filing requirements for cardiovascular and psychiatric drug developers. ECHA's REACH authorization timelines extend novel solvent route development cycles by 18-24 months. The Darmstadt manufacturing complex sustains European API precursor output through integrated multi-step synthesis infrastructure.
India
Multinational procurement offices are shifting sourcing from European legacy suppliers toward cost-competitive KSM and DMF manufacturing. CDSCO mandates BIS-aligned impurity specifications for imported reference standards, tightening market access. Hyderabad and Visakhapatnam clusters attract PLI scheme incentives for large-scale API production zones.
China
Domestic biotech firms outsource early-stage route development to contract manufacturers with documented impurity profiles. NMPA alignment with ICH Q3D guidelines forces analytical capability rebuilding across intermediate suppliers. Yangtze River Delta chemical parks face tightening environmental scrutiny under MEE discharge regulations for antibiotic fermentation operations.
Switzerland
Precision oncology developers command premium pricing for cytotoxic antibody-drug conjugate building blocks. Swissmedic maintains stringent containment facility licensing that limits new market entrants. Basel-area innovation clusters concentrate biotech sponsor technical due diligence teams prioritizing end-to-end CDMO accountability.
Pharmaceutical Fine Chemicals Market Key Industry Players
Premium-margin players sit above commodity-margin players across containment infrastructure and regulatory certification dimensions, with oncology-focused CDMOs capturing long-term offtake agreements while cardiovascular API manufacturers compete on unit cost optimization. The vendor base stratifies into three tiers: integrated innovators with captive manufacturing networks, platform-technology CDMOs bundling route development through commercial supply, and commodity intermediate traders lacking GMP-scale capabilities. Dominant competitive moves include capacity expansion into India under PLI scheme incentives and technology licensing partnerships for continuous flow microreactor platforms.
Among European-anchored diversified chemical conglomerates, Merck KGaA and Evonik Industries exemplify integrated innovators sustaining regional API precursor output through captive manufacturing complexes. DSM represents the platform-technology archetype, occupying a position between discrete fine chemical supply and end-to-end CDMO bundling. Albemarle Corporation anchors the specialty reagent tier, sitting within lithium-based supply chains for psychiatric active pharmaceutical ingredients.
| Leading Market Players |
|---|
| Hengli Petrochemical |
| Merck KGaA |
| Shin-Etsu Chemical |
| Albemarle Corporation |
| DSM |
| Syngenta Group |
| Evonik Industries |
| Eastman Chemical |
| Wanhua Chemical Group |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up CDMO specialists in North America and Europe are consolidating mid-scale containment facilities, tightening pricing discipline for high-potency oncology intermediates while compressing margins for non-specialized excipient traders. This ownership concentration aligns procurement power with certified producers capable of ICH Q3D-compliant impurity documentation.
Pricing Analysis
Long-term offtake agreements with minimum volume commitments anchor the dominant pricing structure for high-potency APIs and intermediates. Three-tier pricing structure across premium, standard, and economy levels separates isolator-grade cytotoxic compounds from standard GMP intermediates and catalog excipients. Cost compression in cardiovascular statin APIs is intensifying because Indian and Chinese manufacturers compete on unit economics. Research institutions exhibit highest price sensitivity for analytical reference standards, while oncology sponsors prioritize supply security over unit cost.
Supply Chain Analysis
Transoceanic freight cost volatility for temperature-controlled shipments of high-potency compounds is reshaping regional sourcing decisions for North American and European sponsors. Supply concentrates in India, China, and Germany for API precursors and intermediates. The chain draws from South American lithium brine, German noble metal catalysts, and Indian KSM manufacturing. Single-source catalyst vulnerability from limited Japanese and German suppliers threatens chiral intermediate synthesis. Distribution runs through direct sales for large-volume API contracts and regional distributors for catalog excipients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical fine chemicals function as a stable compounder, with regulatory filing requirements for drug master files creating sticky demand that resists cyclical downturns.
For Market Incumbents: To counter margin erosion from Indian PLI-subsidized competitors, Merck KGaA and Evonik Industries should deepen captive manufacturing integration in European containment corridors while accelerating continuous flow technology licensing to sustain technology differentiation. Certification investment in EU Green Deal carbon-accounted supply chains offers preferred supplier status with EMA-filing sponsors. For New Entrants and Emerging Players: Enter via Brazil ANVISA-aligned local reference standard manufacturing, where emerging registration requirements for imported KSMs create captive production incentives. Underpenetrated oncology containment capacity in Eastern European clusters offers white-space expansion. Target platform technology agreements bundling route development through commercial supply for Boston and San Francisco virtual biotech sponsors. For Investors and Strategic Acquirers: CDMO consolidators with cross-border regulatory capabilities are the most active acquirer in this space, seeking mid-scale containment specialists in Hyderabad and Visakhapatnam. The long-term viability window favors assets with documented ICH Q3D analytical capabilities and isolator-integrated manufacturing suites. Watch EMA Annex 1 sterile guideline enforcement as an inflection signal for European facility re-qualification capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Manufacturing Scale-Up | Microreactor retrofitting collapses batch release timelines from hours to minutes for clinical trial supply. |
| Backward Integration into KSM Production | Captive supply of key starting materials insulates against CDSCO BIS-aligned impurity specification disruptions. |
| EU Green Deal Certification Program | Carbon-accounted supply chain documentation secures preferred supplier status with EMA-filing oncology sponsors. |
| Long-Term Supply Agreement Expansion | Isolator-grade containment capacity commands multi-year offtake commitments from antibody-drug conjugate developers. |
| Joint Venture in Indian PLI Clusters | Hyderabad and Visakhapatnam partnerships access production-linked incentives for DMF and intermediate manufacturing. |
Research Approach
Bottom-up CDMO procurement modeling reconciled against top-down API precursor production tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads at EMA-filing sponsors, containment facility commissioning engineers, and procurement managers at virtual biotech firms combined with secondary validation from FDA 483 inspection observations, EMA GMP non-compliance reports, CDSCO import alerts, and customs trade data for high-purity intermediate flows.
Historical trendline analysis of contract manufacturing revenue trajectories and capacity utilization rates across the analysis window informed projection frameworks. Segmentation dimensions modeled include product type, therapeutic application, end-user organizational scale, and regional regulatory cluster. CAGRs derived from weighted average of sponsor pipeline density, containment infrastructure capex cycles, and PLI scheme incentive trajectories. Forecast inputs incorporated ICH Q3D implementation timelines and EMA Annex 1 sterile guideline enforcement schedules.
Inputs from regulatory filing databases and CDMO capacity announcements were available through the study window; gaps in privately held contract manufacturer financial disclosures introduce uncertainty bands around market concentration estimates. Forecasts reflect documented assumptions regarding sponsor outsourcing propensity and regulatory harmonization pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Active Ingredients Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Furosemide Market
Pharmaceutical Ingredients
Diosmin API Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
MEK Inhibitors Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Co-Crystal Ingredient Market
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market