
 Global Phase Transfer Catalyst Market | 2026-2036
Global Phase Transfer Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Global Phase Transfer Catalyst Market Foresight
Specialty chemical producers in Germany and Japan are consolidating capacity around high-purity quaternary ammonium salts for pharmaceutical-grade applications. Solvay leverages its integrated alkylamine supply chain to control raw material costs across European manufacturing. Tatva Chintan Pharma Chem Limited anchors South Asian export supply through dedicated fine chemical facilities in Gujarat. Merck KGaA differentiates via stringent quality protocols that align with pharmacopeia standards for drug formulators.
Phase transfer catalysts are surfactant-like compounds, typically quaternary ammonium or phosphonium salts with lipophilic cationic centers, that shuttle reactants between immiscible aqueous and organic phases to accelerate ionic reactions at interfaces. Crown ethers and cryptands offer superior selectivity for specific metal cations but carry higher production costs due to multi-step synthetic routes involving catechol cyclization or diaza-crown formation. Quaternary ammonium salts occupy the largest volume share across fine chemicals synthesis and agrochemical production, where cost efficiency outweighs selectivity demands. Polyethylene glycols are gaining share in environmental remediation applications, as their lower toxicity profile satisfies tightening discharge standards for wastewater treatment operators.
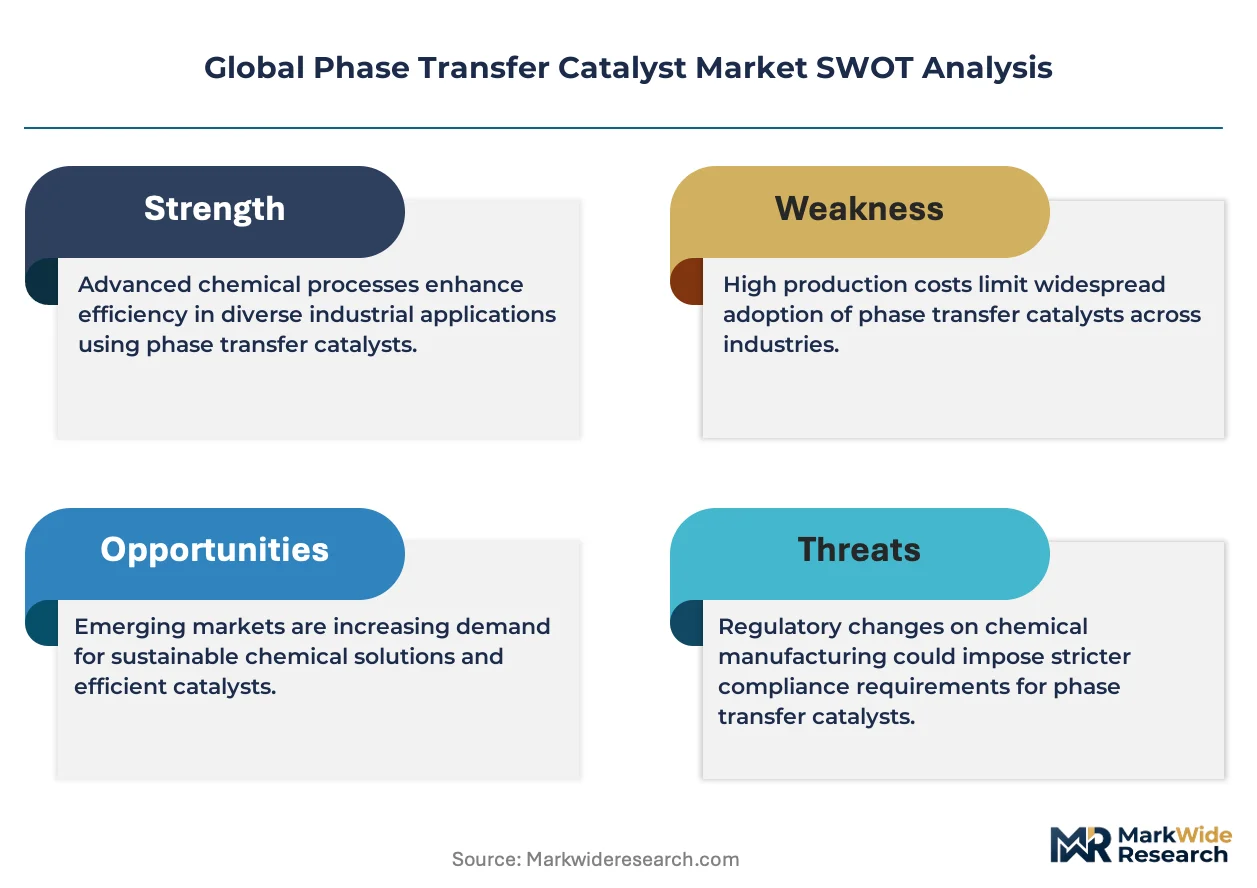
FDA pharmacopeial standards and EPA chemical substance reporting requirements govern catalyst residues in pharmaceutical and agrochemical outputs sold into the United States. REACH registration and the EU Green Deal's chemical sustainability criteria restrict persistent, bioaccumulative quaternary ammonium variants in European supply chains. Stakeholders must monitor evolving substance restrictions across FDA, ECHA, and India's CDSCO to anticipate reformulation costs and qualification timelines for next-generation catalyst systems.
Market Dynamics
Pharmaceutical-grade purity requirements are compressing supplier margins while concentrating procurement among integrated alkylamine producers capable of certifying batch-to-batch consistency for FDA and EMA submissions.
Growth Catalysts
- REACH substance restrictions:ECHA's tightening criteria for persistent quaternary ammonium compounds are accelerating reformulation demand toward biodegradable phosphonium alternatives in European fine chemical synthesis.
- India's CDSCO export certification:Contract research organizations in Gujarat and Hyderabad are scaling GMP-compliant phase transfer catalyst output for North American and European pharmaceutical formulators.
- Continuous flow reactor adoption:Pharmaceutical manufacturers are retrofitting batch processes with microchannel systems that require specialized catalyst formulations optimized for rapid phase transfer kinetics.
Market Restraints
- Alkylamine feedstock volatility:Quaternary ammonium salt production depends on fatty amine derivatives whose pricing tracks palm oil and coconut oil commodity swings through Malaysian and Indonesian supply chains.
- German-Japanese supply concentration:High-purity pharmaceutical-grade capacity clusters among three integrated producers, creating qualification bottlenecks for secondary suppliers seeking pharmacopeia certification.
- Crown ether cost structure:Multi-step synthetic routes involving catechol cyclization limit cryptand economics to specialty metal cation separations where selectivity premiums justify unit costs.
Strategic Opportunities
- Brazilian agrochemical formulation:ANVISA registration pathways for quaternary ammonium catalysts in crop protection chemistry remain underdeveloped relative to synthetic pyrethroid demand from soybean and sugarcane processing.
- EU Green Deal bio-based mandates:The chemical sustainability criteria are creating preferential procurement channels for catalysts derived from renewable alkylamine feedstocks versus petroleum-based alternatives.
- Polyethylene glycol wastewater applications:Municipal treatment operators in California and Ontario are specifying lower-toxicity phase transfer catalysts for heavy metal remediation to satisfy tightening EPA and Environment Canada discharge permits.
Industry Challenges
- Pharmacopeial qualification timelines:USP and EP certification for new quaternary ammonium variants requires 18-24 month stability studies that delay revenue recognition for reformulated catalyst launches.
- Process analytical technology integration:Pharmaceutical manufacturers are mandating real-time release testing protocols that force catalyst suppliers to deploy PAT-compatible spectroscopic fingerprinting capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Phase Transfer Catalyst Market |
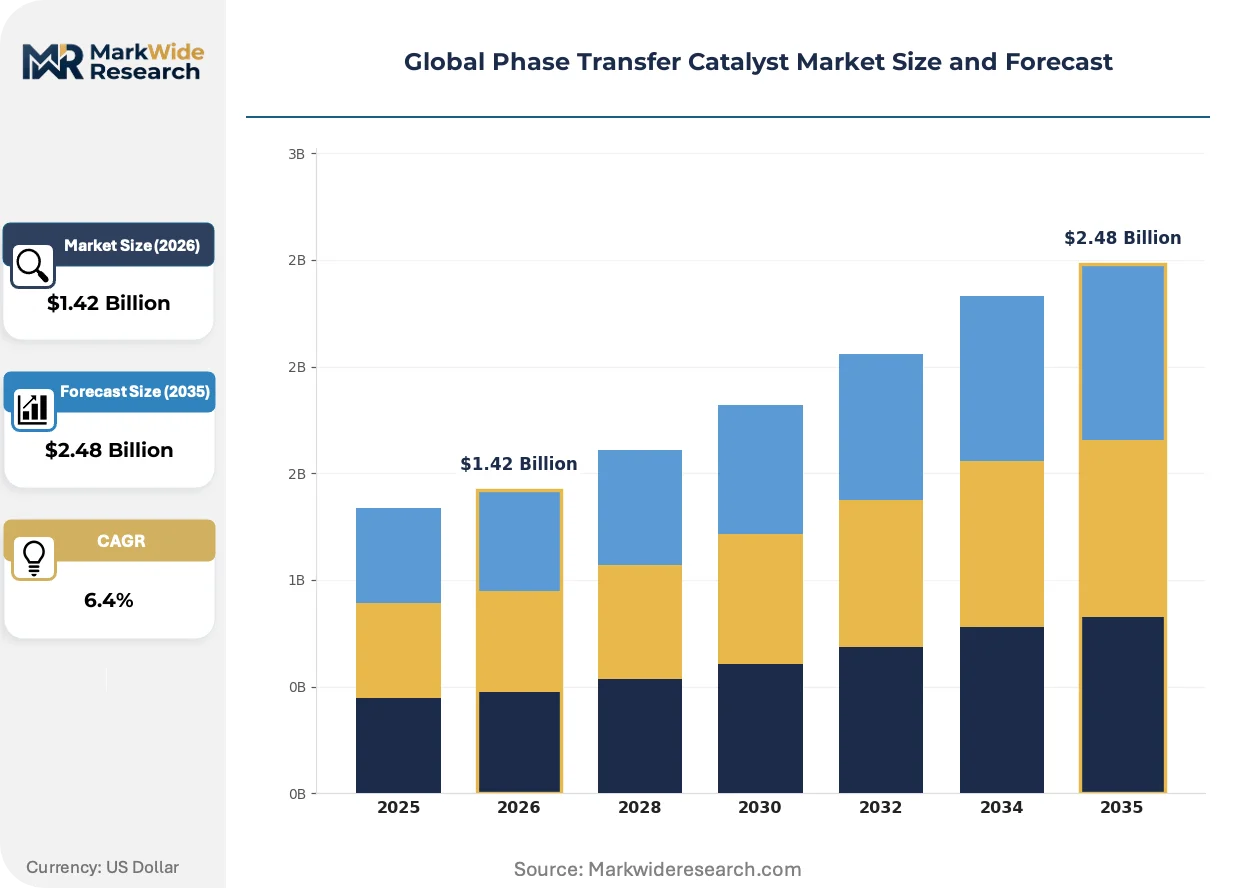
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quaternary Ammonium Salts, Phosphonium Salts, Crown Ethers, Polyethylene Glycols, Cryptands Application: Fine Chemicals Synthesis, Agrochemical Production, Pharmaceutical Manufacturing, Polymerization Processes, Environmental Remediation End User Industry: Chemical Manufacturers, Crop Protection Firms, Drug Formulators, Polymer Producers, Waste Treatment Companies Deployment: Batch Processing, Continuous Flow Reactors, Membrane Reactors, Fixed Bed Reactors, Fluidized Bed Reactors |
| Companies Covered | SACHEM Inc., Solvay, Merck KGaA, Tokyo Chemical Industry Co., Ltd., Tatva Chintan Pharma Chem Limited, Nippon Chemical Industrial Co., Ltd., Dishman Carbogen Amcis Ltd, Evonik Industries AG, PAT IMPEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Phase Transfer Catalyst Market Shifts & Advancements
Process intensification and regulatory chemistry are converging to redefine catalyst specification standards, with sustainability metrics now embedded in procurement criteria alongside traditional performance benchmarks.
Biodegradable quaternary ammonium salts synthesized from renewable fatty acid precursors are overtaking conventional petrochemical-derived variants in European pharmaceutical applications. Formulators in Basel and Frankfurt are qualifying these alternatives to preempt REACH authorization requirements. The shift is compressing margins for legacy alkylamine producers lacking bio-based feedstock integration.
REACH Annex XIV authorization procedures are forcing pharmaceutical manufacturers to document substitution plans for persistent quaternary ammonium compounds used in active ingredient synthesis. ECHA's 2024-2025 substance evaluation timeline is accelerating reformulation investments ahead of sunset date announcements. German fine chemical producers are prioritizing phosphonium salt alternatives to maintain European market access.
Direct procurement partnerships between pharmaceutical manufacturers and catalyst producers are displacing traditional distributor intermediaries in high-volume quaternary ammonium salt categories. Merck KGaA and Solvay have established dedicated supply agreements with Basel-based drug formulators that bypass regional chemical distributors. The disintermediation is most advanced in Switzerland and Germany, where just-in-time inventory requirements favor integrated logistics arrangements over stock-and-resell models.
Global Phase Transfer Catalyst Market Segmentation
Phase transfer catalyst procurement decisions hinge on regulatory compliance thresholds, reactor compatibility constraints, and end-product purity specifications that vary sharply across pharmaceutical versus agrochemical applications. The report examines four segmentation dimensions that collectively determine supplier positioning and margin capture potential.
Product Type:
Buyers prioritize cost-performance tradeoffs against tightening substance restrictions, with substitution economics driving category selection more than historical preference.
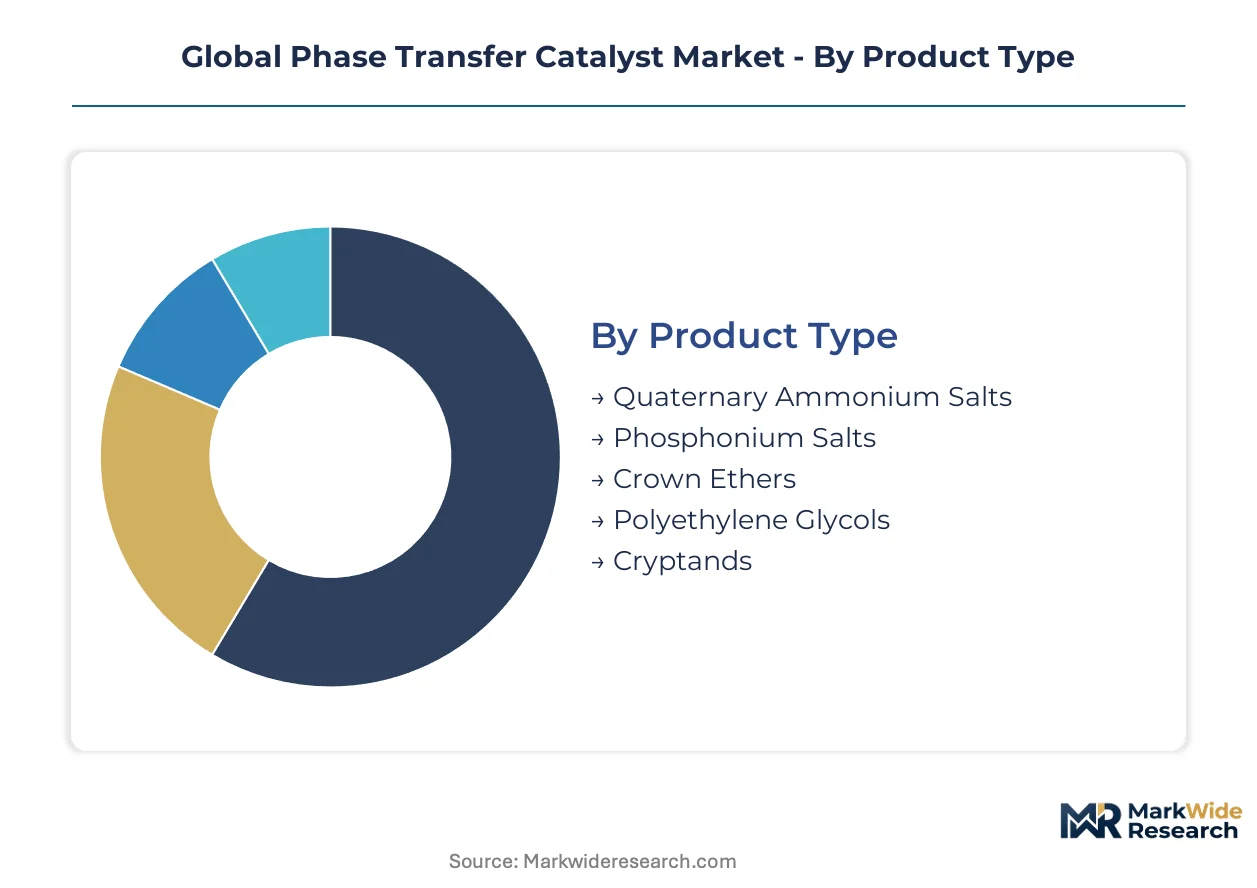
- Quaternary Ammonium Salts:Lipophilic cationic centers with tunable alkyl chain lengths dominate volume demand across fine chemicals and agrochemical synthesis. REACH authorization pressures in Germany and the Netherlands are accelerating shifts toward biodegradable variants derived from renewable fatty acid feedstocks.
- Phosphonium Salts:Superior thermal stability and lower bioaccumulation profiles position these salts as the primary substitute for persistent quaternary ammonium compounds in European pharmaceutical manufacturing. Basel-based formulators are qualifying phosphonium alternatives to preempt ECHA sunset date restrictions.
- Crown Ethers:Catechol-derived macrocycles deliver unmatched metal cation selectivity for specialty separations. Multi-step synthetic routes constrain deployment to high-value applications where selectivity premiums offset production costs.
- Polyethylene Glycols:Lower toxicity profiles satisfy California and Ontario wastewater discharge standards for heavy metal remediation applications.
- Cryptands:Diaza-crown architectures provide exceptional guest encapsulation for nuclear waste processing and rare earth recovery operations.
Quaternary ammonium salts lead on scale; phosphonium salts lead on momentum as REACH substitution deadlines approach.
Application:
Volume concentration tracks regulatory intensity, with pharmacopeial-grade applications commanding premium pricing despite smaller batch sizes.
- Fine Chemicals Synthesis:Contract manufacturers in Gujarat and Hyderabad utilize quaternary ammonium catalysts for intermediate production serving North American and European export markets. CDSCO GMP certification requirements are concentrating procurement among integrated alkylamine producers capable of documenting batch-to-batch consistency.
- Pharmaceutical Manufacturing:Active pharmaceutical ingredient synthesis demands catalyst residues below FDA and EMA pharmacopeial thresholds. USP and EP certification timelines of 18-24 months create qualification bottlenecks that favor incumbent suppliers with established regulatory dossiers.
- Agrochemical Production:Synthetic pyrethroid and herbicide formulation in Brazil and India drives steady demand for cost-optimized catalyst systems.
- Polymerization Processes:Anionic polymerization of styrene and diene monomers requires precise phase transfer control for molecular weight distribution.
- Environmental Remediation:Municipal treatment operators specify polyethylene glycol catalysts to satisfy tightening EPA and Environment Canada discharge permits for heavy metal extraction.
Fine chemicals synthesis anchors current volume; pharmaceutical manufacturing commands the steepest expansion trajectory as CDSCO-certified exports scale.
End User Industry:
Customer sophistication varies widely, with drug formulators imposing the most stringent quality protocols and audit requirements.
- Chemical Manufacturers:Diversified fine chemical producers in Germany and Japan represent the core demand base for high-purity quaternary ammonium salts.
- Drug Formulators:Basel, Frankfurt, and Boston-area pharmaceutical companies mandate real-time release testing compatibility and pharmacopeial-grade certification that excludes secondary suppliers lacking PAT infrastructure.
- Crop Protection Firms:Brazilian and Indian agrochemical formulators prioritize unit economics over purity grades for commodity crop protection chemistry.
- Polymer Producers:Styrene-butadiene rubber manufacturers in Southeast Asia utilize phase transfer catalysts for controlled anionic polymerization.
- Waste Treatment Companies:California and Ontario municipal operators drive polyethylene glycol adoption for heavy metal remediation compliance.
Drug formulators set the quality benchmark; waste treatment companies are gaining share fastest as discharge standards tighten across North America.
Deployment:
Reactor technology selection determines catalyst formulation requirements, with continuous flow systems demanding specialized kinetic optimization.
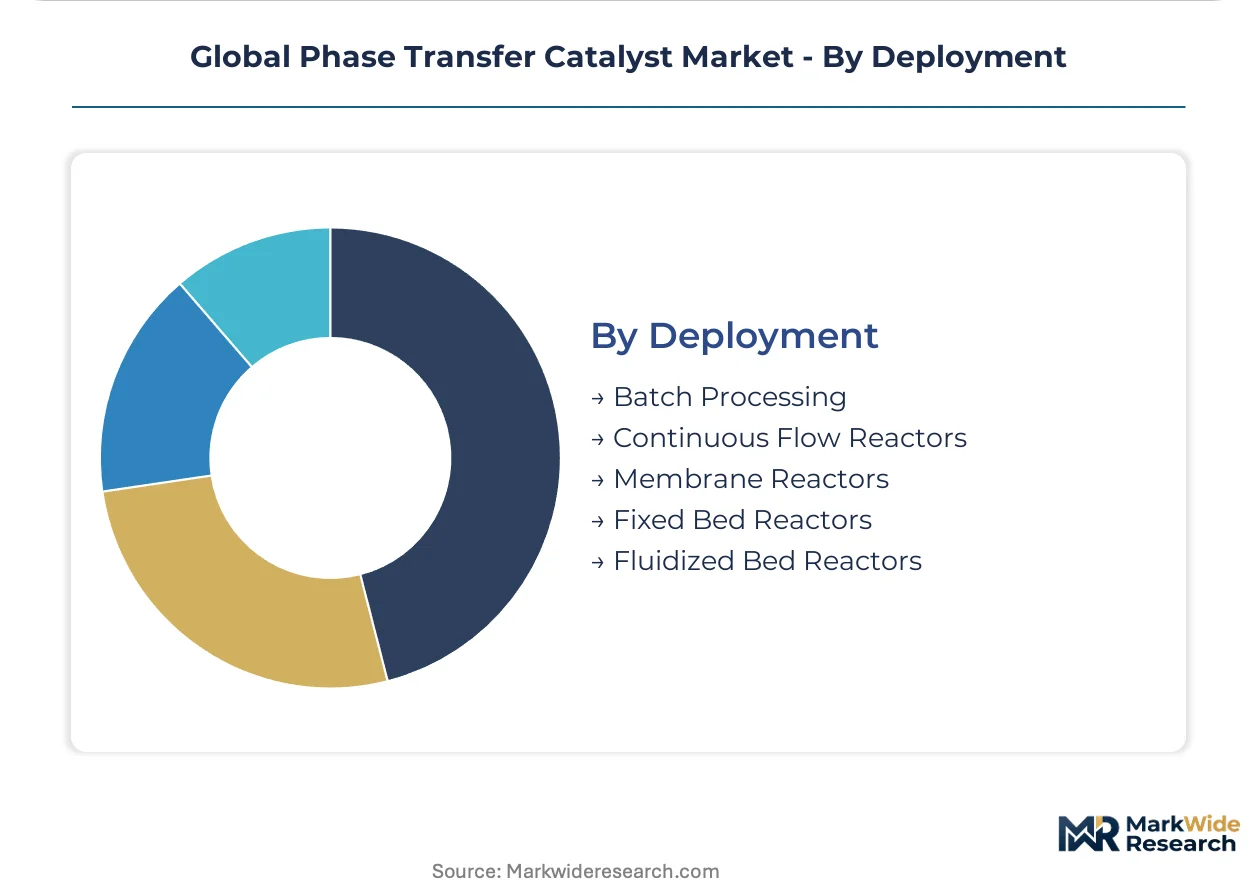
- Batch Processing:Traditional stirred-tank operations remain prevalent in agrochemical and fine chemical production where flexibility outweighs throughput optimization.
- Continuous Flow Reactors:Microchannel systems retrofitted by pharmaceutical manufacturers in Switzerland and Germany require catalyst formulations engineered for rapid phase transfer kinetics and minimal residence time variation.
- Membrane Reactors:Integrated separation-catalysis configurations are emerging for high-value pharmaceutical intermediate production.
- Fixed Bed Reactors:Heterogenized catalyst systems enable catalyst recovery and reuse in large-volume polymerization operations.
- Fluidized Bed Reactors:Excellent heat transfer characteristics suit exothermic reactions in bulk chemical manufacturing.
Batch processing retains installed base dominance; continuous flow reactors are climbing fastest as pharmaceutical manufacturers intensify process economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates pharmaceutical-grade catalyst certification while India scales export-oriented fine chemical output; both markets operate under divergent regulatory timelines that reshape procurement geography.
Germany
Specialty chemical producers in North Rhine-Westphalia and Bavaria dominate high-purity quaternary ammonium salt supply for European drug formulators. REACH Annex XIV authorization procedures from ECHA are accelerating reformulation investments toward biodegradable phosphonium alternatives ahead of sunset date announcements. Frankfurt and Ludwigshafen clusters anchor integrated alkylamine production with backward linkages to certified renewable feedstock supply chains.
India
Contract research organizations in Gujarat and Telangana are scaling GMP-compliant phase transfer catalyst output for North American and European pharmaceutical export markets. CDSCO certification requirements for active pharmaceutical ingredient intermediates are concentrating procurement among integrated producers capable of documenting batch-to-batch consistency. Vadodara and Hyderabad industrial corridors house dedicated fine chemical facilities serving global drug formulators.
United States
FDA pharmacopeial standards and EPA chemical substance reporting requirements govern catalyst residues in pharmaceutical and agrochemical outputs sold into domestic markets. Boston-area and New Jersey-based drug formulators mandate real-time release testing compatibility that excludes secondary suppliers lacking process analytical technology infrastructure. California municipal treatment operators are specifying polyethylene glycol catalysts for heavy metal remediation to satisfy tightening EPA discharge permits.
Switzerland
Basel-based pharmaceutical manufacturers are establishing direct procurement partnerships with catalyst producers that bypass traditional distributor intermediaries. Swissmedic quality protocols align with EMA pharmacopeia standards for drug formulators serving European and export markets. The Basel industrial cluster represents advanced demand for phosphonium salt alternatives as REACH substitution deadlines approach.
Japan
Tokyo Chemical Industry and other specialty producers anchor high-purity catalyst supply for domestic pharmaceutical and electronics chemical synthesis. METI chemical management policies and PMDA pharmaceutical standards enforce stringent purity thresholds that compress supplier margins while concentrating procurement. Osaka and Chiba industrial zones maintain integrated production capabilities for quaternary ammonium and phosphonium salt categories.
Global Phase Transfer Catalyst Market Competitive Landscape
German and Swiss producers anchor the premium-tier certification vector; Indian specialists hold the export-scaling tier for cost-optimized pharmaceutical intermediates. Market structure concentrates high-purity pharmaceutical-grade capacity among three integrated alkylamine producers, creating qualification bottlenecks for secondary suppliers seeking pharmacopeia certification. Two strategic archetypes dominate: vertically integrated chemical conglomerates with captive feedstock supply, and dedicated fine chemical specialists with GMP-certified facilities. Competitive moves center on direct procurement partnerships displacing distributor intermediaries, and backward integration into renewable fatty acid feedstocks to satisfy EU Green Deal bio-based mandates.
Among German-based integrated producers, Merck KGaA and Evonik Industries AG exemplify the premium-tier archetype through established regulatory dossiers and pharmacopeial-grade certification capabilities. Solvay anchors the Belgian-Swiss corridor with integrated alkylamine supply chain control. Tata Chintan Pharma Chem Limited represents the Indian specialist model, occupying a position within Gujarat's export-oriented fine chemical cluster. These three entities illustrate the geographic bifurcation between European certification-heavy supply and Asian volume-scaling production.
| Leading Market Players |
|---|
| SACHEM Inc. |
| Solvay |
| Merck KGaA |
| Tokyo Chemical Industry Co., Ltd. |
| Tatva Chintan Pharma Chem Limited |
| Nippon Chemical Industrial Co., Ltd. |
| Dishman Carbogen Amcis Ltd |
| Evonik Industries AG |
| PAT IMPEX |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in Gujarat and North Rhine-Westphalia anchor production clusters that discipline pricing through captive alkylamine supply and long-term offtake contracts with Basel-based drug formulators. This ownership pattern concentrates margin capture upstream while compressing secondary supplier pricing power through pharmacopeial certification barriers.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-grade quaternary ammonium salts used in agrochemical synthesis. Three-tier pricing structure across pharmacopeia-certified premium, technical-grade standard, and commodity economy levels separates Basel formulators from Gujarat exporters from Brazilian crop protection blenders. Price differentiation hinges on REACH-compliant biodegradability certification and batch-to-batch FDA dossier consistency. Cost compression in the standard tier is intensifying because CDSCO-certified Indian producers are scaling GMP output for North American export markets. Brazilian agrochemical formulators exhibit highest price sensitivity; Swiss drug developers show least.
Supply Chain Analysis
EU Green Deal domestic-content mandates for renewable feedstock sourcing are reshaping procurement patterns among German and Dutch fine chemical producers. Supply concentrates in Germany, India, and Japan for high-purity pharmaceutical-grade output. Raw material flows draw from Malaysian and Indonesian palm oil derivatives, German renewable fatty acid streams, and Japanese electronics-grade phosphine precursors. Single-source vulnerability runs through concentrated alkylamine supply from integrated producers in Ludwigshafen and Vadodara. Distribution runs through direct procurement partnerships displacing regional distributor intermediaries in Switzerland and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in phase transfer catalysts rests on bio-based feedstock transitions that unlock EU Green Deal premium pricing and continuous flow reactor compatibility that commands formulation-grade premiums from pharmaceutical manufacturers.
For Market Incumbents: Cement pharmacopeial certification moats through PAT-compatible spectroscopic fingerprinting investments that exclude secondary suppliers lacking real-time release testing infrastructure. Deepen backward integration into certified renewable fatty acid supply chains to preempt REACH authorization cost pass-through. Threat vector: biodegradable phosphonium salt substitutes from German reformulation investments. Lever: captive alkylamine production in Frankfurt and Ludwigshafen clusters. For New Entrants and Emerging Players: Launch via direct supply agreements with California and Ontario municipal wastewater treatment operators specifying polyethylene glycol catalysts for heavy metal remediation compliance. White-space targets: Brazilian ANVISA registration pathways for quaternary ammonium catalysts in soybean and sugarcane crop protection chemistry; phosphonium salt qualification for Basel-based formulators ahead of ECHA sunset dates. Go-to-market: technical service partnerships with contract research organizations in Gujarat and Hyderabad. For Investors and Strategic Acquirers: Valuations sit cheapest among Indian GMP-certified fine chemical specialists lacking European pharmacopeial dossiers but possessing CDSCO export certification and installed alkylamine capacity. Long-term viability over the next decade favors integrated producers with backward renewable feedstock linkages and continuous flow reactor formulation expertise. Acquisition target archetype: mid-cap Gujarat-based producers with latent REACH compliance capability. Signal to watch: ECHA substance evaluation timeline acceleration triggering reformulation investment spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Fatty Acid Supply | EU Green Deal bio-based mandates create preferential procurement channels for German and Dutch formulators. |
| Phosphonium Salt Capacity Expansion | REACH Annex XIV substitution deadlines drive Basel and Frankfurt qualification demand for persistent quaternary ammonium alternatives. |
| PAT-Compatible Spectroscopic Fingerprinting Deployment | Real-time release testing mandates from Boston-area and New Jersey drug formulators exclude secondary suppliers lacking infrastructure. |
| Direct Procurement Partnership Establishment | Swiss and German pharmaceutical manufacturers bypass distributor intermediaries for just-in-time quaternary ammonium salt inventory. |
| CDSCO GMP Certification Investment | Gujarat and Hyderabad contract research organizations scale export output for North American and European pharmaceutical markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at German and Indian alkylamine facilities, procurement leads at Basel-based drug formulators, distribution channel partners in European specialty chemicals, and technical R&D directors overseeing continuous flow reactor retrofits. Secondary validation drew from ECHA substance registration databases, CDSCO GMP certification records, SEC filings of integrated chemical producers, and Cefic fine chemical production surveys. Bottom-up capacity modeling and top-down demand triangulation anchored segment-level outputs.
Segment-weighting approaches distributed value and volume across product type tiers, application categories spanning fine chemicals synthesis through environmental remediation, end-user industry concentrations, and deployment modes distinguishing batch from continuous flow systems. CAGRs derived from alkylamine feedstock cost trajectories, REACH regulatory timeline impacts, and pharmaceutical manufacturing capital expenditure patterns across the projection horizon. Industry-specific inputs included pharmacopeial qualification timeline distributions and microchannel reactor adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA sunset date announcements or palm oil commodity volatility disrupting Malaysian feedstock supply. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Europe PGM Catalyst Market
Catalysts
Heterogeneous Catalyst Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Global VOC Catalysts Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
Petrochemical Catalyst Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Hydrotreating Catalyst Market
Catalysts
Global Zeolites Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
FCC Catalyst Additive Market
Catalysts
Polymer Catalyst Market
Catalysts
Hydro-Processing Catalysts Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Stationary Emission Control Catalyst Market