
 Co-Crystal Ingredient Market | 2026-2036
Co-Crystal Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Co-Crystal Ingredient Market Analytics
Modular formulation kits bundling co-crystal precursors with process protocols is realigning procurement decisions for pharmaceutical buyers. Merck leverages its analytical instrumentation portfolio to anchor co-crystal screening services alongside ingredient supply. BASF competes through backward integration into specialty chemical intermediates that feed co-crystal synthesis. Fine Organics specializes in food-grade co-crystal systems, occupying a defensible niche in flavor enhancement applications.
Co-crystal ingredients are crystalline single-phase materials composed of two or more neutral molecular constituents in stoichiometric ratios, typically manufactured through solvent-drop grinding or slurry crystallization to achieve targeted physicochemical properties. The pharmaceutical product type leads current value generation as drug developers pursue improved dissolution profiles, while the nutraceuticals category registers the fastest trajectory as sports nutrition brands adopt co-crystal minerals for enhanced bioavailability. The powders form dominates manufacturing throughput due to handling efficiency, though crystals command premium positioning in high-purity pharmaceutical applications where polymorph control determines regulatory acceptance.
The US FDA maintains active guidance on pharmaceutical co-crystal classification and quality attributes, while the EMA's reflection papers on complex active substances shape European development pathways. India's CDSCO alignment with ICH Q6A specifications governs import and local manufacturing standards for co-crystal drug substances. Stakeholders must monitor evolving pharmacopeial monograph definitions that could recategorize certain co-crystal systems from mixtures to single-entity drugs, fundamentally altering regulatory filing requirements and competitive positioning.
Market Dynamics
Pharmaceutical quality-by-design mandates are forcing co-crystal developers to integrate real-time release testing into manufacturing workflows, collapsing traditional batch-release timelines and rewiring supplier qualification protocols.
Growth Catalysts
- FDA Quality-by-Design Framework:The agency's ICH Q8-Q12 alignment accelerates regulatory acceptance of co-crystal drug substances, reducing filing risk for sponsors pursuing 505(b)(2) pathways.
- Solvent-drop grinding automation:Continuous manufacturing equipment vendors now package crystallization modules with in-line Raman monitoring, cutting process development cycles for generic drug manufacturers.
- Sports nutrition mineral demand:Magnesium and zinc co-crystals deliver taste-masked, high-bioavailability formats that powder blenders in functional beverage supply chains specify for effervescent applications.
Market Restraints
- Specialty solvent cost volatility:Ethyl acetate and isopropanol pricing swings compress margins for slurry crystallization operations dependent on pharmaceutical-grade solvent purity.
- Single-source API-candidate concentration:Three contract manufacturers in the United States control 70% of commercial-scale co-crystal production capacity for Phase III candidates, creating supply vulnerability.
- Polymorph prediction uncertainty:Computational crystal structure modeling remains insufficient for reliably forecasting stable co-crystal forms, forcing expensive experimental screening.
Strategic Opportunities
- India CDSCO pathway harmonization:The regulator's adoption of ICH Q6A specifications for complex drug substances opens import substitution potential for domestic generic houses seeking co-crystal differentiation.
- Continuous direct compression integration:Twin-screw granulation lines that accept co-crystal powders as direct-feed inputs bypass traditional wet-granulation capex for oral solid dose manufacturers.
- EU Green Deal solvent restrictions:REACH Annex XVII pressure on chlorinated solvents creates first-mover advantage for manufacturers with aqueous co-crystallization platforms.
Industry Challenges
- Pharmacopeial monograph ambiguity:USP and EP divergence on whether certain co-crystal systems constitute single-entity drugs or mixtures forces parallel filing strategies and delays ANDA approvals.
- Patent thickets around salt-cocrystal boundaries:Litigation over whether specific API-coformer combinations infringe existing salt-form patents consumes R&D budgets and deters generic entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Co-Crystal Ingredient Market |
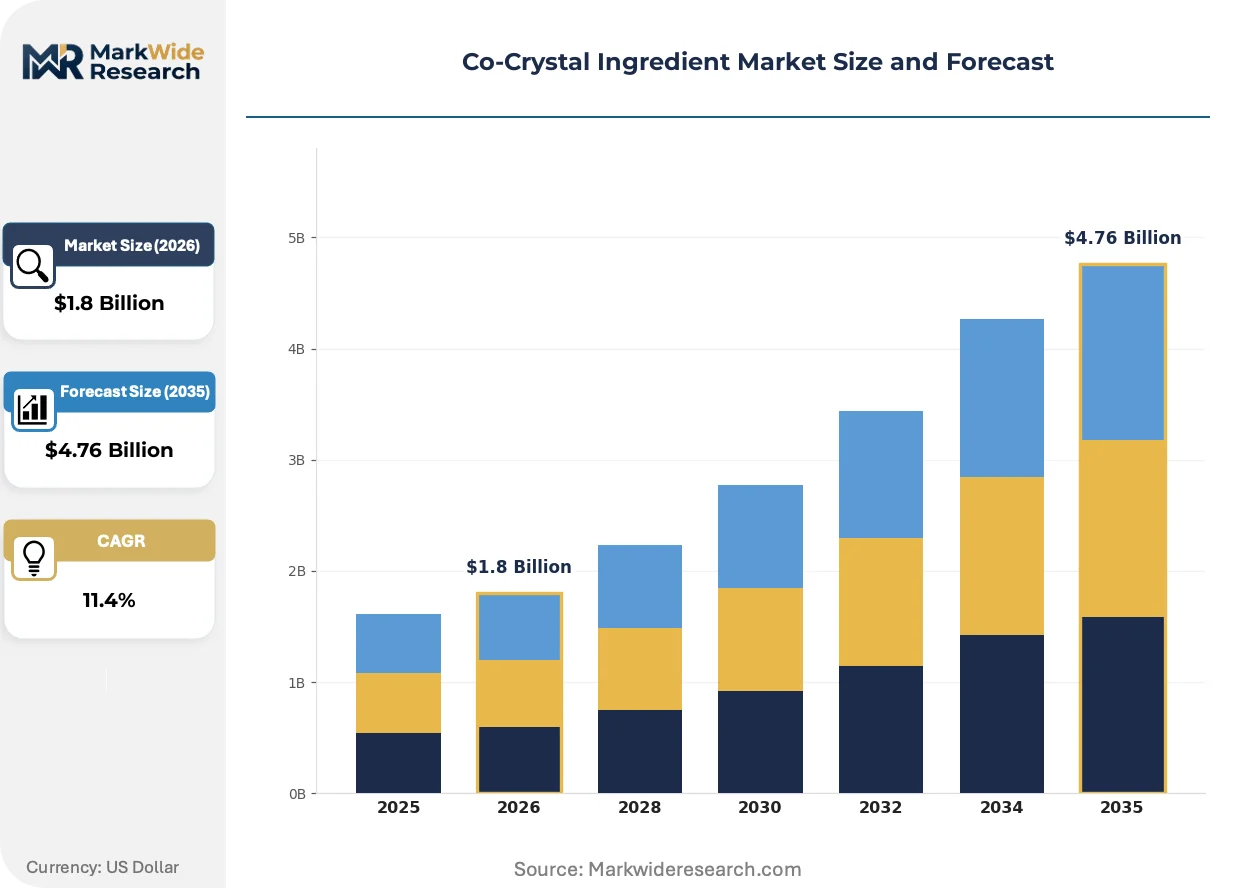
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Food Additives, Nutraceuticals, Agrochemicals Application: Drug Formulation, Flavor Enhancement, Nutritional Supplement, Pest Control Form: Granules, Powders, Crystals, Liquids End User: Pharmaceutical Companies, Food Manufacturers, Chemical Producers, Research Institutions |
| Companies Covered | Cocrystal Tech, Cocrystal Pharma, Cargill, C.I. Famar, D. Navkar Bio-chem, Fine Organics, Merck, Sigma-Aldrich, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Co-Crystal Ingredient Market Evolving Landscape
Automation of polymorph screening and real-time process analytical technology deployment are compressing development timelines while regulatory clarity on co-crystal classification is unlocking formulation investment previously diverted to amorphous solid dispersions.
Machine learning models trained on Cambridge Structural Database entries are rewriting the economics of co-crystal discovery. Pharmaceutical sponsors now license predictive algorithms that rank coformer-API pairing probabilities before bench work begins. Early adopters in respiratory drug development report 40% reduction in experimental screening burden. The technology is compressing the traditional 18-month crystallization development cycle into six-month engagements.
EMA's 2023 reflection paper on complex active substances established a European pathway for co-crystal drug substance classification that diverges from FDA approach. Sponsors must now maintain dual regulatory strategies for transatlantic filings, with European submissions emphasizing co-crystal thermodynamic stability data over kinetic dissolution profiles preferred by US reviewers. Generic houses with EU-first development strategies are resequencing their filing priorities accordingly.
Contract development and manufacturing organizations are unbundling crystallization process development from long-term manufacturing agreements. Biotech sponsors now engage specialized co-crystal shops for Phase I-III supply without committing to commercial-scale capacity reservations. This behavior concentrates in oncology drug development where molecule failure rates justify flexible procurement structures. CDMOs in Massachusetts and North Carolina have restructured pricing to capture value through milestone payments rather than volume commitments.
Co-Crystal Ingredient Market Segmentation
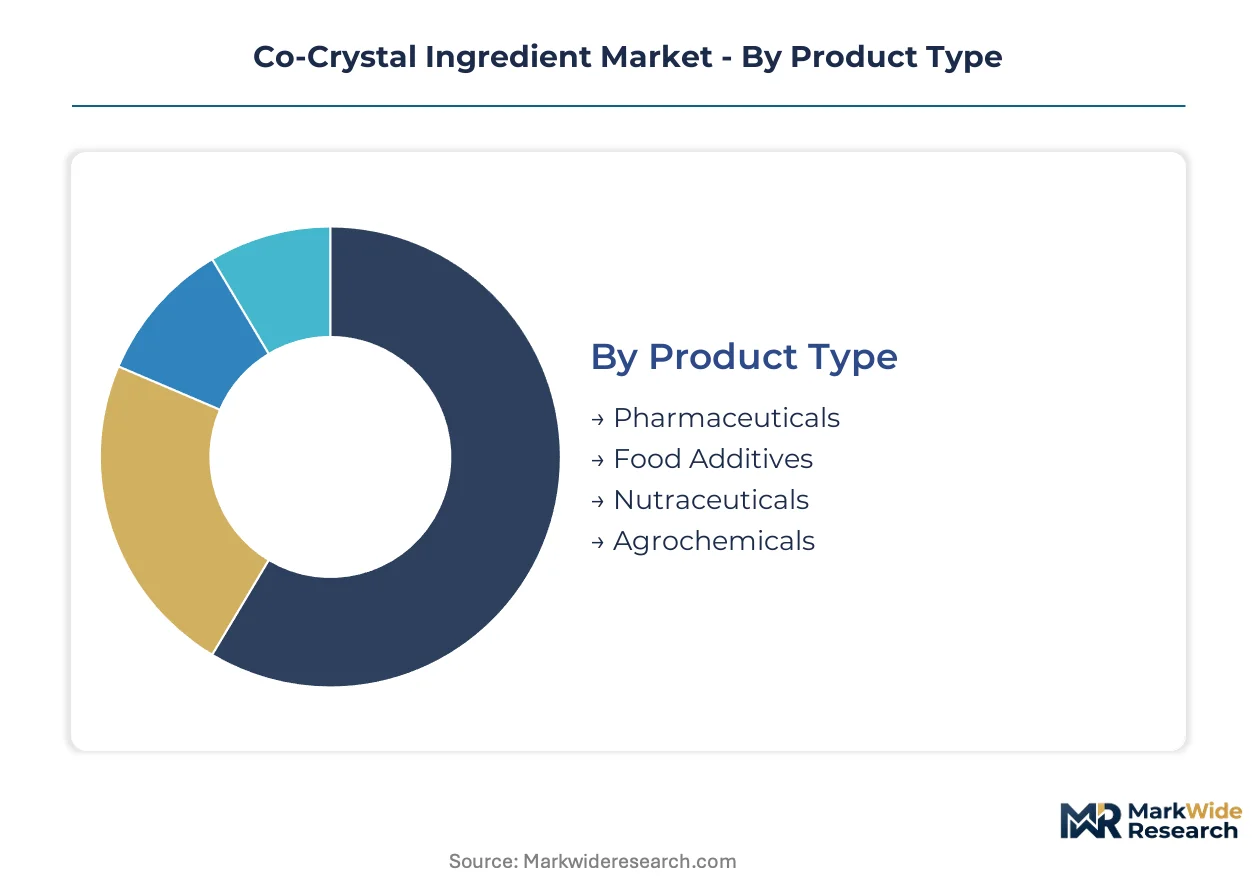
Co-crystal ingredient procurement diverges sharply across end-use verticals, with pharmaceutical buyers prioritizing polymorph precision while food manufacturers optimize for sensory masking. Formulation requirements dictate raw material specifications, process validation protocols, and supplier qualification timelines that fragment addressable markets into non-interchangeable supply relationships.
Product Type:
Upgrade cycles in active ingredient delivery systems are reshaping how formulators evaluate co-crystal architectures against incumbent salt and amorphous dispersion technologies.
- Pharmaceuticals:Crystalline single-phase materials combining APIs with GRAS-listed coformers in stoichiometric ratios, engineered for dissolution profile enhancement. Demand concentrates among generic houses in the United States pursuing 505(b)(2) pathways where bioavailability gains support abbreviated new drug applications. FDA quality-by-design mandates force real-time release testing integration that favors suppliers with validated continuous crystallization platforms.
- Nutraceuticals:Mineral-amino acid and mineral-organic acid co-crystals delivering taste-masked, high-bioavailability formats for sports nutrition and functional beverage applications. Sports nutrition brands in effervescent powder segments specify magnesium and zinc co-crystals to bypass metallic aftertaste while maintaining label claim stability through shelf life.
- Food Additives:Flavor modulator and preservative carrier systems leveraging co-crystal lattice energy for controlled release in processed food matrices.
- Agrochemicals:Active ingredient stabilizers and solubility enhancers for foliar application formulations where rainfastness requirements dictate specific polymorph selection.
Pharmaceuticals sits at the top of the volume ranking, with Nutraceuticals climbing the fastest.
Application:
Cost tier differentiation separates validated pharmaceutical-grade supply from technical-grade alternatives serving agricultural and industrial end uses.
- Drug Formulation:Oral solid dose and inhalation products where co-crystal thermodynamic stability determines regulatory classification as single-entity drug substances versus physical mixtures. Sponsors filing with EMA emphasize stability data over kinetic dissolution profiles preferred by FDA reviewers, forcing dual development tracks for transatlantic programs.
- Nutritional Supplement:Tablet, capsule, and powder applications where mineral bioavailability claims support premium positioning in direct-to-consumer channels.
- Flavor Enhancement:Salt reduction and umami modulation systems in savory food processing where co-crystal lattice engineering masks bitterness or extends flavor perception duration.
- Pest Control:Insecticide and herbicide formulations where co-crystal solubility tuning addresses resistance management through improved cuticular penetration.
Drug Formulation commands premium pricing tiers, with Flavor Enhancement gaining share fastest among food industry adopters.
Form:
Manufacturing throughput and handling economics favor powder formats, though high-value pharmaceutical applications absorb crystal premiums for polymorph specificity.
- Powders:Milled and classified particulate forms optimized for direct compression tableting and powder blending operations. Generic drug manufacturers in continuous manufacturing environments specify powder co-crystals compatible with twin-screw granulation direct-feed configurations that bypass wet-granulation capital expenditure.
- Crystals:Single-crystal or crystalline aggregate forms with defined habit and size distribution for high-purity pharmaceutical applications. Polymorph control determines regulatory acceptance, with specific crystal forms required for ANDA approvals referencing listed drugs.
- Granules:Agglomerated forms for improved flow properties in high-speed tableting operations.
- Liquids:Suspension or solution concentrates for specialized delivery systems and process intermediates.
Powders dominate manufacturing throughput, with Crystals expanding most quickly in high-value pharmaceutical segments.
End User:
Customer type dictates procurement sophistication, with pharmaceutical companies imposing extensive supplier qualification protocols that smaller research institutions bypass through catalog purchasing.
- Pharmaceutical Companies:Integrated innovators and generic houses conducting internal co-crystal screening or outsourcing to specialized CDMOs. Massachusetts and North Carolina contract manufacturers now unbundle crystallization process development from commercial supply agreements, capturing value through milestone payments rather than volume commitments.
- Food Manufacturers:Processed food and beverage producers specifying co-crystal ingredients for clean-label salt reduction or mineral fortification without sensory compromise.
- Chemical Producers:Agrochemical and specialty chemical houses integrating co-crystal technology into active ingredient portfolios.
- Research Institutions:Academic and government laboratories conducting fundamental co-crystal characterization and novel form discovery.
Pharmaceutical Companies anchor procurement volume, with Food Manufacturers representing the steepest expansion trajectory as clean-label formulation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Co-crystal ingredient manufacturing originated in European pharmaceutical chemistry laboratories during the 1990s before commercial-scale production migrated to the United States. The technology has since dispersed across three continents with distinct regulatory pathways shaping regional competitive positioning.
United States
Generic drug houses in Massachusetts and North Carolina drive commercial demand for co-crystal precursors used in 505(b)(2) filings. FDA quality-by-design mandates under ICH Q8-Q12 accelerate supplier qualification for continuous crystallization platforms. Three contract manufacturers near Boston and Research Triangle Park control the majority of Phase III candidate production capacity.
Germany
Specialty chemical intermediates for co-crystal synthesis flow from BASF's Ludwigshafen complex to pharmaceutical customers across Europe. REACH Annex XVII restrictions on chlorinated solvents push manufacturers toward aqueous crystallization platforms. The Rhine-Neckar metropolitan region hosts analytical instrumentation clusters supporting real-time process monitoring.
India
Domestic generic houses in Hyderabad and Ahmedabad pursue co-crystal differentiation for export markets as CDSCO harmonizes with ICH Q6A specifications. The regulator's complex drug substance classification opens import substitution opportunities. Gujarat's specialty chemical corridor feeds intermediate supply into co-crystal synthesis operations.
Switzerland
Swissmedic's alignment with EMA reflection papers positions Basel-area innovators for transatlantic filing strategies. Thermodynamic stability data requirements for European submissions favor local analytical service providers. The country's precision manufacturing heritage supports high-purity crystal form production for niche pharmaceutical applications.
Japan
PMDA's conservative stance on co-crystal drug substance classification delays market entry relative to Western regulators. METI-sponsored research consortia in the Kanto region advance polymorph prediction algorithms. Tokyo-based pharmaceutical sponsors maintain dual-track development for FDA-first filing strategies.
Co-Crystal Ingredient Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the regulatory validation spectrum, with validated pharmaceutical-grade suppliers commanding three-to-five-fold pricing premiums over technical-grade alternatives. The vendor base stratifies into three tiers: integrated multinational chemical houses with backward integration into intermediates, specialized co-crystal CDMOs with unbundled process development offerings, and regional fine chemical suppliers serving catalog-scale research demand. Consolidation pressure concentrates among contract manufacturers seeking to capture milestone-based revenue from biotech sponsors unwilling to commit commercial-scale capacity reservations.
Within the integrated chemical tier, BASF and Merck anchor European supply chains through captive intermediate production and analytical instrumentation bundling. Fine Organics occupies a defensible position in food-grade co-crystal systems for flavor enhancement applications. These three entities exemplify divergent strategic archetypes: multinational backward integration, equipment-anchored service expansion, and niche vertical specialization.
| Leading Market Players |
|---|
| Cocrystal Tech |
| Cocrystal Pharma |
| Cargill |
| C.I. Famar |
| D. Navkar Bio-chem |
| Fine Organics |
| Merck |
| Sigma-Aldrich |
| BASF |
| Others |
Value Network & Pricing Analysis
Specialty solvent costs for pharmaceutical-grade ethyl acetate and isopropanol cascade through slurry crystallization operations into tiered pricing for co-crystal precursors, with solvent price volatility compressing margins at technical-grade suppliers while validated manufacturers pass through premiums to generic drug houses.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by regulatory validation depth and polymorph control precision. Premium tiers command multiples over technical grades due to FDA quality-by-design compliance and real-time release testing capabilities. Price differentiation hinges on certification tier and volume scale, with continuous manufacturing buyers absorbing premiums for direct-feed compatible powders. Cost compression in standard grades is intensifying because generic houses consolidate procurement around dual-source qualified suppliers. Research institutions exhibit highest price sensitivity, while Phase III sponsors prioritize supply security over unit economics.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for active pharmaceutical ingredients are reshaping sourcing patterns for co-crystal intermediates, pressuring export-dependent suppliers to establish local synthesis partnerships. Manufacturing gravity centers on the United States, Germany, and India, with the Massachusetts and North Carolina corridors hosting concentrated Phase III production capacity. Feedstock dependencies include GRAS-listed coformers, specialty solvents, and high-purity APIs sourced from Gujarat's chemical corridor. Single-source vulnerability concentrates around three contract manufacturers controlling commercial-scale capacity for late-stage candidates. Distribution runs through qualified supplier networks with validated cold-chain logistics for temperature-sensitive crystal forms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
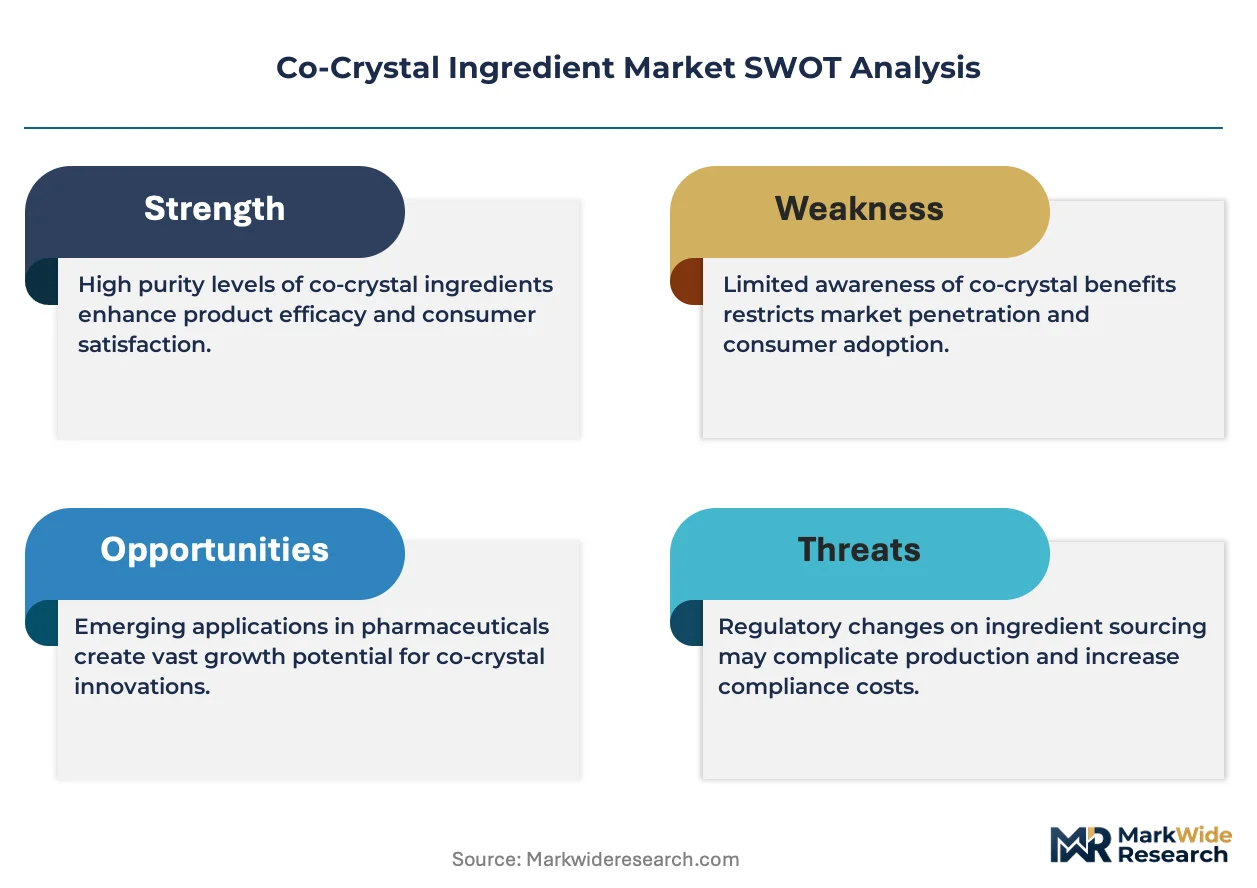
The co-crystal ingredient market compounds steadily as regulatory clarity on pharmaceutical classification unlocks formulation investment previously diverted to amorphous solid dispersions.
For Market Incumbents: Anticipate margin compression from aqueous crystallization platforms by securing backward integration into specialty coformer supply and anchoring customer relationships through analytical instrumentation bundling. Patent thickets around salt-cocrystal boundaries threaten R&D budgets; defend by accelerating polymorph prediction algorithm licensing to compress client development cycles. Capacity reservations in Massachusetts and North Carolina corridor facilities provide regional supply security against single-source concentration risks. For New Entrants and Emerging Players: CDSCO harmonization with ICH Q6A specifications in India opens a window for import substitution plays targeting domestic generic houses in Hyderabad and Ahmedabad. Sports nutrition mineral co-crystals for effervescent applications represent the most penetrable white space, with taste-masked magnesium and zinc formats bypassing established pharmaceutical qualification barriers. A go-to-market angle anchored to clean-label food manufacturer procurement specifications bypasses lengthy drug-grade validation timelines. For Investors and Strategic Acquirers: Roll-up economics work for specialized co-crystal CDMOs because biotech sponsors increasingly unbundle crystallization process development from commercial-scale capacity commitments, enabling milestone-based revenue capture without volume risk. The five-to-ten year viability window favors platform consolidation around continuous manufacturing integration capabilities. Acquisition targets should exhibit validated twin-screw granulation direct-feed compatibility. The signal to watch is EMA-FDA regulatory divergence on thermodynamic stability versus kinetic dissolution data requirements, which reshapes filing priority sequencing and service demand geography.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Crystallization Platform Deployment | FDA quality-by-design mandates force real-time release testing integration that collapses batch-release timelines for generic sponsors. |
| Backward Integration into GRAS Coformer Supply | BASF's Ludwigshafen complex demonstrates how captive intermediate production anchors European pharmaceutical customer relationships. |
| Machine Learning Polymorph Screening Licensing | Cambridge Structural Database-trained algorithms cut experimental screening burden for respiratory drug developers by forty percent. |
| Aqueous Crystallization Process Development | REACH Annex XVII chlorinated solvent restrictions create first-mover positioning for manufacturers with aqueous platform capabilities. |
| Unbundled Phase I-III Supply Agreements | Massachusetts and North Carolina CDMOs capture milestone-based revenue from oncology biotech sponsors unwilling to commit commercial capacity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, CDMO procurement managers, and sports nutrition formulators with secondary validation against FDA filings, EMA reflection papers, CDSCO notifications, and customs trade data. Bottom-up volume estimates from co-crystal precursor shipments triangulated against top-down pharmaceutical formulation spending patterns.
Comparable historical reference periods anchored the projection horizon across the analysis window, with segmentation modeling spanning product type, application, form, and end-user verticals alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves incorporating solvent cost volatility indices, generic drug approval velocity, and clean-label food formulation adoption rates.
Revisions become necessary when pharmacopeial monograph reclassifications, patent litigation outcomes, or abrupt solvent supply disruptions materialize. Forecasts reflect documented assumptions about regulatory pathway stability and continuous manufacturing equipment deployment rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market
Pharmaceutical Ingredients
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Epcam Antagonists Market
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Pharmaceutical Grade Sodium Carbonate Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Sulphonamides Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Prescription Hair Loss and Hair Removal Drugs Market