
 Global Dexamethasone Market | 2026-2036
Global Dexamethasone Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dexamethasone Market Foresight
Asset-light contract manufacturing is tilting competitive dynamics toward firms that outsource API production while retaining formulation expertise. Novartis AG leverages its biologics manufacturing network to secure high-potency corticosteroid capacity without direct chemical synthesis investment. Sun Pharmaceutical Industries Ltd anchors its position through backward integration into Indian API production, shielding margin pools from intermediate price volatility. Hikma Pharmaceuticals competes via specialty injectable portfolios that target hospital formularies across North American and European markets.
Dexamethasone is a synthetic glucocorticoid with a 9-fluoro substituent and 16-methyl group that potentiates anti-inflammatory activity approximately 25-fold above hydrocortisone, manufactured through multi-step steroid backbone modification from plant-derived diosgenin or soy sterols. The compound suppresses cytokine transcription and immune cell migration, serving as a first-line intervention for acute inflammatory cascades, cerebral edema, and chemotherapy-induced nausea. Injectable formulations command premium positioning in hospital emergency settings where rapid bioavailability determines clinical outcomes, while tablet and oral suspension categories serve chronic outpatient management across autoimmune and dermatological therapy areas. Ophthalmic drops occupy a narrow but defensible niche where preservative-free formulations attract specialized prescribing.
The FDA enforces Current Good Manufacturing Practice standards for corticosteroid APIs through its Center for Drug Evaluation and Research, while the EMA's Committee for Medicinal Products for Human Use evaluates dexamethasone-containing products under centralized marketing authorization pathways. India's CDSCO mandates batch release testing for exported corticosteroids through its Central Drugs Laboratory network, creating compliance thresholds that favor established manufacturers over new entrants. Stakeholders must monitor how pharmacovigilance databases track long-term glucocorticoid adverse events, as regulatory pressure on safety labeling could reshape prescribing volumes across chronic therapy segments.
Market Dynamics
Hospital procurement standardization around corticosteroid emergency protocols is compressing supplier selection criteria toward cGMP-certified manufacturers with proven injectable capacity, narrowing the viable vendor pool as health systems consolidate formularies.
Growth Catalysts
- FDA bioequivalence tightening:Heightened scrutiny of generic glucocorticoid dissolution profiles is redirecting hospital procurement toward validated manufacturing networks with demonstrated batch consistency.
- Respiratory emergency protocols:Standardized corticosteroid administration for acute inflammatory cascades in emergency departments is hardwiring dexamethasone into clinical pathways across tertiary care networks.
- India API-to-finished-dose integration:Domestic vertical consolidation is shortening supply cycles for export markets and capturing margin pools previously lost to intermediate traders.
Market Restraints
- Diosgenin feedstock volatility:Plant-derived steroid backbone precursors face harvest-dependent price swings that compress formulation margins during agricultural shortfalls.
- Single-region API concentration:Bulk corticosteroid intermediate production clusters in specific Indian manufacturing corridors, creating geographic vulnerability to localized regulatory actions or logistics disruptions.
- Long-acting glucocorticoid substitution:Betamethasone and triamcinolone alternatives compete for chronic outpatient indications where sustained anti-inflammatory effect reduces dosing frequency.
Strategic Opportunities
- Brazil chronic disease expansion:Underpenetrated autoimmune and dermatology segments in Latin America's largest pharmaceutical market offer volume expansion for tablet and oral suspension categories.
- Preservative-free ophthalmic niche:Specialized dry-eye and post-surgical indications reward formulation expertise with defensible pricing outside commodity injectable competition.
- EMA centralized authorization pathways:Harmonized marketing authorization procedures enable simultaneous multi-country launches that amortize regulatory investment across European hospital networks.
Industry Challenges
- High-potency handling certification:cGMP compliance for corticosteroid APIs demands specialized containment infrastructure and personnel training that extends facility qualification timelines.
- Pharmacovigilance database integration:Long-term glucocorticoid adverse event tracking requires costly signal detection systems and label revision protocols that burden mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dexamethasone Market |
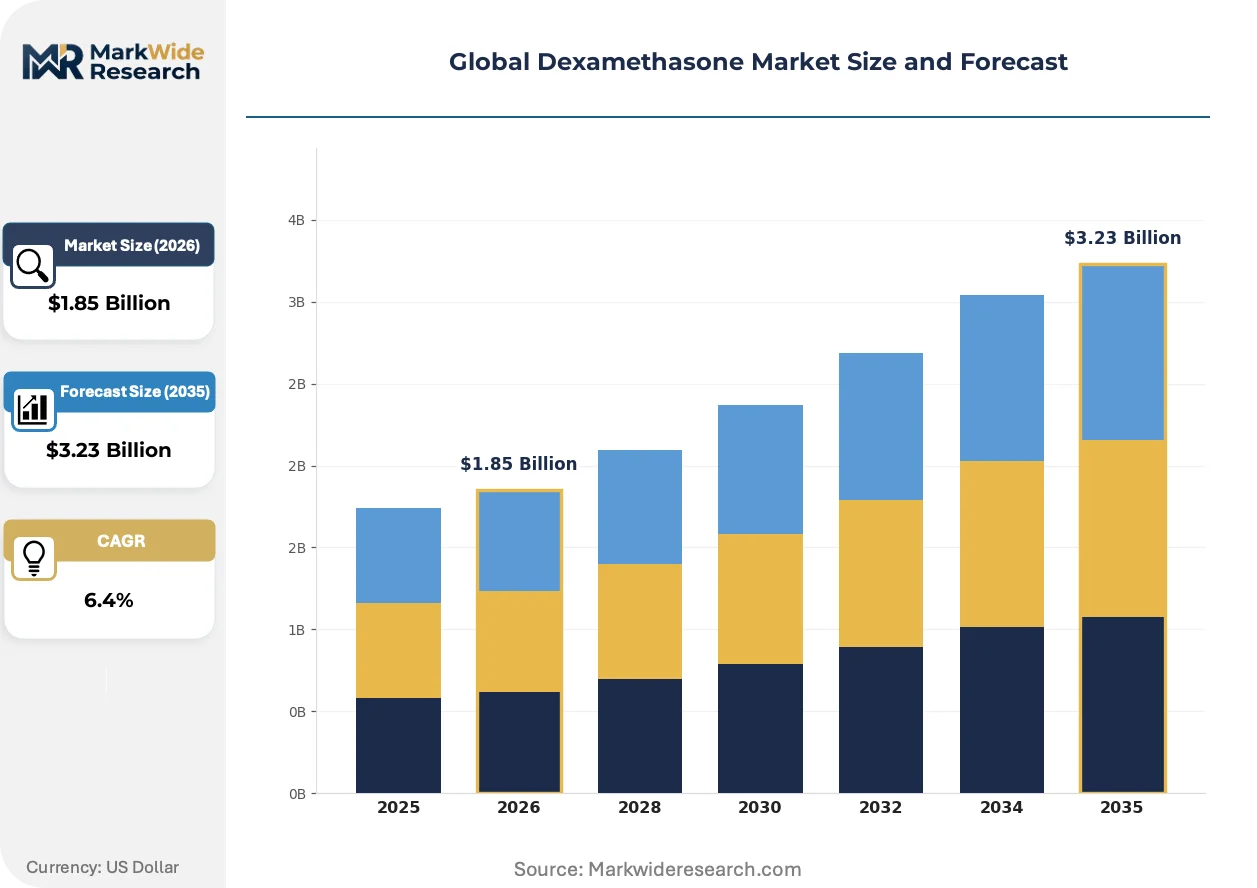
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Tablet, Oral Suspension, Topical Cream, Ophthalmic Drops Therapy Area: Inflammation, Allergic Disorders, Autoimmune Diseases, Respiratory Conditions, Dermatological Conditions End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Home Healthcare Providers, Research Institutes Delivery Mode: Intravenous, Oral, Intramuscular, Epidural, Subcutaneous |
| Companies Covered | Novartis AG, Pfizer Inc, Sun Pharmaceutical Industries Ltd, Cadila Pharmaceuticals, Hikma Pharmaceuticals, Fresenius Kabi, Merck & Co., Inc., Sanofi, Dr. Reddy’s Laboratories Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dexamethasone Market Shifts & Advancements
Process analytical technology and continuous manufacturing are reshaping how corticosteroid APIs achieve quality assurance, compressing batch release timelines while tightening specification control.
Continuous flow chemistry is digitizing steroid backbone modification from diosgenin through fluorination and methylation steps. European contract manufacturers with biologics infrastructure are retrofitting multi-purpose trains for high-potency corticosteroid synthesis. This convergence is compressing capital requirements for entry while raising the technical bar for quality system documentation.
REACH authorization requirements for fluorinated intermediates are forcing reformulation of synthetic pathways across European manufacturing networks. ECHA's sunset date pressures are accelerating migration toward alternative fluorination reagents with improved environmental profiles. German and Swiss API producers are absorbing compliance costs through premium positioning in hospital procurement channels.
Hospital formulary consolidation is compressing supplier rosters toward dual-source arrangements with guaranteed volume commitments. Group purchasing organizations in the United States are unbundling emergency corticosteroid categories from broader anesthesia contracts, creating standalone bidding events that favor manufacturers with dedicated injectable capacity. This disintermediation is visible most acutely in integrated delivery networks spanning multiple states.
Global Dexamethasone Market Segmentation
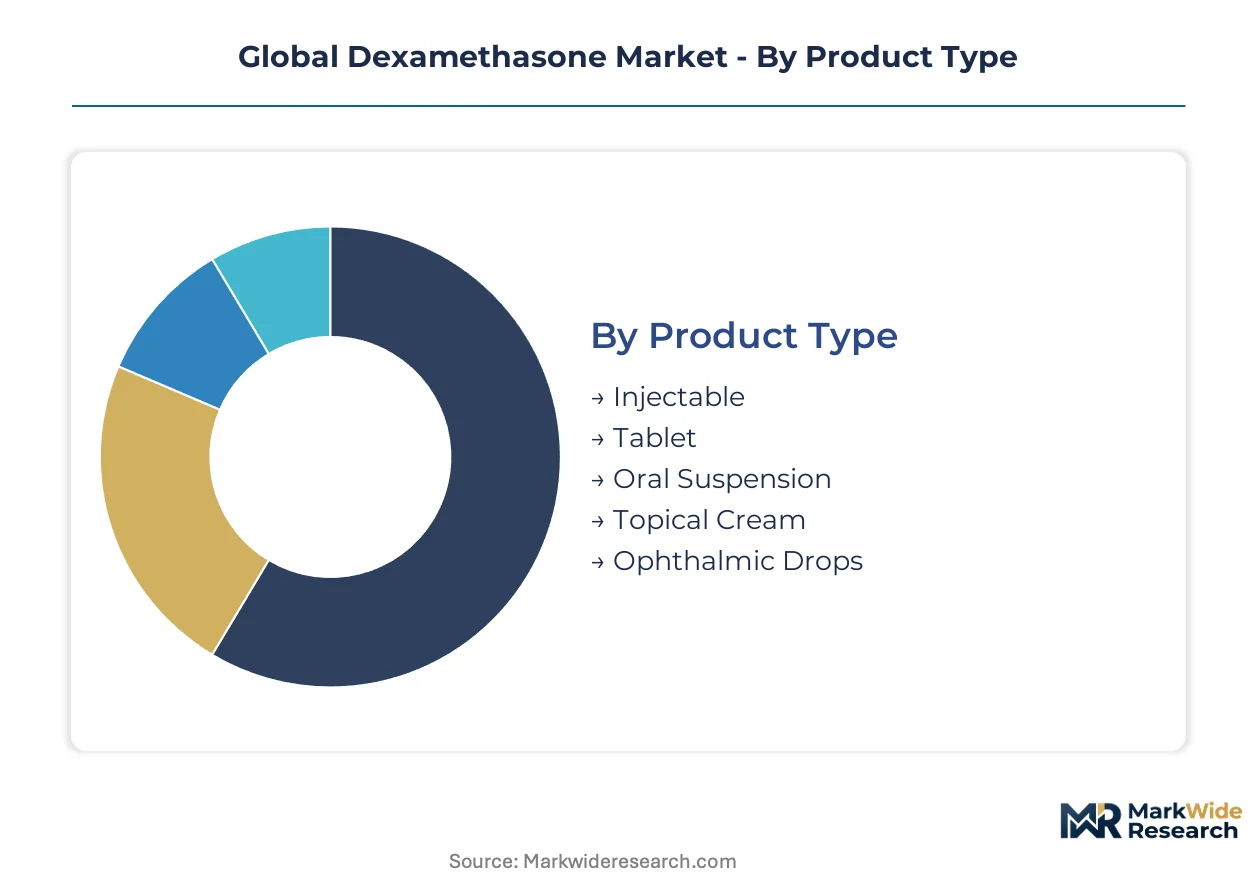
Dexamethasone's formulation diversity creates distinct margin profiles and regulatory pathways. Product type determines manufacturing complexity and hospital procurement priority, while therapy area and delivery mode shape clinical positioning against competing corticosteroids.
Product Type:
Cost tier stratification separates emergency-grade injectables from commoditized oral formats, with manufacturing infrastructure requirements widening the competitive moat at each level.
- Injectable:Aqueous and emulsion formulations for intravenous or intramuscular administration achieve rapid plasma concentration in emergency settings. Hospital procurement in the United States and Germany concentrates demand around cGMP-certified producers with validated sterile fill-finish lines, as FDA and EMA bioequivalence tightening filters out marginal suppliers.
- Tablet:Compressed oral solids with immediate or modified release profiles serve chronic outpatient management where dosing flexibility matters. Demand clusters in India's domestic market and Brazil's expanding public health system, though diosgenin feedstock volatility compresses margin pools during agricultural shortfalls.
- Oral Suspension:Liquid formulations enable pediatric and geriatric dosing where swallowing difficulty prevents tablet use.
- Topical Cream:Dermal preparations with penetration enhancers target localized inflammation without systemic exposure.
- Ophthalmic Drops:Preservative-free formulations command defensible pricing in post-surgical and dry-eye niches.
Injectable commands the established base. The steepest expansion runs through Ophthalmic Drops.
Therapy Area:
Application intensity varies by clinical setting, with acute hospital indications rewarding rapid bioavailability and chronic conditions favoring patient-administered formats.
- Inflammation:Acute inflammatory cascades in trauma, surgery, and sepsis drive highest-volume hospital consumption. Emergency department protocols in tertiary care networks across the United Kingdom, France, and Japan hardwire dexamethasone into standardized corticosteroid administration pathways.
- Respiratory Conditions:Acute exacerbations of asthma and COPD, plus viral pneumonia protocols, anchor demand in pulmonary critical care. India's hospital procurement standardization and CDSCO batch release requirements are concentrating supplier selection toward domestic API-integrated manufacturers.
- Allergic Disorders:Anaphylaxis and severe allergic reactions represent episodic high-dose demand.
- Autoimmune Diseases:Lupus, rheumatoid arthritis, and vasculitis require chronic immunosuppression with dose titration.
- Dermatological Conditions:Eczema, psoriasis, and contact dermatitis utilize topical and systemic routes.
Inflammation anchors volume concentration. Autoimmune Diseases show the most rapid climb as outpatient protocols expand.
End User:
Customer type determines purchasing authority, with integrated delivery networks wielding consolidated formulary power over fragmented outpatient settings.
- Hospitals:Tertiary and secondary acute care facilities command the dominant share through emergency department and surgical protocols. Group purchasing organizations in the United States have unbundled corticosteroid categories from anesthesia contracts, creating standalone bidding events that favor dedicated injectable capacity.
- Specialty Clinics:Rheumatology, dermatology, and ophthalmology practices drive chronic prescribing with patient-specific dosing. Brazil's chronic disease expansion is opening volume growth for tablet and suspension categories outside hospital channels.
- Diagnostic Laboratories:Pre-procedural prophylaxis and contrast reaction preparedness create institutional demand.
- Home Healthcare Providers:Infusion and nursing services enable post-acute corticosteroid continuation.
- Research Institutes:Clinical trial supply and investigator-initiated studies generate variable batch demand.
Hospitals retain procurement dominance. Specialty Clinics are gaining share fastest as care decentralizes.
Delivery Mode:
Route of administration directly governs bioavailability kinetics, manufacturing complexity, and prescriber training requirements.
- Intravenous:Direct vascular delivery achieves immediate peak plasma concentration for cerebral edema and septic shock. EMA centralized authorization pathways enable simultaneous multi-country launches that amortize regulatory investment across European hospital networks.
- Oral:Gastrointestinal absorption enables self-administration and dose flexibility in chronic disease management. Patient compliance advantages in autoimmune and dermatological therapy areas sustain volume despite slower onset versus parenteral routes.
- Intramuscular:Depot formulations provide sustained release for conditions requiring prolonged anti-inflammatory effect.
- Epidural:Perineural delivery targets localized inflammation with reduced systemic exposure.
- Subcutaneous:Tissue absorption offers intermediate kinetics for outpatient settings.
Intravenous holds the revenue core. Oral delivery is climbing fastest on outpatient protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement officers in Germany, India, and the United States command the dominant buyer positions, with integrated delivery networks and government tenders compressing supplier selection toward cGMP-certified manufacturers with validated sterile capacity.
United States
Group purchasing organizations have unbundled emergency corticosteroid categories from anesthesia contracts, creating standalone bidding events that favor dedicated injectable capacity. FDA bioequivalence tightening filters hospital procurement toward validated manufacturing networks with demonstrated batch consistency. The New Jersey and Pennsylvania corridor hosts concentrated sterile fill-finish infrastructure serving tertiary care networks.
Germany
EMA centralized authorization pathways enable simultaneous multi-country launches that amortize regulatory investment across European hospital networks. REACH authorization requirements for fluorinated intermediates force reformulation of synthetic pathways, with German API producers absorbing compliance costs through premium hospital positioning. The Rhine-Main and Bavarian manufacturing clusters specialize in high-potency corticosteroid containment infrastructure.
India
CDSCO batch release testing for exported corticosteroids creates compliance thresholds favoring established manufacturers over new entrants. Domestic API-to-finished-dose integration shortens supply cycles for export markets and captures margin pools previously lost to intermediate traders. The Hyderabad and Mumbai manufacturing corridors concentrate bulk corticosteroid intermediate production.
Brazil
Underpenetrated autoimmune and dermatology segments in Latin America's largest pharmaceutical market offer volume expansion for tablet and oral suspension categories. ANVISA's alignment with ICH guidelines accelerates registration timelines for manufacturers with existing FDA or EMA approvals. The São Paulo and Rio de Janeiro metropolitan areas anchor distribution networks for chronic disease expansion.
Japan
PMDA's stringent GMP inspections for foreign manufacturers create extended facility qualification timelines that favor established suppliers with prior regulatory history. Emergency department protocols in tertiary care networks hardwire dexamethasone into standardized corticosteroid administration pathways. The Kanto and Kansai regions concentrate hospital procurement authority and specialty clinic networks.
Global Dexamethasone Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiers. Hospital formulary consolidation compresses supplier rosters toward dual-source arrangements with guaranteed volume commitments, while mid-scale manufacturers face extended qualification timelines from high-potency handling certification demands. Three archetypes dominate: multinational pharmaceutical conglomerates with biologics infrastructure, Indian API-integrated manufacturers with backward control over diosgenin supply, and European contract manufacturers retrofitting continuous flow chemistry trains. Competitive moves center on sterile capacity expansion and regulatory pathway harmonization across FDA, EMA, and CDSCO jurisdictions.
Among Swiss and German-based conglomerates, Novartis AG occupies a position exemplifying biologics-network leverage for high-potency corticosteroid capacity without direct chemical synthesis investment. Sun Pharmaceutical Industries Ltd and Dr. Reddy's Laboratories Ltd anchor the Indian API-integrated tier, representing backward integration models that shield margin pools from intermediate price volatility. Hikma Pharmaceuticals sits within the specialty injectable archetype, competing via hospital formulary positioning across North American and European markets.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc |
| Sun Pharmaceutical Industries Ltd |
| Cadila Pharmaceuticals |
| Hikma Pharmaceuticals |
| Fresenius Kabi |
| Merck & Co., Inc. |
| Sanofi |
| Dr. Reddy's Laboratories Ltd. |
| Others |
Supply & Pricing Matrix
Hyderabad's concentrated API manufacturing corridors determine downstream pricing leverage through captive diosgenin processing and sterile fill-finish capacity scarcity. CDSCO batch release requirements and FDA bioequivalence tightening amplify cost premiums for validated producers, compressing margins for non-certified competitors.
Pricing Analysis
Certification level (FDA-grade versus non-validated) creates the primary spread across injectable tiers, with cGMP-certified sterile capacity commanding substantial premiums in hospital procurement. Contract-based long-term offtake dominates, with volume scale and geographic delivery cost as secondary differentiation factors. Pricing pressure stems from diosgenin feedstock volatility and REACH compliance costs for fluorinated intermediates. Public health systems in Brazil and India exhibit highest price sensitivity, while integrated delivery networks in the United States prioritize supply assurance over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier-financing arrangements, with supply-chain finance facilities emerging among Indian API-integrated manufacturers. Production gravity centers on India, China, and Germany for corticosteroid intermediates and finished dose. The supply chain draws from diosgenin, soy sterols, and fluorination reagents as critical inputs. Single-region API concentration in Indian manufacturing corridors creates geographic vulnerability to localized regulatory actions. Distribution runs through hospital group purchasing organizations and government tender mechanisms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dexamethasone market operates as a defensive-moat arena where regulatory entrenchment protects incumbent positions. cGMP certification timelines and high-potency handling infrastructure create switching costs that new entrants cannot easily replicate.
For Market Incumbents: Entrench formulary positions through dual-source contracting with guaranteed volume commitments across integrated delivery networks. Expand sterile fill-finish capacity in the New Jersey-Pennsylvania corridor to capture unbundled corticosteroid procurement events. Betamethasone and triamcinolone substitution threats in chronic indications demand formulation differentiation through preservative-free ophthalmic development.
For New Entrants and Emerging Players: Pursue Brazil's underpenetrated autoimmune and dermatology segments where tablet and oral suspension categories face less procurement consolidation. ANVISA's ICH alignment accelerates registration for manufacturers with existing FDA or EMA approvals, lowering barrier entry. Target specialty clinic channels outside hospital procurement dominance, leveraging chronic disease expansion in São Paulo metropolitan distribution networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API-integrated manufacturers with backward control over diosgenin supply and captive sterile capacity. Long-term viability hinges on continuous manufacturing adoption and regulatory pathway harmonization across FDA, EMA, and CDSCO jurisdictions. Acquisition targets should demonstrate established batch release histories and existing high-potency containment infrastructure. Monitor pharmacovigilance database expansion for glucocorticoid adverse event tracking as a signal for potential label revision pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Sterile Capacity Expansion | cGMP-certified injectable lines capture unbundled hospital procurement events in United States integrated delivery networks. |
| Backward Integration into API | Captive diosgenin processing shields margin pools from agricultural harvest volatility and intermediate trader markups. |
| Regulatory Pathway Harmonization | EMA centralized authorization enables simultaneous multi-country launches across European hospital networks. |
| Preservative-Free Formulation Development | Specialized ophthalmic niches reward expertise with defensible pricing outside commodity injectable competition. |
| Continuous Manufacturing Transition | Process analytical technology adoption compresses batch release timelines while tightening specification control. |
Research Methodology
A standing panel of hospital procurement managers, regulatory affairs leads, formulary directors, and sterile manufacturing executives provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA filings, EMA centralized authorization submissions, CDSCO batch release records, and ClinicalTrials.gov protocol databases. Bottom-up demand modeling triangulated against top-down pharmaceutical production capacity assessments.
Scenario bracketing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning formulation type, therapy area, delivery mode, and regional regulatory cluster. CAGRs derived from volume-demand elasticity modeling and pricing trajectory analysis. Forecast inputs incorporated diosgenin harvest cycle patterns, hospital formulary consolidation timelines, and REACH authorization sunset pressures for fluorinated intermediates.
Sensitivities concentrate around diosgenin agricultural shortfalls, localized regulatory enforcement in Indian manufacturing corridors, and pharmacovigilance-driven label revision cascades. Forecasts reflect documented assumptions regarding hospital procurement standardization velocity and continuous manufacturing adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Furosemide Market
Pharmaceutical Ingredients
Sulphonamides Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Cyprosin Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Sterile Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Fixed-Dose Combination Drugs Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Casein and Casein Derivatives Market
Pharmaceutical Ingredients
Encapsulated Salicylic Acid Market
Pharmaceutical Ingredients
Acetaminophen API Market