
 Fosfomycin Trometamol Powder Market | 2026-2036
Fosfomycin Trometamol Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Fosfomycin Trometamol Powder Market Insights
Multi-source API procurement is consolidating among generic pharmaceutical manufacturers seeking supply security for fosfomycin trometamol active pharmaceutical ingredients. Xunda Pharma leverages backward integration into fermentation-based API production to control raw material costs. Zambon anchors its position through specialized powder formulation expertise in European hospital markets. Northeast Pharm competes on manufacturing scale, operating one of the larger fermentation facilities serving domestic and export demand for fosfomycin derivatives.
Fosfomycin trometamol powder comprises a phosphonic acid antibiotic salt formulated as a water-soluble granule for oral suspension, typically reconstituted to deliver a single three-gram therapeutic dose for acute uncomplicated lower urinary tract infections. The compound functions by irreversibly inhibiting bacterial cell wall synthesis through inactivation of the enzyme MurA, providing bactericidal activity against both Gram-positive and Gram-negative uropathogens including extended-spectrum beta-lactamase producing strains. The oral powder and granule product types command preference in outpatient settings where patient compliance with single-dose regimens exceeds that of multi-day antibiotic courses. Injectable formulations retain structural importance in hospital surgical prophylaxis segments where preoperative urinary sterilization requires rapid systemic bioavailability. Sachet packaging dominates retail pharmacy distribution, while blister configurations serve institutional procurement channels requiring unit-dose control.
The FDA enforces Current Good Manufacturing Practice regulations for sterile powder processing facilities, with recent inspection emphasis on cross-contamination controls between beta-lactam and non-beta-lactam antibiotic production lines. The EMA's revised guidelines on antimicrobial resistance require sponsors to demonstrate minimal ecological impact from fosfomycin excretion in wastewater streams as a condition of marketing authorization renewal. China's NMPA mandates bioequivalence studies for domestic generic powder formulations against innovator references before national reimbursement listing eligibility. Stakeholders must monitor evolving resistance surveillance data from the WHO Global Antimicrobial Resistance and Use Surveillance System to anticipate regional prescribing guideline revisions that could shift demand across formulation categories.
Market Dynamics
Hospital formulary committees are tightening single-dose antibiotic protocols as antimicrobial stewardship programs gain enforcement authority, compressing prescribing windows for fosfomycin trometamol powder while elevating documentation requirements for multidrug-resistant organism coverage.
Growth Catalysts
- Extended-spectrum beta-lactamase surveillance:CDC-mandated reporting of resistant uropathogens drives formulary inclusion of fosfomycin trometamol as first-line oral therapy in US outpatient settings.
- Single-dose compliance economics:Medicare reimbursement incentives for reduced readmission rates favor powder formulations over multi-day antibiotic courses in urology clinics.
- Fermentation capacity expansion:Chinese API manufacturers are commissioning additional phosphonic acid production lines to secure supply for generic formulation export.
Market Restraints
- Phosphonic acid feedstock volatility:Price swings in phosphorus pentachloride and maleic anhydride inputs compress margin stability for fermentation-based API producers.
- Cross-contamination facility scarcity:Limited US contract manufacturing sites with validated beta-lactam/non-beta-lactam segregation constrain domestic powder packaging capacity.
- Urinary antiseptic substitution:Methenamine hippurate prescribing is resurging in European markets as a non-antibiotic prophylactic alternative for recurrent cystitis.
Strategic Opportunities
- Indian outpatient urology expansion:CDSCO streamlined bioequivalence pathways for single-dose antibiotics create first-mover positioning for sachet-format registrations.
- Wastewater impact monetization:EMA's ecological risk assessment requirements favor sponsors with validated biodegradation data, creating differentiation for fermentation-derived versus chemically synthesized APIs.
- Direct-to-pharmacy distribution:Bypassing wholesale intermediaries through hospital group purchasing organization contracts captures margin in institutional procurement channels.
Industry Challenges
- MurA resistance surveillance expertise:Clinical microbiology laboratories lack standardized susceptibility testing protocols for fosfomycin, creating diagnostic uncertainty that delays appropriate prescribing.
- Batch sterilization validation timelines:FDA inspection backlogs for powder aseptic processing facilities extend commercialization schedules for new manufacturing entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fosfomycin Trometamol Powder Market |
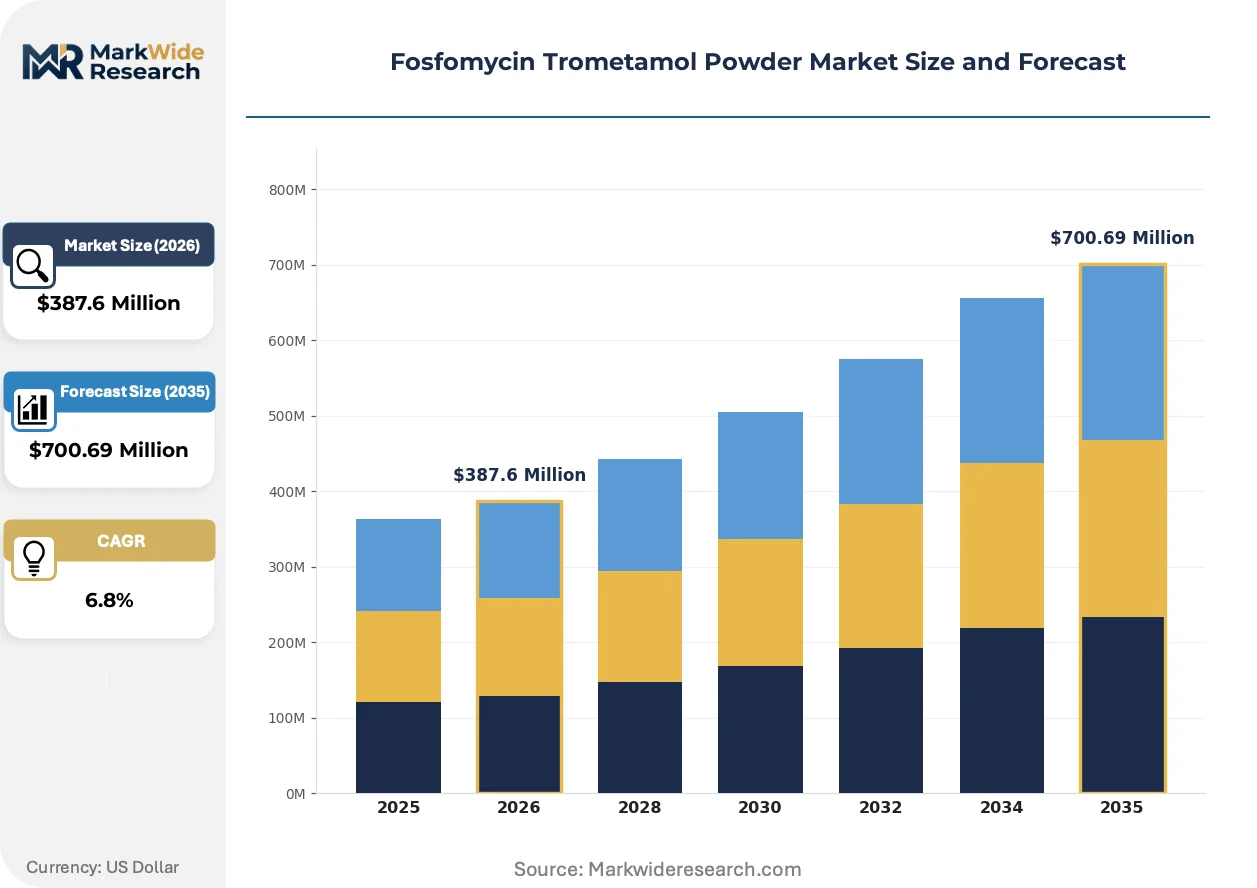
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Powder, Granule Therapy Area: Urinary Tract Infections, Antibiotic Resistant Infections, Bacterial Infections, Surgical Prophylaxis End User: Hospitals, Clinics, Pharmacies, Research Laboratories Packaging Type: Bottles, Sachets, Blisters, Jars |
| Companies Covered | Xunda Pharma, Guilin Hwasun, Zambon, Meiji Seika Pharma, Shanxi C&Y Pharmaceutical, Northeast Pharm, FarmaSino Pharmaceutical, CSPC Pharmaceutical Group, Hunan Huana Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fosfomycin Trometamol Powder Market Trends and Innovations
Formulation science is converging with resistance surveillance infrastructure to reshape how single-dose antibiotics reach prescribing networks, with powder engineering and diagnostic integration emerging as parallel innovation tracks.
Continuous manufacturing for oral antibiotic powders is expanding into hospital procurement channels as equipment suppliers retrofit fluid bed granulation lines for rapid product changeover. European contract manufacturers are adopting these systems to serve fragmented national tender requirements. The technology is expanding into just-in-time production models that reduce inventory carrying costs for multi-source generic portfolios.
EMA's revised environmental risk assessment guidelines now mandate sub-chronic aquatic toxicity studies for all new antibiotic marketing authorizations, forcing API sponsors to commission dedicated ecotoxicology programs. This regulatory shift elevates documentation burdens for chemically synthesized fosfomycin relative to fermentation routes. Generic applicants in Germany and France are responding by consolidating regulatory dossiers to share ecotoxicology data across mutual recognition procedures.
Outpatient urology clinics are consolidating antibiotic prescribing decisions under centralized antimicrobial stewardship committees, displacing individual physician discretion with protocol-driven formulary compliance. Hospital-affiliated ambulatory networks are replacing independent practice purchasing patterns. This concentration is most visible in United States metropolitan markets where health system vertical integration has captured majority urology referral volume.
Fosfomycin Trometamol Powder Market Segmentation
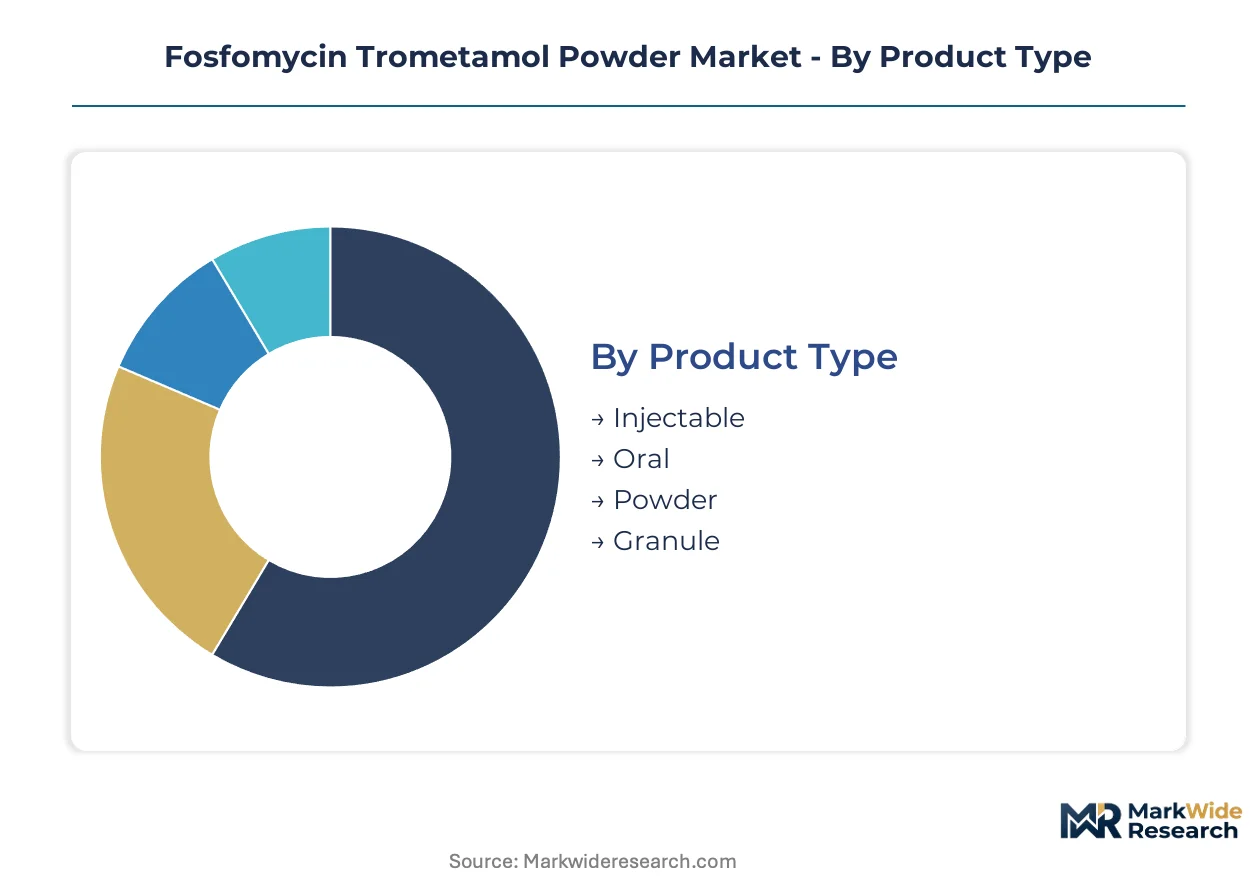
Formulation engineering and prescribing setting determine how fosfomycin trometamol powder reaches patients. Each segmentation axis reveals distinct margin structures, regulatory pathways, and competitive intensity that shape manufacturer positioning.
Product Type:
Customization concentrates in sterile processing requirements while standardization dominates solid oral manufacturing, creating divergent capital intensity across this category.
- Injectable:Sterile solution requiring aseptic filling and endotoxin-controlled manufacturing. Demand clusters in preoperative surgical prophylaxis at tertiary hospitals where rapid systemic bioavailability is non-negotiable. FDA inspection backlogs for sterile powder facilities constrain new entrant capacity.
- Oral:Immediate-release suspension format dominating outpatient urology prescriptions. Medicare reimbursement incentives for reduced readmission rates concentrate demand in United States ambulatory networks. Single-dose compliance economics favor this format over multi-day antibiotic alternatives.
- Powder:Fine-milled granule requiring reconstitution before administration. Hospital formulary committees prioritize this format for antimicrobial stewardship program compliance.
- Granule:Coarser particulate with improved flow properties for automated packaging lines. European contract manufacturers favor this format for national tender fulfillment.
Leading the category by volume: Oral. Growing fastest: Injectable.
Therapy Area:
Application urgency spans from elective prophylaxis to emergency resistant-pathogen coverage, fragmenting pricing power and procurement authority.
- Urinary Tract Infections:Acute uncomplicated cystitis and pyelonephritis requiring rapid bacterial clearance. Outpatient urology clinics in United States metropolitan markets drive volume through protocol-driven prescribing.
- Antibiotic Resistant Infections:Extended-spectrum beta-lactamase producing Enterobacteriaceae coverage. CDC-mandated resistance reporting elevates formulary inclusion for this indication.
- Bacterial Infections:Broad-spectrum gram-positive and gram-negative pathogen targeting. EMA environmental risk assessment requirements favor sponsors with validated biodegradation data.
- Surgical Prophylaxis:Preoperative urinary tract sterilization requiring documented sterility assurance. Hospital group purchasing organization contracts concentrate procurement for this segment.
Volume leader: Urinary Tract Infections. Steepest expansion trajectory: Antibiotic Resistant Infections.
End User:
Customer concentration varies from fragmented retail pharmacy networks to consolidated institutional procurement, reshaping distribution economics.
- Hospitals:Tertiary care institutions with antimicrobial stewardship committees enforcing formulary compliance. Vertical integration of ambulatory networks is displacing independent purchasing patterns.
- Clinics:Outpatient urology and infectious disease practices with protocol-driven prescribing. United States health system consolidation captures majority referral volume in metropolitan markets.
- Pharmacies:Retail and specialty dispensaries handling patient-directed prescriptions. Sachet packaging dominates this channel for convenience and adherence support.
- Research Laboratories:Clinical microbiology facilities developing standardized susceptibility testing protocols. MurA resistance surveillance expertise gaps create diagnostic uncertainty that delays appropriate prescribing.
Hospitals command the largest procurement volumes. Clinics are gaining share fastest as ambulatory networks expand.
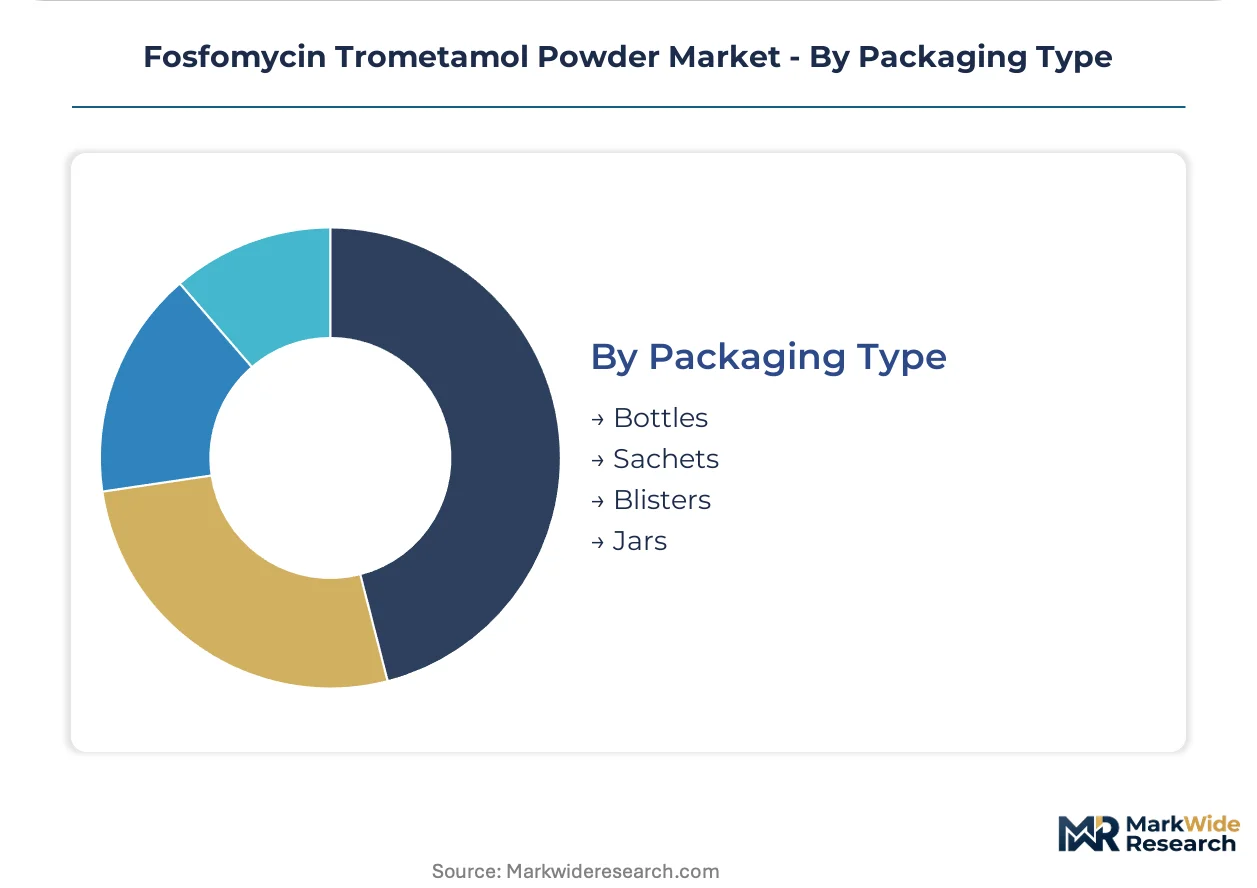
Packaging Type:
Unit-dose control requirements versus bulk dispensing efficiency split this category between institutional and retail channels.
- Bottles:Multi-dose containers for hospital pharmacy bulk compounding. Aseptic processing validation timelines extend commercialization schedules for new manufacturing entrants.
- Sachets:Single-unit foil laminates dominating retail pharmacy distribution. CDSCO streamlined bioequivalence pathways in India create first-mover positioning for this format.
- Blisters:Unit-dose thermoformed configurations serving institutional procurement channels. Cross-contamination facility scarcity in United States contract manufacturing constrains domestic capacity.
- Jars:Wide-mouth containers for reconstitution in clinical settings. Limited adoption outside specialized compounding pharmacies.
Sachets lead by unit volume. Blisters are climbing the fastest on hospital formulary consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphonic acid feedstock availability clusters fermentation capacity in East Asian chemical corridors, while finished formulation demand concentrates in Western hospital procurement networks. Regulatory divergence between FDA antimicrobial stewardship mandates and EMA environmental risk assessments is fragmenting go-to-market pathways. API manufacturing gravity and formulation demand are decoupling geographically.
United States
Outpatient urology clinic consolidation under health system vertical integration is concentrating prescribing decisions in metropolitan ambulatory networks. FDA inspection backlogs for sterile powder facilities constrain domestic packaging capacity expansion. Greater Boston and the Research Triangle host clinical microbiology laboratories developing MurA susceptibility testing protocols.
China
NMPA bioequivalence mandates for national reimbursement listing are accelerating generic powder formulation approvals. Yangtze River Delta fermentation facilities are commissioning additional phosphonic acid production lines to secure API supply for export markets. Zhejiang and Jiangsu provinces concentrate backward-integrated manufacturers controlling raw material costs through captive fermentation.
Germany
EMA environmental risk assessment requirements for antibiotic marketing authorization renewal are elevating documentation burdens for API sponsors. The Eindhoven-Rhine-Ruhr corridor hosts contract manufacturers adopting continuous manufacturing systems for fluid bed granulation. German hospital group purchasing organizations are consolidating procurement through direct-to-pharmacy distribution contracts.
India
CDSCO streamlined bioequivalence pathways for single-dose antibiotics are creating first-mover positioning for sachet-format registrations. Maharashtra and Gujarat pharmaceutical clusters are expanding oral powder formulation capacity for domestic and export markets. Indian outpatient urology expansion is driving demand for patient-compliant single-dose therapies.
Japan
PMDA antimicrobial resistance surveillance integration is tightening formulary inclusion criteria for oral antibiotics. The Kansai region maintains specialized powder formulation expertise serving domestic hospital markets. Japanese clinical microbiology standards are advancing standardized fosfomycin susceptibility testing protocols.
Fosfomycin Trometamol Powder Market Competitive Landscape
Backward integration into fermentation-based API production dominates the current landscape as generic manufacturers seek supply security. The vendor base stratifies between integrated API-formulation players and pure-play contract manufacturers. Three archetypes anchor competitive positioning: fermentation-scale specialists, formulation-engineering specialists, and hybrid API-formulation integrators. Capacity expansion and regulatory dossier consolidation represent the dominant competitive moves.
Among fermentation-scale specialists, Northeast Pharm exemplifies manufacturing-scale competition through large-scale phosphonic acid production facilities. Xunda Pharma occupies a position within the backward-integrated tier, controlling raw material costs through in-house fermentation capacity. Zambon anchors the formulation-engineering specialist archetype, leveraging powder processing expertise in European hospital procurement channels. These three companies represent distinct strategic postures without implying specific market share claims.
| Leading Market Players |
|---|
| Xunda Pharma |
| Guilin Hwasun |
| Zambon |
| Meiji Seika Pharma |
| Shanxi C&Y Pharmaceutical |
| Northeast Pharm |
| FarmaSino Pharmaceutical |
| CSPC Pharmaceutical Group |
| Hunan Huana Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
Backward-integrated Chinese pharmaceutical manufacturers anchor supply-side discipline through captive fermentation capacity, translating upstream phosphorus pentachloride cost control into downstream powder formulation pricing power. This ownership pattern tightens margin structures for pure-play European contract manufacturers lacking comparable upstream leverage.
Pricing Analysis
Warranty and regulatory dossier bundling separate premium-tier fermentation-derived APIs from unbundled chemically synthesized alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification grade, EMA environmental risk assessment documentation, and volume scale commitments. Cost compression in standard-tier sachet formulations is intensifying because Indian CDSCO streamlined bioequivalence pathways attract multi-source generic entrants. Hospital group purchasing organizations demonstrate lowest price sensitivity due to antimicrobial stewardship protocol mandates, while retail pharmacy channels face highest sensitivity from patient out-of-pocket exposure.
Supply Chain Analysis
Domestic-content mandates in China's NMPA national reimbursement listing requirements are reshaping sourcing patterns toward Yangtze River Delta fermentation facilities. API production concentrates in China, India, and Italy, drawing from phosphorus pentachloride, maleic anhydride, and specialized fermentation media inputs. Single-source vulnerability in US sterile powder aseptic processing capacity creates bottlenecks for hospital procurement channels. Distribution runs through hospital group purchasing organization contracts and direct-to-pharmacy institutional channels, bypassing wholesale intermediaries for formulary-controlled antibiotics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where fermentation capacity ownership determines API cost position and formulary access. Players are pursuing upstream phosphonic acid production control as the decisive lever.
For Market Incumbents: Extend fermentation facility footprints into Zhejiang and Jiangsu provinces to lock in phosphorus feedstock cost advantages against emerging Indian API competitors. Consolidate regulatory dossier portfolios across mutual recognition procedures to share EMA ecotoxicology data burdens. Cross-contamination facility scarcity in US contract manufacturing presents a margin defense opportunity through validated beta-lactam segregation investments. For New Entrants and Emerging Players: Launch via CDSCO streamlined bioequivalence pathways targeting Maharashtra and Gujarat pharmaceutical clusters for sachet-format first-mover positioning. White-space concentration appears in Indian outpatient urology expansion and EMA ecological risk assessment differentiation through fermentation-derived API biodegradation data. Direct-to-pharmacy distribution contracts with hospital group purchasing organizations offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap fermentation specialists in China's Yangtze River Delta with validated NMPA bioequivalence dossiers and captive phosphorus pentachloride supply. Long-term viability over the extended pharmaceutical investment horizon hinges on antimicrobial stewardship protocol permanence and MurA resistance surveillance infrastructure buildout. Watch FDA inspection backlog resolution timelines as the critical inflection signal for sterile powder packaging capacity entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation | Xunda Pharma's captive phosphonic acid production controls raw material cost volatility. |
| EMA Ecotoxicology Dossier Consolidation | Generic applicants share mutual recognition procedure data to meet environmental risk requirements. |
| CDSCO Sachet Registration Acceleration | Streamlined bioequivalence pathways create first-mover positioning in Indian outpatient urology. |
| Continuous Manufacturing Adoption | European contract manufacturers retrofit fluid bed granulation for just-in-time national tender fulfillment. |
| Direct-to-Pharmacy Distribution Contracts | Bypassing wholesale intermediaries captures margin in hospital group purchasing organization channels. |
Research Methodology
Multi-period observation of FDA inspection backlogs, NMPA bioequivalence approval timelines, and EMA environmental risk assessment documentation anchored the trend analysis, supplemented by interviews with fermentation plant managers, hospital formulary directors, regulatory affairs leads, and GPO contracts managers. Secondary validation drew from FDA 483 inspection observations, EMA marketing authorization renewal guidelines, CDSCO approval databases, and WHO Global Antimicrobial Resistance surveillance reports. Bottom-up volume modeling across formulation types triangulated against top-down API production capacity estimates.
Input-output matrices mapped phosphonic acid fermentation capacity to finished powder formulation output across the projection horizon. Segmentation dimensions included product type, therapy area, end user, and packaging format, with regional regulatory cluster as the industry-specific overlay. CAGRs were derived from trend extrapolation of antimicrobial stewardship protocol adoption, resistance surveillance reporting mandates, and outpatient urology clinic consolidation patterns. Forecast inputs incorporated phosphorus pentachloride price volatility indices and sterile processing facility utilization rates.
Phosphonic acid feedstock price shocks, FDA aseptic processing inspection delays, and MurA resistance surveillance protocol standardization are the dominant revision risks to volume and value projections. Forecasts reflect assumptions around antimicrobial stewardship permanence and single-dose therapy reimbursement stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Propellants Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Pharmaceutical Indicator Strips Market
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
Prescription Hair Loss and Hair Removal Drugs Market