
 MEK Inhibitors Market | 2026-2036
MEK Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
MEK Inhibitors Market Outlook
The EU Green Deal's pharmaceutical sustainability criteria is restructuring procurement standards across European hospital networks. Novartis leverages its integrated oncology portfolio to sustain leadership in targeted therapy development. AstraZeneca anchors its competitive position through deep investment in combination therapy research. Roche differentiates via diagnostic-companion testing linkages that streamline patient selection for MEK-directed treatment.
MEK inhibitors are small-molecule compounds that selectively block mitogen-activated protein kinase kinase enzymes in the RAS-RAF-MEK-ERK signaling cascade, typically formulated as oral tablets or intravenous solutions for precise oncologic intervention. These agents primarily treat melanoma, non-small cell lung cancer, and solid tumors harboring BRAF or NRAS mutations by interrupting aberrant cell proliferation signals. Selumetinib and trametinib dominate current revenue pools given established pediatric and adult oncology indications, while cobimetinib competes aggressively in combination regimens where dual BRAF-MEK blockade improves progression-free survival. Oral administration routes command the largest patient volume share due to outpatient convenience, though intravenous delivery sustains relevance in hospitalized settings requiring dose intensity control.
FDA breakthrough therapy designation and EMA priority medicines pathways compress development timelines and reshape launch sequencing for MEK-targeted assets. REACH chemical safety standards and evolving EMA good manufacturing practice guidelines constrain active pharmaceutical ingredient sourcing and formulation stability requirements. Stakeholders must monitor emerging resistance mutation profiles and competitive biosimilar pressures to calibrate pipeline prioritization and lifecycle management investments.
Market Dynamics
FDA breakthrough therapy designation and EMA priority medicines pathways compress development timelines and reshape launch sequencing for MEK-targeted assets, while REACH chemical safety standards and evolving EMA good manufacturing practice guidelines constrain active pharmaceutical ingredient sourcing and formulation stability requirements.
Growth Catalysts
- Accelerated regulatory pathways:FDA breakthrough therapy designation and EMA priority medicines status compress clinical trial timelines for MEK-targeted assets. Pediatric oncology indications for selumetinib expand addressable patient populations.
- Combination therapy expansion:Dual BRAF-MEK blockade protocols in melanoma and non-small cell lung cancer improve progression-free survival metrics. Academic medical centers in the United States are expanding targeted therapy protocols.
- Companion diagnostic integration:Diagnostic-companion testing linkages streamline patient selection for MEK-directed treatment. BRAF and NRAS mutation profiling becomes standard in solid tumor workups.
Market Restraints
- API sourcing concentration:Active pharmaceutical ingredient manufacturing for MEK inhibitors concentrates in specific Asian supply hubs, creating single-source vulnerability.
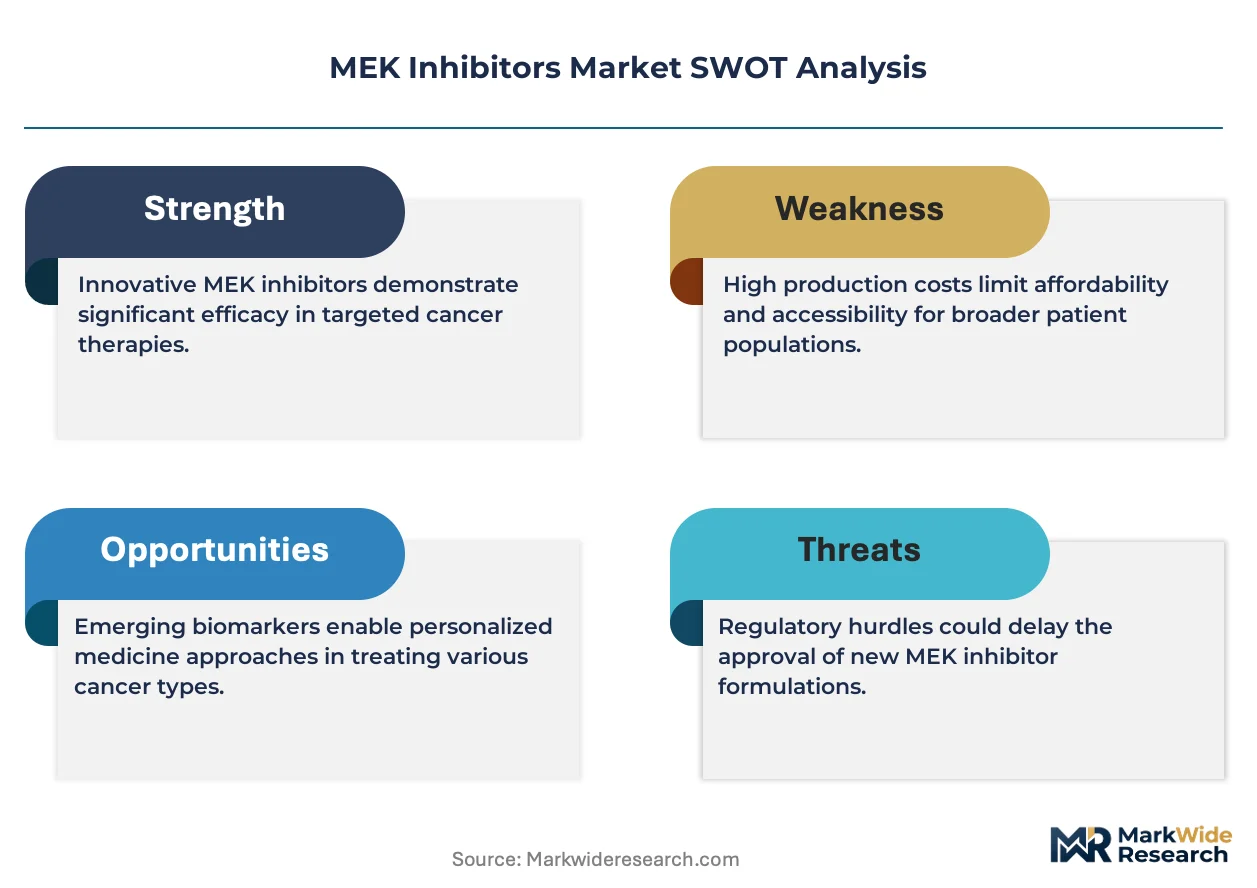
- Resistance mutation emergence:Acquired MEK inhibitor resistance through secondary mutations in the MAPK pathway limits durable response durations.
- REACH compliance costs:ECHA chemical safety assessments and evolving good manufacturing practice guidelines impose substantial reformulation and documentation burdens on European manufacturing.
Strategic Opportunities
- Brain metastasis indications:Blood-brain barrier penetrant MEK inhibitor formulations address unmet need in melanoma and lung cancer central nervous system involvement.
- Adjuvant therapy positioning:Post-surgical MEK inhibitor protocols in resected BRAF-mutant melanoma represent a treatment duration expansion opportunity.
- IRA price negotiation carve-outs:Orphan drug and pediatric exclusivity provisions within the Inflation Reduction Act create pricing protection for selumetinib and similar assets.
Industry Challenges
- Biosimilar preparation timelines:Originator manufacturers must compress lifecycle management investments as trametinib and cobimetinib approach loss-of-exclusivity windows.
- Resistance monitoring infrastructure:Real-time circulating tumor DNA surveillance for MAPK pathway reactivation requires specialized molecular pathology capabilities that many community oncology practices lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEK Inhibitors Market |
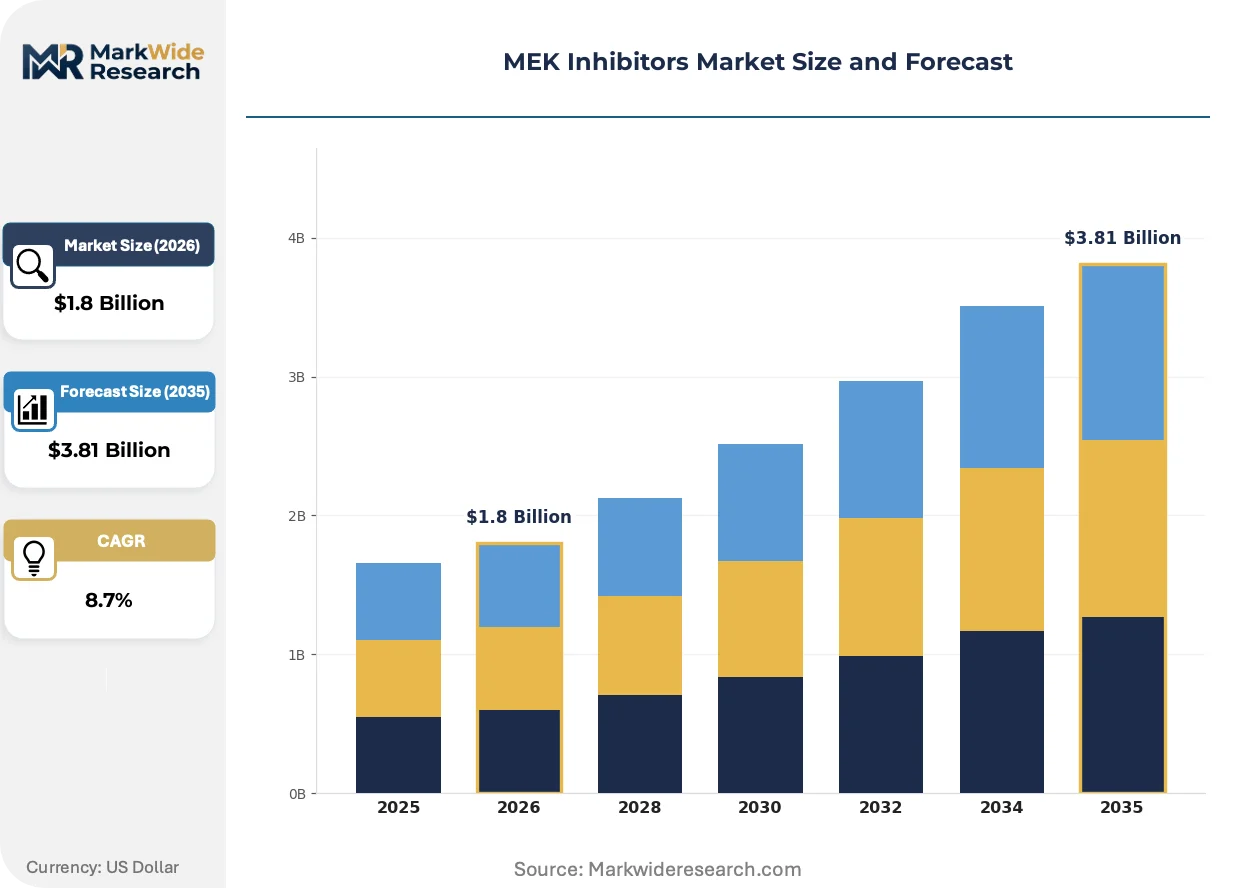
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selumetinib, Trametinib, Cobimetinib, Others Application: Oncology, Autoimmune Disorders, Cardiovascular Diseases, Others End User: Hospitals, Research Laboratories, Clinics, Oncology Centers Administration Route: Oral, Intravenous, Subcutaneous, Others |
| Companies Covered | Novartis, AstraZeneca, Roche, Pfizer, Merck & Co., GlaxoSmithKline, Ono Pharmaceutical, Pierre Fabre, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEK Inhibitors Market Strategic Shifts
Next-generation MEK inhibitor development is unifying precision oncology workflows through deeper integration of real-world evidence platforms and adaptive trial designs that compress evidence generation cycles.
Allosteric MEK inhibitor engineering is unifying target selectivity with improved central nervous system penetration. Biopharmaceutical development teams at major cancer centers are adopting structure-based design platforms to optimize brain permeability. This convergence is unifying melanoma and lung cancer metastasis protocols under single-agent regimens that previously required radiation or surgical intervention.
The EU Green Deal's pharmaceutical sustainability criteria is restructuring procurement standards across European hospital networks. REACH chemical safety standards now mandate comprehensive lifecycle assessments for active pharmaceutical ingredients used in oncology manufacturing. Hospital pharmacy committees in Germany, France, and the Netherlands are rewriting tender specifications to prioritize suppliers with verified green chemistry certifications.
Academic medical centers are consolidating MEK inhibitor prescribing authority within specialized molecular tumor boards. Community oncology practices face credentialing barriers that restrict independent MEK-directed therapy initiation. This concentration is most visible in the United States, where major cancer centers and pharmaceutical R&D clusters dominate adoption patterns and influence regional referral networks.
MEK Inhibitors Market Segmentation
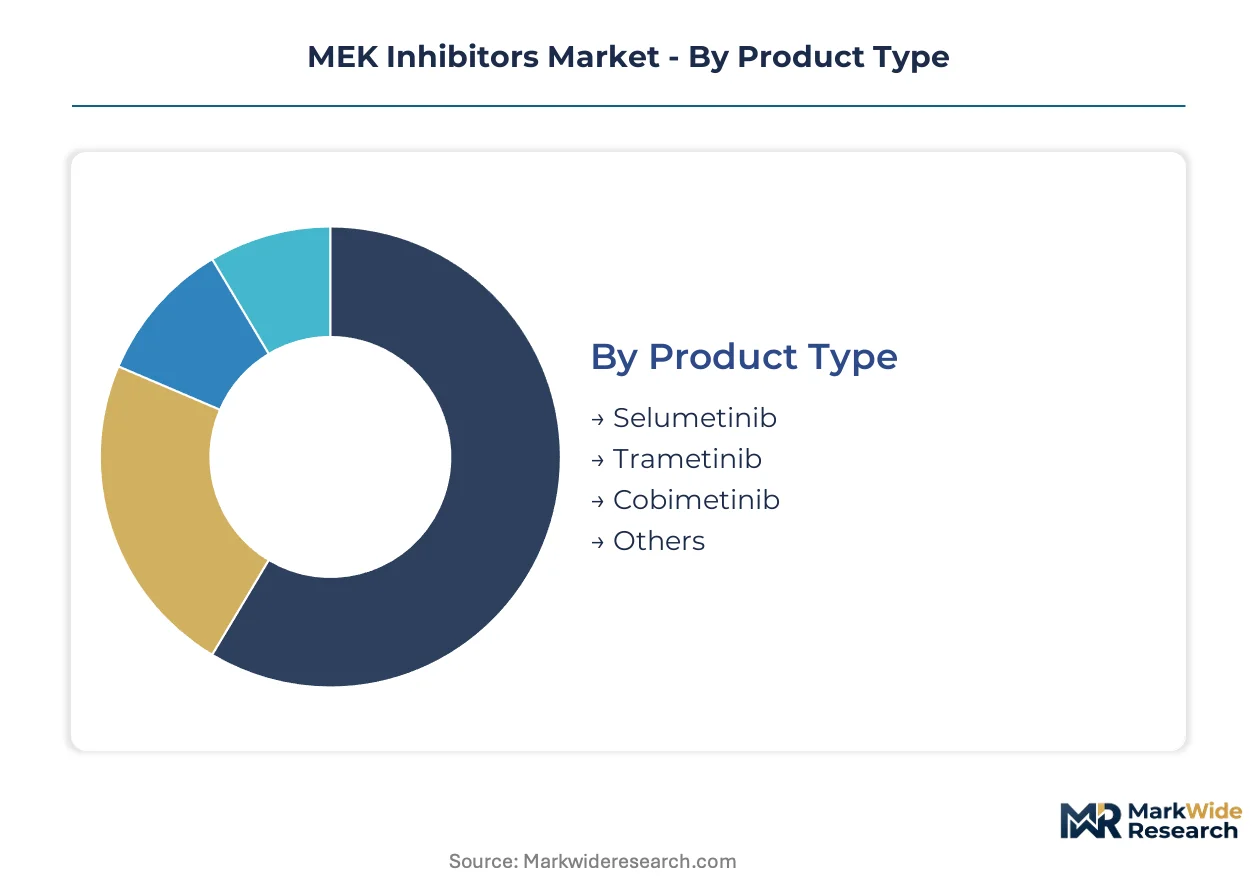
MEK inhibitor segmentation reveals distinct commercial pathways where formulation characteristics, clinical setting requirements, and patient population profiles determine prescribing authority and reimbursement positioning. Each dimension carries specific regulatory, logistical, and clinical implications that shape manufacturer resource allocation.
Product Type:
Selumetinib and trametinib anchor the revenue base through established pediatric and adult oncology indications, while cobimetinib and emerging candidates occupy differentiated combination therapy niches.
- Selumetinib:An allosteric MEK1/2 inhibitor approved for neurofibromatosis type 1 with inoperable plexiform neurofibromas. Pediatric oncology demand concentrates at academic medical centers in the United States where FDA breakthrough therapy designation accelerated access protocols.
- Trametinib:A reversible ATP-noncompetitive MEK1/2 inhibitor formulated for BRAF V600E/K-mutant melanoma and non-small cell lung cancer. Melanoma treatment protocols at major cancer centers in Germany and France drive volume, constrained by emerging MAPK pathway resistance mutations.
- Cobimetinib:Targets combination regimens with vemurafenib in unresectable or metastatic melanoma.
- Others:Investigational MEK inhibitors in Phase II/III trials for solid tumors and hematologic malignancies.
Volume placements concentrate in trametinib; the faster expansion belongs to selumetinib through pediatric indication expansion.
Application:
Oncology applications command the dominant revenue share through mutation-directed solid tumor protocols, while autoimmune and cardiovascular exploration represents pipeline optionality.
- Oncology:BRAF-mutant melanoma, NRAS-mutant melanoma, and non-small cell lung cancer constitute the core addressable population. Companion diagnostic integration at molecular tumor boards in the United States streamlines patient selection.
- Autoimmune Disorders:Preclinical and early-phase investigation explores MEK inhibition in rheumatoid arthritis and inflammatory bowel disease through modulation of immune cell signaling.
- Cardiovascular Diseases:Research-stage evaluation of MEK pathway modulation in cardiac remodeling and fibrosis.
- Others:Rare disease indications and exploratory neuroscience applications.
Prescription volume clusters in oncology; autoimmune disorder research programs are climbing the fastest as immunology divisions expand kinase inhibitor portfolios.
End User:
Hospital and oncology center concentration reflects the specialized infrastructure required for mutation testing, adverse event management, and combination therapy coordination.
- Hospitals:Inpatient administration of intravenous MEK inhibitors and management of severe adverse events including cardiomyopathy and retinal vein occlusion. Major cancer centers in the United States anchor demand through integrated molecular pathology services.
- Oncology Centers:Outpatient oral MEK inhibitor dispensing with structured monitoring protocols. Community practices in France and Germany face credentialing barriers that restrict independent prescribing authority.
- Research Laboratories:Preclinical investigation and biomarker discovery for resistance mechanism characterization.
- Clinics:Limited role restricted to stable patients on established maintenance regimens with remote monitoring support.
Patient volume concentrates in oncology centers; research laboratory procurement is expanding most quickly through pharmaceutical-sponsored investigator-initiated trials.
Administration Route:
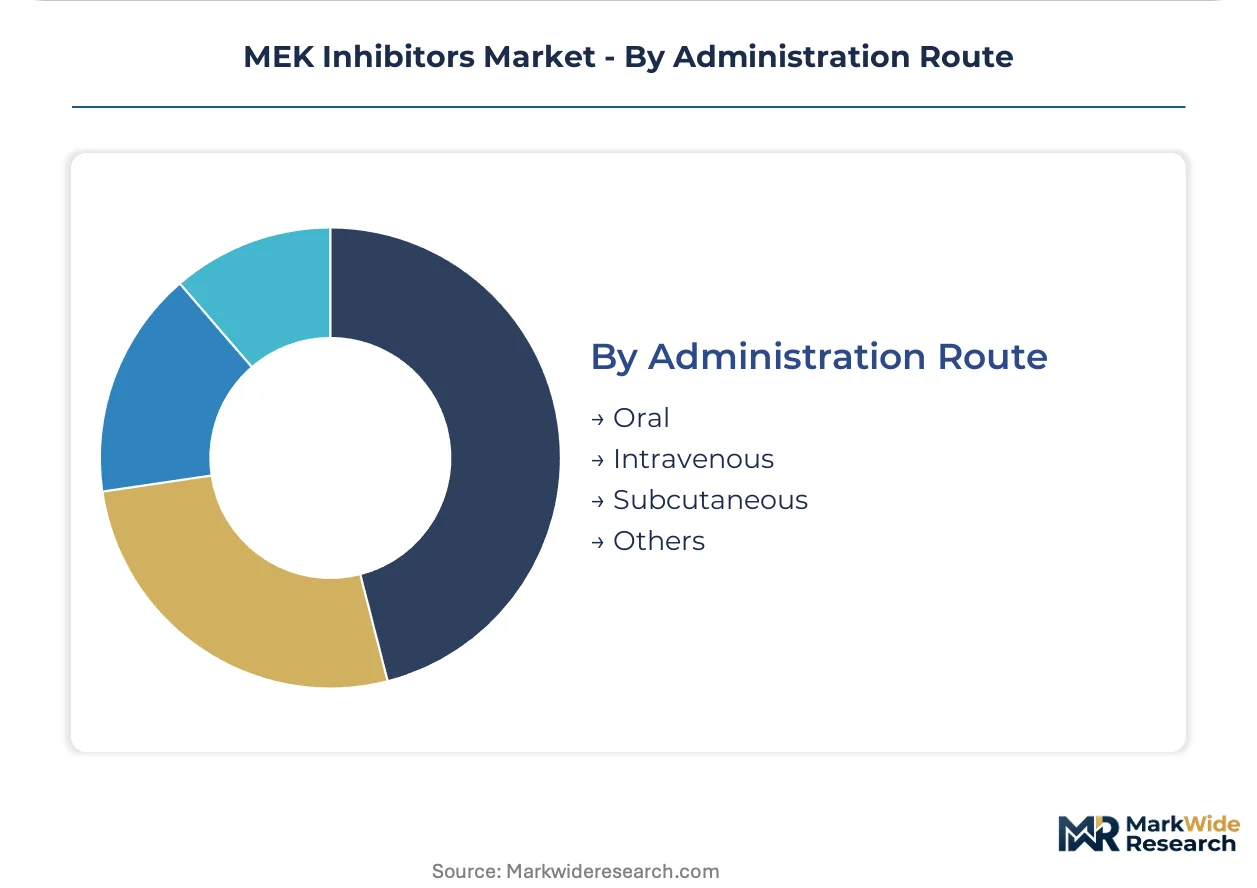
Route selection balances bioavailability requirements, patient convenience, and the need for dose intensity control in hospitalized settings.
- Oral:Tablet and capsule formulations enabling outpatient administration with defined fasting requirements. United States oncology practices favor oral routes for progression-free survival maintenance therapy.
- Intravenous:Hospital-based delivery for patients with compromised gastrointestinal absorption or requiring dose escalation protocols. German and Dutch hospital networks specify IV availability in oncology tender specifications.
- Subcutaneous:Investigational formulations targeting improved bioavailability and patient self-administration.
- Others:Transdermal patches and depot injections in early development.
Dispensing volume concentrates in oral administration; subcutaneous formulation development programs are gaining share fastest through patient preference studies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors the highest concentration of MEK inhibitor clinical trials and molecular tumor board infrastructure worldwide. Major cancer centers in this corridor coordinate combination therapy protocols that influence prescribing patterns across North America and Europe. Pharmaceutical R&D clusters in Basel, Cambridge, and Seoul replicate elements of this model through specialized oncology networks.
United States
Academic medical centers at Memorial Sloan Kettering and MD Anderson drive MEK inhibitor protocol development through integrated companion diagnostic programs. FDA breakthrough therapy designation accelerates pediatric oncology access for selumetinib at specialized children's hospitals. The Inflation Reduction Act's orphan drug carve-outs protect pricing for rare disease indications concentrated in Boston and Houston metropolitan treatment corridors.
Germany
University hospitals in Heidelberg and Munich anchor melanoma combination therapy adoption through structured molecular pathology referral networks. EMA priority medicines pathways compress reimbursement timelines for trametinib-cobimetinib regimens. The EU Green Deal's pharmaceutical sustainability criteria now mandates green chemistry certifications in tender specifications issued by hospital pharmacy committees across Baden-Württemberg and Bavaria.
France
Assistance Publique-Hôpitaux de Paris institutions concentrate MEK inhibitor prescribing authority within centralized molecular tumor boards. ANSM pharmacovigilance requirements shape post-market surveillance for cardiomyopathy and retinal vein occlusion signals. The Île-de-France region's hospital networks restrict community oncology practices from independent MEK-directed therapy initiation without academic center credentialing.
United Kingdom
The Royal Marsden and Christie Hospital anchor NHS England's specialized commissioning for BRAF-mutant melanoma protocols. NICE technology appraisals determine access thresholds for combination MEK-BRAF blockade in metastatic disease. Manchester's biomanufacturing corridor supplies active pharmaceutical ingredients under evolving ECHA REACH compliance frameworks that constrain formulation stability requirements.
Japan
PMDA sakigake designation accelerates MEK inhibitor development timelines for lung cancer indications at Tokyo and Osaka academic centers. Ono Pharmaceutical's domestic manufacturing base supplies combination regimens through hospital purchasing consortia concentrated in the Kanto region. METI's pharmaceutical industry revitalization program incentivizes local production of kinase inhibitors to reduce import dependency from Chinese API suppliers.
MEK Inhibitors Market Competitive Environment
The competitive structure tilts toward integrated oncology portfolio holders with diagnostic-companion testing capabilities. Large pharmaceutical conglomerates dominate through vertically organized research, manufacturing, and commercialization platforms. Three archetypes anchor positioning: diversified oncology majors with targeted therapy pipelines, diagnostic-linked precision medicine platforms, and regional specialists with niche indication focus. M&A activity concentrates on biomarker discovery assets, while strategic partnerships with molecular pathology laboratories secure patient selection workflows.
Among diversified oncology majors, Novartis, AstraZeneca, and Roche exemplify distinct strategic vectors. Novartis represents the integrated portfolio archetype spanning pediatric through adult indications. AstraZeneca occupies a position emphasizing combination therapy research depth. Roche anchors the diagnostic-companion linkage model that streamlines molecular tumor board decision-making. These three structures illustrate how competitive positioning in MEK-targeted therapy depends on upstream control over patient identification infrastructure rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Novartis |
| AstraZeneca |
| Roche |
| Pfizer |
| Merck & Co. |
| GlaxoSmithKline |
| Ono Pharmaceutical |
| Pierre Fabre |
| Bristol-Myers Squibb |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between GMP-validated API batches and standard chemical intermediates manifests in both procurement premiums and supplier qualification timelines. European hospital pharmacy committees now mandate REACH-compliant documentation chains, while United States oncology centers prioritize FDA-registered active pharmaceutical ingredient sources with validated stability data. This bifurcation concentrates pricing power among integrated manufacturers with captive quality-assurance infrastructure.
Pricing Analysis
Value-based pricing anchors on progression-free survival outcomes in BRAF-mutant melanoma protocols, with reimbursement tied to companion diagnostic-confirmed patient selection. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with academic medical centers negotiating lowest net prices through formulary commitment. Pricing pressure stems from biosimilar preparation timelines as trametinib approaches loss-of-exclusivity, compressing originator margins. Community oncology practices exhibit highest price sensitivity due to limited molecular pathology infrastructure, while specialized children's hospitals command premium access for selumetinib pediatric indications.
Supply Chain Analysis
Specialized chemical synthesis workforce availability in India and China anchors active pharmaceutical ingredient production for MEK inhibitor manufacturing. Key inputs draw from pyridine derivative precursors, palladium catalyst systems, and chiral separation resins sourced through validated vendor qualification programs. Single-source vulnerability concentrates in specific Asian supply hubs for advanced intermediates, exposing manufacturers to regulatory inspection delays. Distribution runs through pharmaceutical wholesale networks with cold-chain validation for temperature-sensitive formulations, supplemented by direct-to-hospital arrangements for academic medical center consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MEK inhibitors market operates as a vertical-integration race where control over companion diagnostic infrastructure determines patient access and pricing leverage. Manufacturers securing molecular pathology partnerships upstream capture downstream prescribing authority and formulary positioning.
For Market Incumbents: Hedge against biosimilar compression by deepening backward integration into diagnostic-companion testing platforms and securing pediatric exclusivity provisions within orphan drug frameworks. Resistance mutation surveillance capabilities represent a critical defensive moat as real-time circulating tumor DNA monitoring becomes standard of care. Capacity addition in Basel and Boston corridor manufacturing preserves supply security for breakthrough-designated assets.
For New Entrants and Emerging Players: Community oncology practices underserved by molecular tumor board infrastructure present the most penetrable entry point for MEK-directed therapy initiation support services. Blood-brain barrier penetrant formulation development addresses unmet central nervous system metastasis need with limited current competition. Go-to-market positioning through telemedicine-enabled remote monitoring protocols bypasses credentialing barriers restricting independent prescribing authority.
For Investors and Strategic Acquirers: Re-rating potential sits with biomarker discovery platforms given FDA breakthrough therapy designation acceleration and EMA priority medicines pathway compression. Long-term viability across the analysis window favors assets with demonstrated resistance mechanism characterization capabilities and adaptive trial design infrastructure. Acquisition target archetype: specialized molecular pathology laboratories with established hospital system partnerships. Signal to watch: real-world evidence platform adoption rates at major cancer centers as inflection indicator for combination therapy protocol influence.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Roche's diagnostic-linkage model streamlines molecular tumor board patient selection workflows. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses pediatric oncology access timelines for selumetinib. |
| Manufacturing Scale-Up | EU Green Deal sustainability criteria restructure European hospital network procurement specifications. |
| Pipeline Diversification | Brain metastasis indications address unmet need in melanoma central nervous system involvement. |
| Licensing Agreement | Dual BRAF-MEK blockade protocols improve progression-free survival metrics in combination regimens. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, supplemented by formulary database audits and hospital procurement records. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers validated quantitative assumptions. Bottom-up patient-volume modeling and top-down revenue reconciliation anchored segmentation estimates across the analysis window.
Bottom-up treatment-line and administration-route segmentation combined with top-down regional regulatory cluster aggregation. Dosage form, patient population, and companion diagnostic integration density shaped volume projections throughout the forecast period. CAGRs derived from historical approval velocity analysis and payer access timeline compression factors, with resistance mutation emergence rates and biosimilar entry assumptions as key sensitivity inputs.
Revisions become necessary when regulatory pathway delays, supply chain disruption at Asian API hubs, or resistance mutation profile shifts materialize outside modeled scenarios. Forecasts reflect documented assumptions regarding breakthrough therapy designation velocity and EMA priority medicines uptake curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Encapsulated Salicylic Acid Market
Pharmaceutical Ingredients
Pharmaceutical Chemicals Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Cox 2 Inhibitors Market
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
North America Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Medicinal Chemistry for Drug Discovery Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Sodium Chloride Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market