
 Celecoxib API Market | 2026-2036
Celecoxib API Market Size, Share, and Industry Trends Forecast 2026-2036
Celecoxib API Market Insights
REACH compliance in Europe is expanding the addressable market for high-purity Celecoxib API as EU-based pharmaceutical buyers enforce stricter impurity profiling on imported active ingredients. ScinoPharm leverages its Taiwan-based manufacturing complex to supply validated batches to European contract manufacturers. Hisun Pharmaceutical Nantong anchors its position through backward integration into key starting materials for sulfonamide-based synthesis. Pfizer sustains demand through captive consumption tied to its branded portfolio.
Celecoxib API is a selective cyclooxygenase-2 inhibitor synthesized through a multi-step organic route involving pyrazole ring formation and sulfonamide substitution, with final purity specifications typically exceeding 99.5% and stringent limits on genotoxic impurities per ICH M7 guidelines. The molecule serves as the active backbone for rheumatoid arthritis and acute pain therapies across oral solid dosage forms. Capsule-grade API commands the dominant volume share as the preferred delivery format for chronic administration in arthritis treatment. Injectable formulations represent the fastest-growing product type as hospital systems seek parenteral alternatives for post-surgical pain protocols where oral intake is contraindicated. Direct sales channels capture the largest margin pool by eliminating intermediary markups for high-volume pharmaceutical company procurement.
FDA enforces current Good Manufacturing Practice inspections on overseas API facilities, while China's NMPA mandates registration of drug master files for export-bound Celecoxib production. The European Medicines Agency requires nitrosamine risk assessments that reshape impurity control investments across supplier networks. Stakeholders must monitor evolving pharmacopoeial harmonization between USP, EP, and ChP monographs to preempt batch rejection risks at customs.
Market Dynamics
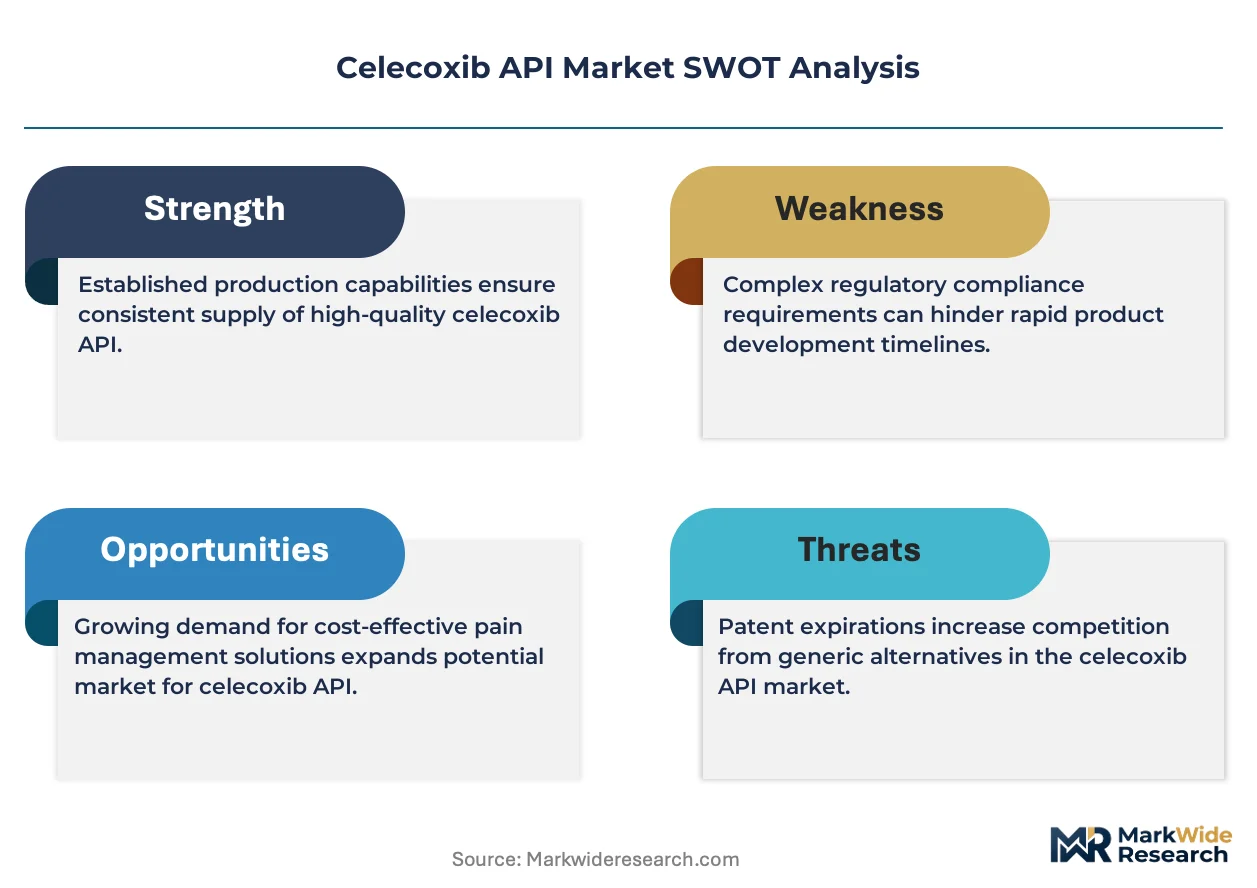
The Celecoxib API market faces intensifying regulatory scrutiny on genotoxic impurity limits, forcing manufacturers to reconfigure synthesis pathways and validation protocols. FDA and EMA alignment on ICH M7 guidelines is compressing batch approval timelines while raising capital requirements for compliance infrastructure.
Growth Catalysts
- Hospital parenteral protocols:Post-surgical pain management programs in tertiary care centers are expanding demand for injectable-grade Celecoxib API as oral administration becomes contraindicated for certain patient cohorts.
- REACH compliance expansion:European pharmaceutical buyers are enforcing stricter impurity profiling on imported active ingredients, widening the addressable market for validated high-purity suppliers.
- China export scaling:Domestic manufacturers are increasing selective COX-2 inhibitor output to serve contract manufacturing organizations across multiple continents.
Market Restraints
- Key starting material concentration:Backward integration into sulfonamide-based synthesis precursors remains limited to a handful of specialized chemical producers, creating supply bottlenecks.
- Nitrosamine assessment costs:EMA-mandated risk evaluations require substantial analytical investment without guaranteed batch clearance, elevating working capital intensity.
- Biologic pain therapy substitution:Monoclonal antibody treatments for rheumatoid arthritis are capturing patient share in reimbursed markets, pressuring long-term small-molecule API volume assumptions.
Strategic Opportunities
- United States purity premium:FDA tightening of non-steroidal anti-inflammatory drug ingredient standards creates first-mover advantage for suppliers with pre-validated impurity control systems.
- Continuous flow chemistry adoption:Integration of flow reactor technology with traditional batch sulfonamide substitution promises yield improvements and reduced solvent waste profiles.
- Direct channel penetration:High-volume pharmaceutical companies are eliminating intermediary markups through captive procurement relationships, capturing margin pool redistribution.
Industry Challenges
- Analytical chemist scarcity:Genotoxic impurity method development and validation require specialized chromatography expertise that outpaces current training pipeline output.
- Pharmacopoeial harmonization lag:Divergent USP, EP, and ChP monograph specifications create batch rejection risks at customs checkpoints, demanding redundant documentation preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Celecoxib API Market |
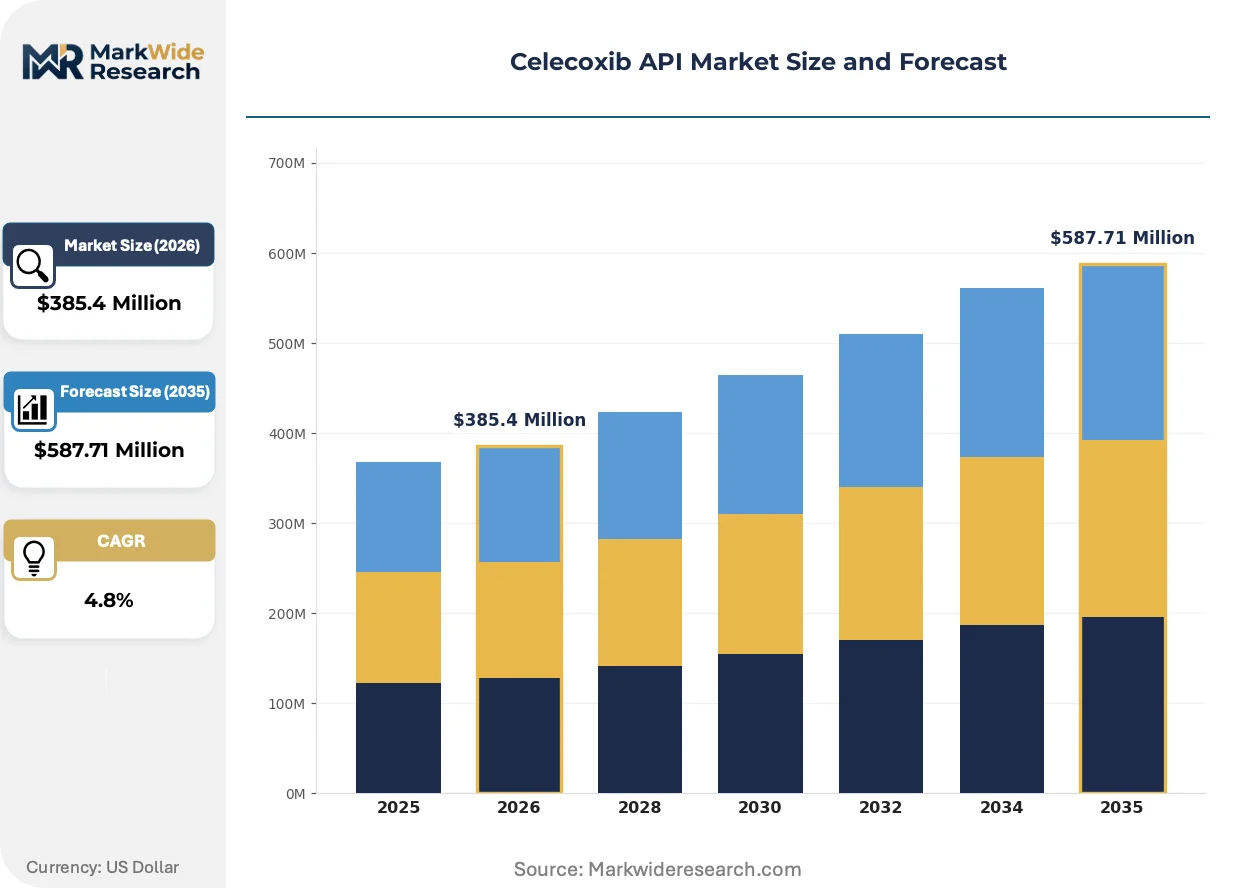
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Injectable, Liquid End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Clinics Application: Arthritis Treatment, Pain Management, Cardiovascular Therapy, Inflammation Reduction Distribution Channel: Direct Sales, Wholesale, Online, Retail Pharmacy |
| Companies Covered | ScinoPharm, Jiangsu Hengrui Medicine, Pfizer, Hisun Pharmaceutical Nantong, Jiangsu Chiatai Qingjiang, Teva Pharmaceuticals, Jiangxi Synergy, Aurobindo Pharma, Viatris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Celecoxib API Market Trends and Innovations
Continuous manufacturing technologies are reshaping Celecoxib API production economics while regulatory convergence on impurity standards compresses competitive differentiation windows. Quality-by-design principles are migrating from guideline aspiration to contractual procurement requirement.
Flow chemistry reactor systems are overtaking traditional batch sulfonamide substitution for pyrazole ring closure steps. Mid-scale API manufacturers in Taiwan and India are piloting these platforms to reduce solvent consumption and improve heat transfer control. The technology is overtaking conventional vessel-based production by enabling real-time process analytical technology integration that satisfies FDA quality metrics.
EMA nitrosamine risk assessment mandates are forcing retrospective evaluation of all approved synthesis pathways. Contract manufacturers must now submit comprehensive impurity fate mapping before batch release. Hospital-system buyers in Germany and France are prioritizing suppliers with completed assessment documentation, shifting procurement preference toward established European contract manufacturing organizations.
Long-term offtake agreements are replacing spot market purchasing for capsule-grade API volumes. Large pharmaceutical companies are consolidating supplier rosters to three validated partners per geography, eliminating smaller traders from qualified vendor lists. This concentration is most visible in United States procurement patterns, where direct sales channels now capture procurement decisions previously routed through distribution intermediaries.
Celecoxib API Market Segmentation
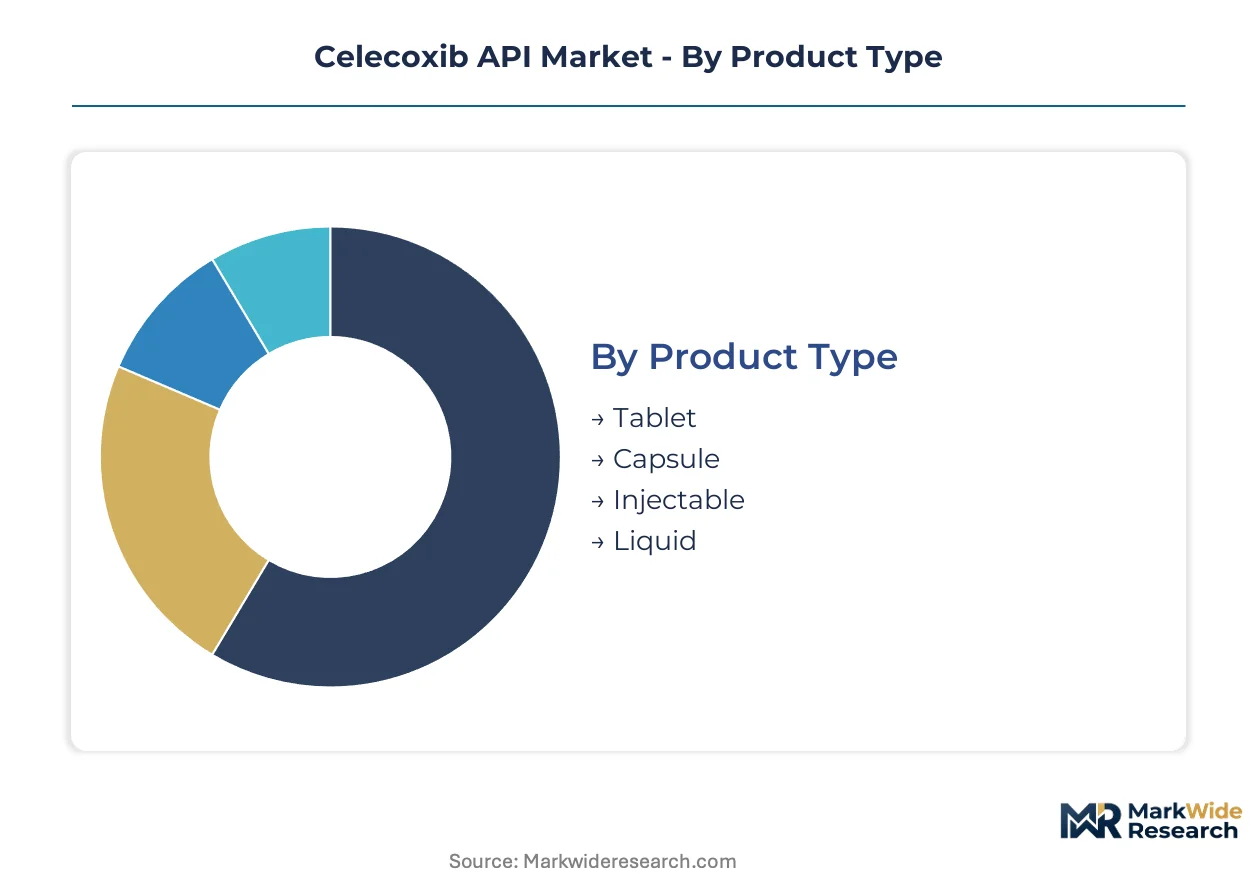
Celecoxib API procurement patterns diver sharply across dosage forms and customer types, with regulatory compliance requirements and administration protocols dictating specification tiers. Pharmaceutical buyers segment suppliers by impurity profiling capabilities and validation documentation depth rather than commodity pricing alone.
Product Type:
Reformulation cycles for oral NSAIDs are shortening as hospital systems demand parenteral alternatives, pushing API manufacturers to validate multiple specification grades simultaneously.
- Capsule:Oral solid dosage forms dominate chronic arthritis therapy prescriptions, requiring excipient-compatible API with particle size distribution optimized for hard-shell gelatin filling. United States pharmaceutical companies procure this grade in the largest volumes for outpatient rheumatoid arthritis protocols.
- Injectable:Sterile-grade API with endotoxin limits below 0.25 EU/mg and particulate matter controls serves post-surgical pain management where oral intake is contraindicated. Tertiary care centers in Germany and France are expanding parenteral formularies fastest.
- Tablet:Compressible granules with specified bulk density for direct compression or wet granulation processes serve cost-sensitive generic markets.
- Liquid:Solubilized or suspension-grade API with taste-masking compatibility addresses pediatric and geriatric patient cohorts with swallowing difficulties.
Capsule sits at the top of the volume ranking, with Injectable climbing the fastest.
End User:
Procurement sophistication varies dramatically across buyer types, with direct pharmaceutical company relationships commanding premium pricing for validated supply security.
- Pharmaceutical Companies:Integrated drug manufacturers with captive formulation capabilities purchase API under long-term offtake agreements with audit rights over supplier facilities. FDA pre-approval inspection records and completed EMA nitrosamine risk assessments are mandatory qualification criteria.
- Contract Manufacturers:CDMOs serving multiple sponsor clients require flexible batch sizing and rapid regulatory documentation turnaround to support abbreviated new drug application filings. Taiwan-based ScinoPharm and similar specialists anchor supply to this segment.
- Research Institutions:Academic and clinical trial material suppliers purchase gram-to-kilogram scale quantities with emphasis on certificate of analysis completeness over price.
- Clinics:Hospital pharmacy compounders source API for extemporaneous preparation of specialized dosage forms for individual patient needs.
Pharmaceutical Companies anchor procurement volume, with Contract Manufacturers expanding their share most aggressively.
Application:
Clinical indication drives API specification stringency, with cardiovascular safety profiling requirements elevating impurity control investments for certain therapeutic areas.
- Arthritis Treatment:Chronic administration of Celecoxib for rheumatoid arthritis and osteoarthritis demands API stability data across 24-month shelf-life projections with photostability validation. United States Medicare reimbursement patterns concentrate demand for this indication.
- Pain Management:Acute post-operative and trauma pain protocols utilize higher-strength formulations with rapid dissolution specifications. Hospital formularies in China are expanding parenteral pain management options fastest.
- Cardiovascular Therapy:Specialized indications with thrombotic event monitoring requirements impose additional genotoxic impurity scrutiny beyond standard ICH M7 thresholds.
- Inflammation Reduction:Off-label and emerging indications for inflammatory conditions drive exploratory API purchases with accelerated stability testing protocols.
Arthritis Treatment commands the largest API volume, with Pain Management applications gaining share most rapidly.
Distribution Channel:
Channel selection determines margin capture and regulatory liability allocation, with direct relationships displacing intermediary-dependent procurement.
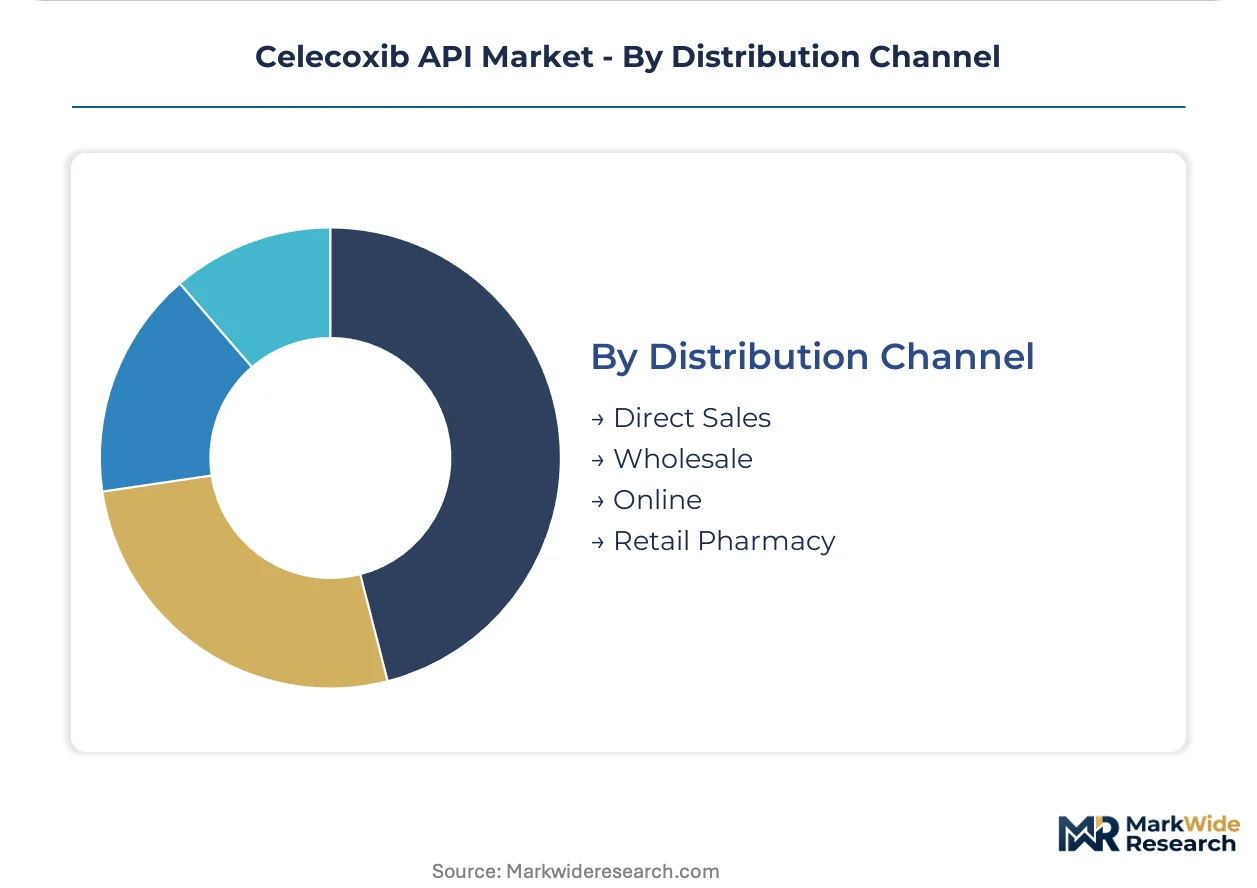
- Direct Sales:Manufacturer-to-pharmaceutical company relationships eliminate distributor markups and enable customized specification negotiation. FDA-registered facilities with completed pre-approval inspections command preferred supplier status.
- Wholesale:Regional chemical distributors serve mid-volume buyers with standard USP-grade material and consolidated logistics.
- Online:Digital procurement platforms facilitate spot purchasing for research quantities and comparator drug sourcing.
- Retail Pharmacy:Compounding pharmacy suppliers access API through specialized distributors with patient-specific batch documentation.
Direct Sales captures the dominant procurement value, with Wholesale retaining volume leadership in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized analytical chemists and quality control specialists cluster in pharmaceutical manufacturing hubs across the United States, Germany, China, India, and Taiwan, anchoring regional supply capabilities for high-purity Celecoxib API production.
United States
FDA pre-approval inspection records and completed nitrosamine risk assessments serve as mandatory qualification criteria for pharmaceutical company procurement. The agency's tightening of non-steroidal anti-inflammatory drug ingredient standards creates first-mover advantage for suppliers with validated impurity control systems. New Jersey and Massachusetts pharmaceutical corridors concentrate formulation expertise and direct sales channel relationships.
Germany
Hospital-system buyers in tertiary care centers expand parenteral pain management formularies fastest across Europe. EMA nitrosamine risk assessment mandates reshape impurity control investments across supplier networks. The Rhine-Main and Bavarian chemical clusters host contract manufacturing organizations prioritizing suppliers with completed assessment documentation.
China
Domestic manufacturers scale selective COX-2 inhibitor output for export markets to contract manufacturing organizations across multiple continents. NMPA mandates registration of drug master files for export-bound Celecoxib production. The Yangtze River Delta and Shandong Peninsula concentrate sulfonamide-based synthesis capacity and backward integration into key starting materials.
India
CDMOs serving multiple sponsor clients require flexible batch sizing and rapid regulatory documentation turnaround for abbreviated new drug application filings. CDSCO enforces pharmacopoeial harmonization alignment with USP and EP monographs to preempt batch rejection risks. Hyderabad and Ahmedabad pharmaceutical zones anchor generic API export capacity with emphasis on cost-sensitive tablet-grade production.
Taiwan
Mid-scale API manufacturers pilot continuous flow chemistry platforms to reduce solvent consumption and improve heat transfer control. The national pharmaceutical regulator aligns with FDA quality metrics for real-time process analytical technology integration. Taichung and Hsinchu science parks concentrate validated batch supply to European contract manufacturers.
Celecoxib API Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Celecoxib API market, creating a tiered structure where integrated pharmaceutical companies maintain captive consumption while specialized API manufacturers serve external formulation clients. The vendor base separates into three strategic archetypes: multinational innovators with branded portfolios, Asian contract manufacturers with scale advantages, and regional specialists with regulatory validation depth. Consolidation pressures favor long-term offtake agreements over spot market purchasing, while direct sales channel penetration eliminates intermediary markups for high-volume procurement.
Among Taiwan-based specialists, ScinoPharm occupies a position exemplifying validated batch supply to European contract manufacturers. Chinese manufacturers Hisun Pharmaceutical Nantong and Jiangsu Hengrui Medicine represent the scale-driven archetype with backward integration into sulfonamide-based synthesis precursors. Pfizer anchors the integrated pharmaceutical company tier through captive consumption tied to branded portfolio demand.
| Leading Market Players |
|---|
| ScinoPharm |
| Jiangsu Hengrui Medicine |
| Pfizer |
| Hisun Pharmaceutical Nantong |
| Jiangsu Chiatai Qingjiang |
| Teva Pharmaceuticals |
| Jiangxi Synergy |
| Aurobindo Pharma |
| Viatris |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements from United States pharmaceutical companies are displacing spot market purchasing, forcing API manufacturers to absorb upfront validation costs and compress margins on standard-grade material while capturing premiums on pre-certified batches. This procurement consolidation is reshaping how suppliers allocate working capital across inventory buffers and analytical infrastructure investments.
Pricing Analysis
Unbundled impurity profiling services now command separate fees from base API transactions, creating a two-tier pricing structure where validated documentation carries standalone value. Price differentiation hinges on ICH M7 compliance depth and FDA pre-approval inspection status, with contract manufacturers in Taiwan and India extracting premiums for completed nitrosamine risk assessments. Cost compression in standard-grade capsule API is intensifying because Chinese manufacturers are scaling export volumes aggressively. Research institutions exhibit the lowest price sensitivity due to certificate-of-analysis requirements, while generic tablet formulators in India remain most responsive to unit cost fluctuations.
Supply Chain Analysis
FDA and EMA qualification gates are concentrating supply relationships among facilities with completed drug master file registrations, effectively filtering out unvalidated producers. Manufacturing capacity clusters in China, India, and Taiwan feed downstream formulation networks across North America and Europe. Pyrazole ring precursors and sulfonamide-based starting materials draw from specialized chemical producers concentrated in Shandong and Jiangsu provinces. Single-source vulnerability persists for genotoxic impurity testing services, where qualified analytical laboratories face capacity constraints. Distribution runs through direct manufacturer-to-pharmaceutical company channels for high-volume procurement, with regional distributors serving research and compounding segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Celecoxib API hinges on manufacturers capturing value from regulatory compliance investments rather than commoditized volume, with continuous flow chemistry adoption offering a structural cost-down pathway for mid-scale producers.
For Market Incumbents: Cement supplier roster consolidation gains by completing EMA nitrosamine risk assessments ahead of competitor filings, locking in preferred status with German and French hospital-system buyers. Expand Taichung and Hsinchu science park capacity to serve European CDMO demand, defending against biologic pain therapy substitution by emphasizing parenteral formulation partnerships with tertiary care centers. Backward integration into sulfonamide-based synthesis precursors remains the critical lever for margin defense. For New Entrants and Emerging Players: REACH compliance expansion in Europe opens a window for validated high-purity suppliers to capture share from traders lacking completed impurity fate mapping documentation. Target injectable-grade API supply to post-surgical pain management programs in Chinese hospital formularies, where parenteral protocol adoption is outpacing validated supplier availability. Lead with real-time process analytical technology integration as a quality differentiation angle against established batch producers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale API manufacturers piloting continuous flow chemistry platforms, where technology validation creates acquisition premiums ahead of broader industry adoption. Position holdings for a five-to-ten year window where regulatory convergence on ICH M7 guidelines consolidates procurement around pre-validated supplier networks. Monitor EMA nitrosamine assessment completion rates as the inflection signal for which facilities will secure long-term offtake agreements versus face qualification exclusion.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Adoption | Taichung manufacturers reduce solvent waste while satisfying FDA quality metrics for real-time process control. |
| Backward Integration into Sulfonamide Precursors | Shandong-based producers anchor supply security by controlling pyrazole ring formation starting materials. |
| EMA Nitrosamine Risk Assessment Completion | German hospital-system buyers prioritize suppliers with documented impurity fate mapping for batch release. |
| Direct Sales Channel Penetration | New Jersey pharmaceutical corridors eliminate distributor markups through captive procurement relationships. |
| Injectable-Grade API Validation | Tertiary care centers in France expand parenteral formularies fastest, creating demand for sterile-grade supply. |
Research Methodology
Direct dialogue with regulatory affairs leads at API manufacturers, hospital procurement managers in German tertiary care centers, formulary directors at United States Medicare plans, and analytical chemistry heads at contract manufacturing organizations grounded qualitative findings. Secondary validation drew from FDA drug master file registrations, EMA nitrosamine assessment submissions, USP monograph revision notices, and customs trade data for selective COX-2 inhibitor shipments. Bottom-up volume estimates triangulated against top-down pharmaceutical company procurement disclosures.
Bottom-up modeling segmented demand across capsule, injectable, tablet, and liquid dosage forms, with separate treatment of arthritis, pain management, cardiovascular, and inflammation reduction applications. Geographic regulatory clusters captured FDA, EMA, NMPA, and CDSCO compliance tiers as distinct supply qualification layers. CAGRs derived from regression analysis of historical API shipment volumes against formulation pipeline disclosures and hospital formulary expansion patterns. Forecast inputs included parenteral protocol adoption rates in Chinese hospital systems and continuous manufacturing technology penetration curves across Taiwan and India facilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt pharmacopoeial harmonization failures or sudden biologic substitution acceleration in reimbursed rheumatoid arthritis markets. A model refresh is warranted upon material change in FDA inspection backlog duration or EMA nitrosamine assessment mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Sodium Chloride Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Heparin Sodium API Market
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Silica Gel Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Epcam Antagonists Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Pemetrexed Market