
 Active Ingredients Market | 2026-2036
Active Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Active Ingredients Market Analysis
The divergence between premium biologic active ingredients and commodity small-molecule APIs is shifting procurement patterns across pharmaceutical supply chains. Sun Pharmaceutical Industries Ltd anchors its position through backward integration into fermentation capacity. Pfizer Inc differentiates via monoclonal antibody platforms. Lonza Group dominates cell-culture manufacturing for complex biologics.
Active ingredients constitute the pharmacologically active components of pharmaceutical, agrochemical, and personal care formulations, typically requiring purity thresholds above 99.5% and defined stereochemical configurations for therapeutic efficacy. Their primary purpose is to deliver measurable biological or chemical effects in finished dosage forms or crop protection products. The end user segmentation reveals agricultural producers and crop protection companies as the dominant demand pool, while formulation type shows liquid preparations capturing margin concentration due to higher barrier-to-entry manufacturing requirements. Application method segmentation indicates soil treatment protocols expanding fastest in precision agriculture adoption.
FDA, EMA, and ICH Q7 guidelines collectively govern active ingredient manufacturing standards, with FDA inspections driving facility upgrades and EMA variations procedures dictating formulation change protocols. These frameworks elevate compliance costs but simultaneously filter subscale competitors from contract manufacturing qualification lists. Stakeholders must monitor evolving biosimilar guidance convergence between FDA and EMA to anticipate portfolio reallocation requirements.
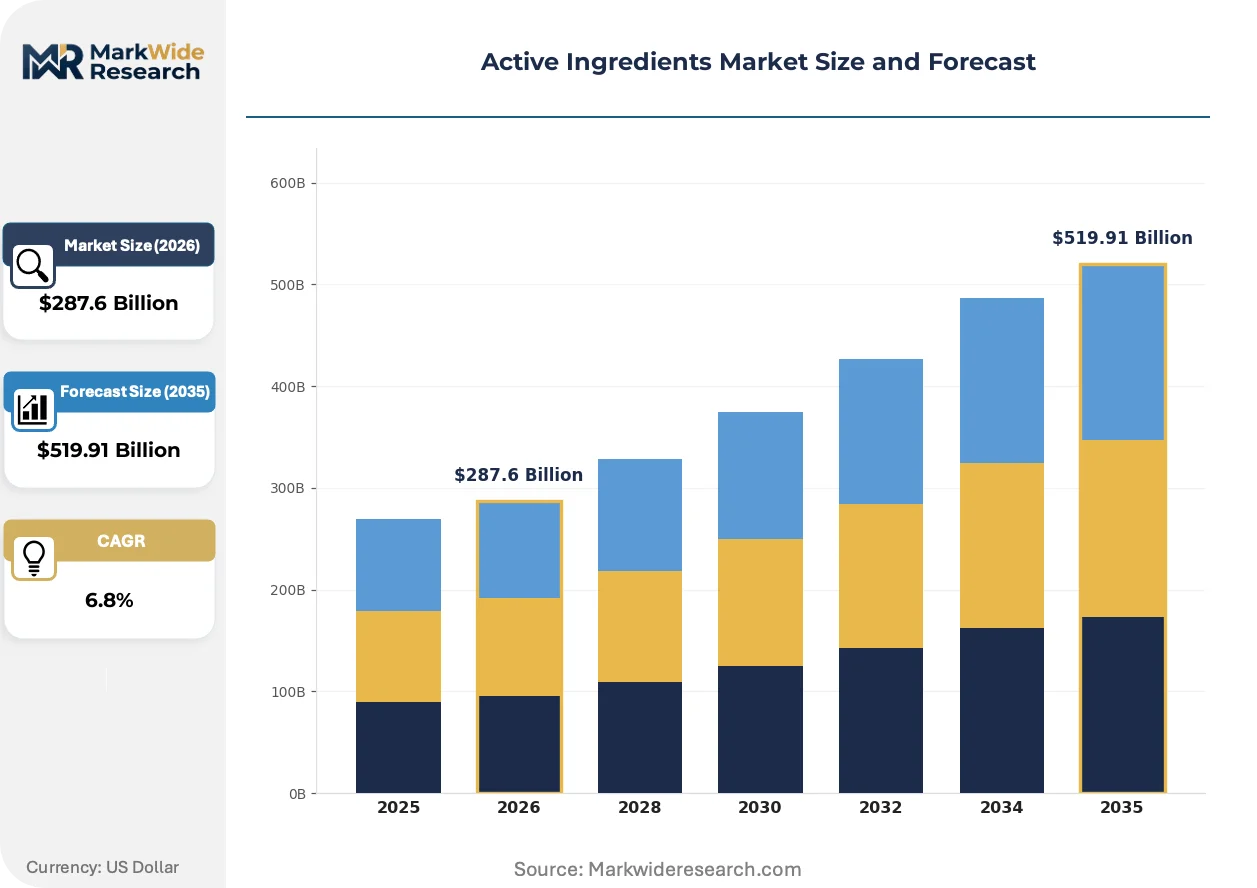
Market Dynamics
Pharmaceutical supply chains are bifurcating between fermentation-derived biologics and synthetic small-molecule APIs as purity thresholds tighten under evolving regulatory frameworks. This structural divergence is compressing margins for commodity chemical manufacturers while rewarding captive fermentation capacity.
Growth Catalysts
- EU REACH impurity thresholds:Imported APIs face tightened contamination limits, forcing contract manufacturers toward high-purity fermentation processes that command premium positioning.
- India's CRO fermentation scale-up:Contract research organizations in Hyderabad and Bangalore are expanding stainless-steel bioreactor capacity to capture biologic active ingredient demand.
- Monoclonal antibody platforms:Cell-culture manufacturing for complex biologics is displacing chemical synthesis in oncology and autoimmune therapeutic categories.
Market Restraints
- Specialized fermentation feedstock volatility:Yeast extract and soy peptone prices fluctuate with agricultural commodity cycles, compressing margin predictability for biologic API producers.
- Single-source chromatography resin supply:Protein A and ion-exchange media concentrate among three global suppliers, creating bottleneck risk for downstream purification.
- Stereochemical synthesis limitations:Chiral small-molecule APIs face yield ceilings in asymmetric catalysis that enzymatic routes have not yet cost-effectively displaced.
Strategic Opportunities
- Brazil ANVISA biosimilar pathway:Emerging regulatory clarity for follow-on biologics creates first-mover advantage for fermentation-based API suppliers establishing local technical dossier capabilities.
- Continuous manufacturing convergence:Integration of flow chemistry with real-time release testing enables smaller-footprint facilities in high-cost geographies.
- Direct-to-formulator digital channels:API marketplaces bypassing traditional distributor networks are capturing early traction among mid-tier generic pharmaceutical manufacturers.
Industry Challenges
- Bioprocess engineer scarcity:Fermentation scale-up expertise concentrates among professionals with decade-plus experience, constraining capacity expansion timelines.
- Multi-product facility validation:Campaign changeover protocols for shared bioreactor trains extend downtime and complicate regulatory filing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Ingredients Market |
| Market Size in 2026 | $287.6 Billion |
| Market Size in 2035 | $519.91 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Plant Growth Regulators End User: Agricultural Producers, Crop Protection Companies, Food Manufacturers, Research Institutions Formulation Type: Liquid, Granule, Powder, Suspension Application Method: Broadcast, Foliar, Soil Treatment, Seed Treatment |
| Companies Covered | Sun Pharmaceutical Industries Ltd, Pfizer Inc, AbbVie Inc, Boehringer Ingelheim International GmbH, Merck KGaA, Aurobindo Pharma Limited, Dr. Reddy’s Laboratories Ltd, Lonza Group, Teva Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Ingredients Market Emerging Trajectories
Continuous processing technologies and real-time analytics are displacing batch manufacturing paradigms across active ingredient production. These shifts compress cycle times while elevating quality assurance burdens.
Single-use bioreactor systems are expanding into commercial-scale manufacturing from their upstream development origins. Biopharmaceutical contract manufacturers in Switzerland and Singapore are adopting disposable stirred-tank configurations for Phase III and launch supply. This technology is expanding into multi-product facilities where stainless-steel changeover validation costs previously prohibited product mix flexibility.
EMA's ICH Q14 guideline implementation is compressing analytical method development timelines for post-approval change management. Drug substance manufacturers must now demonstrate enhanced understanding of design space boundaries prior to regulatory submission. API suppliers serving European markets are responding by embedding quality-by-design principles earlier in process characterization protocols.
Formulator procurement teams are consolidating qualified supplier lists around dual-sourced fermentation capacity with documented viral clearance validation. Large generic pharmaceutical manufacturers in Germany and the United States are disqualifying single-source API relationships regardless of cost position. This concentration behavior is most visible in oncology injectable categories where supply continuity carries highest patient risk weighting.
Active Ingredients Market Segmentation
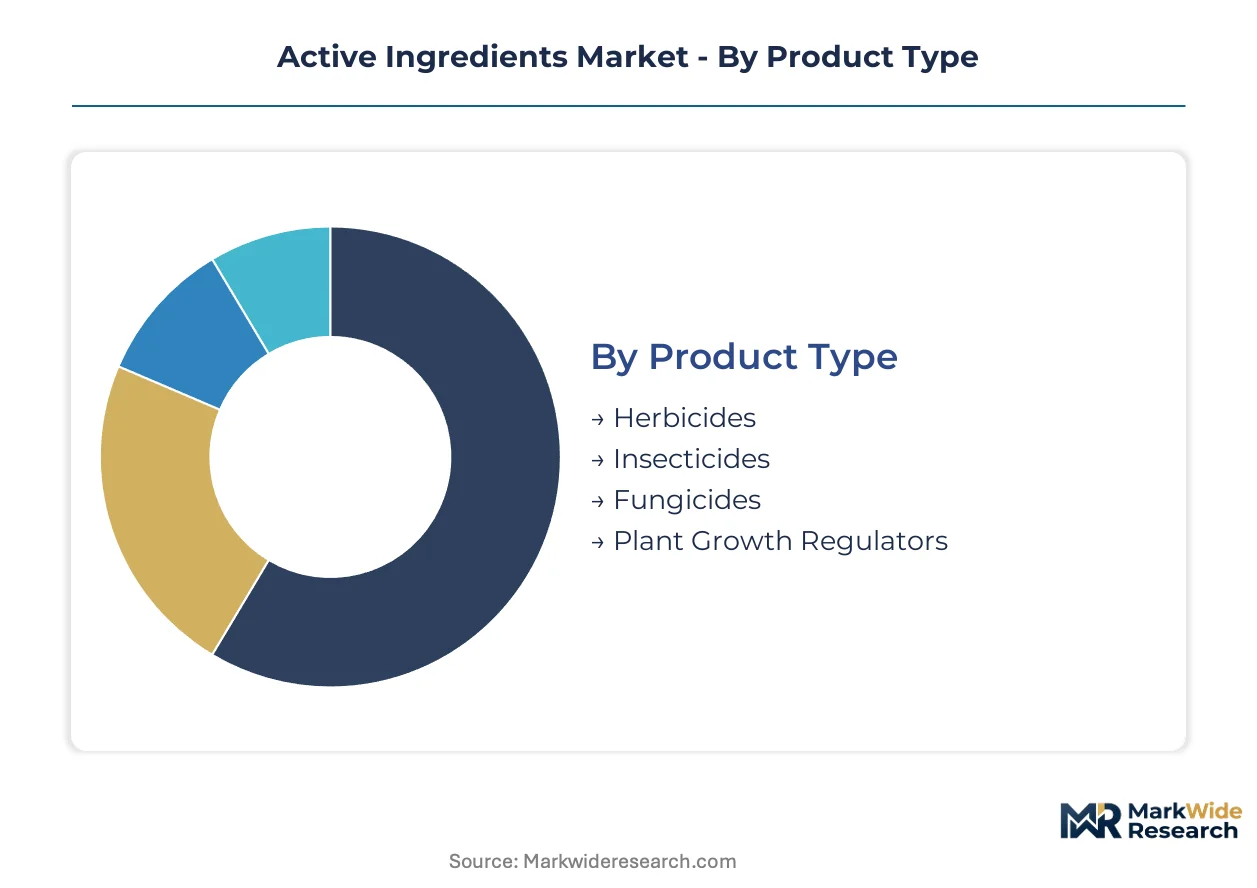
Active ingredient procurement decisions hinge on compatibility between chemical properties and downstream formulation requirements. Each segmentation dimension reveals distinct margin structures and regulatory exposure profiles that shape supplier selection criteria across pharmaceutical and agrochemical value chains.
Product Type:
Cost tier determines formulation complexity and manufacturing capital intensity across agrochemical active ingredient categories.
- Herbicides:Glyphosate and glufosinate-ammonium formulations dominate volume production, requiring high-purity synthesis routes that concentrate manufacturing in India and China. Agricultural producers in Brazil and Argentina drive demand for broad-spectrum weed control actives resistant to supply chain disruptions.
- Insecticides:Neonicotinoid and pyrethroid actives face tightening residue thresholds under EU REACH and US EPA re-registration reviews. Crop protection companies are reformulating around biological alternatives as regulatory pressure intensifies on synthetic chemistries.
- Fungicides:Azole and strobilurin classes anchor disease resistance management programs.
- Plant Growth Regulators:Gibberellin and cytokinin-based actives command premium positioning in specialty crop applications.
Herbicides lead on scale; insecticides lead on momentum.
End User:
Application maturity separates price-sensitive commodity buyers from specification-driven premium purchasers.
- Agricultural Producers:Direct procurement of generic actives concentrates in large-scale farming operations across Iowa, Mato Grosso, and Punjab. These buyers prioritize cost-per-hectare efficiency over brand recognition, driving volume consolidation around multi-source API suppliers.
- Crop Protection Companies:Syngenta Group and Bayer AG maintain captive synthesis capacity for proprietary actives while outsourcing commodity intermediates. Their formulation expertise creates entry barriers for standalone API suppliers lacking downstream integration.
- Food Manufacturers:Residue compliance requirements under FDA and EFSA specifications dictate supplier qualification protocols.
- Research Institutions:Small-batch procurement of novel actives for field trial programs.
Crop protection companies lead on scale; agricultural producers lead on momentum.
Formulation Type:
Manufacturing barrier height correlates directly with margin retention and customer switching costs.
- Liquid:Emulsifiable concentrate and suspension concentrate formats require solvent handling infrastructure and stability testing protocols that filter subscale competitors. Formulators in Germany and Japan prefer liquid actives for precision application equipment compatibility.
- Granule:Controlled-release matrix technologies concentrate among Japanese and Swiss specialty manufacturers.
- Powder:Wettable powder formulations face dust exposure regulations under OSHA and REACH worker protection frameworks.
- Suspension:Nano-sizing capabilities for improved bioavailability are gaining share fastest in high-value horticultural segments.
Liquid formulations lead on scale; suspension formats lead on momentum.
Application Method:
Precision agriculture adoption intensity determines active ingredient specification requirements and service bundling opportunities.
- Soil Treatment:Systemic actives with root uptake mechanisms require extended residual activity profiles that concentrate R&D investment among companies with field trial infrastructure in Australia and Canada. These products command premium positioning in no-till farming systems.
- Foliar:Rapid translocation properties and rainfastness specifications drive formulation innovation. Brazilian soybean producers and Vietnamese rice growers prioritize foliar actives compatible with drone application systems expanding across Southeast Asia.
- Broadcast:Volume-driven commodity application methods concentrate procurement around cost-optimized suppliers.
- Seed Treatment:Micro-dose precision requirements favor high-potency actives with low phytotoxicity thresholds.
Broadcast application leads on scale; soil treatment leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioprocess engineering talent concentrates in Basel, Boston, and Bangalore, anchoring three distinct production ecosystems for fermentation-derived actives. These clusters attract contract manufacturers seeking viral clearance validation expertise. Workforce mobility between pharma and agrochemical sectors tightens labor markets in each hub.
United States
Oncology injectable demand and biosimilar portfolio expansion drive fermentation capacity investment. FDA inspections enforce ICH Q7 compliance upgrades across Puerto Rican and mainland facilities. Greater Boston anchors cell-culture manufacturing expansion as monoclonal antibody platforms displace chemical synthesis in autoimmune therapeutic categories.
Germany
Generic pharmaceutical procurement consolidation and precision agriculture adoption reshape active ingredient specifications. EMA variations procedures dictate formulation change protocols for EU market access. Ludwigshafen and Leverkusen concentrate agrochemical active synthesis capacity as crop protection companies backward-integrate into key intermediates.
India
Contract research organization scale-up and fermentation-based production expansion capture biologic API demand. CDSCO filing requirements tighten documentation standards for export-oriented manufacturers. Hyderabad and Bangalore stainless-steel bioreactor clusters rival Swiss capacity for mammalian cell-culture contract manufacturing.
Switzerland
High-potency active handling capabilities and continuous processing technology adoption sustain premium positioning. Swissmedic guidance convergence with EMA biosimilar pathways streamlines multi-jurisdiction filings. Basel anchors global cell-culture manufacturing for complex biologics as Lonza Group and specialized competitors expand disposable bioreactor deployment.
Brazil
Soybean and sugarcane producer demand for broad-spectrum weed control actives resists supply chain disruption risks. ANVISA biosimilar pathway clarity creates first-mover positioning for fermentation-based API suppliers establishing local technical dossier capabilities. São Paulo state formulation specialists integrate backward into generic active ingredient procurement to bypass import dependency.
Active Ingredients Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across bifurcated supply chains for fermentation-derived biologics versus synthetic small-molecule APIs. The vendor base stratifies into three tiers: integrated innovators with captive fermentation capacity, specialist contract manufacturers with viral clearance validation, and commodity chemical suppliers facing margin compression from purity threshold tightening. Tier-one players defend position through backward integration into bioreactor capacity and chromatography resin supply security. Tier-two competitors capture share via multi-product facility flexibility and regulatory filing expertise.
Within the integrated innovator tier, Sun Pharmaceutical Industries Ltd and Pfizer Inc exemplify divergent strategic postures toward captive fermentation investment. Lonza Group anchors the specialist contract manufacturing segment through cell-culture platform dominance. Among Indian-origin generic suppliers, Aurobindo Pharma Limited and Dr. Reddy's Laboratories Ltd occupy positions shaped by CDSCO export compliance capabilities and US FDA inspection histories. Merck KGaA and Boehringer Ingelheim International GmbH represent European-headquartered competitors with dual exposure to pharmaceutical and agrochemical active ingredient markets.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Ltd |
| Pfizer Inc |
| AbbVie Inc |
| Boehringer Ingelheim International GmbH |
| Merck KGaA |
| Aurobindo Pharma Limited |
| Dr. Reddy's Laboratories Ltd |
| Lonza Group |
| Teva Pharmaceutical Industries Ltd |
| Others |
Supply Flow & Price Mechanics
Continuous manufacturing adoption is compressing production footprints while elevating capital barriers, simultaneously reducing unit economics for qualified producers and concentrating supply among firms with viral clearance validation capabilities. This technology shift rewards fermentation-based biologic API suppliers with documented EMA filing histories while squeezing commodity chemical manufacturers facing REACH impurity threshold compliance costs.
Pricing Analysis
Unbundled fermentation capacity contracts now trade at premiums to bundled full-service offerings as formulators seek flexibility without fixed asset exposure. Three-tier pricing structure across premium biologic, standard synthetic, and economy generic levels reflects purity grade and regulatory filing support differentiation. Pricing pressure stems from Indian CRO stainless-steel bioreactor overcapacity in mammalian cell-culture segments. Agricultural producers in Brazil and Argentina exhibit highest price sensitivity; oncology injectable formulators in Germany show lowest.
Supply Chain Analysis
Bioprocess engineer scarcity in Basel, Boston, and Bangalore constrains fermentation scale-up velocity and extends campaign changeover timelines across multi-product facilities. Active ingredient supply concentrates in India, Switzerland, and the United States for biologics; China and India anchor synthetic small-molecule API production. Manufacturing draws from yeast extract, soy peptone, and chromatography resin inputs where Protein A supply concentrates among three global suppliers. Single-source chromatography resin vulnerability creates downstream purification bottlenecks. Distribution runs through qualified supplier lists consolidating around dual-sourced fermentation capacity with documented viral clearance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate among fermentation-based biologic API suppliers capturing biosimilar portfolio growth, justified by continuous manufacturing cost-down trajectories compressing batch cycle times.
For Market Incumbents: Lock in chromatography resin supply security through long-term offtake agreements with the three dominant global suppliers to neutralize downstream purification bottlenecks. Extend viral clearance validation documentation across multi-product facility campaigns to defend against emerging Indian CRO competitors expanding stainless-steel bioreactor capacity. Captive fermentation investment in Hyderabad and Bangalore clusters anchors cost position against Lonza Group's disposable bioreactor flexibility.
For New Entrants and Emerging Players: Mid-tier generic pharmaceutical manufacturers in Germany and the United States seeking dual-sourced API relationships represent the most penetrable buyer archetype as large formulators disqualify single-source suppliers regardless of cost position. Direct-to-formulator digital channels bypassing traditional distributor networks capture early traction among procurement teams consolidating qualified supplier lists. Target soil treatment protocol actives in precision agriculture adoption corridors across Australia and Canada where extended residual activity specifications filter incumbent competition.
For Investors and Strategic Acquirers: Valuations sit cheapest among commodity chemical API suppliers facing margin compression from REACH impurity threshold tightening and enzymatic route displacement limitations in chiral small-molecule synthesis. Long-term viability favors contract manufacturers with documented EMA variations procedure expertise and mammalian cell-culture platform flexibility. Monitor FDA-EMA biosimilar guidance convergence as inflection indicator for portfolio reallocation requirements across fermentation-derived therapeutic categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Sun Pharmaceutical anchors cost position through captive stainless-steel bioreactor clusters in India. |
| Disposable Bioreactor Deployment | Lonza Group expands commercial-scale single-use systems for Phase III and launch supply flexibility. |
| Regulatory Filing Convergence | Swissmedic guidance alignment with EMA biosimilar pathways streamlines multi-jurisdiction submissions for Basel-based manufacturers. |
| Continuous Manufacturing Adoption | Flow chemistry integration with real-time release testing enables smaller-footprint facilities in high-cost geographies. |
| Direct-to-Formulator Digital Channels | API marketplaces bypass distributor networks to capture mid-tier generic pharmaceutical procurement consolidation. |
Methodological Framework
Coverage spans India, Switzerland, Germany, and the United States, with primary inputs from each regional cluster combining structured interviews with bioprocess engineering directors, regulatory affairs leads at CDSCO and FDA, crop protection company procurement managers, and contract manufacturing organization executives. Secondary validation draws from EMA variations procedure databases, FDA inspection observation reports, REACH registration dossiers, and stainless-steel bioreactor capacity announcements. Bottom-up facility capacity modeling triangulates against top-down therapeutic category demand projections.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions span product type, end user, formulation type, and application method with regulatory framework and viral clearance validation status as industry-specific forecast inputs. CAGRs derive from facility utilization trajectories, campaign changeover frequency assumptions, and biosimilar approval pathway convergence timing. Analytical framework incorporates fermentation yield improvement curves and chromatography resin cost elasticity parameters.
Inputs from EMA and FDA filing databases were available through the study window; gaps in real-time contract manufacturing pricing transparency introduce uncertainty bands around capacity expansion timing assumptions. Forecasts reflect documented assumptions regarding bioprocess engineer workforce mobility and single-use bioreactor adoption velocity. Material deviation in FDA-EMA biosimilar guidance convergence or Protein A resin supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Grade Sodium Carbonate Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Sulphonamides Market
Pharmaceutical Ingredients
US Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market
Pharmaceutical Ingredients
Prescription Hair Loss and Hair Removal Drugs Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market