
 Diosmin API Market | 2026-2036
Diosmin API Market Size, Share, and Industry Trends Forecast 2026-2036
Diosmin API Market Insights
Pharmaceutical-grade diosmin is reorganizing competitive dynamics as buyers enforce tighter impurity profiles and micronization standards. Sichuan Xieli Pharmaceutical leverages captive citrus peel sourcing to secure raw material continuity. Hunan Yuantong Pharmaceutical anchors its position through dedicated hesperidin-to-diosmin conversion capacity. PMC Isochem differentiates via European GMP certification that unlocks hospital procurement channels.
Diosmin API is a semisynthetic flavonoid glycoside manufactured from citrus-derived hesperidin through iodine-catalyzed dehydrogenation, typically dosed at 450 mg in combination with 50 mg hesperidin for venotonic and vascular-protective indications. Tablet formulations dominate volume consumption due to established bioequivalence data and reimbursement alignment, while injectable diosmin captures premium pricing in acute edema management where rapid onset is clinically prioritized. Homecare distribution is expanding fastest as oral regimens displace inpatient observation for stable chronic venous disease patients.
EMA's active substance master file guidelines and FDA's ICH Q3D elemental impurity standards govern diosmin API release specifications, with India's CDSCO imposing parallel bioavailability study requirements on domestic manufacturers. China's NMPA has tightened citrus raw material traceability rules under revised drug master file protocols. Stakeholders must monitor evolving pharmacopeial monograph harmonization between EP, USP, and ChP standards as divergence creates dual-registration burdens.
Market Dynamics
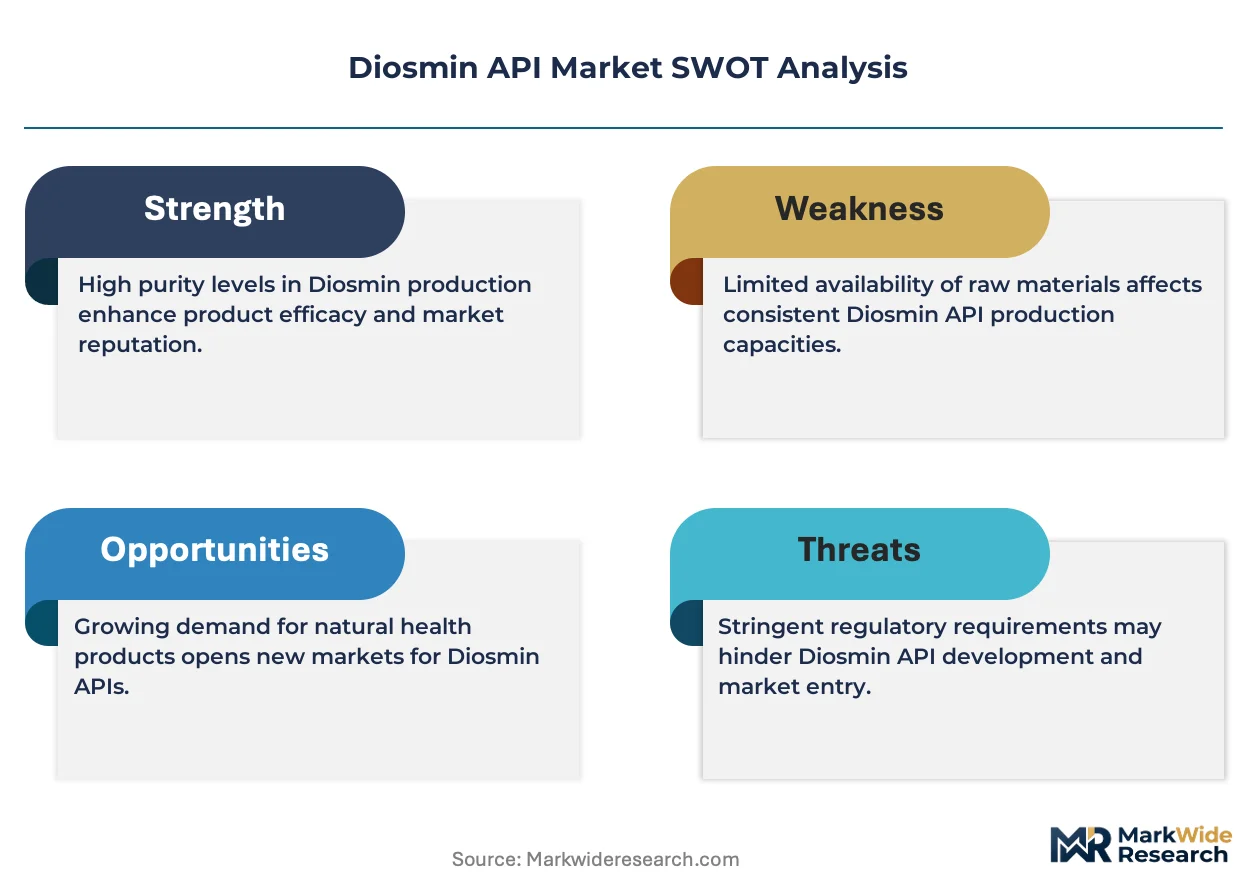
EMA's tightened API purity standards are forcing manufacturers to requalify supplier networks and invest in micronization capacity, compressing margins for non-compliant producers while rewarding certified specialists.
Growth Catalysts
- Chronic venous insufficiency prevalence:Aging demographics across Western Europe and North America are expanding the addressable patient population for venotonic formulations.
- REACH compliance automation:European chemical registration requirements are accelerating adoption of digitized batch tracking systems among API exporters.
- Iodine-catalyzed process refinement:Continuous-flow dehydrogenation technology is improving conversion yields from citrus-derived hesperidin feedstock.
Market Restraints
- Citrus peel supply volatility:Climate-induced harvest fluctuations in Spain and Brazil create raw material discontinuity for semisynthetic production.
- ICH Q3D compliance costs:Elemental impurity testing requirements impose capital burdens on small-batch manufacturers lacking in-house spectrometry.
- Hydroxyethylrutoside substitution:Synthetic venotonic alternatives are capturing formulary positions in cost-sensitive hospital procurement channels.
Strategic Opportunities
- Homecare distribution expansion:Oral diosmin-hesperidin regimens are displacing inpatient observation for stable chronic venous disease patients.
- PLI scheme leverage:India's production-linked incentive framework offers tax benefits for API manufacturers expanding dedicated hesperidin conversion capacity.
- Micronization-as-a-service:Contract particle-size reduction partnerships enable mid-tier formulators to meet bioavailability specifications without capital investment.
Industry Challenges
- Cross-functional talent scarcity:Combined expertise in flavonoid chemistry and regulatory dossier preparation commands premium compensation in Hyderabad and Shanghai clusters.
- Dual-registration synchronization:Diverging EP and USP monograph updates create parallel filing burdens for multi-territory suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diosmin API Market |
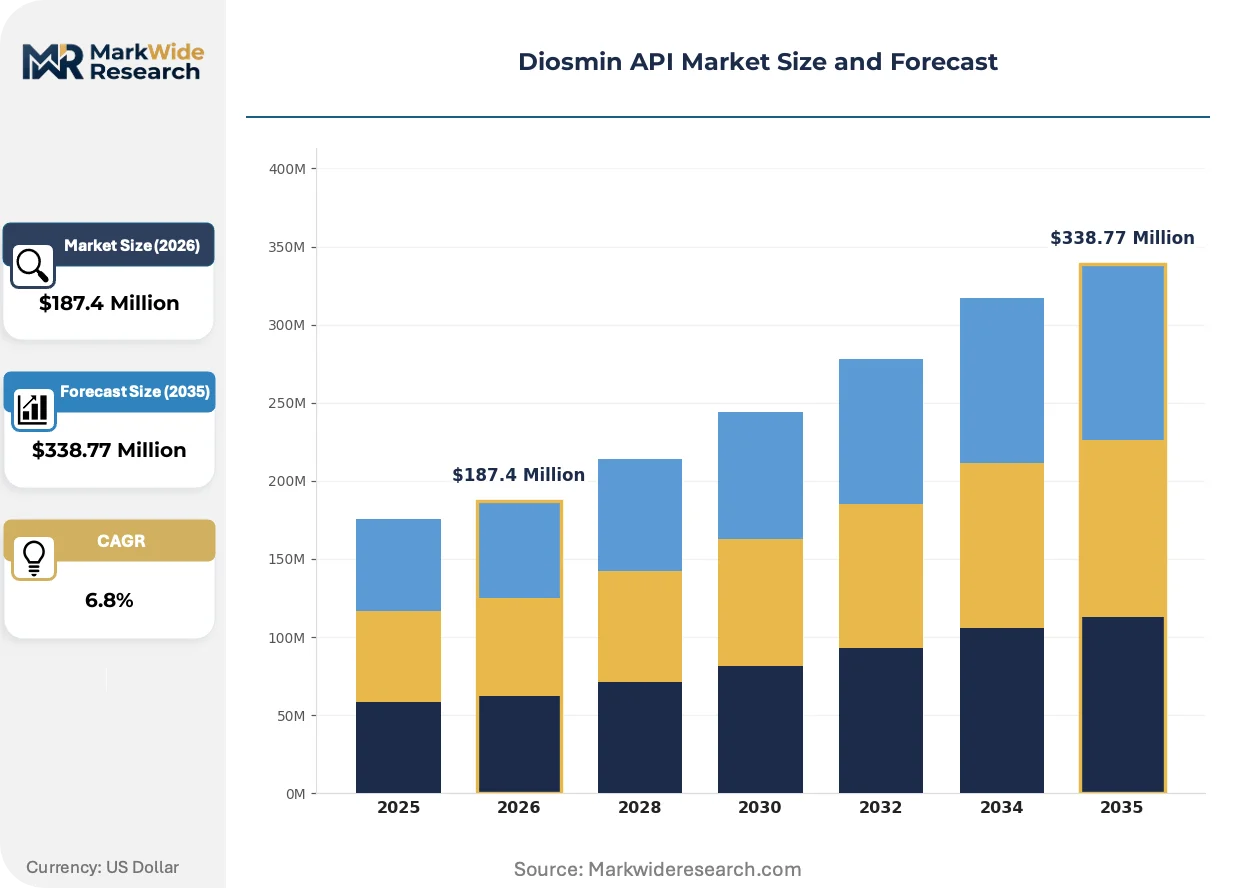
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ointments, Tablets, Capsules, Powders End User: Hospitals, Pharmacies, Clinics, Homecare Form: Topical, Oral, Injectable, Transdermal Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | Sichuan Xieli Pharmaceutical, Hunan Yuantong Pharmaceutical, HealthTech BioActives, Hangzhou Deli Chemical, PMC Isochem, Basic Nutrition, Chengdu Yazhong Bio-pharmaceutical, Mianyang Di'ao Pharmaceutical Co. Ltd, Bajaj Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diosmin API Market Trends and Innovations
Process intensification and regulatory digitization are compressing development timelines while reshaping how API quality is verified across distributed manufacturing networks.
Continuous-flow iodine-catalyzed dehydrogenation is supplanting traditional batch reactors in hesperidin-to-diosmin conversion. European contract manufacturers are adopting this technology to reduce solvent waste and improve lot-to-lot consistency. The shift is enabling smaller-footprint facilities to achieve pharmaceutical-grade output volumes previously requiring multi-reactor installations.
EMA's active substance master file guideline revisions are mandating enhanced citrus raw material traceability documentation. Suppliers must now provide geolocation-tagged harvest records and pesticide residue certificates back to orchard level. Indian exporters serving European formulation houses are investing in blockchain-enabled provenance systems to satisfy these requirements.
Hospital procurement consortia are consolidating API purchasing decisions under centralized pharmacy committees. This concentration is displacing fragmented procurement by individual therapeutic departments. The pattern is most pronounced in Germany's Krankenhausversorgung networks, where standardized venotonic protocols now specify certified micronized grades exclusively.
Diosmin API Market Segmentation
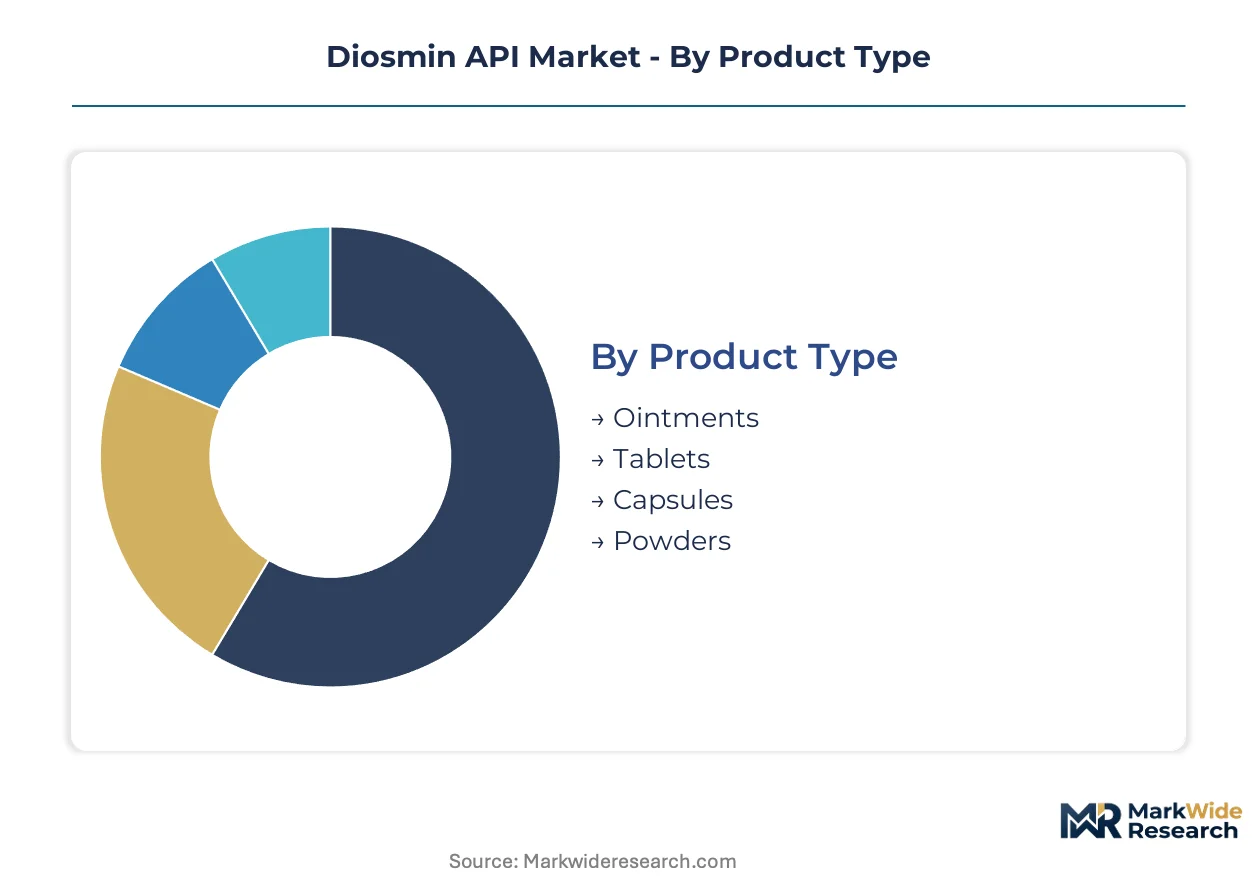
Diosmin API demand fragments across formulation technologies and care settings, with substitution economics varying sharply by delivery mechanism. Understanding segment-specific vulnerability to hydroxyethylrutoside displacement and micronization requirements shapes supplier portfolio decisions.
Product Type:
Tablet and capsule formats face intensifying pressure from synthetic venotonic alternatives in hospital procurement, while topical formulations defend niche positions through localized action claims.
- Tablets:Fixed-dose 450 mg diosmin with 50 mg hesperidin dominates chronic venous insufficiency maintenance therapy. German Krankenhausversorgung networks specify certified micronized grades exclusively, locking out non-compliant suppliers.
- Capsules:Gelatin and HPMC shells accommodate modified-release profiles for gastro-sensitive patient populations. Demand concentrates in Italian and Spanish retail pharmacy channels where patient self-selection drives brand loyalty.
- Ointments:Semisolid bases enable direct application to varicose vein clusters with localized anti-inflammatory action.
- Powders:Bulk API for compounding pharmacies and veterinary formulations requires specialized micronization equipment.
Tablets retain volume leadership; capsules hold the steepest expansion curve.
End User:
Cost-tier stratification separates acute intervention sites from maintenance therapy channels, with reimbursement intensity determining API grade specifications.
- Hospitals:Inpatient venotonic protocols prioritize rapid-onset injectable diosmin for acute edema management. EMA-certified suppliers capture centralized pharmacy committee purchasing in France and Germany.
- Homecare:Oral regimens displace inpatient observation for stable chronic venous disease patients, expanding fastest in UK and Netherlands domiciliary care programs.
- Pharmacies:Community dispensing anchors maintenance therapy volumes with prescription refill patterns.
- Clinics:Specialist phlebology practices drive diagnostic-to-treatment conversion for premium formulations.
Hospitals command premium pricing tiers; homecare gains share fastest through reimbursement alignment.
Form:
Application route determines bioavailability requirements and regulatory pathway complexity, with parenteral formats imposing the steepest compliance burdens.
- Oral:First-pass metabolism necessitates precise particle-size distribution for consistent absorption. CDSCO bioavailability study requirements in India filter out small-batch manufacturers lacking dissolution profiling capacity.
- Injectable:Lyophilized diosmin for acute edema commands premium positioning where rapid venotonic onset is clinically prioritized. EMA's tightened elemental impurity standards under ICH Q3D reshape supplier qualification.
- Topical:Percutaneous absorption limits systemic exposure for localized symptom relief.
- Transdermal:Patch development remains exploratory with adhesion and flux optimization challenges.
Oral formulations anchor volume; injectable climbs fastest through acute care premiumization.
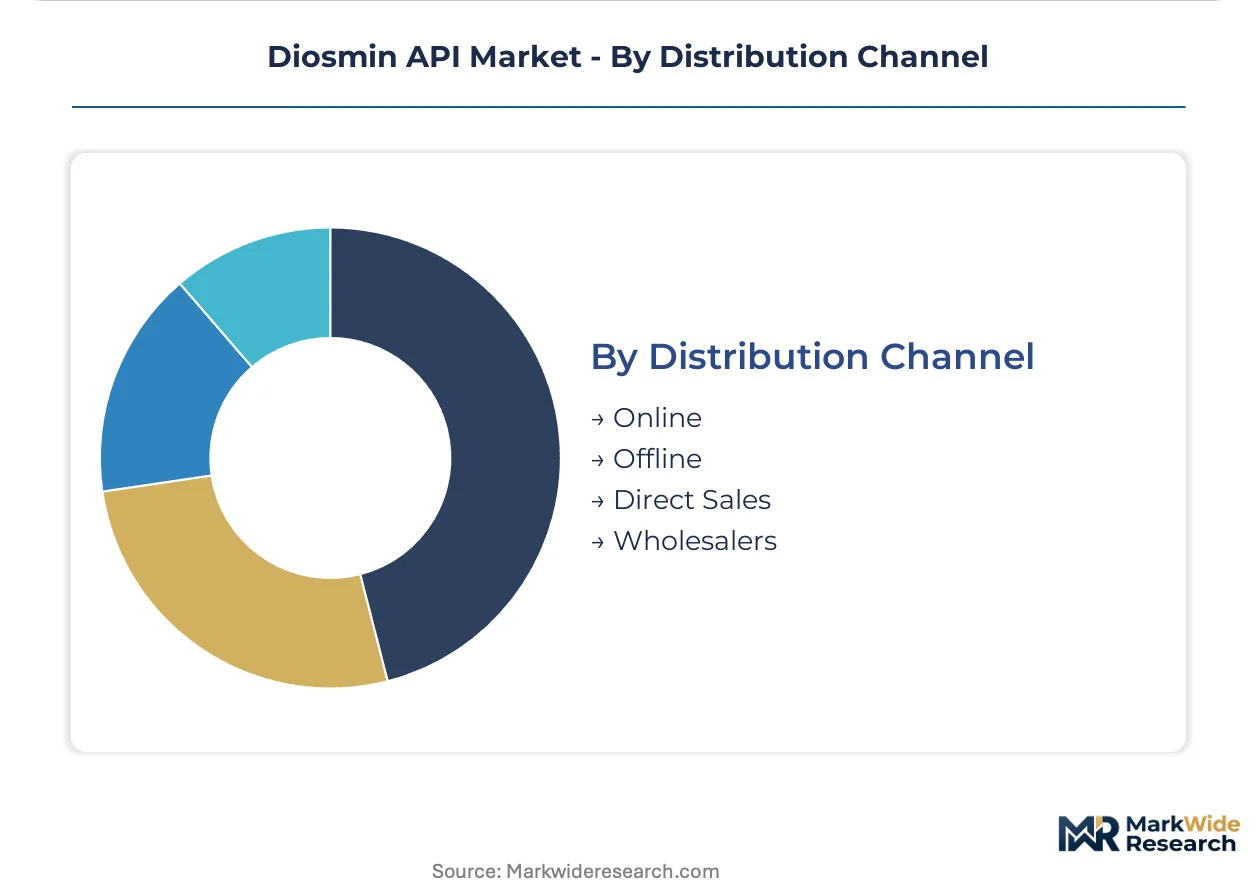
Distribution Channel:
Channel concentration reflects procurement centralization trends, with digital platforms capturing share in post-pandemic replenishment patterns.
- Direct Sales:API manufacturers supply formulation houses under long-term supply agreements with locked micronization specifications. Sichuan Xieli Pharmaceutical leverages captive citrus peel sourcing to secure continuity.
- Wholesalers:Regional distributors aggregate fragmented pharmacy demand across secondary cities in India and China.
- Online:B2B platforms enable mid-tier formulators to source certified grades without established supplier relationships.
- Offline:Traditional pharmaceutical distribution networks retain hospital and clinic channel control.
Direct sales retain volume leadership; online channels expand most quickly through procurement decentralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports diosmin API to European formulation houses under tightened EMA purity protocols, while Chinese manufacturers supply both domestic tablet producers and Southeast Asian contract manufacturers.
India
Hyderabad and Mumbai clusters host contract manufacturers serving export markets for venotonic formulations. CDSCO mandates bioavailability studies for domestic producers, filtering out small-batch operators lacking dissolution profiling capacity. The PLI scheme incentivizes dedicated hesperidin conversion capacity expansion in Gujarat and Maharashtra.
China
Sichuan and Hunan provinces concentrate citrus peel processing and semisynthetic conversion infrastructure. NMPA tightened raw material traceability rules under revised drug master file protocols, requiring geolocation-tagged harvest documentation. Chengdu and Changsha anchor the supplier base for both domestic consumption and API export.
Germany
Krankenhausversorgung hospital networks specify certified micronized diosmin grades exclusively, locking out non-compliant suppliers from centralized procurement. EMA's active substance master file guidelines mandate enhanced citrus provenance documentation. Frankfurt and Munich formulation houses drive premium-tier demand for injectable grades in acute edema protocols.
France
ANSM oversight shapes hospital pharmacy committee purchasing decisions for venotonic APIs. The country's phlebology specialist network maintains high prescription volumes for oral maintenance therapy. Lyon and Paris clusters concentrate formulation R&D and regulatory dossier preparation expertise.
United States
FDA's ICH Q3D elemental impurity standards govern API release specifications for domestic tablet manufacturers. New Jersey and North Carolina formulation hubs source certified grades for chronic venous insufficiency combination products. Homecare distribution expansion drives oral regimen demand as inpatient observation protocols shift.
Diosmin API Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and geographic reach. The supplier base fragments between citrus-captive processors, dedicated conversion specialists, and European GMP-certified contract manufacturers. Three archetypes dominate: vertically integrated peel-to-API processors, standalone hesperidin converters, and regulatory-certified European suppliers. Capacity expansion and micronization technology partnerships represent the dominant competitive vectors.
Among Chinese pharmaceutical manufacturers, Sichuan Xieli Pharmaceutical and Hunan Yuantong Pharmaceutical exemplify the citrus-captive archetype, while PMC Isochem occupies a position within the European certification tier. These three anchors illustrate how geographic concentration of raw material access, dedicated conversion infrastructure, and regulatory credentialing define competitive positioning across the supply base.
| Leading Market Players |
|---|
| Sichuan Xieli Pharmaceutical |
| Hunan Yuantong Pharmaceutical |
| HealthTech BioActives |
| Hangzhou Deli Chemical |
| PMC Isochem |
| Basic Nutrition |
| Chengdu Yazhong Bio-pharmaceutical |
| Mianyang Di'ao Pharmaceutical Co. Ltd |
| Bajaj Healthcare |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory buffers among European formulation houses signal supply-chain rigidity that amplifies pricing power for certified micronized grade suppliers while squeezing spot-market operators dependent on citrus harvest cycles.
Pricing Analysis
Hospital procurement committees anchor pharmaceutical-grade diosmin pricing through centralized venotonic protocol specifications. Three-tier pricing structure across EMA-certified micronized, standard pharmaceutical, and technical grades reflects purity differential and dissolution profiling investment. Cost compression in standard grades intensifies as hydroxyethylrutoside substitutes capture formulary positions. Generic tablet manufacturers exhibit highest price sensitivity; hospital pharmacy networks prioritize certification compliance over unit cost.
Supply Chain Analysis
Forty-five to sixty day raw material lead times from Sichuan and Hunan provinces expose formulators to climate-induced citrus peel harvest volatility. Supply concentrates in China for semisynthetic conversion infrastructure and India for contract manufacturing serving export markets. Iodine catalyst sourcing draws from Japanese and Chilean producers. Single-source vulnerability in citrus peel preprocessing creates discontinuity risk. Distribution runs through direct sales agreements with locked micronization specifications rather than spot-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diosmin API represents early-cycle expansion as homecare oral regimens displace inpatient observation protocols, with chronic venous insufficiency prevalence climbing across aging Western European and North American patient populations.
For Market Incumbents: Compound certification advantage through EMA active substance master file pre-submission consultations and dedicated micronization capacity expansion in Gujarat PLI zones. Hydroxyethylrutoside substitution in German hospital procurement channels demands defensive formulation partnerships that lock in venotonic protocol exclusivity. Captive citrus peel sourcing in Sichuan secures raw material continuity against Brazilian harvest volatility.
For New Entrants and Emerging Players: Differentiate on blockchain-enabled provenance documentation that satisfies EMA geolocation-tagged harvest requirements without legacy system retrofit burden. White-space concentrates in micronization-as-a-service partnerships for mid-tier Indian formulators lacking in-house particle-size reduction equipment. Target CDSCO-registered domestic producers seeking export qualification through European GMP certification pathways.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-credentialing play because EMA and FDA impurity standard harmonization will consolidate supplier tiers around certified specialists with proven dissolution profiling capacity. Acquisition targets cluster among citrus-captive processors with idle conversion capacity and underutilized micronization assets. Monitor ICH Q3D enforcement intensity at CDSCO as inflection signal for Indian export competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Active Substance Master File Submission | Unlocks hospital procurement committee access in Germany and France through certified supplier status. |
| Backward Integration into Citrus Peel Processing | Secures raw material continuity against Spanish and Brazilian climate-induced harvest fluctuations. |
| Continuous-Flow Dehydrogenation Technology Adoption | Reduces solvent waste and improves lot-to-lot consistency for pharmaceutical-grade output. |
| Blockchain-Enabled Provenance System Implementation | Satisfies EMA geolocation-tagged harvest documentation requirements for Indian exporters. |
| Micronization-as-a-Service Partnership Formation | Enables mid-tier formulators to meet bioavailability specifications without capital investment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA drug master file submissions, EMA active substance master file guidelines, and CDSCO bioavailability study protocols. Interviews with regulatory affairs leads at European formulation houses, procurement managers at German Krankenhausversorgung networks, and plant directors at Sichuan conversion facilities inform supply-side dynamics. Bottom-up volume estimates triangulate against top-down addressable patient population modeling for chronic venous insufficiency treatment lines.
Segmentation dimensions modeled span formulation technology, care setting, and distribution channel across the projection horizon. Dosage form segmentation captures tablet, capsule, injectable, and topical delivery mechanisms. Administration route analysis distinguishes oral first-pass metabolism requirements from parenteral elemental impurity standards. Regional regulatory cluster segmentation reflects EMA, FDA, CDSCO, and NMPA protocol divergence. CAGRs derive from patient population epidemiology, reimbursement alignment trajectories, and supplier capacity expansion announcements.
Material uncertainties — citrus harvest volatility, ICH Q3D enforcement timing, hydroxyethylrutoside formulary capture rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EMA-FDA pharmacopeial harmonization progress and PLI scheme continuation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Cyclooxygenase 2 Inhibitor Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Global Penicillin Drug Market
Pharmaceutical Ingredients
Pharmaceutical Hot Melt Extrusion Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Cyprosin Market
Pharmaceutical Ingredients
Glycylglycine Market
Pharmaceutical Ingredients
Synthetic Lethality-Based Drugs and Targets Market
Pharmaceutical Ingredients
Mrna Synthesis Raw Materials Market
Pharmaceutical Ingredients
Global Small Molecule API Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Kitasamycin Market