
 Small-Molecule Injectable Drugs Market | 2026-2036
Small-Molecule Injectable Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Small-Molecule Injectable Drugs Market Outlook
Hospital procurement concentration is hardening across integrated delivery networks, forcing manufacturers to negotiate larger contracts with fewer buyers. Pfizer Inc. leverages its sterile injectable portfolio to sustain long-term supply agreements with major health systems. Fresenius Kabi AG anchors its position through vertical control of active pharmaceutical ingredient and finished-dose manufacturing for critical care injectables.
Small-molecule injectable drugs are sterile liquid or lyophilized formulations administered parenterally, typically requiring aseptic processing, endotoxin control below 0.5 EU/mL, and USP compliance for particulate matter. These products serve acute and chronic therapeutic areas where rapid bioavailability or bypass of gastrointestinal metabolism proves clinically essential. Oncology and infectious disease segments dominate current revenue pools, with intravenous delivery mode capturing the largest share of hospital-administered volumes. Subcutaneous formulations are expanding fastest as self-administration protocols shift patient volume toward homecare settings, redistributing margin pools from institutional to retail channels.
FDA enforces current Good Manufacturing Practice for sterile drug products under 21 CFR Parts 210 and 211, while EMA's Annex 1 revision tightens contamination control expectations for European manufacturing sites. USP Chapter 797 compounding standards and EU GMP Annex 1 together elevate barrier technology and environmental monitoring investments across production networks. Stakeholders must monitor regulatory divergence between FDA and EMA aseptic processing requirements when designing multi-territory manufacturing strategies.
Market Dynamics
Integrated delivery networks are consolidating hospital purchasing into fewer procurement desks, forcing manufacturers to restructure sales organizations around multi-year supply agreements with single buyers controlling billions in annual injectable spend.
Growth Catalysts
- USP Chapter 797 revision:Compounding pharmacies must upgrade to closed-system transfer devices and automated compounding technologies, creating replacement demand for legacy equipment across hospital and outsourced facilities.
- Home infusion expansion:Subcutaneous formulations for oncology and immunology are shifting patient volume from infusion centers to self-administration, opening retail and specialty pharmacy channels previously inaccessible to institutional suppliers.
- Japan's outpatient infrastructure:METI-supported expansion of community-based infusion clinics is redistributing demand from inpatient wards toward ambulatory settings requiring portable, prefilled delivery systems.
Market Restraints
- API supply concentration:Sterile active pharmaceutical ingredient manufacturing clusters in India and China expose finished-dose producers to geopolitical disruption and forced labor compliance investigations.
- Glass vial input volatility:Borosilicate tubing supply from Schott and Corning remains constrained, with pharmaceutical-grade Type I glass pricing subject to energy cost fluctuations and furnace capacity limitations.
- Lyophilization bottleneck:Freeze-drying capacity for unstable small molecules requires 18-24 month equipment lead times, constraining launch timelines for reformulated products.
Strategic Opportunities
- Germany's KHZG hospital digitization:Federal funding for connected medication management systems creates demand for smart prefilled syringes with integrated RFID tracking and cold-chain verification.
- Bioconjugation convergence:Antibody-drug conjugate manufacturing expertise is transferring to small-molecule cytotoxic payloads, enabling high-potency injectable production for targeted oncology therapies.
- Specialty pharmacy networks:Limited distribution channels for controlled substances and REMS-mandated products offer margin protection and direct patient data access unavailable in institutional sales.
Industry Challenges
- Aseptic processing workforce gap:Qualified personnel for isolator operation and environmental monitoring are scarce, with training programs failing to match facility expansion rates in the United States.
- EU GMP Annex 1 compliance timeline:Contamination control strategy documentation and barrier technology upgrades must complete before August 2025 enforcement, compressing capital deployment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small-Molecule Injectable Drugs Market |
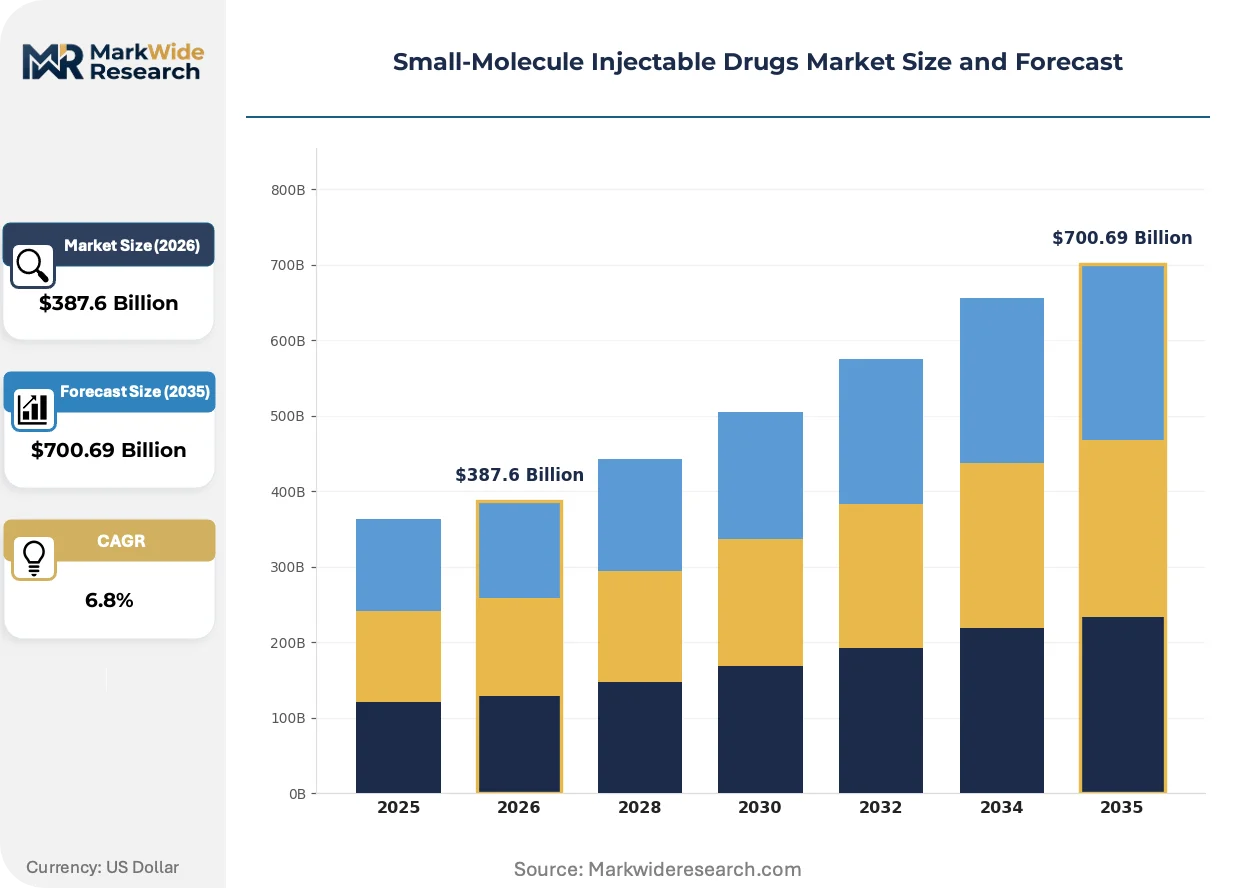
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Monoclonal Antibodies, Vaccines, Insulin Therapy Area: Oncology, Infectious Diseases, Endocrinology, Neurology Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Intraluminal End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Novartis AG, Pfizer Inc., Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., AstraZeneca Plc, Fresenius Kabi AG, Baxter International Inc., Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small-Molecule Injectable Drugs Market Strategic Shifts
Barrier isolation technology and automated visual inspection are compressing production timelines while regulatory harmonization efforts create divergent compliance investments across manufacturing networks.
Ready-to-use (RTU) container closure systems are overtaking traditional bulk vial filling in high-value oncology injectables. Contract manufacturers in Germany and Switzerland are adopting RTU syringes and cartridges to eliminate glass washing and depyrogenation steps. This shift is overtaking conventional aseptic filling lines and compressing batch release timelines from weeks to days.
EMA's Annex 1 revision mandates contamination control strategies with quality risk management principles. European sterile manufacturing sites must implement single-use barrier systems and continuous viable particle monitoring. Oncology and anti-infective fill-finish operations face the steepest compliance investments, with many facilities choosing dedicated isolator suites over open restricted access barrier systems.
Hospital purchasing desks are consolidating injectable procurement into category management functions with dedicated clinical pharmacists. Integrated delivery networks in the United States are replacing individual hospital buying with centralized formulary committees that negotiate system-wide contracts spanning dozens of facilities. This concentration is visible most acutely in oncology and anesthesia therapeutics, where three-year sole-source agreements now dominate high-volume molecules.
Small-Molecule Injectable Drugs Market Segmentation
Segmentation in small-molecule injectables reveals how formulation choices, delivery technologies, and care settings redistribute margin pools across the value chain. Procurement patterns diverge sharply between institutional buyers and emerging homecare channels.
Product Type:
Upgrade cycles in container closure systems and cold-chain infrastructure are reshaping which product formats capture replacement investment across manufacturing networks.
- Biologics:Complex protein and peptide formulations requiring controlled-temperature storage from production through administration. Hospital oncology units in Germany and Japan are consolidating procurement of temperature-sensitive biologics into dedicated cold-chain contracts with penalty clauses for excursion events.
- Monoclonal Antibodies:Large-molecule therapeutics with extended half-lives enabling less frequent dosing. Subcutaneous mAb formulations are displacing intravenous equivalents in US rheumatology and dermatology practices as self-administration protocols expand.
- Vaccines:Immunization products with established fill-finish infrastructure and high-volume manufacturing economics.
- Insulin:Established peptide hormone with mature delivery device ecosystems and concentrated API manufacturing.
Volume placements concentrate in biologics; the faster expansion belongs to monoclonal antibodies.
Therapy Area:
Cost tier differentiation separates acute inpatient injectables from chronic outpatient maintenance therapies with diverging reimbursement and distribution economics.
- Oncology:Cytotoxic and cytostatic agents requiring aseptic handling protocols and specialized compounding infrastructure. USP Chapter 797 compliance investments are concentrating demand for outsourced oncology compounding among three national providers with dedicated isolator capacity.
- Infectious Diseases:Anti-infective agents spanning hospital-acquired infection protocols and outpatient parenteral antimicrobial therapy. Japanese community infusion clinics under METI expansion programs are redistributing infectious disease injectable volume from inpatient wards.
- Endocrinology:Hormone replacement and metabolic disorder management with established home injection training programs.
- Neurology:CNS-active agents with specialized distribution requirements and limited therapeutic alternatives.
Revenue concentration sits with oncology; endocrinology is gaining share fastest as home administration protocols mature.
Delivery Mode:
Application requirements for bioavailability, onset speed, and patient compliance dictate container format and administration setting selection.
- Intravenous:Direct vascular delivery achieving immediate systemic distribution for critical care and high-potency oncology. US integrated delivery networks are consolidating IV injectable procurement into category management functions with formulary committees spanning dozens of facilities.
- Subcutaneous:Tissue depot administration enabling self-injection and reduced healthcare utilization. Germany's KHZG-funded connected medication systems are creating demand for smart prefilled syringes with RFID tracking in subcutaneous oncology and immunology products.
- Intramuscular:Skeletal muscle deposition for sustained-release formulations and vaccine delivery.
- Intraluminal:Cavity-specific administration for localized therapeutic effect in specialized procedures.
Hospital purchasing favors intravenous; subcutaneous formats are climbing the fastest as specialty pharmacy channels expand.
End User:
Customer type determines regulatory pathway, distribution complexity, and margin structure through diverging compliance and service requirements.
- Hospitals:Institutional purchasers with consolidated procurement desks negotiating multi-year supply agreements. Three-year sole-source contracts now dominate high-volume oncology and anesthesia injectables across US integrated delivery networks.
- Homecare:Patient-directed administration with specialty pharmacy intermediation and reimbursement complexity. Japan's outpatient infrastructure expansion under METI programs is redistributing demand toward community-based infusion requiring portable delivery systems.
- Clinics:Ambulatory settings with intermediate volume and mixed procurement autonomy.
- Pharmacies:Retail and specialty channels with direct patient access and REMS-mandated distribution for controlled substances.
Procurement volume aggregates in hospitals; homecare channels show the steepest expansion trajectory as self-administration protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for small-molecule injectable drugs concentrates in the United States, Germany, and Japan as these countries expand outpatient infusion capacity and consolidate hospital procurement. Each market presents distinct regulatory pressures and infrastructure investments that reshape competitive positioning.
United States
Integrated delivery networks now control billions in annual injectable spend through centralized formulary committees. FDA enforcement of 21 CFR Parts 210 and 211 for sterile manufacturing elevates compliance costs for domestic facilities. Boston and Research Triangle Park host concentrated biopharma manufacturing clusters where companies are retrofitting isolator suites ahead of USP Chapter 797 deadlines.
Germany
Federal KHZG funding for connected medication management systems drives demand for smart prefilled syringes with RFID tracking. EMA's Annex 1 revision mandates contamination control strategies that compress capital deployment windows through August 2025. Baden-Württemberg and Bavaria anchor European sterile manufacturing with RTU container closure adoption accelerating across contract manufacturing sites.
Japan
METI-supported expansion of community-based infusion clinics redistributes demand from inpatient wards toward ambulatory settings. PMDA oversight of aseptic processing aligns with international standards while maintaining distinct documentation requirements. The Kansai region around Osaka and the Greater Tokyo area concentrate pharmaceutical manufacturing investments for portable delivery systems.
India
API manufacturing clusters in Hyderabad and Ahmedabad supply sterile active pharmaceutical ingredients to global finished-dose producers. CDSCO regulatory harmonization efforts with ICH standards are upgrading domestic aseptic processing capabilities. Geopolitical scrutiny of forced labor compliance and supply concentration risks is accelerating inspection protocols at export-oriented facilities.
Switzerland
Swissmedic oversight of high-potency injectable manufacturing attracts bioconjugation expertise for cytotoxic oncology payloads. The Basel region and Lake Geneva corridor host specialized fill-finish operations serving European and global markets. RTU technology adoption and barrier isolation investments position Swiss contract manufacturers for EMA Annex 1 compliance leadership.
Small-Molecule Injectable Drugs Market Competitive Environment
United States-based pharmaceutical conglomerates anchor one tier of the market structure; German and Swiss specialists hold differentiated positions in sterile manufacturing and critical care segments. The vendor base organizes around three strategic archetypes: diversified conglomerates with vertical API-to-finished-dose control, mid-cap specialists with isolator technology investments, and contract manufacturers with RTU platform capabilities. Competitive moves center on multi-year sole-source procurement agreements with consolidated health systems and accelerated lyophilization capacity expansion.
Among diversified pharmaceutical conglomerates, Novartis AG and Pfizer Inc. exemplify archetypes with integrated sterile injectable portfolios. Fresenius Kabi AG occupies a distinct position representing German specialists with captive API manufacturing for critical care therapeutics. These named entities anchor commentary on how geographic origin and structural configuration shape competitive positioning without ascribing specific strategic actions or market share claims to individual companies.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| AstraZeneca Plc |
| Fresenius Kabi AG |
| Baxter International Inc. |
| Sanofi S.A. |
| Others |
Value Chain & Pricing Dynamics
Borosilicate Type I glass tubing from Schott and Corning furnaces feeds through three pricing tiers before reaching hospital procurement desks, with energy cost volatility at the furnace level amplifying margin compression downstream for standard-grade vials while premium RTU container formats capture insulation.
Pricing Analysis
High-volume oncology injectables trade on thin margins through sole-source IDN contracts, while limited-distribution specialty products command premium positioning via REMS-mandated channels. Price differentiation rests on USP Chapter 797 compliance certification and cold-chain integrity guarantees. Cost compression in standard intravenous generics is intensifying because consolidated purchasing desks extract volume rebates exceeding manufacturing scale efficiencies. Community infusion clinics exhibit highest price sensitivity; integrated delivery networks with captive specialty pharmacies show least.
Supply Chain Analysis
Dual-sourcing requirements for sterile APIs now mandate qualified secondary suppliers in India and Switzerland alongside primary China relationships, extending qualification timelines. Finished-dose production draws from API clusters in Hyderabad, Ahmedabad, and Shanghai, with borosilicate glass, lyophilization equipment, and isolator technology as critical component dependencies. Single-source vulnerability concentrates in Schott's pharmaceutical-grade tubing capacity. Distribution runs through three-tier wholesaler networks serving hospital systems, with direct specialty pharmacy channels expanding for subcutaneous self-administration products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation into category management functions is forcing subscale manufacturers toward exit or acquisition, with EU GMP Annex 1 compliance costs as the primary elimination mechanism.
For Market Incumbents: To counter API supply concentration risk, Pfizer and Fresenius Kabi are deepening backward integration into captive sterile ingredient manufacturing while simultaneously acquiring isolator-equipped contract fill-finish capacity in Germany and Switzerland ahead of August enforcement deadlines.
For New Entrants and Emerging Players: Specialty pharmacy direct distribution offers the lowest barrier entry path for subcutaneous oncology and immunology formulations, with Japan's METI-funded community infusion clinics as the most penetrable geography for portable delivery system launches through partnership with established cold-chain logistics providers.
For Investors and Strategic Acquirers: Accelerated RTU technology adoption among Swiss and German contract manufacturers is the leading indicator that barrier isolation expertise will command scarcity premiums across the next decade. Acquisition targets should prioritize mid-cap specialists with validated isolator suites and existing EMA Annex 1 documentation, watching for PMDA harmonization announcements as the signal for Japanese market entry viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Freeze-drying bottleneck relief enables accelerated launch timelines for unstable small-molecule reformulations. |
| RTU Platform Adoption | Ready-to-use container systems eliminate glass washing steps, compressing batch release from weeks to days at German sites. |
| Isolator Suite Retrofit | Barrier technology investments position facilities for EU GMP Annex 1 compliance before enforcement deadlines. |
| Specialty Pharmacy Partnership | Limited distribution channel access captures REMS-mandated product margins and direct patient data streams. |
| Backward API Integration | In-house sterile active pharmaceutical ingredient production insulates against India-China supply disruption risks. |
Study Parameters
Document review covered FDA 483 observations, EMA inspection reports, and USP Chapter 797 draft revisions, complemented by interviews with sterile manufacturing executives, hospital formulary directors, GPO contracts managers, and specialty pharmacy operators. Secondary sources included ClinicalTrials.gov entries, CDSCO export registration databases, and customs trade data for borosilicate glass tubing. Bottom-up capacity modeling and top-down procurement spend estimates were triangulated against announced facility investments.
Cross-referencing historical capacity utilization against expert panel input on IDN consolidation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed therapy area, delivery mode, container closure format, and regional regulatory cluster. CAGRs derived from facility expansion announcements, procurement contract durations, and patient volume shift assumptions between inpatient and ambulatory settings.
Inputs from PMDA regulatory filings and METI infrastructure grant disclosures were available through the study window; gaps in real-time IDN contract terms introduce uncertainty bands around manufacturer revenue concentration estimates. Deviation in EU GMP Annex 1 enforcement timing or USP Chapter 797 final rule provisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Propellants Market
Pharmaceutical Ingredients
Chlorzoxazone Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
MEK Inhibitors Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Oral Transmucosal Drugs Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market
Pharmaceutical Ingredients
Global Glycine Supplement Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market