
 Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market | 2026-2036
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Outlook
Active pharmaceutical ingredient manufacturing across India and China is restructuring regional supply chains for DPP-4 inhibitor production. Merck & Co. leverages its established sitagliptin synthesis infrastructure to anchor bulk supply commitments across Southeast Asia. Eli Lilly and Company competes through differentiated fixed-dose combinations that integrate its GLP-1 receptor agonist portfolio. Takeda Pharmaceutical dominates Japanese distribution channels through deep hospital formulary relationships.
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors constitute a class of oral hypoglycemic agents that prolong the half-life of incretin hormones by inhibiting the DPP-4 enzyme, thereby potentiating glucose-dependent insulin secretion with molecular selectivity for the catalytic site of the DPP-4 homodimer. These agents serve primarily as second-line or adjunct therapy in type 2 diabetes management where sulfonylurea intolerance or cardiovascular risk modification is clinically prioritized. Oral tablet formulations command the dominant volume position due to patient adherence advantages and reimbursement alignment with chronic disease protocols. Sitagliptin maintains the largest revenue pool among molecular types, while linagliptin captures premium positioning through its predominantly non-renal elimination pathway that reduces dose adjustment burdens in elderly populations with declining kidney function.
Japan's PMDA, China's NMPA, and India's CDSCO collectively govern market access through divergent bioequivalence standards and local clinical trial requirements that fragment registration timelines across the region. PMDA's Sakigake designation system accelerates review for innovative diabetes combinations, while NMPA's evolving generic consistency evaluation program pressures multinational pricing power in China's volume-based procurement environment. Stakeholders must monitor procurement rule changes in China's national reimbursement drug list and India's PLI scheme for active pharmaceutical ingredients to anticipate margin compression or supply relocation.
Market Dynamics
China's volume-based procurement program is compressing multinational pricing power while accelerating local generic substitution, fundamentally restructuring how DPP-4 inhibitors reach patients across the region.
Growth Catalysts
- Hospital formulary expansion:Endocrinology departments in tier-one Chinese cities are prioritizing glucose-dependent insulin secretagogues with established cardiovascular safety profiles, expanding specialist prescribing pools.
- PMDA Sakigake pathway:Japan's accelerated review designation for innovative diabetes combinations is shortening registration timelines for fixed-dose therapies targeting polypharmacy reduction.
- Renal impairment protocols:Predominantly non-renal elimination pathways are automating dose adjustment workflows in nephrology clinics managing elderly diabetic populations with declining kidney function.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient synthesis for DPP-4 inhibitors clusters in specific Indian and Chinese manufacturing zones, creating single-source vulnerability for regional formulation networks.
- Generic consistency evaluation:China's NMPA bioequivalence requirements impose 18-24 month registration delays on multinational originator products facing local therapeutic substitution.
- Sulfonylurea cost floor:Ultra-low pricing of legacy secretagogues in India's public health programs creates a substitution ceiling for premium oral hypoglycemic uptake in price-sensitive segments.
Strategic Opportunities
- Indonesia's underpenetrated tier-two cities:Rapid urbanization in Surabaya and Bandung is concentrating newly diagnosed type 2 diabetes cases ahead of specialist infrastructure deployment.
- GLP-1 receptor agonist convergence:Fixed-dose combination development integrating incretin-based therapies is opening positioning for differentiated oral regimens in obesity-diabetes comorbidity management.
- India's PLI scheme for APIs:Production-linked incentive structures are attracting backward integration investments that could reshape regional supply geography for DPP-4 inhibitor raw materials.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in stable dipeptide analog synthesis remains concentrated among a limited cohort of medicinal chemistry teams across Asia-Pacific contract development organizations.
- Multi-jurisdiction dossier divergence:Divergent bioequivalence standards between Japan's PMDA, China's NMPA, and India's CDSCO force parallel clinical study designs that fragment development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market |
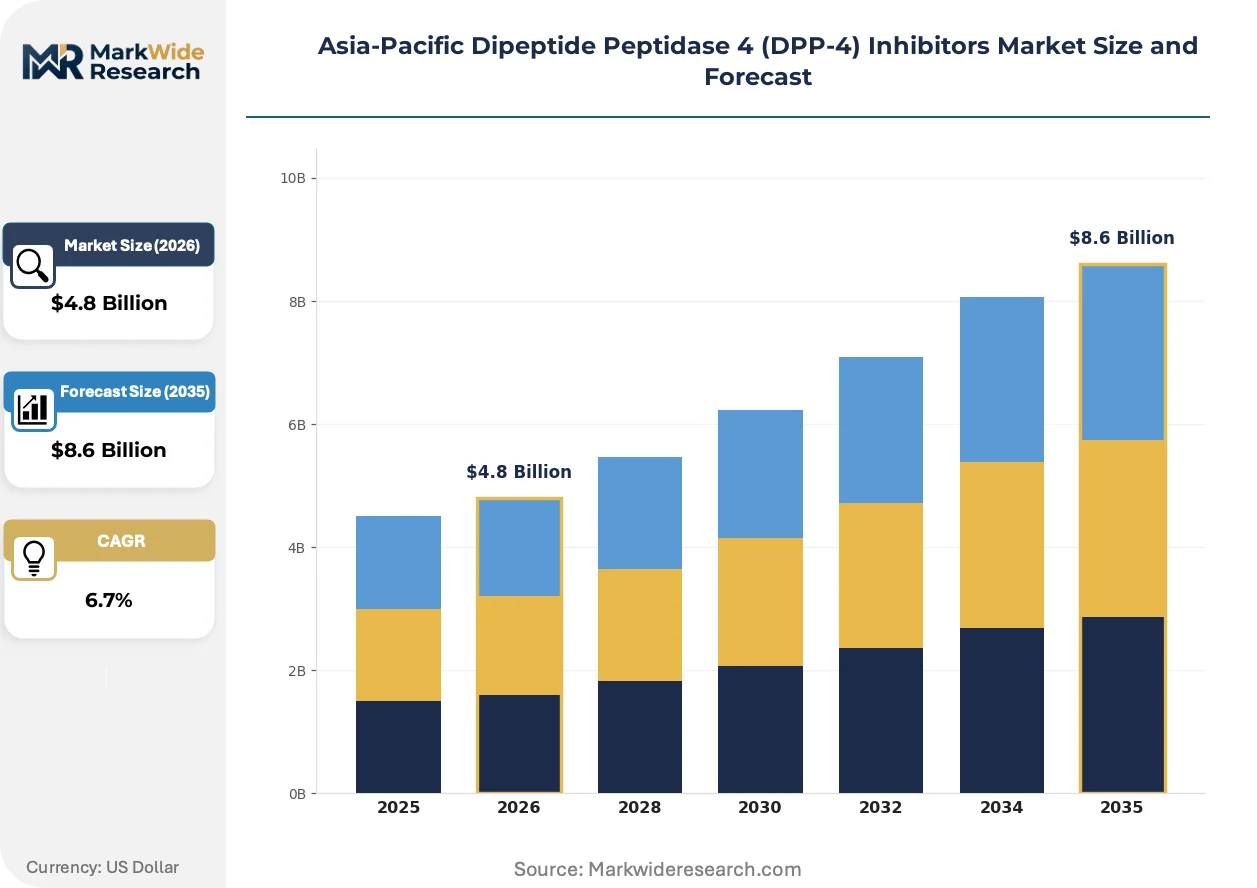
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sitagliptin, Saxagliptin, Linagliptin, Alogliptin Delivery Mode: Oral, Injectable, Tablet, Capsule End User: Hospitals, Clinics, Private Practices, Home Care Therapy Area: Type 2 Diabetes, Metabolic Syndrome, Obesity, Cardiovascular Disease |
| Companies Covered | Merck & Co., Eli Lilly and Company, Novartis AG, AstraZeneca, Boehringer Ingelheim, Takeda Pharmaceutical, Bristol-Myers Squibb, Pfizer Inc., Bayer AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Strategic Shifts
Continuous manufacturing technologies and real-world evidence requirements are converging to compress development cycles while elevating post-market surveillance obligations across Asia-Pacific regulatory jurisdictions.
Continuous direct compression systems are automating tablet production workflows for high-volume DPP-4 inhibitor formulations. Contract manufacturers in Hyderabad and Shanghai are adopting these platforms to reduce batch-to-batch variability and accelerate release timelines. The technology is automating quality assurance protocols that previously required manual intervention, compressing cost structures for generic entrants.
China's NMPA evolving generic consistency evaluation program is mandating bioequivalence demonstrations against reference-listed drugs rather than pharmacokinetic benchmarks alone. This regulatory tightening is forcing reformulation investments among local manufacturers seeking national reimbursement drug list inclusion. Multinational originators are responding by accelerating lifecycle management strategies that emphasize fixed-dose combinations and pediatric extensions.
Hospital procurement consortia in Japan and South Korea are consolidating purchasing authority through regional formulary committees. This buyer concentration is displacing traditional physician-directed prescribing autonomy with centralized therapeutic class reviews. The shift is most visible in Tokyo's metropolitan hospital networks, where endocrinology departments now coordinate glucose-lowering selections through pharmacy and therapeutics committees rather than individual specialist preference.
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Segmentation
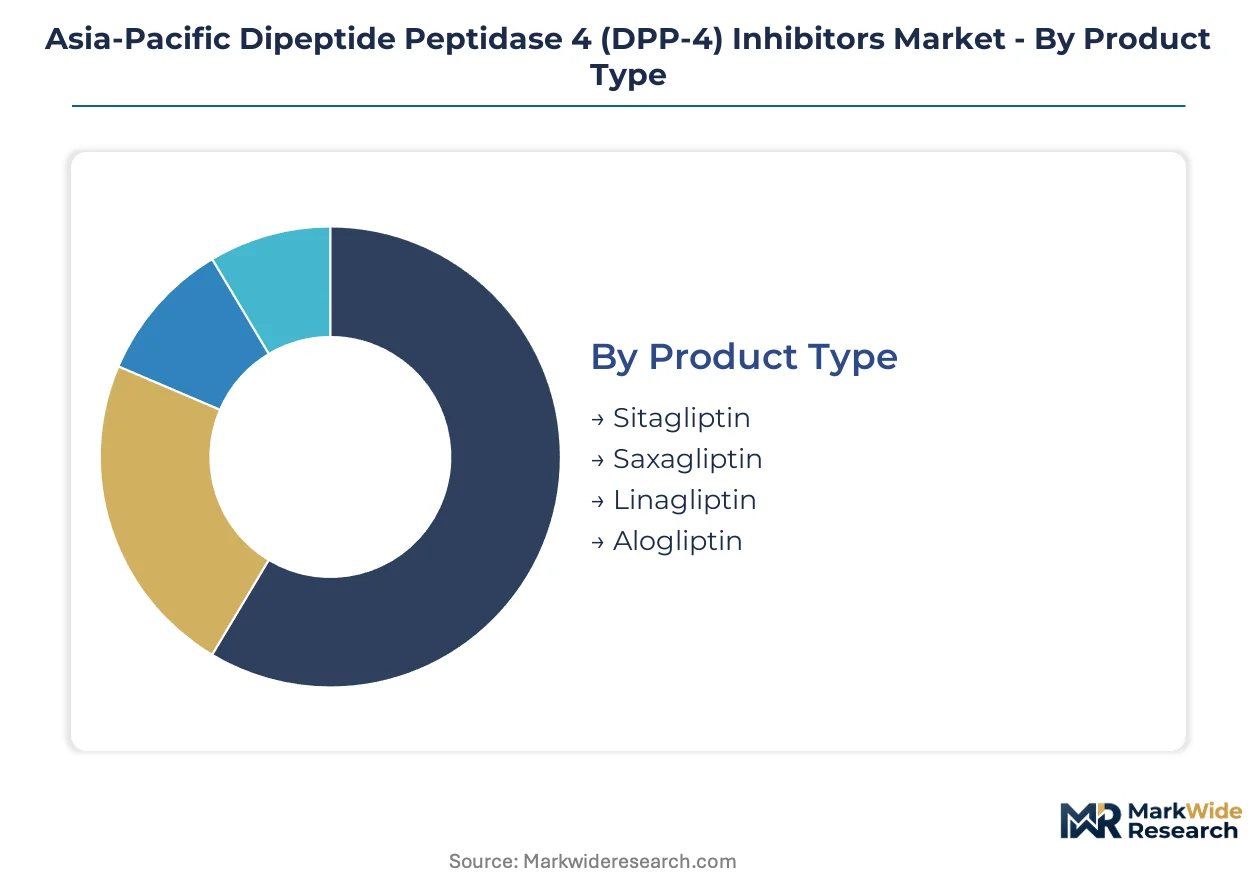
Segmentation of DPP-4 inhibitors across the Asia-Pacific region reveals how formulation chemistry, renal clearance profiles, and reimbursement tiering create distinct competitive battlegrounds. Understanding these divisions illuminates where multinational originators defend premium positioning against local generic substitution.
Product Type:
Customization versus standardization tensions run deepest across molecular architectures, where elimination pathway differentiation commands pricing power in nephrology-heavy prescribing environments.
- Sitagliptin:The catalytic triad-binding mechanism of this first-in-class DPP-4 inhibitor delivers established cardiovascular safety data that hospital formulary committees in Tokyo and Shanghai prioritize. Demand concentrates in China's tier-one cities where volume-based procurement has compressed unit economics, forcing manufacturers toward high-volume, low-margin production models.
- Linagliptin:Predominantly non-renal elimination via hepatic metabolism and biliary excretion eliminates dose adjustment requirements in elderly populations with declining kidney function. Nephrology clinics across Japan's Kansai region and South Korea's Seoul metropolitan area are automating prescribing workflows around this molecular profile.
- Saxagliptin:Active metabolite formation necessitates renal monitoring that fragments adherence in outpatient settings.
- Alogliptin:Pancreatic safety surveillance requirements from Japan's PMDA constrain promotional positioning.
Leading the category by volume: Sitagliptin. Growing fastest: Linagliptin.
Delivery Mode:
Cost tier stratification separates chronic daily administration formats from acute intervention modalities, with reimbursement alignment favoring oral regimens in outpatient diabetes protocols.
- Oral:First-pass metabolism characteristics and gastric pH stability requirements define bioavailability profiles that generic manufacturers in Hyderabad must replicate under CDSCO bioequivalence protocols. Tier-two hospital networks across Indonesia's Java island prioritize oral dispensing for medication adherence programs.
- Tablet:Direct compression manufacturing scales efficiently for high-volume DPP-4 inhibitor production, with contract manufacturers in Shanghai adopting continuous processing to reduce batch release timelines.
- Injectable:Parenteral formulations concentrate in hospital emergency departments managing acute hyperglycemic crises.
- Capsule:Gelatin shell formulations face humidity stability challenges in tropical distribution corridors.
Volume concentration: Oral and tablet formats. Steepest expansion trajectory: Injectable combinations with GLP-1 receptor agonists.
End User:
Customer type fragmentation reflects divergent procurement authority, with centralized hospital purchasing displacing individual physician autonomy in glucose-lowering selections.
- Hospitals:Pharmacy and therapeutics committees in Japan's metropolitan hospital networks now coordinate DPP-4 inhibitor selections through centralized formulary reviews rather than endocrinologist preference. Procurement consortia in Tokyo and Osaka consolidate purchasing power that extracts price concessions from multinational suppliers.
- Clinics:Specialist referral networks in China's tier-one cities concentrate newly diagnosed type 2 diabetes cases ahead of infrastructure deployment in lower-tier urban centers.
- Private Practices:Out-of-pocket payment structures in India's urban corridors create pricing ceilings for premium oral hypoglycemic uptake.
- Home Care:Long-term care facilities face medication management complexity with polypharmacy populations.
Procurement volume leader: Hospitals. Gaining share fastest: Home care segments managing elderly diabetic populations.
Therapy Area:
Maturity gradients separate well-established diabetes protocols from emerging metabolic syndrome applications where clinical evidence requirements delay reimbursement expansion.
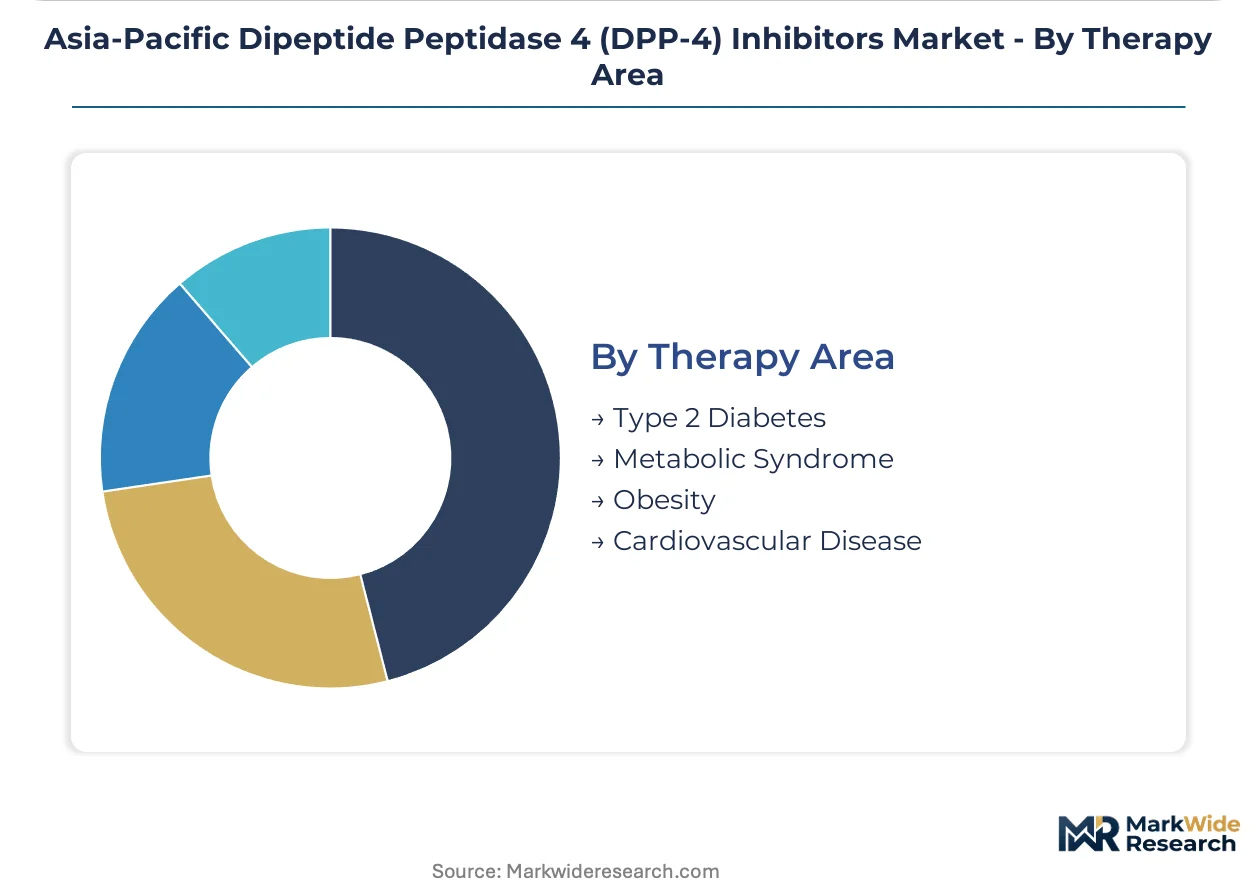
- Type 2 Diabetes:Second-line positioning after metformin intolerance defines standard care pathways that China's national reimbursement drug list codifies. Endocrinology departments prioritize glucose-dependent insulin secretagogues with cardiovascular outcome trial data.
- Cardiovascular Disease:Outcome trial evidence from heart failure populations is reshaping hospital prescribing protocols in South Korea's tertiary centers.
- Metabolic Syndrome:Prediabetes intervention applications face evidence thresholds that NMPA and PMDA have not yet codified for broad reimbursement.
- Obesity:Weight-neutral profiles differentiate DPP-4 inhibitors from sulfonylurea alternatives in bariatric patient management.
Established volume base: Type 2 diabetes. Expanding most quickly: Cardiovascular disease risk modification protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient synthesis for DPP-4 inhibitors clusters in Hyderabad and Shanghai manufacturing corridors, anchoring formulation supply across the Asia-Pacific region. Hospital procurement networks in Tokyo, Seoul, and tier-one Chinese cities drive demand concentration for glucose-dependent insulin secretagogues.
China
Volume-based procurement through the National Healthcare Security Administration compresses multinational pricing while accelerating local generic substitution in Beijing and Shanghai hospital networks. NMPA's generic consistency evaluation program mandates bioequivalence demonstrations that extend registration timelines for originator products. Yangtze River Delta contract manufacturers adopt continuous direct compression systems to reduce batch release timelines for high-volume sitagliptin production.
Japan
Metropolitan hospital networks in Tokyo and Osaka consolidate purchasing authority through pharmacy and therapeutics committees that displace individual endocrinologist prescribing autonomy. PMDA's Sakigake designation accelerates review timelines for innovative fixed-dose diabetes combinations targeting polypharmacy reduction. Kansai region nephrology clinics automate prescribing workflows around linagliptin's non-renal elimination profile for elderly populations with declining kidney function.
India
CDSCO bioequivalence protocols govern generic sitagliptin registration for Hyderabad and Mumbai-based formulation manufacturers seeking export qualification. The PLI scheme for active pharmaceutical ingredients attracts backward integration investments that could reshape regional supply geography for DPP-4 inhibitor raw materials. Maharashtra's public health programs maintain ultra-low sulfonylurea pricing that creates substitution ceilings for premium oral hypoglycemic uptake in price-sensitive segments.
South Korea
Tertiary hospital centers in Seoul prioritize cardiovascular outcome trial data when selecting second-line glucose-lowering therapies for diabetic populations with heart failure comorbidities. MFDS bioequivalence standards align with ICH guidelines while maintaining distinct documentation requirements that fragment parallel submission strategies. Seoul metropolitan procurement consortia extract price concessions from multinational suppliers through centralized therapeutic class reviews.
Indonesia
Rapid urbanization in Surabaya and Bandung concentrates newly diagnosed type 2 diabetes cases ahead of specialist infrastructure deployment in tier-two cities. The national pharmaceutical regulator maintains evolving bioequivalence frameworks that delay generic registration for DPP-4 inhibitor formulations. Java island hospital networks prioritize oral dispensing formats for medication adherence programs in outpatient diabetes management.
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Competitive Environment
Global majors compete with regional champions across distribution infrastructure and hospital formulary access. The vendor base separates into multinational originators defending patent-protected positioning, established generic manufacturers capturing volume-based procurement awards, and emerging local players leveraging cost-advantaged API synthesis. Three archetypes dominate: research-intensive innovators with cardiovascular outcome trial portfolios, high-volume generic specialists with continuous manufacturing platforms, and integrated pharmaceutical groups with captive API supply. Capacity expansion and strategic portfolio diversification toward fixed-dose combinations represent the dominant competitive moves reshaping positioning.
Among research-intensive innovators, Merck & Co. and Eli Lilly and Company occupy positions reflecting distinct strategic emphases. Merck & Co. anchors bulk supply commitments across Southeast Asia through established sitagliptin synthesis infrastructure. Eli Lilly and Company exemplifies portfolio diversification toward differentiated fixed-dose combinations that integrate incretin-based therapies. Takeda Pharmaceutical represents the regional champion archetype with deep hospital formulary relationships dominating Japanese distribution channels.
| Leading Market Players |
|---|
| Merck & Co. |
| Eli Lilly and Company |
| Novartis AG |
| AstraZeneca |
| Boehringer Ingelheim |
| Takeda Pharmaceutical |
| Bristol-Myers Squibb |
| Pfizer Inc. |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Patent-expiry bifurcation between originator sitagliptin and generic alternatives manifests in divergent pricing architectures and supply chain configurations across Asia-Pacific hospital procurement networks. Premium positioning for non-renal elimination pathways commands formulary placement in Japan's Kansai nephrology clinics, while volume-based procurement in China's Yangtze River Delta compresses margins through high-volume, low-unit-cost production models anchored in local API synthesis.
Pricing Analysis
Service-bundling separates cardiovascular outcome trial data packages from unbundled commodity tablet supplies in hospital formulary negotiations. Three-tier pricing structure across premium, standard, and economy levels stratifies by bioequivalence certification tier under NMPA's consistency evaluation program and post-market surveillance commitments. Pricing pressure stems from China's national reimbursement drug list volume-based procurement, which extracts double-digit concessions from multinational suppliers. Public health programs in Maharashtra exhibit highest price sensitivity, while private tertiary centers in Seoul demonstrate lowest sensitivity due to outcome-based reimbursement alignment.
Supply Chain Analysis
Regional distribution centers in Hyderabad and Shanghai operate hub-and-spoke patterns that feed formulation networks across Southeast Asia and East Asia. Active pharmaceutical ingredient synthesis concentrates in India's Hyderabad corridor and China's Yangtze River Delta, drawing from specialized dipeptide analog precursors and catalytic hydrogenation reagents. Single-source vulnerability characterizes the supply base, with batch release timelines tethered to continuous direct compression platform availability. Distribution runs through hospital procurement consortia in Tokyo, Seoul, and tier-one Chinese cities that consolidate purchasing authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where NMPA's generic consistency evaluation program erects barrier-to-entry moats favoring manufacturers with established bioequivalence demonstration capabilities and regulatory affairs infrastructure.
For Market Incumbents: Deepen backward integration into dipeptide analog API synthesis to defend margin position against Hyderabad-based generic entrants capturing volume-based procurement awards. Prioritize certification investment under CDSCO bioequivalence protocols to maintain export qualification for Southeast Asian markets. Anchor capacity in Shanghai continuous manufacturing corridors to compress batch release timelines.
For New Entrants and Emerging Players: Begin with Indonesia's underpenetrated tier-two cities where specialist infrastructure lags behind Surabaya and Bandung diabetes case concentration. Target hospital formulary access through fixed-dose combination development integrating locally manufactured APIs. Pursue licensing arrangements with established Japanese distributors to bypass Takeda's entrenched hospital channel relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated pharmaceutical groups possessing captive API supply given India's PLI scheme catalyst for backward integration investments. Long-term viability favors manufacturers with demonstrated NMPA bioequivalence approval and continuous processing platform deployment. Monitor procurement rule changes in China's national reimbursement drug list as inflection signal for margin compression trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Development | Integrates GLP-1 receptor agonist portfolios to capture obesity-diabetes comorbidity prescribing in Tokyo metropolitan networks. |
| Continuous Manufacturing Scale-Up | Automates quality assurance protocols in Shanghai contract manufacturing to accelerate batch release timelines under NMPA oversight. |
| API Backward Integration | Captures PLI scheme incentives in India's Hyderabad corridor to reshape regional supply geography for dipeptide analog inputs. |
| Regulatory Approval Pathway | Leverages PMDA Sakigake designation to compress review timelines for innovative diabetes combinations in Kansai region. |
| Hospital System Partnership | Secures pharmacy and therapeutics committee placement in Seoul metropolitan procurement consortia through cardiovascular outcome data. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia-Pacific DPP-4 inhibitor market assessment. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors combined with secondary validation from NMPA submissions, PMDA approval databases, CDSCO registration records, and customs import data. Bottom-up patient population modeling and top-down pharmaceutical market sizing provided triangulation checks across the analysis.
Data-stream reconciliation integrated volume-based procurement award tracking with hospital formulary placement databases and API trade flow analysis. Segmentation dimensions included molecular type, elimination pathway, delivery mode, end-user procurement authority, and regional regulatory cluster. CAGRs derived from longitudinal pricing data and volume shipment analysis across the projection horizon. Forecast inputs incorporated bioequivalence approval timelines and continuous manufacturing adoption curves specific to oral hypoglycemic production.
Underlying measurement precision varies by segment; hospital procurement volume data carries tighter precision than private practice prescribing estimates. Forecasts reflect documented assumptions regarding regulatory approval timelines, procurement rule stability, and API supply concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Casein and Casein Derivatives Market
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Amphetamine Drug Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market
Pharmaceutical Ingredients
Global Penicillin Drug Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Oridonin Market
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Encapsulated Salicylic Acid Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market