
 Small-Molecule Injectable Market | 2026-2036
Small-Molecule Injectable Market Size, Share, and Industry Trends Forecast 2026-2036
Small-Molecule Injectable Market Analytics
USP-grade aseptic manufacturing standards are redrawing competitive boundaries for sterile liquid and lyophilized presentations. Pfizer Inc. leverages its global network of certified sterile facilities to supply hospital systems with high-volume injectable antibiotics. Novartis AG anchors its position through specialized cytotoxic manufacturing capabilities for oncology injectables. Merck & Co., Inc. differentiates via end-to-end control of complex synthesis and fill-finish operations for small-molecule parenterals.
Small-molecule injectables comprise chemically synthesized active pharmaceutical ingredients formulated as sterile solutions, lyophilized powders, or suspensions for parenteral administration, typically requiring endotoxin limits below 0.25 EU/mL and particulate control per USP 788. These products serve acute and critical care settings where rapid bioavailability and precise dosing override oral alternatives. Lyophilized injections command premium positioning due to stability advantages and cold-chain flexibility, while intravenous delivery dominates hospital throughput and subcutaneous formats gain traction in home healthcare migration. Oncology therapy areas absorb substantial manufacturing capacity as cytotoxic handling requirements limit qualified production sites.
FDA, EMA, and USP standards collectively govern sterility assurance, container closure integrity, and extractables-leachables profiling for injectable drug products. The FDA's guidance on visible particulates and EMA's Annex 1 revisions for sterile manufacturing are elevating capital requirements for new entrants and forcing legacy facility upgrades. Stakeholders must monitor regulatory divergence between FDA sterility expectations and emerging national standards in priority supply markets to anticipate inspection risks and approval timelines.
Market Dynamics
USP Chapter 797 revisions and FDA sterility guidance are compressing manufacturing capacity while hospital systems simultaneously expand formularies for ready-to-administer presentations. This regulatory tightening against demand pull is fragmenting competitive positioning between legacy facility operators and new entrants.
Growth Catalysts
- Ready-to-administer formulations:Hospital systems are prioritizing pre-filled syringes and premixed bags to reduce compounding errors and pharmacy labor costs. This format preference is pulling manufacturing investment toward aseptic fill-finish lines.
- EMA Annex 1 revisions:The updated sterile manufacturing standards are accelerating facility upgrades across European production sites. Qualified capacity is becoming a scarce asset that incumbent operators can monetize through contract manufacturing premiums.
- Oncology injectable demand:Cytotoxic handling requirements limit qualified production sites to specialized facilities. This supply constraint protects pricing power for manufacturers with certified containment infrastructure.
Market Restraints
- WFI (Water for Injection) system costs:USP-grade water generation and distribution infrastructure requires capital intensity that excludes mid-scale entrants. Distillation and reverse osmosis system validation timelines extend 18-24 months.
- Glass vial supply concentration:Borosilicate tubing and molded vial production clusters in Germany and China create single-source vulnerability. Container closure integrity failures at any major supplier cascade through multiple drug product pipelines.
- Lyophilization capacity scarcity:Freeze-dryer installation and qualification cycles stretch 36-48 months. This equipment bottleneck restricts expansion of stable powder formulations regardless of active pharmaceutical ingredient availability.
Strategic Opportunities
- Subcutaneous home administration:Self-injection devices and smaller-volume presentations are opening ambulatory and home healthcare channels. This format shift captures margin from hospital purchasing committees while reducing infusion center burden.
- India's PLI scheme for pharmaceuticals:Production-linked incentives for active pharmaceutical ingredient and formulation manufacturing are attracting sterile injectable investments. Dedicated industrial parks in Gujarat and Telangana offer integrated utility infrastructure.
- Continuous manufacturing adoption:Real-time release testing integrated with aseptic processing lines is compressing batch release timelines. This technology convergence reduces quarantine inventory and accelerates working capital velocity.
Industry Challenges
- Aseptic processing technician scarcity:ISO 5 cleanroom behavior certification and media fill qualification requirements limit qualified personnel pools. Training curricula at technical institutes lag behind current GMP expectations.
- Container closure integrity validation:Probabilistic leak detection methods and deterministic alternatives require capital investment in helium mass spectrometry or high-voltage leak detection systems. Method selection disputes with regulators delay approval timelines.
- Extractables and leachables profiling:Novel elastomer formulations and coating technologies demand exhaustive compatibility studies. Analytical capacity at qualified contract laboratories is backlogged 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small-Molecule Injectable Market |
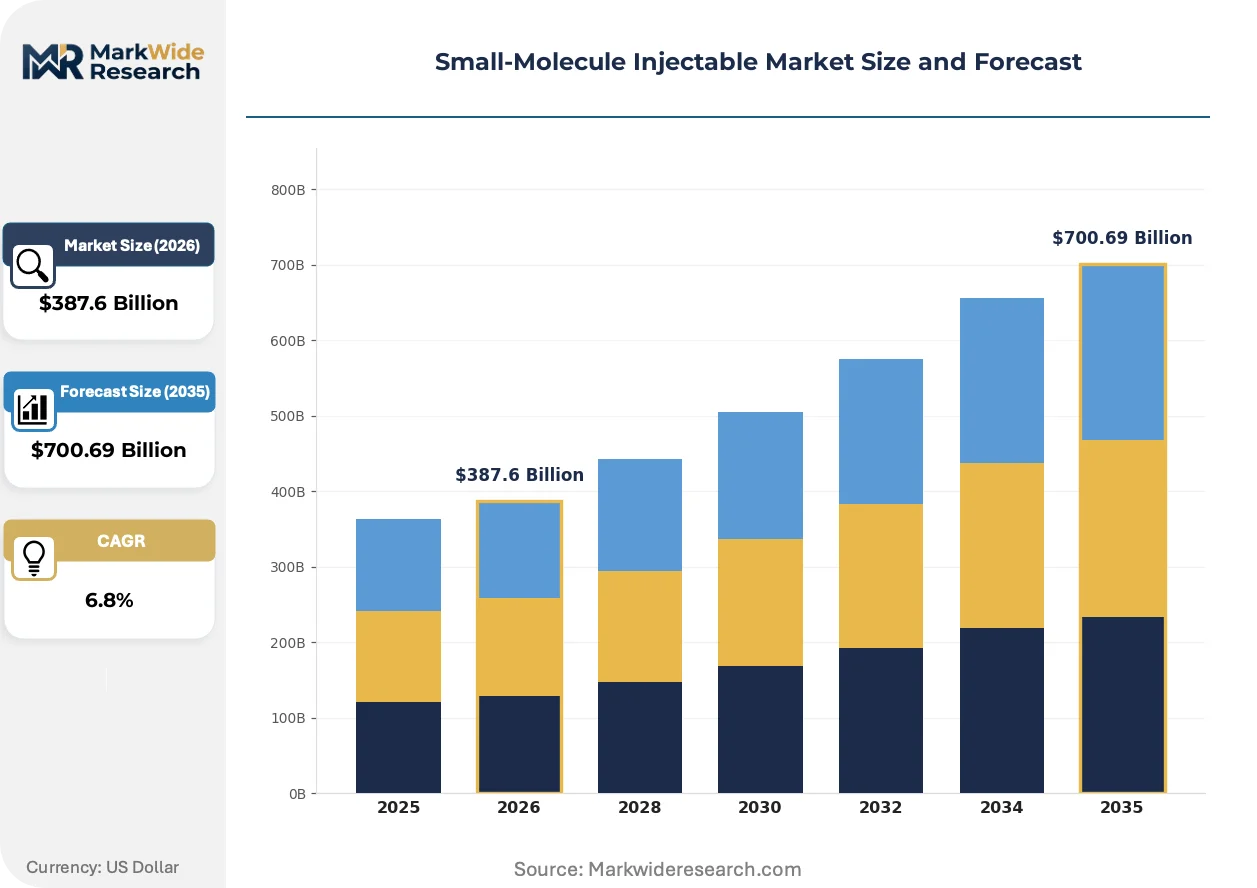
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lyophilized Injections, Solutions, Powders, Suspensions Therapy Area: Oncology, Cardiovascular, Infectious Diseases, Autoimmune Disorders Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Intra-articular End User: Hospitals, Clinics, Home Healthcare, Specialty Pharmacies |
| Companies Covered | Pfizer Inc., Novartis AG, Merck & Co., Inc., AstraZeneca Plc, Johnson & Johnson, F. Hoffmann-La Roche AG, Sanofi S.A., Teva Pharmaceutical Industries Ltd., Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small-Molecule Injectable Market Evolving Landscape
Barrier isolation technology and single-use systems are displacing conventional cleanroom architectures across sterile manufacturing operations. This equipment transition is compressing facility footprints while elevating contamination control assurance.
Restricted access barrier systems (RABS) and isolator technology are displacing traditional Grade A/B cleanroom suites in new facility designs. Large-volume parenteral manufacturers in the United States and Germany are specifying isolator-based filling lines for antibiotic and analgesic production. This displacement is enabling smaller batch sizes with faster changeover, supporting contract manufacturing flexibility for niche oncology products.
FDA guidance on visible particulates and EMA Annex 1 revisions for sterile manufacturing are mandating automated inspection systems and enhanced environmental monitoring. Facility operators must install continuous particle monitoring and rapid microbial detection to satisfy inspector expectations. Small-molecule parenteral manufacturers with legacy manual inspection protocols face capital re-investment or competitive exclusion from hospital formularies.
Hospital purchasing committees are consolidating supplier relationships around manufacturers with integrated fill-finish and device assembly capabilities. This concentration is displacing standalone drug product suppliers who lack pre-filled syringe or auto-injector integration. The shift is most visible in United States health system consolidation, where three-tier pricing structures favor vertically integrated vendors with device design competencies.
Small-Molecule Injectable Market Segmentation
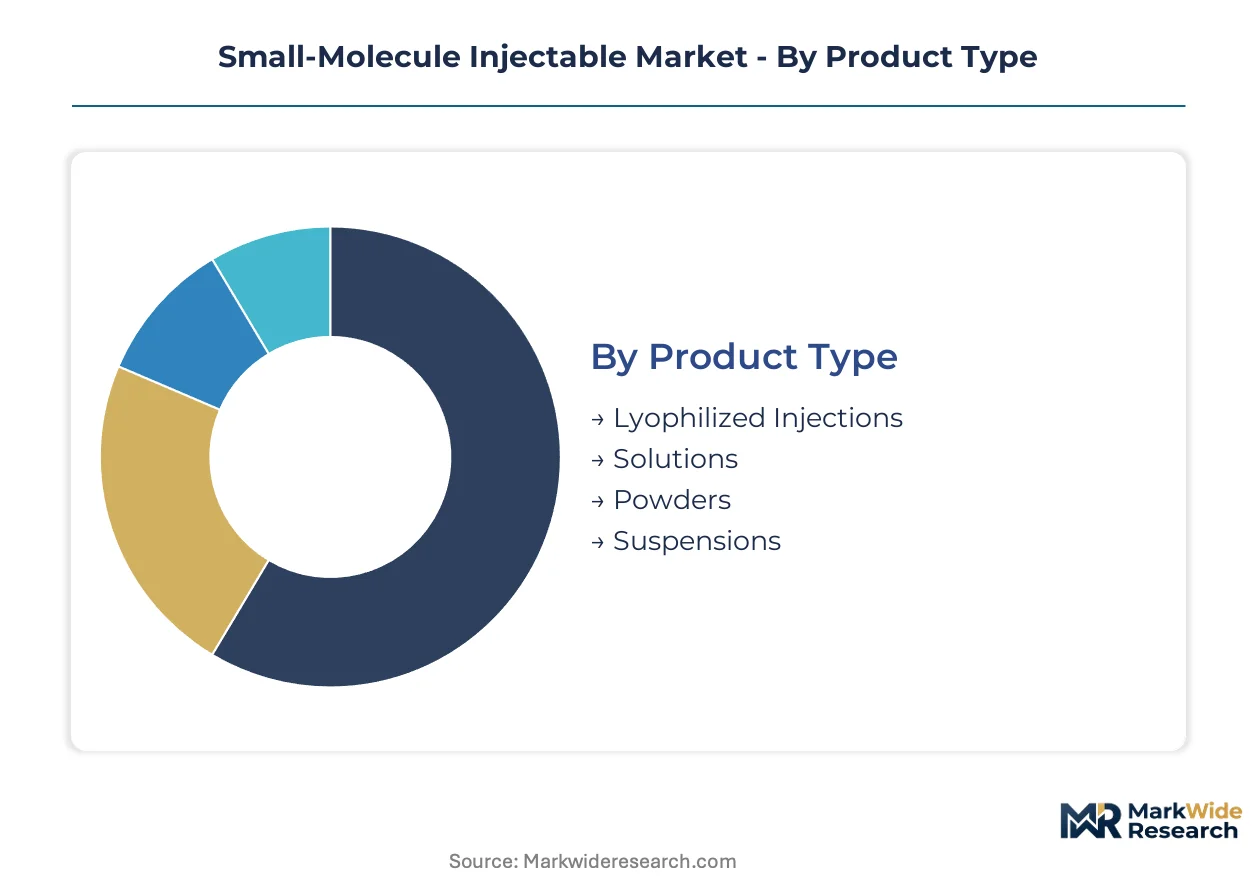
Small-molecule injectables traverse distinct commercial channels based on formulation stability, handling complexity, and administration setting. Segment boundaries determine capital allocation priorities across manufacturing networks.
Product Type:
Channel mix varies sharply by physical state—lyophilized formats flow through specialty distributors with cold-chain flexibility, while ready-to-use solutions penetrate hospital formularies directly.
- Lyophilized Injections:Freeze-dried powders requiring reconstitution before administration deliver extended shelf stability and reduced cold-chain dependency. Demand concentrates in oncology and emergency medicine settings across Germany and the United States, where pharmacy compounding labor costs justify premium positioning. By volume, Solutions lead. By growth pace, Lyophilized Injections are expanding most quickly.
- Solutions:Ready-to-administer sterile liquids eliminate reconstitution steps and reduce medication errors in acute care. Hospital systems in China prioritize this format for high-throughput antibiotic and analgesic protocols.
- Powders:Bulk sterile powders for extemporaneous compounding serve institutional pharmacy operations with custom dosing flexibility.
- Suspensions:Particulate formulations for depot delivery and modified release target intra-articular and intramuscular applications.
Cost tiering separates premium lyophilized presentations from commodity solution volumes.
Therapy Area:
Application intensity drives manufacturing qualification requirements—cytotoxic handling elevates oncology above standard aseptic processing.
- Oncology:Cytotoxic small-molecule injectables require specialized containment infrastructure and operator certification. Manufacturing capacity concentrates in Switzerland, Germany, and select United States sites with barrier isolation technology. By patient volume, Infectious Diseases leads. By manufacturing margin, Oncology commands the steepest expansion trajectory.
- Cardiovascular:Emergency thrombolytics and antiarrhythmics demand rapid availability through hospital crash carts and cath labs.
- Infectious Diseases:High-volume antibiotic and antiviral injectables sustain continuous fill-finish operations across large-scale parenteral facilities.
- Autoimmune Disorders:Immunosuppressive and anti-inflammatory injectables serve infusion center and home administration protocols.
Supply concentration in certified cytotoxic sites protects oncology pricing power against infectious disease commoditization.
Delivery Mode:
Customer type stratification—hospital purchasing committees versus home healthcare payers—shapes route selection and device integration requirements.
- Intravenous:Direct vascular delivery dominates hospital throughput for antibiotics, oncology, and critical care medications. United States health systems specify IV bags with integrated closed-system transfer devices.
- Subcutaneous:Self-administration formats capture ambulatory and home healthcare channels through pre-filled syringes and auto-injectors. By procedure volume, Intravenous leads. By channel shift velocity, Subcutaneous is gaining share fastest.
- Intramuscular:Depot formulations for sustained release target institutional and public health vaccination programs.
- Intra-articular:Joint-space injections for localized anti-inflammatory delivery serve orthopedic and rheumatology clinics.
Margin structures favor subcutaneous device-integrated presentations over commodity IV bags.
End User:
Maturity gradients separate consolidated hospital networks from fragmented home healthcare expansion.
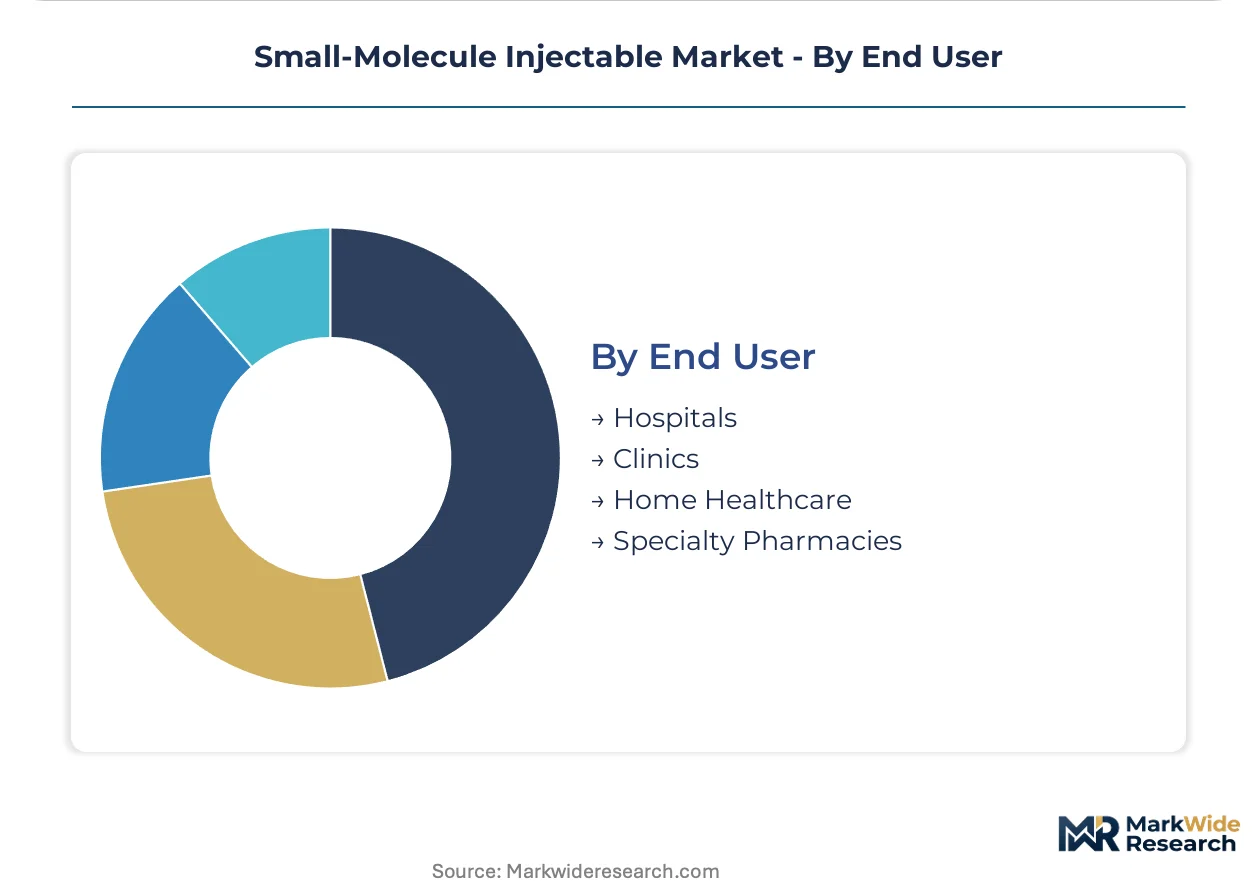
- Hospitals:Integrated delivery networks consolidate formulary decisions around ready-to-administer formats and sole-source contracting. United States three-tier pricing structures reward manufacturers with vertical device capabilities.
- Clinics:Outpatient infusion and injection centers prioritize scheduling efficiency through rapid-preparation presentations.
- Home Healthcare:Self-injection protocols expand reimbursement eligibility for subcutaneous oncology and autoimmune therapies. By revenue concentration, Hospitals dominate. By enrollment growth, Home Healthcare climbs the fastest.
- Specialty Pharmacies:Limited distribution networks manage cold-chain logistics for temperature-sensitive biologics and lyophilized small molecules.
Procurement centralization in hospital systems contrasts with patient-direct dispensing through specialty pharmacy channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified sterile manufacturing capacity clusters in the United States, Germany, China, and Switzerland, with emerging investments in India and the United Kingdom expanding qualified production footprints. Hospital formulary expansion and regulatory tightening are pulling capacity toward these jurisdictions.
United States
FDA sterility guidance and USP Chapter 797 revisions are compressing legacy facility operations while hospital systems expand ready-to-administer formularies. The agency's updated visible particulate standards mandate automated inspection system upgrades. Boston and Research Triangle Park host concentrated contract manufacturing clusters where barrier isolation technology is displacing conventional cleanroom architectures.
Germany
EMA Annex 1 revisions are accelerating facility upgrades across Bavaria and Baden-Württemberg, where borosilicate glass vial production concentrates. Industrial parks around Frankfurt and Stuttgart integrate dedicated WFI generation infrastructure. Qualified lyophilization capacity here commands contract manufacturing premiums as freeze-dryer installation cycles stretch 36-48 months.
China
NMPA alignment with international GMP standards is elevating capital requirements for domestic sterile injectable producers. Yangtze River Delta and Pearl River Delta industrial corridors are attracting dedicated aseptic manufacturing investments. Shanghai and Suzhou clusters specialize in high-volume antibiotic fill-finish operations for hospital system procurement.
Switzerland
Swissmedic oversight of cytotoxic handling certification protects specialized oncology injectable manufacturing margins. Basel and Zurich regions concentrate containment infrastructure for potent compound processing. This qualified capacity scarcity insulates pricing power against commoditization pressures in standard aseptic segments.
India
CDSCO regulatory convergence with FDA and EMA standards is channeling PLI scheme incentives toward sterile injectable investments. Gujarat and Telangana pharmaceutical parks offer integrated utility infrastructure for USP-grade water generation. Hyderabad and Ahmedabad clusters are expanding dedicated isolator-based filling lines for export markets.
Small-Molecule Injectable Market Competitive Landscape
Concentration sits with integrated pharmaceutical conglomerates possessing certified sterile facilities and device assembly capabilities. Tiered competitive positioning separates legacy operators with barrier isolation infrastructure from mid-scale entrants facing 18-24 month WFI system validation timelines. Three archetypes dominate: global diversified majors with end-to-end fill-finish control, specialized cytotoxic manufacturers with containment expertise, and contract manufacturing organizations with flexible batch-size capabilities. Dominant competitive moves include facility upgrade investments to satisfy EMA Annex 1 and FDA sterility expectations, and strategic partnerships with device designers for pre-filled syringe integration.
Among Swiss and German pharmaceutical conglomerates, F. Hoffmann-La Roche AG and Novartis AG exemplify the cytotoxic-specialized archetype with certified containment infrastructure for oncology injectables. Pfizer Inc. occupies a position representing scale-driven, vertically integrated fill-finish operations across multiple therapeutic categories. These three anchors illustrate how regulatory qualification depth and device integration capabilities determine hospital formulary access and contract manufacturing premiums.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Merck & Co., Inc. |
| AstraZeneca Plc |
| Johnson & Johnson |
| F. Hoffmann-La Roche AG |
| Sanofi S.A. |
| Teva Pharmaceutical Industries Ltd. |
| Fresenius Kabi AG |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with certified sterile manufacturers lock in supply access and price visibility for hospital systems navigating FDA sterility guidance and USP Chapter 797 compliance costs. These agreements tether pricing to qualification depth rather than commodity API costs, embedding regulatory certification as the primary value driver.
Pricing Analysis
EMA Annex 1 revisions dictate the pricing tier structure across European sterile injectable markets. Three-tier pricing structure across premium, standard, and economy levels separates isolator-based oncology manufacturers from conventional cleanroom operators and commodity antibiotic suppliers. Pricing pressure stems from WFI system validation timelines extending 18-24 months, which excludes mid-scale entrants and compresses margins in the standard tier. Hospital purchasing committees exhibit lowest price sensitivity for cytotoxic containment-certified products, while infectious disease injectables face commoditization through volume tendering.
Supply Chain Analysis
Quarantine inventory cycles stretching 36-48 months for lyophilization equipment constrain working capital velocity across sterile manufacturing networks. Borosilicate glass vial production draws from Germany and China, while qualified aseptic fill-finish capacity centers on the United States, Switzerland, and India. Single-source vulnerability in German tubing supply creates cascade risk through multiple drug product pipelines. Distribution runs through specialty distributors for lyophilized formats and direct hospital contracting for ready-to-use solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologic and biosimilar substitution threatens small-molecule injectable volume retention, forcing incumbents to defend through formulation innovation and device integration that biologics cannot easily replicate.
For Market Incumbents: Secure isolator-based containment certification ahead of EMA Annex 1 enforcement waves to maintain oncology pricing premiums against commoditization. Backward integration into pre-filled syringe assembly capabilities captures margin from hospital formulary consolidation. Barrier isolation technology investment defends against emerging Indian contract manufacturers leveraging PLI scheme incentives. For New Entrants and Emerging Players: Lead with subcutaneous home administration formats where self-injection device integration opens ambulatory channels underserved by legacy hospital-focused suppliers. India's Gujarat and Telangana pharmaceutical parks offer the most penetrable geography for greenfield sterile facilities with integrated WFI infrastructure. Target contract manufacturing premiums for niche oncology products requiring specialized containment. For Investors and Strategic Acquirers: Swiss and German cytotoxic-specialized manufacturers with certified containment infrastructure represent the priority acquisition archetype for long-term viability across the 5-10 year window. CDSCO regulatory convergence in India signals emerging capacity competition that will reshape contract manufacturing premiums. Watch for FDA sterility guidance enforcement variance as the inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Deployment | EMA Annex 1 compliance elevates barrier isolation as mandatory for European oncology supply. |
| Pre-filled Syringe Integration | Hospital formulary consolidation rewards manufacturers with in-house device assembly capabilities. |
| Lyophilization Capacity Expansion | Freeze-dryer scarcity protects pricing power for stable powder formulations in cold-chain-limited markets. |
| India PLI Scheme Utilization | CDSCO-aligned facilities in Gujarat and Telangana capture export share from legacy European sites. |
| Continuous Manufacturing Adoption | Real-time release testing compresses batch quarantine timelines and accelerates working capital turns. |
Research Methodology
Cross-validation between primary interviews with sterile manufacturing executives, hospital formulary directors, and regulatory affairs specialists and secondary validation through FDA 483 observations, EMA inspection reports, and USP Chapter revision drafts anchors the qualitative findings. Bottom-up triangulation across facility capacity databases and top-down reconciliation with pharmaceutical trade flow data ensures segmentation integrity.
Sensitivity analysis across dosage form, therapy area, administration route, and regional regulatory cluster dimensions tests forecast robustness over the projection horizon. CAGRs derive from modeled capacity utilization rates, regulatory compliance cost trajectories, and hospital procurement pattern shifts. Forecast inputs incorporate isolator technology adoption curves and PLI scheme incentive allocation timelines.
The analysis sits within stated boundaries; outcomes outside sustained FDA-EMA regulatory convergence or abrupt glass vial supply disruption would require recalibration. Forecasts reflect documented assumptions regarding sterility guidance enforcement intensity and hospital consolidation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Ibuprofen Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Pharmaceutical Indicator Strips Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Medicinal Chemistry for Drug Discovery Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Pharmaceutical Desiccants Market
Pharmaceutical Ingredients
Pharmaceutical Grade Sodium Carbonate Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Amphetamine Drug Market
Pharmaceutical Ingredients
Oral Transmucosal Drugs Market
Pharmaceutical Ingredients
Fixed-Dose Combination Drugs Market