
 Oral Doxycycline Hyclate Market | 2026-2036
Oral Doxycycline Hyclate Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Doxycycline Hyclate Market Analysis
Hospital procurement groups is reorganizing demand patterns across the Oral Doxycycline Hyclate landscape, pulling volume away from fragmented retail channels toward centralized tender systems. Pfizer leverages its vertical integration across API and finished dose to sustain supply security for institutional buyers. Teva Pharmaceutical Industries anchors its position through broad generic portfolio breadth, while Sun Pharmaceutical competes on cost-engineered manufacturing from its Indian base. Dr. Reddy's Laboratories differentiates via regulatory dossier depth across multiple geographies.
Oral doxycycline hyclate is a semisynthetic tetracycline antibiotic formulated as the hyclate salt for enhanced aqueous solubility and gastric stability, typically dosed at 100 mg for systemic bacterial infections. The compound functions primarily as a protein synthesis inhibitor targeting the 30S ribosomal subunit, with applications spanning respiratory, dermatological, and vector-borne disease protocols. Tablet formulations dominate current volume due to manufacturing scalability and extended shelf stability, while Lyme Disease therapy represents the fastest-expanding clinical application as endemic regions widen across North American and European geographies. Community Pharmacies channel distribution maintains the widest margin pool through direct patient access and insurance reimbursement capture.
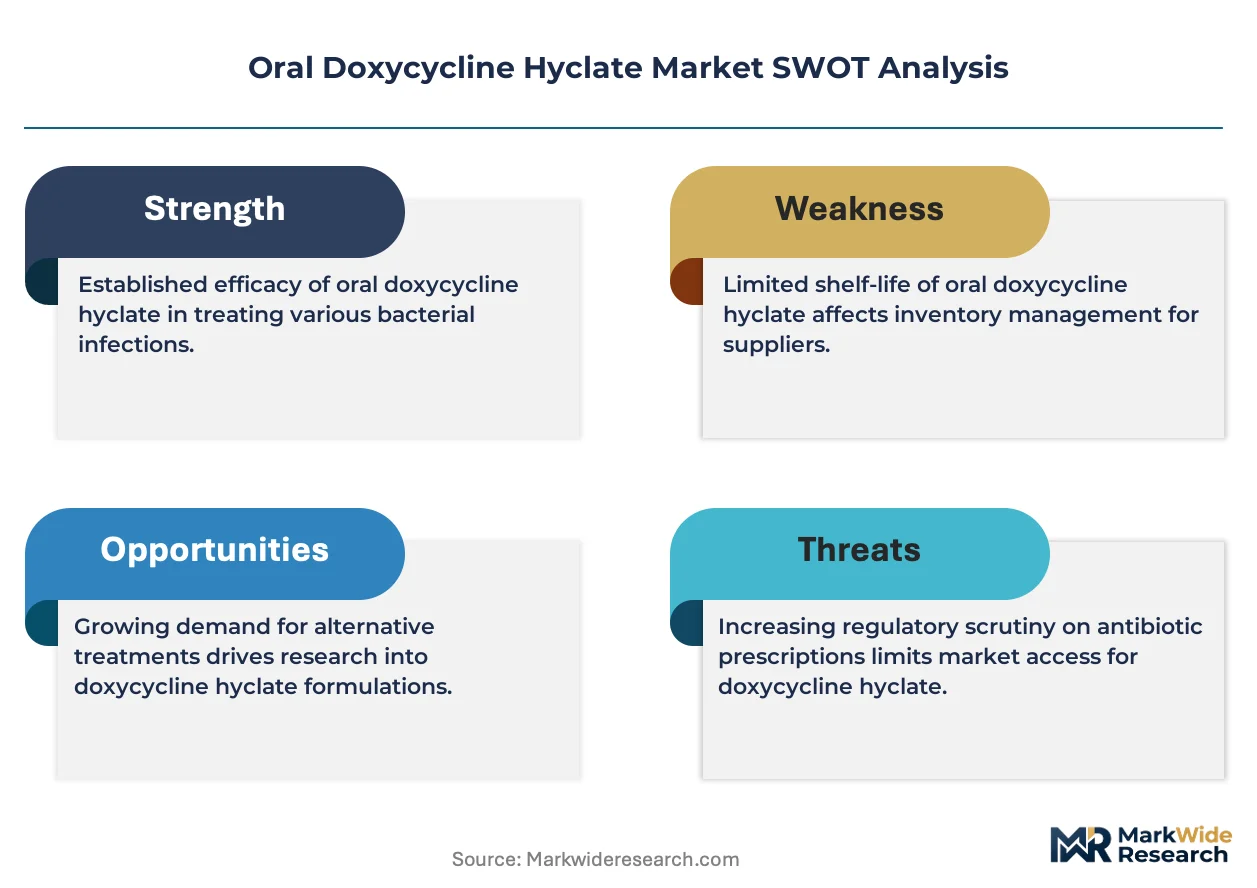
FDA bioequivalence requirements and EMA GMP inspections shape manufacturer compliance burdens, with India's CDSCO aligning domestic standards to ICH frameworks for export market access. The EPA monitors tetracycline discharge from API synthesis facilities, pressuring environmental remediation investments at production sites. Stakeholders must monitor evolving FDA guidance on nitrosamine impurity thresholds and corresponding reformulation timelines.
Market Dynamics
Hospital procurement consolidation is compressing margin pools across the Oral Doxycycline Hyclate landscape, displacing fragmented retail pharmacy purchasing with centralized tender systems that extract volume discounts from manufacturers.
Growth Catalysts
- EMA GMP inspection alignment:India's CDSCO harmonizing domestic standards to ICH frameworks accelerates export market access for API-to-finished-dose manufacturers targeting European hospital tenders.
- Lyme Disease protocol expansion:Vector-borne disease endemic zones widening across Minnesota, Wisconsin, and New York state health systems are pulling prophylactic and therapeutic demand into institutional procurement channels.
- Tablet formulation stability:Extended shelf-life characteristics of hyclate salt tablets reduce cold-chain infrastructure requirements, enabling distribution to rural health posts in Rajasthan and Uttar Pradesh.
Market Restraints
- API synthesis environmental compliance:EPA tetracycline discharge monitoring at fermentation facilities forces wastewater remediation capex that squeezes cost-competitive Indian exporters.
- Generic substitution ceiling:FDA tightened bioequivalence standards for tetracyclines create dossier resubmission burdens that freeze marginal generic applicants from formulary access.
- Photodegradation instability:Doxycycline's light-sensitive molecular structure necessitates amber packaging and controlled storage, adding logistics complexity for tropical climate distribution.
Strategic Opportunities
- Sub-Saharan Africa malaria co-treatment protocols:WHO prequalification pathways for doxycycline as Plasmodium falciparum prophylaxis open institutional procurement channels in Kenya, Nigeria, and Ghana national health systems.
- Community pharmacy clinic integration:Retail chains embedding point-of-care diagnostic capabilities for tick-borne disease are capturing prescription volume before hospital referral.
- Continuous manufacturing technology:Direct compression and hot-melt extrusion convergence reduces batch-to-batch variability, cutting FDA review timelines for supplemental new drug applications.
Industry Challenges
- Nitrosamine impurity detection protocols:FDA guidance requiring reformulation timelines for N-nitrosodimethylamine thresholds forces manufacturers to validate new synthetic routes under accelerated regulatory pressure.
- Multiparametric bioequivalence study design:Complex pharmacokinetic endpoint requirements for tetracycline class generics demand specialized clinical research organization capabilities that concentrate in Hyderabad and Mumbai.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Doxycycline Hyclate Market |
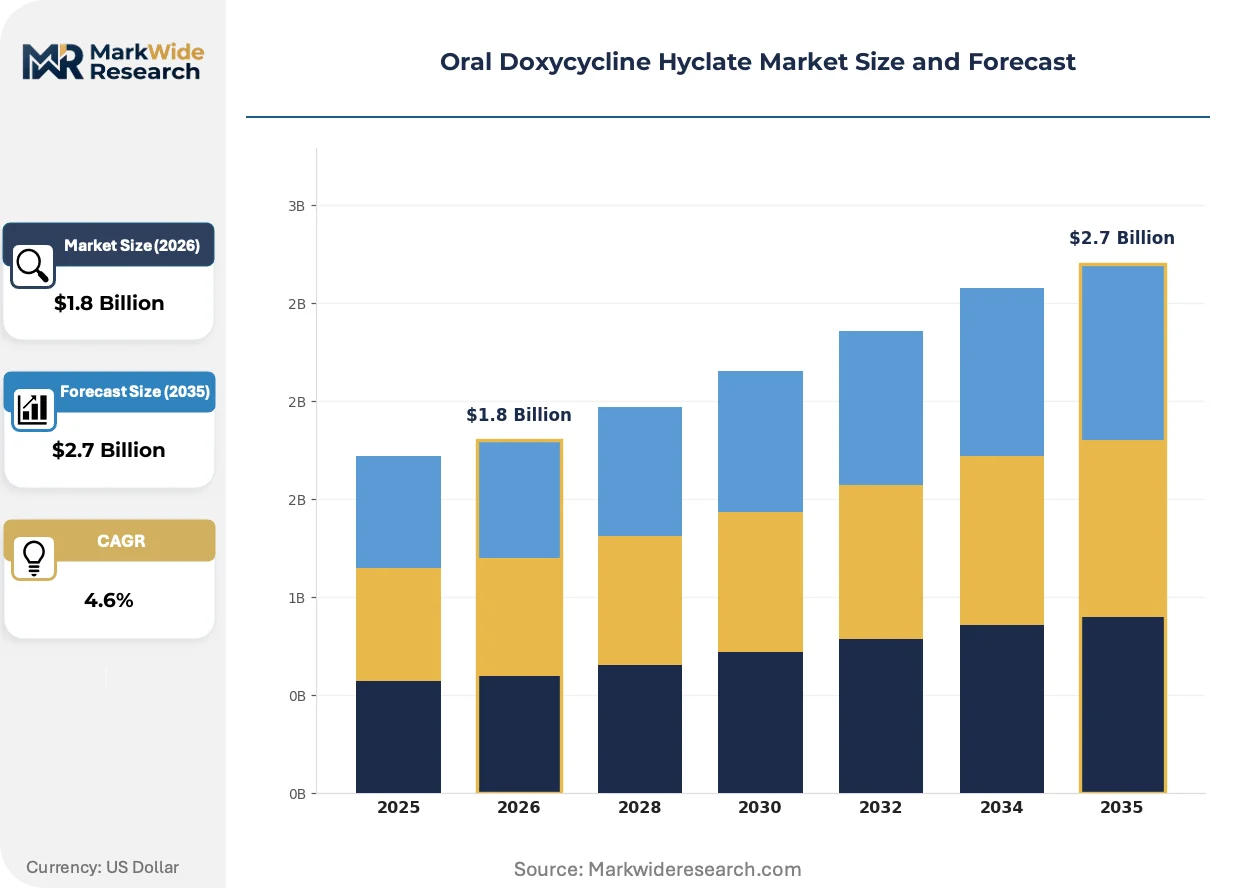
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Syrup, Suspension, Powder Therapy Area: Respiratory Infections, Skin Disorders, Sexually Transmitted Diseases, Urinary Tract Infections, Lyme Disease End User: Hospitals, Specialty Clinics, Community Pharmacies, Research Laboratories, Long-Term Care Facilities Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales, Institutional Sales |
| Companies Covered | Pfizer, Teva Pharmaceutical Industries, Mylan, Sun Pharmaceutical, Lupin, Amneal Pharmaceuticals, Alembic Pharmaceuticals, Cipla, Dr. Reddy's Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Doxycycline Hyclate Market Emerging Trajectories
Reformulation science and procurement digitization are splitting competitive advantage between cost-engineered commodity supply and regulatory-premium positioning across the Oral Doxycycline Hyclate landscape.
Modified-release tablet technologies are bifurcating the market between immediate-release generics and gastroretentive formulations that reduce dosing frequency. Hospital systems in Texas and Florida are piloting once-daily 200 mg extended-release protocols for outpatient cellulitis management. This technology is compressing the therapeutic window advantage of branded alternatives while forcing generic manufacturers to choose between bioequivalence study investment and commodity volume positioning.
REACH authorization requirements for tetracycline API intermediates are tightening supplier qualification burdens across European manufacturing networks. ECHA substance evaluation dossiers now mandate full supply chain disclosure for 4-epianhydrotetracycline impurity controls. German and French hospital procurement coalitions are responding by consolidating supplier lists to pre-qualified Indian manufacturers with demonstrated EMA inspection histories.
Direct-to-patient digital pharmacy platforms are disintermediating traditional wholesale distribution for chronic Lyme prophylaxis prescriptions. Telehealth-integrated dispensaries in Massachusetts and Connecticut are capturing recurring 100 mg tablet demand through subscription models that bypass retail pharmacy fulfillment. This channel rotation is most visible in northeastern US states where tick exposure risk awareness campaigns have elevated patient-initiated consultation rates.
Oral Doxycycline Hyclate Market Segmentation
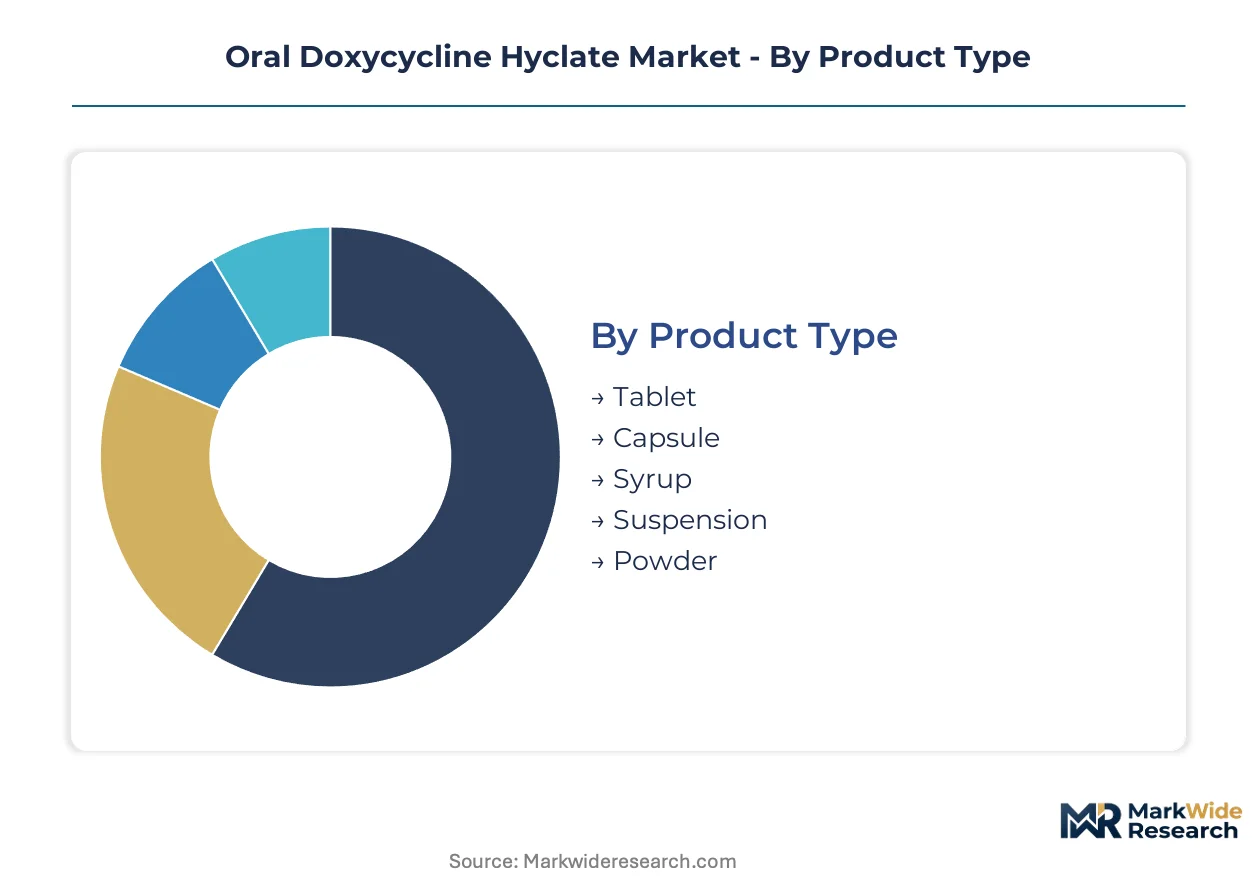
Oral doxycycline hyclate demand fragments across formulation physics, clinical protocols, and procurement channel economics. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that shape manufacturer positioning strategies.
Product Type:
Domestic consumption in India and the United States favors tablet formats for supply chain simplicity, while export markets to Sub-Saharan Africa and Southeast Asia pull suspension and powder formats for pediatric and rural deployment.
- Tablet:Hyclate salt compressed into immediate-release or modified-release matrices dominates institutional tenders. Minnesota and Wisconsin state health systems specify 100 mg tablets for Lyme Disease prophylaxis protocols.
- Capsule:Gelatin-encapsulated formulations serve patients with tablet dysphagia. Demand concentrates in long-term care facilities across Florida and Arizona where geriatric populations require alternative administration routes.
- Syrup:Liquid pediatric formulations face stability challenges from photodegradation. Amber packaging requirements add logistics cost for tropical climate distribution to Nigeria and Ghana.
- Suspension:Reconstitutable powder for oral suspension enables cold-chain-free distribution to Rajasthan and Uttar Pradesh rural health posts.
- Powder:Bulk API-in-bottle formats support compounding pharmacies and veterinary crossover applications with minimal formulation overhead.
Tablet holds the largest share; momentum sits with modified-release formats as Texas and Florida hospital systems pilot once-daily 200 mg cellulitis protocols.
Therapy Area:
Cost tier stratification separates acute infection management from chronic prophylaxis, with vector-borne applications commanding premium positioning through protocol specificity.
- Lyme Disease:Prophylactic and therapeutic protocols for Borrelia burgdorferi infection are expanding across Minnesota, Wisconsin, and New York state health systems as endemic zones widen. Massachusetts and Connecticut telehealth platforms capture recurring prescriptions through subscription models.
- Respiratory Infections:Community-acquired pneumonia and atypical bronchitis protocols drive volume through community pharmacy channels. Seasonal demand fluctuation in northern US states creates inventory planning complexity.
- Skin Disorders:Acne vulgaris and rosacea applications compete with topical alternatives. Dermatology clinics in Florida and California favor 40 mg modified-release formulations for reduced phototoxicity profiles.
- Sexually Transmitted Diseases:Chlamydia trachomatis protocols anchor public health procurement in Kenya and Nigeria national health systems.
- Urinary Tract Infections:Second-line positioning behind fluoroquinolones limits volume to resistant-strain scenarios and patient-specific contraindications.
Respiratory Infections holds the largest share; Lyme Disease is climbing the fastest as patient-initiated consultation rates surge in northeastern US states.
End User:
Customer type determines procurement mechanics, with institutional buyers extracting volume discounts and retail channels preserving margin through insurance reimbursement capture.
- Hospitals:Centralized tender systems in Texas and Florida procurement coalitions displace fragmented purchasing with formulary consolidation.
- Community Pharmacies:Direct patient access and insurance reimbursement capture maintain the widest margin pool across the distribution landscape.
- Specialty Clinics:Dermatology and infectious disease practices in California and New York prescribe branded modified-release alternatives for differentiation.
- Long-Term Care Facilities:Geriatric dosing protocols favor liquid and capsule formats for administration compliance in Florida and Arizona facilities.
- Research Laboratories:Investigational use and bioequivalence study supply concentrate in Hyderabad and Mumbai CRO clusters.
Community Pharmacies holds the largest share; momentum sits with Hospitals as procurement consolidation accelerates.
Distribution Channel:
Volume scale separates high-throughput institutional flows from fragmented retail fulfillment, with digital platforms emerging as a distinct margin-compression vector.
- Hospital Pharmacies:Captive dispensing within integrated delivery networks in Texas and Florida eliminates wholesale markup.
- Retail Pharmacies:Chain and independent operators in Massachusetts and Connecticut face disintermediation pressure from telehealth-integrated dispensaries.
- Online Pharmacies:Direct-to-patient platforms for chronic Lyme prophylaxis bypass traditional wholesale distribution in northeastern US states.
- Institutional Sales:Direct manufacturer contracts with Kenya, Nigeria, and Ghana national health systems for WHO prequalification pathways.
- Direct Sales:Compounding pharmacy and veterinary supply relationships with minimal intermediary economics.
Retail Pharmacies holds the largest share; Online Pharmacies is gaining share fastest as subscription models capture recurring demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API-to-finished-dose integration concentrates manufacturing leverage in India, while hospital procurement consolidation in the United States and European tender harmonization reshape demand geography. Regulatory alignment pressures are fragmenting competitive access across major markets.
United States
Minnesota, Wisconsin, and New York state health systems are expanding Lyme Disease prophylactic protocols as endemic zones widen. FDA tightened bioequivalence standards for tetracyclines create dossier resubmission burdens that freeze marginal generic applicants. Massachusetts and Connecticut telehealth-integrated dispensaries capture recurring 100 mg tablet demand through subscription models bypassing retail pharmacy.
Germany
Hospital procurement coalitions in North Rhine-Westphalia and Bavaria consolidate supplier lists to pre-qualified manufacturers with demonstrated EMA inspection histories. ECHA substance evaluation dossiers mandate full supply chain disclosure for 4-epianhydrotetracycline impurity controls under REACH authorization. German institutional buyers extract volume discounts through centralized tender systems displacing fragmented purchasing.
India
Domestic API-to-finished-dose integration supports cost-competitive export positioning from Hyderabad and Mumbai CRO clusters. CDSCO alignment with ICH frameworks accelerates European hospital tender access for manufacturers with EMA GMP inspection records. Rajasthan and Uttar Pradesh rural health posts pull reconstitutable powder formulations enabling cold-chain-free distribution.
United Kingdom
Lyme Disease patient-initiated consultation rates surge through digital pharmacy platforms in Greater London and Southeast England. MHRA post-Brexit regulatory divergence from EMA creates parallel dossier requirements for tetracycline generics. NHS procurement frameworks favor manufacturers with demonstrated UK-specific bioequivalence study capabilities.
Brazil
ANVISA pharmaceutical regulator harmonization with ICH standards opens institutional procurement pathways for WHO prequalified doxycycline suppliers. São Paulo and Rio de Janeiro state health systems anchor demand for respiratory infection protocols through community pharmacy channels. Brazilian manufacturers face EPA-aligned environmental discharge monitoring pressures at API synthesis facilities.
Oral Doxycycline Hyclate Market Vendor Landscape
Concentration sits with vertically integrated pharmaceutical conglomerates and cost-engineered Indian generic specialists. Three strategic archetypes dominate: API-to-finished-dose integrated multinationals, broad-portfolio generic houses, and regulatory dossier specialists. Competitive moves center on formulary consolidation capture and EMA inspection history leverage.
Within the integrated multinational tier, Pfizer anchors supply security positioning through captive API production. Teva Pharmaceutical Industries and Sun Pharmaceutical exemplify divergent scale strategies—Teva through broad generic portfolio breadth, Sun through cost-engineered manufacturing from its Indian base. Dr. Reddy's Laboratories occupies a regulatory specialist position via dossier depth across multiple geographies.
| Leading Market Players |
|---|
| Pfizer |
| Teva Pharmaceutical Industries |
| Mylan |
| Sun Pharmaceutical |
| Lupin |
| Amneal Pharmaceuticals |
| Alembic Pharmaceuticals |
| Cipla |
| Dr. Reddy's Laboratories |
| Others |
Supply Flow & Price Mechanics
Ninety-day API inventory buffers at Indian fermentation facilities now determine margin capture for European hospital tenders, linking supply-chain depth directly to pricing power in institutional procurement channels. This inventory-to-tender dynamic separates manufacturers with backward-integrated API production from formulation-only competitors facing volatile input costs.
Pricing Analysis
FDA bioequivalence standards dictate the pricing tier structure across oral doxycycline hyclate supply, with EMA-inspected manufacturers commanding premium positioning against CDSCO-only suppliers. Pricing stratifies across GMP-certified premium, ICH-aligned standard, and domestic-economy tiers based on regulatory dossier depth and volume commitment scale. Cost compression in the economy tier is intensifying because EPA wastewater remediation capex squeezes margin at Indian API synthesis sites. Hospital procurement coalitions exhibit lowest price sensitivity due to formulary consolidation leverage, while retail pharmacy channels face highest sensitivity from telehealth-integrated dispensary disintermediation.
Supply Chain Analysis
Strategic stockpiling of 4-epianhydrotetracycline impurity-controlled API dominates inventory strategy over just-in-time approaches, given REACH authorization delays and EMA inspection scheduling uncertainty. Supply concentrates in India, China, and the United States for tetracycline API fermentation and finished-dose compression. Raw material dependencies center on corn-steep liquor fermentation feedstock, amber packaging resins, and specialized excipients for modified-release matrices. Single-source vulnerability runs through Hyderabad and Mumbai CRO clusters for bioequivalence study execution. Distribution runs through hospital pharmacy captive dispensing, retail chain fulfillment, and direct-to-patient digital platforms for chronic prophylaxis.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery anchored to vector-borne disease endemic zone expansion across North American and European geographies, with Lyme Disease protocol adoption driving recurring demand baselines.
For Market Incumbents: Secure EMA inspection history leverage through proactive CDSCO-ICH alignment investments, locking pre-qualified supplier status for German and French hospital procurement coalitions. Prioritize nitrosamine impurity protocol validation to preempt FDA reformulation timelines that threaten formulary retention. Backward integration into captive API fermentation insulates margin from EPA discharge compliance cost inflation at third-party synthesis sites. For New Entrants and Emerging Players: Differentiate on modified-release formulation technology to capture Texas and Florida hospital system pilot programs for once-daily cellulitis protocols. Target Sub-Saharan Africa WHO prequalification pathways for malaria prophylaxis procurement in Kenya, Nigeria, and Ghana national health systems. Deploy telehealth-integrated subscription models for chronic Lyme prophylaxis in Massachusetts and Connecticut to bypass established retail pharmacy distribution. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-premium consolidation play because FDA tightened bioequivalence standards concentrate competitive access among dossier-deep specialists with EMA inspection records. Acquisition targets should display demonstrated multi-geography regulatory filing capabilities and API-to-finished-dose integration. Monitor CDSCO-EMA harmonization progress as the inflection signal for Indian manufacturer export market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EMA GMP Inspection Pre-Qualification | Unlocks German and French hospital tender access before competitor dossier resubmissions complete. |
| Nitrosamine Impurity Protocol Validation | Accelerates FDA supplemental approval timelines relative to manufacturers forced into reformulation cycles. |
| Modified-Release Formulation Development | Captures Texas and Florida hospital outpatient cellulitis protocol pilots displacing immediate-release generics. |
| WHO Prequalification Pathway Entry | Opens institutional procurement channels in Kenya, Nigeria, and Ghana national malaria prophylaxis programs. |
| Telehealth-Integrated Dispensing Platform | Bypasses retail pharmacy markup in Massachusetts and Connecticut chronic Lyme subscription markets. |
Methodological Framework
Desk research of FDA bioequivalence guidance documents, EMA GMP inspection records, and CDSCO regulatory circulars preceded structured interviews with hospital procurement managers, formulary directors, regulatory affairs leads, and API synthesis facility operators. Secondary validation drew from ClinicalTrials.gov bioequivalence study registrations, REACH authorization dossiers, and hospital tender announcement databases. Bottom-up volume estimates across formulation types and therapy areas triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across the projection horizon isolates volume drivers (Lyme Disease protocol expansion, respiratory infection seasonality) from value drivers (modified-release premium positioning, regulatory tier stratification). Segmentation modeling incorporates product type, therapy area, end user procurement channel, and regional regulatory cluster dimensions. CAGRs derive from fitted growth curves calibrated to historical tender award patterns and endemic zone epidemiological projections.
The analysis sits within stated boundaries; outcomes outside sustained FDA-EMA regulatory alignment or accelerated vector-borne disease spread would require recalibration. Forecasts reflect assumptions regarding CDSCO inspection capacity expansion and nitrosamine impurity threshold stability. Practitioners should keep alternative scenarios live as EPA discharge enforcement intensity and telehealth regulatory frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Heparin Sodium API Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Zinc Bacitracin Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Histamine H2-Receptor Antagonists Market
Pharmaceutical Ingredients
Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Diosmin API Market
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market