
 CMO/CDMO Market | 2026-2036
CMO/CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
CMO/CDMO Market Analysis
Pharmaceutical outsourcing channels is reshaping how drug sponsors access manufacturing capacity without owning fixed assets. Lonza Group anchors high-value biologics production through its Swiss and US facilities, while Thermo Fisher Scientific extends integrated clinical-to-commercial service lines across multiple continents. Samsung Biologics dominates mammalian cell culture capacity in Asia, leveraging single-use bioreactor platforms that reduce cross-contamination risks for multi-product facilities.
A contract manufacturing organization and contract development and manufacturing organization provides outsourced pharmaceutical production services spanning active pharmaceutical ingredient synthesis, formulation development, fill-finish operations, and analytical testing under current Good Manufacturing Practice standards. The primary commercial purpose centers on enabling drug developers to convert laboratory-scale molecules into validated, reproducible commercial batches without capital-intensive facility construction. Small molecules still occupy the largest revenue share within product type segmentation, though gene therapies represent the fastest-expanding margin pool as viral vector manufacturing scarcity commands premium pricing. Among end users, biotech firms compete most aggressively for limited capacity slots, often accepting longer lead times to secure specialized biologics expertise that pharmaceutical companies increasingly insource.
FDA enforces process validation and quality system regulations that determine facility inspection outcomes and drug approval timelines, while EMA's Annex 1 revisions on sterile manufacturing push European sponsors toward certified CDMO partners with isolator-based filling lines. The EU AI Act introduces emerging compliance dimensions for automated process control systems used in continuous manufacturing. Stakeholders must monitor regulatory divergence between FDA's quality maturity model and EMA's evolving GMP expectations when selecting multi-regional manufacturing partners.
Market Dynamics
Biologics manufacturing scarcity is forcing sponsor pipelines toward specialized outsourcing partnerships as facility qualification timelines stretch and regulatory inspection backlogs accumulate across multiple jurisdictions.
Growth Catalysts
- EMA Annex 1 Revisions:Sterile manufacturing mandates for isolator-based filling lines push European sponsors toward certified CDMO partners with validated aseptic processing capabilities.
- Single-Use Bioreactor Platforms:Disposable manufacturing systems reduce cross-contamination risks and enable rapid product changeovers in multi-product facilities serving gene therapy developers.
- Switzerland:Specialized manufacturing clusters in Basel and Visp attract high-value biologics production through concentrated technical expertise and streamlined regulatory pathways.
Market Restraints
- Platinum Group Metal Volatility:Catalyst costs for hydrogenation reactions in active pharmaceutical ingredient synthesis create margin pressure on small-molecule contract manufacturers.
- Asian Mammalian Cell Culture Concentration:Over-reliance on Korean and Chinese bioreactor capacity exposes sponsor pipelines to geopolitical disruption and export control friction.
- Viral Vector Manufacturing Bottleneck:Transfection efficiency limitations and plasmid DNA supply constraints restrict gene therapy batch yields regardless of facility investment.
Strategic Opportunities
- India:CDSCO regulatory harmonization initiatives and PLI scheme incentives position the country for cost-competitive fill-finish and formulation development services.
- Continuous Manufacturing Convergence:Integration of process analytical technology with real-time release testing enables smaller-footprint facilities with higher throughput per square meter.
- EU AI Act Compliance Services:Automated process control system validation creates advisory revenue streams for CDMOs supporting sponsor digital transformation.
Industry Challenges
- Cell Line Development Expertise Gap:Shortages of molecular biologists with CHO and HEK293 platform experience extend lead times for biologics process development.
- Multi-Product Facility Qualification:Cleaning validation requirements and changeover protocols consume operational capacity and complicate scheduling for contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CMO/CDMO Market |
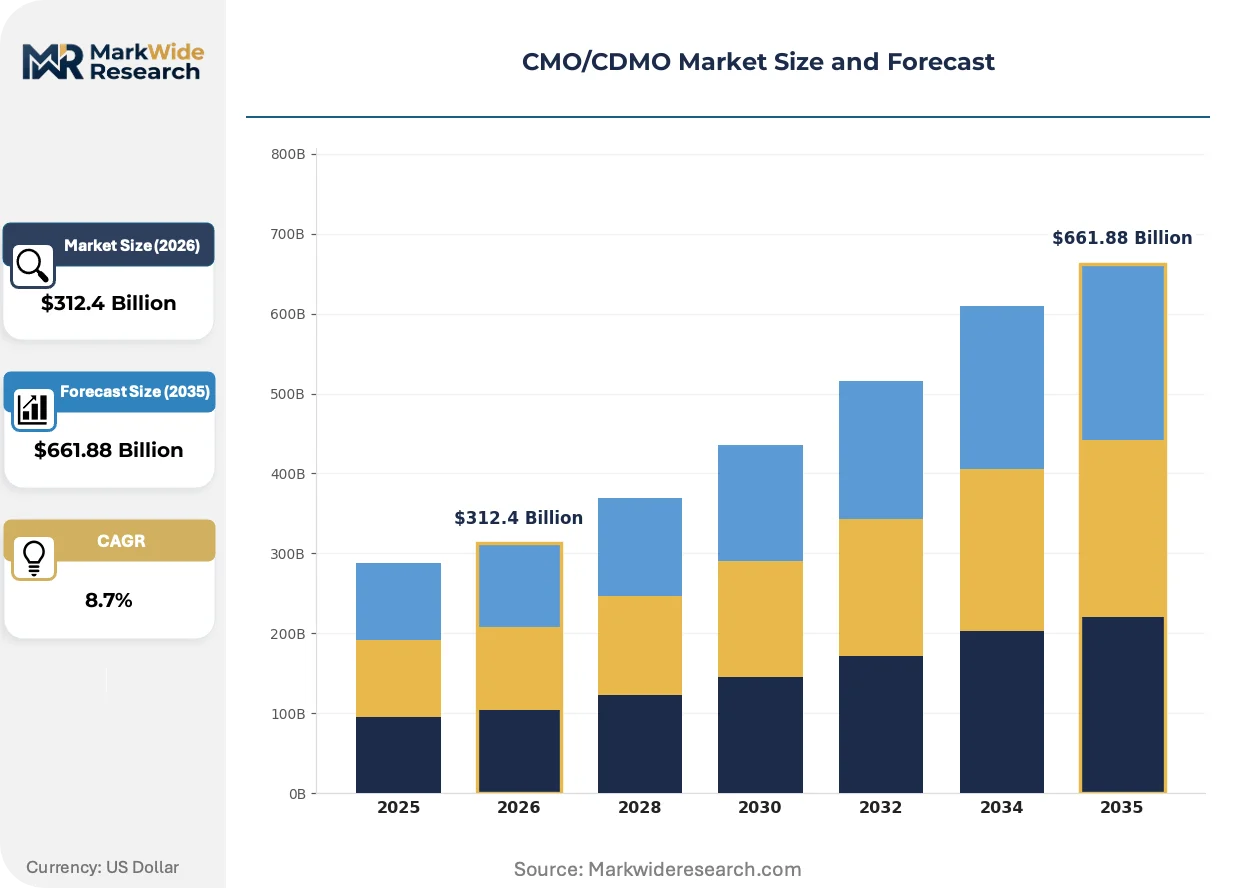
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $661.88 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Manufacturing, Development, Packaging, Lab Services End User: Pharmaceutical Companies, Biotech Firms, Medical Device Manufacturers, Nutraceutical Producers Therapy Area: Oncology, Cardiovascular, Neurology, Infectious Diseases Product Type: Small Molecules, Biologics, Gene Therapies, Peptides |
| Companies Covered | Lonza Group, Thermo Fisher Scientific, Catalent, Samsung Biologics, Pfizer CentreOne, Evonik Health Care, WuXi Biologics, Recipharm, Asymchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CMO/CDMO Market Emerging Trajectories
Digital twin technology and distributed manufacturing models are compressing development timelines while regulatory divergence between FDA quality maturity frameworks and EMA sterile processing mandates reshapes partnership selection criteria.
Digital twin platforms are virtualizing process development workflows by creating computational replicas of bioreactor performance and purification train behavior. Gene therapy developers adopt these simulations to reduce scale-up experimentation and predict critical quality attributes before physical batch production. This virtualization is compressing technology transfer timelines and reducing failed batch costs for complex biologics.
EU AI Act provisions on automated decision-making in manufacturing processes impose documentation and human-oversight requirements on continuous production systems. Pharmaceutical sponsors must demonstrate algorithmic transparency for real-time release algorithms and adaptive process control. European CDMOs with validated digital quality systems capture sponsor preference as FDA and EMA expectations on artificial intelligence governance diverge.
Sponsor procurement teams now segment manufacturing partnerships by regulatory filing geography rather than consolidating under single global contracts. Biotech firms maintain separate CDMO relationships for FDA-facing and EMA-facing submissions to isolate inspection risk and accelerate parallel regulatory pathways. This fragmentation is most visible among Phase III-stage sponsors with anticipated simultaneous US and European commercial launches.
CMO/CDMO Market Segmentation
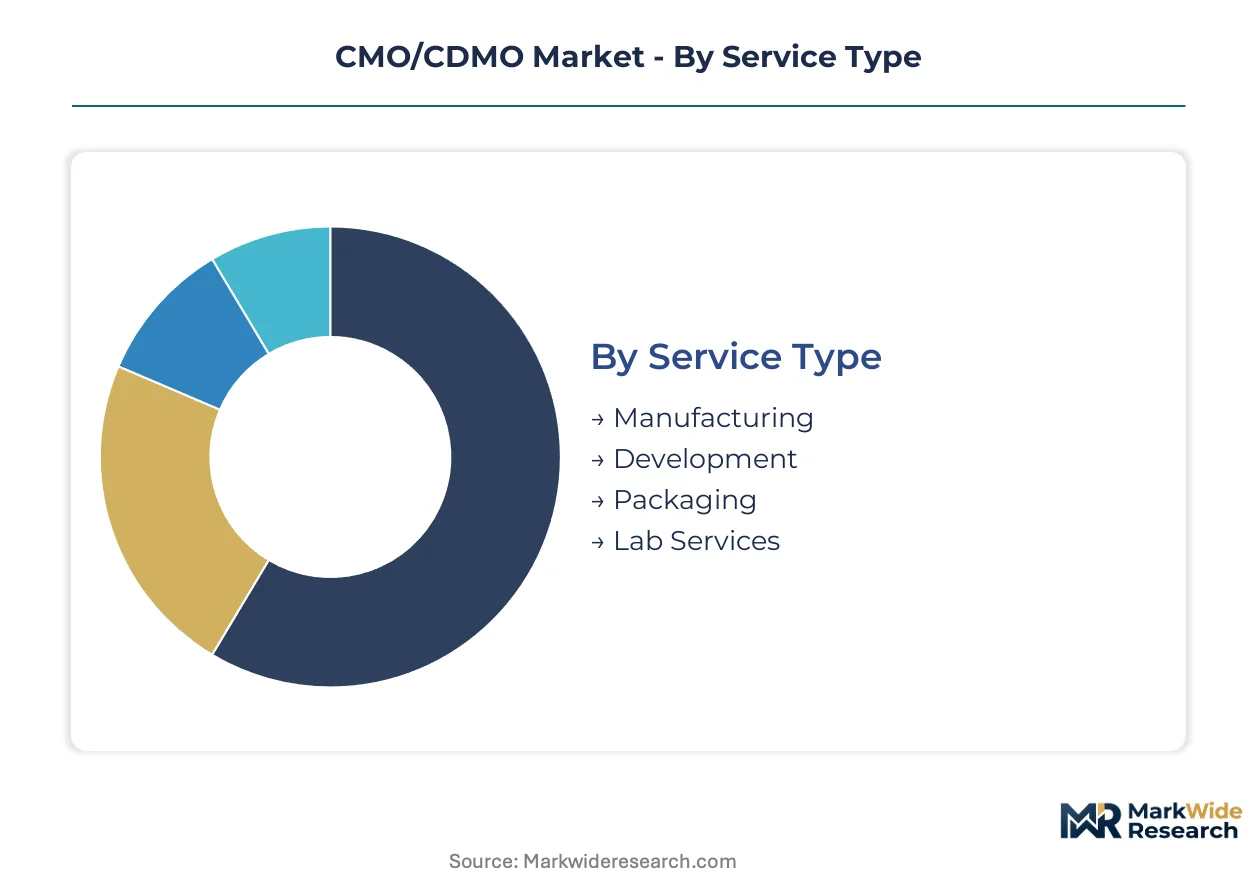
Service specialization determines capacity allocation and margin capture across the CMO/CDMO landscape. Contract manufacturers segment capabilities by molecule complexity, therapeutic focus, and client risk profiles to optimize facility utilization and regulatory positioning.
Service Type:
Cost tier differentiation separates commodity execution from high-value advisory functions across the outsourcing value chain.
- Manufacturing:Commercial-scale production of APIs and drug products under cGMP conditions with validated processes and established analytical methods. Demand concentrates at mammalian cell culture facilities in South Korea and Switzerland as biologics capacity scarcity extends lead times for late-stage sponsors.
- Development:Process design, scale-up, and characterization activities bridging discovery chemistry to commercial readiness. European biotech firms rotate procurement toward CDMOs with integrated development-to-manufacturing platforms to compress technology transfer timelines.
- Packaging:Primary and secondary packaging operations including serialization for track-and-trace compliance.
- Lab Services:Analytical testing, stability studies, and release testing supporting regulatory submissions.
Manufacturing holds installed capacity. Development is rotating up the share rankings.
End User:
Customer type shapes contract structure, risk allocation, and technical service intensity across sponsor relationships.
- Pharmaceutical Companies:Large-cap sponsors with established quality systems and multi-site manufacturing networks. Swiss and German pharma majors retain selective outsourcing for capacity overflow and specialized biologics rather than commodity small molecules.
- Biotech Firms:Venture-backed developers lacking manufacturing infrastructure and regulatory expertise. These sponsors drive demand for fully integrated CDMO partnerships spanning cell line development through commercial supply, accepting premium pricing for speed-to-clinic.
- Medical Device Manufacturers:Combination product developers requiring sterile fill-finish and device assembly integration.
- Nutraceutical Producers:Dietary supplement and functional food manufacturers seeking GMP-adjacent production capabilities.
Pharmaceutical Companies anchor volume commitments. Biotech Firms are climbing the fastest as a share of new contract initiations.
Therapy Area:
Application focus determines facility qualification requirements, regulatory pathway complexity, and pricing power across therapeutic categories.
- Oncology:Cytotoxic and biologic cancer therapeutics requiring containment infrastructure and specialized handling protocols. Demand clusters at facilities with isolator-based filling lines and potent compound capabilities in Ireland and Singapore.
- Cardiovascular:Small-molecule and biologic therapies for heart failure, hypertension, and metabolic indications with established manufacturing processes.
- Neurology:CNS-targeted therapies including antibody and gene therapy approaches facing blood-brain barrier delivery challenges.
- Infectious Diseases:Antibiotics, antivirals, and vaccine production with surge capacity requirements for pandemic preparedness.
Oncology commands premium capacity allocation. Infectious Diseases is gaining share fastest amid antimicrobial resistance investment cycles.
Product Type:
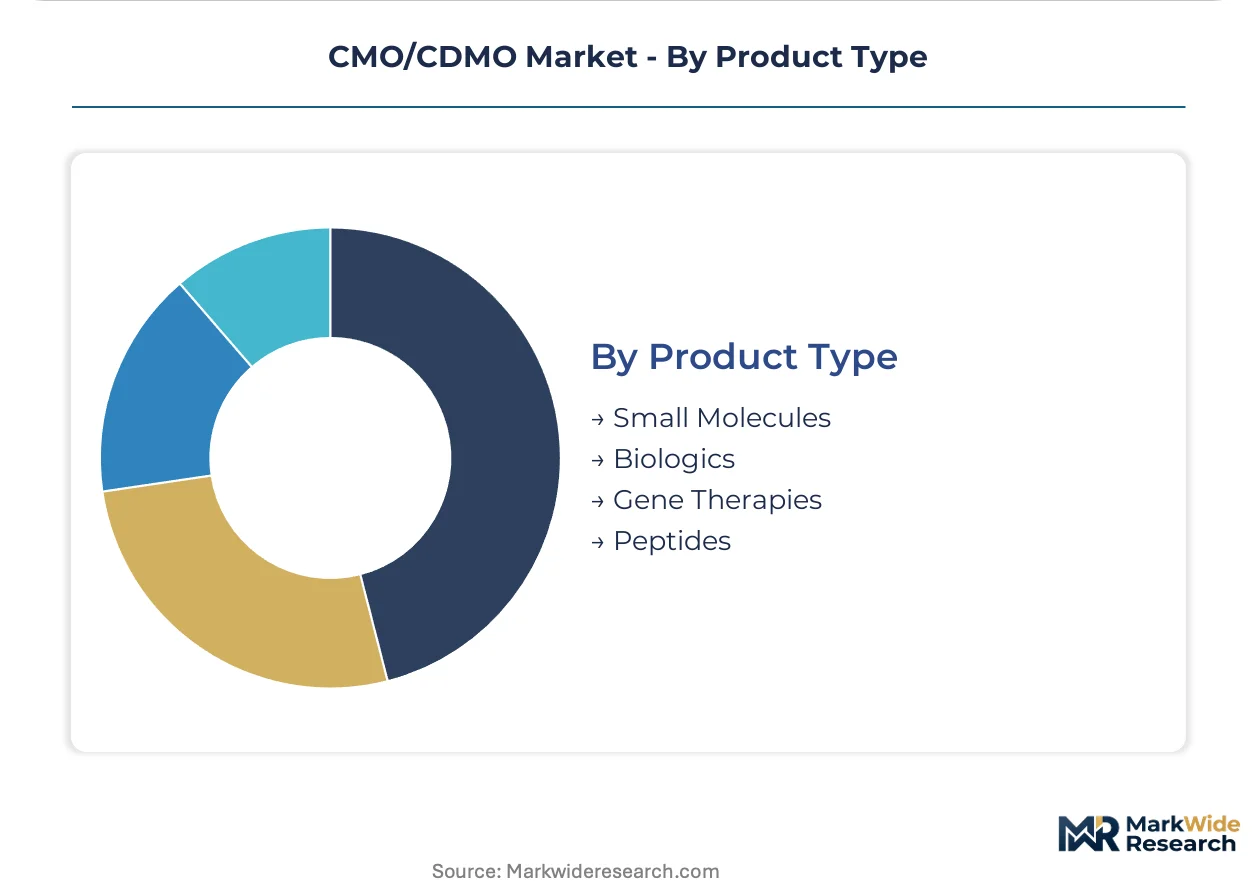
Molecule class dictates process technology, capital intensity, and regulatory scrutiny across the manufacturing portfolio.
- Small Molecules:Synthetic organic chemistry-based APIs and formulated drug products with mature process analytical technology. Indian and Chinese manufacturers compete on cost for standard oral solids while European specialists retain high-potency and controlled-substance niches.
- Biologics:Proteins and monoclonal antibodies produced in CHO or microbial expression systems. Capacity constraints in mammalian cell culture drive sponsor competition for slots at facilities with proven FDA and EMA inspection histories.
- Gene Therapies:Viral vector and plasmid-based treatments with transfection-limited batch yields and plasmid DNA supply bottlenecks.
- Peptides:Synthetic and recombinant peptide therapeutics bridging small molecule and biologic manufacturing approaches.
Small Molecules retain the largest installed base. Gene Therapies represent the steepest expansion trajectory as viral vector scarcity supports pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Swiss and South Korean biologics facilities while Indian and Chinese manufacturers compete on cost for small-molecule commoditized production. This asymmetry reflects divergent regulatory pathways and capital intensity across geographies.
United States
FDA quality maturity frameworks and accelerated approval pathways drive sponsor demand for domestic fill-finish and viral vector capacity. The IRA price negotiation provisions push large pharma toward outsourced manufacturing to preserve margin flexibility. Massachusetts and North Carolina clusters anchor mammalian cell culture investment as biotech venture funding concentrates in Boston and Research Triangle corridors.
Switzerland
Swissmedic streamlined inspection reciprocity with FDA and EMA attracts simultaneous US-European filing strategies from gene therapy developers. Federal innovation incentives and concentrated technical talent pools in Basel and Visp sustain premium pricing for complex biologics. Lonza Group anchors high-value production through specialized manufacturing clusters serving global sponsor pipelines.
South Korea
MFDS regulatory harmonization and government-backed biopharma investment programs position the country as Asia's mammalian cell culture hub. Samsung Biologics dominates regional capacity through single-use bioreactor platforms that reduce cross-contamination risks. Songdo and Incheon free economic zones concentrate biologics infrastructure with expedited customs clearance for plasmid DNA and cell bank imports.
India
CDSCO regulatory harmonization initiatives and PLI scheme incentives reposition the country from API commoditization toward high-value formulation development. Cost-competitive fill-finish operations in Hyderabad and Ahmedabad attract mid-stage biotech sponsors seeking capacity overflow. Contract manufacturers leverage WHO prequalification pathways to serve emerging market distribution requirements.
Germany
EMA Annex 1 sterile manufacturing mandates push European sponsors toward German CDMOs with isolator-based filling lines and validated aseptic processing. Evonik Health Care anchors specialized capabilities in lipid nanoparticle formulation and controlled-substance APIs. Frankfurt-Rhine-Main and Bavarian biotechnology corridors concentrate process analytical technology expertise for continuous manufacturing adoption.
CMO/CDMO Market Vendor Landscape
Integrated platform providers and specialized biologics pure-plays split the market along capital intensity and therapeutic focus lines. The vendor base concentrates around three strategic archetypes: global diversified conglomerates with clinical-to-commercial service lines, regional biologics specialists with mammalian cell culture dominance, and emerging Asian cost-leaders expanding upstream into development services. Capacity expansion and strategic technology licensing constitute the dominant competitive moves as qualification timelines stretch and sponsor procurement fragments by regulatory geography.
Within the integrated platform tier, Thermo Fisher Scientific and Lonza Group exemplify archetype consolidation through geographic diversification and regulatory multi-homing capabilities. Samsung Biologics occupies a distinct position as the scale-driven Asian pure-play, representing regional concentration strategies that leverage government-backed infrastructure investment. These three anchors illustrate how competitive positioning stratifies across capital access, regulatory relationships, and therapeutic specialization rather than undifferentiated capacity scale.
| Leading Market Players |
|---|
| Lonza Group |
| Thermo Fisher Scientific |
| Catalent |
| Samsung Biologics |
| Pfizer CentreOne |
| Evonik Health Care |
| WuXi Biologics |
| Recipharm |
| Asymchem |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Korean and Chinese mammalian cell culture capacity exposes sponsor pipelines to geopolitical disruption while simultaneously compressing pricing spreads between premium biologics slots and standard small-molecule contracts. This concentration dynamic forces procurement teams to accept extended lead times for specialized manufacturing or absorb tariff-driven cost escalations that reshape total cost of ownership calculations across outsourcing tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order gene therapy viral vector production from standard small-molecule API contracts. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification grade and FDA/EMA inspection history as primary differentiation drivers. Cost compression in small-molecule commoditized tiers is intensifying because Indian and Chinese manufacturers compete aggressively on scale. Biotech firms with limited manufacturing infrastructure exhibit highest price sensitivity, while large pharmaceutical sponsors prioritize speed-to-clinic over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for plasmid DNA and cell bank imports. Manufacturing capacity concentrates in Switzerland, South Korea, and Ireland for high-value biologics, while India and China anchor small-molecule API production. Raw material dependencies include platinum group metals for hydrogenation catalysts, single-use bioreactor consumables, and viral vector plasmid DNA. Distribution runs through sponsor-direct partnerships for clinical supply and wholesale channels for commercial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified aseptic processing expertise and viral vector manufacturing capability constitute the binding constraints that determine competitive outcomes across sponsor procurement decisions. The gap between demand for specialized biologics capacity and available facility slots with proven regulatory inspection histories creates asymmetric bargaining power for incumbent operators.
For Market Incumbents: Pre-empt emerging Asian cost-leaders by accelerating isolator-based filling line investments ahead of EMA Annex 1 enforcement deadlines. Secure backward integration into plasmid DNA supply to insulate gene therapy pipelines from transfection efficiency bottlenecks. Defensive consolidation around Swiss and South Korean manufacturing clusters preserves premium positioning against regional specialists expanding upstream into development services. For New Entrants and Emerging Players: Establish a beachhead in Indian fill-finish and formulation development services where CDSCO regulatory harmonization and PLI scheme incentives reduce qualification barriers. Target mid-stage biotech sponsors seeking capacity overflow for Phase II/III transitions as the most penetrable client segment. Differentiate through integrated clinical-to-commercial platforms that compress technology transfer timelines relative to commodity manufacturers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized biologics pure-plays with mammalian cell culture dominance and proven FDA/EMA inspection histories. Long-term viability across the forecast window rests on regulatory multi-homing capabilities and therapeutic specialization depth rather than undifferentiated capacity scale. Monitor viral vector manufacturing yield improvements as the critical inflection indicator for gene therapy margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Based Filling Line Investment | EMA Annex 1 compliance mandates position certified CDMOs for European sponsor preference. |
| Single-Use Bioreactor Platform Expansion | Samsung Biologics leverages disposable systems to reduce cross-contamination risks in multi-product facilities. |
| Digital Twin Technology Adoption | Virtual process development compresses scale-up timelines for gene therapy batch optimization. |
| Plasmid DNA Supply Integration | Backward control over transfection inputs insulates viral vector yields from external supply constraints. |
| Regulatory Multi-Homing Certification | Swissmedic-FDA-EMA reciprocity streamlines simultaneous filing strategies for global launches. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and customs trade data to establish demand-side validation. Conversations with drug development executives, regulatory affairs leads, CDMO procurement managers, and formulary directors informed capacity allocation and pricing dynamics. Bottom-up facility capacity modeling and top-down sponsor pipeline analysis were triangulated to cross-validate market sizing.
Forecast inputs include service type segmentation, therapy area concentration, product type complexity tiers, and regional regulatory cluster differentiation across the projection horizon. CAGRs were derived from facility investment trajectories, sponsor outsourcing penetration rates, and regulatory inspection backlog trends. Modeled variables incorporate biologics capacity scarcity duration, viral vector manufacturing yield improvements, and EMA Annex 1 compliance cost pass-through assumptions.
Stress conditions across platinum group metal price volatility, Korean-Chinese export control friction, and FDA quality maturity enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and sponsor insourcing propensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Prefilled Formalin Vials Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Global Pharmaceutical Cartridges Market
Pharmaceutical Equipment
Global Pharmaceutical Membrane Filtration Market
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
North America and Europe Pharmaceutical Stability & Storage Services Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
Lyophilization Equipment Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
North America Pharmacy Automation Market