
 Respiratory Inhaler Devices Market | 2026-2036
Respiratory Inhaler Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Inhaler Devices Market Outlook
Aluminum is hardening its position over stainless steel in canister construction for metered-dose inhalers, cutting per-unit weight and improving propellant compatibility. GSK plc leverages backward integration into active pharmaceutical ingredient supply to protect margin pools on its respiratory portfolio. AstraZeneca anchors its position through sustained R&D intensity in biologic-naïve patient segments. Boehringer Ingelheim GmbH differentiates via specialized positioning in dual bronchodilator combinations.
Respiratory inhaler devices are drug-delivery systems engineered to aerosolize or powderize pharmaceutical agents for direct pulmonary deposition, typically achieving particle sizes between one and five micrometers to optimize alveolar absorption. These devices serve the primary commercial purpose of managing chronic obstructive pulmonary disease, asthma, and other lower-respiratory conditions through controlled, repeatable dosing. Metered-dose inhalers retain the largest installed base but face margin compression from generic erosion, while dry powder inhalers capture expanding share in maintenance therapy due to breath-actuated convenience and elimination of coordination requirements. Soft mist inhalers represent the fastest-growing product category, though from a smaller base, propelled by slower-velocity aerosol generation that improves lung deposition rates in elderly populations.
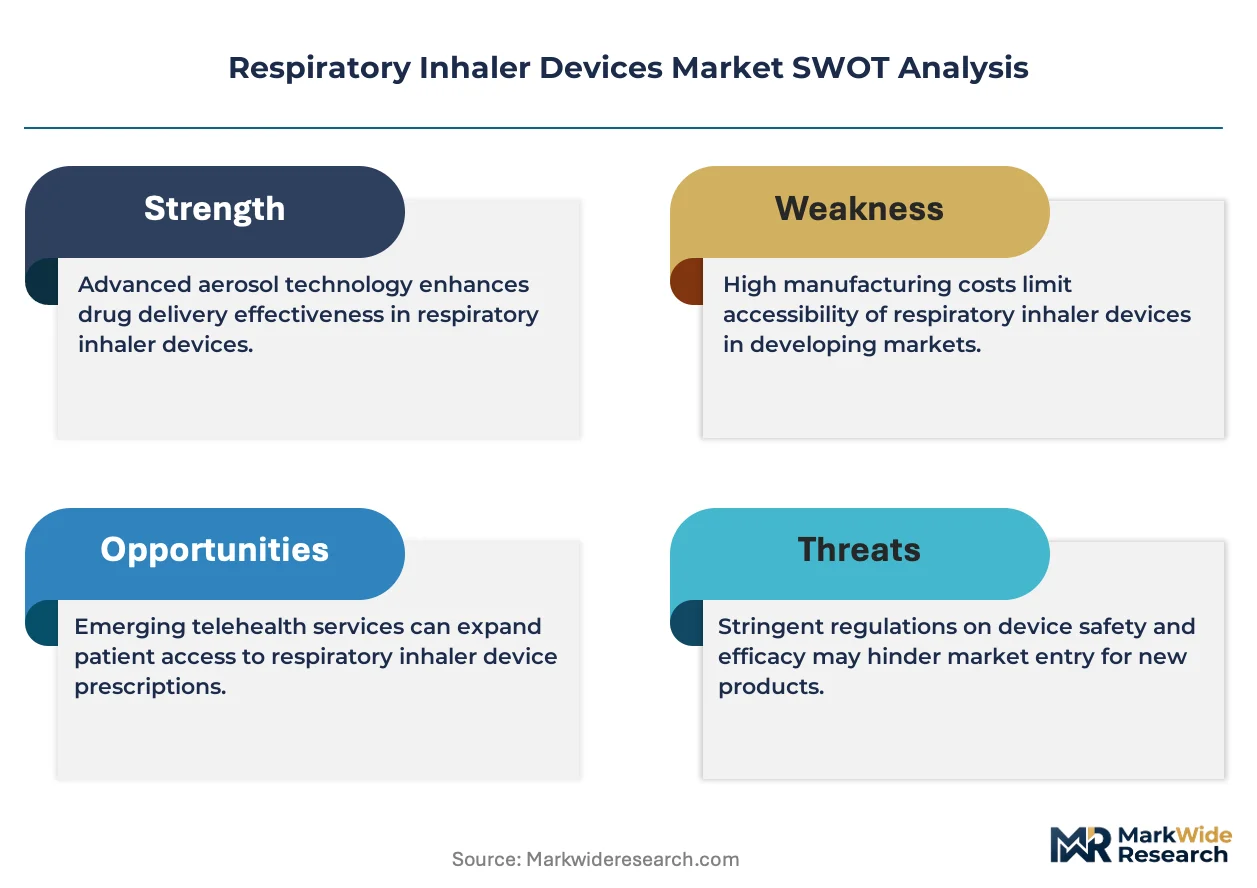
FDA bioequivalence standards for inhaled generics, EMA's Medical Device Regulation migration timelines, and EPA restrictions on hydrofluoroalkane propellants collectively reshape formulation roadmaps and device redesign cycles across manufacturers. These frameworks force portfolio-level decisions on propellant transitions, clinical trial investments, and regional labeling strategies. Stakeholders must monitor regulatory divergence between the FDA and EMA on acceptable surrogate endpoints for generic inhaler approval, as this gap will determine which companies can synchronize global launches and which face fragmented market entry timelines.
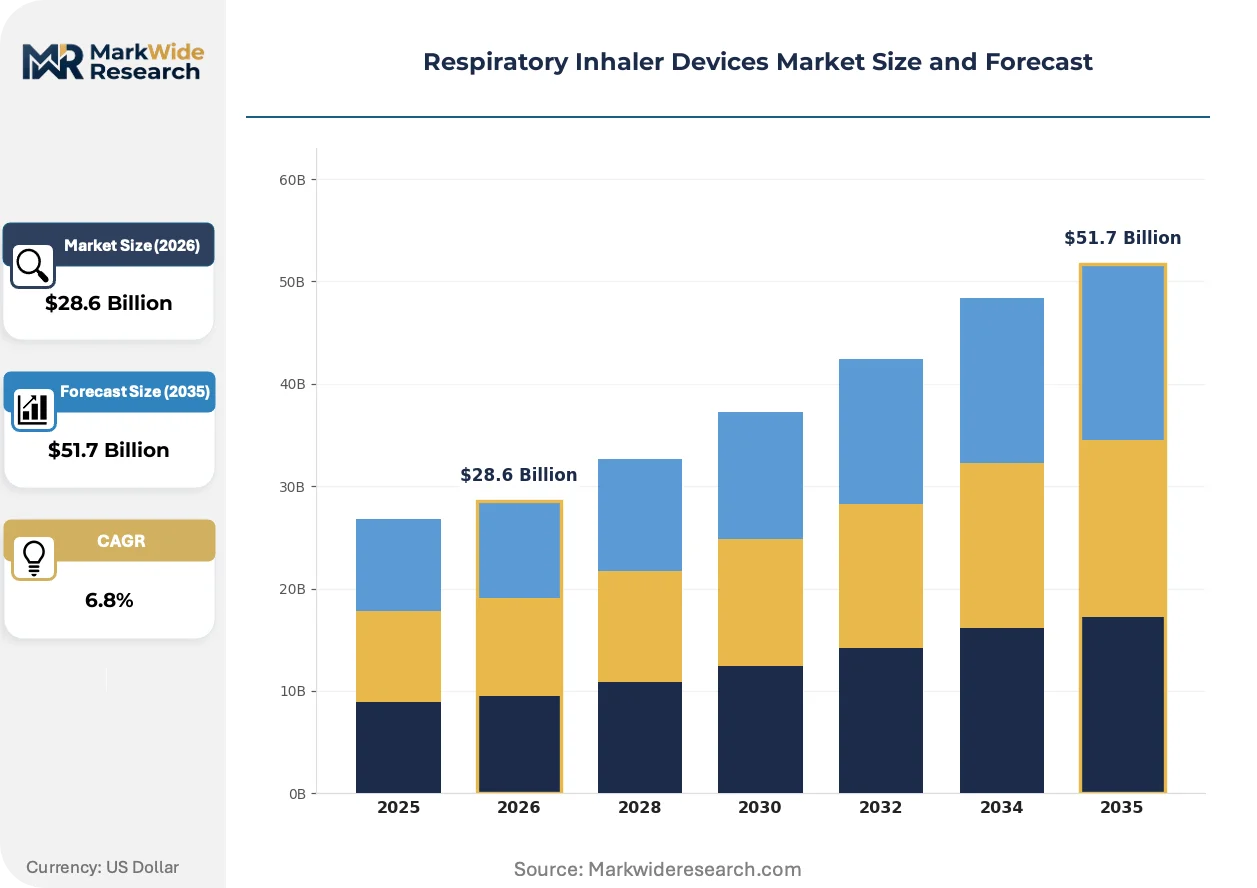
Market Dynamics
EPA restrictions on hydrofluoroalkane propellants are forcing wholesale reformulation of metered-dose inhaler portfolios, compressing device redesign cycles from five years to eighteen months across manufacturers.
Growth Catalysts
- Home care migration:Portable inhaler systems capture expanding share as post-acute care shifts toward residential settings in the United States and Germany.
- FDA bioequivalence pathway:Updated guidance for generic inhaled drugs accelerates competitive entry and expands patient access to lower-cost alternatives.
- Aluminum canister adoption:Lightweight aluminum displaces stainless steel in MDI construction, cutting per-unit weight and improving propellant compatibility profiles.
Market Restraints
- Propellant transition costs:HFA-152a and HFO-1234ze development requires capital-intensive toxicology packages and new manufacturing lines.
- Supply concentration:Active pharmaceutical ingredient production for respiratory biologics concentrates among three European contract manufacturers.
- Generic erosion pressure:Patent cliffs on established bronchodilator molecules compress margins on legacy metered-dose platforms.
Strategic Opportunities
- Pediatric breath-actuated designs:Untapped demand exists for dry powder inhalers calibrated to lower inspiratory flow rates in children.
- Soft mist inhaler expansion:Slower aerosol velocity improves deposition in elderly populations with compromised coordination.
- EMA MDR alignment:Early compliance with Medical Device Regulation timelines creates first-mover positioning in European markets.
Industry Challenges
- Aerosol engineering talent scarcity:Particle size optimization and lung deposition modeling require specialized computational fluid dynamics expertise that outpaces graduate program output.
- Cross-regional trial complexity:Divergent FDA and EMA positions on acceptable surrogate endpoints fragment clinical development timelines and inflate protocol costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Inhaler Devices Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metered-Dose Inhalers, Dry Powder Inhalers, Nebulizers, Soft Mist Inhalers End User: Hospitals, Home Care, Clinics, Emergency Services Delivery Mode: Pneumatic, Ultrasonic, Mesh, Compressed Gas Functionality: Therapeutic, Diagnostic, Preventive, Emergency Care |
| Companies Covered | GSK plc, AstraZeneca, Cipla Ltd., Boehringer Ingelheim GmbH, Teva Pharmaceutical Industries Ltd., Novartis AG, CHIESI Farmaceutici S.p.A., Lupin Ltd., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Inhaler Devices Market Strategic Shifts
Connected inhaler technology is reshaping adherence monitoring and reimbursement models, embedding sensors and wireless transmission into device architectures previously defined purely by mechanical aerosol generation.
Digital dose counters and Bluetooth-enabled adherence trackers are integrating into dry powder and soft mist platforms. Pulmonology clinics in the United States and United Kingdom are adopting these systems for remote patient monitoring programs. The technology is integrating real-world evidence generation into payer contract negotiations, shifting value demonstration from clinical trial data to longitudinal usage patterns.
REACH restrictions on fluorinated greenhouse gases and the EU F-Gas Regulation are accelerating propellant transitions toward low-global-warming-potential alternatives. Formulation groups must redesign stability profiles and particle size distributions around HFO-1234ze and HFA-152a chemistries. European manufacturing facilities face the most compressed compliance timelines, with several German and Swiss sites already converting production lines.
Hospital procurement committees are consolidating respiratory device contracts around single-vendor ecosystems that bundle inhalers with nebulizers and diagnostic spirometry. Integrated delivery networks in the United States are replacing fragmented purchasing across individual pulmonologists. This concentration is most visible in the Midwest and Southeast regions, where Catholic health systems and for-profit chains have completed multi-year standardization initiatives.
Respiratory Inhaler Devices Market Segmentation
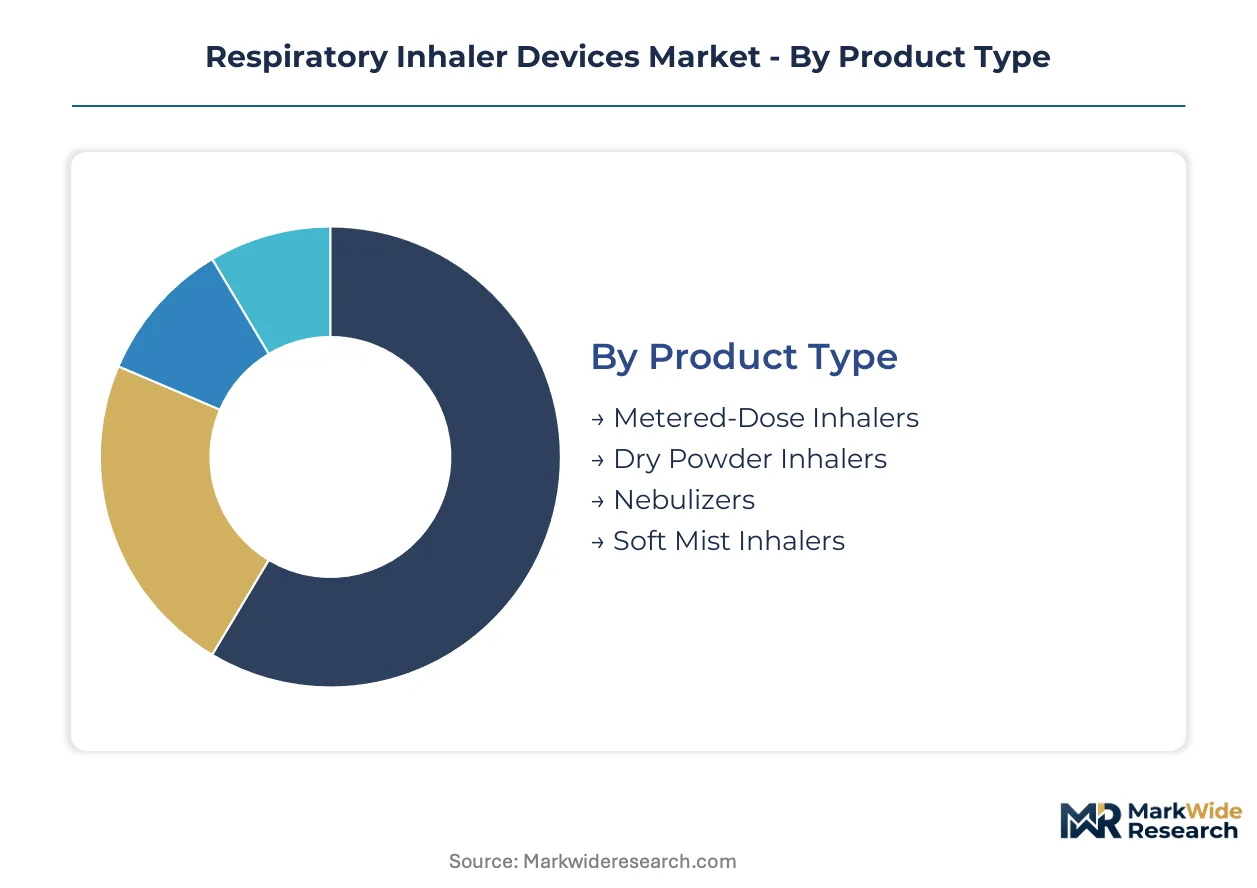
Respiratory inhaler segmentation maps directly to reimbursement pathways and regulatory approval burdens. Device categories carry distinct FDA and EMA certification requirements that shape manufacturer portfolio economics and geographic launch sequencing.
Product Type:
FDA 510(k) clearance and EMA MDR Class IIa/IIb designations vary sharply across device architectures, with propellant-bearing systems facing the heaviest toxicology documentation.
- Metered-Dose Inhalers:Pressurized canister systems deliver aerosolized drug-propellant suspensions through a metering valve. United States demand concentrates in maintenance therapy for COPD, where Medicare Part B reimbursement density supports premium device uptake despite generic molecule erosion.
- Dry Powder Inhalers:Breath-actuated systems eliminate coordination requirements through de-agglomeration of micronized drug-lactose blends. Germany's home care migration and statutory health insurance breath-actuated preference policies accelerate adoption in elderly maintenance populations.
- Soft Mist Inhalers:Mechanical spring mechanisms generate slow-velocity aerosol plumes without propellants. Japan's PMDA fast-track designation for geriatric deposition improvements expands addressable patient pools.
- Nebulizers:Compressor or vibrating mesh systems convert liquid formulations into respirable droplets for acute exacerbation management. United Kingdom NHS hospital-at-home programs drive pneumatic unit procurement.
Leading the category by volume: Metered-Dose Inhalers. Expanding most quickly: Soft Mist Inhalers.
End User:
Procurement authority and device specification control shift dramatically across care settings, from centralized hospital pharmacy committees to individual patient retail acquisition.
- Home Care:Patient-owned portable systems for chronic disease self-management. United States integrated delivery network bundling contracts and Germany's SGB V ambulatory care reimbursement expansion concentrate demand growth in residential settings.
- Hospitals:Institution-controlled inventories for inpatient acute management. Catholic health system standardization initiatives in the US Midwest and Southeast consolidate purchasing around single-vendor inhaler-nebulizer-spirometry ecosystems.
- Clinics:Outpatient pulmonology and primary care dispensing. United Kingdom NHS primary care network formularies increasingly restrict to breath-actuated and connected device options.
- Emergency Services:Pre-hospital and ambulance stock for acute bronchospasm. France's SAMU centralized procurement and ANSM emergency use labeling requirements shape device selection.
Volume leadership: Hospitals. Steepest expansion trajectory: Home Care.
Delivery Mode:
Technical differentiation in aerosol generation mechanics determines particle size distribution, lung deposition efficiency, and corresponding clinical evidence requirements for regulatory submission.
- Pneumatic:Compressed air jet nebulization with baffle-based droplet sizing. US hospital procurement consolidation favors established jet platforms with lowest per-treatment supply costs.
- Mesh:Piezoelectric vibration of perforated membranes for silent, portable operation. Switzerland's Swissmedic favorable positioning for pediatric and nocturnal therapy indications expands prescribing.
- Ultrasonic:High-frequency crystal vibration generating larger droplet spectra. Limited to diagnostic sputum induction and certain antibiotic delivery by EMA heat-degradation concerns.
- Compressed Gas:Oxygen or air-driven large-volume nebulization for critical care. ICU sedation protocols in German university hospitals specify gas-driven systems for continuous bronchodilator delivery.
Installed base dominance: Pneumatic. Gaining share fastest: Mesh.
Functionality:
Clinical purpose classification determines trial endpoint selection, payer evidence requirements, and pricing authority across preventive, acute, and diagnostic applications.
- Therapeutic:Chronic symptom control through scheduled bronchodilator or anti-inflammatory delivery. US commercial payer step-therapy protocols and Medicare coverage determination processes concentrate volume on maintenance-indicated devices.
- Preventive:Pre-exposure or pre-exercise prophylaxis against bronchospasm. Australian TGA scheduling and private formulary positioning for exercise-induced asthma expand pediatric prescribing.
- Diagnostic:Bronchoprovocation or sputum induction for pulmonary function assessment. Academic medical center research budgets in the Netherlands and Belgium sustain specialized nebulizer demand.
- Emergency Care:Rapid reversal of acute airflow obstruction. Saudi Arabia's SFDA emergency use authorization pathway and MOH central purchasing for ambulance fleets shape regional specifications.
Revenue concentration: Therapeutic. Climbing the fastest: Preventive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand concentrates on premium device uptake, driven by Medicare Part B reimbursement density and chronic respiratory disease prevalence. Germany and Japan follow with distinct regulatory accelerators. China and the United Kingdom round out the geographic spread with divergent procurement models.
United States
Integrated delivery networks in the Midwest and Southeast consolidate purchasing around single-vendor ecosystems bundling inhalers with nebulizers and spirometry. FDA bioequivalence guidance for generic inhaled drugs reshapes competitive entry pathways. Boston's medical device corridor hosts manufacturing facilities converting production lines for low-global-warming-potential propellant transitions.
Germany
Statutory health insurance breath-actuated preference policies accelerate dry powder inhaler adoption in elderly maintenance populations. EU F-Gas Regulation and REACH restrictions compress manufacturing compliance timelines. Swiss and German sites near Basel already convert production lines for HFO-1234ze and HFA-152a chemistry transitions.
Japan
PMDA fast-track designation for geriatric deposition improvements expands addressable patient pools for soft mist inhaler platforms. METI standards on medical device quality systems shape local manufacturing requirements. Osaka-Kobe pharmaceutical clusters concentrate formulation expertise for pulmonary delivery systems.
China
NMPA medical device registration pathways for imported inhaler platforms create tiered market access timelines. Dual carbon goals and MEE environmental standards accelerate domestic propellant alternative development. Shanghai and Suzhou industrial parks attract contract manufacturing investment for respiratory device assembly.
United Kingdom
NHS primary care network formularies increasingly restrict prescribing to breath-actuated and connected device options. NICE technology appraisals influence reimbursement thresholds for novel inhaler mechanisms. Cambridge-Oxford-London research triangle sustains specialized nebulizer demand for academic pulmonary function assessment.
Respiratory Inhaler Devices Market Competitive Environment
Backward integration into active pharmaceutical ingredient supply dominates the current landscape, with manufacturers securing captive production of respiratory biologics to protect margin pools. The vendor base organizes around three strategic archetypes: diversified pharmaceutical conglomerates with respiratory portfolios, specialized inhalation technology developers, and contract manufacturing organizations with pulmonary device expertise. M&A activity concentrates on API supply security and digital health platform acquisitions. Geographic expansion into Asia-Pacific markets represents the second dominant competitive vector.
Among diversified pharmaceutical conglomerates, GSK plc and AstraZeneca exemplify archetypes built on sustained R&D intensity and biologic-naïve patient segment focus. Boehringer Ingelheim GmbH occupies a position within the specialized bronchodilator combination tier, differentiated through dual-therapy positioning. These three entities represent distinct strategic postures without implying specific market share claims or operational details beyond their visible portfolio concentrations.
| Leading Market Players |
|---|
| GSK plc |
| AstraZeneca |
| Cipla Ltd. |
| Boehringer Ingelheim GmbH |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| CHIESI Farmaceutici S.p.A. |
| Lupin Ltd. |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery network bundling contracts in the United States Midwest and Southeast are forcing manufacturers to absorb connectivity module costs into device pricing, compressing margins on standard MDI platforms while creating tiered separation between connected and mechanical-only systems. This procurement concentration rewards suppliers with captive API production and multi-device ecosystem capabilities, penalizing standalone inhaler specialists.
Pricing Analysis
Volume concentrates in legacy metered-dose platforms where generic molecule erosion accelerates price compression, while margins persist in soft mist and connected dry powder systems commanding formulary preference through adherence data. Price differentiation rests on FDA bioequivalence tier certification and Bluetooth-enabled remote monitoring bundling. Pricing pressure intensifies in standard MDI categories as HFA-152a transition costs collide with Medicare Part B reimbursement caps. Hospital procurement committees show lowest price sensitivity; retail pharmacy channels exhibit highest.
Supply Chain Analysis
Reverse logistics flows for propellant-bearing canisters face EPA hazardous waste routing requirements that extend replenishment cycles and inflate working capital needs for United States distributors. Manufacturing concentrates in Germany, Switzerland, and the United States around Basel and Boston corridor facilities converting lines for HFO-1234ze chemistry. Aluminum canister feedstock and piezoelectric mesh components draw from Chinese and Japanese specialty suppliers. Single-source vulnerability concentrates in European API contract manufacturing. Distribution runs through hospital GPO contracts and retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where propellant transition capital requirements and EMA MDR compliance timelines will force sub-scale manufacturers toward exit or acquisition.
For Market Incumbents: To counter generic erosion in established bronchodilator portfolios, secure captive supply of respiratory biologics through backward integration into API production, and accelerate EMA MDR Class IIa certification timelines to capture first-mover positioning in European hospital procurement consolidations. For New Entrants and Emerging Players: Enter via pediatric breath-actuated dry powder designs calibrated to sub-30 L/min inspiratory flow rates, where established players maintain limited SKU depth. Target Germany's statutory health insurance breath-actuated preference policies as the most penetrable reimbursement environment. Pursue pulmonology clinic direct partnerships bypassing hospital GPO gatekeepers. For Investors and Strategic Acquirers: The window for entry favors specialized inhalation technology developers with HFO-1234ze formulation expertise and PMDA fast-track relationships. Long-term viability hinges on regulatory synchronization capabilities across FDA and EMA divergence. Monitor ANSM and Swissmedic positioning on surrogate endpoint acceptance as the inflection signal for global launch timing advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Propellant Chemistry Transition | HFO-1234ze and HFA-152a conversion secures EPA compliance and European F-Gas Regulation alignment ahead of competitor timelines. |
| Connected Device Platform Launch | Bluetooth-enabled adherence tracking integrates real-world evidence into United States payer contract negotiations and step-therapy positioning. |
| EMA MDR Class IIa Certification | Early compliance creates preferred supplier status in German and United Kingdom hospital procurement consolidations. |
| Pediatric Formulation Development | Low-flow-rate dry powder designs address untapped demand in Australia's TGA-scheduled exercise-induced asthma segment. |
| API Supply Security Investment | Captive biologics production protects margin pools as respiratory portfolio concentration intensifies among European contract manufacturers. |
Study Parameters
FDA 510(k) filings, EMA MDR submission databases, and ClinicalTrials.gov protocol records formed the secondary backbone, cross-referenced against primary interviews with respiratory device engineering directors, hospital GPO contracts managers, and pulmonology clinic procurement leads. Bottom-up and top-down triangulation validated manufacturer-reported shipment data against national reimbursement claims and import-export customs records.
The analytical lens combined bottom-up patient population modeling with top-down pharmaceutical revenue attribution across device categories. Segmentation dimensions included product architecture, end-use setting, delivery mechanism, and regional regulatory cluster. CAGRs were derived from slope analysis of historical reimbursement density and projected chronic disease prevalence curves, incorporating propellant transition cost pass-through assumptions and generic entry timing scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA-EMA surrogate endpoint divergence and REACH restriction acceleration timelines. Practitioners should monitor PMDA geriatric fast-track designations and Catholic health system standardization announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
BFS Syringes Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Global Glucometer Market
Medical Devices
Massage Equipment Market
Medical Devices
Orthodontic Headgear Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Snare Devices Market
Medical Devices
Global Stereotaxic Instrument Market
Medical Devices
Wireless Neurostimulator Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Intraocular Lens (IOL) Market