
 Endocarditis Drugs Market | 2026-2036
Endocarditis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Endocarditis Drugs Market Foresight
Combination therapy bundling is realigning procurement patterns across hospital formularies, with dual-antibiotic regimens increasingly packaged as standardized kits rather than individual vials. Pfizer Inc. leverages its manufacturing scale to dominate injectable cephalosporin supply chains for acute bacterial endocarditis protocols. Fresenius Kabi AG anchors hospital-critical care channels through its parenteral compounding infrastructure. Novartis AG differentiates via targeted R&D intensity in anti-infective drug delivery systems.
Endocarditis drugs comprise antimicrobial agents formulated to eradicate vegetations on cardiac valves, typically requiring bactericidal concentrations achievable through extended-interval intravenous dosing with agents such as vancomycin or aminoglycosides. These pharmaceuticals serve the primary purpose of sterilizing infected endocardial tissue while preventing embolic complications and valve destruction. Vancomycin retains structural importance in methicillin-resistant Staphylococcus aureus coverage, though nephrotoxicity monitoring constrains margin expansion. Intravenous administration routes occupy the dominant share of acute therapy, while oral step-down protocols represent the fastest-growing configuration as outpatient parenteral antimicrobial programs mature.
The FDA's antibacterial drug development guidance shapes trial design requirements, while the EMA's orphan drug incentives influence European development priorities for resistant gram-positive endocarditis therapies. Health Canada and the FDA both mandate rigorous pharmacovigilance for aminoglycoside-containing regimens, directly affecting labeling and dosing recommendations. Stakeholders must monitor evolving breakpoint revisions from CLSI and EUCAST, as susceptibility criteria shifts will determine formulary positioning and therapeutic algorithm updates across major hospital systems.
Market Dynamics
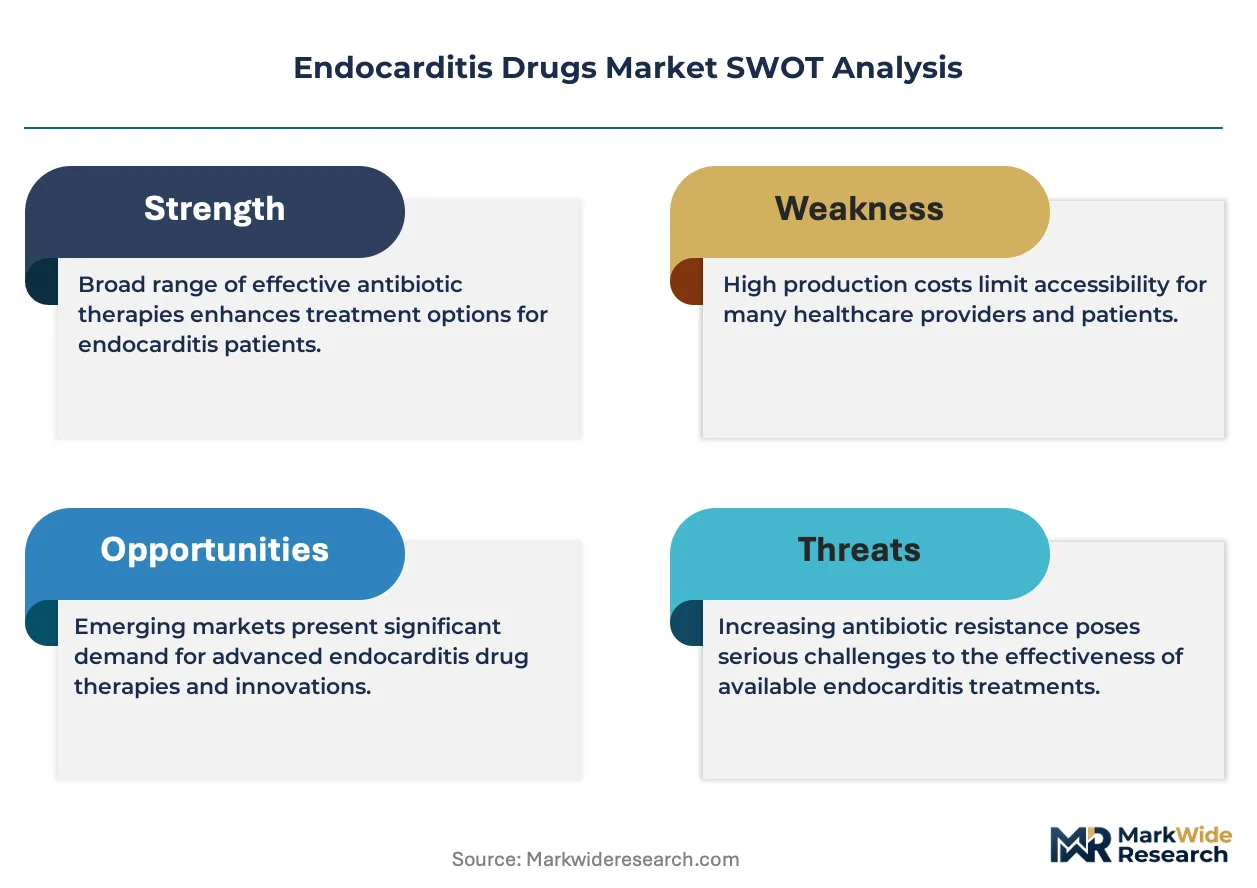
Hospital antimicrobial stewardship programs are systematically replacing empiric broad-spectrum protocols with pathogen-directed endocarditis therapy, compressing formulary diversity while elevating pharmacoeconomic scrutiny of every agent selection.
Growth Catalysts
- CLSI Breakpoint Revisions:Updated susceptibility criteria from the Clinical and Laboratory Standards Institute are accelerating formulary updates for targeted gram-positive coverage in academic medical centers.
- Outpatient Parenteral Antimicrobial Therapy:Maturing OPAT infrastructure in the United States is extending treatment duration outside hospital walls, creating new reimbursement pathways for oral step-down regimens.
- EMA Orphan Drug Incentives:European development priorities for resistant endocarditis therapies are attracting sponsor investment in novel anti-infective delivery platforms.
Market Restraints
- Vancomycin Supply Concentration:Injectable glycopeptide manufacturing clusters heavily in Asian API producers, exposing hospital procurement to geopolitical shipment disruptions.
- Aminoglycoside Nephrotoxicity Surveillance:FDA and Health Canada pharmacovigilance mandates require intensive therapeutic drug monitoring, inflating nursing labor costs per treatment course.
- Generic Cephalosporin Substitution:Low-cost injectable beta-lactams from Fresenius Kabi and comparable compounders erode branded margin structures in acute bacterial protocols.
Strategic Opportunities
- Sub-Saharan Africa Hospital Infrastructure:Underpenetrated infectious disease capacity in Nigeria and Kenya offers first-mover positioning for standardized endocarditis kits as cardiac surgery programs expand.
- Long-Acting Liposomal Formulations:Convergence of nanotechnology with anti-infective pharmacology promises extended-interval dosing that reduces nursing burden and length-of-stay metrics.
- Japan's Specified Disease Treatment Research Program:PMDA regulatory tailwinds for intractable infections create accelerated approval pathways for novel agents targeting prosthetic valve endocarditis.
Industry Challenges
- ID-Pharmacy Specialist Shortage:Fellowship-trained infectious disease pharmacists remain scarce relative to stewardship program expansion targets, constraining protocol implementation velocity.
- Legacy EHR Integration Friction:Antimicrobial decision support modules require expensive customization against entrenched Epic and Cerner installations, delaying real-time susceptibility alerting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endocarditis Drugs Market |
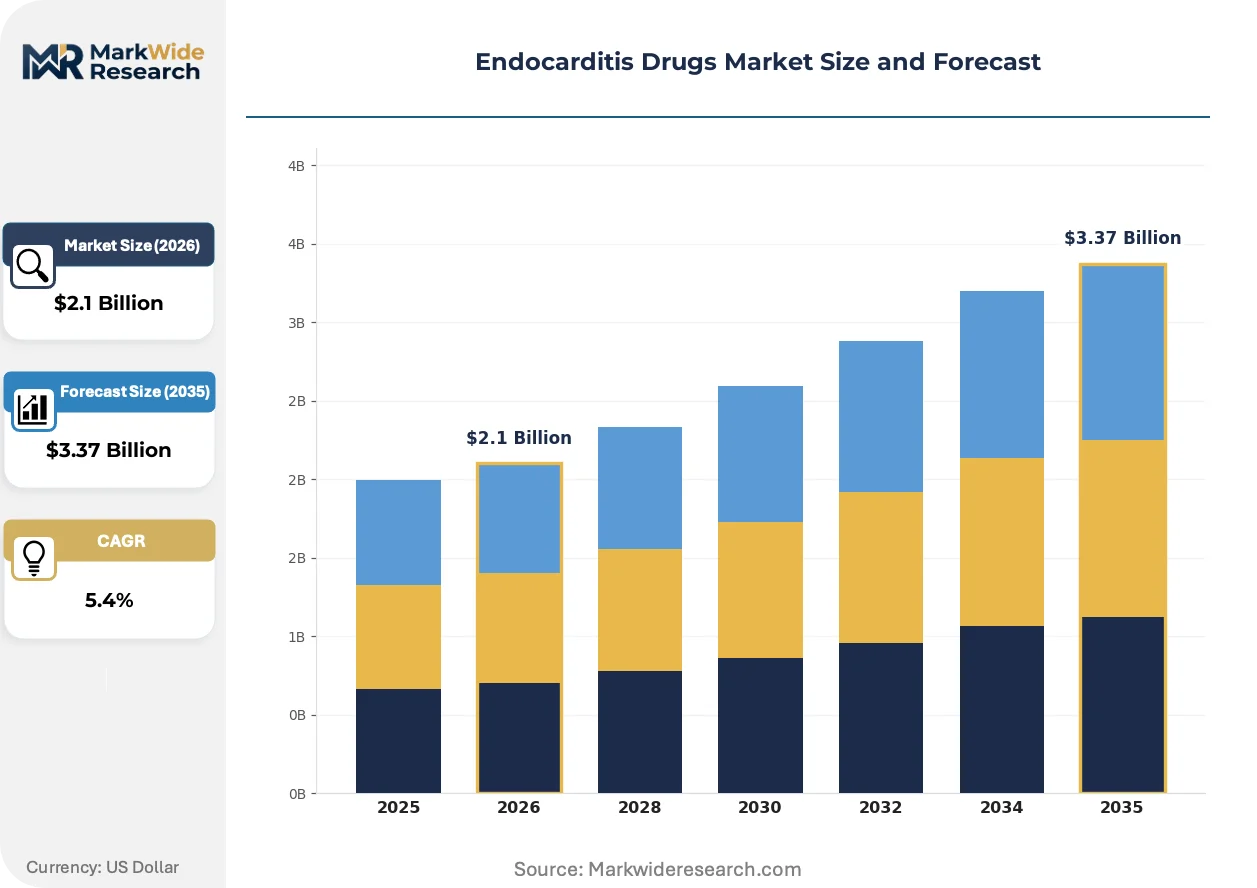
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Penicillins, Cephalosporins, Aminoglycosides, Vancomycin Administration Route: Intravenous, Oral, Intramuscular, Inhalation End User: Hospitals, Clinics, Home Care, Outpatient Facilities Therapeutic Area: Cardiology, Infectious Diseases, Internal Medicine, Emergency Medicine |
| Companies Covered | F. Hoffmann-La Roche Ltd., Fresenius Kabi AG, Pfizer Inc., Eli Lilly and Company, Basilea Pharmaceutica Ltd., Novartis AG, Teva Pharmaceutical Industries Limited, Allergan, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endocarditis Drugs Market Shifts & Advancements
Endocarditis therapeutics are converging on precision-targeted delivery systems and ambulatory care models that compress hospital dependency while elevating pharmacokinetic optimization.
Pharmacokinetic-guided dosing software is decentralizing vancomycin therapeutic drug monitoring from centralized hospital laboratories to point-of-care platforms. Community hospitals and urgent infusion centers are adopting cloud-based Bayesian forecasting tools at accelerating pace. This capability compression is enabling earlier discharge decisions and reducing nephrotoxicity event rates through real-time exposure adjustment.
REACH registration requirements in Europe are reshaping environmental risk assessment obligations for anti-infective manufacturers, particularly for aminoglycoside discharge into wastewater streams. Pharmaceutical sponsors must now submit extended aquatic toxicity data packages prior to market authorization. Injectable antibiotic portfolios face reformulation pressures in Germany and France where river basin contamination thresholds are tightening fastest.
Hospital purchasing cooperatives are consolidating endocarditis drug procurement through sole-source agreements with integrated delivery networks, displacing fragmented individual hospital contracting. Group Purchasing Organizations like Vizient and Premier are extracting volume commitments for standardized dual-therapy kits. This channel concentration is most visible in the United States where IDN consolidation has reduced independent community hospital negotiating leverage by half over the past decade.
Endocarditis Drugs Market Segmentation
Endocarditis drug procurement diverges sharply across clinical settings, with FDA and EMA approval pathways dictating which formulations penetrate acute care versus ambulatory channels. Stewardship programs filter segment selection through pharmacoeconomic lenses, compressing formulary diversity while elevating targeted therapy positioning.
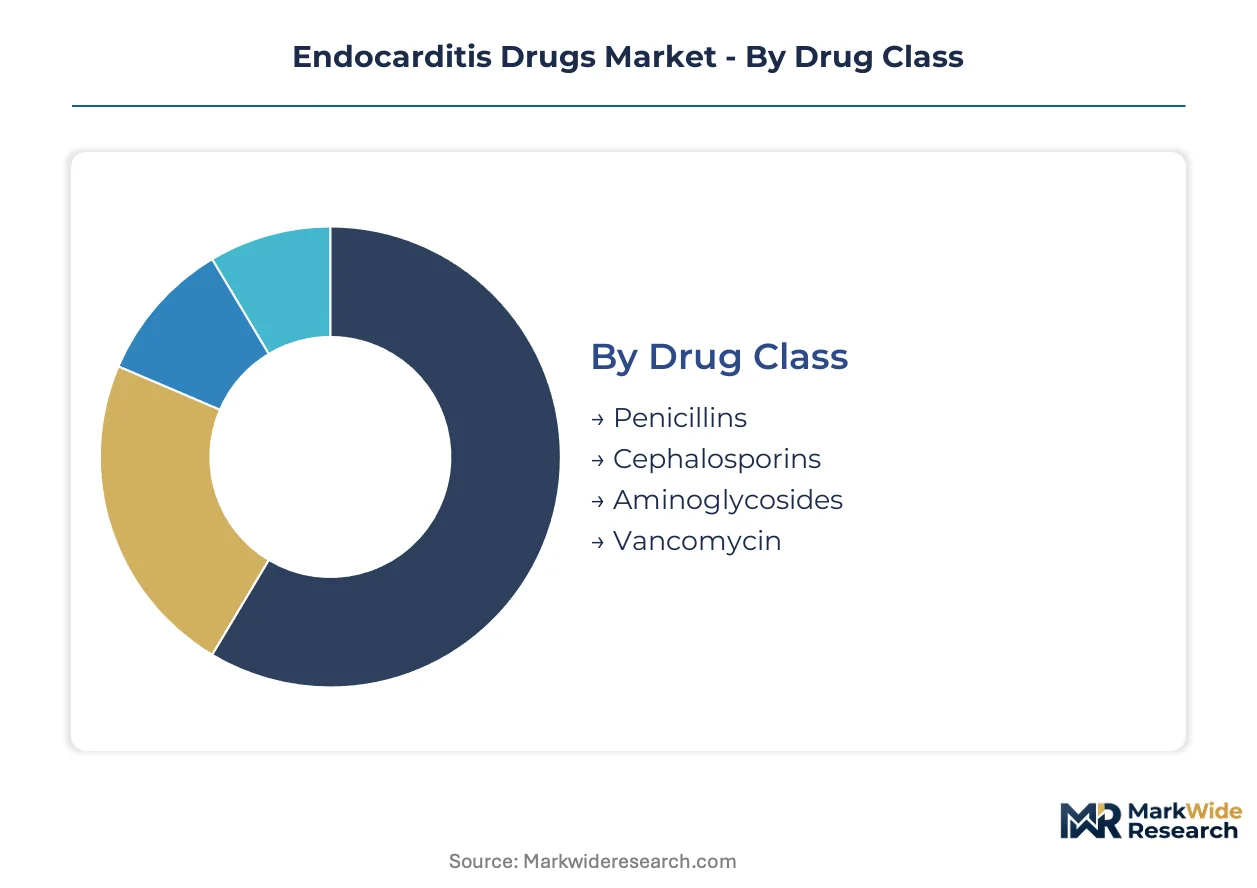
Drug Class:
FDA antibacterial drug development guidance and EMA orphan drug incentives create divergent certification burdens across antimicrobial categories, with glycopeptide and lipopeptide pathways requiring extended renal safety databases.
- Penicillins:Beta-lactam agents such as penicillin G and ampicillin retain foundational status in streptococcal endocarditis protocols. Academic medical centers in the United States anchor demand for high-dose continuous infusion regimens, though beta-lactamase resistance patterns constrain empiric deployment.
- Cephalosporins:Injectable third-generation agents deliver gram-negative coverage extension critical for polymicrobial prosthetic valve infections. Fresenius Kabi AG and comparable compounders dominate supply chains with generic ceftriaxone, eroding branded margin structures through hospital GPO contracts.
- Aminoglycosides:Gentamicin and streptomycin provide synergistic bactericidal activity against enterococci in combination regimens. FDA and Health Canada pharmacovigilance mandates require intensive therapeutic drug monitoring, inflating nursing labor costs per treatment course.
- Vancomycin:Glycopeptide standard for methicillin-resistant Staphylococcus aureus coverage with nephrotoxicity surveillance constraints.
Vancomycin sits at the top of the volume ranking, with cephalosporins climbing the fastest as oral step-down protocols mature.
Administration Route:
Route selection determines reimbursement coding complexity, with intravenous formulations commanding higher facility fees under Medicare Severity Diagnosis-Related Groups while oral equivalents trigger pharmacy benefit manager scrutiny.
- Intravenous:Extended-interval dosing of vancomycin and aminoglycosides achieves bactericidal concentrations required for vegetation sterilization. Hospital-based infectious disease departments in the United States drive protocol standardization, with pharmacokinetic-guided dosing software compressing therapeutic drug monitoring turnaround.
- Oral:Step-down regimens following intravenous stabilization enable outpatient parenteral antimicrobial therapy program expansion. Maturing OPAT infrastructure creates new reimbursement pathways, though bioavailability concerns limit agent selection to fluoroquinolones and linezolid derivatives.
- Intramuscular:Ceftriaxone depot formulations support community-based treatment completion in resource-limited settings.
- Inhalation:Investigational liposomal delivery systems target pulmonary septic emboli complications.
Intravenous administration retains dominant volume position, with oral delivery gaining share fastest as length-of-stay reduction incentives intensify.
End User:
Facility type determines formulary control mechanisms, with integrated delivery networks extracting volume commitments through sole-source agreements that displace fragmented individual hospital contracting.
- Hospitals:Academic medical centers anchor the largest volume of guideline-directed endocarditis management in the United States. Antimicrobial stewardship programs systematically replace empiric broad-spectrum protocols with pathogen-directed therapy, elevating pharmacoeconomic scrutiny of every agent selection.
- Clinics:Infectious disease specialty practices coordinate transition from inpatient to ambulatory parenteral therapy. Baylor Scott and White and comparable systems in Texas demonstrate scalable OPAT infrastructure deployment.
- Home Care:Infusion nursing services enable treatment completion outside institutional walls.
- Outpatient Facilities:Urgent infusion centers adopt cloud-based Bayesian forecasting tools for decentralized monitoring.
Hospitals command the volume ranking, with outpatient facilities expanding most quickly as site-of-neutral payment models advance.
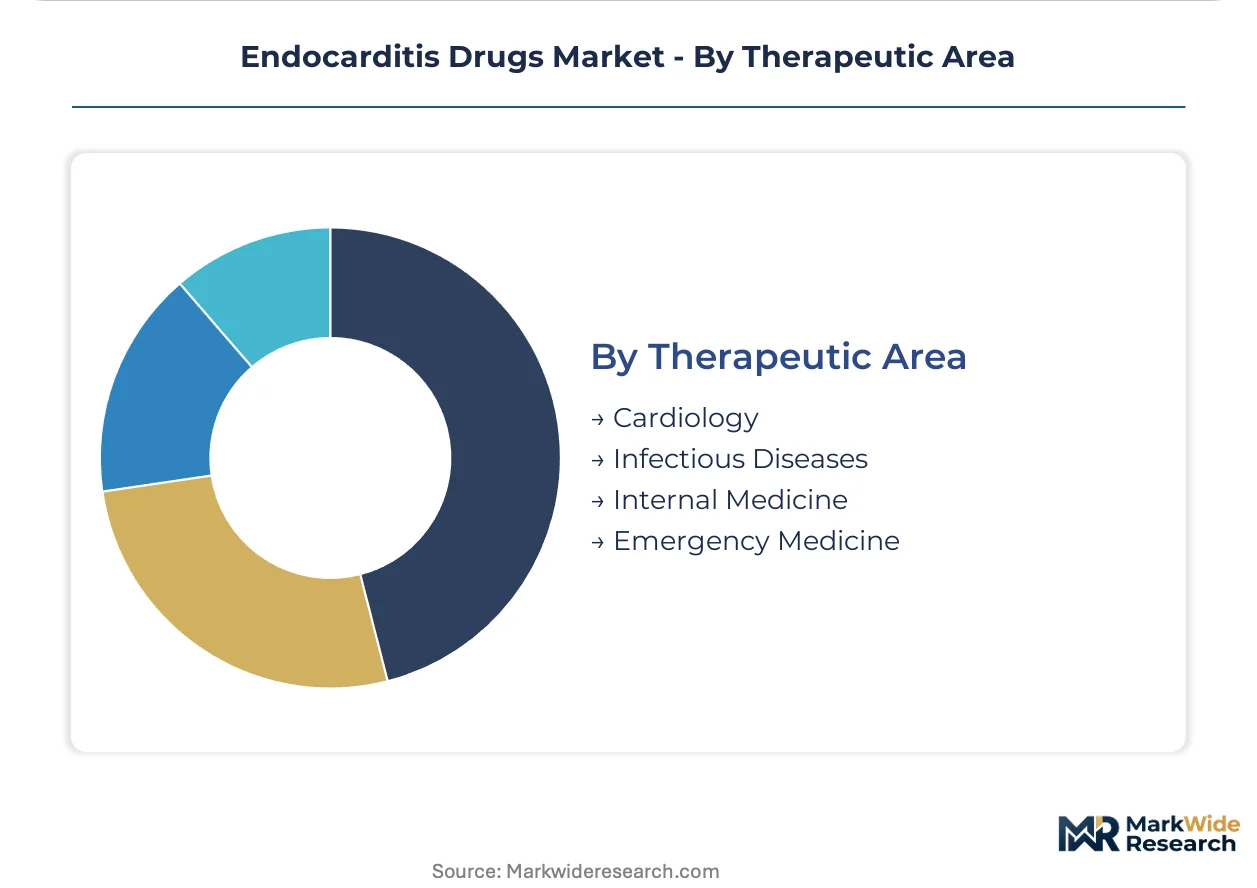
Therapeutic Area:
Specialty board certification requirements shape prescribing authority, with cardiology and infectious disease fellowship training creating distinct therapeutic algorithm preferences.
- Cardiology:Cardiac surgeons and structural interventionalists prioritize valve preservation outcomes in prosthetic device infections. Cleveland Clinic and Mayo Clinic anchor demand for multidisciplinary endocarditis team protocols combining surgical and medical management.
- Infectious Diseases:Fellowship-trained specialists direct empiric-to-targeted therapy transitions and duration optimization. Scarcity of ID-pharmacy dual-trained clinicians constrains stewardship program expansion velocity across community hospital systems.
- Internal Medicine:Hospitalists manage uncomplicated native valve presentations under protocolized pathways.
- Emergency Medicine:Emergency departments initiate empiric coverage pending blood culture results.
Infectious diseases specialization sits at the top of the volume ranking, with cardiology integration climbing the fastest as surgical referral networks formalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Injectable antibiotic manufacturing for endocarditis protocols originated in European pharmaceutical clusters during the mid-twentieth century, with Basel and Frankfurt anchoring early glycopeptide production scale-up before Asian API infrastructure assumed dominant supply positions.
United States
Academic medical centers in Boston and Houston drive protocol standardization for guideline-directed endocarditis management. FDA antibacterial drug development guidance reshapes clinical trial endpoints for novel agents targeting prosthetic valve infections. Cleveland Clinic anchors multidisciplinary team protocols combining surgical intervention with extended-interval vancomycin dosing.
Germany
Hospital antimicrobial stewardship programs in Bavaria and North Rhine-Westphalia systematically replace empiric broad-spectrum protocols with pathogen-directed therapy. REACH registration requirements impose extended aquatic toxicity data obligations on aminoglycoside manufacturers prior to market authorization. Frankfurt's parenteral compounding infrastructure supports standardized dual-therapy kit distribution across integrated delivery networks.
Japan
PMDA's Specified Disease Treatment Research Program creates accelerated approval pathways for intractable infections including resistant gram-positive endocarditis. METI funding priorities favor nanotechnology convergence with anti-infective pharmacology for extended-interval dosing platforms. Osaka-based research hospitals pilot pharmacokinetic-guided dosing software for decentralized therapeutic drug monitoring.
India
CDSCO regulatory pathways for injectable antibiotics attract contract manufacturing investment from European and North American sponsors seeking cost-competitive API production. Maharashtra's pharmaceutical clusters around Mumbai and Pune specialize in generic cephalosporin bulk manufacturing for hospital procurement cooperatives. Hospital infrastructure expansion in Delhi-NCR creates demand for standardized endocarditis treatment protocols.
Switzerland
Swissmedic orphan drug incentives align with EMA frameworks to attract sponsor investment in novel anti-infective delivery systems for resistant endocarditis therapies. Basel anchors concentrated R&D intensity in liposomal formulation technologies. Roche and Novartis heritage clusters maintain specialized manufacturing capabilities for high-potency injectable antibiotics.
Endocarditis Drugs Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with captive manufacturing infrastructure. Hospital formulary consolidation through group purchasing organizations compresses vendor diversity while elevating scale-based procurement advantages. Three archetypes dominate: integrated Big Pharma with stewardship program relationships, generic injectable compounders with GPO contract density, and specialty anti-infective developers with orphan drug positioning. Competitive moves concentrate on manufacturing scale expansion and strategic partnerships for combination therapy kit standardization.
Among diversified pharmaceutical conglomerates, Pfizer Inc., Novartis AG, and Fresenius Kabi AG occupy distinct positioning vectors. Pfizer represents the manufacturing-scale archetype with dominant injectable cephalosporin supply chain presence. Novartis exemplifies targeted R&D intensity in drug delivery system innovation. Fresenius Kabi anchors hospital-critical care channels through parenteral compounding infrastructure. Eli Lilly and Company, Merck & Co., Inc., and Teva Pharmaceutical Industries Limited sit within mid-tier scale positions, while Basilea Pharmaceutica Ltd. and F. Hoffmann-La Roche Ltd. represent specialized anti-infective development orientations.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Fresenius Kabi AG |
| Pfizer Inc. |
| Eli Lilly and Company |
| Basilea Pharmaceutica Ltd. |
| Novartis AG |
| Teva Pharmaceutical Industries Limited |
| Allergan |
| Merck & Co., Inc. |
| Others |
Supply & Pricing Matrix
Vancomycin-to-cephalosporin cost bifurcation separates premium glycopeptide therapy from commodity beta-lactam substitution across hospital formularies, with this tier divergence manifesting in both procurement contracting structures and API sourcing geographies. Stewardship-driven formulary compression elevates pharmacoeconomic scrutiny of every agent selection while GPO volume commitments harden price transparency across integrated delivery networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs endocarditis drug procurement, with glycopeptide premiums reflecting FDA-mandated renal safety databases and generic cephalosporin economy tiers anchored in Fresenius Kabi contract density. Price differentiation hinges on therapeutic drug monitoring bundling and stewardship program certification status. Cost compression in the aminoglycoside segment intensifies because nursing labor surveillance requirements inflate per-treatment course economics. Community hospital systems exhibit highest price sensitivity, while academic medical centers prioritize clinical outcome metrics over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Frankfurt and Basel anchor European hospital-critical care channels, with hub-and-spoke patterns radiating parenteral compounding infrastructure toward integrated delivery networks. API manufacturing concentrates in India, China, and Switzerland, with Maharashtra pharmaceutical clusters feeding generic cephalosporin bulk to procurement cooperatives. Injectable glycopeptide production draws from Asian fermentation capacity and European finishing facilities. Single-source vulnerability in vancomycin API exposes hospital procurement to geopolitical shipment disruptions. Distribution runs through group purchasing organization contracts that displace fragmented individual hospital negotiating leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA antibacterial drug development guidance operates as a regulatory compounder, with updated clinical trial endpoint requirements accelerating novel agent pathways and reshaping pharmacoeconomic validation standards across hospital formularies.
For Market Incumbents: Anchor manufacturing scale advantages through captive parenteral compounding infrastructure expansion in hospital-critical care channels. Defend against generic substitution pressure by deepening stewardship program relationships and pharmacokinetic-guided dosing software integration. Vertical integration into liposomal formulation R&D preserves margin structures against commodity cephalosporin erosion. For New Entrants and Emerging Players: Long-acting liposomal delivery platforms offer technology-first positioning against entrenched injectable supply chains. Sub-Saharan Africa hospital infrastructure expansion presents the most penetrable geography, with Nigeria and Kenya cardiac surgery programs creating first-mover windows for standardized dual-therapy kits. Partner with regional distributors possessing cold-chain logistics capability rather than building direct hospital sales forces. For Investors and Strategic Acquirers: Consolidation pressure builds where ID-pharmacy specialist scarcity constrains stewardship program implementation velocity across community hospital systems. Five-to-ten year viability favors sponsors with orphan drug positioning in resistant gram-positive therapies and nanotechnology-enabled extended-interval dosing platforms. Monitor PMDA accelerated approval pathway utilization rates as inflection indicator for novel anti-infective delivery system investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Stewardship Program Partnership | Hospital formulary access locks in protocol-driven demand for targeted gram-positive coverage agents. |
| Liposomal Formulation R&D Investment | Nanotechnology convergence with anti-infective pharmacology reduces nursing burden and length-of-stay metrics. |
| OPAT Infrastructure Expansion | Outpatient parenteral antimicrobial therapy maturation creates new reimbursement pathways for oral step-down regimens. |
| Generic API Backward Integration | Captive supply of cephalosporin active pharmaceutical ingredients defends margin structures against compounder competition. |
| Regulatory Orphan Drug Positioning | EMA and Swissmedic incentives attract sponsor investment in resistant endocarditis therapies with extended market exclusivity. |
Research Methodology
Direct dialogue with infectious disease pharmacists, hospital procurement managers, formulary directors, and regulatory affairs specialists grounded qualitative insights, cross-referenced against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital GPO contract databases. Bottom-up and top-down triangulation validated volume estimates across drug class, administration route, and end-user segments.
Bottom-up modeling anchored in treatment protocol penetration rates and dosing duration assumptions, while top-down analysis cross-checked against antimicrobial expenditure reports from academic medical centers. Segmentation dimensions spanned drug class, administration route, end-user facility type, and regional regulatory cluster. CAGRs derived from epidemiological trend extrapolation and formulary adoption curve analysis, with pharmacokinetic-guided dosing software penetration and OPAT infrastructure expansion serving as key demand elasticity inputs.
The model holds under stable CLSI breakpoint revision timelines and continued GPO consolidation; deviation in vancomycin supply chain disruption severity or ID-pharmacy workforce expansion rates would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Atorvastatin API Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Clozapine Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Chloramphenicol Eye Drops Market
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Global Benzodiazepines Market
Pharmaceuticals
Germany Opioids Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Global Opioid Induced Constipation Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Obsessive Compulsive Disorder (OCD) Drug Market
Pharmaceuticals
Medicinal Fungi Market