
 Canada Dental Devices Market | 2026-2036
Canada Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Dental Devices Market Insights
Equipment leasing and managed service agreements is reconfiguring competitive dynamics across the Canada Dental Devices Market, lowering capital barriers for mid-sized dental groups seeking advanced imaging and milling systems. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to anchor premium positioning among Canadian university dental schools and large clinic networks. Straumann Group competes through specialized implantology workflows that dominate the surgical segment in Quebec and Ontario. Henry Schein, Inc. controls distribution reach through its direct sales force serving independent practitioners in secondary Canadian cities.
Canada dental devices encompass instruments, equipment, and consumables engineered to ISO 13485 quality management standards for diagnosis, treatment, and prevention of oral conditions, with critical specifications including biocompatibility per ISO 10993 and sterilization validation per CSA Z314. These products serve licensed dental professionals across clinical, hospital, and research settings where precision tolerances of ±5 micrometers govern prosthetic fit and long-term patient outcomes. Dental implants and digital impression systems represent the fastest-expanding product categories as Canadian practitioners replace conventional polyvinyl siloxane molds with intraoral scanning platforms. Restorative materials maintain mature, high-margin positions driven by recurring consumable demand from established dental clinics. Preventive care products occupy volume-leading status through broad distribution across retail pharmacy and direct-to-practitioner channels.
Health Canada's Medical Devices Directorate, the Canadian Dental Association's infection control guidelines, and CSA Group's electrical safety standards collectively govern market access, product registration timelines, and clinical adoption protocols for dental technologies nationwide. Provincial dental regulatory colleges in Ontario, Alberta, and British Columbia layer additional equipment sterilization and operator training requirements that shape purchasing criteria for clinic owners. Stakeholders must monitor Health Canada's transition toward enhanced post-market surveillance obligations and the potential harmonization of Canadian medical device regulations with FDA quality system requirements, as these shifts will determine which manufacturers can sustain market presence without costly regulatory duplication.
Market Dynamics
Digital dentistry platforms are compressing equipment replacement cycles across Canadian dental practices, as intraoral scanners and chairside milling systems displace analog impression workflows and outsourced laboratory relationships.
Growth Catalysts
- Health Canada Class II/III licensing acceleration:Streamlined Medical Devices Directorate pathways for CAD/CAM systems are shortening time-to-market for manufacturers with established ISO 13485 quality systems.
- Ontario dental service organization consolidation:Multi-site practice networks in the Greater Toronto Area are standardizing procurement across locations, creating volume commitments that justify premium technology investments.
- Intraoral scanning adoption:Digital impression systems eliminate polyvinyl siloxane material costs while improving patient throughput in high-volume urban clinics.
Market Restraints
- Titanium and zirconia supply concentration:Implant manufacturers face input cost volatility tied to global raw material markets beyond domestic hedging capacity.
- CSA Z314 sterilization validation requirements:Compliance timelines for reusable surgical instruments create working capital burdens for distributors managing inventory turns.
- Legacy analog laboratory networks:Conventional crown-and-bridge laboratories in secondary Canadian cities resist volume erosion from chairside milling adoption.
Strategic Opportunities
- Prairie province penetration:Saskatchewan and Manitoba independent practitioners remain underpenetrated by digital workflow vendors focused on Vancouver and Toronto corridors.
- Managed service agreements:Equipment leasing bundled with software subscriptions and preventive maintenance is lowering capital barriers for mid-sized dental groups.
- Health Canada-FDA harmonization potential:Alignment of quality system requirements would reduce regulatory duplication costs for manufacturers serving both markets.
Industry Challenges
- CAD/CAM technician training gaps:Dental schools and continuing education programs struggle to produce sufficient operators proficient in digital design software.
- Legacy practice management system integration:Intraoral scanners and milling units require middleware development to connect with established patient record platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Dental Devices Market |
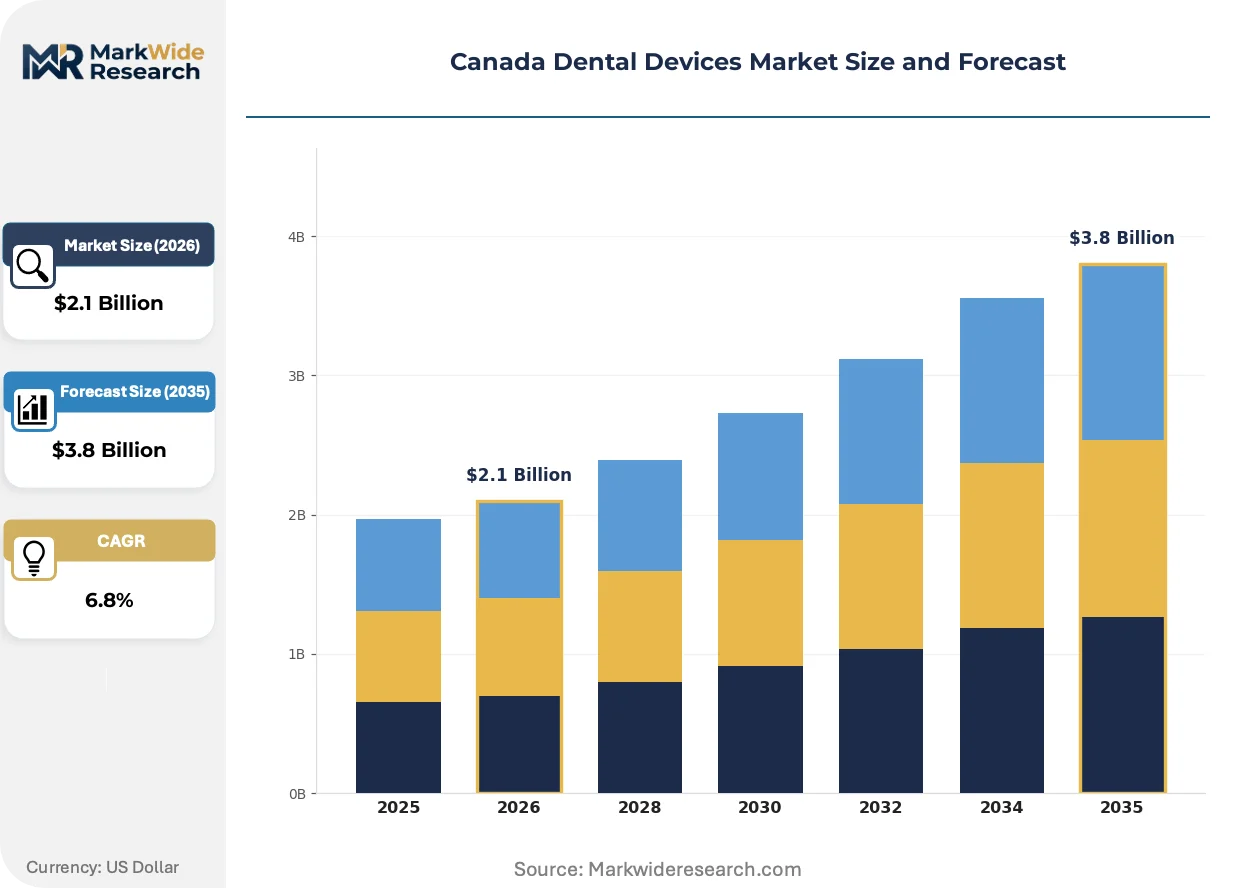
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Implants, Orthodontic Devices, Restorative Materials, Preventive Care Products End User: Dental Clinics, Hospitals, Research Institutions, Home Care Technology: CAD/CAM, Cone Beam CT, Laser Dentistry, Digital Impressions Application: Cosmetic Dentistry, Surgical Procedures, Oral Hygiene, Diagnostics |
| Companies Covered | Dentsply Sirona, 3M, Carestream Health, A-Dec Inc., Patterson Companies Inc., Envista Holdings Corp., Straumann Group, Henry Schein, Inc., Align Technology, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Dental Devices Market Trends and Innovations
Canadian dental device procurement is pivoting from capital purchase models toward subscription-based access, while regulatory pressure and patient expectations accelerate the obsolescence of analog clinical workflows.
Intraoral scanning technology captures three-dimensional dental anatomy without elastomeric impression materials, eliminating patient discomfort and laboratory shipping delays. Multi-site dental service organizations in British Columbia and Ontario are deploying these systems across their networks within compressed 18-to-24-month standardization windows. Chairside milling is rendering obsolete the conventional two-visit crown preparation model that dominated Canadian restorative dentistry for decades.
Health Canada's Medical Devices Directorate is tightening post-market surveillance obligations for Class III implantable devices, requiring manufacturers to submit periodic safety updates and adverse event analyses. This regulatory shift is extending product lifecycle management costs for dental implant suppliers while creating compliance differentiation among vendors with robust pharmacovigilance infrastructure. Surgical implantology segments in Quebec and Alberta are responding by consolidating supplier relationships toward manufacturers with established Canadian regulatory affairs capabilities.
Leasing structures combined with per-procedure software licensing are displacing outright equipment ownership among mid-sized dental groups seeking to preserve balance sheet flexibility. Independent practitioners in secondary Canadian cities are accessing premium imaging and milling technologies through managed service agreements that bundle hardware, maintenance, and consumable supply. This financing innovation is most visible in Alberta and Atlantic Canada, where dental clinic ownership fragmentation previously constrained capital deployment for digital workflow adoption.
Canada Dental Devices Market Segmentation
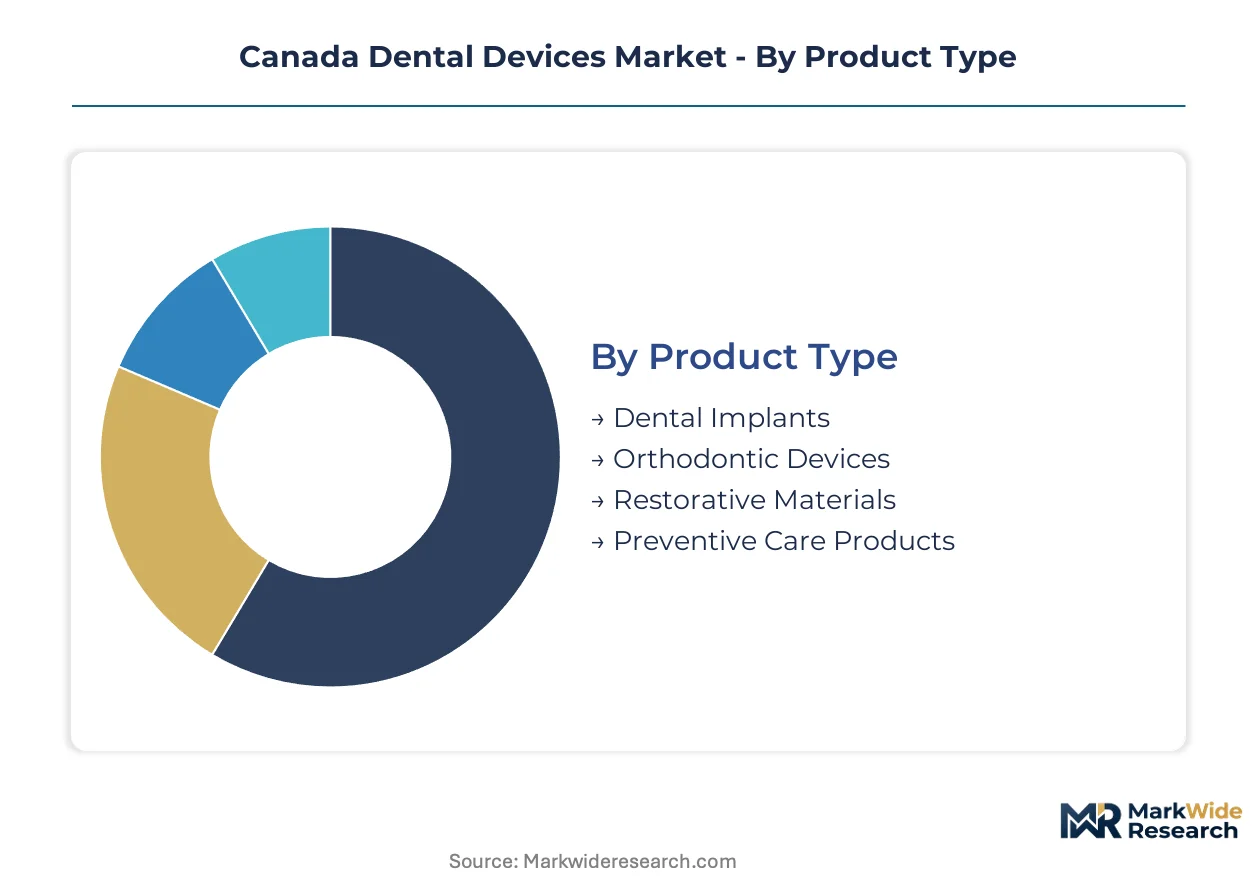
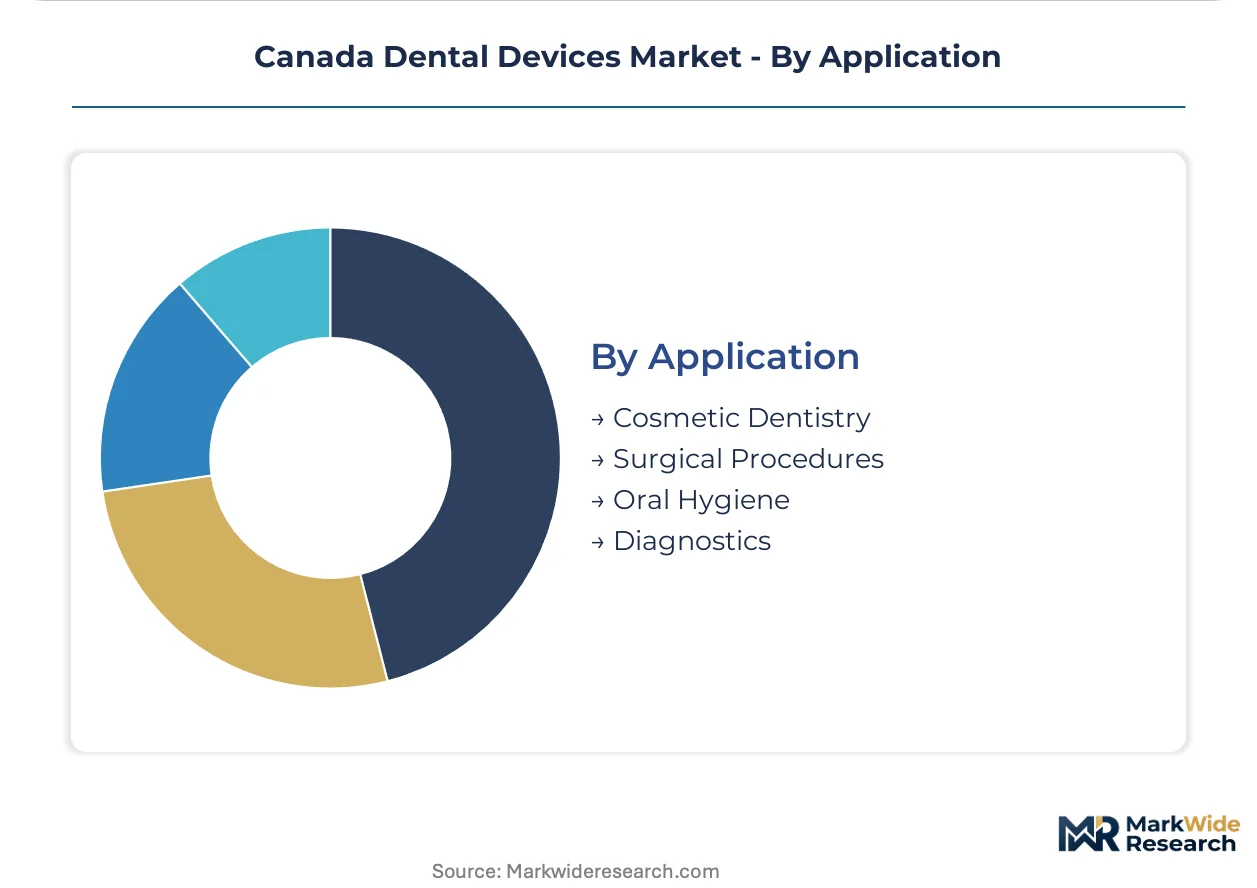
Segmentation in the Canada Dental Devices Market reveals distinct procurement patterns across product categories, with digital workflows commanding premium pricing while consumable materials generate recurring revenue streams. Understanding these divisions clarifies where capital investment concentrates versus where operational budgets flow.
Product Type:
After-sales service intensity varies sharply across dental product categories, with implant systems requiring surgical support and restorative materials demanding minimal technical intervention.
- Dental Implants:Titanium and zirconia fixtures with surface modifications for osseointegration, governed by Health Canada Class III licensing. Demand concentrates in Quebec and Ontario surgical centers where Straumann and Dentsply Sirona maintain dedicated field engineering teams for case planning support.
- Orthodontic Devices:Clear aligner systems and fixed appliances manufactured to patient-specific digital prescriptions. British Columbia's dental service organizations are standardizing aligner platforms across multi-site networks, compressing procurement timelines for traditional bracket systems.
- Restorative Materials:Composite resins, glass ionomers, and ceramic formulations with ISO 10993 biocompatibility validation.
- Preventive Care Products:Fluoride varnishes, sealants, and prophylaxis consumables distributed through Henry Schein's direct sales network to independent Ontario practitioners.
Restorative materials hold the largest share; momentum sits with dental implants.
End User:
Customer type determines purchasing authority, with consolidated dental service organizations negotiating enterprise contracts while independent practitioners rely on distributor relationships.
- Dental Clinics:Private practices and corporate chains performing diagnosis, treatment, and preventive services. The Greater Toronto Area's consolidated clinic networks are deploying standardized CAD/CAM equipment across locations, creating volume commitments that reshape distributor margins.
- Hospitals:Academic medical centers and community hospitals with oral surgery departments. Vancouver General Hospital and McGill University Health Centre anchor demand for advanced imaging and implantology infrastructure in their respective provinces.
- Research Institutions:University dental schools conducting clinical trials and materials science investigation.
- Home Care:Direct-to-consumer whitening systems and orthodontic monitoring devices sold through retail pharmacy channels.
Dental clinics dominate volume; hospitals are climbing the fastest in per-site technology expenditure.
Technology:
Maturity curves separate established imaging modalities from emerging digital workflows, with replacement cycles compressing as software subscription models displace capital purchases.
- CAD/CAM:Computer-aided design and manufacturing systems integrating intraoral scanning with chairside milling. Dentsply Sirona's ecosystem anchors premium positioning among Canadian university dental schools requiring comprehensive training infrastructure.
- Cone Beam CT:Three-dimensional radiographic systems with sub-millimeter resolution for implant planning and endodontic assessment. Alberta's independent practitioners are adopting these systems through managed service agreements that bundle hardware with preventive maintenance.
- Laser Dentistry:Soft and hard tissue lasers for periodontal and restorative applications with CSA electrical safety certification requirements.
- Digital Impressions:Intraoral scanners eliminating polyvinyl siloxane materials from crown-and-bridge workflows.
Cone Beam CT holds installed base leadership; digital impressions are gaining share fastest through Ontario and British Columbia clinic standardization programs.
Application:
Procedure reimbursement patterns from provincial health plans and private insurance shape technology allocation across cosmetic, surgical, hygiene, and diagnostic applications.
- Cosmetic Dentistry:Veneer, whitening, and aesthetic restoration procedures with limited public coverage. Vancouver and Toronto metropolitan corridors concentrate demand where patient out-of-pocket spending supports premium material selection.
- Surgical Procedures:Implant placement, bone grafting, and periodontal surgery requiring sterile field protocols. Quebec's regulatory colleges enforce equipment sterilization standards per CSA Z314 that elevate capital requirements for surgical suite certification.
- Oral Hygiene:Preventive scaling, prophylaxis, and patient education services.
- Diagnostics:Radiographic imaging, caries detection, and oral cancer screening with Health Canada Class II device registration.
Surgical procedures command the highest per-procedure device intensity; cosmetic dentistry is expanding most quickly in private-pay urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada's Medical Devices Directorate licensing framework and provincial procurement consolidation programs are concentrating device demand in Ontario and British Columbia metropolitan corridors.
Ontario
Dental service organizations in the Greater Toronto Area are standardizing CAD/CAM equipment across multi-site networks within compressed 18-month procurement windows. The Royal College of Dental Surgeons of Ontario enforces equipment sterilization protocols per CSA Z314 that elevate capital requirements for clinic certification. Toronto's consolidated clinic networks are deploying intraoral scanners at scale, displacing conventional polyvinyl siloxane workflows.
British Columbia
Private dental clinic chains in Vancouver are expanding equipment procurement budgets as digital dentistry platforms replace legacy analog systems. Health Canada Class II device registration timelines for cone beam CT systems are accelerating compliance investments among regional distributors. The Vancouver metropolitan corridor anchors demand for advanced imaging infrastructure serving high-volume urban practices.
Quebec
Surgical implantology segments in Montreal are consolidating supplier relationships toward manufacturers with established Canadian regulatory affairs capabilities. The Ordre des dentistes du Québec enforces continuing education requirements for digital workflow adoption that shape purchasing criteria for clinic owners. Montreal's university dental schools are anchoring demand for comprehensive CAD/CAM training infrastructure.
Alberta
Independent practitioners in Calgary and Edmonton are accessing premium imaging technologies through managed service agreements that bundle hardware with preventive maintenance. Health Canada's transition toward enhanced post-market surveillance obligations for Class III implantable devices is extending product lifecycle management costs for regional suppliers. Alberta's secondary cities are experiencing compressed equipment replacement cycles as digital platforms displace analog workflows.
Prairie Provinces
Saskatchewan and Manitoba independent practitioners remain underpenetrated by digital workflow vendors historically focused on Vancouver and Toronto corridors. Provincial regulatory colleges in these provinces layer additional operator training requirements that slow technology adoption relative to coastal markets. Winnipeg and Saskatoon clinic networks are beginning to standardize procurement through emerging dental service organizations.
Canada Dental Devices Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers capable of delivering end-to-end digital workflows spanning imaging, design, and manufacturing. Tiered competitive positioning separates premium ecosystem vendors from specialized component suppliers and broad-line distributors. Two strategic archetypes dominate: integrated CAD/CAM platform providers anchoring university and large clinic network relationships, and specialized implantology workflow vendors dominating surgical segments. Competitive dynamics center on strategic partnerships with dental service organizations and portfolio diversification into subscription-based service models.
Among North American-integrated platform providers, Dentsply Sirona and Envista Holdings Corp. exemplify the premium ecosystem archetype through comprehensive digital dentistry infrastructure. Straumann Group occupies a specialized position within implantology workflows, particularly across Quebec and Ontario surgical centers. Henry Schein, Inc. represents the distribution-centric model, leveraging direct sales force coverage to serve independent practitioners in secondary Canadian cities. These three company structures illustrate how competitive positioning fragments across integrated platform, specialized surgical, and broad distribution vectors.
| Leading Market Players |
|---|
| Dentsply Sirona |
| 3M |
| Carestream Health |
| A-Dec Inc. |
| Patterson Companies Inc. |
| Envista Holdings Corp. |
| Straumann Group |
| Henry Schein, Inc. |
| Align Technology, Inc. |
| Others |
Pricing and Supply Chain Analysis
Titanium and zirconia feedstock concentration in Chinese and Japanese metallurgical facilities anchors margin capture at the implant fixture tier, while Canadian distributors absorb working capital burdens from CSA Z314 sterilization validation timelines. Health Canada Class III licensing requirements create certification-grade pricing spreads that separate premium ecosystem vendors from standard-tier component suppliers.
Pricing Analysis
Certification level creates the primary spread across the Canada Dental Devices Market, with ISO 13485-validated CAD/CAM systems commanding premium positioning against non-certified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and software subscription depth. Cost compression in the standard tier is intensifying because independent practitioners in secondary cities negotiate volume commitments through dental service organization procurement networks. Mid-sized dental groups exhibit highest price sensitivity due to balance sheet constraints, while university dental schools show lowest sensitivity given training infrastructure requirements.
Supply Chain Analysis
Extended payment terms from Henry Schein's distribution network and supply-chain finance facilities from Patterson Companies are easing inventory carrying costs for independent practitioners. Manufacturing concentration in Germany, Switzerland, and the United States feeds precision milling equipment and implant surface technologies into Canadian ports. Raw material dependencies on titanium sponge, zirconia powder, and optical sensor arrays expose distributors to commodity price volatility from aerospace and electronics sector demand competition. Distribution runs through direct sales forces serving consolidated clinic networks alongside regional distributors covering independent practitioners in Atlantic Canada and the Prairie Provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada Dental Devices Market operates as a regulatory entrenchment story where Health Canada licensing timelines and provincial college equipment sterilization mandates create switching costs that protect incumbent positions. Network effects from CAD/CAM ecosystem standardization across dental service organization chains reinforce this defensive structure.
For Market Incumbents: Build regulatory affairs infrastructure as the primary moat by expanding Health Canada Medical Devices Directorate liaison capabilities and accelerating adverse event reporting systems ahead of enhanced post-market surveillance obligations. Consolidate channel control through exclusive managed service agreements with Ontario and British Columbia dental service organizations to lock out emerging platform competitors. Counter the threat from cloud-native software entrants by deepening in-house production of middleware connecting legacy practice management systems to digital impression hardware. For New Entrants and Emerging Players: Saskatchewan and Manitoba independent practitioners present the most penetrable geographic white space, with regulatory college training requirements lagging coastal adoption curves by 24-36 months. Target Alberta secondary cities through equipment leasing bundled with CSA Z314 compliance consulting to differentiate from established distributors focused on Toronto and Vancouver corridors. Deploy direct-to-practitioner digital marketing bypassing Henry Schein's sales force coverage as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap CAD/CAM component specialists with established ISO 13485 quality systems and Health Canada registration pathways already cleared. Long-term viability over the next decade hinges on regulatory harmonization potential between Health Canada and FDA quality system requirements that would reduce compliance duplication costs. Watch for Health Canada-FDA alignment announcements as the critical inflection signal indicating which manufacturers can sustain cross-border market presence without redundant certification investments.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class III Licensing Acceleration | Shortens time-to-market for CAD/CAM manufacturers with established ISO 13485 quality infrastructure. |
| Dental Service Organization Partnership | Creates volume commitments across Ontario and British Columbia multi-site clinic networks. |
| Managed Service Agreement Expansion | Lowers capital barriers for mid-sized dental groups in Alberta and Atlantic Canada. |
| CSA Z314 Compliance Consulting Bundle | Differentiates distributors serving Quebec and Ontario surgical centers facing sterilization validation timelines. |
| Digital Workflow Training Infrastructure | Addresses technician proficiency gaps at McGill and University of Toronto dental schools. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dental clinic owners, biomedical equipment procurement managers, and Health Canada regulatory affairs specialists; and secondary validation against hospital procurement databases, GPO contracts, and CSA Group standards documentation. Bottom-up triangulation from provincial dental college equipment registries and top-down cross-check against distributor shipment records anchored volume estimates. Primary fieldwork concentrated in the Greater Toronto Area, Vancouver metropolitan corridor, and Montreal surgical centers to capture procurement pattern variation across consolidated and independent practice archetypes.
Forecast inputs considered technology adoption curves across CAD/CAM, cone beam CT, and intraoral scanning platforms alongside provincial reimbursement policy trajectories and dental service organization consolidation timelines. Segmentation modeling spanned product type, end user category, technology maturity tier, and application intensity across the analysis window. CAGRs derived from equipment replacement cycle compression rates observed in Ontario and British Columbia standardization programs, weighted against Prairie province adoption lag factors. Implant surface technology innovation pipelines and clear aligner platform penetration rates served as industry-specific demand drivers.
Practitioners should monitor Health Canada-FDA harmonization progress, titanium and zirconia commodity price volatility, and dental service organization merger activity for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Dental Calipers Market
Dental Devices
Chile Dental Devices Market
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
Dental Chair Market
Dental Devices
South Korea Dental Devices Market
Dental Devices
Dental Caries and Endodontic Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Europe Dental Implants Market
Dental Devices
Dental Suction Mirror Market
Dental Devices
Dental Implants Market
Dental Devices
Plaque Disclosing Aids Market
Dental Devices
Dental Laboratory Handpiece Market