
 Dental Scalers Market | 2026-2036
Dental Scalers Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Scalers Market Analysis
China is reshaping dental scaler manufacturing capacity through expanded precision instrument clusters in Zhejiang and Jiangsu provinces. Dentsply Sirona leverages integrated production networks across multiple continents to sustain cost advantages in ultrasonic platforms. Hu-Friedy anchors its position through specialized stainless-steel instrument forging capabilities. NSK Nakanishi competes on miniaturized piezoelectric handpiece engineering for premium clinical segments.
Dental scalers are mechanical or electromechanical instruments designed for supragingival and subgingival calculus removal, operating at frequencies between 18,000 and 50,000 Hz for ultrasonic variants or through manual curette action with carbon steel or stainless-steel working ends. Ultrasonic scalers dominate clinical throughput in high-volume dental clinics due to reduced operator fatigue and shorter procedure times, while piezoelectric variants command premium positioning through linear tip displacement that preserves root surface integrity. Magnetostrictive technology occupies the mid-tier with established service infrastructure, whereas handheld scalers retain utility in resource-limited settings and as adjunctive tools.
The FDA governs powered dental scaler clearance through 510(k) substantial equivalence reviews, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for reusable surgical instruments including scalers. China's NMPA aligns domestic registration with GB standards for active medical devices, creating parallel compliance obligations for multinational suppliers. Stakeholders must monitor evolving sterilization validation protocols and material biocompatibility testing requirements as regulatory convergence pressures accelerate across major markets.
Market Dynamics
Ultrasonic scaler platforms are displacing magnetostrictive systems as infection control protocols mandate single-use barrier sleeves and autoclavable handpiece designs, compressing replacement cycles and forcing equipment refresh investments across dental service organizations.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's updated substantial equivalence pathway for powered dental instruments accelerates product registration timelines, enabling faster commercialization of next-generation ultrasonic platforms.
- Dental Service Organization Consolidation:Large DSOs in the United States centralize equipment purchasing through master service agreements, creating volume pull for standardized scaler fleets across multi-site networks.
- Piezoelectric Linear Displacement:Piezoelectric technology preserves root surface integrity during subgingival procedures, expanding adoption in periodontal specialty practices seeking reduced post-operative sensitivity.
Market Restraints
- Precision Forging Concentration:Stainless-steel instrument forging capabilities cluster in Zhejiang and Jiangsu provinces, creating supply vulnerability for Western OEMs dependent on Chinese precision manufacturing clusters.
- EU MDR Clinical Evidence Burden:The EU Medical Device Regulation imposes strengthened clinical evidence requirements for reusable surgical instruments, extending registration timelines and compliance costs for scaler manufacturers.
- Manual Scaler Substitution:Handheld curettes retain utility in resource-limited settings and as adjunctive tools for fine calculus removal, limiting ultrasonic penetration in price-sensitive segments.
Strategic Opportunities
- India Dental Infrastructure Buildout:Underpenetrated dental clinic networks in tier-2 and tier-3 Indian cities present whitespace for mid-tier ultrasonic platforms as CDSCO streamlines active medical device registrations.
- Autoclave-Integrated Systems:Convergence of ultrasonic generators with automated sterilization workflows addresses infection control labor costs, appealing to high-throughput clinics seeking operational efficiency.
- Direct-to-Clinic Distribution:E-procurement platforms displace traditional dental distributor networks, enabling manufacturers to capture margin and access real-time utilization data for predictive maintenance services.
Industry Challenges
- Piezoelectric Transducer Calibration:Specialized technician expertise for miniaturized handpiece engineering remains scarce, extending service turnaround times and complicating field support networks.
- Legacy Generator Compatibility:Multi-generational ultrasonic base units in installed bases create integration friction for new tip designs, forcing manufacturers to maintain obsolete connector specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Scalers Market |
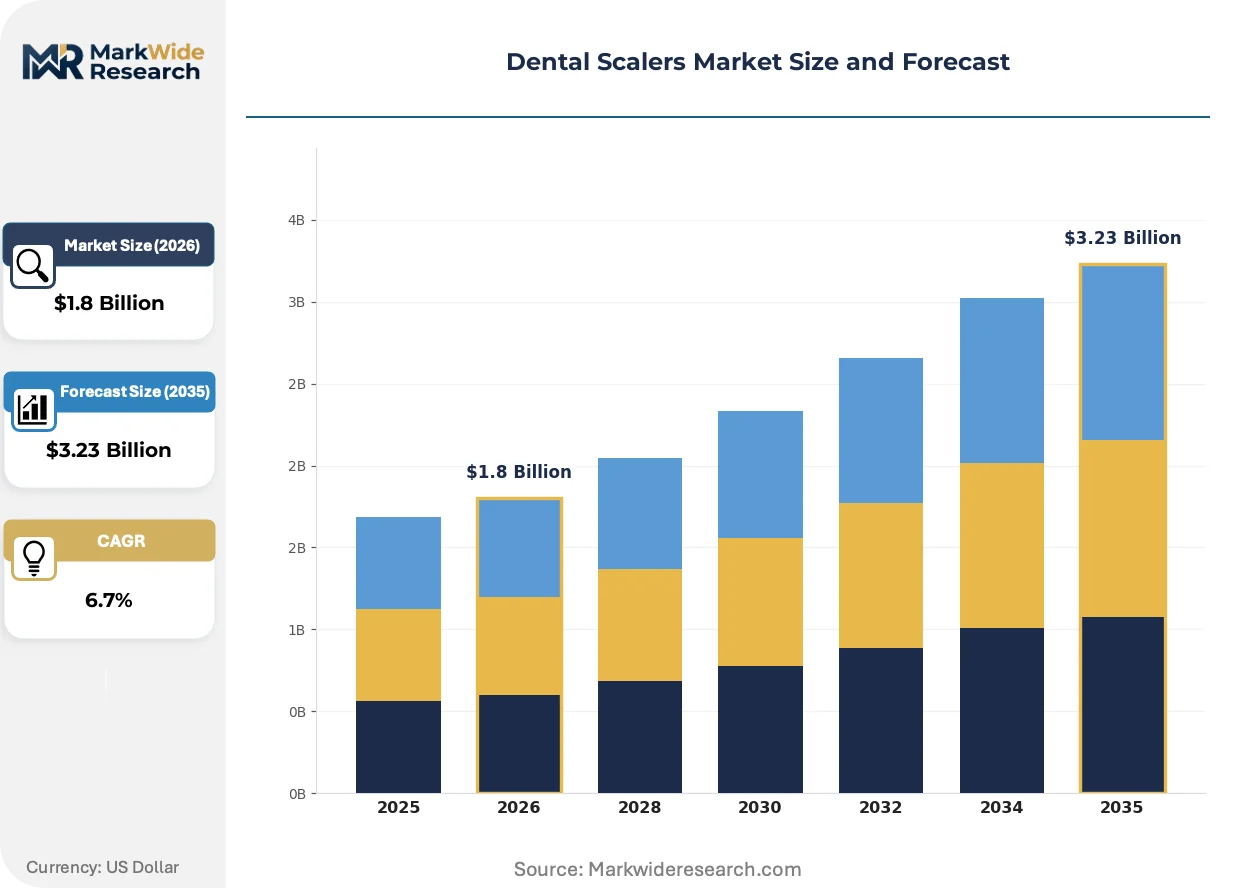
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Scalers, Magnetostrictive Scalers, Piezoelectric Scalers, Handheld Scalers End User: Dental Clinics, Hospitals, Private Practitioners, Research Institutes Technology: Electric, Manual, Battery-operated, Wireless Application: Periodontal Treatment, Plaque Removal, Teeth Cleaning, Dental Care |
| Companies Covered | Dentsply Sirona, Henry Schein, Hu-Friedy, Brasseler USA, Envista Holdings Corporation, Coltene Group, Den-Mat Holdings, EMS Dental, NSK Nakanishi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Scalers Market Emerging Trajectories
Active tip cooling systems and smart pressure-feedback mechanisms are redefining clinical safety standards, while supply chain regionalization and digital procurement platforms reshape how dental equipment reaches end-users.
Magnetostrictive stack technology is hybridizing with piezoelectric control electronics to create dual-mode ultrasonic platforms that switch between elliptical and linear tip displacement. High-volume general dentistry practices in the United States are adopting these hybrid systems at accelerated replacement cycles. This convergence is compressing the pure-play magnetostrictive segment while expanding addressable procedure scope for single-device investments.
The EU Medical Device Regulation's tightened sterilization validation protocols for reusable surgical instruments are forcing scaler manufacturers to redesign handpiece sealing architectures. Industrial consequence includes mandatory biocompatibility testing expansion and technical documentation remediation for legacy product lines. Premium ultrasonic platforms with integrated autoclave tracking chips are capturing preference share as clinics seek automated compliance documentation.
Large dental service organizations are consolidating equipment specifications across multi-state networks, displacing individualized clinic purchasing autonomy. Traditional dental distributors lose volume to manufacturer-direct contracts and group purchasing organizations. This concentration is most visible in the United States where DSOs now control equipment procurement for thousands of operatories through standardized scaler fleet agreements.
Dental Scalers Market Segmentation
Dental scaler procurement patterns diverge sharply across clinical settings, with infection control mandates and procedure volume dictating technology choices. Understanding these segment boundaries reveals where equipment refresh cycles concentrate and which specifications command premium positioning.
Product Type:
Use-case spectrum spans high-throughput automated removal to precision manual intervention, with technology selection driven by procedure mix and capital budget cycles.
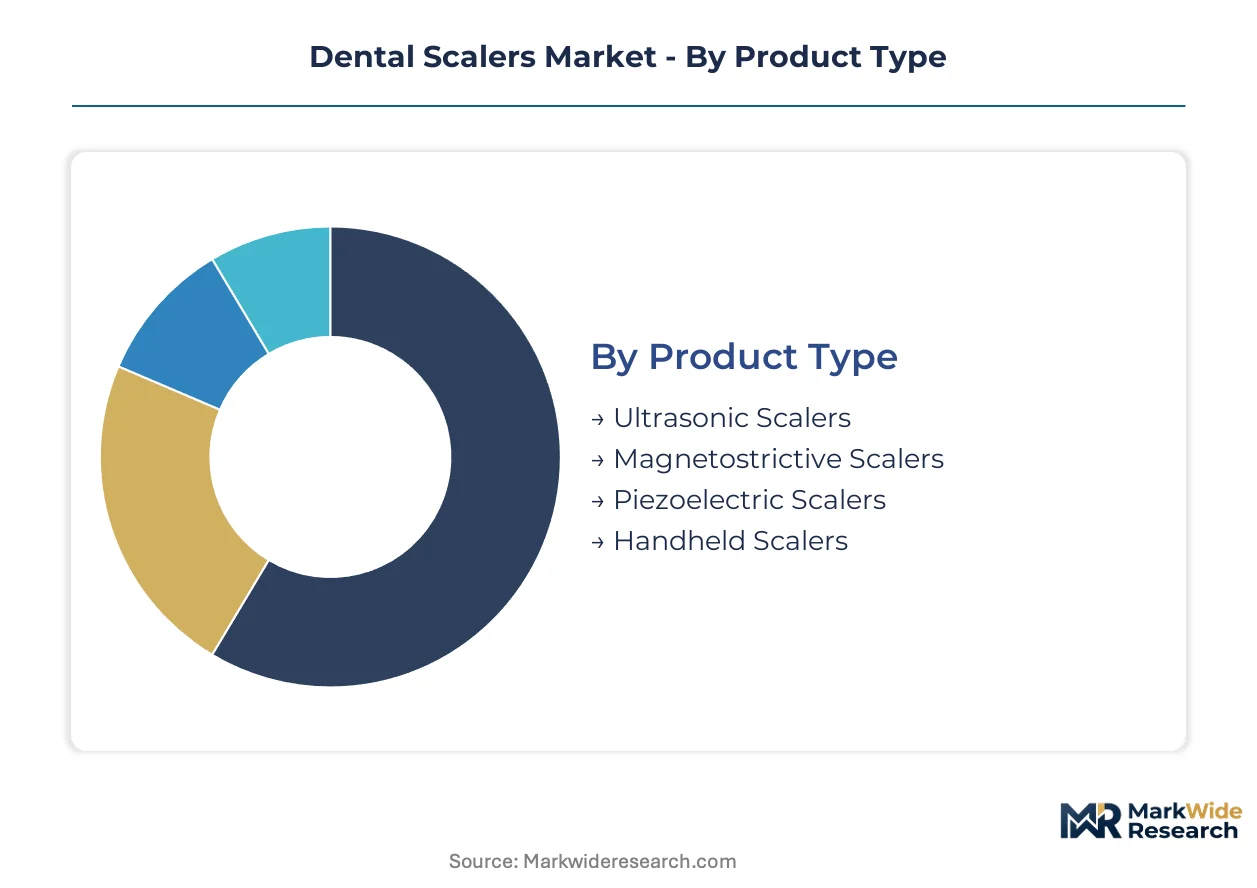
- Ultrasonic Scalers:Electromechanical platforms operating between 18,000 and 50,000 Hz dominate high-volume dental clinics through reduced operator fatigue and compressed procedure times. United States dental service organizations centralize procurement of these systems through multi-site fleet standardization agreements.
- Piezoelectric Scalers:Linear tip displacement technology preserves root surface integrity during subgingival procedures, commanding premium placement in periodontal specialty practices where post-operative sensitivity reduction drives patient retention.
- Magnetostrictive Scalers:Elliptical tip motion systems occupy mid-tier positioning with established service infrastructure and lower capital entry points.
- Handheld Scalers:Manual curettes with carbon steel or stainless-steel working ends retain utility in resource-limited settings and as adjunctive tools for fine calculus removal.
The dominant share belongs to Ultrasonic Scalers, while Piezoelectric Scalers is closing the gap fastest.
End User:
Customer concentration patterns reflect reimbursement structures and capital deployment autonomy across institutional and independent practice models.
- Dental Clinics:High-throughput outpatient facilities generate the bulk of scaler demand as infection control protocols mandate single-use barrier sleeves and accelerated equipment replacement cycles.
- Hospitals:Integrated health systems prioritize autoclave-compatible designs and centralized sterilization workflows, with procurement governed by value analysis committees.
- Private Practitioners:Independent operators balance equipment longevity against technology refresh pressures, often retaining legacy generator systems longer than institutional counterparts.
- Research Institutes:Academic dental schools and clinical research organizations drive demand for precision instrumentation with documented biocompatibility profiles and calibration traceability.
Volume concentrates with Dental Clinics, though Hospitals demonstrate the steepest expansion trajectory as ambulatory surgery center networks proliferate.
Technology:
Power source architecture determines mobility, maintenance burden, and integration complexity within clinical workflows.
- Electric:Mains-powered generators deliver consistent amplitude output for sustained high-volume operation, dominating installed bases in fixed operatory configurations.
- Manual:Human-powered curettes eliminate electrical dependency and generator capital expense, sustaining presence in field dentistry and humanitarian deployment contexts.
- Battery-operated:Cordless portability enables operatory flexibility and reduced trip hazards, gaining preference in renovated clinic layouts and mobile dental units.
- Wireless:Inductive charging handpieces eliminate physical connectors, reducing failure points and simplifying sterilization protocols for infection-sensitive environments.
Electric systems retain the dominant installed base, while Wireless configurations are gaining share fastest as clinic renovation cycles accelerate.
Application:
Clinical indication specificity dictates tip geometry, amplitude settings, and cooling requirements across the procedure spectrum.
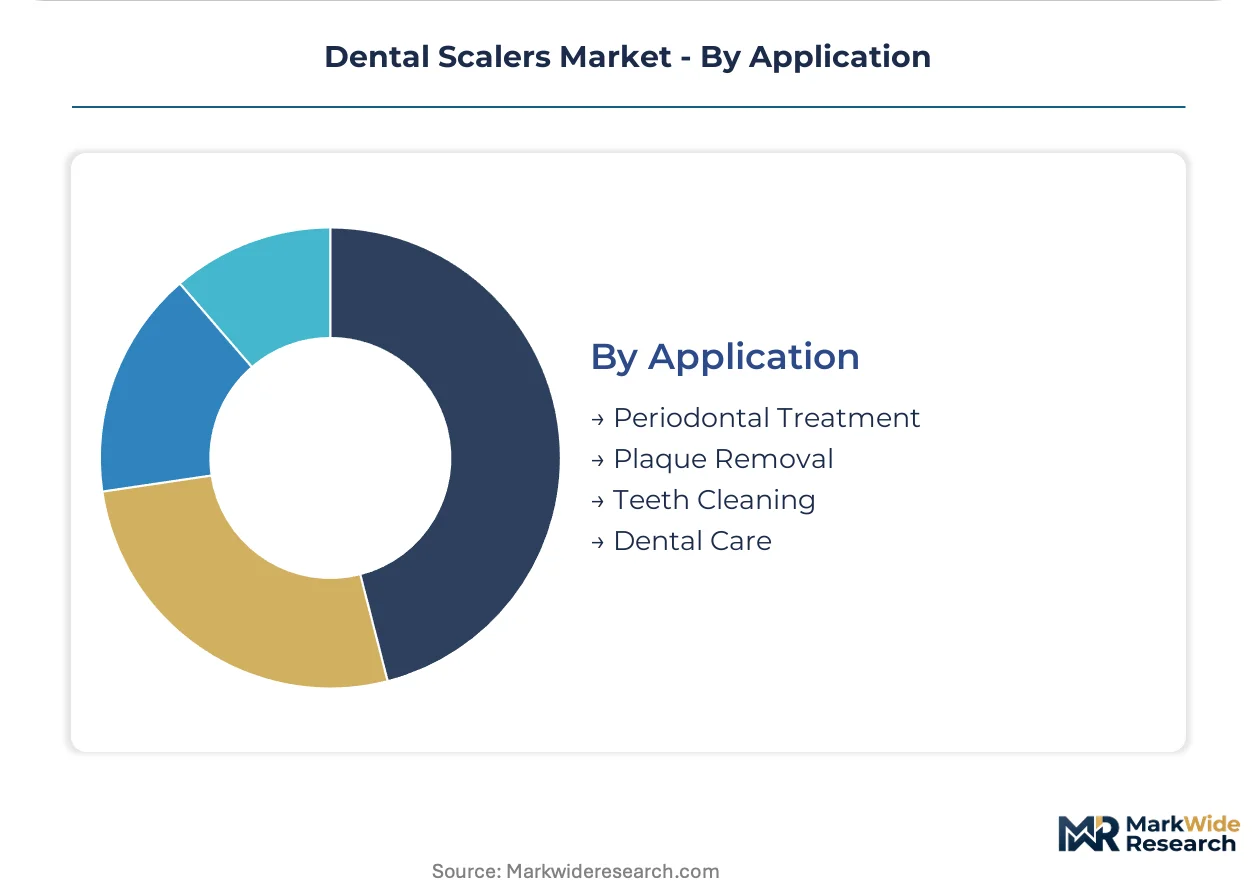
- Periodontal Treatment:Subgingival calculus removal demands precision tip control and active cooling to prevent thermal injury to periodontal ligament tissues.
- Plaque Removal:Supragingival biofilm disruption represents the highest-frequency indication, driving demand for durable tips and rapid sterilization turnaround.
- Teeth Cleaning:Prophylaxis procedures prioritize patient comfort and aerosol management, influencing handpiece ergonomics and suction integration specifications.
- Dental Care:Broad preventive and maintenance applications span pediatric through geriatric patient populations with varying tissue sensitivity profiles.
Plaque Removal commands the dominant procedure volume, while Periodontal Treatment shows the fastest adoption intensity as specialty practice referrals expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor procurement velocity in the United States, while parallel regulatory frameworks in other major markets create differentiated compliance obligations for scaler manufacturers seeking geographic expansion.
United States
Dental service organizations in Texas and Florida centralize equipment purchasing through master service agreements, consolidating thousands of operatories under standardized scaler fleet specifications. The FDA's updated substantial equivalence reviews for powered dental instruments compress registration timelines for next-generation ultrasonic platforms. Precision instrument distributors cluster in the Northeast Corridor, linking Midwest manufacturing with coastal clinical networks.
Germany
Periodontal specialty practices in Bavaria and Baden-Württemberg drive premium-tier demand for piezoelectric systems with documented root surface preservation. The EU Medical Device Regulation imposes strengthened clinical evidence requirements for reusable surgical instruments, extending technical documentation obligations for active device registrations. Industrial sterilization equipment manufacturers concentrate in North Rhine-Westphalia, supplying automated autoclave systems to dental clinic networks.
China
Domestic dental clinic chains in Zhejiang and Jiangsu provinces expand ultrasonic scaler procurement as infection control protocols align with international standards. The NMPA aligns active medical device registrations with GB standards, creating parallel compliance tracks for multinational suppliers. Precision stainless-steel forging clusters in Wenzhou and Taizhou anchor component supply for both domestic OEMs and Western brands.
India
Tier-2 and tier-3 cities in Maharashtra and Gujarat present whitespace for mid-tier ultrasonic platforms as dental infrastructure expands beyond metropolitan centers. The CDSCO streamlines active medical device registrations through risk-based classification pathways, reducing entry barriers for imported equipment. Regional distributor networks in Delhi-NCR and Bangalore consolidate procurement for multi-clinic dental chains.
Japan
Geriatric dental care facilities in Tokyo and Osaka prioritize compact ultrasonic systems with integrated aerosol management. The PMDA maintains stringent biocompatibility testing requirements for reusable surgical instruments, favoring established suppliers with documented sterilization validation. Miniaturized handpiece engineering capabilities concentrate in the Nagoya industrial corridor, serving both domestic demand and premium export segments.
Dental Scalers Market Vendor Landscape
Capability concentration sits with specialized forging and piezoelectric engineering tiers; scale advantage sits with integrated dental equipment conglomerates. The vendor base stratifies across three archetypes: precision instrument specialists with captive metallurgy capabilities, diversified dental equipment platforms with multi-category portfolios, and regional fabricators serving price-sensitive replacement markets. Consolidation pressure intensifies as dental service organizations demand fleet standardization, while technology licensing agreements proliferate for miniaturized transducer designs.
Within the precision-forging tier, Hu-Friedy and Brasseler USA exemplify specialized stainless-steel instrument capabilities. Dentsply Sirona occupies a position spanning both equipment integration and multi-continental production networks. These three anchors represent divergent strategic postures: metallurgy-centric specialization, diversified platform scale, and hybrid manufacturing-distribution integration.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Henry Schein |
| Hu-Friedy |
| Brasseler USA |
| Envista Holdings Corporation |
| Coltene Group |
| Den-Mat Holdings |
| EMS Dental |
| NSK Nakanishi |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Zhejiang and Jiangsu precision forging clusters compresses margin buffers for Western OEMs while amplifying price tier spreads between premium piezoelectric systems and economy magnetostrictive alternatives. FDA 510(k) clearance timelines and EU MDR clinical evidence burdens further stratify procurement costs across buyer archetypes.
Pricing Analysis
United States dental service organizations command 15-25% unit cost advantages over independent European clinics through centralized fleet agreements spanning thousands of operatories. Three-tier pricing structure across premium piezoelectric, standard ultrasonic, and economy magnetostrictive levels reflects differentiation by sterilization validation depth and tip calibration traceability. Pricing pressure stems from CDSCO registration streamlining in India, which enables mid-tier imports to undercut legacy premium positioning. Price-sensitive private practitioners in tier-2 Indian cities resist premium tiers, while periodontal specialists in Germany and Japan absorb premium positioning for documented root surface preservation.
Supply Chain Analysis
Export control regimes on miniaturized piezoelectric transducer technology limit component flows from Japanese engineering corridors to emerging manufacturers in India and Southeast Asia. Stainless-steel forging concentrates in China's Wenzhou and Taizhou clusters, with secondary precision machining capacity in Germany's Solingen region and specialized handpiece assembly in Japan's Nagoya corridor. Supply chain risk centers on single-source vulnerability for piezoelectric ceramic substrates sourced from South Korean and Japanese suppliers. Distribution runs through dental service organization procurement platforms displacing traditional distributor networks, with direct manufacturer contracts capturing utilization data for predictive maintenance monetization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manual curette substitution in resource-limited settings and price-sensitive segments threatens ultrasonic penetration, forcing incumbents to defend equipment refresh cycles through infection control protocol alignment and operational efficiency demonstrability.
For Market Incumbents: Entrench fleet standardization agreements with dental service organizations by bundling autoclave-integrated systems with predictive maintenance subscriptions, neutralizing manual scaler substitution through documented procedure time compression and operator fatigue reduction. Deepen captive supply of precision-forged stainless components through backward integration into Wenzhou-area forging partnerships, insulating margin pressure from Chinese supply concentration.
For New Entrants and Emerging Players: Pursue whitespace in India's tier-2 and tier-3 dental infrastructure buildout by positioning mid-tier ultrasonic platforms with simplified sterilization protocols beneath CDSCO streamlined registration pathways. Target periodontal specialty practices seeking piezoelectric alternatives through direct-to-clinic e-procurement platforms, bypassing entrenched distributor relationships with transparent calibration documentation and rapid tip replacement logistics.
For Investors and Strategic Acquirers: EU MDR clinical evidence requirements reshape the acquisition landscape toward targets with sterilization validation infrastructure and biocompatibility testing capabilities already embedded. Long-term viability hinges on consolidation plays that capture dental service organization procurement concentration. Watch FDA 510(k) clearance velocity for next-generation hybrid ultrasonic platforms as the inflection signal indicating which engineering teams can compress commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Faster clearance timelines for powered dental instruments compress competitive response windows for ultrasonic platform launches. |
| Autoclave Integration Partnership | Convergence with sterilization equipment manufacturers addresses infection control labor costs in high-throughput clinic networks. |
| Direct-to-Clinic E-Procurement Launch | Disintermediation of traditional dental distributors captures margin and generates real-time utilization data assets. |
| Piezoelectric Transducer Licensing | Technology agreements for miniaturized handpiece engineering accelerate product development without captive R&D investment. |
| Precision Forging Joint Venture | Upstream control over Zhejiang stainless-steel clusters mitigates supply vulnerability for Western OEMs. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with dental equipment procurement directors, periodontal practice administrators, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, NMPA registration records, hospital procurement databases, and dental service organization capital expenditure disclosures. Bottom-up equipment unit economics triangulated against top-down market sizing through geographic procedure volume modeling and replacement cycle assumptions.
Forecast inputs span product type segmentation across ultrasonic, piezoelectric, magnetostrictive, and handheld platforms; end-user concentration patterns across dental clinics, hospitals, private practitioners, and research institutes; technology architecture differentiation by power source; and application intensity across periodontal treatment, plaque removal, and prophylaxis procedures. CAGRs derive from installed base depreciation curves, infection control protocol refresh mandates, and dental service organization fleet standardization velocity. Industry-specific inputs include autoclave compatibility certification timelines and piezoelectric transducer calibration service infrastructure penetration.
Sensitivities concentrate around FDA regulatory pathway modifications, EU MDR clinical evidence requirement evolution, and Chinese precision manufacturing cluster disruption scenarios. Forecasts reflect documented assumptions regarding equipment replacement cycle compression and infection control protocol adoption rates. Material shifts in dental service organization procurement consolidation or sterilization validation technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Orthodontic Wax Market
Dental Devices
Dental Etching Liquid Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Dental Braces Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
Dental Forceps Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Dental Units Market
Dental Devices
Dental Irrigation Devices Market
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Dental CAD Market
Dental Devices
3D Printed Clear Dental Aligners Market