
 Dental Implants Market | 2026-2036
Dental Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Implants Market Analysis
A shift from single-source titanium procurement to multi-source supply agreements is pivoting how manufacturers secure raw material for implant production. Straumann leverages vertically integrated zirconia milling capabilities to sustain margin control across premium product lines. Nobel Biocare competes through specialized surface modification technologies that accelerate osseointegration timelines. Osstem Implant anchors volume leadership in Asia-Pacific markets through cost-optimized manufacturing scale.
Dental implants are screw-shaped prosthetic devices, typically machined from grade 4 or grade 5 titanium alloy or yttria-stabilized tetragonal zirconia polycrystal, designed for surgical insertion into the maxilla or mandible to support crowns, bridges, or dentures. Endosteal implants dominate procedural volume due to established long-term survival data and broad surgeon familiarity, while zirconia variants are gaining preference among metal-sensitive patients and anterior aesthetic zones. Titanium remains the material backbone for most manufacturers, though zirconia adoption is accelerating in European markets where aesthetic outcomes command premium positioning. Two-stage placement procedures still generate the majority of revenue, though immediate placement protocols are reshaping surgical workflows in high-volume oral surgery practices.
FDA 510(k) clearance pathways and EU MDR conformity assessments govern market access for new implant systems, with notified bodies demanding extended clinical follow-up data under revised medical device regulations. ISO 10993 biocompatibility testing and ASTM F136 titanium alloy specifications establish baseline material safety thresholds that all commercial entrants must satisfy. Stakeholders must monitor evolving reimbursement codes from CMS and national health technology assessment bodies, as coverage decisions for immediate loading protocols will reshape procedure economics and manufacturer training investments.
Market Dynamics
The dental implants market is undergoing a fundamental restructuring as immediate loading protocols compress treatment timelines and reshape surgeon training investments. This procedural acceleration is forcing manufacturers to recalibrate their clinical education budgets and field support infrastructure.
Growth Catalysts
- EU MDR conformity assessments:Elevated biocompatibility documentation requirements under revised medical device regulations are filtering out marginal competitors and consolidating demand among qualified suppliers.
- Full-arch rehabilitations:Oral surgery clinics are expanding dedicated implantology units as patient volumes for All-on-4 and similar protocols climb in the United States and Germany.
- Grade 5 titanium alloy:Superior fatigue resistance and osseointegration performance characteristics are displacing grade 4 variants in premium implant lines.
Market Restraints
- Sponge titanium supply concentration:Ukrainian and Russian feedstock disruptions have exposed vulnerability in the specialty titanium sponge supply chain for implant-grade alloy production.
- EU MDR clinical data requirements:Extended follow-up mandates for new implant system approvals are extending time-to-market by 18-36 months for novel surface technologies.
- Zirconia substitution ceiling:Brittle fracture risk under occlusal load limits yttria-stabilized tetragonal zirconia polycrystal to anterior and single-tooth applications.
Strategic Opportunities
- Immediate loading protocols:CMS reimbursement pathway expansion for same-day provisionalization would unlock procedure economics in US Medicare Advantage populations.
- Digital surgical workflows:Convergence of cone-beam computed tomography with intraoral scanning and chairside milling is compressing restoration delivery from weeks to hours.
- South Korea's specialist density:Underpenetrated rural provinces present volume expansion potential as national health insurance coverage for implants broadens.
Industry Challenges
- Prosthodontist-oral surgeon coordination:Fragmented referral pathways between surgical placement and restorative phases create treatment abandonment and complication liability.
- ISO 10993-5 cytotoxicity testing capacity:Bottlenecks at accredited laboratories are delaying biocompatibility certification for modified surface coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Implants Market |
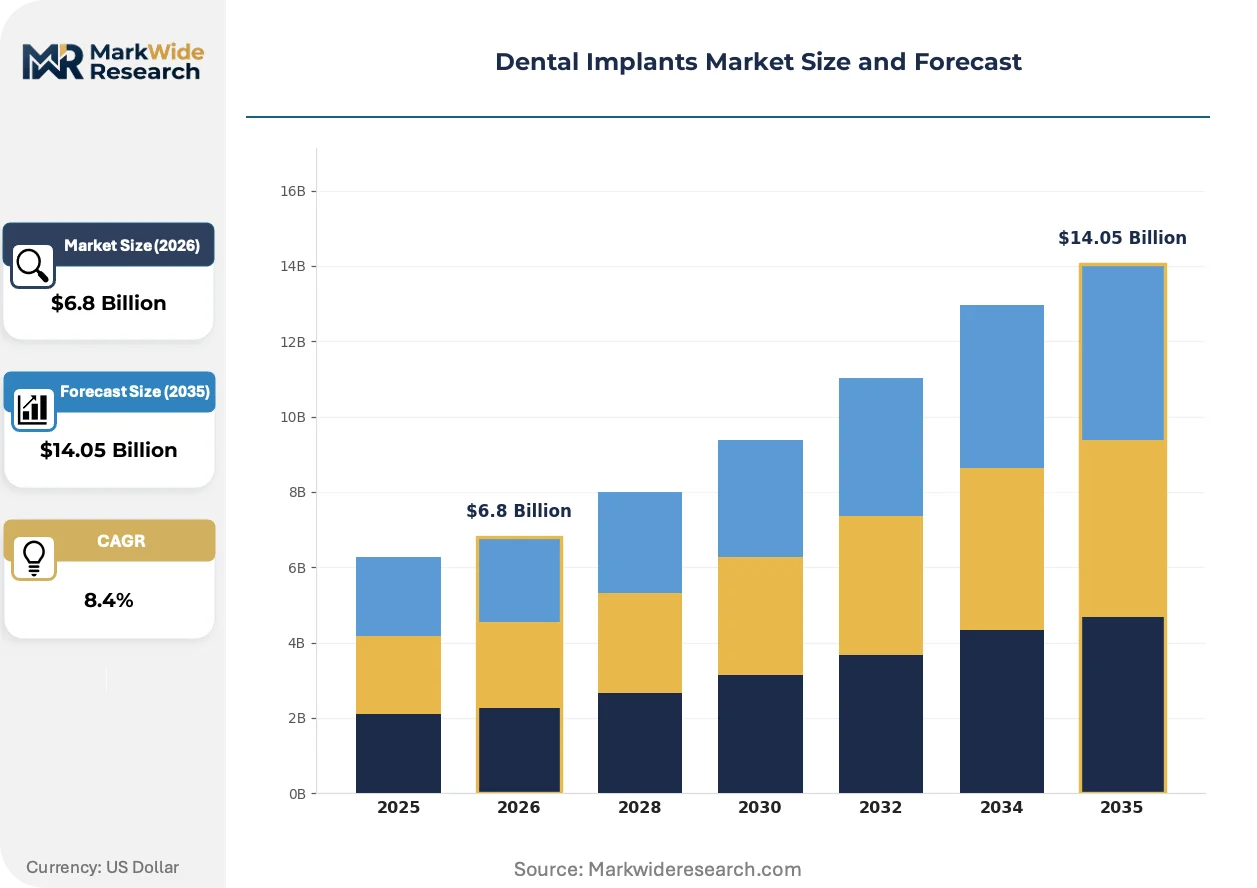
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
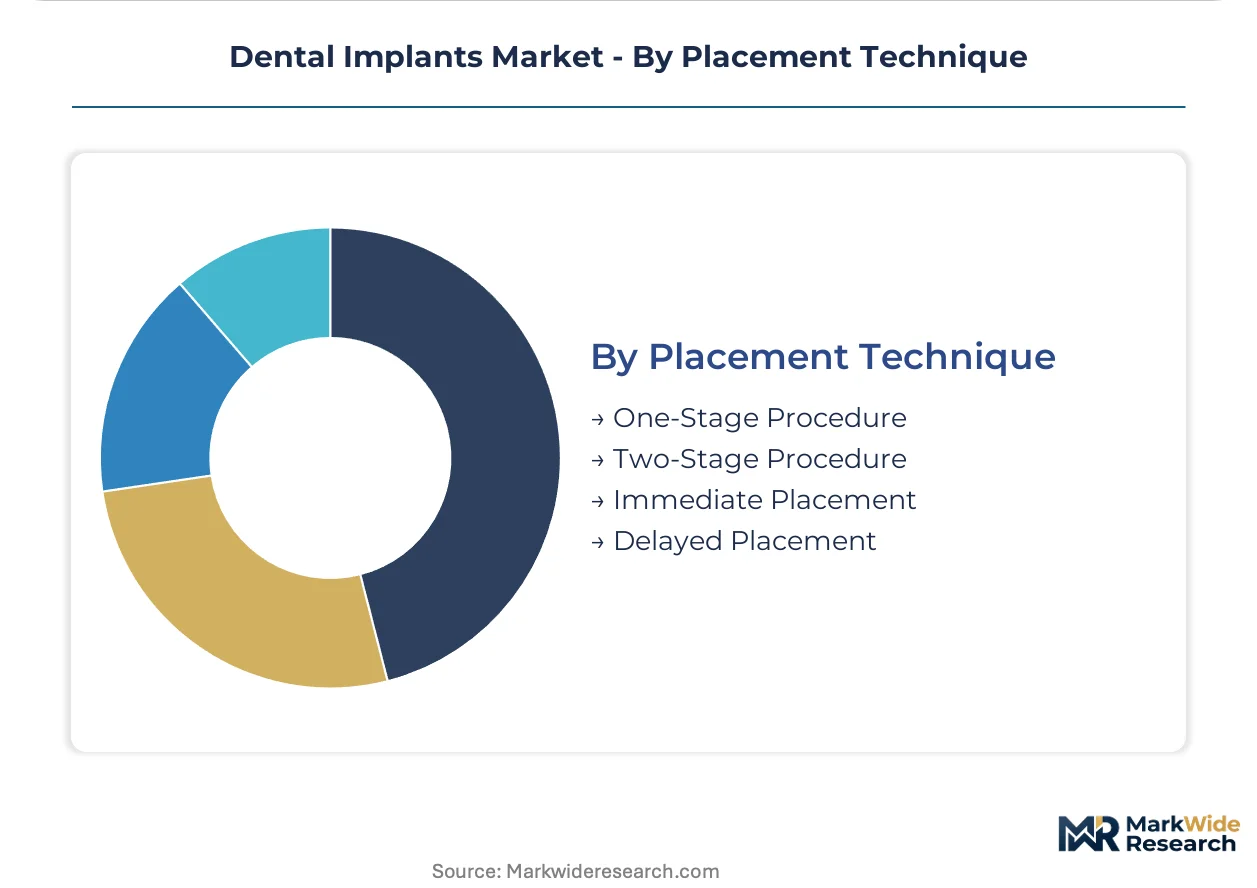
| Segmentation | Product Type: Endosteal Implants, Subperiosteal Implants, Zygomatic Implants, Mini Implants Material: Titanium, Zirconia, Polymer, Stainless Steel End User: Dentists, Oral Surgeons, Specialists, General Practitioners Placement Technique: One-Stage Procedure, Two-Stage Procedure, Immediate Placement, Delayed Placement |
| Companies Covered | Dentsply Sirona, BioHorizons, Straumann, MegaGen, Hiossen, Nobel Biocare, Osstem Implant, Neodent, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Implants Market Emerging Trajectories
Digital dentistry ecosystems are collapsing traditional boundaries between diagnostic imaging, surgical planning, and prosthetic fabrication. This integration is compressing value chains and redistributing margin capture across hardware, software, and consumable layers.
Guided surgery systems are modularizing implant placement workflows by decoupling preoperative planning from intraoperative execution. High-volume oral surgery practices in Germany and South Korea are adopting these platforms to standardize outcomes across operator experience levels. This modularity is enabling procedure volume scaling without proportional specialist headcount expansion.
FDA 510(k) clearance pathways are tightening evidentiary standards for novel implant surface modifications following post-market surveillance data on late-stage failures. Manufacturers must now submit extended clinical follow-up for hydrophilic and nanostructured surfaces. Premium product lines in the United States face the steepest compliance cost escalation as predicate device comparisons grow more stringent.
Direct-to-manufacturer purchasing is displacing traditional dental distributor intermediaries for high-volume implant orders. Large dental service organizations in the United States are negotiating enterprise pricing agreements that bypass regional dealer networks. This channel compression is most visible in metropolitan markets where DSO consolidation has concentrated buying power among fewer decision-makers.
Dental Implants Market Segmentation
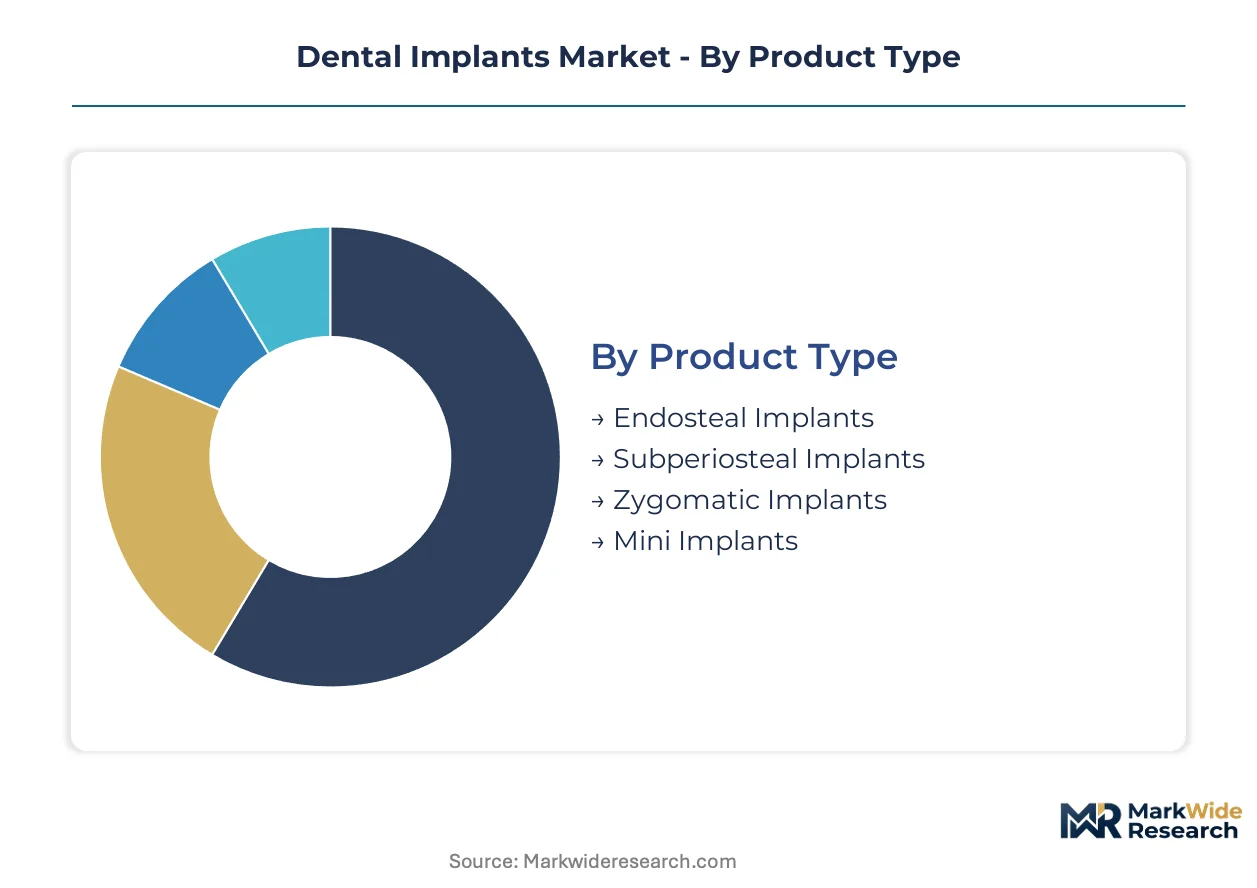
Implant manufacturers configure product portfolios across multiple technical and commercial dimensions. Surgical workflow preferences and material biocompatibility requirements drive divergent R&D investment priorities across these segment boundaries.
Product Type:
Volume concentration favors established screw-form designs with decades of survival data, while premium positioning attaches to specialized anatomical solutions.
- Endosteal Implants:Screw or cylinder-form devices inserted directly into alveolar bone, typically fabricated from grade 4 or grade 5 titanium alloy. Demand concentrates in United States oral surgery clinics performing full-arch rehabilitations, driven by reimbursement pathway maturity and specialist density. Two-stage placement protocols still dominate this segment's procedural economics.
- Subperiosteal Implants:Custom-cast metal frameworks resting atop the jawbone beneath periosteal tissue, reserved for patients with insufficient bone height for endosteal placement. German maxillofacial centers represent concentrated demand as complex case referrals accumulate in university hospital networks. High fabrication costs and surgical complexity constrain volume expansion.
- Zygomatic Implants:Extended-length fixtures engaging the zygomatic bone for maxillary atrophy cases, requiring specialized surgical training.
- Mini Implants:Reduced-diameter temporary anchorage devices for orthodontic stabilization and narrow-ridge scenarios.
Mature deployment sits with Endosteal Implants. Newer deployment is concentrated in Zygomatic Implants as severe atrophy cases increasingly bypass bone grafting protocols.
Material:
Cost tier separation runs from commodity-grade metals through premium ceramic systems, with biocompatibility certification costs widening margin spreads between tiers.
- Titanium:Grade 4 commercially pure and grade 5 Ti-6Al-4V ELI alloys constitute the material backbone for most manufacturers, with ASTM F136 specifications governing implant-grade certification. South Korean production facilities achieve cost optimization through sponge titanium sourcing agreements and in-house alloy processing. Fatigue resistance under cyclic occlusal loading remains the decisive performance metric.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystal offers metal-free aesthetics for anterior zones and hypersensitive patients. European markets show steepest adoption curves as private-pay aesthetic dentistry commands premium positioning. Brittle fracture risk under posterior occlusal loads limits application scope.
- Polymer:Polymethyl methacrylate and PEEK provisional components for immediate-load temporization.
- Stainless Steel:Historical legacy material now restricted to temporary anchorage and orthodontic applications.
Mature deployment sits with Titanium. Newer deployment is concentrated in Zirconia as metal-free protocols gain share in aesthetic-driven European practices.
End User:
Customer type segmentation reflects training depth and case complexity referral patterns rather than simple volume scaling.
- Oral Surgeons:Maxillofacial specialists handle complex full-arch reconstructions, zygomatic placements, and medically compromised patients. United States academic medical centers concentrate demand for these high-complexity procedures. Immediate loading protocol adoption reshapes their surgical workflow investments.
- Dentists:General practitioners and prosthodontists perform single-tooth and straightforward multi-unit restorations in private practice settings. German dental chambers report expanding continuing education enrollment as GDPs seek to retain implant revenue within primary care relationships.
- Specialists:Periodontists and prosthodontists with advanced implant training occupy intermediate complexity tiers.
- General Practitioners:Primary care physicians occasionally coordinate pre-surgical medical clearance for implant candidates.
Mature deployment sits with Dentists. Newer deployment is concentrated in Oral Surgeons as full-arch protocol volume climbs and case complexity escalates.
Placement Technique:
Procedure economics hinge on chair-time compression and provisionalization timing, with reimbursement codes lagging clinical capability advances.
- Two-Stage Procedure:Traditional protocol with submerged healing period before second-stage abutment connection, generating the majority of current revenue. Established long-term survival data supports continued preference in medically compromised patients and graft-dependent sites. South Korean national health insurance coverage still favors this conservative approach.
- Immediate Placement:Extraction-site implant insertion with or without simultaneous provisionalization compresses treatment timelines from months to hours. United States DSOs are scaling these protocols through standardized digital workflows and surgeon training academies. CMS reimbursement pathway uncertainty constrains Medicare Advantage penetration.
- One-Stage Procedure:Transmucosal healing with immediate abutment connection, intermediate between two-stage and immediate protocols.
- Delayed Placement:Extended healing intervals following extraction or grafting before implant insertion.
Mature deployment sits with Two-Stage Procedure. Newer deployment is concentrated in Immediate Placement as digital planning accuracy and surface technology confidence improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sponge titanium feedstock from Ukrainian and Russian sources has historically supplied alloy production for implant-grade manufacturing, creating geographic vulnerability that manufacturers now address through diversification into Japanese and Kazakh suppliers.
United States
Oral surgery clinics in metropolitan markets drive procedural volume for full-arch rehabilitations. FDA 510(k) clearance pathways govern market access for novel implant surface technologies. Dallas and Houston surgical centers concentrate demand for immediate loading protocols as DSO consolidation accelerates.
Germany
Maxillofacial university hospitals generate complex case referrals for zygomatic and subperiosteal placements. EU MDR conformity assessments under notified body supervision extend approval timelines for modified surface coatings. Munich and Berlin academic clusters anchor specialized surgical training infrastructure.
South Korea
National health insurance reimbursement expansion drives implant penetration into underpenetrated rural provinces. MFDS regulates biocompatibility certification under harmonized medical device standards. Seoul Capital Area manufacturing facilities achieve cost optimization through vertical integration into titanium alloy processing.
Switzerland
Private-pay aesthetic dentistry commands premium positioning for zirconia and immediate-load solutions. Swissmedic oversees conformity assessment for high-risk implantable devices. Basel and Zurich clusters concentrate precision milling capabilities for ceramic restoration components.
Japan
Aging demographics expand edentulous patient pools requiring implant-supported prosthetics. PMDA reviews clinical data submissions under Pharmaceuticals and Medical Devices Act frameworks. Osaka-Kobe industrial corridor hosts titanium sponge processing and alloy refinement operations.
Dental Implants Market Vendor Landscape
Global majors compete with regional champions across surface technology and digital workflow integration. Market structure concentrates among tiered players with differentiated certification depth and manufacturing scale. Three archetypes dominate: premium integrated manufacturers with in-house alloy processing, mid-scale specialists in ceramic aesthetics, and volume-driven Asian producers with cost-optimized fabrication. Consolidation proceeds through strategic technology licensing and selective geographic expansion rather than large-scale acquisition.
Within the premium integrated tier, Straumann and Nobel Biocare exemplify archetypes combining surface modification expertise with controlled supply chains. Osstem Implant anchors the volume-driven Asian producer position. These three represent distinct strategic postures rather than direct segment overlap, with each occupying differentiated territory across material certification, procedural protocol support, and geographic reach.
| Leading Market Players |
|---|
| Dentsply Sirona |
| BioHorizons |
| Straumann |
| MegaGen |
| Hiossen |
| Nobel Biocare |
| Osstem Implant |
| Neodent |
| Zimmer Biomet |
| Others |
Supply Flow & Price Mechanics
Large dental service organizations in the United States negotiate enterprise pricing agreements that bypass regional dealer networks, compressing margins for traditional distributors while concentrating buying power among fewer decision-makers. This channel compression reshapes how manufacturers structure volume discounts and service bundles across metropolitan markets.
Pricing Analysis
Warranty and surgical training bundling separates premium implant lines from commodity-grade alternatives, with extended osseointegration guarantees and field support commanding substantial markups over bare-device transactions. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by surface technology certification and alloy grade. Pricing pressure stems from DSO procurement centralization and direct-to-manufacturer purchasing trends. General practitioners show highest price sensitivity, while oral surgery clinics prioritize clinical outcomes over per-unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, South Korea, and the United States maintain hub-and-spoke patterns to serve high-volume oral surgery practices with rapid replenishment capabilities. Sponge titanium feedstock draws from Japanese and Kazakh suppliers following disruptions to Ukrainian and Russian sources. ISO 10993 biocompatibility testing capacity constraints create certification bottlenecks for modified surface coatings. Distribution runs through authorized dealer networks for smaller accounts, while enterprise customers receive direct fulfillment from manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental implants market functions as a cost-of-compliance arena where EU MDR conformity assessments and extended clinical follow-up mandates erect formidable barriers against undercapitalized entrants, entrenching qualified incumbents with established notified body relationships.
For Market Incumbents: Deploy backward integration into titanium alloy processing to secure margin control against sponge feedstock volatility. Consolidate surface technology patent portfolios to defend against nanostructured coating substitutes. Expand clinical education infrastructure to capture immediate loading protocol adoption among high-volume oral surgery practices. For New Entrants and Emerging Players: Direct-to-practitioner digital platforms offer lower-friction entry paths than traditional dealer channel capture. Target underpenetrated rural provinces in South Korea where national health insurance expansion broadens addressable demand. Lead with cost-optimized zirconia aesthetics for metal-sensitive patient segments in European private-pay markets. For Investors and Strategic Acquirers: The window for entry favors manufacturers with captive ISO 10993 testing relationships and established EU MDR technical documentation. Mid-scale ceramic specialists with precision milling capabilities represent attractive acquisition profiles. Watch CMS reimbursement pathway decisions for immediate loading protocols as the decisive inflection signal for US Medicare Advantage penetration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Extended clinical follow-up data satisfies notified body demands under revised medical device regulations. |
| Digital Surgical Workflow Integration | Cone-beam CT convergence with intraoral scanning compresses restoration delivery timelines for oral surgery clinics. |
| Multi-Source Titanium Procurement | Japanese and Kazakh sponge suppliers reduce dependency on historically concentrated Ukrainian and Russian feedstock. |
| Immediate Loading Protocol Training Academies | Standardized surgeon education enables procedure volume scaling without proportional specialist headcount expansion. |
| Zirconia Aesthetic Line Expansion | Metal-free positioning captures premium private-pay demand in European anterior restoration markets. |
Methodological Framework
FDA 510(k) clearance databases, EU MDR notified body documentation, and hospital procurement records formed the secondary backbone for implant system tracking and regulatory pathway analysis. Primary interviews with oral surgeons, prosthodontists, biomedical engineers, and GPO contracts managers validated demand patterns and purchasing criteria. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Historical trendline analysis of implant placement procedures informed growth trajectory modeling across material type, placement technique, and end-user segmentation dimensions. CAGRs were derived from weighted average procedure volume projections incorporating reimbursement pathway maturation and specialist density expansion. Surface technology adoption curves and digital workflow penetration rates served as industry-specific forecast inputs throughout the modeling period.
Inputs from notified body conformity assessment timelines and CMS reimbursement deliberations were available through the study window; gaps in real-time DSO procurement contract terms introduce uncertainty bands around enterprise pricing trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Impression Tray Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Malocclusion Market
Dental Devices
Global Dental Turbine Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Dental Braces Market
Dental Devices
Dental Contouring Market
Dental Devices
Dental Piezoelectric Ultrasonic Unit Market
Dental Devices
Europe Dental Aligners Market
Dental Devices
Turkey CAD/CAM Dental Devices Market
Dental Devices
Intraoral Dental Scanner Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Dental Needle Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
Global Dental Bone Graft Substitutes Market