
 Vaccine Management Solution Market | 2026-2036
Vaccine Management Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccine Management Solution Market Outlook
Capital-intensity divergence between cloud-native entrants and legacy health IT incumbents is collapsing as subscription models democratize access to advanced vaccine logistics platforms. Oracle Corporation leverages its Cerner acquisition to anchor hospital-centric administration tool deployments across North American health systems. McKesson Corporation sustains distribution dominance through backward integration into cold chain storage solutions. Infosys Public Services, Inc. competes on cost-optimized government immunization program implementations in emerging markets.
Vaccine management solutions encompass integrated software-hardware systems that monitor temperature-sensitive biologics from manufacture through patient administration, typically maintaining 2°C to 8°C cold chain integrity via IoT sensor networks and automated alert protocols. These platforms serve to eliminate dose wastage, ensure regulatory compliance, and accelerate immunization coverage rates. Cloud-based systems now lead technology adoption as health systems abandon on-premise infrastructure, while AI Analytics represents the fastest-expanding segment as predictive demand forecasting reduces inventory carrying costs. Tracking Software commands the largest product-type revenue pool due to serialization mandates, though Distribution Services is narrowing the gap through last-mile logistics optimization.
The FDA enforces drug supply chain traceability standards that compel pharmaceutical distributors to deploy interoperable tracking systems by statutory deadlines. EMA's Falsified Medicines Directive and India's CDSCO cold chain guidelines similarly mandate digital verification layers, creating compliance-driven demand across multiple jurisdictions. WHO prequalification standards for temperature monitoring devices further shape procurement specifications in low-resource settings. Stakeholders must monitor evolving AI governance frameworks and data localization requirements as these will determine platform architecture decisions and cross-border deployment feasibility.
Market Dynamics
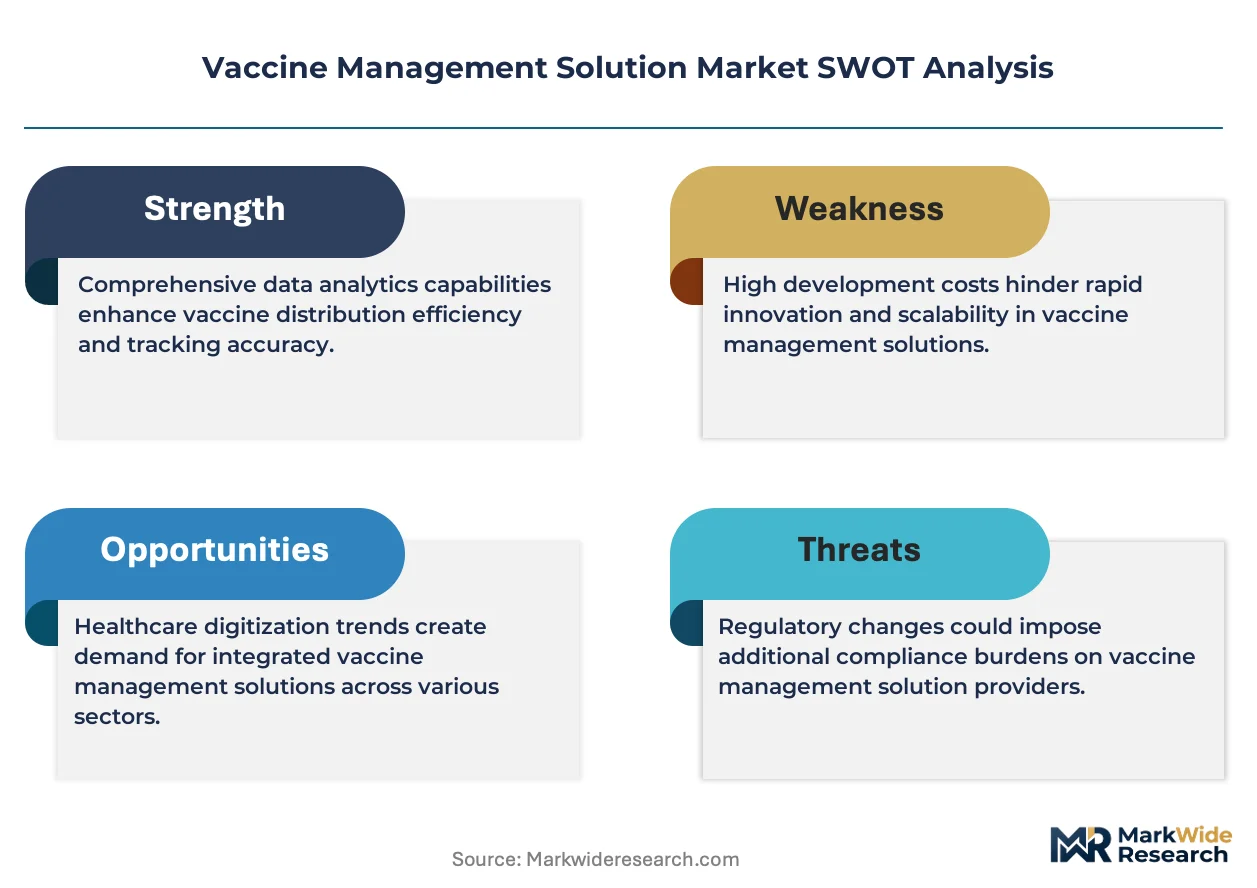
Cloud-native architecture is collapsing the traditional capital barrier that once separated hospital IT departments from advanced cold chain analytics, forcing legacy vendors into accelerated SaaS transitions or partnership models.
Growth Catalysts
- FDA DSCSA Serialization Mandates:Pharmaceutical distributors must deploy interoperable tracking systems by statutory deadlines, creating compliance-driven procurement cycles for verification platforms.
- AI-Powered Demand Forecasting:Predictive algorithms reduce inventory carrying costs for temperature-sensitive biologics, accelerating adoption among large hospital systems.
- India CDSCO Cold Chain Guidelines:Digital verification layers are now mandatory for vaccine distribution, expanding addressable market for monitoring device manufacturers.
Market Restraints
- Lithium-Ion Battery Supply Concentration:IoT sensor networks depend on battery cells sourced primarily from East Asian suppliers, exposing cold chain hardware to input volatility.
- Legacy System Integration Friction:Hospital ERP systems built on 1990s architectures resist API connectivity, extending deployment timelines for unified vaccine management platforms.
- Data Localization Requirements:Cross-border cloud deployments face fragmentation as jurisdictions impose sovereignty rules on patient immunization records.
Strategic Opportunities
- Last-Mile Drone Delivery:UAV networks for remote vaccine distribution remain underdeveloped outside Rwanda and Ghana, offering first-mover positioning for logistics integrators.
- WHO Prequalification Standards:Temperature monitoring device certification opens procurement channels in low-resource settings previously served by informal suppliers.
- Blockchain-Sensor Convergence:Immutable ledger integration with IoT data streams addresses counterfeiting vulnerabilities in high-value biologics supply chains.
Industry Challenges
- Specialized Technician Scarcity:Deployment of ultra-low temperature freezers requiring minus 70 degrees Celsius calibration exceeds available field service capacity in secondary cities.
- Multi-Jurisdiction Compliance Burden:Platform architects must reconcile FDA traceability standards with EMA Falsified Medicines Directive and divergent national data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccine Management Solution Market |
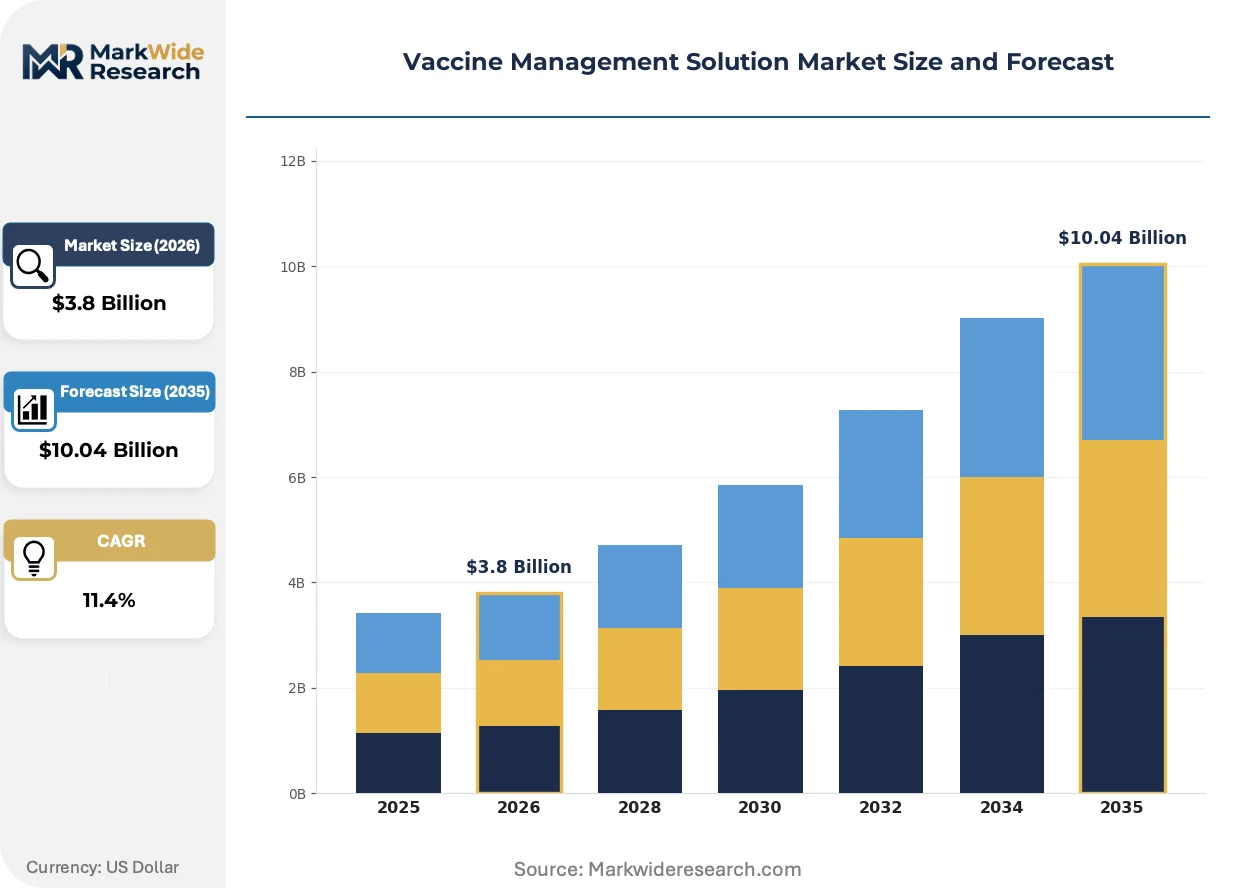
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Solutions, Tracking Software, Administration Tools, Distribution Services End User: Pharmacies, Hospitals, Clinics, Government Agencies Technology: IoT Solutions, Cloud-based Systems, Mobile Applications, AI Analytics Application: Immunization Programs, Clinical Trials, Emergency Responses, Research Studies |
| Companies Covered | IBM Corporation, Oracle Corporation, Accenture, VaxCare Corp, McKesson Corporation, Cardinal Health, Infosys Public Services, Inc., Siemens Healthineers, CureMD Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccine Management Solution Market Strategic Shifts
Digital immunization infrastructure is undergoing platform consolidation as point solutions give way to integrated software-hardware ecosystems spanning manufacture through patient administration.
Edge computing architectures for cold chain monitoring is bifurcating the vendor landscape between lightweight sensor-only providers and full-stack analytics platforms. Regional hospital networks are adopting hybrid models faster than academic medical centers, which retain on-premise data lakes. This technology is compressing alert response times from hours to minutes while fragmenting supplier tiers.
EMA's Falsified Medicines Directive enforcement is tightening serialization requirements for pharmaceutical distributors operating across European Union member states. Manufacturers must now maintain centralized verification repositories accessible to national medicines agencies. Small and mid-sized distributors in Southern Europe are responding through consortium-based compliance pooling rather than independent system builds.
Subscription-based procurement for vaccine logistics software is displacing perpetual license models among public health departments with constrained capital budgets. Annual recurring revenue structures lower entry barriers for municipal immunization programs. This shift is most visible in German state health ministries modernizing legacy scheduling systems.
Vaccine Management Solution Market Segmentation
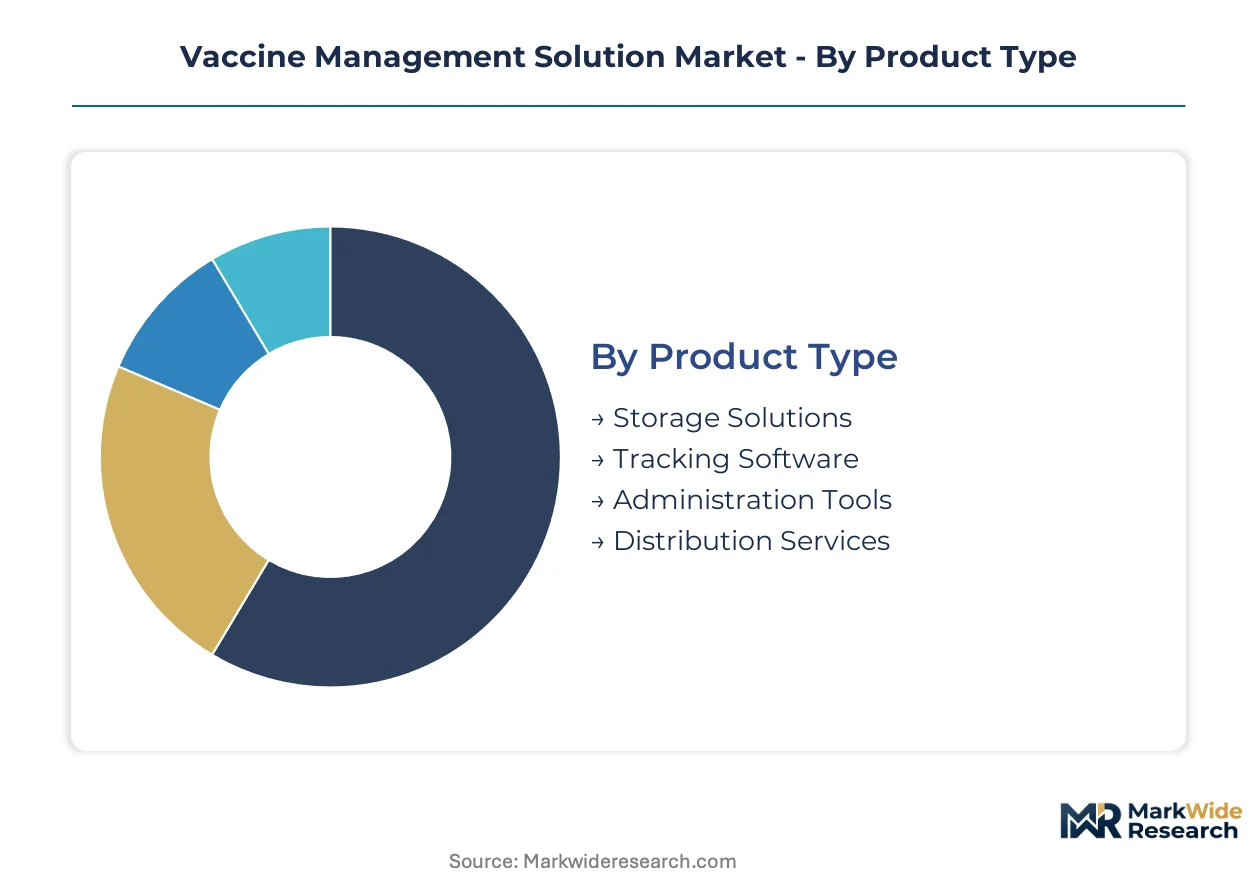
Vaccine management solutions fragment across four distinct dimensions that determine procurement pathways and deployment complexity. Product type governs hardware-software mix and capital intensity. Technology selection shapes integration requirements with legacy hospital infrastructure. End user and application categories dictate regulatory compliance layers and contract structures.
Product Type:
Channel mix varies sharply: Storage Solutions and Tracking Software flow through pharmaceutical distributors with FDA DSCSA compliance requirements, while Administration Tools deploy directly into hospital IT procurement cycles and Distribution Services route through government tender processes.
- Storage Solutions:Ultra-low temperature freezers and refrigerated units maintain 2°C to 8°C cold chain integrity for mRNA and viral vector vaccines. Demand concentrates in United States academic medical centers upgrading for next-generation biologics, constrained by specialized technician scarcity for minus 70 degrees Celsius calibration.
- Tracking Software:Serialization and verification platforms enforce FDA drug supply chain traceability mandates through interoperable data exchange. German pharmaceutical distributors prioritize these systems to meet EMA Falsified Medicines Directive deadlines, driving compliance-driven procurement cycles.
- Administration Tools:Hospital-centric scheduling and dose registry systems anchor Oracle Cerner deployments across North American health systems.
- Distribution Services:Last-mile logistics and cold chain custody management narrow the revenue gap through optimization.
Tracking Software dominates installed base. Distribution Services is where expansion concentrates.
End User:
Cost tier stratification separates premium enterprise deployments from budget-constrained municipal programs. Government Agencies and Hospitals absorb platform complexity, while Pharmacies and Clinics prioritize turnkey solutions with minimal IT overhead.
- Government Agencies:National immunization programs require population-scale scheduling, adverse event reporting, and cross-jurisdictional data interoperability. India's state health ministries drive cost-optimized implementations under CDSCO cold chain guidelines, expanding addressable market for monitoring device manufacturers.
- Hospitals:Integrated electronic health record connectivity and real-time inventory visibility anchor procurement criteria. United States health systems favor cloud-native architectures collapsing traditional capital barriers.
- Pharmacies:Retail chains prioritize lightweight mobile-first solutions for community vaccination sites.
- Clinics:Federally qualified health centers select subscription models lowering entry barriers for constrained capital budgets.
Hospitals anchor premium tier revenue. Government Agencies represent the steepest expansion trajectory as digital immunization infrastructure scales.
Technology:
Application maturity separates proven deployments from emerging architectures. IoT Solutions and Cloud-based Systems command production budgets, while AI Analytics and Mobile Applications capture innovation investment.
- Cloud-based Systems:SaaS delivery models displace on-premise infrastructure as health systems abandon capital-intensive legacy deployments. German state health ministries modernize scheduling systems through annual recurring revenue structures visible in municipal procurement shifts.
- AI Analytics:Predictive demand forecasting algorithms reduce inventory carrying costs for temperature-sensitive biologics. Large United States hospital systems accelerate adoption as predictive capabilities compress waste rates.
- IoT Solutions:Sensor networks with automated alert protocols maintain cold chain integrity via edge computing architectures.
- Mobile Applications:Field vaccination worker tools gain traction in last-mile drone delivery corridors.
Cloud-based Systems hold majority deployment share. AI Analytics is climbing the fastest as procurement criteria prioritize predictive capabilities.
Application:
Volume concentration varies by program scale and urgency. Immunization Programs and Emergency Responses drive peak procurement cycles, while Clinical Trials and Research Studies sustain specialized niche demand.
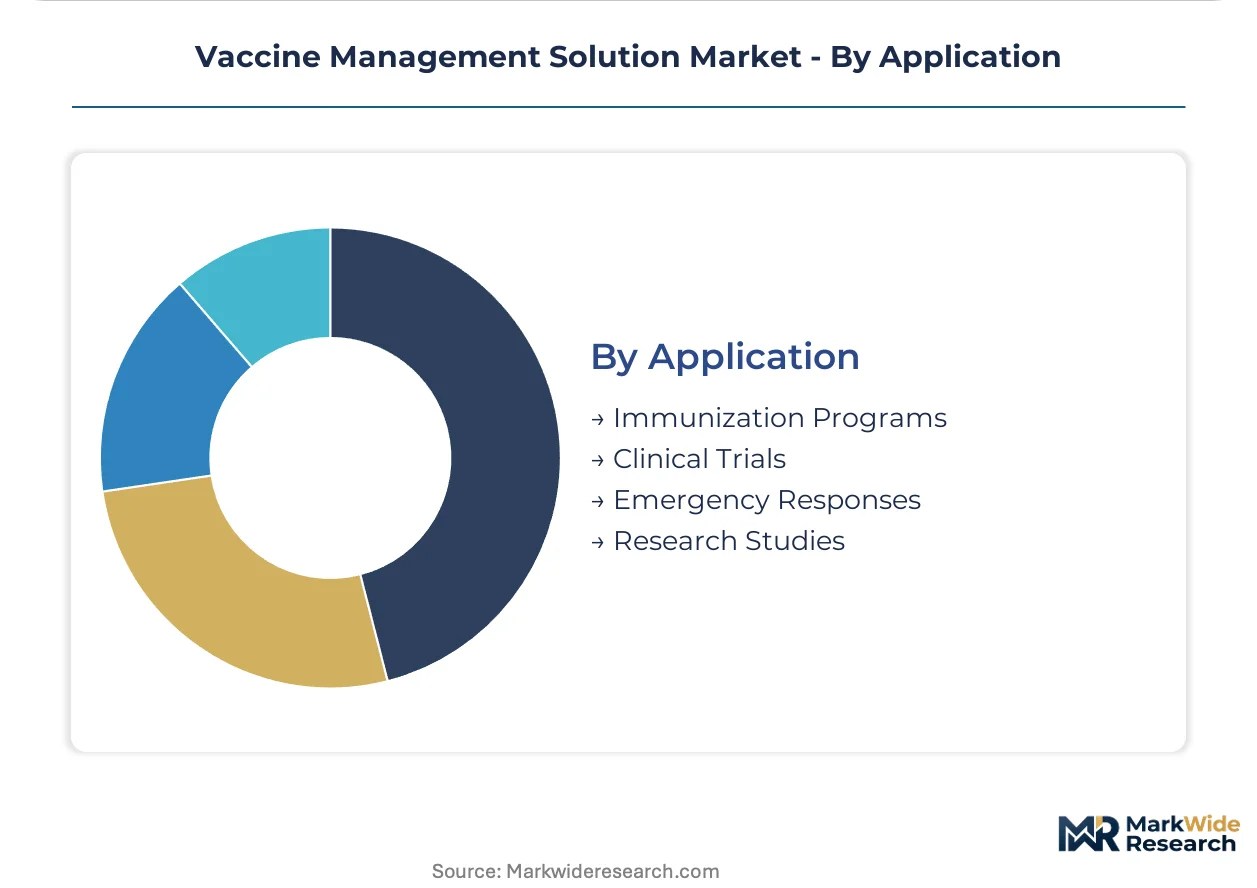
- Immunization Programs:Population-scale deployment platforms integrate scheduling, supply forecasting, and coverage tracking for national health agencies. India's Universal Immunization Programme modernization under CDSCO digital verification mandates expands monitoring device procurement channels.
- Emergency Responses:Rapid deployment architectures for pandemic and outbreak scenarios prioritize mobile cold chain and field verification. WHO prequalification standards for temperature monitoring devices shape procurement specifications in low-resource settings previously served by informal suppliers.
- Clinical Trials:Phase III vaccine studies require GCP-compliant chain of custody documentation and site-level inventory reconciliation.
- Research Studies:Academic and epidemiological investigations utilize specialized analytics for immunization coverage pattern analysis.
Immunization Programs anchor recurring revenue. Emergency Responses is gaining share fastest as outbreak preparedness budgets institutionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States hospital systems deploying premium cloud-native architectures, while Indian state health ministries drive cost-optimized implementations that compress margins for platform vendors.
United States
Academic medical centers in Boston and the Research Triangle upgrade ultra-low temperature infrastructure for mRNA biologics. FDA DSCSA serialization mandates compel pharmaceutical distributors to deploy interoperable tracking systems by statutory deadlines. The Southeast corridor from Atlanta to Miami anchors hospital-centric administration tool deployments.
Germany
State health ministries modernize legacy scheduling systems through subscription-based procurement models. EMA Falsified Medicines Directive enforcement tightens serialization requirements for pharmaceutical distributors operating across European Union member states. The Rhine-Ruhr industrial cluster concentrates cold chain hardware distribution hubs serving Central European markets.
India
State health ministries drive population-scale immunization program digitization under cost constraints. CDSCO cold chain guidelines mandate digital verification layers for vaccine distribution, expanding procurement channels for monitoring device manufacturers. Karnataka and Maharashtra host implementation centers for government immunization platform rollouts.
United Kingdom
NHS trusts prioritize cloud-native architectures displacing on-premise infrastructure in London and Manchester health systems. GDPR compliance frameworks shape data localization requirements for patient immunization records. The Oxford-Cambridge arc sustains clinical trial application demand for GCP-compliant chain of custody documentation.
Japan
Metropolitan hospital networks in Tokyo and Osaka adopt predictive demand forecasting algorithms to reduce inventory carrying costs for temperature-sensitive biologics. PMDA guidance on digital health platforms influences procurement specifications for integrated vaccine management systems. The Kansai region anchors pharmaceutical distributor investments in serialization infrastructure.
Vaccine Management Solution Market Competitive Environment
Concentration sits with diversified health IT conglomerates that leverage existing hospital relationships to anchor vaccine management platform deployments. Three to four enterprise-scale vendors capture premium-tier revenue through integrated electronic health record connectivity. Strategic archetypes separate cloud-native entrants with SaaS delivery models from legacy incumbents executing forced transitions. Competitive moves center on M&A for cold chain hardware capabilities and strategic partnerships bridging software-hardware integration gaps.
Among diversified technology conglomerates, IBM Corporation and Oracle Corporation occupy positions spanning enterprise software through health system infrastructure. McKesson Corporation exemplifies distribution-centric archetypes with backward integration into cold chain custody management. Infosys Public Services, Inc. represents cost-optimized implementation specialists competing for government immunization program tenders in emerging markets.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Accenture |
| VaxCare Corp |
| McKesson Corporation |
| Cardinal Health |
| Infosys Public Services, Inc. |
| Siemens Healthineers |
| CureMD Healthcare |
| Others |
Value Chain & Pricing Dynamics
FDA DSCSA serialization mandates and WHO prequalification standards gate both supply qualification and price differentiation simultaneously, forcing platform vendors to absorb certification costs while tiering offerings around compliance depth. Configured-to-order deployments for hospital EHR integration command substantial premiums over standardized SaaS tiers for municipal immunization programs. Price differentiation rests on certification grade and geographic delivery cost, with cloud-native entrants compressing mid-market pricing through subscription models. Cost optimization pressure intensifies in Indian state tenders, while United States academic medical centers show lowest price sensitivity for ultra-low temperature infrastructure.
Pricing Analysis
Configured-to-order pricing for Oracle Cerner-anchored hospital deployments spreads substantially above standardized SaaS tiers for government immunization programs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated serialization platforms from CDSCO-compliant monitoring devices and basic scheduling modules. Pricing pressure stems from Infosys Public Services competing on cost-optimized tenders in emerging markets. Municipal health departments exhibit highest price sensitivity; integrated health systems least.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for IoT sensor networks and lithium-ion battery cells. Hardware assembly concentrates in China, South Korea, and Taiwan; software development clusters in United States and Germany. Cold chain equipment draws from East Asian electronics suppliers and German precision engineering. Single-source vulnerability sits with specialized temperature sensor manufacturers. Distribution runs through pharmaceutical distributors with DSCSA compliance mandates and government tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting around interoperability mandates, with FDA DSCSA deadlines forcing consolidation of point solutions into unified ecosystems spanning manufacture through patient administration.
For Market Incumbents: Shield hospital relationships through accelerated SaaS transitions and backward integration into cold chain hardware capabilities. Cloud-native entrants threaten premium-tier revenue through subscription democratization. Certification investment in WHO prequalification standards anchors defensive positioning in low-resource procurement channels. For New Entrants and Emerging Players: Last-mile drone delivery corridors in sub-Saharan Africa present white-space opportunity where incumbent logistics networks under-serve remote vaccination sites. WHO prequalification standards open procurement channels previously captured by informal suppliers. Partner with regional drone operators for first-mover positioning in Ghana and Rwanda corridors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native vaccine logistics platforms as SaaS delivery models displace on-premise infrastructure deployments. Long-term viability favors vendors with integrated software-hardware stacks and government contract pipelines. Monitor CDSCO tender award velocity as inflection indicator for emerging market expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Hardware Backward Integration | McKesson Corporation sustains distribution dominance through captive storage solution production. |
| Platform Integration Partnership | Oracle Corporation leverages Cerner acquisition to anchor EHR-connected administration tool deployments. |
| WHO Prequalification Certification | Monitoring device manufacturers unlock procurement channels in India's Universal Immunization Programme. |
| Geographic Expansion via Government Tender | Infosys Public Services captures cost-optimized implementations in Karnataka and Maharashtra state ministries. |
| AI Analytics Product Launch | Predictive demand forecasting capabilities reduce inventory carrying costs for United States hospital systems. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital IT procurement managers, pharmaceutical distribution executives, state health ministry officials, and cold chain logistics specialists. Secondary validation drew from FDA DSCSA guidance documents, CDSCO cold chain guidelines, WHO prequalification standards, EMA Falsified Medicines Directive enforcement notices, and hospital procurement database extracts. Bottom-up sizing of product-type deployments triangulated against top-down health system IT spending benchmarks.
Across the analysis window, value projections were derived from segment-level CAGRs applied to baseline penetration rates across cloud-based systems, AI analytics, IoT solutions, and mobile applications. Modeled dimensions encompassed product type, technology architecture, end-user category, and application urgency. Forecast inputs incorporated statutory compliance deadlines, health system modernization budgets, and emerging market digitization trajectories.
Forecasts assume regulatory continuity in FDA DSCSA enforcement, EMA Falsified Medicines Directive implementation, and CDSCO cold chain guidelines; material policy shifts would require re-modeling of procurement cycle timing and platform architecture requirements. Practitioners should keep alternative scenarios live as data localization requirements and AI governance frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Retropharyngeal Abscess Treatment Market
Infectious Disease
Burkholderia Infections Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Viral Gastroenteritis Market
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Valley Fever Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Chlamydia Infection Treatment Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Periodic Fever Syndrome Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Global Infectious Disease Drugs Market
Infectious Disease
Chikungunya Fever Market