
 Dental Piezoelectric Ultrasonic Unit Market | 2026-2036
Dental Piezoelectric Ultrasonic Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Piezoelectric Ultrasonic Unit Market Outlook
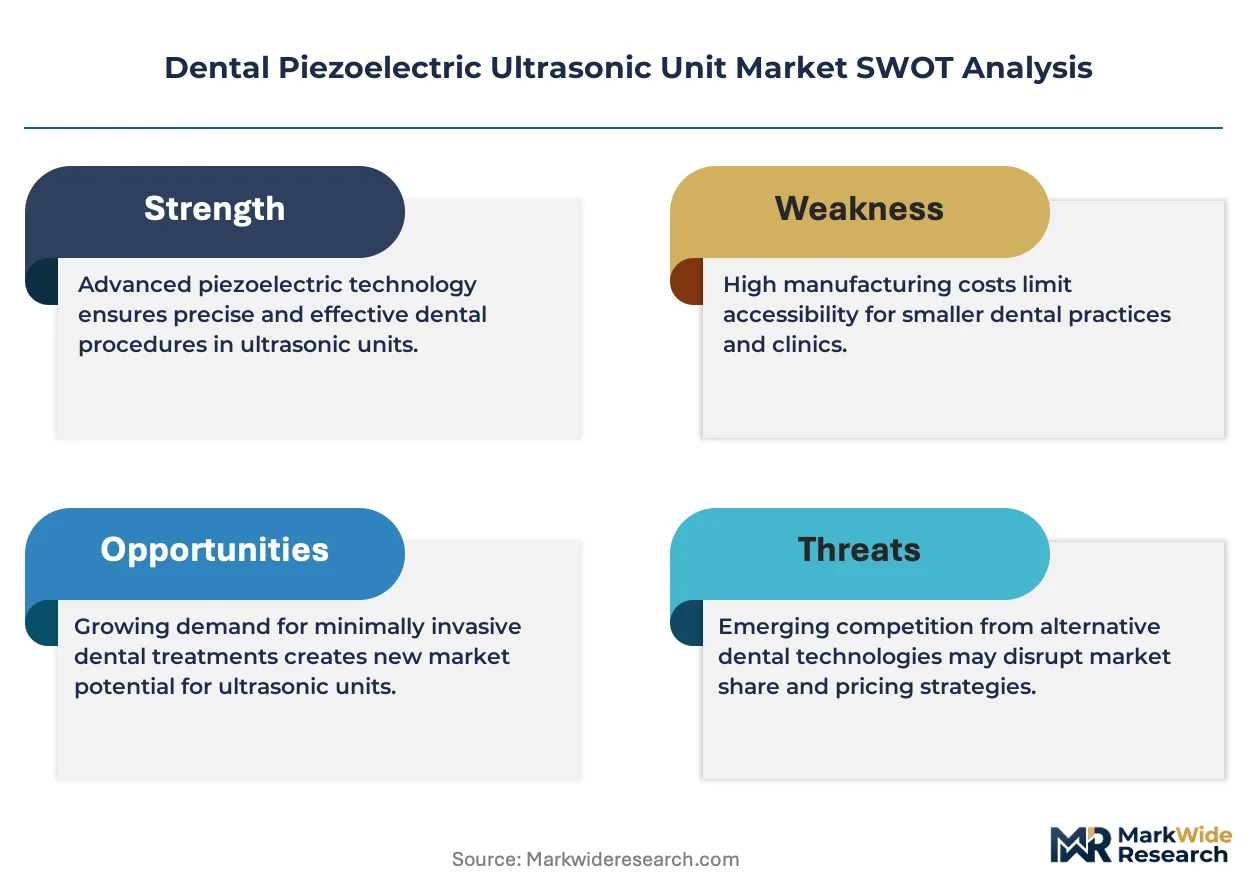
German and Italian precision component manufacturers is realigning capacity toward piezoelectric ceramic transducers for dental applications. Dentsply Sirona leverages integrated digital workflows to sustain its position across premium tabletop systems. Kerr Corporation anchors North American distribution through specialized dental dealer networks. Cefla S.C. competes on manufacturing scale in electromagnetic compatibility-compliant handpiece production.
A dental piezoelectric ultrasonic unit converts electrical energy into mechanical vibrations via lead zirconate titanate ceramic transducers operating at frequencies between 25 and 35 kHz, enabling selective cutting of mineralized tissue without thermal damage to surrounding soft tissue. Portable units dominate ambulatory dental clinic procurement due to space constraints and multi-operatory flexibility, while tabletop configurations retain margin concentration in hospital-based oral surgery suites. Periodontology represents the most mature application segment, whereas implantology drives replacement demand as osteotomy preparation protocols advance.
CE marking under the EU Medical Device Regulation and FDA 510(k) clearance govern electrical safety and biocompatibility standards for piezoelectric dental devices, with ISO 13485 quality management certification now a baseline requirement for supplier qualification. Japan's PMDA maintains distinct electromagnetic compatibility testing protocols that create incremental compliance costs for non-domestic manufacturers. Stakeholders must monitor evolving software integration requirements as wireless connectivity and treatment logging capabilities become standard features in next-generation systems.
Market Dynamics
The Dental Piezoelectric Ultrasonic Unit Market is restructuring around EU Medical Device Regulation compliance timelines, which are compressing certification cycles and forcing component suppliers to consolidate electromagnetic compatibility testing capabilities ahead of 2027 renewal deadlines.
Growth Catalysts
- EU MDR CE marking acceleration:German dental clinics are fast-tracking piezoelectric unit procurement to secure grandfathered device approvals before stricter biocompatibility documentation requirements take effect.
- Periodontal therapy protocol standardization:French university hospitals are mandating piezoelectric bone surgery for implant site preparation, creating institutional demand pull.
- Lead zirconate titanate transducer yield improvements:Italian ceramic manufacturers have achieved defect rate reductions that lower unit production costs.
Market Restraints
- Piezoelectric ceramic supply concentration:High-purity PZT powder production clusters in three Japanese prefectures, exposing buyers to shipping disruption risk.
- FDA 510(k) predicate device limitations:Novel frequency modulation algorithms face extended review timelines when no cleared comparator exists.
- Er:YAG laser substitution in soft tissue:Some Italian oral surgery centers are redirecting capital toward multi-wavelength laser platforms.
Strategic Opportunities
- Spain's private dental roll-up wave:Consolidated practice chains in Madrid and Barcelona are standardizing equipment across acquired locations.
- Wireless handpiece integration:Bluetooth-enabled torque feedback systems are converging with piezoelectric drivers for real-time osteotomy monitoring.
- Japan PMDA electromagnetic compatibility harmonization:METI is aligning test protocols with IEC 60601-2-60, reducing duplicate certification costs.
Industry Challenges
- ISO 13485 auditor capacity constraints:Notified bodies in Germany and France are booking quality management certification reviews 14-18 months in advance.
- Legacy scaler tip inventory stranding:Clinics with substantial non-universal thread规格 investments face write-downs during platform migrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Piezoelectric Ultrasonic Unit Market |
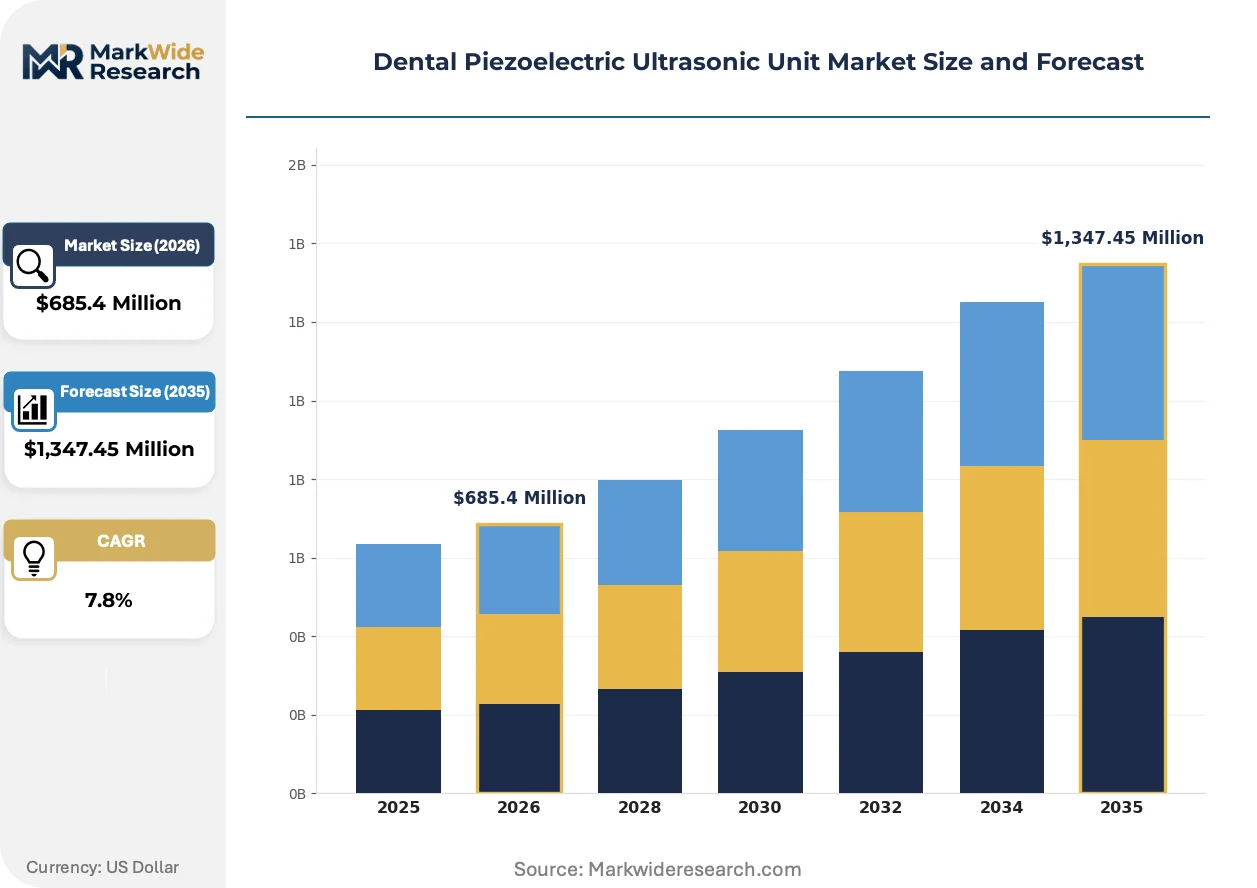
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,347.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Tabletop Units, Handpieces, Accessories Application: Periodontology, Implantology, Oral Surgery, Endodontics End User: Dental Clinics, Hospitals, Research Institutions, Dental Schools Technology: Ultrasonic Technology, Electromechanical Systems, Software Integration, Wireless Solutions |
| Companies Covered | Cefla S.C., Dentsply Sirona, Aseptico Inc., Parkell Inc., Coltene Whaledent, Den-Mat Holdings LLC, Deldent, Kerr Corporation, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Piezoelectric Ultrasonic Unit Market Strategic Shifts
Digital workflow integration is redefining competitive advantage in dental piezoelectric systems, with software-controlled amplitude modulation and cloud-based treatment logging becoming baseline expectations rather than premium differentiators.
Multi-frequency transducer architecture is modularizing the hardware layer of piezoelectric units. German oral surgery suites are adopting swappable 25 kHz and 35 kHz handpiece modules within single generator housings. This flexibility is modularizing procurement decisions, allowing clinics to defer specialty tip investments until case mix justifies expansion.
EU Medical Device Regulation Article 10 technical documentation requirements are intensifying post-market surveillance obligations for piezoelectric device manufacturers. The regulation mandates systematic complaint trending and clinical follow-up protocols that smaller component suppliers cannot resource internally. Western European private practice distributors are demanding manufacturer-held liability insurance minimums that filter out sub-scale competitors.
Fee-for-service reimbursement compression in France is shortening equipment replacement cycles among independent practitioners. Leasing arrangements through specialized dental finance intermediaries are displacing outright purchase as the dominant acquisition mode. This shift is most visible in Paris and Lyon, where practice valuation multiples favor cash preservation over balance sheet asset ownership.
Dental Piezoelectric Ultrasonic Unit Market Segmentation
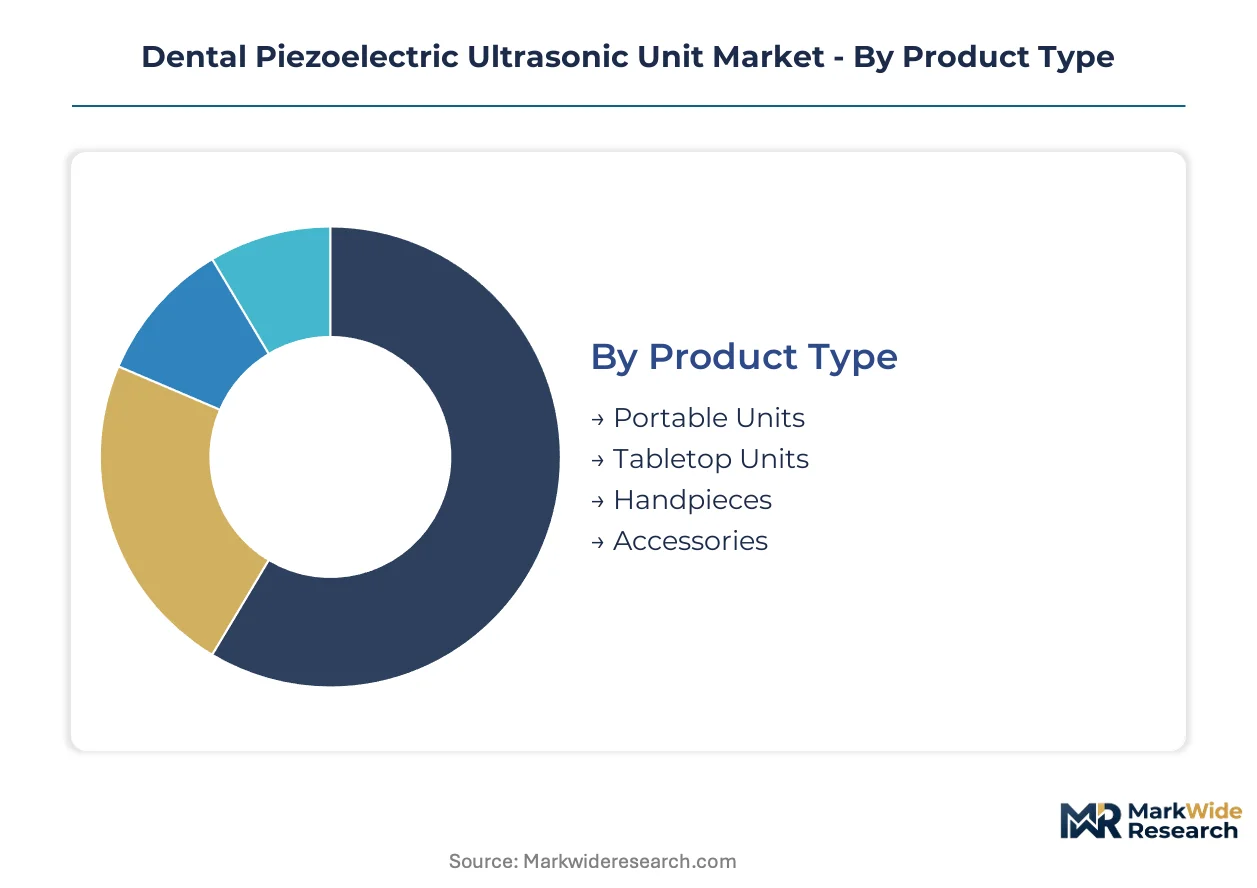
Segmentation in the Dental Piezoelectric Ultrasonic Unit Market reveals distinct regulatory pathways and procurement economics across product configurations and clinical settings. Each category carries specific certification burdens that shape manufacturer investment priorities and distributor margin structures.
Product Type:
Portable units and tabletop systems face divergent CE marking timelines under EU MDR, with portable configurations requiring additional electromagnetic compatibility documentation for battery-powered variants.
- Portable Units:Battery-powered generators housed in compact enclosures for multi-operatory deployment. German private dental clinics in Munich and Hamburg prioritize these for space-constrained practice layouts where equipment mobility supports chairside efficiency. CE marking for portable units demands expanded electrical safety testing under IEC 60601-1 third edition.
- Tabletop Units:Fixed-installation generators with integrated irrigation systems and amplitude modulation controls. French hospital-based oral surgery suites in Paris and Lyon specify these for implant osteotomy protocols requiring sustained power output. FDA 510(k) predicates for tabletop systems are more established, compressing US market entry timelines.
- Handpieces:Detachable transducer assemblies with universal or proprietary thread specifications.
- Accessories:Scaler tips, irrigation tubing, and sterilization cassettes.
Portable units sit at the top of the volume ranking, with tabletop configurations climbing the fastest as hospital procurement consolidates around centralized equipment standards.
Application:
Clinical application determines reimbursement coding and thus capital equipment recovery periods, with periodontology offering established fee schedules versus implantology's procedure-specific variability.
- Periodontology:Calculus removal and root planing using linear oscillation patterns. Italian dental clinics in Milan and Rome represent mature demand centers where piezoelectric units have displaced magnetostrictive alternatives. Fee-for-service reimbursement in Italy's private sector supports 36-48 month equipment replacement cycles.
- Implantology:Osteotomy preparation and ridge splitting via selective cutting action. Spanish private dental roll-ups in Madrid and Barcelona are standardizing piezoelectric protocols across acquired practices to reduce surgical variability. ISO 13485 certification is mandatory for suppliers targeting implantology applications due to higher liability exposure.
- Oral Surgery:Third molar extraction and bone harvesting procedures.
- Endodontics:Canal debridement and apical surgery applications.
Periodontology commands the highest procedure volume, while implantology is gaining share fastest as surgical protocol standardization accelerates across Western European teaching hospitals.
End User:
Customer type segmentation tracks procurement authority concentration, with dental clinics exhibiting fragmented purchasing decisions versus hospital materials management departments.
- Dental Clinics:Independent and group practice settings where clinician-owners control equipment selection. French private practitioners in Lyon and Marseille increasingly favor leasing arrangements through specialized dental finance intermediaries. CE marking and ISO 13485 compliance are baseline requirements for supplier qualification.
- Hospitals:Academic medical centers and community hospital oral surgery departments with centralized procurement functions. German university hospitals in Berlin and Heidelberg mandate piezoelectric units for implant site preparation protocols. EU MDR technical documentation requirements extend hospital liability to post-market surveillance obligations.
- Research Institutions:Biomechanical testing and transducer development facilities.
- Dental Schools:Training programs requiring standardized equipment platforms for curriculum consistency.
Dental clinics dominate absolute unit shipments, with hospitals expanding most quickly as institutional procurement standardizes around electromagnetic compatibility-compliant platforms.
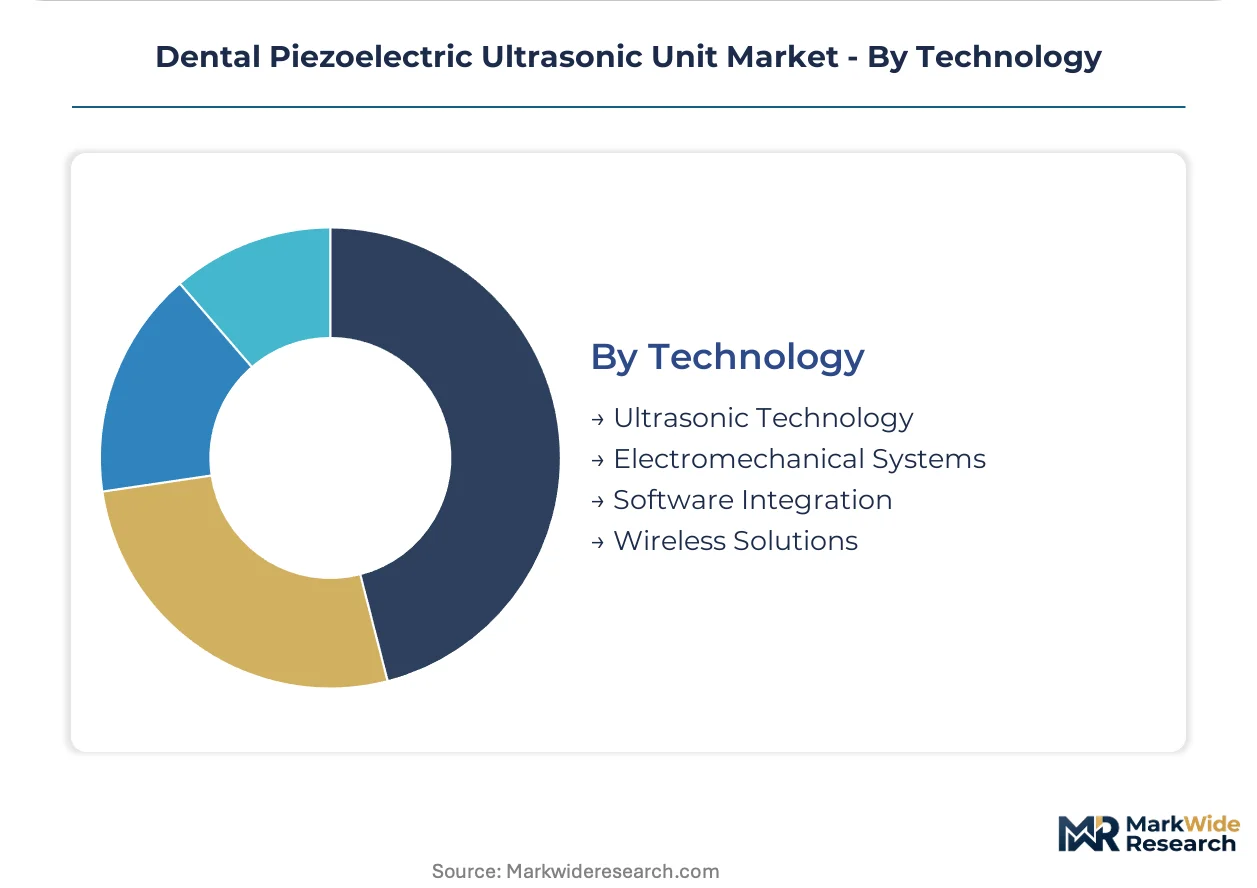
Technology:
Technology architecture determines software validation burdens, with wireless-enabled systems requiring additional cybersecurity documentation under EU MDR Annex I.
- Ultrasonic Technology:Lead zirconate titanate ceramic transducers operating at 25-35 kHz frequencies. Italian ceramic manufacturers in Emilia-Romagna have achieved yield improvements that lower transducer production costs. PMDA electromagnetic compatibility testing in Japan creates incremental compliance costs for non-domestic suppliers.
- Electromechanical Systems:Handpiece torque feedback and irrigation pressure modulation. German precision component manufacturers in Baden-Württemberg are realigning capacity toward piezoelectric dental applications. CE marking under EU MDR governs electrical safety and biocompatibility standards.
- Software Integration:Cloud-based treatment logging and amplitude modulation algorithms.
- Wireless Solutions:Bluetooth-enabled handpiece connectivity and real-time data transmission.
Ultrasonic technology anchors current revenue concentration, with wireless solutions following the steepest expansion trajectory as digital workflow integration becomes a baseline procurement requirement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands higher per-clinic equipment density than France, yet Spanish private dental roll-ups are deploying capital faster than either market as consolidation accelerates across Madrid and Barcelona.
Germany
Baden-Württemberg precision manufacturers are redirecting ceramic transducer capacity toward dental applications as medical device demand strengthens. KBA and BfArM oversight of electromagnetic compatibility testing compresses product launch timelines for imported systems. Munich and Hamburg dental clinics prioritize portable configurations for space-constrained multi-operatory layouts.
France
Lyon and Marseille independent practitioners are shifting toward leasing arrangements through specialized dental finance intermediaries as fee-for-service reimbursement tightens. ANSM biocompatibility documentation requirements under EU MDR Article 10 intensify post-market surveillance obligations for device suppliers. Paris university hospitals now mandate piezoelectric protocols for implant site preparation.
Italy
Milan and Rome private clinics have completed the displacement of magnetostrictive alternatives, establishing mature replacement demand cycles. CE marking compliance costs filter sub-scale competitors from the supplier base. Emilia-Romagna ceramic manufacturers have achieved defect rate reductions in lead zirconate titanate transducer production.
Spain
Madrid and Barcelona dental roll-ups are standardizing equipment across acquired locations to reduce surgical variability and capture procurement scale. The Spanish Agency for Medicines and Health Products aligns with EU MDR renewal deadlines compressing certification cycles for non-domestic manufacturers. Andalusian private practice chains are replicating the consolidation model.
Japan
Tokyo and Osaka oral surgery centers maintain distinct procurement preferences for domestically manufactured transducer assemblies. PMDA electromagnetic compatibility testing protocols create incremental compliance costs for European and North American suppliers. METI initiatives to harmonize test standards with IEC 60601-2-60 are reducing duplicate certification burdens.
Dental Piezoelectric Ultrasonic Unit Market Competitive Environment
German and Italian producers anchor the component supply tier; US and Swiss specialists hold integrated system positions. The market structure concentrates around three to five vertically integrated manufacturers controlling generator and handpiece assembly, while ceramic transducer supply fragments across regional specialists. Two strategic archetypes dominate: precision component fabricators with captive ceramic capacity, and digital workflow integrators bundling software-controlled amplitude modulation. Competitive moves center on electromagnetic compatibility testing consolidation ahead of EU MDR deadlines, and backward integration into transducer manufacturing to secure PZT supply.
Among integrated system manufacturers, Dentsply Sirona and Kerr Corporation exemplify contrasting geographic anchoring strategies, while Cefla S.C. occupies a position within the European manufacturing scale tier. Dentsply Sirona represents the digital workflow integrator archetype through its positioning across premium tabletop configurations. Kerr Corporation sits within the North American distribution-focused tier, leveraging specialized dental dealer networks for market access. Cefla S.C. anchors Italian manufacturing scale in electromagnetic compliance-compliant handpiece production, competing on production efficiency rather than software differentiation.
| Leading Market Players |
|---|
| Cefla S.C. |
| Dentsply Sirona |
| Aseptico Inc. |
| Parkell Inc. |
| Coltene Whaledent |
| Den-Mat Holdings LLC |
| Deldent |
| Kerr Corporation |
| Boston Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
Lead zirconate titanate powder spot indices in Japanese prefectures cascade through three pricing tiers for finished piezoelectric units, with ceramic purity grades separating premium hospital systems from economy-tier clinic procurement in Western Europe.
Pricing Analysis
Distributor markups of 22-28 percent on tabletop systems compress manufacturer margins while direct-to-clinic leasing arrangements through dental finance intermediaries reshape acquisition economics. Three-tier pricing structure across premium, standard, and economy levels tracks CE marking tier and ISO 13485 certification status. Pricing pressure stems from reimbursement compression in French fee-for-service dentistry. Independent practitioners in Lyon and Marseille exhibit highest price sensitivity; Paris university hospitals show lowest.
Supply Chain Analysis
Specialized ceramic engineers in Baden-Württemberg and Emilia-Romagna command premium wages that inflate transducer assembly costs across European manufacturing nodes. High-purity PZT powder production clusters in three Japanese prefectures alongside precision machining capacity in Germany and Italy. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade ceramic feedstock. Distribution runs through specialized dental dealer networks in North America and direct manufacturer relationships in Western European hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in Germany and France exceed Spanish certification timelines by 8-14 months, creating manufacturing relocation incentives.
For Market Incumbents: Deploy electromagnetic compatibility testing consolidation ahead of EU MDR renewal deadlines. Secure captive PZT supply through backward integration into ceramic transducer manufacturing. Counter Er:YAG laser substitution in Italian oral surgery centers by bundling software-controlled amplitude modulation as standard. For New Entrants and Emerging Players: Specialized dental finance intermediaries offer channel access without incumbent dealer network investments. Target Spanish private dental roll-ups in Madrid and Barcelona for fastest penetration. Pursue wireless handpiece integration partnerships to bypass generator hardware development costs. For Investors and Strategic Acquirers: Asymmetric upside sits with precision component fabricators holding captive ceramic capacity and ISO 13485 certification. Five-to-ten year viability hinges on EU MDR technical documentation capabilities and post-market surveillance infrastructure. Monitor PMDA electromagnetic compatibility harmonization progress with IEC 60601-2-60 as inflection signal for Japanese market entry cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Accelerated certification cycles ahead of 2027 renewal deadlines compress competitive timelines for German manufacturers. |
| Backward Integration into PZT Transducers | Captive ceramic supply secures margin control against Japanese powder production concentration risks. |
| Wireless Handpiece Development | Bluetooth-enabled torque feedback convergence with piezoelectric drivers enables real-time osteotomy monitoring differentiation. |
| Hospital System Partnership | Paris and Lyon university hospital standardization mandates create institutional demand pull for tabletop configurations. |
| Software Companion Development | Cloud-based treatment logging and amplitude modulation algorithms shift competitive advantage toward digital workflow integrators. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental equipment procurement managers, biomedical engineers at university hospitals, GPO contracts administrators, and ceramic transducer manufacturing executives with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract registries. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Historical reference periods anchored volume and value trajectories across the projection horizon, with segmentation modeled across product configuration, clinical application, end-user type, and technology architecture dimensions. CAGRs derived from fitted growth curves incorporating PZT ceramic yield improvements, EU MDR compliance cost inflation, and wireless connectivity adoption curves as dental-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA electromagnetic compatibility harmonization delays and Japanese ceramic supply disruptions. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory timeline adherence. Practitioners should monitor EU MDR notified body auditor capacity constraints and Spanish dental roll-up consolidation velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Nano Dentistry Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Dental Radiometer Market
Dental Devices
Asia-Pacific Dental Lab Market
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
Dental Contouring Market
Dental Devices
China Dental Implants Market
Dental Devices
North America Dental Aligners Market
Dental Devices
China Dental Devices Market
Dental Devices
Canada Dental Devices Market
Dental Devices
Dental Caries Market
Dental Devices
Dental Forceps Market
Dental Devices
Dental Implants and Abutment Systems Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Dental Autoclave Market
Dental Devices
Dental 3D Scanners Market