
 Pentane Market | 2026-2036
Pentane Market Size, Share, and Industry Trends Forecast 2026-2036
Pentane Market Intelligence
China's expansion of petrochemical capacity is reshaping the supply dynamics for pentane feedstocks. ExxonMobil Corporation leverages its vast integrated refining operations to supply multiple pentane isomers. In contrast, SK Innovation competes on the basis of its specialized production of high-purity cyclopentane for the electronics sector. Royal Dutch Shell maintains a strong position through its extensive global distribution network.
Pentane is a volatile liquid alkane hydrocarbon, C5H12, derived from natural gas liquids or crude oil refining. Its low boiling point and high vapor pressure make it an effective component in various industrial processes. The blowing agent application, particularly for polyurethane and polystyrene foams, represents the largest market segment by volume. Within product types, n-pentane is the primary choice for foam blowing, while isopentane is valued in specialty chemical synthesis and as a fuel additive.
Regulations governing volatile organic compounds and ozone-depleting substances directly influence pentane selection. The US EPA's SNAP program and the EU's F-Gas Regulation and REACH framework guide the use of pentane isomers as alternatives to fluorinated blowing agents. Navigating these disparate regional compliance requirements is a critical challenge for producers and end-users. Success depends on developing formulations that meet both environmental standards and final product performance criteria.
Market Dynamics
The global regulatory clampdown on hydrofluorocarbons, driven by the EU's F-Gas Regulation, is the primary force shaping the market. This creates a direct pull for pentane as a substitute blowing agent in polyurethane foam manufacturing for insulation.
Growth Catalysts
- HFC Phase-Down:EU F-Gas Regulation forces hydrofluorocarbon replacement, creating direct demand for pentane as a blowing agent in insulation foams.
- Energy Efficiency Standards:Stricter global building codes require high-performance insulation, increasing consumption of pentane-blown polyurethane and polystyrene foams.
- Cold Chain Logistics:Growth in refrigerated transport for food and pharmaceuticals fuels demand for pentane-based insulation in containers and packaging.
Market Restraints
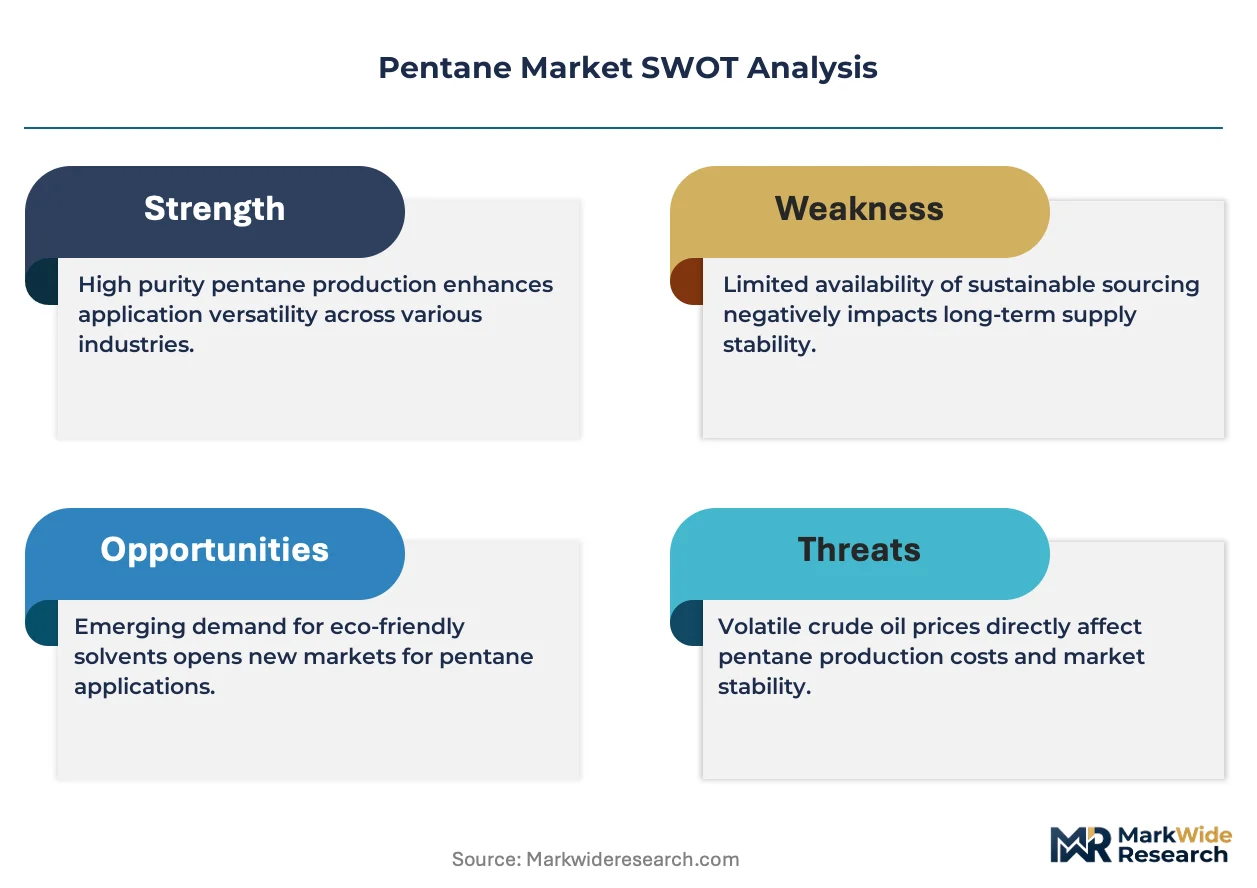
- Feedstock Volatility:Pentane's price is tied to volatile crude oil and natural gas liquid (NGL) markets, creating cost instability for producers and end-users.
- Handling and Safety Costs:High flammability requires costly specialized storage, transport, and processing equipment, increasing operational and capital expenditures.
- Substitution by HFOs:Non-flammable hydrofluoroolefins (HFOs) pose a substitution threat in applications where fire safety regulations are exceptionally stringent.
Strategic Opportunities
- High-Purity Electronics:Expanding production of high-purity cyclopentane for the electronics sector, used in manufacturing liquid crystal displays and other components.
- Latin American Construction:Targeting construction markets in Mexico and Brazil where new energy efficiency regulations create demand for modern insulation materials.
- Optimized Isomer Blends:Developing tailored n-pentane/isopentane blends to fine-tune insulation performance and processing for specific foam formulations.
Industry Challenges
- Regulatory Fragmentation:Navigating disparate regional compliance requirements for volatile organic compounds, such as the EU's REACH framework and varying state-level rules in the United States.
- Supply Chain Complexity:Managing the logistics for a highly flammable material requires specialized infrastructure and adherence to strict transport codes, complicating delivery to remote markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pentane Market |
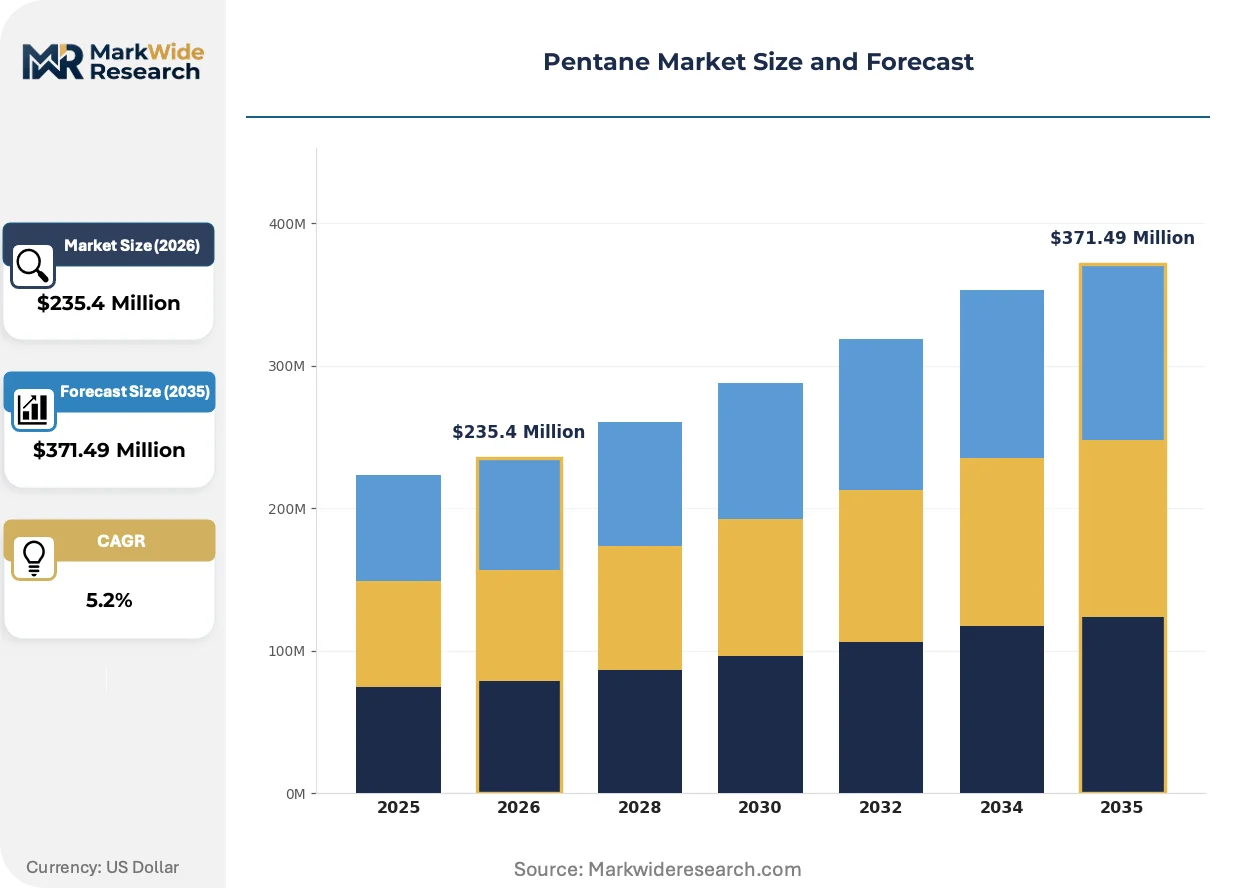
| Market Size in 2026 | $235.4 Million |
| Market Size in 2035 | $371.49 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: n-Pentane, Isopentane, Cyclopentane, Mixed Pentane Application: Blowing Agent, Solvent, Refrigerant, Fuel Additive, Chemical Intermediate End Use Industry: Foam Manufacturing, Pharmaceutical Production, Cosmetic Formulation, Paints & Coatings, Agrochemicals Packaging Type: Drums, Bulk Tanks, Cylinders, Intermediate Bulk Containers |
| Companies Covered | INEOS Group Holdings, LG Chem, ExxonMobil Corporation, Maruzen Petrochemical, SK Innovation, Royal Dutch Shell, Chevron Phillips Chemical Company, Bharat Petroleum Corporation Limited, Phillips 66, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pentane Market Strategic Shifts & Innovations
Innovation in the pentane market centers on balancing enhanced product performance with stringent environmental regulations. This involves advancements in chemical formulation and process technology to meet demands for sustainability and efficiency.
Pentane-HFO blends are an emerging composite blowing agent system. These formulations combine pentane's cost-effectiveness with the low flammability of hydrofluoroolefins. Foam manufacturers are adopting these blends, which is hybridizing the market by creating a mid-tier category balancing safety, cost, and insulation value.
The European Union's REACH framework continues to influence the chemical supply chain. It imposes stringent data-gathering and safety assessment requirements on pentane isomers sold within the EU. This regulatory burden impacts smaller producers, who must invest in compliance testing or form consortiums.
A shift toward lifecycle cost analysis is altering purchasing decisions for insulation materials. The focus on upfront pentane cost is giving way to a total cost of ownership model that includes long-term energy savings. This change is most pronounced in commercial construction and cold storage.
Pentane Market Segmentation
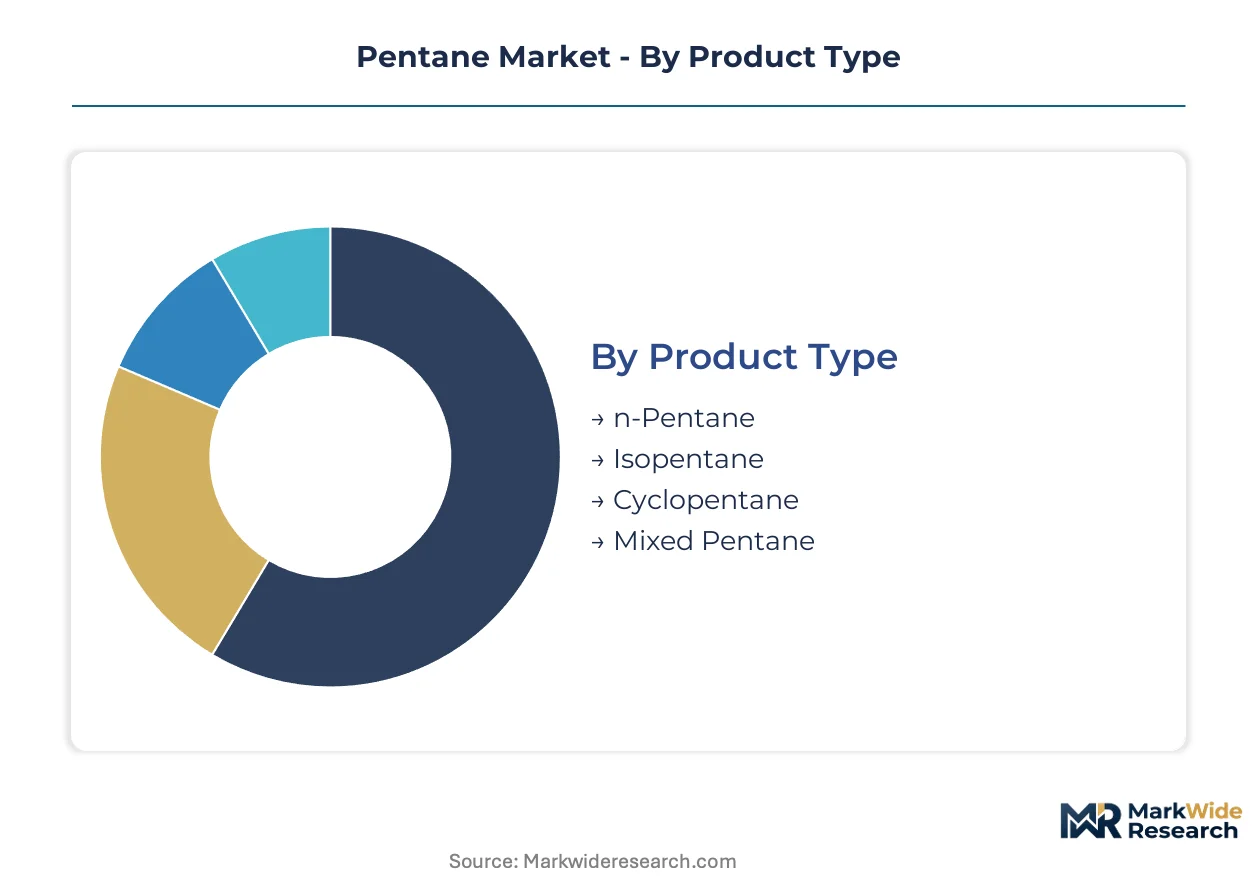
The pentane market structure reflects distinct product specifications and diverse end-use requirements across various industries. Detailed segmentation helps stakeholders understand specific demand drivers and supply chain complexities for each category. This analysis provides a granular view of market dynamics and strategic focus areas.
Product Type:
The pentane market is segmented across a diverse use-case spectrum based on distinct isomeric forms.
- n-Pentane:This straight-chain alkane is the primary choice for blowing agent applications due to its low boiling point and cost-effectiveness. Demand is concentrating in building insulation manufacturing in China, driven by the EU's F-Gas Regulation.
- Cyclopentane:A cyclic pentane isomer, it is valued for its high purity and specific physical properties, particularly in the electronics sector. Expansion of high-purity cyclopentane production supports manufacturing liquid crystal displays and other sensitive components.
- Isopentane:This branched isomer sees use in specialty chemical synthesis, contributing to various industrial processes. It also functions as a fuel additive, improving octane ratings in gasoline blends.
- Mixed Pentane:This blend of pentane isomers offers a cost-effective solution for industrial processes where precise isomer separation is not critical. It finds application in general solvent uses and as a feedstock.
The dominant share belongs to n-Pentane, while Cyclopentane is closing the gap fastest.
Application:
Market demand for pentane isomers is driven by varying volume concentration across critical industrial applications.
- Blowing Agent:This application represents the largest market segment by volume, particularly for polyurethane and polystyrene foams. Stricter global energy efficiency standards in construction increase consumption of pentane-blown insulation.
- Solvent:Pentane isomers serve as effective solvents in various industrial processes due to their non-polar nature and volatility. Demand for pentane as a solvent in chemical processing and industrial cleaning is influenced by evolving VOC regulations.
- Chemical Intermediate:Pentane functions as a building block in the synthesis of more complex organic compounds, including polymers and resins. Its use as a chemical intermediate is vital for downstream product manufacturing.
- Fuel Additive:Isopentane, in particular, is blended into gasoline formulations to enhance octane levels and improve engine performance. This application is tied to global fuel quality standards.
- Refrigerant:While niche, pentane finds limited use as a refrigerant in specific industrial systems, often in blend formulations. Environmental concerns and safety regulations impact its adoption in this segment.
The largest volume consumption is observed in Blowing Agent, with Solvent demonstrating significant expansion.
End Use Industry:
Demand patterns for pentane are shaped by the specific customer type requirements within key end-use industries.
- Foam Manufacturing:This industry is a primary consumer of pentane, especially for producing insulation foams for buildings and cold chain logistics. The HFC phase-down under the EU F-Gas Regulation creates direct demand for pentane as a substitute.
- Pharmaceutical Production:Pentane isomers are employed as solvents in extraction, purification, and crystallization processes within the pharmaceutical sector. High purity requirements are crucial for this end-use industry.
- Paints & Coatings:Pentane acts as a solvent in the formulation of paints, coatings, and adhesives, contributing to viscosity control and drying properties. Regulatory frameworks governing VOC emissions influence its use in this sector.
- Agrochemicals:Pentane is utilized as a solvent or carrier in the production of various agrochemical products, including pesticides and herbicides. Its inert nature ensures stability of active ingredients.
- Cosmetic Formulation:In the cosmetics industry, pentane functions as a solvent and carrier for active ingredients in personal care products. Formulations prioritize product stability and safety.
Foam Manufacturing drives the majority of demand, while Pharmaceutical Production is experiencing accelerated uptake.
Packaging Type:
The supply concentration for pentane dictates the prevalent packaging types for efficient distribution.
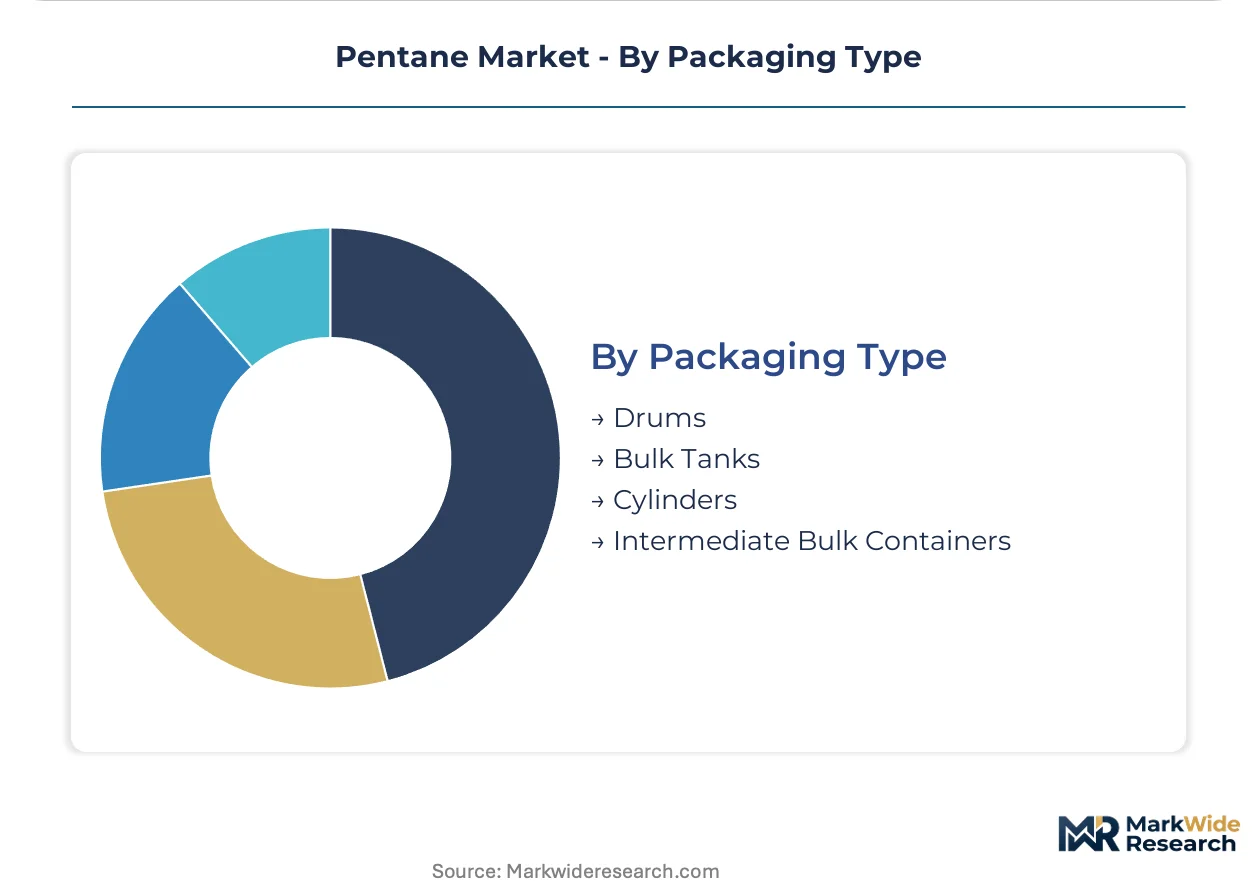
- Bulk Tanks:Large volumes of pentane are transported and stored in bulk tanks for major industrial users, such as petrochemical plants and large-scale foam manufacturers. This method offers significant cost efficiencies for high-volume delivery.
- Drums:Standard drums are used for smaller to medium-sized orders, catering to chemical distributors and various industrial clients requiring manageable quantities. Specialized handling and storage are necessary due to flammability.
- Intermediate Bulk Containers:IBCs provide a middle-ground solution for volumes larger than drums but smaller than bulk tanks, offering improved handling and storage efficiency. They are common for medium-scale industrial applications.
- Cylinders:Pentane in cylinders serves specialized applications, often involving high-purity grades or laboratory use where precise dispensing of smaller quantities is required. Safety protocols for flammable gases are stringent.
Large-scale industrial supply primarily utilizes Bulk Tanks, with Drums serving diverse smaller-volume requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive global shipping lanes and strategic port infrastructure facilitate the international distribution of pentane, connecting major production hubs to diverse end-use markets. Demand for pentane is particularly strong in regions undergoing significant industrial expansion and stringent environmental regulations.
China
China's robust construction sector and expanding industrial base drive substantial demand for pentane, especially in insulation foam manufacturing. The country's dual carbon goals promote energy-efficient building practices. Major petrochemical complexes in the Yangtze River Delta region are increasing capacity to meet this surging domestic requirement.
Germany
German manufacturers utilize pentane extensively as a blowing agent for high-performance insulation foams, driven by strict building codes. The EU F-Gas Regulation directly mandates the phase-down of hydrofluorocarbons, creating a strong pull for pentane alternatives. Chemical parks in North Rhine-Westphalia develop new pentane-based foam formulations.
United States
The United States market sees significant pentane consumption in construction insulation and as a chemical intermediate. The US EPA's SNAP program guides the adoption of pentane isomers as alternatives to fluorinated blowing agents. The Gulf Coast petrochemical corridor remains a critical hub for pentane production and distribution.
Brazil
Brazil's expanding construction market and increasing investment in cold chain logistics fuel demand for pentane-blown insulation materials. New energy efficiency regulations create opportunities for modern building materials across the country. Industrial zones around São Paulo and Rio de Janeiro are experiencing increased uptake of pentane for foam production.
South Korea
South Korea exhibits strong demand for high-purity cyclopentane, particularly from its advanced electronics manufacturing sector. National environmental policies encourage the use of pentane isomers in insulation applications to enhance energy efficiency. Major petrochemical complexes in Ulsan and Yeosu are key suppliers to both domestic and international markets.
Pentane Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying essential pentane isomers. The pentane market exhibits a tiered structure, with large integrated petrochemical companies alongside specialized producers focusing on high-purity grades. Strategic archetypes include global energy majors with vast refining capacities and niche chemical companies serving specific industrial needs. Capacity expansion and strategic partnerships remain dominant competitive moves among market participants.
Within the global energy major archetype, ExxonMobil Corporation exemplifies integrated refining operations, leveraging its vast scale to supply multiple pentane isomers across diverse end-use markets. Royal Dutch Shell plc, another prominent energy company, occupies a strong position through its extensive global distribution network, which facilitates efficient delivery of pentane products worldwide. SK Innovation Co., Ltd. represents the specialized producer archetype, focusing on high-purity cyclopentane for the electronics sector, demonstrating a targeted market strategy that addresses specific industrial requirements. These entities collectively shape the competitive dynamics through their distinct operational models and market focus.
| Leading Market Players |
|---|
| INEOS Group Holdings |
| LG Chem |
| ExxonMobil Corporation |
| Maruzen Petrochemical |
| SK Innovation |
| Royal Dutch Shell |
| Chevron Phillips Chemical Company |
| Bharat Petroleum Corporation Limited |
| Phillips 66 |
| Others |
Cost & Logistics Intelligence
Global shipping lanes' cost dynamics influence pentane supply concentration and subsequent price differentiation. Specialized transportation infrastructure is essential for distributing this flammable chemical, adding to overall logistical expenses. These costs directly impact the competitive landscape for pentane producers and end-users, especially for high-volume applications.
Pricing Analysis
Volume-based tiered pricing structures characterize the pentane market, influenced by purity and delivery scale. This pricing model often combines commodity spot rates for mixed pentane with long-term contract-based offtake agreements for n-pentane and cyclopentane. Price differentiation stems from the specific isomer required and the certification level for high-purity grades. Pricing pressure arises from volatile crude oil and natural gas liquid markets, creating cost instability for producers. Smaller foam manufacturers and general solvent users typically exhibit the highest price sensitivity.
Supply Chain Analysis
Commodity price volatility in crude oil and natural gas liquids dominates pentane supply chain risk. Geographic supply concentration centers in China, the United States Gulf Coast, and South Korea, which are major petrochemical hubs. Pentane production primarily draws from natural gas liquids and crude oil refining as raw material dependencies. Distribution runs through a network of bulk tanks for large industrial users and drums for diverse smaller-volume requirements. Managing flammability risks requires specialized transport and storage protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pentane market dynamics are at a platform-economics inflection, driven by the interoperability shift towards pentane-HFO blends in insulation manufacturing.
For Market Incumbents: Build a resilient supply chain moat through strategic feedstock agreements and diversified production sites. Invest in R&D for optimized pentane-HFO blends to counter substitution threats from non-flammable hydrofluoroolefins. Expand capacity in key demand regions like China to solidify market share in foam manufacturing. Certification investment in new formulations can reinforce product performance criteria against evolving environmental standards.
For New Entrants and Emerging Players: Establish a beachhead in high-purity cyclopentane for the electronics sector, leveraging specialized production capabilities. Target Latin American construction markets, where new energy efficiency regulations create demand for modern insulation materials. A go-to-market angle focused on developing tailored n-pentane/isopentane blends for specific foam formulations offers differentiation. The solvent application segment, particularly in chemical processing, presents a penetrable white-space opportunity for specialty isomers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized chemical companies with strong intellectual property in pentane isomer separation. Long-term viability is anchored in the regulatory-driven demand for HFC alternatives in insulation, offering sustained growth. Acquisition targets should possess robust R&D capabilities in next-generation blowing agents and strong regional distribution networks. The signal to watch is the market share growth of pentane-HFO blends as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increasing output in China supports insulation foam manufacturing for building and cold chain logistics. |
| Green Manufacturing Transition | Adopting sustainable processes reduces environmental compliance costs and enhances market reputation. |
| Long-term Supply Agreement | Securing feedstock stabilizes costs for major foam producers amidst crude oil price volatility. |
| Joint Venture | Partnering for advanced pentane-HFO blend development accelerates market entry and technology sharing. |
| Vertical Integration into Feedstock | Captive supply mitigates volatility from crude oil and natural gas liquid markets for producers. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from market intelligence. Primary research involved discussions with petrochemical plant managers, foam manufacturers, chemical distributors, and electronics procurement leads. Secondary data sources included customs trade data, SEC 10-K filings, American Chemistry Council (ACC) reports, and governmental energy efficiency standards. The study employed both bottom-up and top-down triangulation to ensure data accuracy and market sizing integrity.
Forecast inputs considered historical market performance, technological advancements, and regulatory shifts across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-use industry, packaging type, and regional regulatory frameworks. Compound annual growth rates were derived from a comprehensive review of historical growth trajectories and projected future demand. Industry-specific forecast inputs included HFC phase-down schedules and crude oil price forecasts.
Sensitivities concentrate around unforeseen shifts in crude oil prices, new environmental regulations, or breakthrough blowing agent technologies. Forecasts reflect assumptions documented through expert consensus and quantitative modeling. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Bioisobutene Market
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Global Butadiene Market
Petrochemicals
Petrochemicals Market
Petrochemicals
Alkylate Market
Petrochemicals
Oman Pyrolysis Gasoline Market
Petrochemicals
Propylene Carbonate Market
Petrochemicals
Fossil Fuel-Based Plastics Market
Petrochemicals
Propylene Market
Petrochemicals
Pentaerythritol Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Petrochemical Feedstock Market
Petrochemicals
Military Propellants Market
Petrochemicals
Global Polypropylene Market
Petrochemicals
Synthetic and Biobased Butadiene Market
Petrochemicals
Global Methyl Tertiary Butyl Ether Market